
 Global Live Streaming Video Platform Market | 2026-2036
Global Live Streaming Video Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Live Streaming Video Platform Market Outlook
Southeast Asia is fragmenting as a live streaming production hub, with Indonesia and Vietnam adding datacenter capacity to serve regional latency requirements. Alphabet Inc. leverages its YouTube infrastructure to sustain low-latency delivery at scale across multiple continents. ByteDance Ltd. anchors its competitive position through algorithmic content distribution that integrates live and on-demand video within single ecosystems. Tencent Holdings Ltd. dominates gaming-centric streaming through deep integration with its interactive entertainment portfolio.
A live streaming video platform comprises software encoding pipelines, content delivery networks, and real-time transcoding infrastructure that processes audiovisual feeds with sub-five-second latency for synchronous viewer interaction. These systems serve commercial broadcasting, interactive commerce, and distance education by converting raw video signals into adaptive bitrate streams optimized for variable network conditions. Cloud services within the product type dimension lead infrastructure spending as enterprises abandon on-premise hardware for elastic compute scaling. The subscription service type captures recurring revenue from professional broadcasters while ad-supported models sustain mass-market consumer platforms with lower per-user monetization.
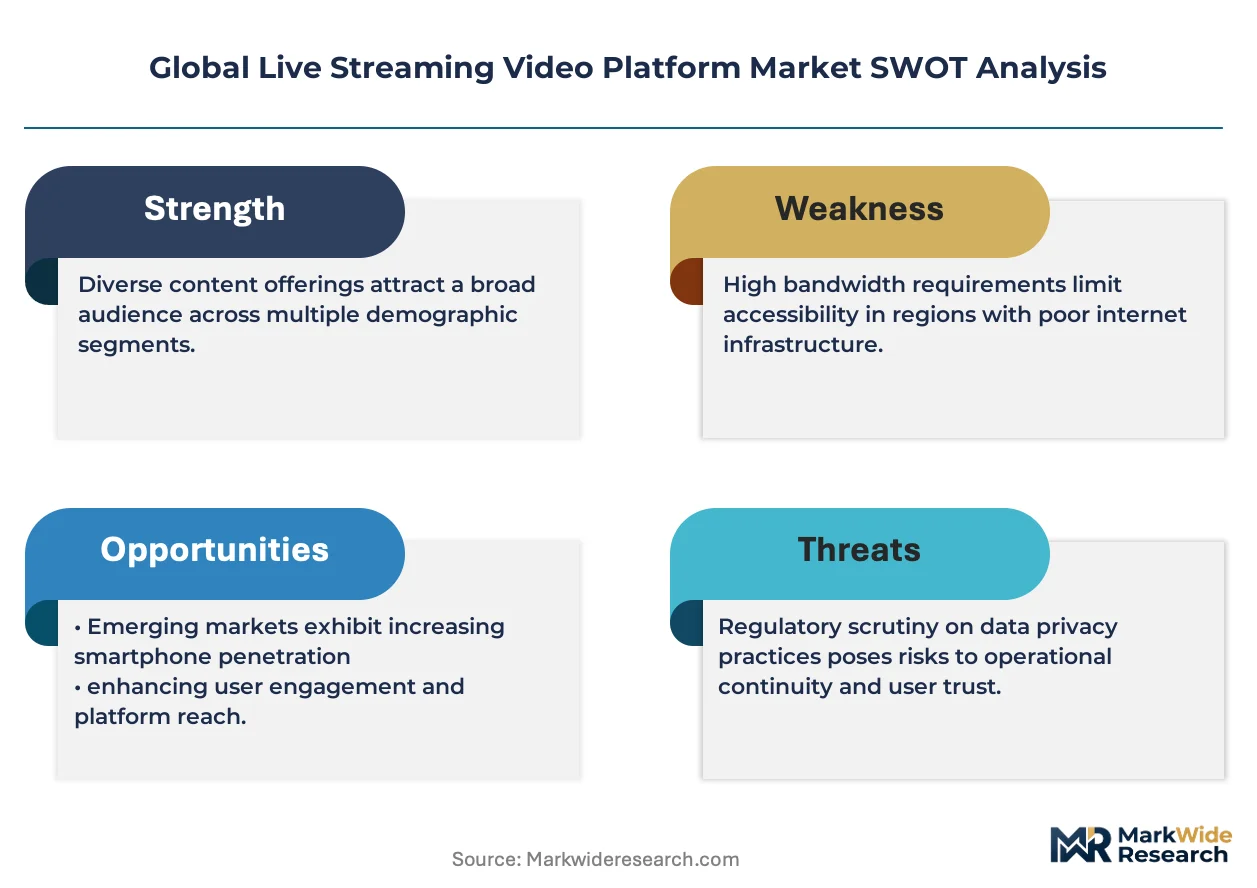
The Federal Communications Commission in the United States enforces net neutrality principles that shape bandwidth pricing for streaming delivery, while China's Ministry of Industry and Information Technology mandates local data residency for platform operations. The EU AI Act imposes transparency requirements on algorithmic recommendation systems that curate live content feeds, affecting product architecture decisions across multiple jurisdictions. Stakeholders must monitor evolving content liability frameworks that shift compliance burdens from users to platform operators.
Market Dynamics
Enterprise migration from on-premise broadcast hardware to elastic cloud infrastructure is compressing capital deployment cycles and forcing incumbent vendors to restructure pricing models around consumption-based metering.
Growth Catalysts
- EU Digital Services Act:Content moderation mandates under this framework compel platforms to deploy automated compliance pipelines, expanding addressable market for real-time AI moderation tools and transcoding services.
- Esports broadcasting:Professional gaming leagues in South Korea and the United States drive sustained infrastructure investment for sub-second latency delivery to synchronous audiences.
- Cloud encoding:Elastic compute scaling eliminates upfront hardware procurement for mid-market broadcasters, lowering barriers to professional-grade live production.
Market Restraints
- Bandwidth cost volatility:Net neutrality enforcement by the FCC creates pricing uncertainty for last-mile delivery, compressing margins for ad-supported platforms dependent on scale economics.
- Datacenter concentration:Southeast Asian capacity build-outs in Indonesia and Vietnam remain insufficient for regional redundancy, exposing latency-sensitive applications to single-point failures.
- Codec licensing fragmentation:Patent pool disputes around AV1 and HEVC create legal friction for hardware decoder integration in mobile devices.
Strategic Opportunities
- Brazilian regulatory alignment:Pending content liability frameworks mirror EU DSA obligations, creating first-mover advantage for compliance-integrated platform entrants.
- Interactive commerce convergence:Live shopping integrations merge transactional and entertainment workflows, opening new monetization layers for creator economy platforms.
- Edge computing deployment:5G MEC nodes enable broadcast-grade contribution from mobile devices without dedicated encoding hardware.
Industry Challenges
- Real-time transcoding expertise:Shortage of engineers proficient in low-latency protocol optimization (SRT, WebRTC) delays product roadmaps for mid-tier platforms.
- Legacy SDI integration:Hybrid environments requiring signal conversion from serial digital interface to IP-based workflows introduce failure points and training overhead.
- Cross-border data routing:China's MIIT residency mandates complicate multi-continental content distribution architectures for multinational broadcasters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Live Streaming Video Platform Market |
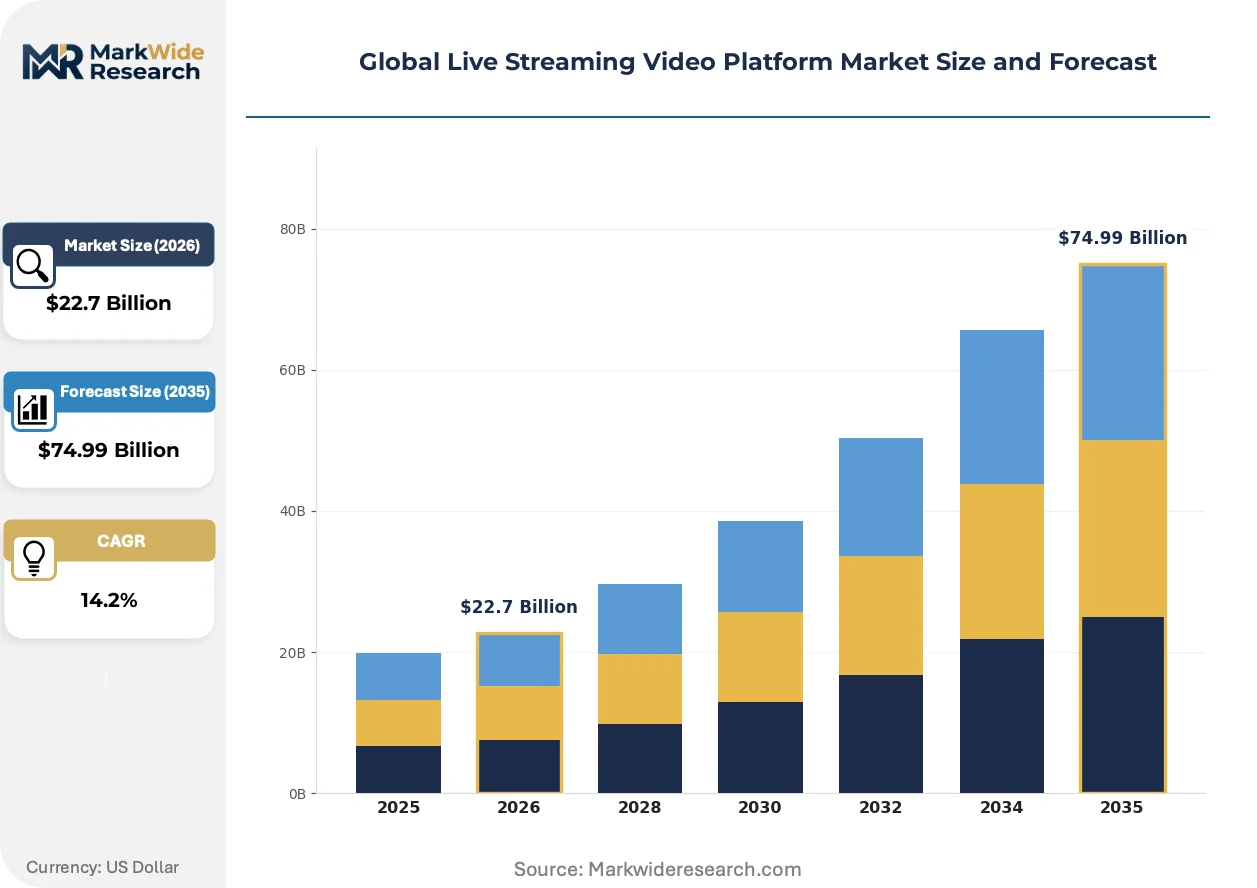
| Market Size in 2026 | $22.7 Billion |
| Market Size in 2035 | $74.99 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Integrated Solutions, Cloud Services End User: Enterprises, Content Creators, Educators, Creators Service Type: Subscription, Ad-Supported, Pay-Per-View, Freemium Distribution Channel: Direct Sales, Online Marketplaces, Third-Party Distributors, Partnerships |
| Companies Covered | Alphabet Inc., ByteDance Ltd., Tencent Holdings Ltd., Meta Platforms Inc., Amazon.com Inc., Microsoft Corp., Twitch Interactive, Inc., Brightcove Inc., Wowza Media Systems LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Live Streaming Video Platform Market Strategic Shifts
Algorithmic personalization and edge-distributed infrastructure are converging to redefine how live content reaches audiences, shifting competitive advantage from raw scale to predictive delivery optimization.
WebRTC-based contribution protocols are collapsing the latency gap between professional broadcast workflows and consumer-grade streaming. Mid-market sports leagues and house-of-worship broadcasters adopt these tools for remote production without satellite truck deployment. The technology is collapsing the traditional tiering between broadcast and prosumer equipment categories.
The EU AI Act imposes transparency requirements on algorithmic recommendation systems that curate live content feeds. Platform operators must now document ranking logic and provide audit trails for regulatory examination. Gaming-centric platforms in Europe face particular scrutiny due to real-time chat integration and minor audience exposure.
Enterprise procurement of live streaming infrastructure now favors outcome-based contracts tied to uptime SLAs rather than perpetual software licenses. Media companies and educational institutions negotiate performance guarantees with cloud vendors, shifting operational risk to service providers. This pattern is most visible in North American and Western European enterprise accounts.
Global Live Streaming Video Platform Market Segmentation
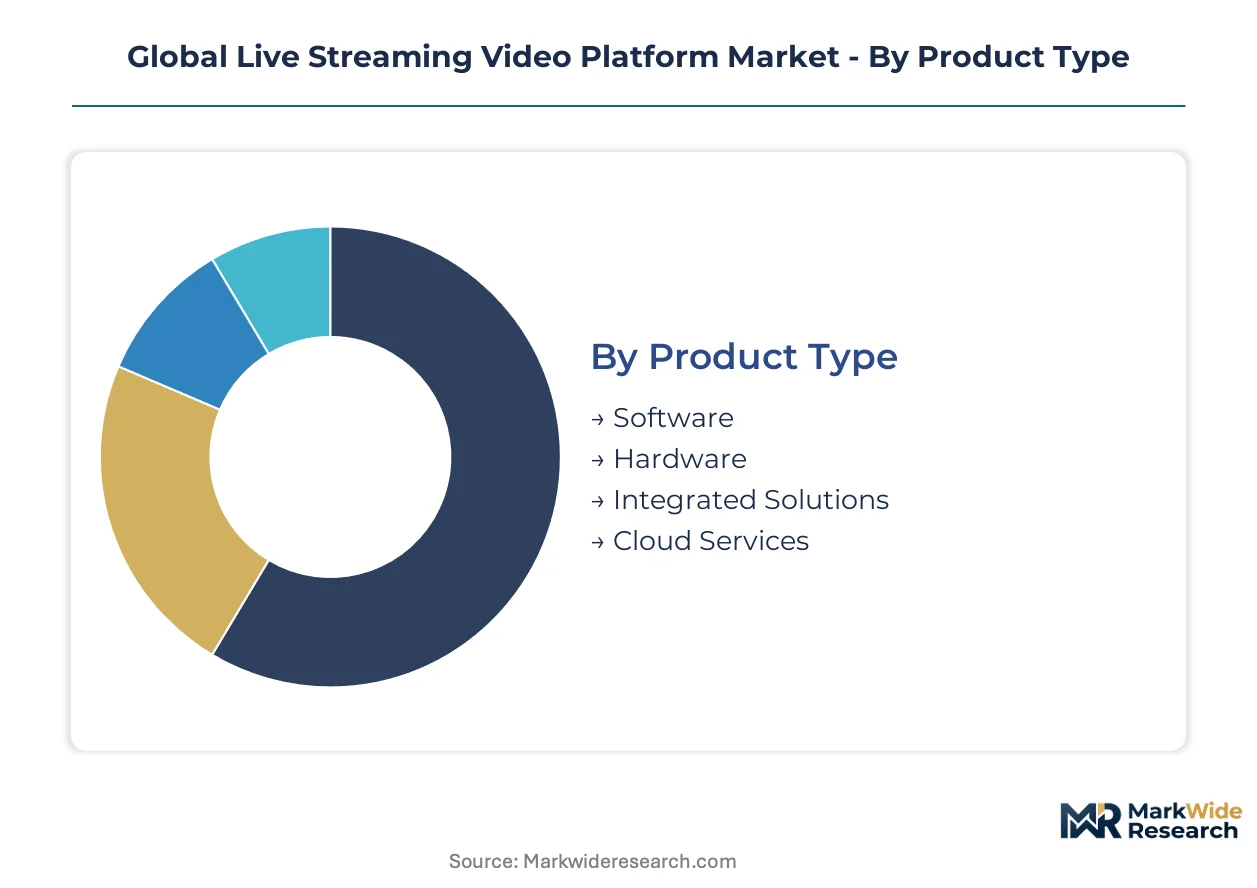
Live streaming video platform segmentation reveals divergent infrastructure requirements across deployment modes and monetization models. Technical specifications for latency tolerance, encoding complexity, and compliance integration vary substantially between enterprise broadcasters and individual creators. Platform vendors must architect modular product lines that span professional broadcast-grade systems through consumer-accessible tools without fragmenting development resources.
Product Type:
Mature on-premise hardware solutions coexist with rapidly maturing cloud-native alternatives, creating a bifurcated procurement landscape where enterprise buyers weigh capital efficiency against operational control.
- Software:Browser-based encoding clients and standalone production applications enable mid-market broadcasters to deploy professional workflows without dedicated appliance procurement. Demand concentrates among regional sports networks and religious institutions in the United States seeking to replace aging hardware with subscription-based alternatives that shift capital expenditure to operational budgets.
- Cloud Services:Elastic compute infrastructure for real-time transcoding, adaptive bitrate packaging, and global CDN orchestration processes video feeds through distributed edge nodes. South Korean esports broadcasters and Chinese interactive commerce platforms drive capacity expansion, requiring sub-second latency delivery to synchronous audiences across metropolitan clusters.
- Hardware:Dedicated encoding appliances and capture cards with onboard HEVC/AV1 acceleration serve broadcasters with stringent security or latency requirements that preclude public cloud dependency.
- Integrated Solutions:Bundled software-hardware packages with unified control interfaces reduce integration overhead for educational institutions and corporate communications teams with limited engineering staff.
Cloud Services retains volume leadership; Cloud Services holds the steepest expansion curve.
End User:
Procurement authority separates between centralized IT departments managing enterprise-wide deployments and individual creators making discretionary purchasing decisions through self-service channels.
- Enterprises:Fortune 500 communications teams, financial services institutions, and healthcare systems procure live streaming infrastructure for internal town halls, investor relations broadcasts, and telemedicine consultations. Compliance mandates under HIPAA in the United States and GDPR in Europe require audit trails and data residency controls that favor vendors with regional datacenter presence.
- Content Creators:Individual streamers, influencer networks, and small production collectives monetize audience attention through platform-native tools and third-party production software. Brazil's expanding creator economy and Indonesia's mobile-first entertainment markets sustain demand for lightweight, smartphone-optimized encoding solutions.
- Educators:Universities and K-12 districts deploy lecture capture and remote classroom systems, prioritizing LMS integration and accessibility compliance over broadcast-grade production values.
- Creators:Professional production studios serving brand clients and media companies operate at the intersection of enterprise reliability requirements and creative workflow flexibility.
Enterprises dominate current procurement volume; Content Creators are climbing the fastest as platform economics lower professional production barriers.
Service Type:
Monetization architecture determines platform infrastructure investment intensity, with subscription models funding sustained R&D while ad-supported delivery prioritizes scale economics and engagement optimization.
- Subscription:Recurring revenue contracts with professional broadcasters, corporate communications departments, and educational institutions provide predictable cash flows that fund platform development. North American and Western European enterprise accounts increasingly negotiate outcome-based contracts tied to uptime SLAs.
- Ad-Supported:Free-to-access platforms monetize viewer attention through programmatic advertising insertion, requiring massive concurrent audience scale to achieve unit economics viability. FCC net neutrality enforcement in the United States creates bandwidth pricing uncertainty that compresses margins for scale-dependent operators.
- Pay-Per-View:Transactional access to premium live events—combat sports, concert broadcasts, theatrical releases—generates concentrated revenue spikes with minimal ongoing infrastructure commitment.
- Freemium:Tiered feature access converts free users to paid tiers through gated production tools, analytics dashboards, or distribution capabilities, common among creator economy platforms in South Korea and Vietnam.
Subscription captures the highest revenue per user; Ad-Supported is gaining share fastest as emerging market smartphone penetration expands addressable audiences.
Distribution Channel:
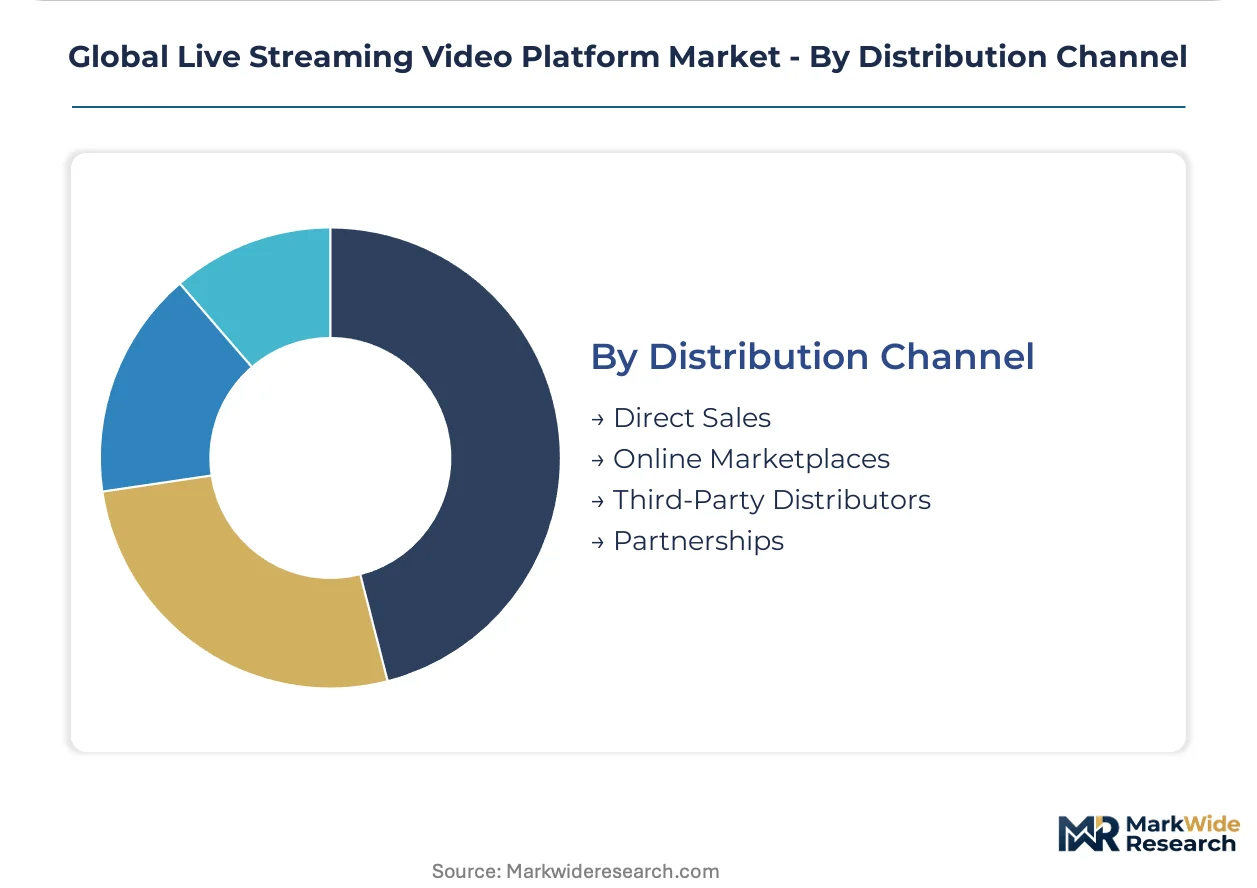
Route-to-market strategy reflects customer technical sophistication, with self-service adoption growing among smaller accounts while complex enterprise deployments require consultative sales engagement.
- Direct Sales:Vendor field organizations and inside sales teams manage enterprise procurement cycles, professional services integration, and ongoing account expansion. Large media companies and multinational corporations in Germany, Japan, and the United States favor direct relationships for mission-critical broadcast infrastructure.
- Online Marketplaces:Self-service procurement through vendor websites and cloud marketplaces enables rapid deployment for technically proficient smaller teams. Indian edtech startups and Southeast Asian gaming streamers leverage AWS Marketplace and Azure Marketplace for instant infrastructure provisioning.
- Third-Party Distributors:Value-added resellers and systems integrators provide local support, training, and integration services in markets where vendor direct presence remains limited.
- Partnerships:Strategic alliances with broadcast equipment manufacturers, telecom operators, and platform aggregators embed streaming capabilities within broader solution portfolios.
Direct Sales retains the highest contract value concentration; Online Marketplaces are expanding most quickly as cloud-native buyers bypass traditional procurement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Datacenter build-outs concentrate in jurisdictions with favorable bandwidth pricing and creator economy density. Platform operators route traffic through regional edge nodes to satisfy latency requirements for interactive commerce and esports broadcasting.
United States
Enterprise broadcast adoption drives infrastructure investment from Fortune 500 communications teams and financial services institutions. FCC net neutrality enforcement shapes bandwidth pricing uncertainty for last-mile delivery. Los Angeles and New York media clusters host production studios serving brand clients with hybrid cloud workflows.
China
Interactive commerce platforms sustain massive concurrent audience scale through algorithmic content distribution. MIIT data residency mandates require local platform operations with domestic datacenter presence. Shenzhen and Hangzhou technology corridors anchor ByteDance and Tencent infrastructure build-outs.
South Korea
Esports leagues generate concentrated demand for sub-second latency delivery to synchronous gaming audiences. The country's national broadcasting regulator enforces content standards for minor audience exposure. Seoul metropolitan datacenters process real-time transcoding for professional gaming tournaments.
Germany
Enterprise procurement favors outcome-based contracts with uptime SLAs for mission-critical broadcast infrastructure. EU AI Act transparency requirements apply to algorithmic recommendation systems curating live feeds. Berlin and Munich media technology clusters serve multinational corporate communications deployments.
Brazil
Creator economy expansion sustains demand for smartphone-optimized encoding solutions among individual streamers. Pending content liability frameworks mirror EU DSA obligations for platform operator accountability. São Paulo technology startups leverage cloud marketplaces for rapid infrastructure provisioning.
Global Live Streaming Video Platform Market Competitive Environment
Hyperscale technology conglomerates and specialized streaming infrastructure providers split the market into distinct capability tiers. Consolidation pressure intensifies as enterprise buyers demand integrated solutions spanning contribution, transcoding, and global distribution. Cloud-native challengers and legacy broadcast vendors represent opposing strategic archetypes. Capacity expansion and strategic partnerships dominate competitive moves as players address regional latency requirements.
Within the hyperscale tier, Alphabet Inc. and ByteDance Ltd. occupy positions defined by algorithmic distribution scale and integrated content ecosystems. Tencent Holdings Ltd. anchors the gaming-centric specialization vector through interactive entertainment portfolio alignment. Brightcove Inc. and Wowza Media Systems LLC represent the infrastructure-focused archetype serving mid-market broadcasters with modular deployment options.
| Leading Market Players |
|---|
| Alphabet Inc. |
| ByteDance Ltd. |
| Tencent Holdings Ltd. |
| Meta Platforms Inc. |
| Amazon.com Inc. |
| Microsoft Corp. |
| Twitch Interactive, Inc. |
| Brightcove Inc. |
| Wowza Media Systems LLC |
| Others |
Value Chain & Pricing Dynamics
Datacenter overcapacity in Southeast Asia compresses bandwidth pricing for edge delivery nodes while forcing infrastructure providers toward consumption-based metering models that align supplier revenue with actual utilization rates.
Pricing Analysis
The EU Digital Services Act dictates the pricing tier structure for compliance-integrated platform tiers, separating premium subscription offerings with automated moderation pipelines from standard ad-supported tiers with basic filtering. Price differentiation rests on latency guarantees and data residency controls, with enterprise broadcasters in Germany and Japan least sensitive to per-unit costs while individual creators in Brazil and Indonesia face acute pressure from smartphone-optimized encoding subscription fees. Cost compression in the mid-market SaaS tier is intensifying because cloud-native challengers displace legacy appliance vendors with elastic compute alternatives.
Supply Chain Analysis
Upstream semiconductor fabrication for video encoding ASICs draws from Taiwan, South Korea, and the United States, with HEVC and AV1 decoder chips anchoring hardware cost structures. Raw material dependencies span silicon wafers, high-bandwidth memory modules, and specialized optical transceivers for fiber backhaul. Single-source vulnerability concentrates in advanced node GPU supply for real-time transcoding workloads. Distribution runs through hyperscaler cloud marketplaces and direct enterprise field sales with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud encoding services represent a service-attach opportunity where recurring-revenue transcoding contracts expand faster than perpetual hardware licenses, with outcome-based uptime SLAs capturing enterprise procurement preference.
For Market Incumbents: Insulate core enterprise accounts through backward integration into regional edge node operations, particularly in South Korea and Germany where latency requirements preclude multi-hop routing. Fortify compliance-integrated product lines against specialized AI moderation entrants by embedding automated pipeline documentation that satisfies EU AI Act audit requirements.
For New Entrants and Emerging Players: Build out modular WebRTC-based contribution tools targeting mid-market sports leagues and religious institutions in the United States that lack satellite truck capital budgets. Brazil's pending content liability frameworks create first-mover positioning for platform entrants offering pre-integrated DSA-aligned moderation stacks through self-service cloud marketplace channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native infrastructure providers serving esports broadcasters with sub-second latency SLAs, indicating superior cash-flow quality versus ad-dependent consumer platforms. Long-term viability favors specialists with demonstrated protocol optimization expertise in SRT and WebRTC stacks. Monitor 5G MEC deployment density as inflection indicator for mobile-first broadcast-grade contribution viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Deployment | 5G MEC nodes enable broadcast-grade mobile contribution without dedicated encoding hardware in metropolitan clusters. |
| Compliance Pipeline Integration | Automated AI moderation tools embedded within transcoding workflows satisfy EU Digital Services Act mandates. |
| Cloud Marketplace Expansion | AWS Marketplace and Azure Marketplace channels accelerate procurement cycles for Indian edtech and Southeast Asian gaming segments. |
| Protocol Standardization Investment | WebRTC and SRT optimization expertise collapses latency gaps between professional and prosumer broadcast tiers. |
| Regional Datacenter Buildout | Jakarta and Ho Chi Minh City capacity additions address Southeast Asian fragmentation and latency requirements. |
Study Parameters
A standing panel of platform engineering directors, enterprise IT procurement officers, content creator network operators, and regulatory compliance leads provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against SEC filings from hyperscale technology conglomerates, hyperscaler capex disclosure reports, and EU regulatory implementation guidance documents. Bottom-up segment sizing triangulated against top-down market aggregation across deployment mode, monetization architecture, and regional adoption pattern dimensions.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeling spanning product type, end user archetype, service type, and distribution channel. CAGRs derived from fitted growth curves incorporating enterprise cloud migration velocity, creator economy platform participation rates, and esports viewership expansion as industry-specific forecast inputs.
Practitioners should monitor bandwidth pricing regulatory shifts and codec patent pool litigation outcomes for early signals requiring forecast revision. Cross-checking against hyperscaler infrastructure capex disclosures and regional datacenter permitting databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Global Cloud Video Streaming Market
Video Streaming (OTT) Services
Asia Pacific Video Streaming Market
Video Streaming (OTT) Services
Online Streaming Service Market
Video Streaming (OTT) Services
Advertising-Based Video on Demand Market
Video Streaming (OTT) Services
United States Online Video Platform Market
Video Streaming (OTT) Services
Mexico OTT TV and Video Market
Video Streaming (OTT) Services
Enterprise Streaming Media Market
Video Streaming (OTT) Services
Indonesia OTT Market
Video Streaming (OTT) Services
Live Streaming Pay-Per-View Market
Video Streaming (OTT) Services
Global Over-The-Top Market
Video Streaming (OTT) Services
Video-On-Demand [Vod] Market
Video Streaming (OTT) Services
Global Transactional Video on Demand Market
Video Streaming (OTT) Services
Over the Top (OTT) Services Market
Video Streaming (OTT) Services
Latin America OTT Platform Market
Video Streaming (OTT) Services
Video Servers Market
Video Streaming (OTT) Services
Sports Streaming Platform Market