
 Global Svod Market | 2026-2036
Global Svod Market Size, Share, and Industry Trends Forecast 2026-2036
Global Svod Market Outlook
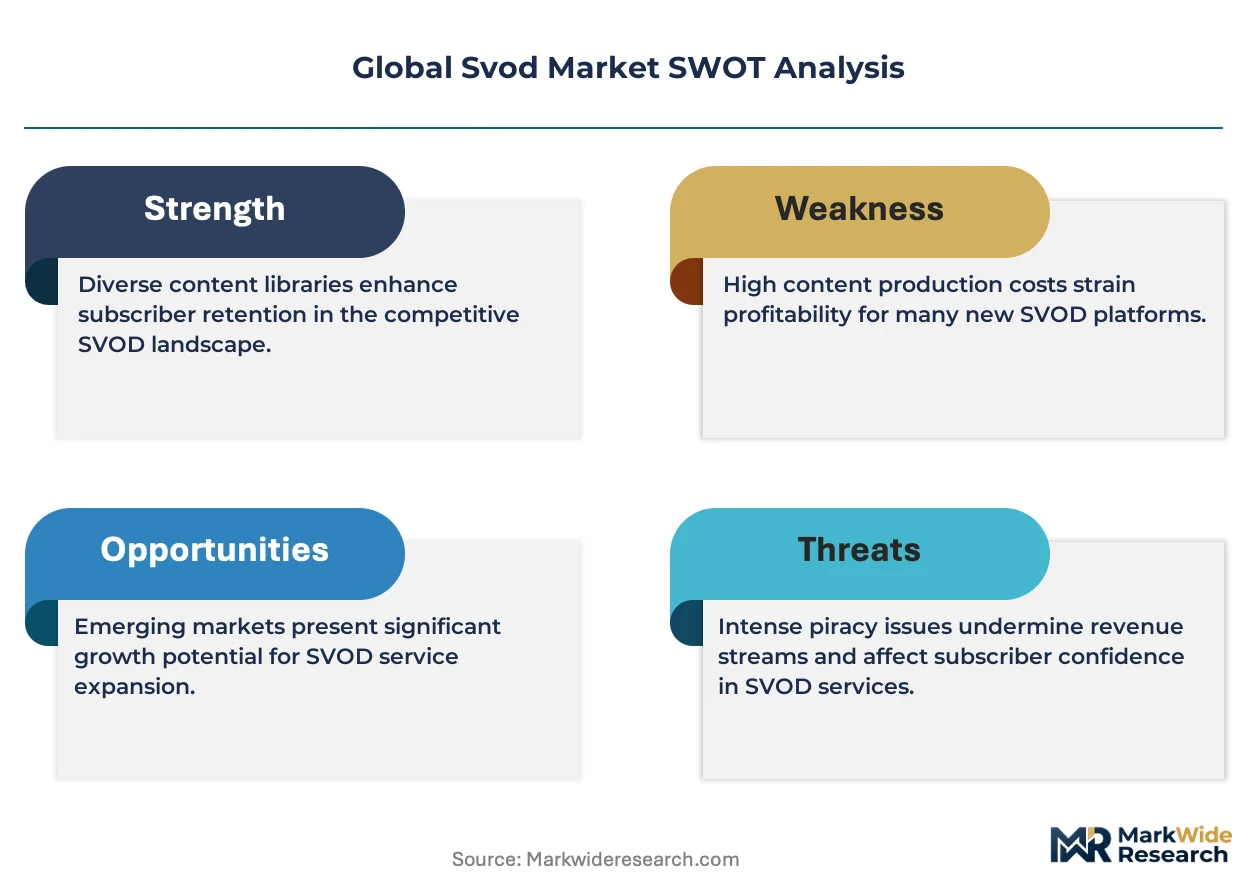
Platform licensing revenue is fragmenting across original content production, regional exclusivity deals, and ad-supported tier monetization. Netflix leverages its global production infrastructure to sustain localized content pipelines across multiple continents. Disney+ anchors its competitive position through exclusive franchise intellectual property and bundled service architectures. Amazon Prime Video differentiates by integrating streaming with broader e-commerce and logistics subscription ecosystems.
Subscription video on demand refers to streaming services that deliver video content to subscribers through internet-connected devices, typically utilizing adaptive bitrate streaming protocols to maintain quality across varying bandwidth conditions. The primary commercial purpose centers on recurring revenue generation through continuous content refreshment and subscriber retention mechanics. Movies and TV series command the largest current revenue share within content type segmentation, while ad-supported pricing models represent the fastest-expanding subscriber acquisition channel. Distribution through mobile platforms shows disproportionate growth in emerging markets where smartphone penetration exceeds fixed broadband availability.
The EU Digital Services Act and GDPR impose content moderation transparency and data processing constraints on platforms operating across European markets. The FCC in the United States governs broadcast standards that influence streaming quality benchmarks and closed captioning requirements for accessibility compliance. Stakeholders must monitor evolving content quota regulations in jurisdictions such as France and Canada that mandate minimum percentages of domestic production in platform catalogs.
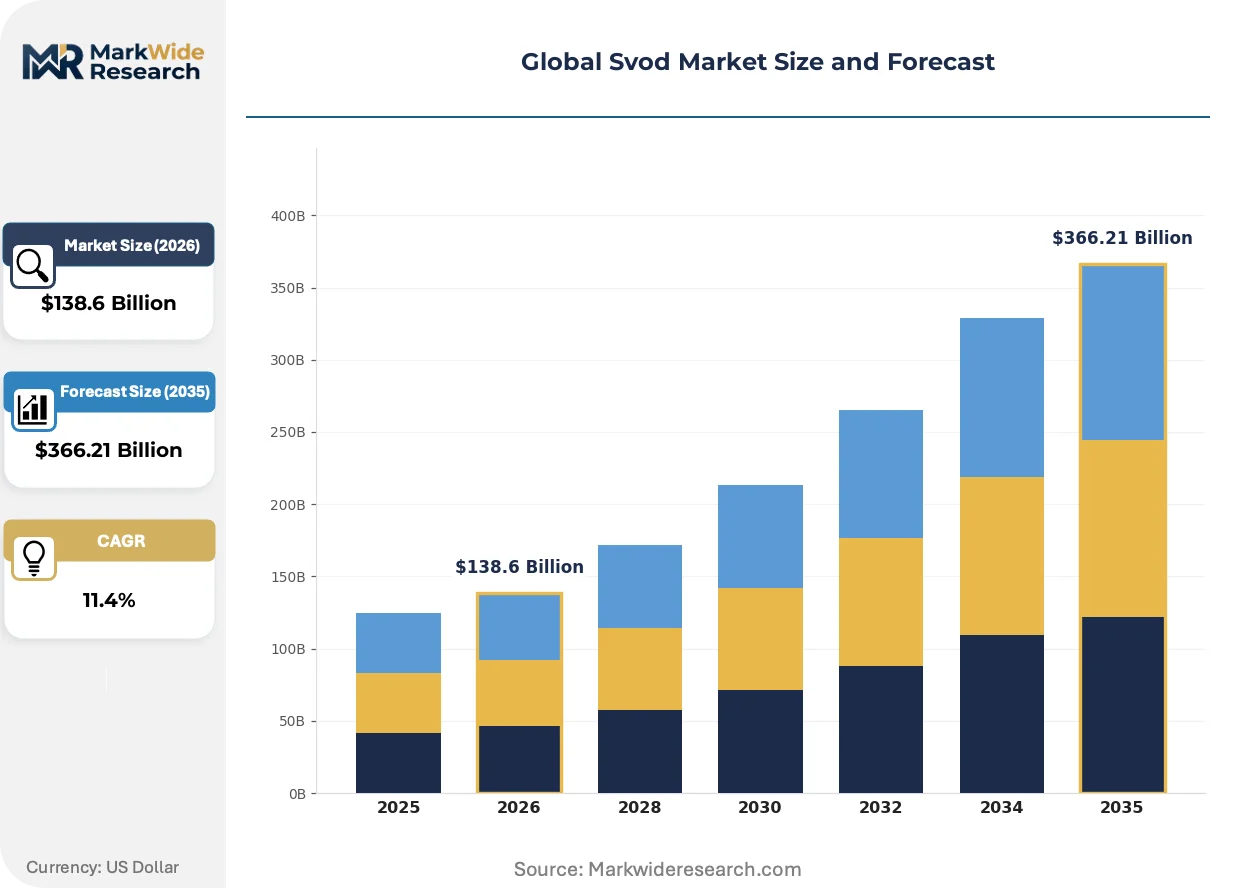
Market Dynamics
Content licensing revenue fragmentation across original production, regional exclusivity, and ad-supported tiers is forcing platforms to restructure their monetization architectures around localized subscriber acquisition economics rather than global catalog uniformity.
Growth Catalysts
- EU Digital Services Act compliance:Platforms investing in transparent content moderation systems are securing preferential licensing terms with European broadcasters and studio partners seeking regulatory-aligned distribution partners.
- Mobile-first streaming infrastructure:Adaptive bitrate protocols optimized for variable bandwidth conditions are unlocking subscriber growth in India, Brazil, and Southeast Asia where smartphone penetration exceeds fixed broadband deployment.
- Household demand concentration:Emerging market households are driving the fastest-expanding subscriber base as middle-class formation accelerates discretionary entertainment spending in urban centers.
Market Restraints
- Original content production cost inflation:Talent compensation and production facility scarcity in premium filming locations are compressing platform margins on exclusive programming investments.
- Exclusive catalog concentration risk:Reliance on franchise intellectual property from limited studio suppliers creates vulnerability to renegotiation leverage shifts during contract renewal windows.
- Data processing constraints:GDPR and equivalent privacy frameworks in multiple jurisdictions are restricting personalization algorithm training data availability and cross-border subscriber analytics portability.
Strategic Opportunities
- Ad-supported tier expansion:Lower-price subscription options are capturing price-sensitive household segments previously excluded from premium streaming access across Latin American and South Asian markets.
- Content quota regulatory tailwinds:France and Canada are mandating minimum domestic production percentages in platform catalogs, creating first-mover advantages for services with established local production infrastructure.
- Bundle architecture convergence:Integration of streaming with logistics, e-commerce, and telecommunications subscription ecosystems is reducing churn through multi-service lock-in mechanisms.
Industry Challenges
- Localization talent scarcity:Demand for culturally nuanced content adaptation and dubbing professionals exceeds supply in high-growth language markets, delaying regional catalog rollout timelines.
- Legacy broadcast integration complexity:Platforms acquiring traditional media assets face technical and organizational friction in merging linear scheduling systems with on-demand streaming architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Svod Market |
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $366.21 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Movies, TV Series, Documentaries, Animated Content Pricing Model: Ad-Supported, Subscription-Based, Tiered Pricing, Freemium Distribution Channel: Direct-to-Consumer, Aggregators, Cable Partnerships, Mobile Platforms Device Type: Smart TVs, Mobile Devices, Laptops, Streaming Devices |
| Companies Covered | Netflix, Amazon Prime Video, Disney+, Apple TV+, Max, Paramount+, Hulu, Google LLC, Cisco Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Svod Market Strategic Shifts
Streaming technology is migrating from centralized server architectures toward edge-computing and peer-assisted delivery models that reduce bandwidth costs and improve latency for live content experiences.
AV1 codec deployment is migrating from experimental status toward mainstream adoption as hardware decoder penetration in smart televisions and mobile system-on-chips reaches critical mass. Mid-tier streaming services are accelerating migration timelines to reduce CDN expenditure as 4K and HDR content volumes expand. This compression efficiency gain is migrating from cost-saving mechanism toward competitive necessity as ad-supported tiers multiply concurrent streams per household.
GDPR enforcement actions by CNIL and equivalent national regulators are tightening consent frameworks for behavioral advertising and cross-service data profiling. Platforms must now implement granular opt-in mechanisms for personalized recommendation engines, increasing operational compliance overhead. European subscriber segments are responding with elevated churn sensitivity when consent requests interrupt onboarding flows.
Household subscription stacking fatigue is compressing the average duration of single-platform loyalty as economic pressures force prioritization decisions. Brazilian and Indian consumers are rotating between services monthly rather than maintaining continuous multi-platform relationships. This behavior is fragmenting content release window strategies and pressuring platforms toward continuous marquee programming schedules rather than seasonal drops.
Global Svod Market Segmentation
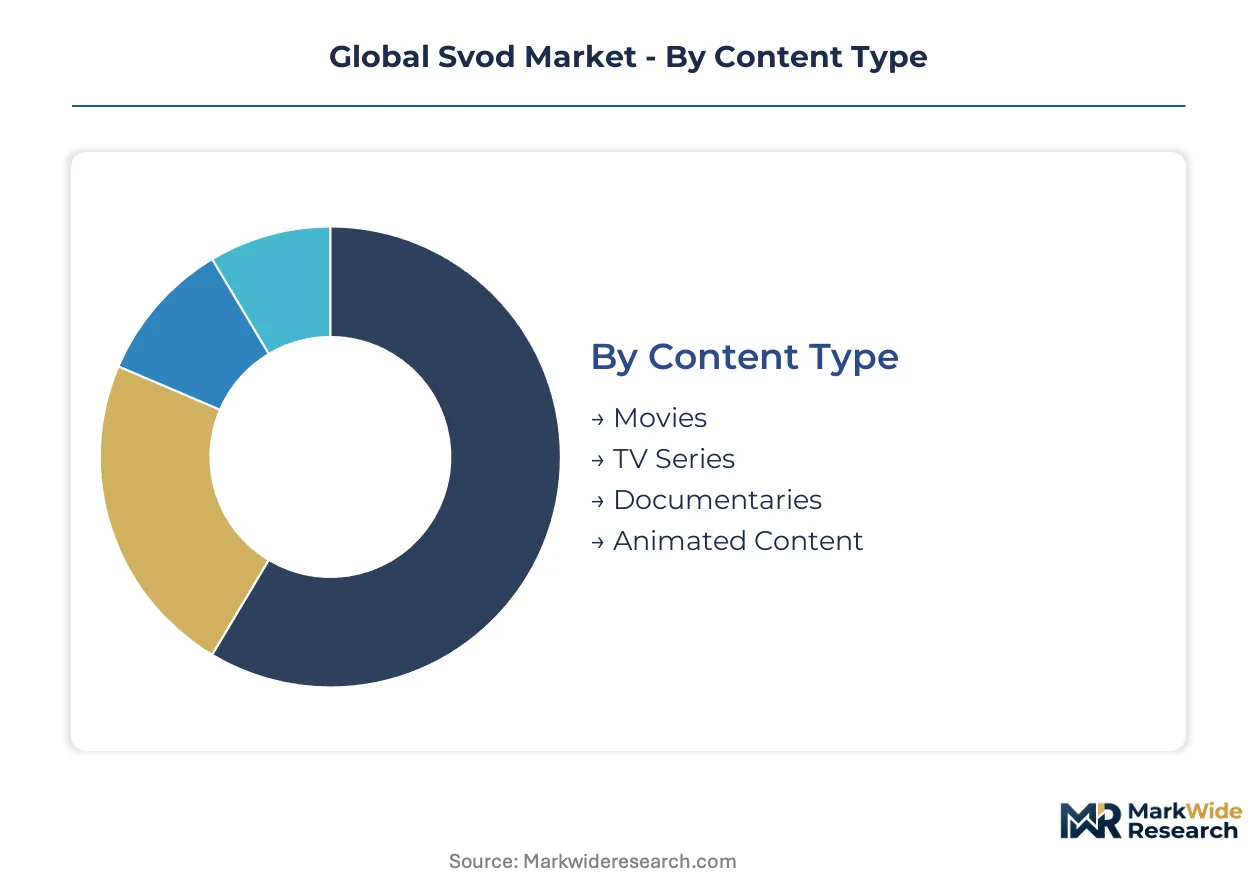
SVOD platforms engineer monetization architectures around distinct content consumption patterns and device ecosystems. Segmentation clarity enables targeted subscriber acquisition economics and localized catalog investment priorities across heterogeneous market conditions.
Content Type:
After-sales service intensity varies dramatically by content type, with live-action productions demanding continuous technical support for localization pipelines and animated content requiring specialized post-production maintenance.
- Movies:Feature-length productions utilize theatrical-to-streaming window compression strategies. Demand concentrates in urban Indian and Brazilian households where theatrical infrastructure gaps accelerate direct-to-platform consumption preferences.
- TV Series:Episodic formats sustain subscriber retention through scheduled release cadences and cliffhanger-driven engagement mechanics. Seasonal production cycles create predictable content refreshment obligations for platform operations teams.
- Documentaries:Factual content carries lower per-title production overhead with extended shelf life. Niche audience concentration in educated European demographics supports premium pricing tolerance for specialized factual catalogs.
- Animated Content:Family-oriented animation commands multi-generational household viewership with reduced churn sensitivity. Localization complexity for dubbing and cultural adaptation increases operational service intensity in non-English markets.
Movies hold the largest share; momentum sits with TV Series.
Pricing Model:
Cost tier differentiation structures platform accessibility across income-stratified subscriber bases, with ad-supported architectures reducing entry barriers in price-sensitive emerging markets.
- Ad-Supported:Lower-fee tiers monetize through programmatic advertising insertion with reduced content resolution. Brazilian and Southeast Asian consumers exhibit strongest adoption elasticity as discretionary entertainment budgets face inflationary pressure.
- Subscription-Based:Pure subscription models eliminate advertising interruption for premium user experiences. Established North American and Western European households demonstrate highest willingness-to-pay for uninterrupted viewing.
- Tiered Pricing:Multi-level structures segment concurrent stream allowances and video quality specifications. Household composition variations drive selection between individual, standard, and premium tier commitments.
- Freemium:Limited-catalog free access converts users to paid subscriptions through content gating mechanisms. Mobile-first Indian consumers show highest conversion responsiveness from freemium trial to paid commitment.
Subscription-Based maintains revenue concentration; Ad-Supported climbs the fastest.
Distribution Channel:
Application-specific distribution strategies align with regional telecommunications infrastructure maturity and legacy media partnership availability.
- Direct-to-Consumer:Platform-owned applications capture full subscriber relationship data and margin retention. First-party distribution dominates in markets with mature app store ecosystems and reliable payment infrastructure.
- Aggregators:Bundled service marketplaces reduce customer acquisition costs through cross-promotional placement. Latin American telecommunications bundles demonstrate strongest aggregator dependency for subscriber growth.
- Cable Partnerships:Legacy operator integrations extend platform reach into broadband-television bundled households. Older demographic segments in North American and European markets exhibit persistent cable-originated streaming adoption.
- Mobile Platforms:Carrier-billed subscriptions bypass credit card infrastructure gaps in emerging economies. Prepaid mobile wallet integration enables access for unbanked consumer segments across India and Southeast Asia.
Direct-to-Consumer commands margin leadership; Mobile Platforms gain share fastest.
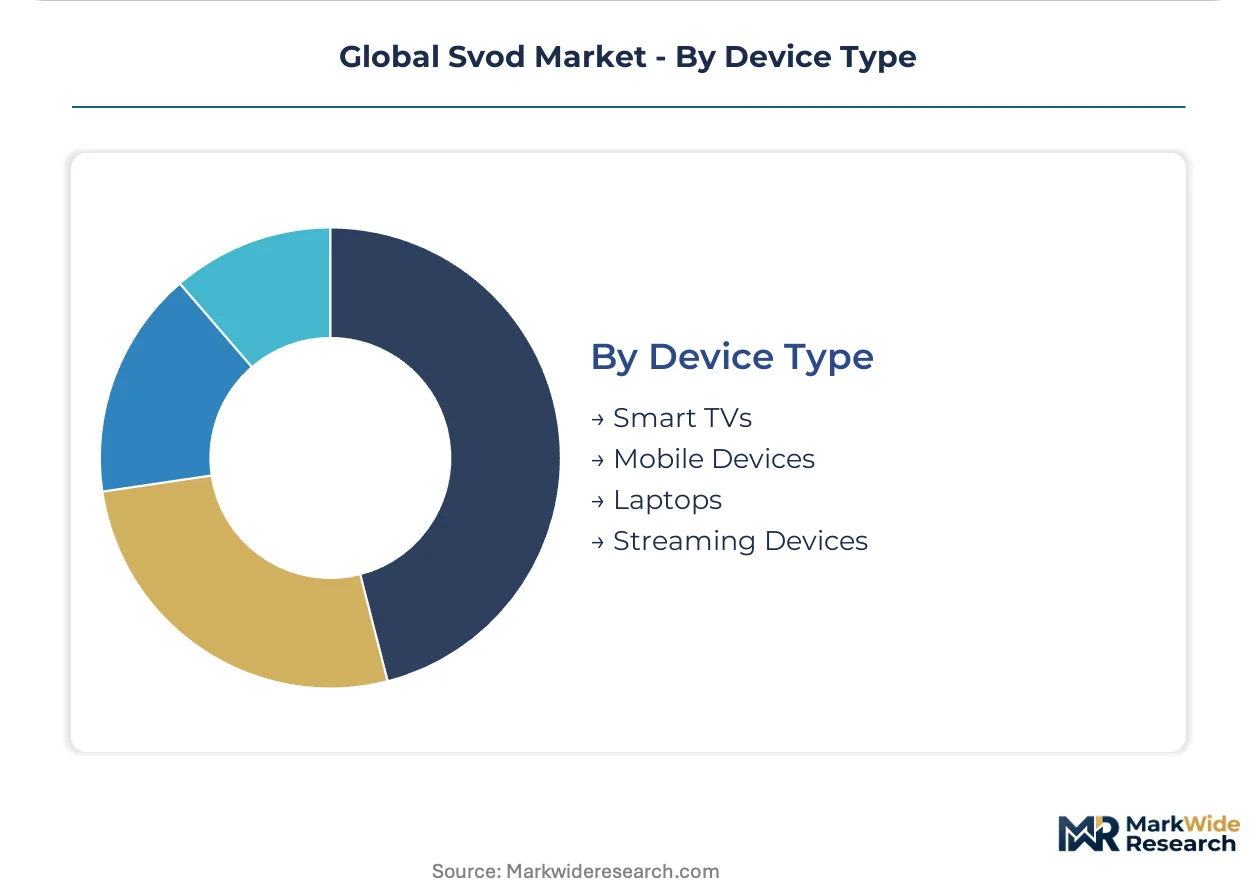
Device Type:
Hardware-specific optimization requirements drive divergent development resource allocation and quality assurance protocols across screen formats.
- Smart TVs:Large-format displays demand highest bitrate encoding for 4K HDR presentation quality. Living-room-centric viewing in developed market households sustains longest average session durations and premium tier attachment.
- Mobile Devices:Smartphone consumption requires adaptive bitrate protocols for cellular network variability. Commute and transit viewing patterns in dense Asian urban centers concentrate mobile-specific engagement.
- Laptops:Personal computer access supports multitasking behaviors and secondary-screen viewing. Student and remote-worker demographics exhibit highest laptop-originated streaming frequency.
- Streaming Devices:Dedicated hardware dongles and set-top boxes extend platform access to non-smart television displays. Price-sensitive households in transitional technology markets favor streaming device upgrades over full television replacement.
Smart TVs anchor revenue per user; Mobile Devices show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Households in India and Brazil exhibit extreme price elasticity, rotating monthly between services to maximize content access per dollar spent, while subscribers in Germany and Japan demonstrate lower churn sensitivity and higher willingness to pay for uninterrupted premium experiences.
United States
Urban coastal households drive premium tier attachment through smart TV-centric viewing, with longest average session durations concentrated in Los Angeles and New York metropolitan clusters. FCC closed captioning mandates and broadcast quality benchmarks shape platform technical compliance investments. Silicon Valley technology corridors supply adaptive bitrate streaming infrastructure and cloud delivery architectures to global platform operators.
India
Mobile-first consumption dominates as prepaid mobile wallet integration bypasses credit card infrastructure gaps for unbanked segments in Mumbai and Bangalore. TRAI content moderation frameworks and data localization requirements impose operational constraints on foreign platform architectures. Hyderabad and Chennai production hubs generate localized original content to satisfy domestic catalog quota expectations.
Brazil
Price-sensitive households in São Paulo and Rio de Janeiro exhibit highest ad-supported tier adoption elasticity as inflation pressures discretionary entertainment budgets. ANVISA content classification standards intersect with platform self-regulatory protocols for family-oriented programming. São Paulo state anchors Latin American dubbing and localization talent clusters serving Portuguese-language market expansion.
Germany
Western European subscribers demonstrate lowest churn rates and highest tolerance for tiered pricing structures segmenting concurrent stream allowances. GDPR enforcement by federal and state data protection authorities restricts personalization algorithm training data availability. Berlin and Munich production facilities supply original German-language content meeting domestic quota regulations in platform catalogs.
Japan
Aging demographic segments sustain cable-originated streaming adoption through legacy operator integrations in Tokyo and Osaka metropolitan areas. METI digital content distribution guidelines influence platform licensing transparency requirements. Kyoto animation production clusters specialize in family-oriented animated content with reduced localization complexity for Asian market export.
Global Svod Market Competitive Environment
Capability concentration sits with technology-integrated conglomerates possessing cloud infrastructure and e-commerce logistics ecosystems; scale advantage sits with pure-play streaming specialists commanding global subscriber bases and localized production pipelines. The vendor structure fragments across three strategic tiers: franchise IP holders leveraging exclusive studio libraries, technology platforms integrating streaming with broader subscription ecosystems, and regional specialists optimizing for single-market content quotas. Dominant competitive moves include bundle architecture convergence reducing churn through multi-service lock-in, and accelerated original production commitments satisfying domestic content mandates in regulated jurisdictions.
Within the pure-play streaming tier, Netflix and Disney+ exemplify divergent archetypes—one leveraging global production infrastructure across multiple continents, the other anchoring competitive position through exclusive franchise intellectual property and bundled service architectures. Amazon Prime Video occupies a distinct position integrating streaming with logistics and e-commerce subscription ecosystems. Among technology-integrated platforms, Apple TV+ represents the premium-originals archetype with focused catalog curation rather than volume-based content strategies.
| Leading Market Players |
|---|
| Netflix |
| Amazon Prime Video |
| Disney+ |
| Apple TV+ |
| Max |
| Paramount+ |
| Hulu |
| Google LLC |
| Cisco Systems |
| Others |
Value Chain & Pricing Dynamics
Hyderabad and Chennai production clusters anchor localized original content pipelines, translating regional talent density into pricing leverage for platforms negotiating exclusive regional catalogs against global competitors.
Pricing Analysis
Extended content licensing contracts drive lifetime subscriber value, with platforms monetizing through three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on concurrent stream allowances and 4K HDR resolution tiers. Cost compression in ad-supported tiers intensifies as Brazilian and Indian households rotate monthly between services. Emerging market consumers exhibit extreme price sensitivity while German subscribers tolerate premium uninterrupted experiences.
Supply Chain Analysis
Supplier-financing through extended production payment terms enables independent studios to sustain original content pipelines despite platform cash flow pressures. Content production concentrates in India, Brazil, and South Korea where localization talent clusters reduce dubbing costs. Raw material dependencies include cloud compute capacity, CDN bandwidth, and post-production software licensing. Single-source vulnerability sits with major cloud infrastructure providers. Distribution runs through direct-to-consumer applications and telecommunications bundle partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscriber acquisition economics follow cyclical recovery patterns as household discretionary entertainment spending rebounds from inflationary compression in key emerging markets.
For Market Incumbents: Pre-empt churn acceleration by deepening exclusive regional catalog investments in São Paulo and Mumbai production hubs. Lock in dubbing talent through multi-year service contracts before scarcity inflates localization costs. Defend against ad-supported tier erosion by bundling streaming with logistics and e-commerce subscription ecosystems.
For New Entrants and Emerging Players: Establish a beachhead in documentary and factual content segments where production overhead remains lower and shelf life extends monetization windows. Target educated European demographics demonstrating premium pricing tolerance for specialized catalogs. Deploy freemium conversion mechanics optimized for mobile-first Indian consumers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms with established edge-computing infrastructure and AV1 codec deployment capabilities. Long-term viability hinges on regulatory-aligned content moderation systems satisfying EU Digital Services Act transparency mandates. Monitor GDPR enforcement actions by CNIL and equivalent national regulators as churn sensitivity inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Original Content Production Scale-Up | Hyderabad and São Paulo facilities satisfy domestic quota regulations in India and Brazil. |
| Ad-Supported Tier Launch | Lower-price options capture price-sensitive households across Latin American and South Asian markets. |
| Localization Infrastructure Investment | Dubbing talent scarcity in high-growth language markets delays regional catalog rollouts. |
| Bundle Architecture Convergence | Integration with telecommunications and e-commerce ecosystems reduces subscriber churn through multi-service lock-in. |
| Edge-Computing Delivery Expansion | Peer-assisted streaming models reduce bandwidth costs and improve latency for live content experiences. |
Study Parameters
Operator-level perspectives from platform content strategy executives, localization production heads, telecommunications partnership directors, and regulatory compliance officers anchored the qualitative base. Primary intelligence combined with secondary validation against TRAI content moderation frameworks, ANVISA classification standards, SEC streaming platform filings, and EU Digital Services Act implementation guidance. Bottom-up subscriber modeling triangulated against top-down market sizing across the analysis window.
Scenario-bracketing framed projections across conservative, baseline, and expansion trajectories without discrete year anchoring. Segmentation dimensions modeled include content type, pricing architecture, distribution channel, and device ecosystem alongside regional regulatory cluster variations. CAGRs derived from subscriber growth run-rates, average revenue per user movements, and content cost inflation assumptions. Forecast inputs incorporated mobile penetration curves, broadband infrastructure deployment timelines, and domestic production quota compliance costs.
Stress conditions across GDPR enforcement intensity, emerging market currency volatility, and talent compensation inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding household discretionary spending recovery and platform consolidation timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Global Live Streaming Video Platform Market
Video Streaming (OTT) Services
Indonesia OTT Market
Video Streaming (OTT) Services
Global Over-The-Top Content Market
Video Streaming (OTT) Services
United States OTT Market
Video Streaming (OTT) Services
Sports Streaming Platform Market
Video Streaming (OTT) Services
Global Over-The-Top Market
Video Streaming (OTT) Services
Video Servers Market
Video Streaming (OTT) Services
Global Cloud Video Streaming Market
Video Streaming (OTT) Services
Subscription Video on Demand (Svod) Market
Video Streaming (OTT) Services
United States Online Video Platform Market
Video Streaming (OTT) Services
Asia Pacific Video Streaming Market
Video Streaming (OTT) Services
Streaming Services Market
Video Streaming (OTT) Services
Live Streaming Pay-Per-View Market
Video Streaming (OTT) Services
Global Transactional Video on Demand Market
Video Streaming (OTT) Services
OTT Content Market
Video Streaming (OTT) Services
Over the Top (OTT) Services Market