
 Video-On-Demand [Vod] Market | 2026-2036
Video-On-Demand [Vod] Market Size, Share, and Industry Trends Forecast 2026-2036
Video-On-Demand [Vod] Market Analytics
Platform unbundling is restructuring subscriber decision-making across the Video-On-Demand ecosystem. Netflix Inc. leverages its global production infrastructure to sustain original content pipelines across multiple languages. Amazon.com, Inc. anchors its streaming service within a broader Prime membership architecture, creating cross-subsidized retention mechanics. Apple Inc. differentiates through premium device-software integration, controlling playback quality standards across its hardware ecosystem.
Video-on-demand denotes a digital content distribution system enabling users to select and view video programming at self-determined times via internet protocol delivery, typically employing adaptive bitrate streaming protocols to maintain playback continuity across variable bandwidth conditions. The technology serves commercial entertainment consumption, educational programming, and corporate training applications. Subscription delivery models dominate revenue generation, while ad-supported tiers capture price-sensitive demographics and expand total addressable audience pools. Smart TV device penetration concentrates viewing hours in living-room environments, shifting advertising value toward connected television inventory. Bundled offerings that combine multiple streaming services under unified billing are emerging as a structural response to subscription fatigue.
The Federal Communications Commission enforces closed-captioning accessibility standards and net neutrality principles that affect streaming quality of service. The European Union's Digital Services Act and Audiovisual Media Services Directive impose content moderation duties and territorial licensing requirements that reshape catalog availability across member states. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs fragment platform economics and influence content investment allocation.
Market Dynamics
Direct-to-consumer streaming is collapsing theatrical release windows and fragmenting content licensing across exclusive platform silos. Studios now prioritize subscriber retention metrics over box office revenue, forcing distributors to rebuild acquisition strategies around binge-release formats and algorithmic recommendation engines.
Growth Catalysts
- EU Digital Services Act:The regulation mandates transparency in content recommendation systems and strengthens creator compensation frameworks, compelling platforms to invest in original European productions.
- Smart TV penetration:Connected television devices concentrate viewing hours in living-room environments, shifting advertising inventory value toward addressable TV formats.
- Adaptive bitrate streaming:The technology maintains playback continuity across variable bandwidth conditions, enabling reliable service delivery in emerging markets with infrastructure constraints.
Market Restraints
- Content cost inflation:Original programming budgets strain platform economics as talent and production expenses escalate across major production hubs.
- Subscriber acquisition costs:Marketing expenditures concentrate in saturated markets where churn rates compress lifetime value calculations.
- Cross-border licensing friction:Territorial rights fragmentation under EU Audiovisual Media Services Directive limits catalog uniformity across member states.
Strategic Opportunities
- Ad-supported tier expansion:Lower-price subscription options capture price-sensitive demographics previously excluded from paid streaming ecosystems.
- Educational content verticals:Institutional licensing agreements with universities and corporate training departments open B2B revenue streams.
- Cloud gaming convergence:Integration of interactive entertainment formats creates hybrid consumption platforms spanning passive and active engagement modes.
Industry Challenges
- Content moderation scale:Platform-scale review of user-generated uploads strains operational resources under expanding regulatory mandates.
- Legacy system integration:Established broadcasters face technical debt when migrating linear scheduling infrastructure to on-demand architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video-On-Demand [Vod] Market |
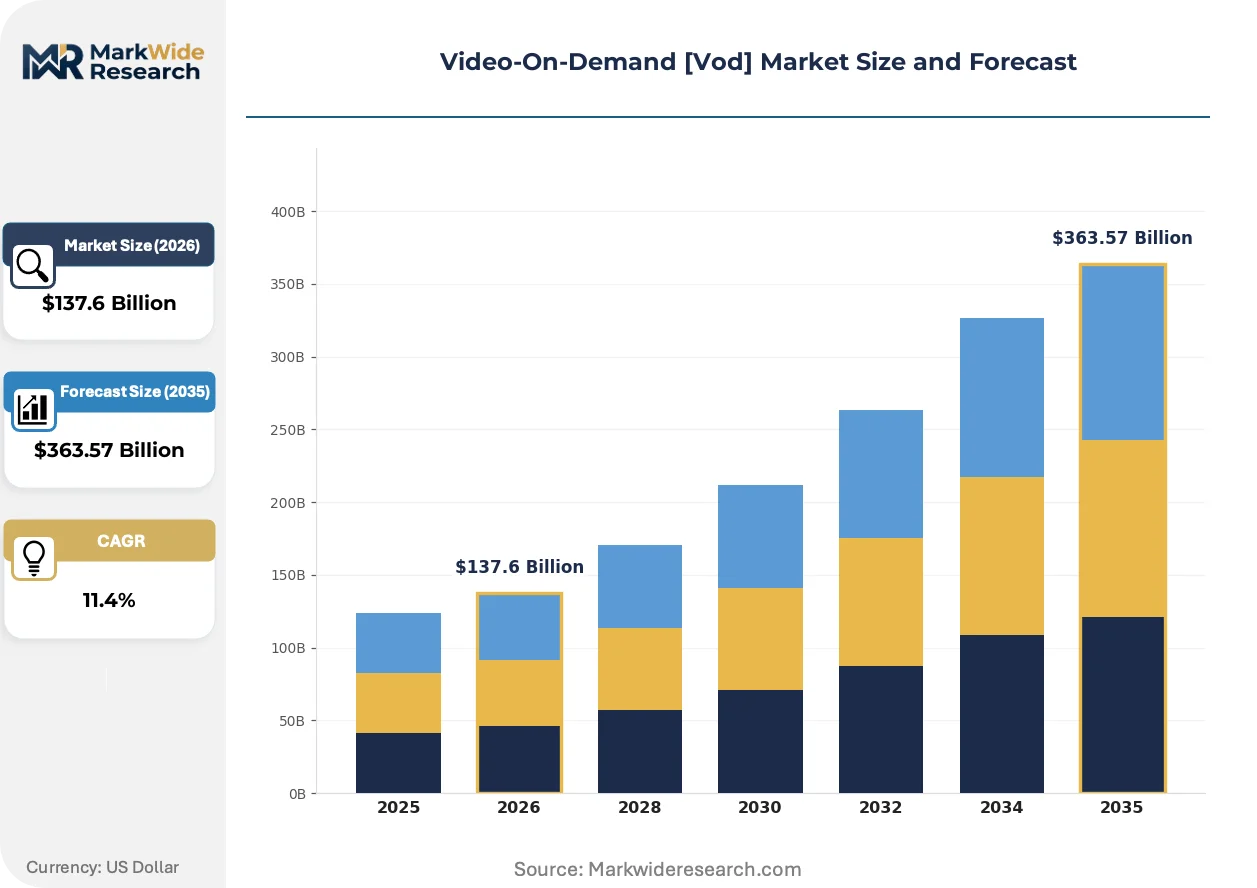
| Market Size in 2026 | $137.6 Billion |
| Market Size in 2035 | $363.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Movies, TV Shows, Documentaries, Sports Delivery Model: Subscription, Transactional, Ad-Supported, Bundled Device Type: Smart TVs, Smartphones, Tablets, Set-Top Boxes User Demographics: Adults, Children, Seniors, Families |
| Companies Covered | Netflix Inc., Amazon.com, Inc., The Walt Disney Company, Warner Bros. Discovery, Inc., Alphabet Inc., Apple Inc., Comcast Corporation, Paramount Global, Roku, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video-On-Demand [Vod] Market Evolving Landscape
Algorithmic personalization engines are restructuring how content surfaces to viewers, replacing editorial curation with predictive engagement models. This shift compresses discovery friction while concentrating consumption around platform-owned intellectual property.
AV1 codec compression is overtaking legacy H.264 standards in premium streaming deployments. The royalty-free format reduces bandwidth requirements by thirty-five percent at equivalent visual quality. Major platform operators in North America and Western Europe have accelerated migration timelines. The transition is overtaking infrastructure upgrade cycles and forcing CDN providers to reconfigure edge server configurations.
The EU's Audiovisual Media Services Directive imposes content quota obligations requiring thirty percent European works in on-demand catalogs. Member state regulators enforce graduated penalties for non-compliance. Smaller platforms with limited original production capacity face catalog restructuring costs, while established studios leverage existing European content libraries to satisfy mandates without incremental investment.
Subscription bundling arrangements are displacing standalone service commitments as households manage platform proliferation. Retail and telecommunications channels aggregate multiple streaming subscriptions under unified billing relationships. This consolidation is most visible in United States and United Kingdom markets where average household subscription counts peaked and began contracting.
Video-On-Demand [Vod] Market Segmentation
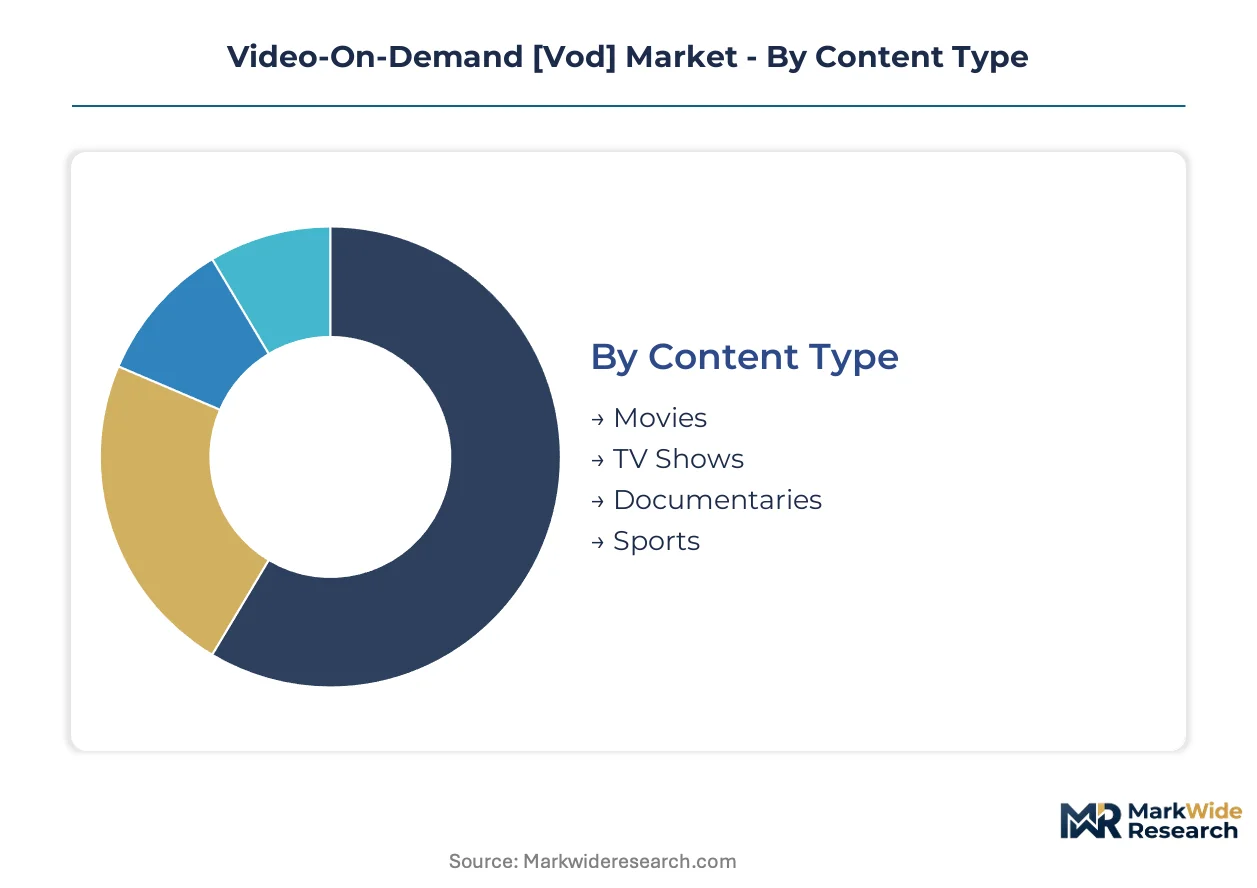
Segmentation reveals how Video-On-Demand platforms allocate content investment and technical infrastructure across distinct consumption patterns. Each dimension—content, delivery mechanism, device, and audience—shapes pricing architecture and retention mechanics differently.
Content Type:
Content categories differ in production cost intensity and licensing complexity, with some functioning as standalone subscriber acquisition tools while others embed within broader entertainment ecosystems.
- Movies:Theatrical window collapse has shifted blockbuster releases directly to streaming platforms, with studios prioritizing day-and-date availability to maximize subscriber acquisition in competitive markets. Major franchises concentrate viewing hours during opening weekends, driving infrastructure scaling requirements for peak load management.
- TV Shows:Serialized episodic formats dominate total viewing time and enable sustained engagement through binge-release or weekly drop strategies. European platforms invest heavily in local-language series to satisfy AVMSD quota obligations while building regional subscriber bases.
- Documentaries:Lower production costs attract niche audience segments with strong demographic targeting value for advertisers.
- Sports:Live event rights command premium pricing and require specialized low-latency streaming infrastructure.
TV Shows lead volumes today; Sports is gaining share fastest.
Delivery Model:
Revenue architecture separates into recurring commitment, one-time purchase, advertising-supported, and aggregated access structures, each demanding distinct customer relationship management and technology stacks.
- Subscription:Recurring revenue models dominate platform economics, with tiered pricing separating premium 4K/HDR streams from standard-definition access. Netflix and Amazon Prime anchor this segment through global content pipelines and cross-subsidized membership benefits.
- Transactional:Electronic sell-through and rental models capture windowing revenue for theatrical releases before subscription availability. Disney and Warner Bros. Discovery leverage this channel to extract maximum per-title value from franchise properties.
- Ad-Supported:Lower-price tiers expand addressable audiences among price-sensitive demographics, with connected TV inventory commanding premium CPM rates.
- Bundled:Telecommunications and retail channels aggregate multiple services under unified billing to combat subscription fatigue.
Subscription leads volumes today; Ad-Supported is expanding most quickly.
Device Type:
Hardware penetration patterns determine encoding strategies, with living-room environments favoring high-bitrate streams while mobile consumption prioritizes efficiency and offline caching.
- Smart TVs:Connected television devices concentrate advertising value through addressable formats and premium brand-safe inventory. Samsung and LG operating systems function as platform gatekeepers, extracting carriage fees and data-sharing agreements from streaming services.
- Smartphones:Mobile-first consumption dominates emerging markets with limited fixed broadband infrastructure, requiring aggressive compression and adaptive bitrate protocols.
- Tablets:Portable larger screens serve travel and secondary-room viewing with intermediate quality requirements.
- Set-Top Boxes:Legacy cable and satellite hardware bridges linear and on-demand consumption for older demographic segments.
Smart TVs lead volumes today; Smartphones are climbing the fastest.
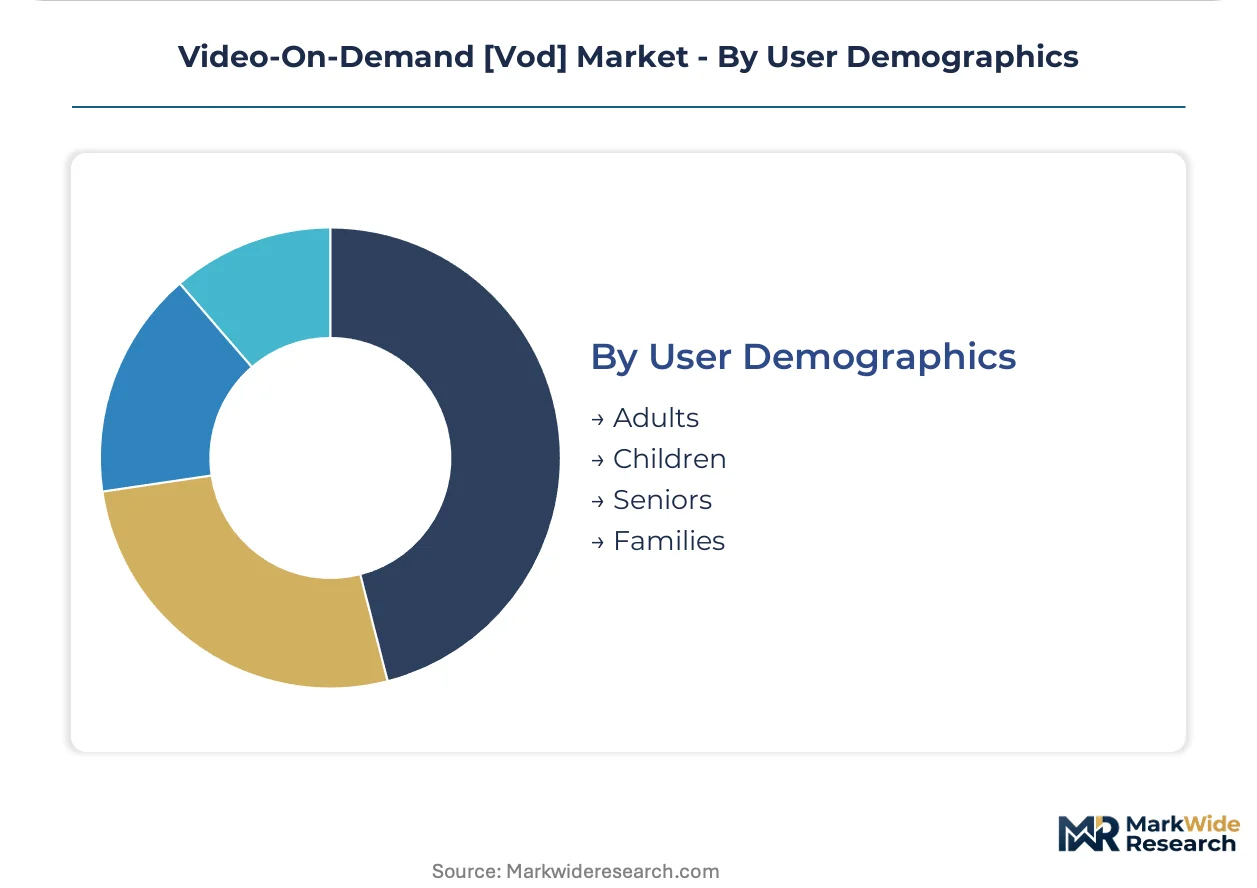
User Demographics:
Audience segmentation shapes content rating systems, parental control features, and recommendation algorithm training data, with family co-viewing driving the largest platform investments.
- Families:Multi-generational co-viewing commands the largest content budgets, with platforms expanding kids' verticals and parental control infrastructure to capture household decision-making. Disney+ and Netflix invest disproportionately in animation and family-friendly originals.
- Adults:The 18-49 demographic drives subscription revenue concentration and prestige original programming greenlights.
- Children:Dedicated profiles and content verticals build early brand loyalty with long lifetime value implications.
- Seniors:Underpenetrated segments require simplified interfaces and larger text accessibility features.
Families lead volumes today; Seniors are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Video-On-Demand industry traces its commercial origins to the United States, where cable operators first deployed digital distribution infrastructure in the late 1990s. This technological lineage established North American regulatory frameworks and business models that subsequently diffused to Europe and Asia-Pacific markets.
United States
Studio consolidation around direct-to-consumer streaming and the collapse of theatrical windows concentrate investment in Los Angeles and New York production clusters. The Federal Communications Commission enforces closed-captioning accessibility standards and net neutrality principles affecting streaming quality of service. Silicon Valley technology firms anchor adaptive bitrate streaming innovation, while Atlanta hosts expanding original content production facilities serving multiple platform operators.
United Kingdom
London-based creative industries supply premium scripted content to global platforms, with British productions commanding disproportionate international licensing value. Ofcom implements the Audiovisual Media Services Directive's thirty percent European content quota alongside domestic public service broadcasting obligations. Manchester and Birmingham emerge as secondary production hubs as platforms decentralize original programming investment beyond the capital.
Germany
Europe's largest consumer market sustains robust demand for local-language original series and sports rights acquisitions. The Commission for Youth Media Protection enforces content rating systems and parental control mandates under federal media law. Berlin and Munich host competing platform engineering centers, with Cologne concentrating sports streaming infrastructure development.
India
Mobile-first consumption patterns and aggressive pricing tiers expand addressable audiences across tier-two and tier-three cities. The Telecom Regulatory Authority of India governs net neutrality and content delivery network interconnection frameworks affecting streaming quality. Mumbai anchors Bollywood content licensing while Bengaluru houses technical operations for multiple international platform subsidiaries.
South Korea
K-drama and K-pop content verticals generate exceptional export demand across Southeast Asian and Latin American markets. The Korea Communications Commission regulates content classification and platform competition under the Broadcasting Communications Development Act. Seoul's Gangnam district concentrates platform headquarters and original production investment, with Busan hosting specialized post-production facilities.
Video-On-Demand [Vod] Market Competitive Landscape
Premium-margin players sit above commodity-margin players across content investment intensity and subscriber lifetime value dimensions. The market structure consolidates around global platforms with diversified revenue architectures and regional specialists with localized content advantages. Three archetypes dominate: vertically integrated studios with legacy intellectual property libraries, technology-platform operators with hardware-software ecosystems, and telecommunications carriers with bundled distribution channels. Competitive dynamics center on exclusive content acquisition and cross-platform bundling arrangements that reduce subscriber churn.
Among technology-platform operators, Netflix Inc., Amazon.com, Inc., and Apple Inc. occupy distinct positioning vectors within the competitive landscape. Netflix exemplifies the pure-play streaming archetype with global original production infrastructure. Amazon represents the cross-subsidized membership model where streaming services anchor broader retail ecosystem retention. Apple sits within the premium hardware-integrated tier, controlling playback quality standards across its device ecosystem. These three entities illustrate how divergent parent-company economics produce heterogeneous competitive strategies despite converging on similar subscriber-facing value propositions.
| Leading Market Players |
|---|
| Netflix Inc. |
| Amazon.com, Inc. |
| The Walt Disney Company |
| Warner Bros. Discovery, Inc. |
| Alphabet Inc. |
| Apple Inc. |
| Comcast Corporation |
| Paramount Global |
| Roku, Inc. |
| Others |
Value Network & Pricing Analysis
Subscriber consolidation around bundled offerings is forcing platforms to restructure content acquisition economics and compress profit margins across mid-tier service tiers. This demand-side pressure cascades into supply chain recalibration as studios prioritize direct-to-consumer streaming over legacy licensing windows.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates 4K/HDR streaming from standard-definition access and ad-supported entry points. Price differentiation rests on content exclusivity and device integration depth, with Apple commanding hardware-software premiums while Amazon cross-subsidizes through retail membership. Cost compression in ad-supported tiers is intensifying because inventory oversupply depresses CPM rates. Price-sensitive households in emerging markets exhibit highest elasticity, while premium subscribers in North America show lowest sensitivity to annual increases.
Supply Chain Analysis
Technical talent scarcity in Los Angeles, London, and Seoul is constraining original production capacity and inflating above-the-line costs for exclusive content. Geographic supply concentration centers on these three production clusters, with post-production workflows drawing from specialized facilities in Vancouver and Sydney. Raw material dependencies span cloud compute infrastructure, CDN edge server networks, and licensed intellectual property catalogs. Single-source vulnerability in major franchise rights creates renewal risk during competitive bidding cycles. Distribution runs through telecommunications carriers, smart TV operating systems, and direct app store relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where production cost differentials between Los Angeles and Atlanta, combined with regulatory quota advantages in European co-production treaties, reward footprint diversification.
For Market Incumbents: Acquire exclusive sports rights and live event franchises to differentiate from algorithmic recommendation competitors. Secure backward integration into post-production facilities in lower-cost geographies to offset talent inflation. Defensive moves must address churn acceleration from bundled telecommunications offerings and ad-supported tier proliferation. For New Entrants and Emerging Players: Capture educational content verticals and institutional licensing agreements with universities and corporate training departments. White-space concentration sits in B2B subscription models and niche language markets underserved by global platforms. Go-to-market execution should emphasize API-first integration with learning management systems. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists possessing localized content libraries and existing AVMSD quota compliance. Long-term viability favors platforms with diversified revenue architectures spanning advertising, subscription, and transactional windows. Monitor sports rights renewal cycles and franchise exclusivity expirations as inflection indicators for competitive position shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Original Content Pipeline Expansion | European co-production treaties satisfy AVMSD quotas while accessing regional talent subsidies. |
| Ad-Supported Tier Infrastructure | Connected TV inventory integration captures addressable advertising budgets shifting from linear broadcast. |
| Cloud Gaming Convergence | Interactive entertainment hybrids expand engagement metrics beyond passive consumption hours. |
| Educational Vertical Development | Institutional licensing opens recurring B2B revenue streams with lower churn characteristics. |
| Smart TV Operating System Partnership | Samsung and LG carriage agreements secure living-room device gatekeeper positioning. |
Research Methodology
Direct dialogue with platform content executives, CDN infrastructure engineers, regulatory affairs specialists, and telecommunications bundling managers grounded qualitative findings. Secondary validation drew from FCC filing databases, EU regulatory implementation notices, SEC streaming segment disclosures, and smart TV manufacturer shipment reports. Bottom-up subscriber and revenue modeling triangulated against top-down market sizing from production investment tracking.
Segmented volume and value trajectories emerged from cross-referencing content type, delivery mechanism, device category, and demographic dimensions across the projection horizon. CAGRs derived from historical platform subscriber curves, content spend intensity ratios, and regional broadband penetration elasticities. Forecast inputs incorporated AVMSD quota compliance costs, adaptive bitrate streaming infrastructure deployment cycles, and sports rights auction dynamics.
Regulatory enforcement divergence, franchise exclusivity renewal outcomes, and macroeconomic subscription elasticity are the dominant revision risks to modeled trajectories. Forecasts reflect documented assumptions about content cost inflation trajectories and bundling partnership structures. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Global Live Streaming Video Platform Market
Video Streaming (OTT) Services
Global Over-The-Top Content Market
Video Streaming (OTT) Services
Video Streaming Market
Video Streaming (OTT) Services
Global Transactional Video on Demand Market
Video Streaming (OTT) Services
Video on Demand Market
Video Streaming (OTT) Services
Asia Pacific Video Streaming Market
Video Streaming (OTT) Services
Global Over-The-Top Market
Video Streaming (OTT) Services
Global Svod Market
Video Streaming (OTT) Services
Streaming Spending Market
Video Streaming (OTT) Services
United States OTT Market
Video Streaming (OTT) Services
Streaming Media Services Market
Video Streaming (OTT) Services
Online Video Platform Market
Video Streaming (OTT) Services
Subscription Video on Demand (Svod) Market
Video Streaming (OTT) Services
Global Cloud Video Streaming Market
Video Streaming (OTT) Services
India Smart TV and OTT Market
Video Streaming (OTT) Services
United States Online Video Platform Market