
 E-Sports and Games Streaming Market | 2026-2036
E-Sports and Games Streaming Market Size, Share, and Industry Trends Forecast 2026-2036
E-Sports and Games Streaming Market Foresight
Cloud-native streaming architecture is rewriting how competitive gaming content reaches audiences, replacing legacy broadcast pipelines with edge-compute delivery networks. Twitch leverages its first-mover infrastructure to dominate live esports viewership in North America and Europe. Huya anchors its position through deep integration with Chinese mobile gaming ecosystems and proprietary tournament IP. NVIDIA Corporation differentiates via GPU-accelerated encoding that reduces stream latency for competitive broadcasts.
E-sports and games streaming encompasses the live and on-demand distribution of competitive video gaming content through internet-connected platforms, typically requiring sub-100ms latency for real-time audience interaction and 1080p60 minimum resolution for professional tournament broadcasts. The primary commercial purpose is to monetize aggregated attention through advertising, subscriptions, and virtual goods sales while building franchise value for game publishers. Mobile platforms represent the fastest-expanding segment as smartphone-native audiences in Asia-Pacific markets shift consumption from traditional broadcast to app-based streaming. Subscription monetization captures the most stable revenue pools where platforms like YouTube Gaming and Twitch retain recurring payments for ad-free viewing and exclusive content access.
The Federal Communications Commission shapes bandwidth allocation rules that directly affect streaming quality obligations for US-based platforms, while China's Ministry of Industry and Information Technology enforces content licensing requirements that govern tournament broadcast permissions. South Korea's Korea Communications Commission mandates specific infrastructure standards for esports-dedicated venues. Stakeholders must monitor how evolving data localization requirements across these jurisdictions affect cross-border tournament streaming rights and latency guarantees.
Market Dynamics
Cloud-native streaming infrastructure is hybridizing with edge-compute delivery networks, compressing latency thresholds below 50ms and forcing tournament broadcasters to abandon legacy satellite distribution models entirely.
Growth Catalysts
- 5G Network Rollouts:South Korea's Ministry of Science and ICT mandates sub-10ms latency standards for esports-dedicated venues, enabling real-time audience interaction at scale.
- Mobile Gaming Ecosystems:Smartphone-native audiences across Southeast Asia shift consumption from traditional broadcast to app-based streaming, expanding addressable viewership pools.
- Government-Backed Infrastructure:China's MIIT content licensing requirements normalize competitive gaming as mainstream entertainment through dedicated television channels and stadium construction.
Market Restraints
- Bandwidth Cost Volatility:Peering agreement disputes between Tier-1 internet backbone providers in the United States create unpredictable transit pricing for 4K/8K tournament streams.
- Supply Concentration Risk:GPU-accelerated encoding hardware relies on foundry capacity concentrated in Taiwan, exposing broadcasters to geopolitical supply disruptions.
- Data Localization Mandates:Russia's sovereign internet laws and China's cybersecurity regulations fragment cross-border tournament streaming rights into jurisdiction-locked silos.
Strategic Opportunities
- Underpenetrated Latin American Markets:Brazil's ANATEL spectrum allocations for fixed wireless access create first-mover openings for Portuguese-language esports broadcasting infrastructure.
- Cloud Gaming Convergence:Integration of interactive betting layers with live streams opens new monetization channels for tournament organizers in regulated European markets.
- India's Digital Infrastructure Push:TRAI's net neutrality frameworks and cheap data pricing enable mobile-first esports consumption among 600 million smartphone users.
Industry Challenges
- Broadcast Engineering Talent Scarcity:Real-time video pipeline optimization for sub-100ms latency requires specialized skills concentrated among Silicon Valley and Seoul engineering clusters.
- Cross-Platform Integration Complexity:Synchronizing chat, betting, and social features across Twitch, YouTube Gaming, and proprietary apps demands expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Sports and Games Streaming Market |
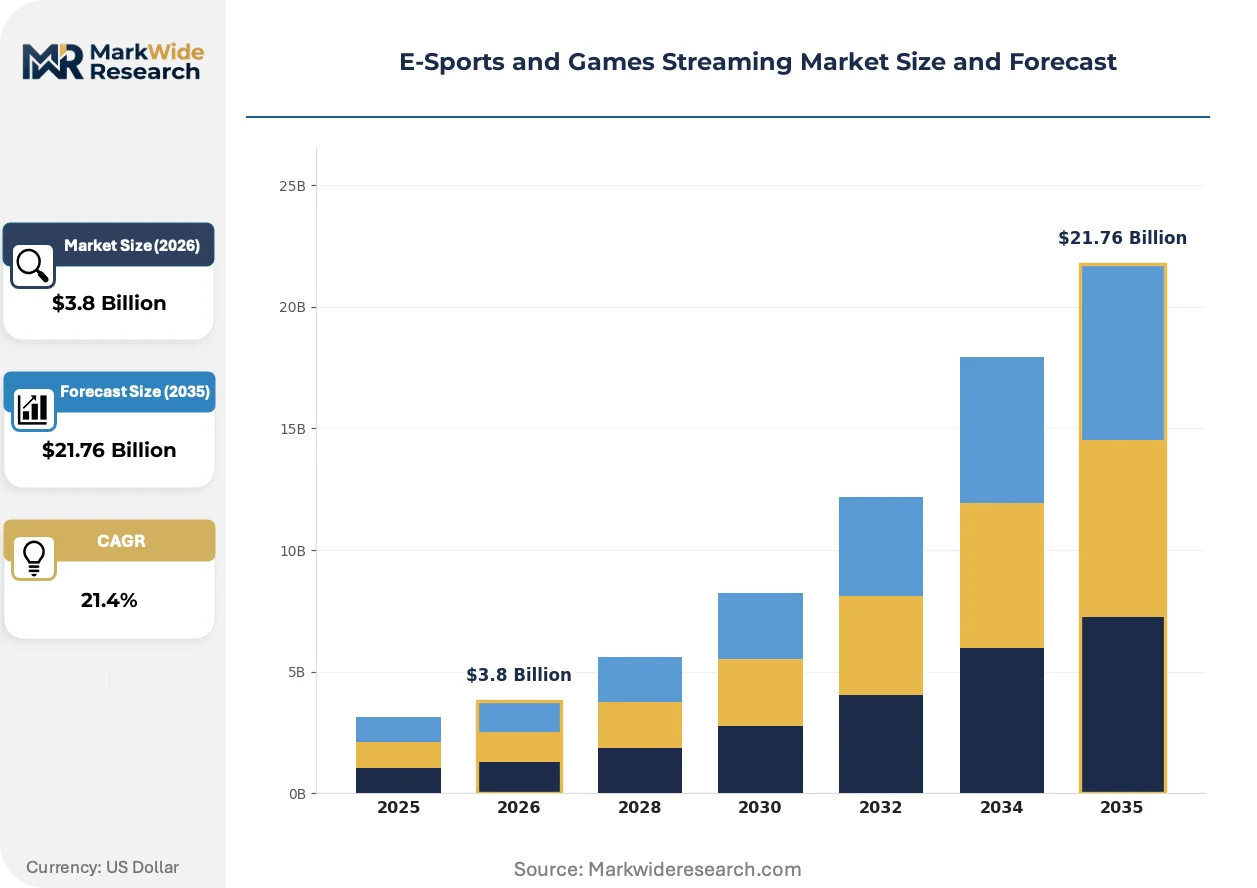
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $21.76 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: PC, Console, Mobile, Cloud Content Type: Live Events, Tournaments, On-Demand, User-Generated Monetization Model: Subscription, Ad-Supported, Pay-Per-View, Donations Viewer Demographics: Gen Z, Millennials, Casual Gamers, Hardcore Gamers |
| Companies Covered | Twitch, YouTube Gaming, Facebook Gaming, Huya, Douyu, Tencent Holding Limited, Valve Corporation, Electronic Arts Inc, NVIDIA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Sports and Games Streaming Market Shifts & Advancements
Interactive streaming technologies are compressing the distance between spectator and competitor, transforming passive viewership into participatory revenue streams through real-time wagering and co-streaming features.
WebRTC-based low-latency protocols are hybridizing with traditional HLS delivery stacks, enabling broadcasters to serve both interactive betting audiences and conventional viewers from unified infrastructure. Esports tournament organizers in Malta and Isle of Man licensing jurisdictions adopt these hybrid pipelines first, compressing time-to-market for real-time engagement features by 40% versus rebuild approaches.
The FCC's 2023 spectrum reallocation orders for the 6GHz band expand unlicensed capacity for venue-scale wireless production, reducing cabling costs for temporary tournament installations. Broadcasters operating under these rules now deploy fully wireless camera arrays in NBA-scale arenas, though European counterparts await ETSI harmonization before equivalent rollouts.
Co-streaming culture shifts viewer loyalty from platforms to individual creators, fragmenting audience aggregation economics. Brazilian and Mexican Portuguese-language streamers on YouTube Gaming capture tournament viewership that previously centralized on Twitch, rotating advertising spend toward creator-direct sponsorship models rather than platform media buys.
E-Sports and Games Streaming Market Segmentation
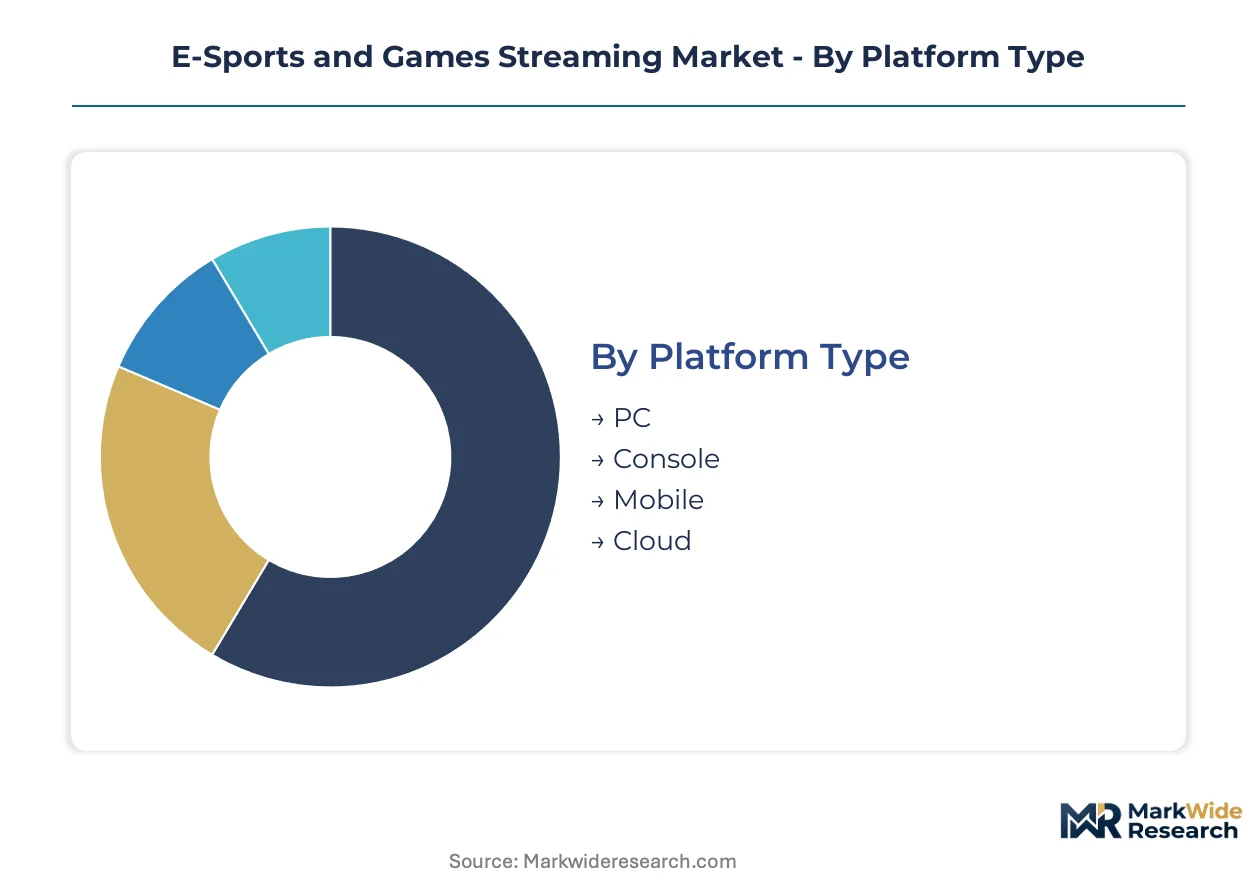
Platform architecture determines latency budgets and encoding requirements for competitive gaming broadcasts. Content format shapes monetization velocity and audience retention curves. Viewer cohorts concentrate purchasing power differently across virtual goods and subscription tiers.
Platform Type:
Cost tier stratification separates premium hardware investments from mass-market accessibility plays across the streaming value chain.
- PC:Desktop platforms deliver 240Hz capture pipelines and uncompressed RGB feeds for professional tournament broadcasts. Demand concentrates in South Korea and Germany where gaming cafe cultures sustain dedicated spectator venues and LAN infrastructure investments drive subscription attach rates.
- Console:PlayStation and Xbox ecosystems lock streaming distribution behind proprietary network stacks with 1080p60 output caps. Sony's PlayStation Network and Microsoft's Xbox Live capture recurring subscription revenue through integrated tournament pass sales in the United States and United Kingdom markets.
- Mobile:Smartphone-native streaming operates on H.265 hardware encoding with adaptive bitrate ceilings at 720p60 for thermal-constrained devices. Southeast Asian markets in Indonesia and Vietnam rotate consumption toward app-based platforms as fixed broadband penetration lags mobile data ubiquity.
- Cloud:Remote rendering pipelines eliminate local hardware requirements through NVIDIA GeForce Now and Xbox Cloud Gaming infrastructure. Latency-sensitive competitive titles face deployment constraints in markets without edge node presence.
PC holds installed capacity. Mobile is rotating up the share rankings.
Content Type:
Application format dictates production cost structures and advertising yield differential between scheduled programming and ambient user feeds.
- Live Events:Single-session broadcasts of publisher showcases and season launches require redundant ingest paths and failover switching. Electronic Arts and Riot Games anchor sponsorship commitments around tentpole reveals in Los Angeles and Seoul production facilities.
- Tournaments:Multi-day bracket competitions deploy observer clients and augmented reality overlays for narrative packaging. The League of Legends World Championship and The International Dota 2 championship concentrate viewership spikes that strain CDN capacity in European and North American evening timezones.
- On-Demand:Edited highlight packages and VOD libraries extend content half-life through algorithmic recommendation surfacing. YouTube Gaming's archive infrastructure captures long-tail search traffic for tutorial and post-match analysis content.
- User-Generated:Unaffiliated streamer content operates on lower production values with higher chat interactivity density. Twitch's co-streaming permissions for major events fragment audience aggregation toward individual creator channels.
Tournaments command premium CPMs. User-Generated is climbing the fastest on total hours consumed.
Monetization Model:
Customer payment behavior separates predictable recurring revenue from transaction-dependent advertising volatility.
- Subscription:Monthly fee structures on Twitch Turbo and YouTube Premium Gaming remove advertising loads and enable exclusive badge cosmetics. South Korean consumers demonstrate highest willingness-to-pay for ad-free tournament viewing through dedicated esports platform memberships.
- Ad-Supported:Pre-roll and mid-roll inventory on free tiers captures brand budget from endemic gaming peripherals and non-endemic automotive advertisers. Supply path optimization challenges persist around programmatic insertion for live content with unpredictable duration.
- Pay-Per-View:One-time access fees for championship finals and closed beta reveals test price elasticity among hardcore fan segments. UFC and WWE crossover events in the United States market validate premium pricing for hybrid entertainment-gaming spectacles.
- Donations:Direct creator payments through Bits and Super Chat mechanisms bypass platform revenue shares. Brazilian and Mexican Portuguese-language streamers on YouTube Gaming rotate monetization toward fan-funded models as regional advertising CPMs lag North American benchmarks.
Subscription holds installed capacity. Ad-Supported is rotating up the share rankings.
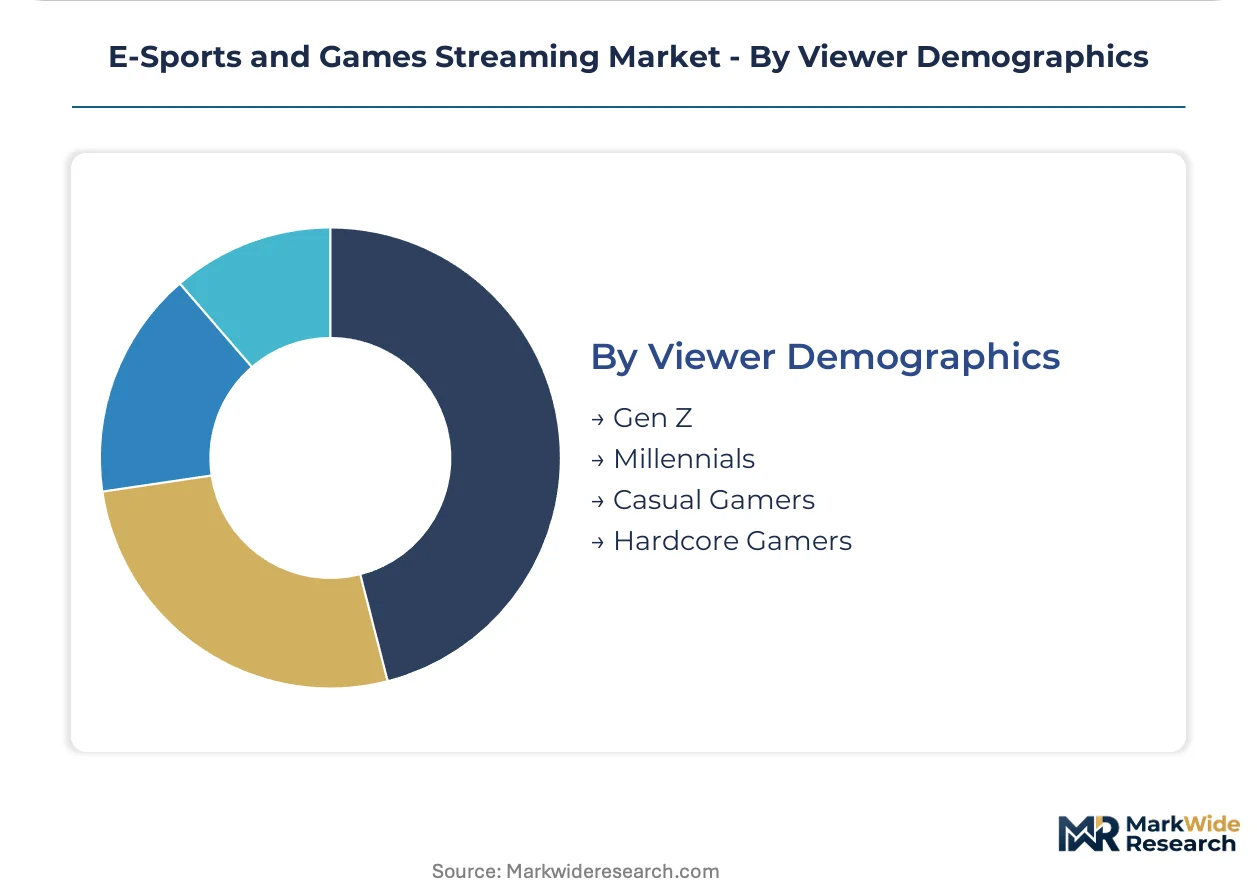
Viewer Demographics:
Audience maturity segments separate established purchasing power from emerging lifetime value accumulation curves.
- Gen Z:Cohorts aged 12-27 demonstrate platform-native navigation with minimal friction toward mobile-first consumption. Indian smartphone users in this bracket concentrate engagement on Loco and Rooter as domestic alternatives to global platforms.
- Millennials:Viewers aged 28-43 sustain higher average revenue per user through subscription stacking and merchandise purchases. Parenting status in this demographic shifts viewing patterns toward condensed highlight formats over live session commitment.
- Casual Gamers:Irregular play patterns correlate with event-driven tournament viewing rather than habitual stream consumption. Mobile-exclusive titles like Garena Free Fire in Southeast Asia capture this segment through low-barrier competitive formats.
- Hardcore Gamers:Daily play commitment above two hours predicts simultaneous streaming consumption and premium virtual goods expenditure. PC and console tournament viewership concentrates overwhelmingly in this segment across German and South Korean markets.
Millennials hold installed capacity. Gen Z is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea exports live tournament broadcast infrastructure to Southeast Asian markets while importing cloud encoding hardware from Taiwan and the United States. Content licensing agreements flow from Chinese platforms into Vietnamese and Indonesian distribution networks. Tournament production talent migrates from Seoul and Los Angeles toward emerging venues in São Paulo and Mumbai.
United States
Cloud gaming infrastructure investments and collegiate esports scholarship programs drive platform expansion across university networks. The Federal Communications Commission's 6GHz spectrum reallocation enables wireless production arrays in NBA-scale tournament venues. Los Angeles anchors premium broadcast production with Riot Games and Electronic Arts operating flagship studios for tentpole event coverage.
South Korea
Government-backed esports stadium construction and dedicated television channel licensing normalize competitive gaming as mainstream entertainment. The Korea Communications Commission mandates sub-10ms latency standards for venue-scale wireless infrastructure. Seoul's Gangnam district concentrates production facilities where OBS client optimization and augmented reality overlay development occur.
China
Mobile-native streaming consumption and proprietary tournament intellectual property expansion dominate platform strategy. The Ministry of Industry and Information Technology enforces content licensing requirements that govern cross-border broadcast permissions. Shenzhen and Hangzhou host engineering clusters where H.265 hardware encoding and adaptive bitrate algorithms receive continuous refinement.
Brazil
Portuguese-language creator ecosystems and fixed wireless access spectrum allocations create infrastructure investment openings. ANATEL's regulatory frameworks for 5G fixed wireless enable low-latency tournament streaming outside fiber-served metro cores. São Paulo's Pinheiros district emerging as a production hub where local talent agencies negotiate creator-direct sponsorship models.
Germany
Gaming cafe cultures and LAN infrastructure investments sustain dedicated spectator venue networks. ETSI harmonization timelines for 6GHz unlicensed spectrum delay wireless production array deployments relative to US counterparts. Cologne's ESL Gaming facility anchors European tournament production with redundant ingest paths for multi-day bracket competitions.
E-Sports and Games Streaming Market Competitive Landscape
Channel-controlling players compete with product-specialist players for audience aggregation and encoding technology dominance. The market structure concentrates around three to five platforms capturing majority viewership hours while dozens of regional specialists fragment remaining share. Two strategic archetypes dominate: infrastructure-integrated platforms owning distribution and encoding stacks, and content-licensed specialists operating on rented cloud capacity. Competitive moves center on exclusive tournament broadcast rights acquisitions and edge-compute node geographic expansion.
Within the infrastructure-integrated tier, Twitch and YouTube Gaming exemplify platform archetypes that combine audience aggregation with proprietary delivery networks. NVIDIA Corporation occupies a position representing hardware-accelerated encoding specialization for broadcast latency reduction. Huya anchors the mobile-integrated specialist category with deep ecosystem ties to smartphone gaming distribution. These three entities collectively illustrate how competitive positioning stratifies between global reach and regional ecosystem capture.
| Leading Market Players |
|---|
| Twitch |
| YouTube Gaming |
| Facebook Gaming |
| Huya |
| Douyu |
| Tencent Holding Limited |
| Valve Corporation |
| Electronic Arts Inc |
| NVIDIA Corporation |
| Others |
Supply & Pricing Matrix
Trans-Pacific fiber routes carry the bulk of live tournament traffic between Seoul production facilities and Los Angeles distribution nodes, with per-gigabit transit costs compressing margins on 4K broadcast tiers while concentrating pricing power among Tier-1 backbone providers. This corridor's cost dynamics force tournament organizers to tier service offerings around latency guarantees, with premium sub-50ms feeds commanding substantial markups over standard 200ms HLS delivery.
Pricing Analysis
Current-generation H.265 hardware encoding commands premium positioning against prior-gen H.264 software pipelines and emerging AV1 next-gen trials. Three-tier pricing structure across premium, standard, and economy levels segments broadcasters by resolution-latency bundles, with quality grade and geographic delivery cost as primary differentiation drivers. Pricing pressure stems from bandwidth cost volatility in peering disputes, squeezing margins on ad-supported tiers. Mobile-first Southeast Asian platforms demonstrate highest price sensitivity, while South Korean dedicated esports venues show lowest sensitivity due to government infrastructure subsidies.
Supply Chain Analysis
Upstream GPU-accelerated encoding hardware feeds from Taiwan foundry capacity, South Korean memory fabrication, and United States fabless design houses. Raw material dependencies include advanced node silicon wafers, high-bandwidth memory stacks, and specialized video codec IP cores. Single-source vulnerability concentrates in Taiwan's leading-edge foundry capacity, exposing broadcasters to geopolitical disruption. Distribution runs through cloud hyperscaler marketplaces and direct OEM procurement for venue-scale installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based platform memberships represent a service-attach opportunity expanding faster than hardware-dependent advertising tiers, with recurring revenue pools capturing stable cash flows as tournament viewership fragments across creator-direct models.
For Market Incumbents: Build exclusive tournament IP moats through multi-year publisher partnerships that lock competitor access to tentpole events like League of Legends World Championship and The International. Defend against co-streaming fragmentation by integrating betting and social layers directly into proprietary apps, while adding edge-compute capacity in São Paulo and Mumbai to reduce latency for emerging market expansion. For New Entrants and Emerging Players: Latin American fixed wireless access zones offer geographic underpenetration with ANATEL spectrum allocations enabling low-latency infrastructure outside fiber-served metros. Target Portuguese-language creator ecosystems in Brazil's Pinheiros district through direct sponsorship models, bypassing platform media buys. Deploy WebRTC-based hybrid pipelines first in Malta-licensed betting jurisdictions to compress time-to-market for interactive features. For Investors and Strategic Acquirers: Carve-out targets emerge from telecommunications carriers with underutilized 5G network slicing capacity and dormant esports venue investments. Long-term viability hinges on platforms controlling both encoding technology and audience aggregation, with vertical integration into edge infrastructure as the durable model. Watch for FCC 6GHz harmonization signals in Europe as inflection indicator for wireless production array adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Compute Node Expansion | Deploys NVIDIA GPU clusters in São Paulo and Mumbai to compress latency below 50ms for tournament broadcasts. |
| Exclusive Tournament IP Acquisition | Locks multi-year broadcast rights for Riot Games and Valve Corporation tentpole events against competitor access. |
| Interactive Betting Layer Integration | Opens Malta and Isle of Man regulated wagering channels as participatory revenue streams alongside passive viewership. |
| Creator-Direct Sponsorship Pivot | Bypasses platform media buys to capture Brazilian and Mexican Portuguese-language streamer audiences on YouTube Gaming. |
| Wireless Production Array Deployment | Leverages FCC 6GHz spectrum reallocation to eliminate cabling costs in NBA-scale tournament venues. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with tournament organizers, CDN engineering leads, platform monetization executives, and betting jurisdiction licensing officers; and secondary validation against SEC filings of infrastructure providers, TRAI net neutrality frameworks, FCC spectrum orders, and hyperscaler capex disclosures. Bottom-up triangulation across platform subscriber disclosures and top-down cross-checks against advertising load estimates anchored volume and value outputs.
Forecast inputs considered platform type segmentation by PC, console, mobile, and cloud architectures; content format splits across live events, tournaments, on-demand, and user-generated; and monetization model tiers spanning subscription, ad-supported, pay-per-view, and donations. CAGRs derived from elasticity modeling of smartphone penetration curves and 5G deployment timelines across the analysis window, with encoding technology substitution rates and regulatory licensing velocity as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud hyperscalers entering exclusive tournament rights bidding would shift outcomes substantially. Cross-checking against App Annie mobile streaming engagement data and Sensor Tower platform download metrics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Enterprise Streaming Media Market
Video Streaming (OTT) Services
Streaming Spending Market
Video Streaming (OTT) Services
Global Over-The-Top Market
Video Streaming (OTT) Services
United States Online Video Platform Market
Video Streaming (OTT) Services
Indonesia OTT Market
Video Streaming (OTT) Services
Online Video Platform Market
Video Streaming (OTT) Services
OTT Content Market
Video Streaming (OTT) Services
Asia Pacific Video Streaming Market
Video Streaming (OTT) Services
Video Streaming Market
Video Streaming (OTT) Services
Global Over-The-Top Content Market
Video Streaming (OTT) Services
Video on Demand Market
Video Streaming (OTT) Services
Online Streaming Service Market
Video Streaming (OTT) Services
Streaming Services Market
Video Streaming (OTT) Services
Media Streaming Market
Video Streaming (OTT) Services
Mexico OTT TV and Video Market
Video Streaming (OTT) Services
Video Servers Market