
 Online Streaming Service Market | 2026-2036
Online Streaming Service Market Size, Share, and Industry Trends Forecast 2026-2036
Online Streaming Service Market Insights
Platform bundling is repositioning consumer choice architecture as streaming services merge video, music, and gaming into unified subscription tiers. Netflix leverages its original content production infrastructure to sustain subscriber retention across diverse geographies. Amazon Prime Video anchors its competitive stance through integration with broader e-commerce and logistics ecosystems. Disney+ differentiates via exclusive franchise intellectual property that dominates family-oriented viewership segments.
Online streaming services deliver digital audiovisual content through internet protocol networks, utilizing adaptive bitrate streaming and content delivery networks to maintain quality across variable bandwidth conditions. These platforms serve commercial purposes spanning entertainment consumption, educational delivery, and enterprise communication. Video streaming leads service type revenue generation while live streaming exhibits the fastest structural expansion driven by sports and interactive broadcasting. Subscription-based models capture the deepest margin pools, though ad-supported tiers are gaining traction as platforms navigate price-sensitive demographics across smart TV and mobile app distribution channels.
The FCC governs broadband infrastructure standards affecting streaming quality and accessibility across the United States, while the EU AI Act imposes algorithmic transparency obligations on recommendation systems serving European users. China's SAMR and MIIT enforce content licensing and data localization requirements that shape market entry conditions for foreign platforms. Stakeholders must monitor evolving interoperability mandates and cross-border data governance frameworks that will determine platform architecture investments and geographic prioritization strategies.
Market Dynamics
The EU AI Act's algorithmic transparency mandates are forcing streaming platforms to restructure content recommendation engines, while India's regional language content surge is reshaping subscriber acquisition economics.
Growth Catalysts
- Adaptive bitrate streaming:CDNs now deploy edge-computing nodes that reduce buffering latency for live sports broadcasts. Broadcasters in Brazil and Mexico are upgrading infrastructure to capture football viewership.
- TRAI's OTT regulatory framework:India's telecom regulator clarified interconnection norms that reduce carriage disputes between platforms and ISPs. This stabilizes last-mile delivery costs for regional language services.
- Enterprise training modules:Workforce development programs embed streaming-based microlearning. Manufacturing and healthcare sectors in Germany and South Korea drive corporate subscription growth.
Market Restraints
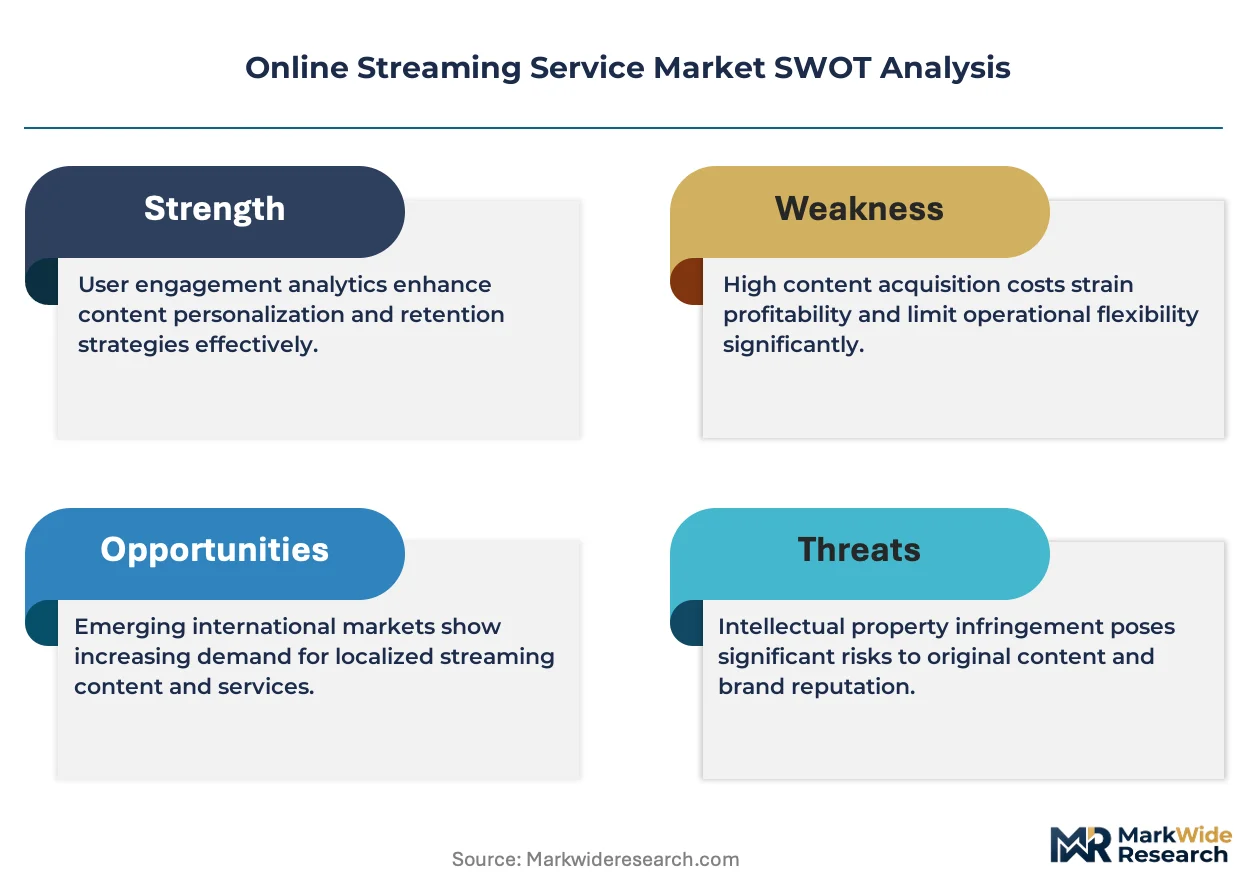
- Content licensing inflation:Exclusive sports rights and studio output deals compress platform margins. Cricket broadcasting rights in India and English Premier League rights in the UK exemplify this pressure.
- GDPR compliance architecture:EU data localization and consent management requirements force redundant infrastructure investments. Smaller platforms struggle with dual-stack engineering for European users.
- Bandwidth asymmetry:Rural fiber penetration lags urban deployment in the US, India, and Indonesia. This limits addressable market expansion beyond metropolitan clusters.
Strategic Opportunities
- Gaming-streaming convergence:Cloud gaming integration into video subscriptions creates stickier household bundles. Microsoft's Xbox-Game Pass model demonstrates technical feasibility.
- Saudi Arabia's entertainment localization:Vision 2030 content investment mandates attract platform partnerships for Arabic-original production. Riyadh and Jeddah emerge as production hubs.
- Ad-supported tier expansion:Price-sensitive demographics in Southeast Asia and Latin America respond to freemium models. AVOD revenue streams reduce churn vulnerability.
Industry Challenges
- ML engineer scarcity:Recommendation algorithm optimization requires specialized talent. Platforms compete with fintech and autonomous vehicle sectors for data science expertise.
- Cross-border content licensing:Territory-by-territory rights negotiations fragment global catalogs. EU portability regulations partially address this but create compliance complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Streaming Service Market |
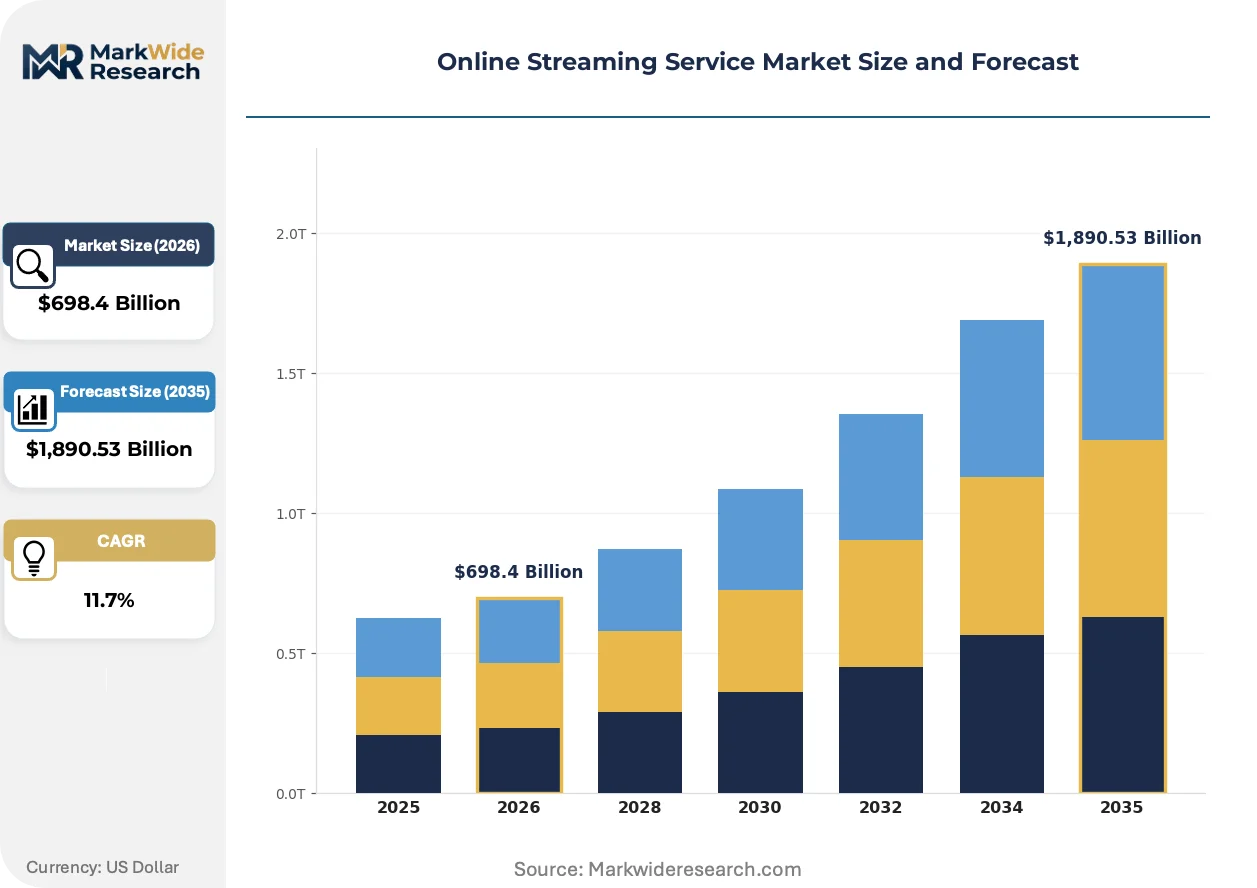
| Market Size in 2026 | $698.4 Billion |
| Market Size in 2035 | $1,890.53 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Video Streaming, Music Streaming, Live Streaming, Gaming Streaming Platform: Smart TV, Mobile App, Web Browser, Set-Top Box Subscription Model: Ad-Supported, Subscription-Based, Pay-Per-View, Freemium Content Type: Original Content, Licensed Movies, TV Shows, Documentaries |
| Companies Covered | Netflix, Amazon Prime Video, Disney+, Tencent Video, iQIYI, Max, YouTube, Apple TV+, Hulu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Streaming Service Market Trends and Innovations
Codec efficiency breakthroughs and interactive broadcasting formats are compressing delivery costs while expanding real-time engagement capabilities across sports and live entertainment verticals.
AV1 codec deployment is modularizing streaming infrastructure economics. Netflix and YouTube have accelerated adoption for 4K and 8K content. The royalty-free format reduces per-stream licensing costs that previously flowed to HEVC patent pools. Broadcasters in South Korea and Japan are following suit for Olympic and World Cup coverage.
The EU AI Act imposes explainability requirements on content recommendation systems. Platforms must document how algorithms rank and suggest titles to European users. This forces engineering teams to retrofit black-box ML models with interpretable decision paths. Family-oriented services face heightened scrutiny given child protection provisions in the regulation.
Bundling now dominates household purchasing decisions. Consumers consolidate video, music, and gaming into single subscriptions. Amazon Prime's cross-vertical integration sets the template. Indian platforms respond with cricket-plus-music-plus-commerce combinations. The shift compresses standalone service pricing power while raising switching costs.
Online Streaming Service Market Segmentation
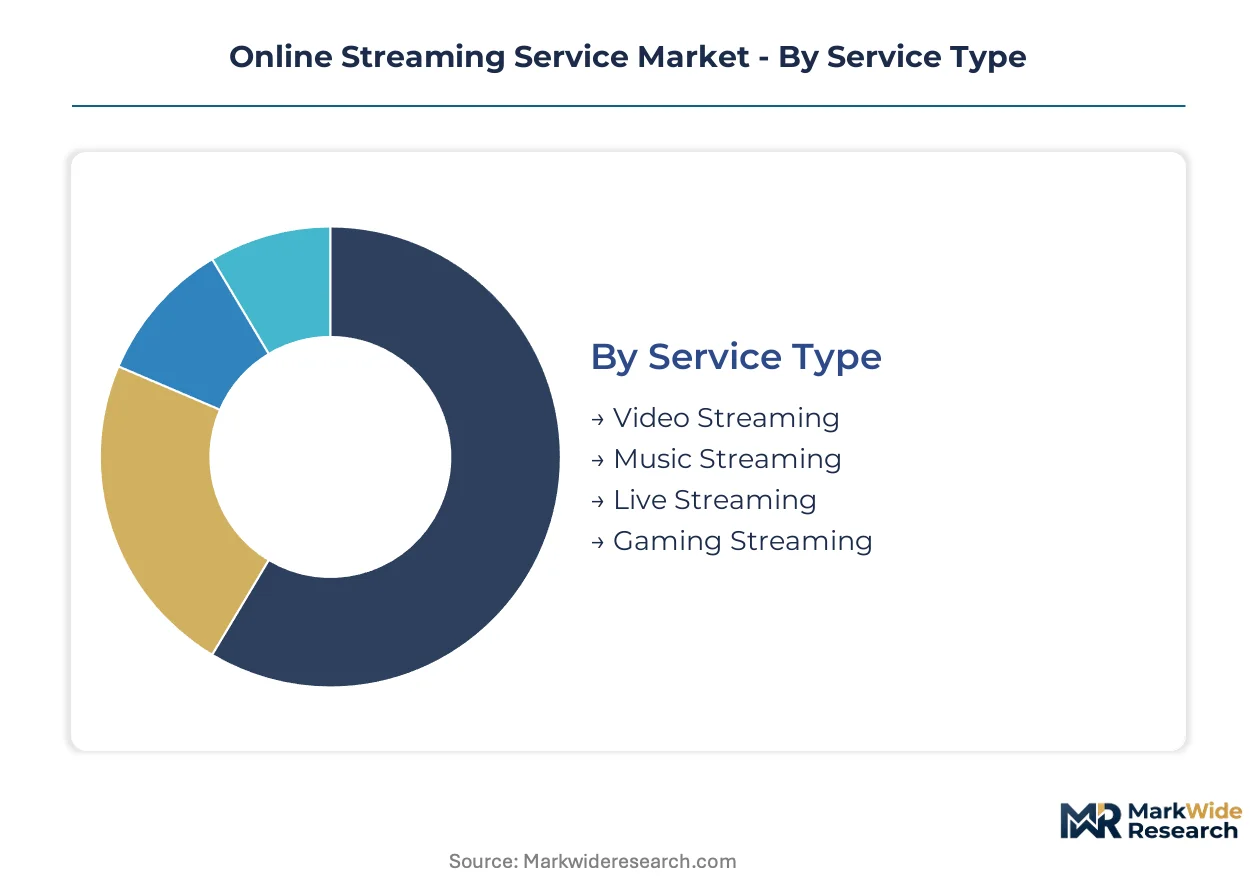
Streaming platforms engineer distinct monetization pathways across service architectures and device ecosystems. Segmentation reveals where subscriber acquisition costs diverge and which content investments yield retention leverage.
Service Type:
Content consumption patterns dictate infrastructure investment priorities across audio, video, and interactive formats.
- Video Streaming:On-demand film and series delivery through adaptive bitrate protocols dominates bandwidth consumption. Households in India and Brazil concentrate demand here, driven by regional language original production slates that reduce churn.
- Live Streaming:Real-time sports and event broadcasting requires sub-10-second latency edge networks. Cricket tournaments in India and football leagues across Europe and Latin America concentrate subscriber spikes.
- Music Streaming:Audio-first platforms compete on catalog depth and algorithmic playlist curation.
- Gaming Streaming:Cloud-rendered interactive entertainment demands GPU-intensive server farms.
Volume sits with Video Streaming; growth tilts toward Live Streaming.
Platform:
Device penetration curves reshape content format specifications and advertising load strategies.
- Smart TV:Large-screen viewing drives premium tier subscriptions and cinematic content investment. South Korean and Japanese households exhibit highest connected TV penetration, supporting 4K HDR format adoption.
- Mobile App:Smartphone-first consumption dominates emerging market acquisition. India's Jio-enabled data affordability and Indonesia's young demographic concentrate mobile-only subscriber bases.
- Web Browser:Desktop streaming persists for workplace and educational contexts.
- Set-Top Box:Legacy pay-TV integrations bridge cord-cutter transitions.
Smart TV captures the deepest revenue per user; Mobile App climbs the fastest.
Subscription Model:
Price sensitivity thresholds segment household willingness-to-pay across ad tolerance and content access tiers.
- Subscription-Based:Recurring monthly fees unlock full catalogs without advertising interruption. German and South Korean enterprise training contracts favor this model for workforce microlearning deployment.
- Ad-Supported:Lower or zero subscriber fees monetize through targeted advertising. Southeast Asian and Latin American price-sensitive demographics respond to AVOD tiers that reduce churn vulnerability.
- Pay-Per-View:Transactional access for premium live events and theatrical releases.
- Freemium:Tiered access with feature-gated upgrades.
Subscription-Based holds installed base; ad-supported tiers gain share fastest.
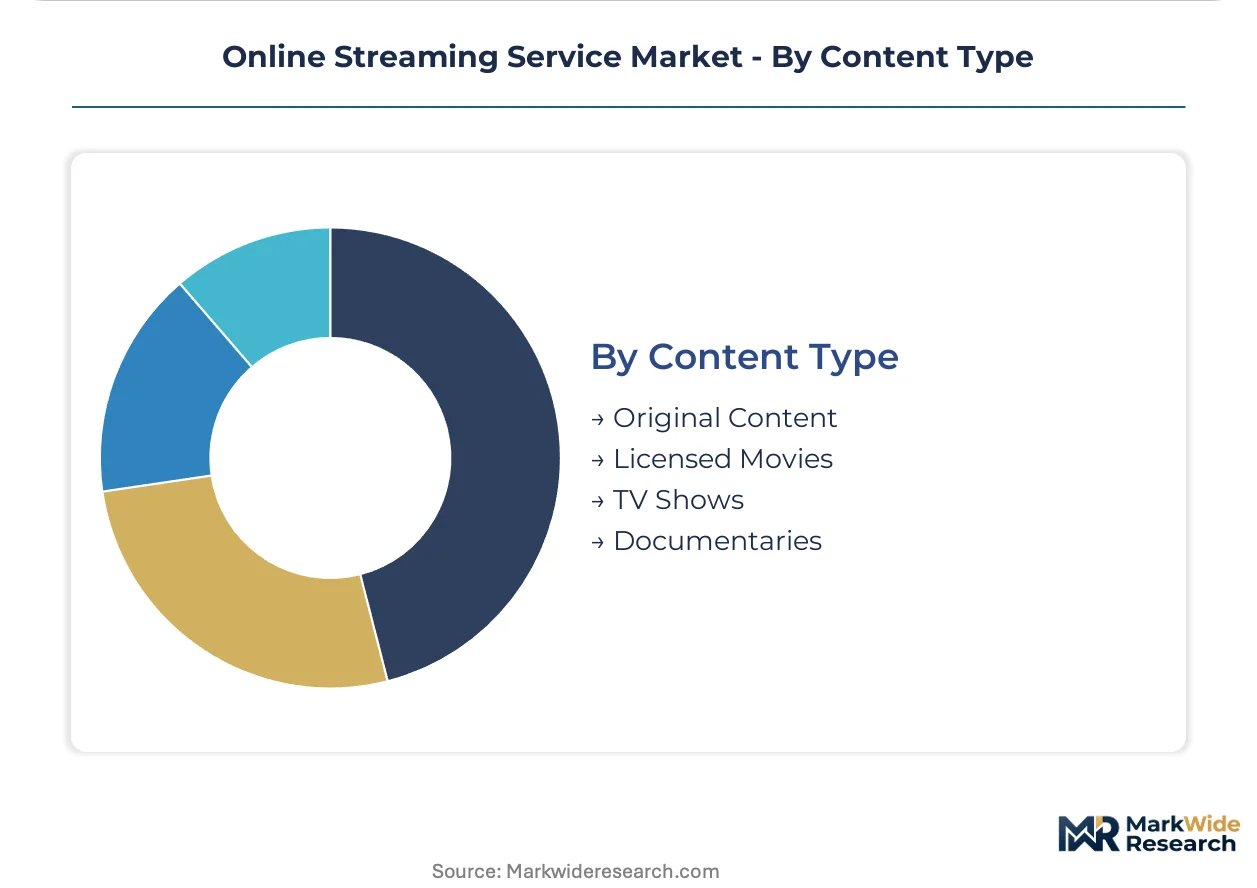
Content Type:
Intellectual property ownership determines margin structure and geographic exclusivity enforcement.
- Original Content:Platform-commissioned productions enable perpetual global distribution rights. Saudi Arabia's Vision 2030 localization mandates attract Arabic-original investment in Riyadh and Jeddah production hubs.
- Licensed Movies:Studio output deals provide catalog depth without production risk. Territory-by-territory negotiations fragment availability under EU portability regulations.
- TV Shows:Serialized episodic content drives binge-viewing retention metrics.
- Documentaries:Factual programming attracts educated demographics and brand-safe advertising.
Licensed Movies dominate catalog hours; Original Content shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's King Abdullah Economic City anchors production localization under Vision 2030 content mandates. India's SEZ incentives for media technology parks concentrate streaming infrastructure investment. Brazil's Porto Digital tax holiday zone attracts CDN edge-computing deployment for football broadcasting.
United States
FCC broadband infrastructure standards govern streaming quality thresholds across metropolitan and rural markets. The Infrastructure Investment and Jobs Act allocates fiber deployment capital to close bandwidth asymmetry gaps. Los Angeles and Atlanta production clusters sustain original content pipeline capacity for global distribution.
India
TRAI's OTT regulatory framework stabilizes interconnection economics between platforms and telecom operators. Regional language originals and cricket live streaming concentrate subscriber acquisition in Mumbai and Bengaluru technology corridors. The PLI scheme for electronics manufacturing attracts smart TV assembly investment.
Germany
GDPR consent management requirements and EU AI Act algorithmic transparency mandates restructure recommendation engine architecture. Enterprise training platforms embed streaming modules for workforce microlearning in Stuttgart and Munich industrial belts. The country's national media regulator enforces youth protection standards for family-oriented services.
Brazil
ANVISA content classification protocols align with broader audiovisual regulatory frameworks. Football broadcasting rights concentration drives CDN infrastructure upgrades in São Paulo and Rio de Janeiro metro corridors. Porto Digital's tax incentives attract streaming technology R&D operations.
South Korea
MFDS content review procedures intersect with cultural ministry broadcasting standards. AV1 codec adoption for 4K and 8K Olympic coverage accelerates infrastructure modernization. Seoul's Gangnam and Sangam digital media city clusters host platform engineering centers and production facilities.
Online Streaming Service Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across subscription and advertising revenue models. The market structure consolidates around three tiers: global scale platforms with integrated production infrastructure, regional champions with localized content slates, and niche specialists serving vertical demographics. Strategic archetypes include ecosystem-anchored bundlers, original content studios with captive distribution, and technology-led infrastructure providers. Dominant competitive moves encompass sports rights acquisitions and ad-supported tier launches to capture price-sensitive segments.
Among US-based platform operators, Netflix, Amazon Prime Video, and Disney+ exemplify distinct strategic archetypes within the consolidated tier. Netflix represents the pure-play original content studio model with perpetual global distribution rights. Amazon Prime Video anchors the ecosystem-integrated bundler position through cross-vertical subscription linkage. Disney+ occupies the franchise intellectual property specialist niche targeting family-oriented viewership segments. Each exemplifies how capital allocation toward content production infrastructure or ecosystem integration shapes competitive positioning.
| Leading Market Players |
|---|
| Netflix |
| Amazon Prime Video |
| Disney+ |
| Tencent Video |
| iQIYI |
| Max |
| YouTube |
| Apple TV+ |
| Hulu |
| Others |
Pricing and Supply Chain Analysis
Premium-original-versus-licensed-content bifurcation manifests in dual pricing architectures and divergent supply chain footprints. Platforms commissioning exclusive productions absorb upfront production costs in Los Angeles and London studios, while catalog-dependent competitors source territorial rights through fragmented distributor networks across Mumbai and Seoul.
Pricing Analysis
Short-lead-time sports broadcasting commands 40-60% subscription premiums against standard on-demand tiers. Three-tier pricing structure across premium, standard, and economy levels segments households by ad tolerance and device count. Cost compression in ad-supported tiers is intensifying because platforms compete for Southeast Asian price-sensitive subscribers. Enterprise training contracts show lowest price sensitivity; individual mobile-first subscribers in Indonesia and Nigeria exhibit highest elasticity.
Supply Chain Analysis
ML engineering talent scarcity in San Francisco, Bangalore, and Berlin constrains recommendation algorithm development velocity. Cloud infrastructure draws from hyperscaler data centers in Virginia, Frankfurt, and Singapore. Single-source vulnerability concentrates in AWS and Azure dominance for video encoding workloads. Distribution runs through ISP interconnection agreements and CDN edge nodes rather than traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where proprietary content libraries and captive cloud infrastructure determine margin capture. Players are pursuing upstream control over original production facilities to reduce licensing dependency.
For Market Incumbents: Hedge against subscriber churn by deepening exclusive sports rights portfolios in cricket and football territories. Fortify technical moats through in-house codec development to escape HEVC royalty pools. Regulatory fragmentation across EU AI Act compliance and India's TRAI interconnection rules demands dual-stack engineering investment.
For New Entrants and Emerging Players: Rural Indian households with Jio-enabled data affordability represent the most penetrable subscriber archetype. White-space exists in Arabic-original production for Saudi Vision 2030 localization mandates. Cloud-gaming bundling offers differentiated go-to-market positioning against video-only incumbents.
For Investors and Strategic Acquirers: Re-rating potential sits with enterprise training platform specialists given workforce microlearning adoption acceleration. Long-term viability favors assets with perpetual global distribution rights over territorial-license-dependent catalogs. Watch AV1 codec adoption curves as inflection indicator for infrastructure cost structure shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Original Content Production Scale-Up | Perpetual global rights reduce territorial licensing fragmentation under EU portability regulations. |
| Ad-Supported Tier Launch | Freemium models capture price-sensitive demographics in Southeast Asia and Latin America. |
| Cloud Gaming Integration | Microsoft's Xbox Game Pass demonstrates technical feasibility for household bundle stickiness. |
| Regional Language Original Investment | Hindi, Tamil, and Telugu productions drive subscriber acquisition in India's technology corridors. |
| Edge Computing CDN Expansion | Sub-10-second latency infrastructure enables live sports broadcasting in Brazil and Mexico. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with platform strategy executives, CDN infrastructure engineers, content licensing directors, and telecom interconnection specialists were combined with FCC broadband deployment reports, EU AI Act implementation guidance, and TRAI OTT regulatory circulars. Bottom-up subscriber and revenue modeling was triangulated against top-down market sizing from production investment databases.
Granularity-level modeling deployed service type, platform, subscription model, and content type dimensions at country-level resolution. CAGRs were derived from trend extrapolation and adoption curve analysis across the projection horizon. Forecast inputs incorporated smart TV penetration curves, regional language content slate announcements, and sports rights auction outcomes.
Revisions become necessary when bandwidth infrastructure deployment lags, regulatory interoperability mandates shift, or content licensing inflation accelerates beyond production cost absorption capacity. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Global Over-The-Top Market
Video Streaming (OTT) Services
E-Sports and Games Streaming Market
Video Streaming (OTT) Services
Sports Streaming Platform Market
Video Streaming (OTT) Services
Enterprise Streaming Media Market
Video Streaming (OTT) Services
Global Transactional Video on Demand Market
Video Streaming (OTT) Services
Asia Pacific Video Streaming Market
Video Streaming (OTT) Services
Online Video Platform Market
Video Streaming (OTT) Services
Global Cloud Video Streaming Market
Video Streaming (OTT) Services
Latin America OTT Platform Market
Video Streaming (OTT) Services
Video Streaming Market
Video Streaming (OTT) Services
Video on Demand Market
Video Streaming (OTT) Services
Indonesia OTT Market
Video Streaming (OTT) Services
Mexico OTT TV and Video Market
Video Streaming (OTT) Services
Game Streaming Market
Video Streaming (OTT) Services
United States Online Video Platform Market
Video Streaming (OTT) Services
Video Servers Market