
 United States OTT Market | 2026-2036
United States OTT Market Size, Share, and Industry Trends Forecast 2026-2036
United States OTT Market Analytics
Hollywood's content production infrastructure is consolidating around streaming-first distribution models. Netflix leverages its global content library to sustain subscriber retention across demographic cohorts. Disney+ anchors family-oriented programming with exclusive franchise access. Amazon Prime Video competes through bundled e-commerce and entertainment value propositions.
Over-the-top (OTT) content refers to audio, video, and media delivered via internet protocol networks without requiring traditional terrestrial, satellite, or cable television distribution, typically encoded in adaptive bitrate streaming formats such as H.264, HEVC, or AV1 for quality scaling across bandwidth conditions. The primary commercial purpose is direct-to-consumer monetization of entertainment, sports, and informational programming through subscription or advertising revenue models. SVOD subscription tiers currently command the largest revenue pools, while AVOD formats attract price-sensitive user segments with expanding advertiser interest. Smart TVs and dedicated streaming devices dominate consumption endpoints, though smartphone viewing continues rising among Gen Z audiences.
FCC net neutrality rulings and Copyright Office DMCA enforcement shape platform operating conditions and content licensing frameworks. FTC consumer protection oversight governs subscription billing transparency and auto-renewal disclosure requirements. Stakeholders must monitor evolving state-level privacy legislation, as California's CCPA and emerging sector-specific rules in New York and Illinois create compliance fragmentation that affects targeted advertising economics and data-driven personalization capabilities.
Market Dynamics
Streaming platforms are consolidating around proprietary content libraries as the primary subscriber retention mechanism, compressing the window between theatrical release and exclusive digital availability while fragmenting audience attention across multiple paid subscriptions.
Growth Catalysts
- FCC Broadband Infrastructure Investment:Federal Communications Commission funding for rural fiber deployment expands addressable subscriber bases beyond urban corridors. Households previously underserved by bandwidth constraints now access 4K streaming tiers.
- Adaptive Bitrate Streaming Protocols:HEVC and AV1 codec adoption reduces data consumption per viewing hour. Mobile carriers and fixed broadband providers accommodate higher concurrent streams without infrastructure overhaul.
- Cord-Cutting Household Migration:Traditional cable bundle dissolution accelerates as regional sports networks lose exclusive distribution rights. Former linear subscribers convert to direct platform relationships.
Market Restraints
- Content Licensing Cost Inflation:Exclusive rights to live sports franchises and studio back catalogs command premium renewal rates. Platform content acquisition budgets face input cost volatility from auction-style bidding wars.
- California Production Cluster Concentration:Los Angeles-San Francisco corridor dominance creates geographic supply risk. Wildfire disruptions and labor action in this corridor halt original programming pipelines.
- Net Neutrality Regulatory Uncertainty:FCC classification shifts expose streaming traffic to potential throttling or paid prioritization. Platform delivery costs become contingent on administrative rulemaking cycles.
Strategic Opportunities
- Midwestern and Southern State Penetration:Texas, Florida, and Ohio metropolitan areas show subscription gap versus coastal adoption rates. Localized Spanish-language content investments capture Hispanic household growth.
- Ad-Supported Tier Expansion:AVOD models attract price-sensitive segments previously excluded from subscription economics. Advertiser demand for connected TV inventory outpaces supply, improving CPM rates.
- Smart TV Operating System Integration:Roku, Samsung Tizen, and Amazon Fire TV embed platform applications at hardware layer. Frictionless activation reduces subscriber acquisition cost versus app store download pathways.
Industry Challenges
- Machine Learning Recommendation Engineering Talent:Streaming platforms compete for scarce data scientists capable of optimizing content discovery algorithms. Compensation inflation in this function compresses R&D efficiency metrics.
- Legacy Pay-TV Carriage Agreement Wind-Down:Platform operators must manage contractual exit penalties and subscriber notification requirements. Operational complexity increases during hybrid distribution periods.
- Multi-State Privacy Compliance Fragmentation:California CCPA, Virginia CDPA, and emerging Colorado/Connecticut statutes create divergent data governance requirements. Targeted advertising personalization capabilities degrade under strictest interpretations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States OTT Market |
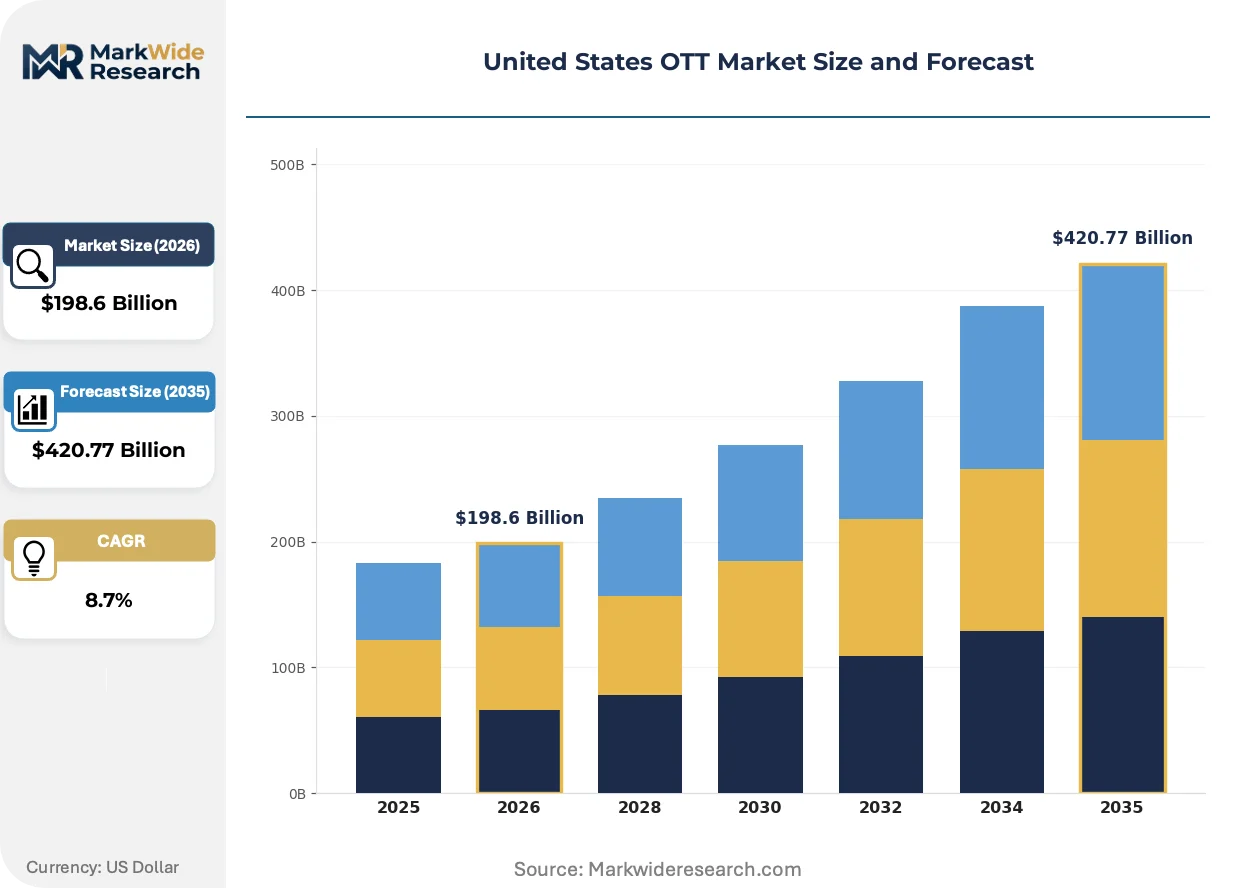
| Market Size in 2026 | $198.6 Billion |
| Market Size in 2035 | $420.77 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Movies, TV Shows, Live Sports, Documentaries Subscription Model: SVOD, AVOD, FVOD, Hybrid Device Type: Smart TVs, Streaming Devices, Smartphones, Tablets Target Audience: Millennials, Families, Seniors, Gen Z |
| Companies Covered | Netflix, Amazon Prime Video, Hulu, Disney+, Max, Paramount+, Peacock, Apple TV+, YouTube Premium, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States OTT Market Evolving Landscape
Codec standardization and regulatory pressure on data practices are compressing technical differentiation windows while elevating privacy-engineering capabilities as competitive differentiators in platform development roadmaps.
AV1 codec deployment is unifying streaming quality thresholds across device categories. Platform engineering teams at major services now encode original content in AV1 for simultaneous delivery to smart TVs, mobile handsets, and browser clients. This compression efficiency is unifying previously fragmented device-specific encoding pipelines into single-master workflows, reducing storage and transcoding infrastructure overhead.
FTC subscription billing transparency enforcement is tightening auto-renewal disclosure requirements. The Commission's amended Negative Option Rule mandates explicit consent mechanisms and simplified cancellation pathways. California-based platforms face dual compliance burden with state-level automatic renewal laws, forcing product team reallocation toward regulatory engineering rather than feature development.
Household subscription stacking behavior is fragmenting platform loyalty patterns. Consumers now maintain three to four concurrent paid services versus single-bundle relationships, rotating cancellations based on content release calendars. This churn volatility concentrates in Gen Z and millennial cohorts, where free trial arbitrage and seasonal signup patterns disrupt traditional annual retention forecasting models.
United States OTT Market Segmentation
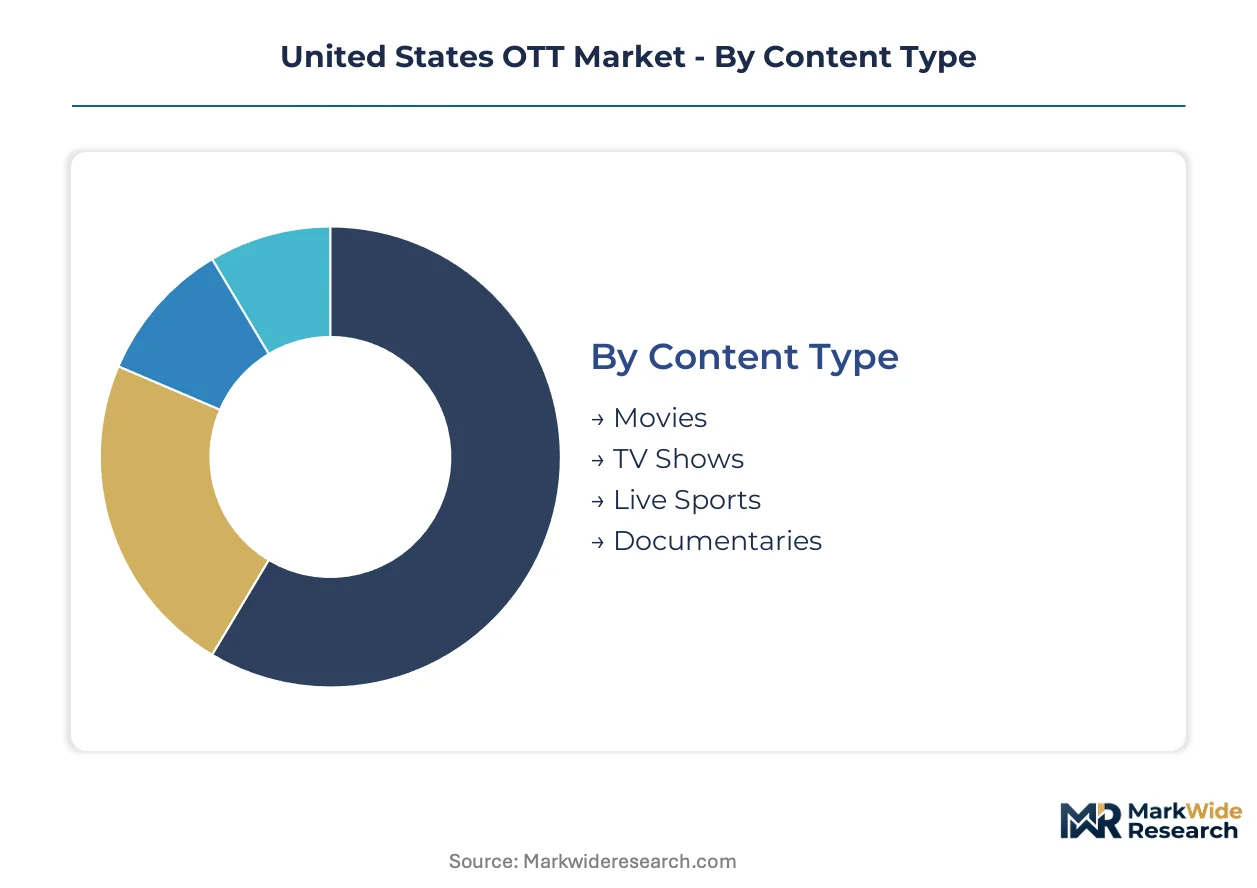
Streaming platforms configure their content libraries, monetization mechanics, and distribution endpoints around distinct audience behaviors and technical capabilities. Segmentation reveals where platform engineering investments concentrate and which household profiles drive subscription economics.
Content Type:
Original programming and licensed catalogs serve fundamentally different strategic purposes within platform portfolios, with integration depth varying from standalone theatrical releases to embedded franchise universes.
- Movies:Feature-length content commands premium licensing fees from studio distributors. California production clusters supply theatrical-window titles migrating to exclusive streaming availability within compressed release schedules.
- TV Shows:Serialized episodic formats anchor subscriber retention through binge-release and weekly-drop strategies. Platform commissioning pipelines concentrate in Los Angeles-San Francisco corridor production facilities.
- Live Sports:Real-time event broadcasting requires specialized low-latency infrastructure. Regional sports network dissolution accelerates direct platform carriage negotiations for NFL, NBA, and MLS franchise rights.
- Documentaries:Factual programming attracts niche audience segments with lower per-title acquisition costs. True crime and nature subgenres sustain consistent viewership outside tentpole release calendars.
Volume placements concentrate in TV Shows; the faster expansion belongs to Live Sports.
Subscription Model:
Monetization architecture stratifies across direct payment, advertising-supported, and hybrid tiers that embed multiple revenue streams within single subscriber relationships.
- SVOD:Subscription video-on-demand generates recurring revenue through monthly or annual payment commitments. California-headquartered platforms leverage exclusive content libraries to justify tiered pricing differentiation.
- AVOD:Advertising-supported tiers monetize price-sensitive households through connected TV inventory sales. FTC disclosure requirements govern auto-renewal transparency for promotional rate conversions.
- FVOD:Free video-on-demand operates through transactional or ad-supported windows without subscription commitment. Library depth constraints limit platform differentiation in this segment.
- Hybrid:Combined subscription-advertising models embed both revenue streams within tiered service levels. FCC broadband infrastructure investments expand addressable bases for households accessing ad-supported entry points.
Revenue concentration sits with SVOD; AVOD gains share fastest among price-sensitive demographic cohorts.
Device Type:
Endpoint hardware determines codec optimization requirements, user interface complexity, and activation friction within subscriber acquisition funnels.
- Smart TVs:Integrated operating systems embed platform applications at hardware layer. Samsung Tizen and Roku OS dominate US household penetration with frictionless activation pathways.
- Streaming Devices:Dedicated hardware attachments upgrade legacy television sets. Amazon Fire TV and Apple TV compete through ecosystem integration with complementary services.
- Smartphones:Mobile handsets require adaptive bitrate streaming optimization for cellular bandwidth constraints. Gen Z consumption patterns drive vertical video format experimentation and shorter session durations.
- Tablets:Mid-size portable screens serve travel and secondary household viewing contexts. iPad dominance in US tablet installed base shapes platform iOS development prioritization.
Smart TVs capture the largest viewing hour share; smartphones represent the steepest expansion trajectory among Gen Z audiences.
Target Audience:
Demographic cohorts exhibit distinct content preferences, price sensitivity thresholds, and platform loyalty patterns that shape subscriber lifetime value calculations.
- Millennials:Ages 28-43 cohort maintains highest subscription stacking behavior with three to four concurrent services. Nostalgia-driven reboots and prestige drama formats sustain engagement.
- Families:Households with children prioritize parental controls and educational content libraries. Disney+ anchors this segment through exclusive franchise access and bundled pricing structures.
- Seniors:Ages 65+ viewers demonstrate lower churn rates but require simplified interface design. Large-button navigation and closed captioning defaults reduce technical friction.
- Gen Z:Ages 12-27 cohort exhibits highest trial arbitrage and seasonal signup patterns. Social media-native discovery drives content selection with influencer recommendation influence.
Millennials generate the highest revenue per household; Gen Z shows the fastest-growing adoption velocity among emerging subscriber bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Broadband fiber deployments and studio production infrastructure anchor geographic demand patterns across US metropolitan corridors. California's content production clusters concentrate original programming supply, while Texas and Florida metros represent underpenetrated expansion zones. FCC infrastructure investments reshape addressable household maps beyond coastal corridors.
California
Los Angeles-San Francisco corridor studios supply theatrical-window titles migrating to streaming within compressed release schedules. California CCPA privacy regulations constrain data-driven personalization capabilities for platforms headquartered in-state. Hollywood production facilities anchor original commissioning pipelines disrupted by wildfire risks and labor action concentration.
Texas
Dallas-Fort Worth and Houston metros show subscription penetration gaps versus coastal adoption rates with Hispanic household growth driving Spanish-language content demand. FCC rural broadband funding expands fiber access to previously bandwidth-constrained exurban counties. Austin's tech corridor hosts platform engineering operations competing for machine learning talent with California headquarters.
New York Metro
Advertising industry concentration in Manhattan supports connected TV inventory demand and AVOD tier expansion among media-buying decision-makers. New York's emerging sector-specific privacy rules create compliance fragmentation affecting targeted advertising economics. Brooklyn and Queens production stages supplement California pipeline capacity for East Coast original programming.
Florida
Miami and Tampa metropolitan areas exhibit subscription velocity among retiree inflows seeking simplified interface streaming services. State-level consumer protection frameworks govern auto-renewal disclosure requirements overlapping with FTC Negative Option Rule enforcement. Orlando's post-production facilities serve regional sports network dissolution with specialized live event infrastructure.
Pacific Northwest
Seattle's cloud computing infrastructure hosts platform streaming delivery architectures with latency optimization for West Coast audiences. Washington state privacy legislation approaches California CCPA stringency, creating dual compliance burdens for Seattle-headquartered technology providers. Portland's independent production sector supplies documentary and factual programming at lower per-title acquisition costs.
United States OTT Market Competitive Landscape
Global majors compete with regional champions across content library depth and distribution technology integration. The US OTT market structures around three tiers: legacy studio platforms with theatrical back catalogs, technology-native services with algorithmic personalization engines, and telecom-affiliated bundles leveraging broadband subscriber relationships. Dominant competitive moves include exclusive sports franchise rights auctions and smart TV operating system pre-installation partnerships.
Within the technology-native tier, Netflix and Amazon Prime Video exemplify scale-driven content commissioning capabilities. Disney+ occupies a position as the studio-legacy archetype with franchise-exclusive family programming. Among telecom-affiliated platforms, Peacock represents bundled broadband-entertainment value propositions competing on subscriber acquisition cost efficiency.
| Leading Market Players |
|---|
| Netflix |
| Amazon Prime Video |
| Hulu |
| Disney+ |
| Max |
| Paramount+ |
| Peacock |
| Apple TV+ |
| YouTube Premium |
| Others |
Value Network & Pricing Analysis
Households maintaining three to four concurrent streaming subscriptions anchor the dominant tiered pricing model, with platform operators segmenting access through bundled service inclusions and standalone ad-supported tiers. This buyer concentration forces pricing discipline around content library depth rather than pure cost competition.
Pricing Analysis
Service bundling with broadband, e-commerce, or mobile subscriptions obscures standalone content pricing while creating switching costs. Three-tier pricing structure across premium, standard, and economy levels differentiates by concurrent stream count and resolution tier. Cost compression in ad-supported tiers is intensifying because connected TV inventory demand outpaces supply. Price-sensitive Hispanic households and rural fiber expansion zones show highest elasticity, while franchise-exclusive family subscribers demonstrate lowest sensitivity.
Supply Chain Analysis
Production workforce availability in California's Los Angeles-San Francisco corridor concentrates original content supply with escalating below-the-line labor competition. Content creation draws from Los Angeles production stages, New York Metro soundstages, and Austin post-production facilities. Talent pipeline constraints in machine learning recommendation engineering and visual effects specialization create single-source vulnerability for platform R&D. Distribution runs through cloud infrastructure providers with edge caching nodes and smart TV OS pre-installation partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Original programming commissioning capacity constraints prop pricing power for platforms controlling exclusive franchise rights, compressing margins for catalog-dependent competitors.
For Market Incumbents: Deepen exclusive sports franchise rights accumulation to lock in subscriber retention against regional sports network dissolution. Expand in-house production of unscripted and documentary formats to reduce California production cluster dependency. Vertical integration into smart TV operating systems via pre-installation partnerships secures distribution leverage against app store gatekeepers. For New Entrants and Emerging Players: Enter via Spanish-language original programming targeting Texas and Florida Hispanic household growth with localized commissioning. White-space concentration sits in Midwestern metropolitan subscription gaps versus coastal adoption rates. AVOD tier launch with connected TV inventory partnerships offers lowest customer acquisition cost pathway. For Investors and Strategic Acquirers: The window for entry favors platforms controlling proprietary IP with franchise extension potential and established smart TV OS distribution. Long-term viability hinges on exclusive content renewal rates and engineering talent retention. Watch for FCC net neutrality classification shifts as inflection indicator for delivery cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Sports Franchise Rights Acquisition | Direct carriage negotiations with NFL, NBA, and MLS displace regional sports network intermediaries. |
| AVOD Tier Expansion | Connected TV inventory demand from Manhattan media buyers improves CPM rates for price-sensitive segments. |
| Smart TV OS Pre-installation Partnerships | Roku, Samsung Tizen, and Amazon Fire TV embed applications at hardware layer reducing acquisition friction. |
| California Production Cluster Diversification | Brooklyn, Queens, and Austin facilities mitigate wildfire and labor action concentration risk. |
| Machine Learning Talent Retention Programs | Data scientist compensation inflation in recommendation engineering compresses R&D efficiency metrics. |
Research Methodology
Independent corroboration across platform content commissioning executives, FCC regulatory affairs specialists, and connected TV advertising buyers underwrites the qualitative findings. Primary interviews with smart TV OS product managers, post-production facility operators, and streaming device procurement teams combined with secondary validation from SEC filings, FCC broadband deployment reports, and FTC enforcement actions. Bottom-up subscriber modeling and top-down advertising revenue triangulation anchor volume estimates.
Comparable-period anchoring to theatrical window compression trends and cord-cutting household migration rates established the forecast baseline. Segmentation dimensions span content type, subscription model, device endpoint, and demographic cohort across the analysis window. CAGRs derive from subscriber stacking behavior trajectories, AVOD tier adoption curves, and FCC infrastructure investment deployment schedules. Codec efficiency gains and state-level privacy compliance fragmentation feed sensitivity parameters.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FCC net neutrality reclassification or California wildfire production disruptions. Projections reflect assumptions regarding broadband deployment velocity and sports rights auction dynamics. Material deviation in exclusive content renewal rates or smart TV OS distribution terms warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Indonesia OTT Market
Video Streaming (OTT) Services
Video Servers Market
Video Streaming (OTT) Services
Global Svod Market
Video Streaming (OTT) Services
Latin America OTT Platform Market
Video Streaming (OTT) Services
United States Online Video Platform Market
Video Streaming (OTT) Services
India Smart TV and OTT Market
Video Streaming (OTT) Services
E-Sports and Games Streaming Market
Video Streaming (OTT) Services
Global Transactional Video on Demand Market
Video Streaming (OTT) Services
Subscription Video on Demand (Svod) Market
Video Streaming (OTT) Services
Streaming Media Services Market
Video Streaming (OTT) Services
Over the Top (OTT) Services Market
Video Streaming (OTT) Services
Game Streaming Market
Video Streaming (OTT) Services
Mexico OTT TV and Video Market
Video Streaming (OTT) Services
Global Over-The-Top Market
Video Streaming (OTT) Services
Enterprise Streaming Media Market
Video Streaming (OTT) Services
Video on Demand Market