
 Global Over-The-Top Content Market | 2026-2036
Global Over-The-Top Content Market Size, Share, and Industry Trends Forecast 2026-2036
Global Over-The-Top Content Market Foresight
Subscriber concentration among households is consolidating as streaming fatigue drives churn toward bundled offerings and ad-supported tiers. Netflix dominates original content production with global localization strategies. Amazon leverages its Prime ecosystem to sustain video engagement through retail cross-subsidization. Disney anchors family-oriented catalog strength across multiple international territories.
Over-the-top content delivers audio, video, and interactive media directly to end users via internet protocol networks, bypassing traditional broadcast, cable, or satellite distribution infrastructure. The technology relies on adaptive bitrate streaming protocols such as HLS and DASH to maintain playback quality across variable bandwidth conditions. Video streaming leads subscription revenue generation while ad-supported models capture fastest-growing user acquisition. Smart TVs anchor viewing time per session, whereas smartphones compete for fragmented consumption moments throughout daily routines.
The EU Digital Services Act imposes transparency requirements on algorithmic recommendation systems and illegal content removal timelines. The FCC in the United States maintains net neutrality debates that shape last-mile delivery costs for OTT providers. India's TRAI periodically reviews tariff regulations affecting bundled telecom and streaming offerings. Stakeholders must monitor how divergent national content quota rules and data localization mandates reshape platform operating economics and library investment priorities.
Market Dynamics
Enterprise video streaming deployments are compressing sales cycles as organizations replace legacy conferencing infrastructure with integrated training and internal communications platforms, while regulatory fragmentation across jurisdictions forces parallel compliance investments.
Growth Catalysts
- EU Digital Services Act:Transparency mandates on algorithmic systems are accelerating vendor investment in explainable recommendation engines, creating competitive differentiation for compliant platforms.
- India's broadband expansion:Fiber-to-the-home rollouts in tier-2 and tier-3 cities under TRAI oversight are unlocking subscriber bases previously unreachable by streaming services.
- Adaptive bitrate streaming:HLS and DASH protocol refinements are automating quality optimization across variable network conditions, reducing churn from buffering events.
Market Restraints
- Content production cost inflation:Original programming budgets for premium scripted series have tripled since 2019, squeezing margin structures for non-vertically integrated platforms.
- Net neutrality uncertainty:FCC regulatory oscillations in the United States create persistent risk of last-mile delivery cost reclassification for OTT traffic.
- Substitution by gaming platforms:Interactive entertainment formats are capturing Gen Z screen time previously allocated to passive video consumption.
Strategic Opportunities
- Indonesia's underpenetrated market:Mobile-first streaming adoption among the archipelago's 270 million population offers expansion runway for localized content investments.
- Convergence of streaming and commerce:Shoppable video integrations are merging entertainment and transaction layers, opening new revenue pools beyond subscription and advertising.
- Brazil's PLI scheme extensions:Local production tax incentives are reducing effective content costs for platforms establishing regional headquarters.
Industry Challenges
- Machine learning engineer scarcity:Recommendation system optimization and personalization pipeline development face acute talent competition from technology and financial services sectors.
- Multi-territory licensing complexity:Fragmented music and sports rights across EU member states under divergent copyright implementations inflate legal overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Over-The-Top Content Market |
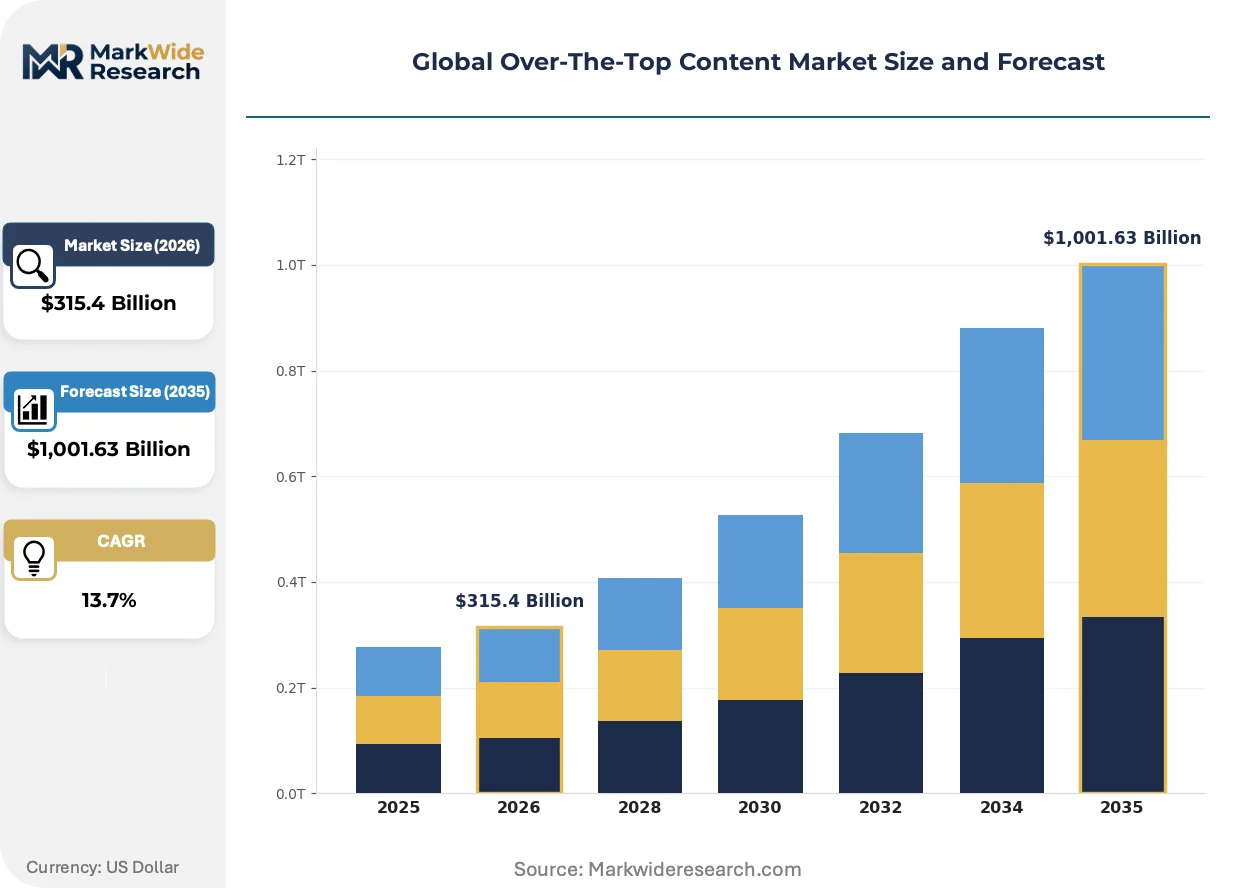
| Market Size in 2026 | $315.4 Billion |
| Market Size in 2035 | $1,001.63 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Video Streaming, Music Streaming, Gaming Streaming, Digital Advertising Subscription Model: Ad-Supported, Subscription-Based, Transactional, Freemium Device Type: Smart TVs, Smartphones, Tablets, Computers End User: Individual Consumers, Enterprises, Educational Institutions, Governments |
| Companies Covered | The Walt Disney Company (Disney+ and Hulu), Apple Inc. (Apple TV+), Netflix Inc., Roku Inc. (The Roku Channel), Paramount Global (Paramount+ and Pluto TV), Google LLC (YouTube), Tencent Holdings Ltd (Tencent Video), Brightcove Inc., Amazon.com Inc. (Prime Video), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Over-The-Top Content Market Shifts & Advancements
Artificial intelligence is penetrating content workflows from creation through distribution, compressing production timelines while regulatory frameworks mature around algorithmic accountability and data governance.
Generative AI tools for automated dubbing, subtitling, and thumbnail generation are automating localization workflows that previously required manual studio intervention. Mid-tier streaming services in Southeast Asia and Latin America are adopting these capabilities fastest, reducing time-to-market for international catalog expansion from months to weeks. The technology is automating cost structures that previously favored platforms with centralized production hubs.
The EU AI Act's risk-based classification system is imposing documentation burdens on recommendation algorithms deemed high-risk for systemic influence. Platforms operating across the 27 member states must maintain audit trails for training data and model decisions, redirecting engineering resources toward compliance infrastructure. Family-oriented services with children's content recommendation layers face the most stringent oversight timelines.
Ad-supported tier migration is restructuring subscriber economics as households trade commercial-free experiences for price reductions. Latin American markets exhibit the fastest behavioral shift, with Brazil and Mexico leading ad-tier adoption curves. The pattern is compressing average revenue per user while expanding total addressable audience pools for targeted advertising insertion.
Global Over-The-Top Content Market Segmentation
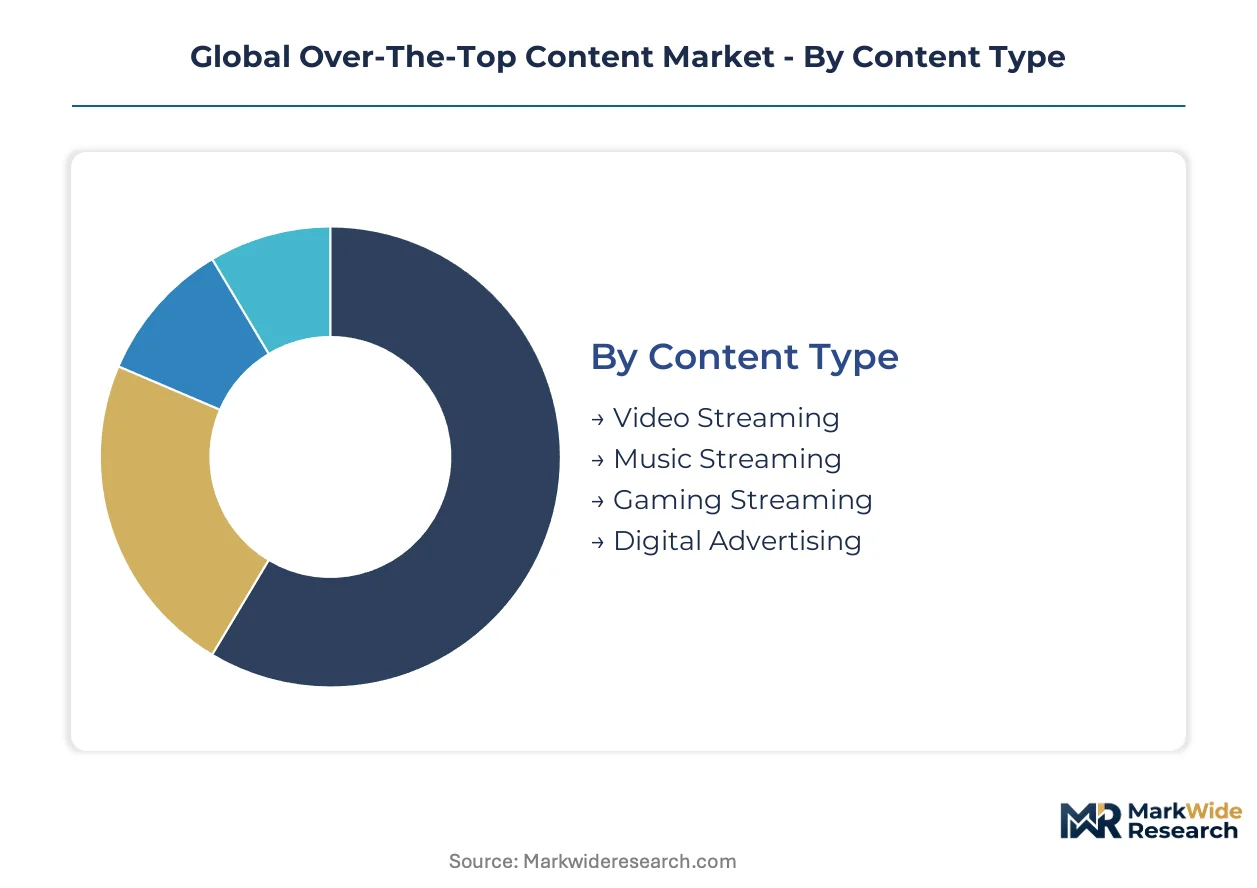
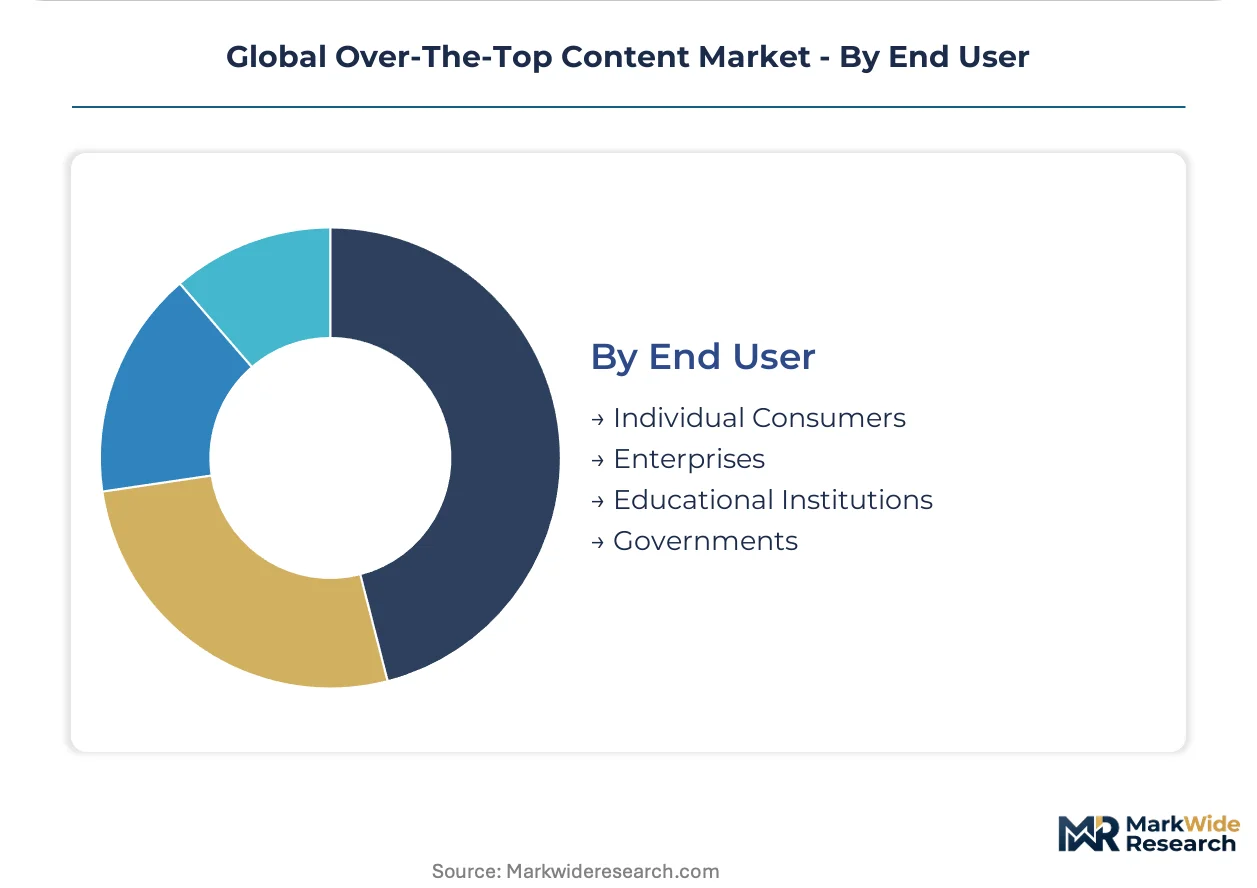
Content type, subscription model, device preference, and end-user category each reshape platform engineering priorities and monetization architecture. Distinct technical requirements across these dimensions force parallel infrastructure investments.
Content Type:
Adaptive bitrate streaming protocols differentiate technical specifications across content categories.
- Video Streaming:HLS and DASH protocols dominate delivery infrastructure, with CDN edge nodes optimizing for variable bandwidth conditions across residential broadband. Demand concentrates in India as fiber-to-the-home rollouts expand addressable subscriber bases beyond saturated Western markets.
- Music Streaming:Lossy compression standards balance audio fidelity against mobile data consumption, with caching algorithms prioritizing playlist prefetching for offline playback. Latin American markets exhibit steepest expansion trajectory as prepaid mobile data bundles reduce entry barriers.
- Gaming Streaming:Cloud render pipelines require sub-50ms latency thresholds, constraining viable deployment to fiber-connected urban clusters.
- Digital Advertising:Programmatic insertion engines synchronize with content management systems for dynamic ad replacement.
Mature deployment sits with Video Streaming. Newer deployment is concentrated in Gaming Streaming.
Subscription Model:
Revenue architecture separates platforms by customer acquisition cost tolerance and lifetime value horizons.
- Ad-Supported:Targeting algorithms leverage first-party viewing data for addressable advertising, with Brazil and Mexico leading behavioral migration toward commercial-inclusive tiers. The model compresses average revenue per user while expanding total addressable audience pools.
- Subscription-Based:Recurring revenue streams fund original content production, with annual plans reducing monthly churn exposure. Households in Germany and France consolidate spending around bundled offerings as streaming fatigue intensifies.
- Transactional:Premium window releases capture early-access willingness for theatrical bypass content.
- Freemium:Conversion funnel optimization concentrates engineering resources on paywall timing algorithms.
Subscription-Based models anchor established platform economics. Ad-Supported deployment is expanding most quickly in price-sensitive markets.
Device Type:
Screen dimensions and network connectivity reshape content formatting and delivery optimization.
- Smart TVs:4K HDR pipelines dominate living room consumption, with HDMI 2.1 bandwidth enabling uncompressed audio passthrough. Session duration peaks on large screens as lean-back viewing displaces mobile fragmentation.
- Smartphones:Portrait-mode short-form content and offline download functionality prioritize cellular data efficiency. Southeast Asian markets lead mobile-first consumption patterns among transit-dependent commuters.
- Tablets:Mid-size screens balance portability against video real estate for travel and bedside use cases.
- Computers:Browser-based access supports multitasking behaviors and corporate firewall navigation.
Smart TV deployment dominates premium content consumption. Smartphone deployment is gaining share fastest among younger demographics.
End User:
Procurement authority and budget cycles segment platform sales motion complexity.
- Individual Consumers:Direct-to-consumer subscription flows emphasize frictionless onboarding and payment method flexibility. Churn management algorithms target retention offers at cancellation intent signals.
- Enterprises:Internal communications and training deployments compress sales cycles as organizations replace legacy conferencing infrastructure. Compliance requirements under the EU Digital Services Act reshape vendor selection criteria.
- Educational Institutions:Volume licensing agreements accommodate semester-based enrollment fluctuations.
- Governments:Data localization mandates and content quota regulations constrain platform architecture choices.
Individual Consumer deployment remains volume-dominant. Enterprise deployment is climbing the fastest as remote work infrastructure investment persists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Broadband fiber deployments in India and Indonesia anchor subscriber growth momentum for streaming platforms, while regulatory frameworks in the European Union and United States reshape content moderation obligations and platform accountability standards.
United States
Household streaming fatigue drives consolidation toward bundled offerings and ad-supported tiers as consumers seek price relief. The FCC maintains net neutrality debates that shape last-mile delivery costs for OTT traffic. Los Angeles and New York City anchor original content production clusters where studio infrastructure supports premium scripted series development.
India
Expanding fiber-to-the-home rollouts in tier-2 and tier-3 cities unlock subscriber bases previously unreachable by streaming services. TRAI periodically reviews tariff regulations affecting bundled telecom and streaming offerings. Mumbai and Bangalore concentrate localization investments where platforms adapt international catalogs for regional language audiences.
Germany
Households consolidate spending around bundled offerings as streaming fatigue intensifies across saturated Western European markets. The EU Digital Services Act imposes transparency requirements on algorithmic recommendation systems and illegal content removal timelines. Berlin anchors compliance engineering clusters where platforms maintain audit trails for training data and model decisions.
Brazil
Ad-tier adoption curves lead Latin American behavioral shifts toward commercial-inclusive streaming experiences. Local production tax incentives under PLI scheme extensions reduce effective content costs for platforms establishing regional headquarters. São Paulo concentrates regional headquarters investment where platforms optimize Latin American content acquisition strategies.
Indonesia
Mobile-first streaming adoption among the archipelago's population offers expansion runway for localized content investments. The country's national telecommunications regulator shapes mobile data bundle structures affecting streaming accessibility. Jakarta anchors Southeast Asian content adaptation clusters where platforms compress localization timelines through automated dubbing workflows.
Global Over-The-Top Content Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue niche content verticals and regional localization advantages. The market structure consolidates around vertically integrated entertainment conglomerates with captive studio infrastructure, mid-tier platforms dependent on licensed catalog depth, and technology-native entrants leveraging cloud infrastructure scale. Three archetypes dominate: ecosystem-anchored platforms cross-subsidizing video through retail or device sales, pure-play streaming specialists prioritizing original content production, and advertising-technology platforms monetizing aggregated audience reach. Competitive moves concentrate on M&A activity securing exclusive content libraries and geographic expansion through localized production hubs.
Among US-based entertainment conglomerates, The Walt Disney Company, Netflix Inc., and Amazon.com Inc. exemplify distinct strategic archetypes. Disney represents ecosystem-anchored positioning through family-oriented catalog strength and franchise IP leverage across multiple international territories. Netflix occupies the pure-play specialist tier with global localization strategies prioritizing original content production volume. Amazon anchors cross-subsidization architecture where Prime membership economics sustain video engagement through retail ecosystem integration.
| Leading Market Players |
|---|
| The Walt Disney Company (Disney+ and Hulu) |
| Apple Inc. (Apple TV+) |
| Netflix Inc. |
| Roku Inc. (The Roku Channel) |
| Paramount Global (Paramount+ and Pluto TV) |
| Google LLC (YouTube) |
| Tencent Holdings Ltd (Tencent Video) |
| Brightcove Inc. |
| Amazon.com Inc. (Prime Video) |
| Others |
Supply & Pricing Matrix
Content delivery network bandwidth costs cascade through subscription tier architecture, with edge server proximity to subscriber clusters determining whether platforms absorb infrastructure overhead into premium pricing or push variable delivery expenses toward ad-supported tiers. Fiber interconnect fees in India and Indonesia compress margin structures for localized entrants competing against hyperscaler-owned backbone networks.
Pricing Analysis
Service bundling separates premium tiers with offline download privileges and 4K HDR pipelines from ad-supported tiers carrying commercial load and standard-definition caps. Three-tier pricing structure across premium, standard, and economy levels anchors on content access windows, with theatrical-release proximity commanding highest subscription rates. Price differentiation tracks original content exclusivity and device concurrency limits. Pricing pressure stems from content production cost inflation as original programming budgets expand. Individual consumers in Latin America exhibit highest price sensitivity, while enterprise training deployments show lowest sensitivity due to compliance-driven procurement authority.
Supply Chain Analysis
Cloud render infrastructure for gaming streaming rests on hyperscaler data center concentration in the United States, Ireland, and Singapore. Content licensing pipelines draw from studio production clusters in Los Angeles, Mumbai, and São Paulo. Machine learning engineer talent pools face single-source vulnerability from technology sector competition. Distribution runs through ISP last-mile partnerships and smart TV OEM pre-installation agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adaptive bitrate streaming protocols are displacing legacy broadcast infrastructure, compressing deployment timelines for internet-native distribution while regulatory frameworks mature around algorithmic accountability.
For Market Incumbents: Anchor defensive positioning through captive studio infrastructure investments in Mumbai and São Paulo, insulating against content cost inflation while streaming fatigue intensifies churn risk. Prioritize backward integration into localization technology stacks, automating dubbing and subtitling workflows that previously required manual studio intervention. The EU AI Act's documentation burdens on recommendation algorithms threaten engineering resource allocation.
For New Entrants and Emerging Players: Enter via Indonesia's mobile-first streaming gap, where 270 million population and limited fiber penetration favor smartphone-optimized ad-supported tiers over premium subscription plays. Target enterprise video streaming deployments replacing legacy conferencing infrastructure, compressing sales cycles through compliance-forward positioning under EU Digital Services Act transparency mandates. Shoppable video integrations offer differentiated go-to-market angles merging entertainment and transaction layers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier platforms with licensed catalog depth and regional localization capabilities in Brazil and Southeast Asia, where PLI scheme extensions and automated dubbing workflows reduce effective content costs. Long-term viability hinges on 5-10 year infrastructure buildout in tier-2 Indian cities under TRAI oversight. Watch ad-tier adoption curves in Latin America as inflection indicators for household price sensitivity thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Prime ecosystem economics sustain video engagement through retail cross-subsidization in competitive markets. |
| Geographic Expansion | Regional headquarters in São Paulo leverage Brazil's PLI scheme extensions for Latin American content optimization. |
| Strategic Partnership | ISP bundling agreements under TRAI tariff reviews expand addressable subscriber bases in Indian tier-2 cities. |
| Acquisition of Specialist Firm | Automated dubbing technology targets compress localization timelines from months to weeks for Southeast Asian catalogs. |
| Product Launch | Ad-supported tier migration captures price-sensitive households in Brazil and Mexico through commercial-inclusive experiences. |
Research Methodology
Document review covered SEC filings from entertainment conglomerates, TRAI tariff orders, EU Digital Services Act implementation guidelines, and hyperscaler capex disclosures, complemented by interviews with platform engineering directors, content licensing executives, ISP partnership managers, and enterprise procurement officers. Secondary validation drew from CDN traffic analytics, smart TV OEM shipment data, and fiber rollout databases. Bottom-up subscriber modeling triangulated against top-down addressable market sizing across the analysis window.
Model outputs projected segment-level revenue trajectories across content type, subscription model, device preference, and end-user category dimensions throughout the forecast period. CAGRs derived from historical growth rate regression adjusted for broadband infrastructure deployment curves and regulatory implementation timelines. Industry-specific inputs included content production budget inflation indices and algorithmic recommendation engine development cost curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FCC net neutrality reclassification scenarios and EU AI Act enforcement intensity shifts. Projections reflect assumptions on fiber-to-the-home penetration rates and content localization automation adoption. A small set of named triggers—TRAI tariff restructuring, EU Digital Services Act penalty precedents, and Gen Z gaming substitution rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Online Video Platform Market
Video Streaming (OTT) Services
Streaming Services Market
Video Streaming (OTT) Services
Enterprise Streaming Media Market
Video Streaming (OTT) Services
Global Svod Market
Video Streaming (OTT) Services
Video-On-Demand [Vod] Market
Video Streaming (OTT) Services
Online Streaming Service Market
Video Streaming (OTT) Services
Video on Demand Market
Video Streaming (OTT) Services
United States OTT Market
Video Streaming (OTT) Services
Streaming Spending Market
Video Streaming (OTT) Services
Subscription Video on Demand (Svod) Market
Video Streaming (OTT) Services
Global Over-The-Top Market
Video Streaming (OTT) Services
United States Online Video Platform Market
Video Streaming (OTT) Services
Global Transactional Video on Demand Market
Video Streaming (OTT) Services
Live Streaming Pay-Per-View Market
Video Streaming (OTT) Services
Indonesia OTT Market
Video Streaming (OTT) Services
Latin America OTT Platform Market