
 Streaming Services Market | 2026-2036
Streaming Services Market Size, Share, and Industry Trends Forecast 2026-2036
Streaming Services Market Insights
The EU AI Act is broadening the cost-of-entry calculus for streaming platforms operating across European markets. Netflix leverages its global content infrastructure to sustain compliance investments without fragmenting its distribution architecture. Amazon Prime Video anchors its competitive position through backward integration into cloud delivery infrastructure, reducing marginal streaming costs.
Streaming services deliver encoded audiovisual content over internet protocol networks to subscriber endpoints, typically employing adaptive bitrate algorithms that adjust resolution between 240p and 4K based on real-time bandwidth conditions. The primary commercial purpose is recurring revenue generation through licensed or original content libraries distributed on-demand. Monthly subscription models dominate revenue pools, while ad-supported tiers represent the fastest-growing segment as platforms pursue price-sensitive demographics. Live sports content commands premium pricing and disproportionate subscriber retention value across device types.
The FCC governs net neutrality principles affecting streaming quality-of-service in the US, while the EU Green Deal imposes energy-efficiency reporting on data centers powering European streaming delivery. India's TRAI regulates tariff transparency for over-the-top services, influencing platform pricing architecture. Stakeholders must monitor evolving content localization mandates and carbon disclosure requirements as regulatory fragmentation intensifies across jurisdictions.
Market Dynamics
Enterprise streaming adoption for internal communications and training is compressing B2B sales cycles while the EU AI Act forces platforms to restructure content moderation workflows and compliance architectures.
Growth Catalysts
- Enterprise Training Demand:Corporations deploy streaming platforms for workforce upskilling and internal knowledge transfer, creating subscription revenue pools outside consumer entertainment.
- EU AI Act Compliance Spending:The regulation mandates algorithmic transparency for content recommendation systems, driving platform investment in explainable AI infrastructure.
- Broadband Infrastructure Rollout:India's tier-two and tier-three cities gain fiber connectivity, unlocking subscriber bases previously constrained by bandwidth limitations.
Market Restraints
- Content Licensing Cost Volatility:Sports rights auctions and studio exclusivity deals inflate programming budgets unpredictably, squeezing margin structures.
- Cloud Infrastructure Concentration:Three hyperscale providers dominate video delivery compute, creating supplier power asymmetries for independent streaming operators.
- Net Neutrality Uncertainty:The FCC's evolving stance on traffic prioritization threatens quality-of-service guarantees for bandwidth-intensive 4K streams.
Strategic Opportunities
- Ad-Supported Tier Expansion:Price-sensitive demographics in India and Southeast Asia accept commercial interruptions in exchange for reduced subscription fees.
- Live Sports Betting Integration:Real-time wagering overlays during matches create incremental revenue per viewer through partnerships with regulated gambling platforms.
- EU Green Deal Alignment:Carbon-neutral data center certifications attract ESG-mandated institutional investors and enterprise procurement teams.
Industry Challenges
- Codec Patent Licensing Complexity:H.266/VVC and AV1 royalty frameworks remain unsettled, delaying hardware decoder deployment and compressing device compatibility windows.
- Localization Talent Scarcity:Dubbing and subtitling pipelines struggle to scale for simultaneous global releases, creating release-date gaps across linguistic markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Streaming Services Market |
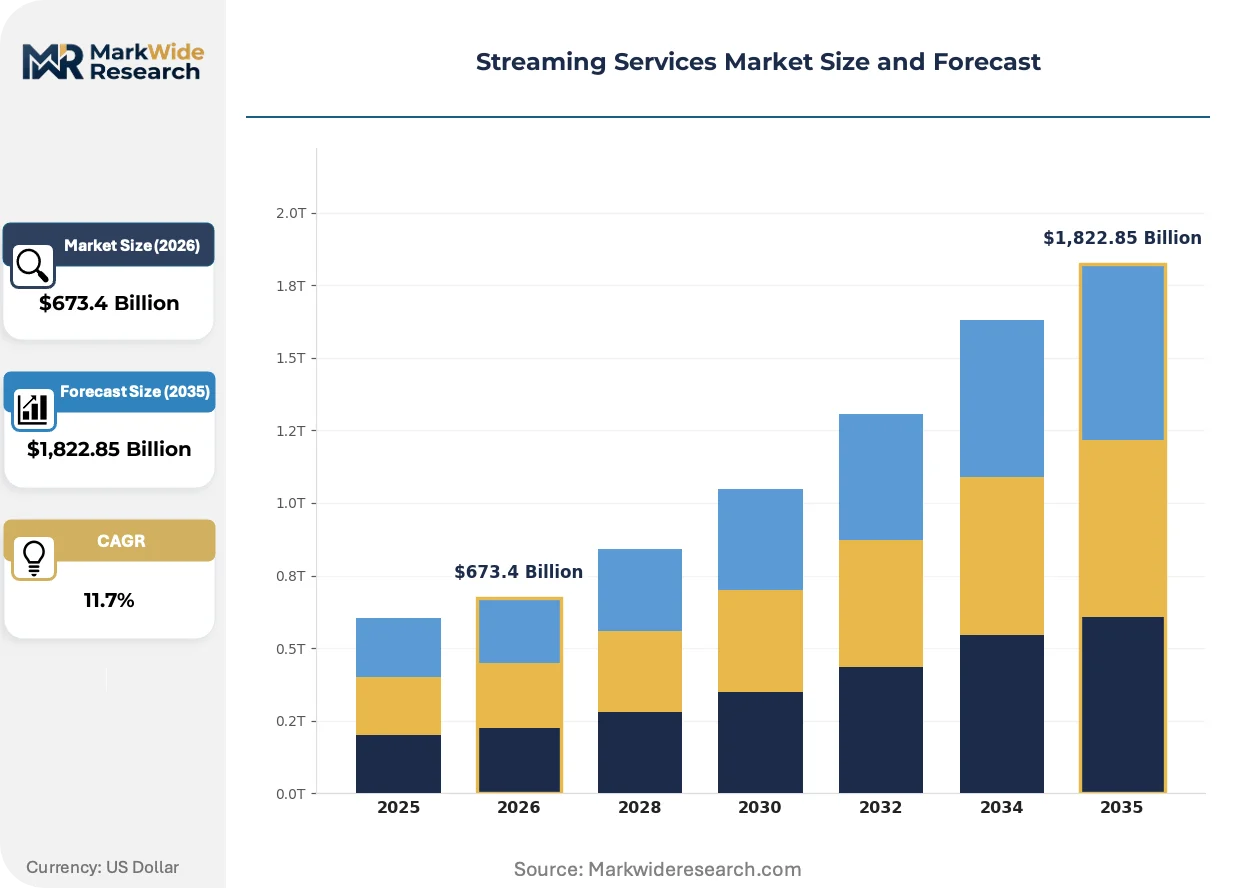
| Market Size in 2026 | $673.4 Billion |
| Market Size in 2035 | $1,822.85 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Subscription Model: Ad-Supported, Monthly Subscription, Annual Subscription, Pay-Per-View Content Type: Movies, TV Shows, Documentaries, Live Sports Device Type: Smart TVs, Mobiles, Tablets, Consoles Target Audience: Families, Students, Professionals, Seniors |
| Companies Covered | Max, Paramount+, Netflix, Peacock, Apple TV+, Amazon Prime Video, Hulu, ESPN+, Disney+, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Streaming Services Market Trends and Innovations
Streaming infrastructure is consolidating around edge-computing architectures that reduce latency for live content while regulatory pressure on algorithmic transparency reshapes platform engineering priorities.
AI-driven content personalization engines analyze viewing patterns to predict subscriber churn and recommend retention offers. Platforms deploy these systems across recommendation surfaces and email marketing channels. The technology is integrating predictive analytics into content acquisition decisions, shifting greenlight authority from creative executives to data science teams.
The EU AI Act imposes documentation requirements on automated content moderation systems that flag or demote material. Platforms must maintain audit trails for algorithmic decisions affecting content visibility. European operators are responding by hiring compliance engineers and restructuring machine-learning pipelines to satisfy ex-ante transparency mandates.
Subscription fatigue is fragmenting household spending across multiple services, compressing average tenure per platform. Consumers rotate memberships monthly to access exclusive releases, then cancel. This behavior concentrates in North American and Western European markets where platform density exceeds willingness to maintain simultaneous subscriptions.
Streaming Services Market Segmentation
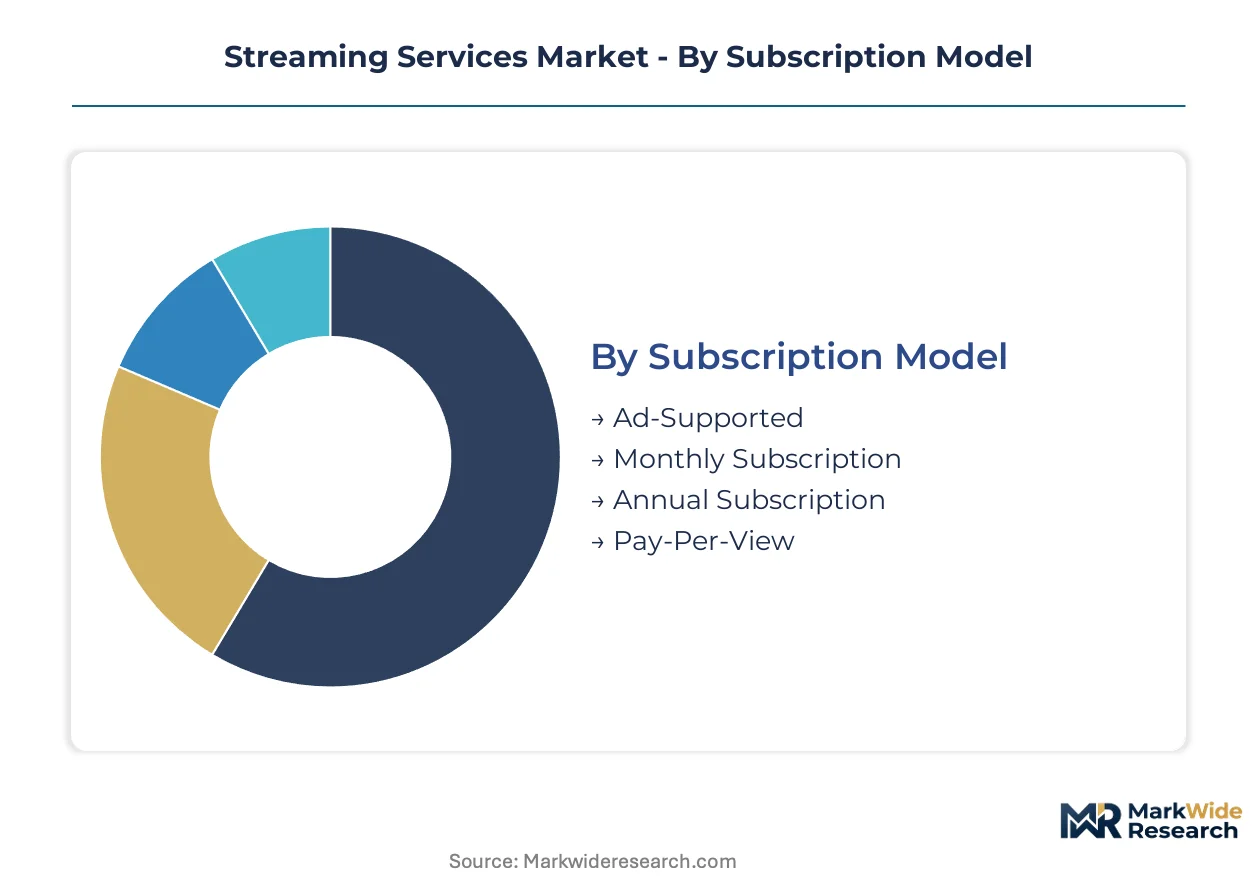
Streaming platforms engineer revenue architecture and content delivery around four distinct segmentation axes. Subscription models determine cash flow predictability, while content type shapes infrastructure investment and licensing strategy. Device and audience segmentation direct codec selection, user interface design, and geographic rollout sequencing.
Subscription Model:
Supply concentration in monthly subscriptions creates margin pressure as platforms compete for retention through original content spend.
- Ad-Supported:Lower entry price points offset by programmatic advertising revenue, with CPM rates climbing as connected TV inventory tightens. Demand concentrates in India and Southeast Asia where price sensitivity exceeds content exclusivity preferences. AVOD tiers are expanding most quickly as platforms chase subscriber volume over average revenue per user.
- Monthly Subscription:Recurring billing with cancellation flexibility dominates revenue pools across North American and Western European markets. This segment anchors platform valuation multiples and funds original production slates.
- Annual Subscription:Prepaid commitments improve cash flow visibility and reduce churn, typically offered at 15-20% discounts versus monthly rates. Enterprises favor annual terms for workforce training deployments.
- Pay-Per-View:Transactional access for live sports and theatrical window releases, capturing event-based demand without ongoing commitment. Margins compress under sports rights inflation.
Today's leader: Monthly Subscription. Tomorrow's challenger: Ad-Supported.
Content Type:
Production cost tiers stratify content investment, with live sports commanding disproportionate infrastructure and licensing expenditure.
- Live Sports:Real-time delivery demands sub-10-second latency and redundant edge infrastructure, with rights auctions inflating programming budgets unpredictably. Demand concentrates in Brazil, Mexico, and Saudi Arabia where football leagues drive platform selection.
- Movies:Theatrical window compression and direct-to-streaming releases reshape studio distribution economics, with 4K HDR mastering requirements elevating technical delivery standards.
- TV Shows:Serialized content generates sustained engagement and reduces cancellation rates through cliffhanger retention mechanics. Binge-release versus weekly episode strategies split by platform brand positioning.
- Documentaries:Lower production costs and awards prestige attract niche subscriber segments, with true crime and nature subgenres outperforming in retention metrics.
Live Sports commands the steepest expansion trajectory in subscriber acquisition spending.
Device Type:
Hardware distribution channels determine platform addressable market, with smart TV pre-installation agreements functioning as primary user acquisition funnels.
- Smart TVs:Native applications on Samsung, LG, and TCL hardware capture living room viewing sessions with highest average watch time per session. Platform operators negotiate revenue-share arrangements with television manufacturers for default placement.
- Mobiles:Smartphone-first consumption dominates India, Indonesia, and Nigeria where cellular data plans outpace fixed broadband penetration. Vertical video formats and download-for-offline features optimize for commute and fragmented viewing contexts.
- Tablets:Travel and co-viewing use cases sustain this segment despite smartphone screen size convergence, with higher completion rates for long-form content versus mobile.
- Consoles:Gaming hardware integration captures male-skewing demographics aged 18-34, with PlayStation and Xbox storefronts extracting 30% platform fees on subscription transactions.
Smart TVs retain viewing share leadership. Mobiles are climbing the fastest in emerging market penetration.
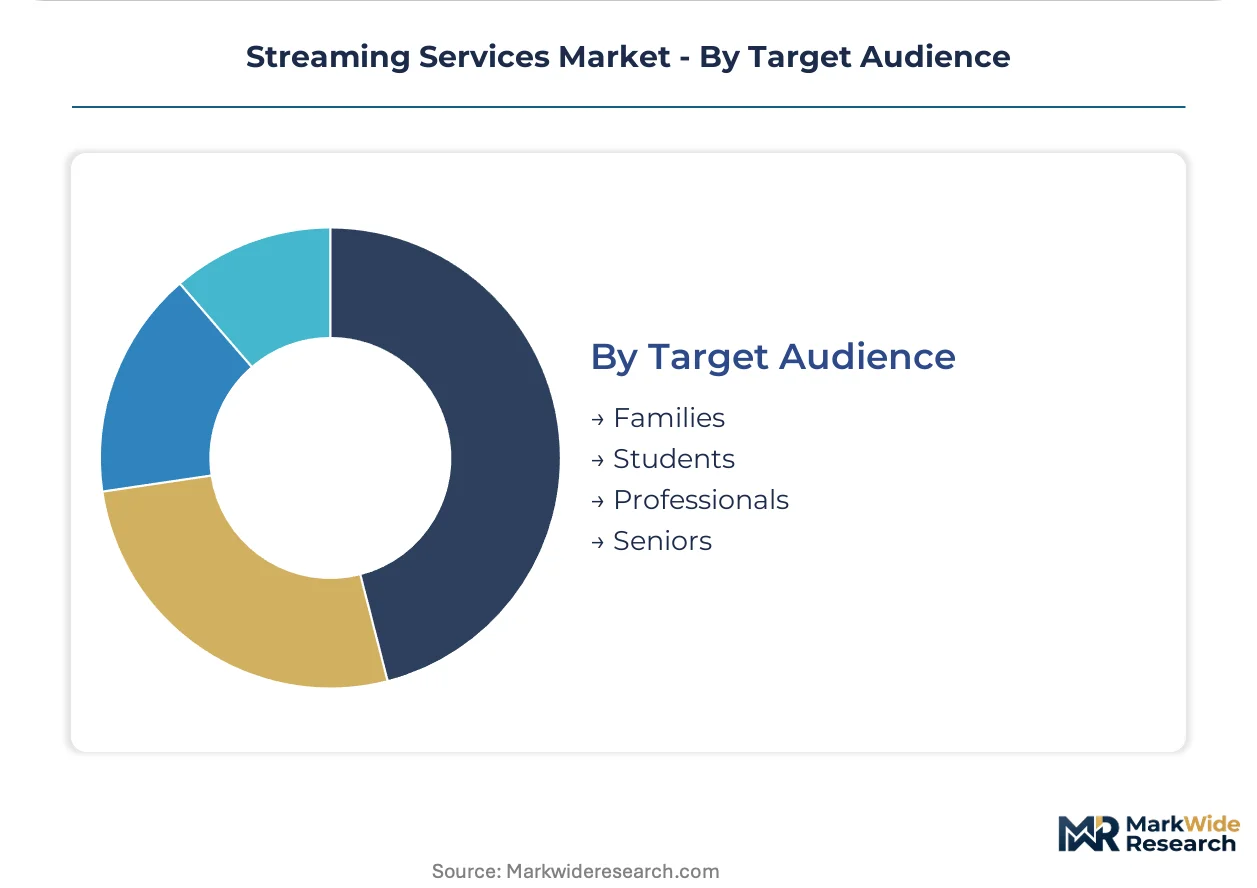
Target Audience:
Household composition and disposable income segmentation direct content acquisition and pricing architecture.
- Families:Parental controls, multiple user profiles, and children's content libraries justify premium tier pricing. Demand concentrates in suburban US and Canadian markets where shared viewing remains normative.
- Students:Discounted pricing through university email verification builds lifetime value through early habit formation, with mobile-first consumption patterns.
- Professionals:Time-shifted viewing and premium documentary access align with fragmented schedules and higher willingness to pay for ad-free experiences.
- Seniors:Simplified interfaces and legacy television content catalogs reduce onboarding friction, with customer service touchpoints requiring voice support optimization.
Families represent the highest lifetime value segment. Students are gaining share fastest in emerging market acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Bangalore and Hyderabad anchor India's streaming infrastructure buildout, while Los Angeles and London concentrate content production expertise that feeds platform libraries worldwide.
United States
Hollywood studio proximity and cloud infrastructure density in Northern Virginia drive platform headquarters concentration. The FCC's net neutrality deliberations shape traffic prioritization rules affecting 4K delivery quality. Los Angeles hosts the dominant content production cluster where Netflix and Disney+ commission original programming.
India
Broadband penetration into tier-two and tier-three cities unlocks subscriber bases exceeding 100 million potential users. TRAI mandates tariff transparency for over-the-top services, constraining pricing architecture flexibility. Bangalore anchors the technical operations hub where Disney+ Hotstar and Amazon Prime Video localize platform engineering.
Germany
EU AI Act compliance requirements reshape content moderation workflows for platforms serving German-speaking markets. The EU Green Deal imposes energy-efficiency reporting obligations on Frankfurt data centers powering streaming delivery. Munich hosts broadcast technology specialists supplying encoding infrastructure to European operators.
Brazil
Football league streaming rights command premium subscriber acquisition spending across Portuguese-speaking Latin America. ANVISA regulates advertising content for health and wellness categories appearing in platform ad tiers. São Paulo concentrates the regional headquarters operations for Netflix, Amazon Prime Video, and Disney+.
South Korea
K-content export demand drives platform investment in Korean drama and film acquisition. The country's national broadcasting regulator enforces content rating standards affecting parental control feature implementation. Seoul anchors the production cluster where CJ ENM and Studio Dragon supply programming to global platforms.
Streaming Services Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across subscription video-on-demand markets. The structure stratifies into three tiers: technology-anchored platforms with cloud infrastructure advantages, entertainment conglomerates leveraging studio libraries, and regional specialists targeting linguistic niche audiences. Competitive positioning depends on original content spend efficiency, subscriber acquisition cost discipline, and live sports rights portfolio depth. Consolidation pressure intensifies as platforms pursue M&A to expand geographic footprint and technology licensing to reduce encoding costs.
Among technology-anchored operators, Amazon.com Inc. and Apple Inc. exemplify the diversified conglomerate archetype, deploying streaming as a component of broader ecosystem lock-in strategies. Netflix Inc. occupies a position as the focused pure-play specialist, representing the standalone subscription revenue model without adjacent hardware or retail operations. These three entities anchor the competitive structure that smaller regional platforms must navigate through differentiation in local content or pricing.
| Leading Market Players |
|---|
| Max |
| Paramount+ |
| Netflix |
| Peacock |
| Apple TV+ |
| Amazon Prime Video |
| Hulu |
| ESPN+ |
| Disney+ |
| Others |
Pricing and Supply Chain Analysis
Enterprise procurement teams negotiating workforce training deployments concentrate buying power around annual subscription commitments, anchoring platform pricing models to recurring revenue predictability rather than transactional flexibility. This buyer archetype preference for prepaid terms compresses sales cycles while forcing ad-supported tiers to compete on marginal cost efficiency.
Pricing Analysis
The bundled-versus-unbundled service split separates premium ad-free experiences from commercial-interruption tiers across platform portfolios. Three-tier pricing structure across premium, standard, and economy levels differentiates by resolution grade and simultaneous stream count. Price differentiation stems from content exclusivity windows and geographic licensing cost variation. Pricing pressure intensifies in India and Southeast Asia where cellular data affordability constrains willingness to pay. Students and price-sensitive households exhibit highest price elasticity, while families with multiple user profiles demonstrate lowest sensitivity due to shared-account convenience.
Supply Chain Analysis
Single-source vulnerability sits with hyperscale cloud providers dominating video encoding and delivery infrastructure. Content delivery networks draw from concentrated server farms in the United States, Ireland, and Singapore. Raw material dependencies include silicon for encoding hardware, rare earth elements for data center cooling systems, and optical fiber for last-mile connectivity. Tariff exposure on Chinese-manufactured smart TV components threatens device affordability in price-sensitive markets. Distribution runs through original equipment manufacturer pre-installation agreements and direct-to-consumer app store downloads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The streaming services market represents a late-cycle quality story where subscriber retention now depends on premium 4K HDR and spatial audio specifications rather than content volume alone. Enterprise training demand shifts toward integrated learning management systems with analytics dashboards.
For Market Incumbents: Hedge against sports rights inflation by diversifying into documentary and unscripted content with lower production cost variance. Backward integration into cloud delivery infrastructure reduces marginal streaming costs and insulates against hyperscale provider pricing power. Defensive patent licensing around AV1 and H.266 codecs protects device compatibility windows from royalty framework uncertainty.
For New Entrants and Emerging Players: Mobile-first distribution channels in India, Indonesia, and Nigeria offer the most penetrable subscriber acquisition pathway. Regional language content pipelines with simultaneous dubbing capability unlock tier-two and tier-three city demand. Ad-supported tier launches with programmatic CPM optimization capture price-sensitive demographics without requiring original content spend.
For Investors and Strategic Acquirers: Technology conglomerates with adjacent cloud infrastructure are the most active acquirer in this space, pursuing targets with live sports rights portfolios. Long-term viability hinges on content localization talent pipelines and algorithmic transparency compliance architecture. Watch EU AI Act enforcement patterns as the inflection indicator for compliance cost trajectories across European operations.
| Strategic Initiative | Industry Significance |
|---|---|
| Ad-Supported Tier Expansion | Captures price-sensitive Indian subscribers through reduced entry fees offset by programmatic advertising revenue. |
| Live Sports Rights Acquisition | Brazilian and Saudi football league exclusives drive disproportionate subscriber retention across Latin American markets. |
| Edge Computing Infrastructure Deployment | Frankfurt and Mumbai data center expansions reduce latency for real-time sports wagering integration. |
| EU Green Deal Certification | Carbon-neutral delivery credentials attract ESG-mandated institutional capital and enterprise procurement teams. |
| Enterprise Training Platform Integration | Workforce upskilling modules with analytics dashboards compress B2B sales cycles and improve annual contract value. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary conversations with platform engineering executives, content acquisition leads, TRAI regulatory affairs specialists, and enterprise training procurement officers supplied operational data. Secondary validation drew from FCC net neutrality filings, EU AI Act implementation guidance, SEC 10-K streaming segment disclosures, and hyperscaler capex announcements. Bottom-up subscriber modeling and top-down market sizing triangulated volume estimates.
Segment-weighting approaches applied differential growth assumptions across subscription models, content types, device categories, and audience demographics. Deployment architecture, content localization intensity, and regional broadband penetration patterns shaped the analytical framework. CAGRs derived from trend extrapolation anchored in historical subscriber trajectory and pricing elasticity parameters. Codec licensing timelines and data center energy efficiency standards entered as scenario variables.
Regulatory enforcement variance, sports rights auction outcomes, and net neutrality rule reversals are the dominant revision risks to modeled trajectories. Forecasts reflect documented assumptions about broadband infrastructure rollout pace and enterprise adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Advertising-Based Video on Demand Market
Video Streaming (OTT) Services
Video Streaming Market
Video Streaming (OTT) Services
Sports Streaming Platform Market
Video Streaming (OTT) Services
Streaming Spending Market
Video Streaming (OTT) Services
OTT Content Market
Video Streaming (OTT) Services
Global Transactional Video on Demand Market
Video Streaming (OTT) Services
Global Live Streaming Video Platform Market
Video Streaming (OTT) Services
Online Video Platform Market
Video Streaming (OTT) Services
Video on Demand Market
Video Streaming (OTT) Services
Enterprise Streaming Media Market
Video Streaming (OTT) Services
Global Svod Market
Video Streaming (OTT) Services
United States OTT Market
Video Streaming (OTT) Services
Mexico OTT TV and Video Market
Video Streaming (OTT) Services
Live Streaming Market
Video Streaming (OTT) Services
India Smart TV and OTT Market
Video Streaming (OTT) Services
Live Streaming Pay-Per-View Market