
 Subscription Video on Demand (Svod) Market | 2026-2036
Subscription Video on Demand (Svod) Market Size, Share, and Industry Trends Forecast 2026-2036
Subscription Video on Demand (Svod) Market Analytics
Original content production spending is reshaping margin-pool migration from licensed third-party catalogs toward captive studio output. Netflix dominates exclusive programming investment across drama and unscripted verticals. Disney+ anchors family-oriented intellectual property franchises that sustain multi-year subscriber retention. Amazon Prime Video leverages its e-commerce bundling architecture to subsidize video acquisition costs.
Subscription Video on Demand denotes a digital content delivery model where users pay recurring fees for unlimited access to streaming libraries hosted on cloud infrastructure with adaptive bitrate protocols. The primary commercial purpose centers on replacing linear broadcast consumption with algorithm-curated, on-demand viewing across internet-connected endpoints. Premium subscription models command the deepest margin pools as consumers accept higher monthly outlays for ad-free experiences and simultaneous stream allowances. Smart TV platforms represent the fastest-growing endpoint category as original equipment manufacturers embed native applications directly into television operating systems.
The Federal Communications Commission enforces net neutrality principles that prevent internet service providers from throttling streaming traffic, while the European Union Digital Services Act imposes transparency obligations on recommendation algorithms and content moderation practices. These frameworks shape platform technical architectures and content licensing negotiations. Stakeholders must monitor regulatory divergence between bandwidth utility classifications and algorithmic accountability mandates as jurisdictions develop divergent compliance standards.
Market Dynamics
Original content production spending is compressing licensed catalog margins while cloud-based encoding infrastructure is virtualizing distribution economics across streaming platforms. The structural force reshaping competitive positioning centers on captive studio output replacing third-party licensing as the primary subscriber acquisition mechanism.
Growth Catalysts
- Broadband infrastructure expansion:Fiber deployment in Brazil and India is extending addressable household reach for 4K streaming services. Government spectrum allocation programs accelerate last-mile connectivity in underserved municipalities.
- FCC net neutrality enforcement:Throttling prohibitions preserve consistent streaming quality across internet service provider networks. This regulatory framework prevents bandwidth discrimination against video traffic.
- Smart TV native application embedding:Original equipment manufacturers pre-install streaming clients directly into television operating systems. This technical integration removes friction from subscriber onboarding workflows.
Market Restraints
- Content cost inflation:Exclusive programming licensing fees and production budgets escalate faster than subscription pricing power. Sports rights auctions in particular compress platform margins.
- EU Digital Services Act compliance:Transparency obligations for recommendation algorithms impose engineering overhead and audit costs. Content moderation staffing requirements add operational fixed costs.
- Subscription fatigue accumulation:Households face mounting monthly outlays across multiple streaming services. Churn rates intensify as consumers rotate between platforms quarterly.
Strategic Opportunities
- Ad-supported tier penetration:Lower-price subscription options capture price-sensitive segments without cannibalizing premium subscribers. Advertiser demand for connected television inventory exceeds available supply.
- Live event streaming integration:Sports and concert broadcasts attract episodic subscribers who convert to annual commitments. This content category commands premium advertising rates.
- Cloud gaming convergence:Interactive entertainment bundles with video subscriptions increase platform stickiness. Microsoft and Sony infrastructure investments validate this technical architecture.
Industry Challenges
- Data science talent scarcity:Recommendation algorithm optimization requires specialized machine learning expertise. Compensation inflation for these roles outpaces general technology hiring.
- Legacy content delivery network migration:Transitioning from third-party CDN contracts to proprietary edge infrastructure demands capital deployment and engineering reorganization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subscription Video on Demand (Svod) Market |
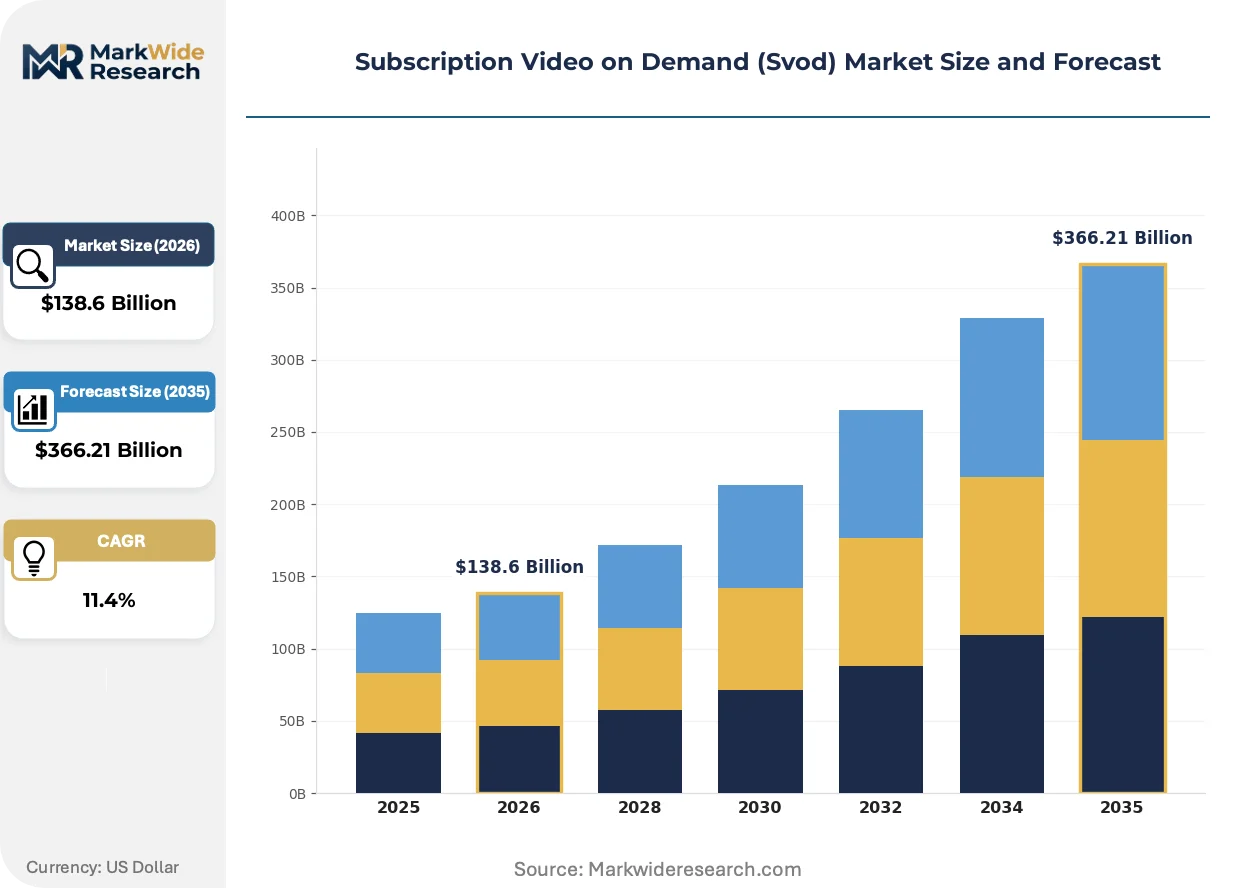
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $366.21 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ad-Supported, Premium, Bundled, On-Demand Content Type: Movies, TV Shows, Documentaries, Original Series Platform: Smart TVs, Mobile Apps, Streaming Devices, Desktop Subscription Model: Monthly, Annual, Pay-Per-View, Trial |
| Companies Covered | Netflix, Amazon Prime Video, Disney+, Hulu, Apple TV+, HBO Max, Paramount+, Peacock, Discovery+, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subscription Video on Demand (Svod) Market Evolving Landscape
Cloud-native encoding and serverless streaming architectures are compressing infrastructure costs while enabling real-time personalization at scale. The dominant technical trajectory centers on virtualizing hardware-dependent functions into software-defined workflows.
Edge computing infrastructure is virtualizing content delivery by pushing encoding and caching closer to end-user locations. Streaming platforms deploy micro-data centers within internet service provider networks to reduce latency. This distributed architecture enables interactive features and reduces origin server load during peak viewing hours.
The EU Digital Services Act imposes algorithmic transparency mandates that force platforms to document recommendation system logic. Engineering teams must build audit trails and explainability interfaces that increase development overhead. Family-oriented content categories face heightened scrutiny under these accountability requirements.
Household viewing patterns are fragmenting across multiple simultaneous subscriptions with shorter average tenure per platform. Consumers rotate services monthly rather than maintaining year-round commitments to single providers. This behavioral shift is most pronounced among younger demographics in the United States and United Kingdom.
Subscription Video on Demand (Svod) Market Segmentation
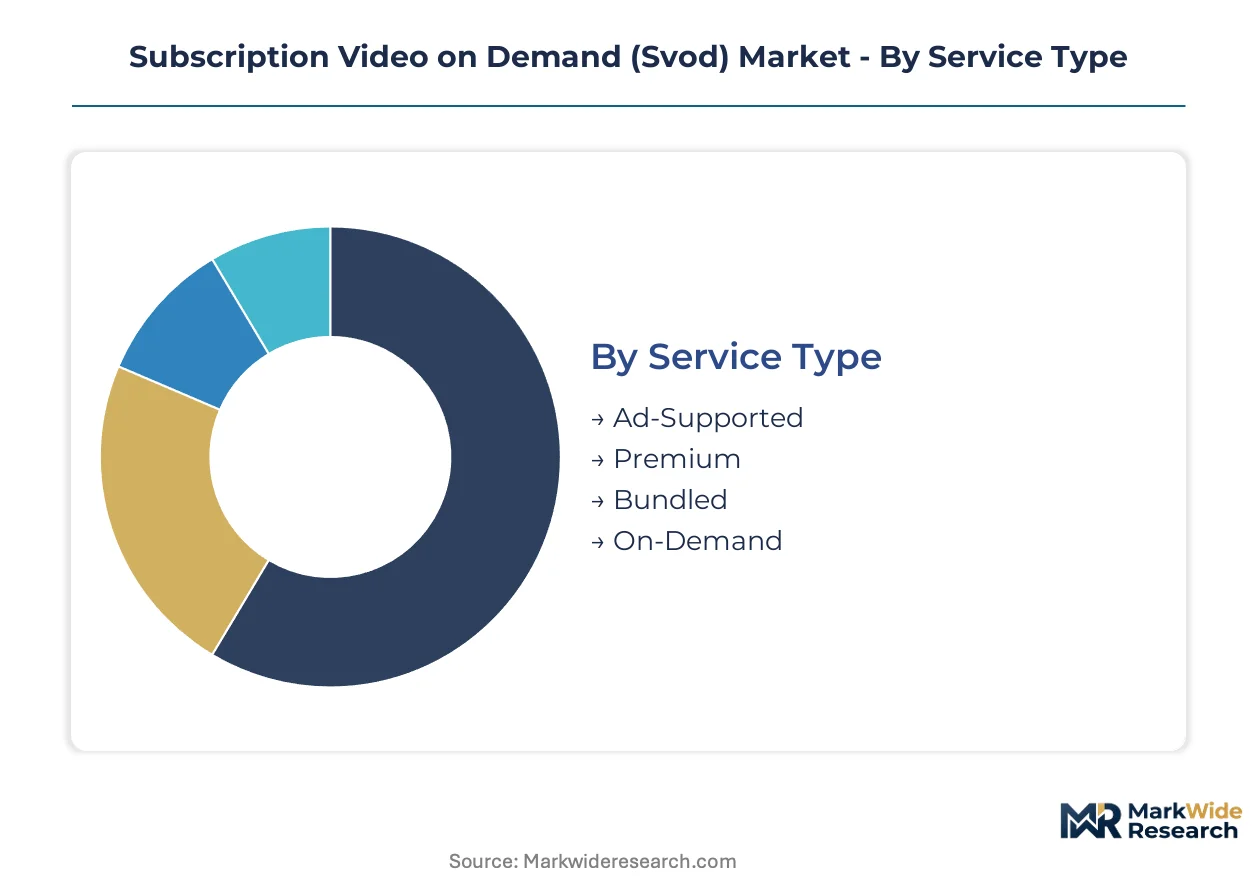
Segmentation in the Subscription Video on Demand market reveals how platform economics fragment across pricing tolerance, content preferences, and device ecosystems. Each dimension carries distinct margin profiles and subscriber lifetime value characteristics that shape capital allocation decisions.
Service Type:
Mature premium tiers anchor revenue pools while emerging ad-supported formats reshape acquisition economics across price-sensitive demographics.
- Premium:Ad-free experiences with simultaneous stream allowances command the highest monthly outlays and lowest churn rates. Households in the United States sustain this tier through multi-year commitments driven by exclusive original programming investments.
- Ad-Supported:Lower-price entry points capture price-sensitive segments without cannibalizing full-rate subscribers. Brazil and India exhibit concentrated uptake here as broadband expansion meets localized content libraries.
- Bundled:E-commerce and telecommunications packaging subsidizes video acquisition costs through cross-subsidy architectures.
- On-Demand:Transactional rental models serve episodic viewers seeking specific theatrical releases outside subscription commitments.
Premium retains volume leadership; Ad-Supported holds the steepest expansion curve.
Content Type:
Production cost tiers separate catalog strategies, with scripted originals demanding capital intensity that unscripted and licensed libraries cannot match.
- Original Series:Exclusive drama and unscripted programming drives subscriber acquisition and platform differentiation. Netflix anchors global investment here, while Disney+ leverages family-oriented intellectual property franchises for multi-year retention.
- Movies:Theatrical windowing compression accelerates streaming-first releases. India demonstrates concentrated demand for regional language film libraries as broadband infrastructure extends.
- TV Shows:Licensed catalog content fills engagement gaps between original production cycles.
- Documentaries:Lower production costs attract niche subscriber segments with above-average educational attainment.
Original Series commands the deepest margin pools; Documentaries are climbing the fastest as production efficiency improves.
Platform:
Endpoint distribution economics favor integrated hardware-software ecosystems over third-party application layers.
- Smart TVs:Native application embedding removes friction from subscriber onboarding as original equipment manufacturers pre-install streaming clients directly into television operating systems. United States household penetration accelerates cord-cutting behavior through connected television ecosystems.
- Mobile Apps:India exhibits concentrated mobile-first consumption patterns where smartphone screens dominate viewing time.
- Streaming Devices:External hardware attachments serve legacy television installations and hospitality verticals.
- Desktop:Browser-based access retains importance for workplace viewing and secondary screen companion experiences.
Smart TVs dominate engagement duration; Mobile Apps are gaining share fastest in emerging markets.
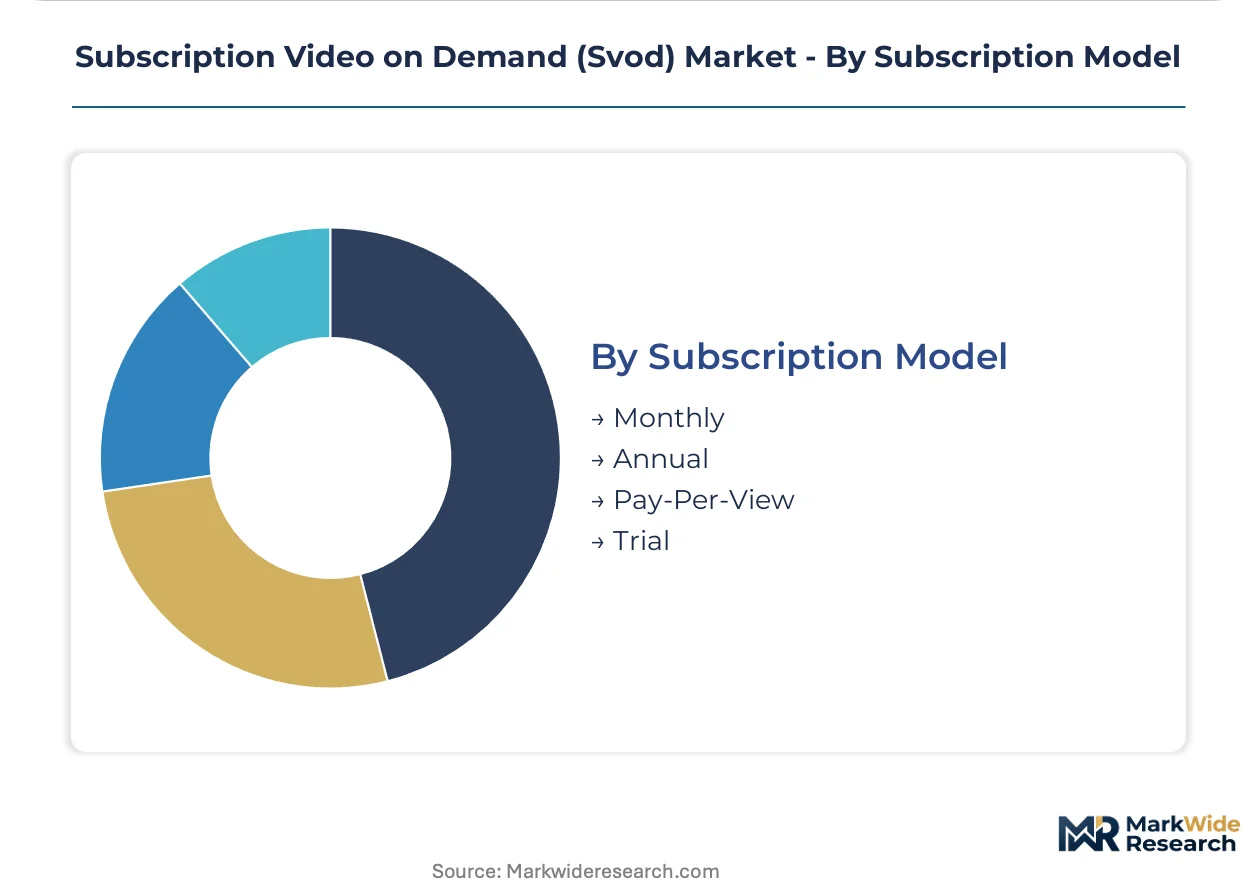
Subscription Model:
Commitment structures segment cash flow predictability, with annual prepayment improving working capital against monthly flexibility preferences.
- Monthly:Flexible cancellation terms accommodate subscription fatigue behaviors where households rotate services quarterly. Younger demographics in the United States and United Kingdom exhibit pronounced tenure fragmentation here.
- Annual:Prepaid commitments reduce churn exposure and improve customer lifetime value calculations. Brazil shows concentrated uptake where currency volatility encourages locking in exchange rates.
- Trial:Free-to-paid conversion funnels require content front-loading to demonstrate value before billing initiation.
- Pay-Per-View:Event-based access serves live sports and concert broadcasts with premium advertising rates.
Monthly sustains subscriber counts; Annual is expanding most quickly as platforms incentivize commitment through pricing discounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Household viewing patterns diverge sharply across geographies. United States consumers prioritize ad-free premium tiers with simultaneous streaming allowances. Brazilian and Indian households concentrate in mobile-first, ad-supported segments where localized content libraries drive platform selection.
United States
Cord-cutting acceleration and connected television penetration sustain premium subscription demand. FCC net neutrality enforcement prevents internet service providers from throttling streaming traffic. Los Angeles anchors original content production with studio facilities concentrated in Burbank and Culver City.
Brazil
Fiber deployment in São Paulo and Rio de Janeiro extends broadband reach for 4K streaming services. Government spectrum allocation programs accelerate last-mile connectivity in underserved municipalities. São Paulo hosts the dominant regional content localization hub for Portuguese-language programming.
India
Smartphone-first consumption patterns concentrate viewing time on mobile applications. TRAI regulatory frameworks govern content moderation and data localization requirements. Mumbai and Hyderabad sustain original series production facilities serving Hindi and regional language markets.
United Kingdom
Subscription fatigue behaviors intensify quarterly platform rotation among younger demographics. Ofcom broadcasting standards intersect with EU Digital Services Act transparency obligations for recommendation algorithms. London clusters streaming technology engineering talent and post-production facilities.
Germany
Annual prepaid commitments reduce churn exposure amid currency volatility concerns. GDPR compliance requirements shape data handling architectures for subscriber analytics. Berlin and Munich concentrate European headquarters operations for major platform operators.
Subscription Video on Demand (Svod) Market Competitive Landscape
Capability concentration sits with original content production studios; scale advantage sits with technology-integrated distribution platforms. The market structure fragments across three tiers: global pure-play streamers, diversified media conglomerates with captive libraries, and e-commerce or telecommunications bundlers subsidizing video acquisition. Strategic archetypes include exclusive programming investors, intellectual property franchise holders, and cross-subsidy bundlers. Competitive moves center on sports rights auctions and proprietary edge infrastructure deployment.
Among pure-play streaming specialists, Netflix and Disney+ exemplify divergent content strategies. Netflix occupies the position of drama and unscripted programming investor with global distribution scale. Disney+ represents the intellectual property franchise model anchored on family-oriented retention mechanics. Amazon Prime Video sits within the cross-subsidy tier where e-commerce bundling architecture subsidizes video acquisition costs.
| Leading Market Players |
|---|
| Netflix |
| Amazon Prime Video |
| Disney+ |
| Hulu |
| Apple TV+ |
| HBO Max |
| Paramount+ |
| Peacock |
| Discovery+ |
| Others |
Value Network & Pricing Analysis
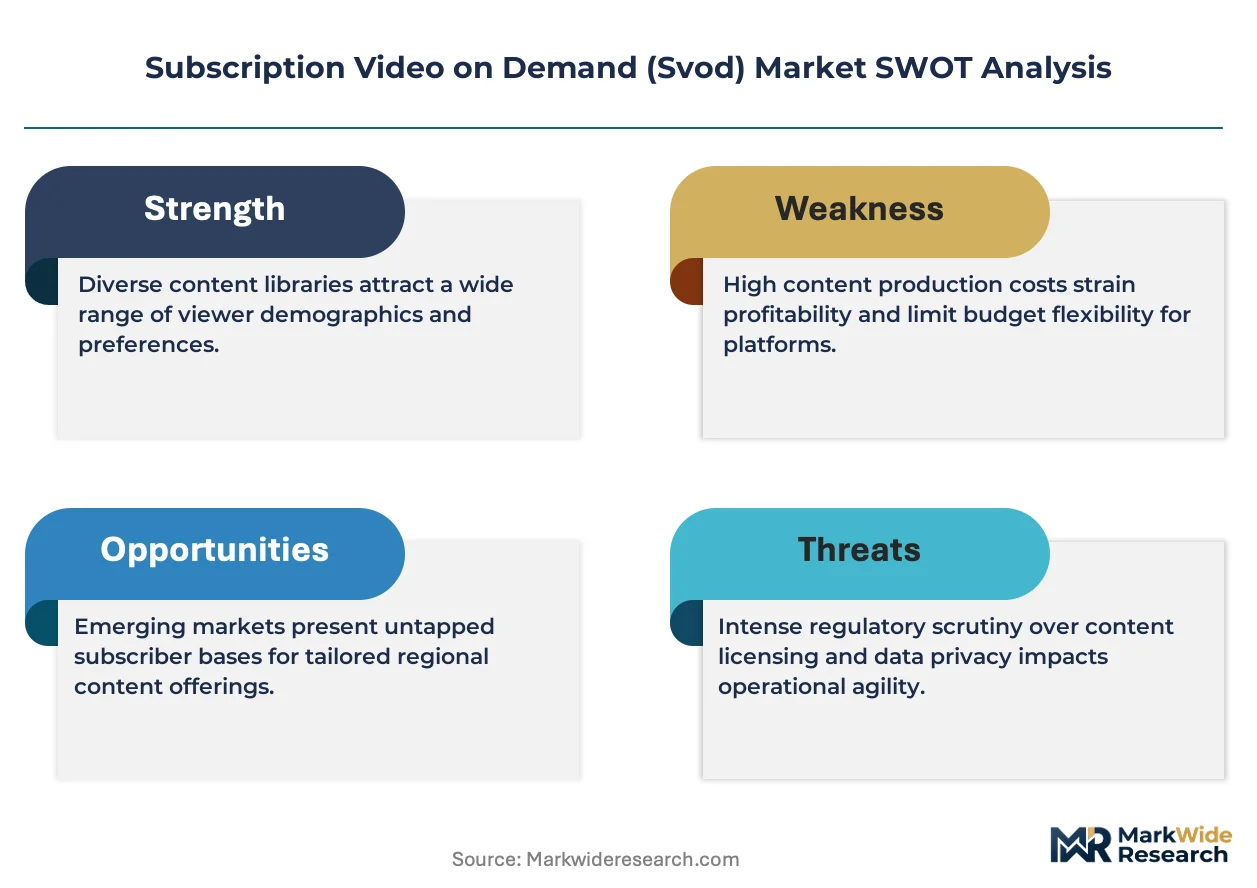
Regulatory bandwidth chokepoints under FCC net neutrality provisions and EU Digital Services Act obligations determine both tiered subscription spreads and cloud infrastructure deployment patterns across streaming platforms. These compliance frameworks force capital allocation toward edge computing nodes and algorithmic audit systems that compress margins in ad-supported tiers while preserving premium pricing power.
Pricing Analysis
Long-term content licensing contracts anchor platform economics alongside spot-market sports rights auctions that introduce volatility into acquisition budgets. Three-tier pricing structure across premium, ad-supported, and bundled levels separates households by price sensitivity and simultaneous stream requirements. Pricing pressure stems from escalating original production budgets that outpace subscription pricing power in mature markets. Ad-supported tiers capture the most price-sensitive segments in Brazil and India, while premium commitments dominate United States households with multi-year retention mechanics.
Supply Chain Analysis
Upstream cloud encoding infrastructure and content delivery network capacity concentrate supply-side leverage among hyperscale providers in the United States, Ireland, and Singapore. Streaming platforms draw from proprietary edge servers, third-party CDN contracts, and ISP-co-located micro-data centers to virtualize distribution. Single-source vulnerability sits with concentrated hyperscale cloud providers for transcoding and storage workloads. Distribution runs through smart TV native applications, mobile carrier bundling, and direct-to-consumer web portals that fragment endpoint control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect around smart TV operating system interoperability as original equipment manufacturers consolidate control over subscriber onboarding workflows and native application distribution.
For Market Incumbents: Pre-empt churn acceleration by locking exclusive original programming into multi-year output deals before sports rights inflation escalates further. Prioritize backward integration into cloud gaming infrastructure to increase platform stickiness against emerging interactive entertainment bundlers. FCC net neutrality enforcement preserves consistent streaming quality but intensifies competition for bandwidth-intensive live event content. For New Entrants and Emerging Players: Establish a beachhead in localized ad-supported tiers across Brazilian and Indian municipalities where broadband expansion meets underserved price-sensitive demand. Target mobile-first consumption patterns with smartphone-optimized encoding and regional language content libraries. Go-to-market through telecommunications bundling partnerships that subsidize customer acquisition costs. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors intellectual property franchise holders with multi-year subscriber retention mechanics and captive studio output capabilities. Long-term viability centers on platforms with demonstrated pricing power in premium tiers and engineering depth in recommendation algorithm optimization. Watch sports rights auction intensity as an inflection indicator for margin compression velocity across the sector.| Strategic Initiative | Industry Significance |
|---|---|
| Original Content Production Scale-Up | Captive studio output displaces licensed catalog dependencies for Netflix and Disney+ subscriber acquisition. |
| Edge Infrastructure Deployment | Micro-data centers within ISP networks reduce latency for Amazon Prime Video interactive features. |
| Ad-Supported Tier Launch | Lower-price entry points capture Brazilian and Indian price-sensitive segments without cannibalizing premium subscribers. |
| Smart TV OS Partnership | Native application embedding removes friction from subscriber onboarding for Samsung and LG television ecosystems. |
| Cloud Gaming Convergence | Interactive entertainment bundles with Microsoft and Sony infrastructure validate technical architecture for platform stickiness. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with streaming platform executives, content licensing directors, smart TV original equipment manufacturer product managers, telecommunications bundling strategists, and FCC regulatory affairs specialists. Secondary validation drew from SEC 10-K filings, EU Digital Services Act implementation guidance, TRAI broadcast sector reports, and hyperscaler capex disclosures. Bottom-up subscriber and revenue modeling triangulated against top-down market sizing from broadband penetration curves and cord-cutting velocity metrics.
Calibration against historical subscription growth trajectories and content spend-to-revenue ratios anchored projections across the analysis window. Segmentation dimensions modeled include service type tier, content category capital intensity, platform endpoint distribution, and regional regulatory cluster. CAGRs derived from regression analysis of broadband infrastructure deployment schedules and household disposable income elasticity. Forecast inputs incorporated sports rights auction cycles and EU algorithmic transparency compliance cost estimates.
Stress conditions across FCC net neutrality enforcement variance, EU Digital Services Act audit cost inflation, and Brazilian real currency volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about cord-cutting acceleration rates and smart TV replacement cycles. Quarterly review of sports rights auction intensity and churn rate inflection is advised to detect margin compression signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Video-On-Demand [Vod] Market
Video Streaming (OTT) Services
India Smart TV and OTT Market
Video Streaming (OTT) Services
Global Live Streaming Video Platform Market
Video Streaming (OTT) Services
Online Streaming Service Market
Video Streaming (OTT) Services
Global Svod Market
Video Streaming (OTT) Services
Online Video Platform Market
Video Streaming (OTT) Services
Video on Demand Market
Video Streaming (OTT) Services
Video Streaming Market
Video Streaming (OTT) Services
Live Streaming Pay-Per-View Market
Video Streaming (OTT) Services
E-Sports and Games Streaming Market
Video Streaming (OTT) Services
Global Transactional Video on Demand Market
Video Streaming (OTT) Services
Game Streaming Market
Video Streaming (OTT) Services
Indonesia OTT Market
Video Streaming (OTT) Services
Media Streaming Market
Video Streaming (OTT) Services
Live Streaming Market
Video Streaming (OTT) Services
Streaming Media Services Market