
 Media Streaming Market | 2026-2036
Media Streaming Market Size, Share, and Industry Trends Forecast 2026-2036
Media Streaming Market Outlook
Multi-source content licensing is restructuring how platforms secure exclusive programming. Netflix Inc. leverages its in-house production network across multiple continents to reduce dependency on third-party studios. Amazon.com Inc. anchors its streaming portfolio within a broader Prime membership ecosystem, blending retail and entertainment value. Apple Inc. differentiates through premium original content budgets and tight hardware-software integration across its device base.
Media streaming encompasses the digital transmission of audio-visual content over internet protocol networks, utilizing adaptive bitrate streaming technologies such as HLS and DASH to maintain playback quality across variable bandwidth conditions. The technology serves commercial entertainment delivery, enterprise communications, and institutional education by enabling real-time or on-demand access without local storage requirements. Subscription services dominate revenue generation through recurring billing models, while ad-supported tiers capture price-sensitive audiences and expand total addressable reach. Smart TV platforms represent the fastest-growing consumption endpoint as household viewing shifts from linear broadcast to internet-connected displays. Live events, particularly sports, command premium pricing and attract sustained advertiser commitment due to appointment-viewing behavior.
The FCC in the United States enforces net neutrality principles that affect bandwidth prioritization and streaming quality of service, while the EU's GDPR and Digital Services Act impose strict data governance and algorithmic transparency obligations on platforms operating across member states. Content rating frameworks from national regulators in Germany, France, and the United Kingdom shape age-gating requirements and editorial investment decisions. Stakeholders must monitor evolving interoperability mandates and cross-border licensing complexity as fragmentation between regional regulatory regimes intensifies.
Market Dynamics
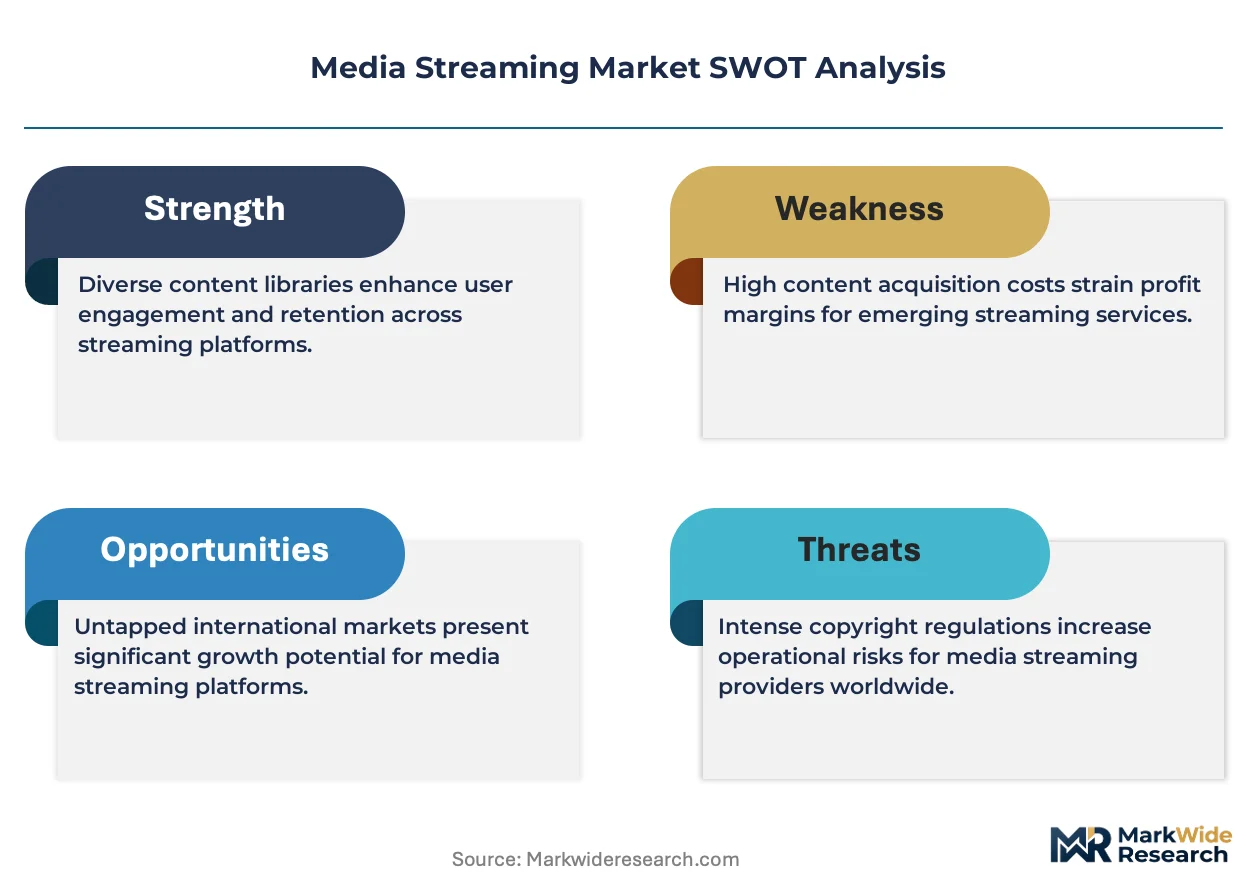
Adaptive bitrate streaming protocols are compressing infrastructure costs while fragmenting audience attention across multiple simultaneous subscriptions, forcing platforms to defend retention through exclusive content investments rather than technical differentiation alone.
Growth Catalysts
- EU AI Act compliance mandates:Platforms operating across member states must reengineer recommendation algorithms for transparency, creating demand for explainable AI tooling and audit services.
- Enterprise education deployment:Universities and corporate training departments are adopting lecture-capture and remote learning platforms at accelerated procurement cycles.
- India mobile-first consumption:Regional language originals and low-bandwidth optimization are unlocking subscriber growth in tier-2 and tier-3 cities.
Market Restraints
- Content licensing cost inflation:Sports rights and premium franchise exclusives command escalating minimum guarantees, compressing platform margins.
- CDN bandwidth concentration:Three hyperscale cloud providers control critical edge delivery infrastructure, creating single-source dependency risk.
- Cross-border data friction:GDPR localization requirements and India's data protection rules fragment content libraries and complicate personalization engines.
Strategic Opportunities
- Ad-supported tier expansion:Price-sensitive subscriber segments in Southeast Asia and Latin America represent addressable audiences previously excluded from paid subscriptions.
- Live commerce convergence:Streaming platforms integrating shoppable video with entertainment content are capturing retail media budgets from traditional digital advertising.
- Smart TV OS bundling:Pre-installed application deals with Samsung, LG, and TCL reduce customer acquisition costs and improve retention through reduced friction.
Industry Challenges
- Machine learning engineer scarcity:Recommendation system optimization and real-time personalization require specialized talent concentrated at major technology employers.
- Legacy broadcast integration:Sports leagues and content studios maintain parallel linear distribution contracts, complicating exclusive windowing strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Media Streaming Market |
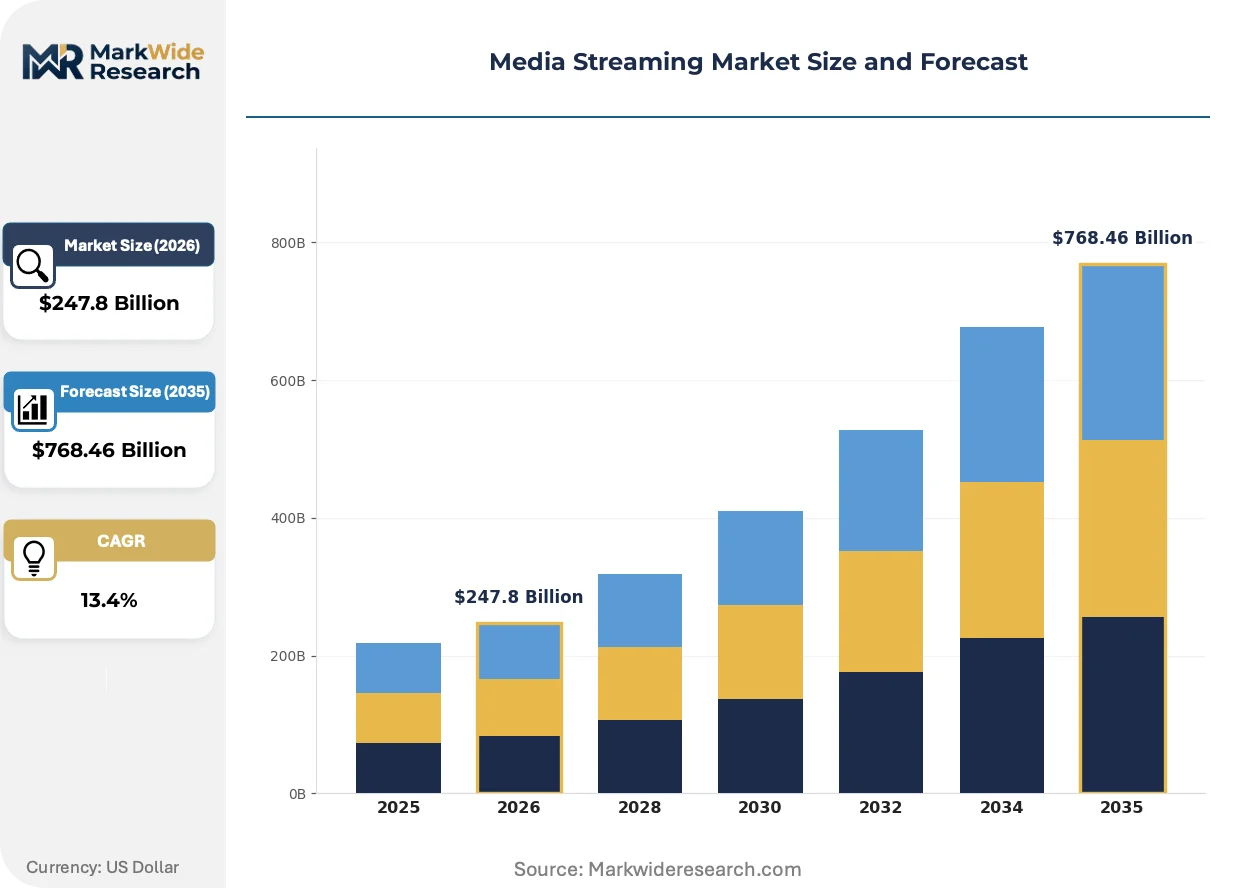
| Market Size in 2026 | $247.8 Billion |
| Market Size in 2035 | $768.46 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Subscription, Ad-Supported, Pay-Per-View, Free Content Type: Movies, TV Shows, Sports, Live Events End User: Consumers, Businesses, Educational Institutions, Government Platform: Web, Mobile, Smart TV, Gaming Consoles |
| Companies Covered | Netflix Inc., Amazon.com Inc., Alphabet Inc., The Walt Disney Company, Apple Inc., Warner Bros. Discovery Inc., Tencent Holdings Ltd., iQIYI Inc., Comcast Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Media Streaming Market Strategic Shifts
Generative AI tools are compressing production timelines for localized dubbing, subtitling, and promotional asset generation while raising new intellectual property and labor displacement concerns across content supply chains.
Edge computing infrastructure is automating real-time encoding decisions at the network periphery, reducing origin server load and improving start-up latency for viewers on congested last-mile connections. Telecommunications operators in Germany and South Korea are deploying these nodes aggressively. The structural consequence is shifting capital expenditure from centralized hyperscale data centers toward distributed telco partnerships.
The EU Digital Services Act imposes algorithmic transparency and risk assessment obligations on platforms with over 45 million monthly active users, mandating external auditing and public disclosure of content moderation systems. Content recommendation engines must now document ranking parameters and provide user override options. French and German regulators are pioneering enforcement frameworks that other member states are adopting.
Viewer subscription behavior is fragmenting into sequential rather than simultaneous platform relationships, with households rotating services monthly based on content release calendars. This "subscription hopping" pattern compresses customer lifetime value calculations and forces platforms toward event-driven retention tactics. The phenomenon is most pronounced among 18-34 age demographics in the United States and United Kingdom.
Media Streaming Market Segmentation
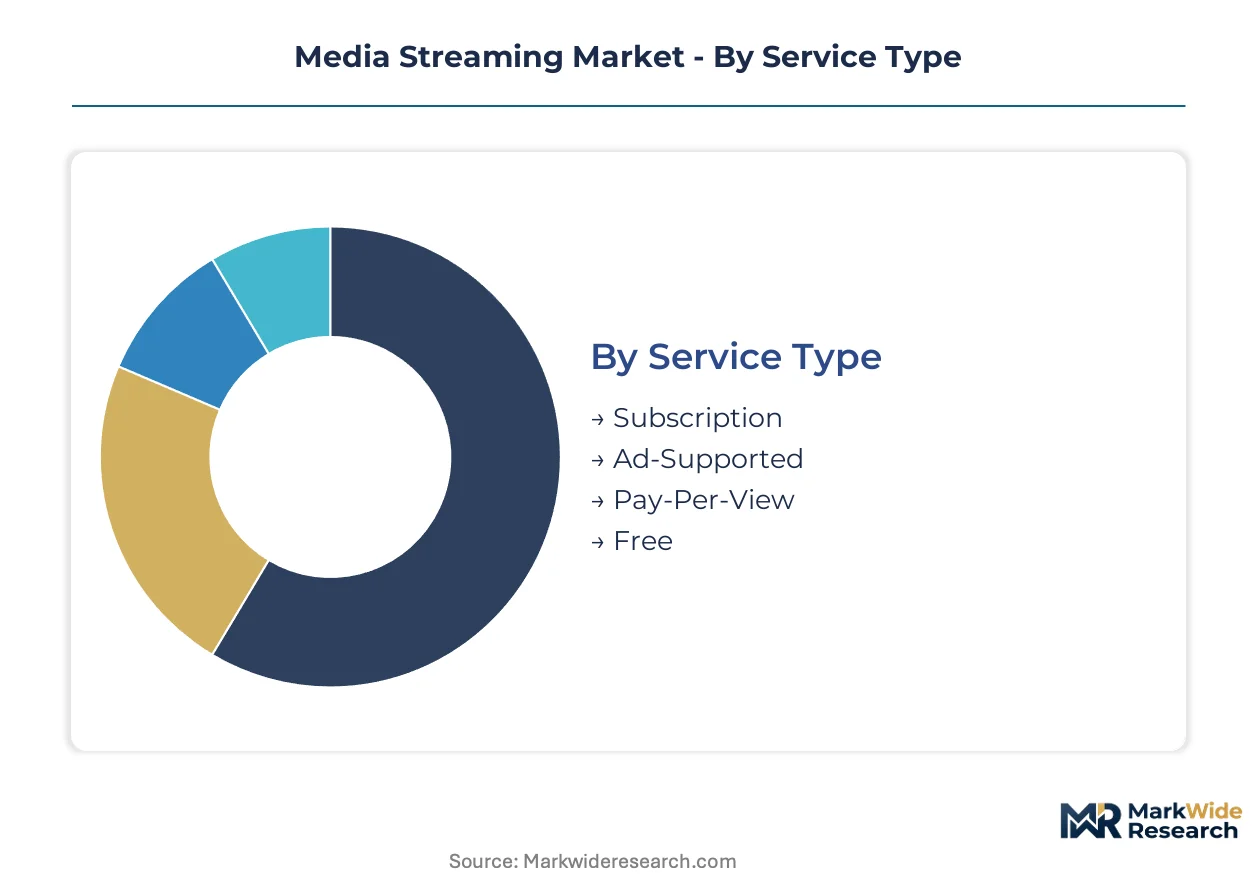
Segmentation in media streaming reveals how monetization models, content formats, and access devices create distinct competitive arenas with diverging margin profiles and regulatory exposure. Platform operators must align infrastructure investments with the specific consumption patterns and payment behaviors of each segment cluster.
Service Type:
Revenue capture mechanisms differentiate platforms through billing frequency, advertising load tolerance, and content exclusivity windows.
- Subscription:Recurring monthly or annual billing generates predictable revenue streams and funds exclusive original programming investments. Enterprise learning management systems and premium entertainment bundles in Germany and South Korea anchor demand concentration here.
- Ad-Supported:Lower or zero consumer fees attract price-sensitive audiences while delivering targeted impressions to retail media buyers. Southeast Asian markets and Latin American tier-2 cities are driving platform investments in this tier as smartphone penetration deepens.
- Pay-Per-View:Transactional access to live sports championships and premium movie releases captures event-driven viewing occasions without ongoing commitment.
- Free:Library content supported by advertising or public funding serves as acquisition funnel entry points and regulatory compliance vehicles in jurisdictions with local content quotas.
Mature deployment sits with Subscription. Newer deployment is concentrated in Ad-Supported.
Content Type:
Production cost structures and licensing complexity vary dramatically across entertainment formats, shaping platform portfolio strategies.
- Movies:Feature-length productions command windowing negotiations with theatrical distributors and carry high per-title acquisition costs. Indian regional language originals and Korean genre films are expanding addressable audiences beyond English-language dominance.
- TV Shows:Serialized episodic content drives sustained engagement and reduces churn through cliffhanger retention mechanics. European co-productions under the EU Digital Services Act transparency mandates are climbing the fastest in regulatory-compliant commissioning.
- Sports:Live competition rights require massive minimum guarantees and face complex blackout restrictions across national broadcast markets.
- Live Events:Concerts, award ceremonies, and political broadcasts deliver appointment-viewing audiences that advertisers pay premium rates to reach.
Volume leadership belongs to TV Shows. Margin pressure concentrates in Sports.
End User:
Procurement authority and budget source fundamentally alter sales cycles, content requirements, and data handling obligations.
- Consumers:Individual household accounts drive scale economics through mass-market pricing and standardized content libraries. Subscription hopping behavior among 18-34 demographics in the United States and United Kingdom compresses lifetime value calculations here.
- Businesses:Corporate training departments and internal communications teams require enterprise-grade security, analytics dashboards, and integration with learning management systems. Procurement cycles accelerated post-pandemic as distributed workforces demanded asynchronous video capabilities.
- Educational Institutions:Universities and K-12 districts deploy lecture-capture platforms with accessibility compliance and plagiarism detection integration. India's National Education Policy implementation is expanding addressable procurement in this segment.
- Government:Public sector deployments prioritize data sovereignty, audit trails, and local infrastructure residency under GDPR and national security frameworks.
Account density peaks with Consumers. Contract value expansion sits with Educational Institutions.
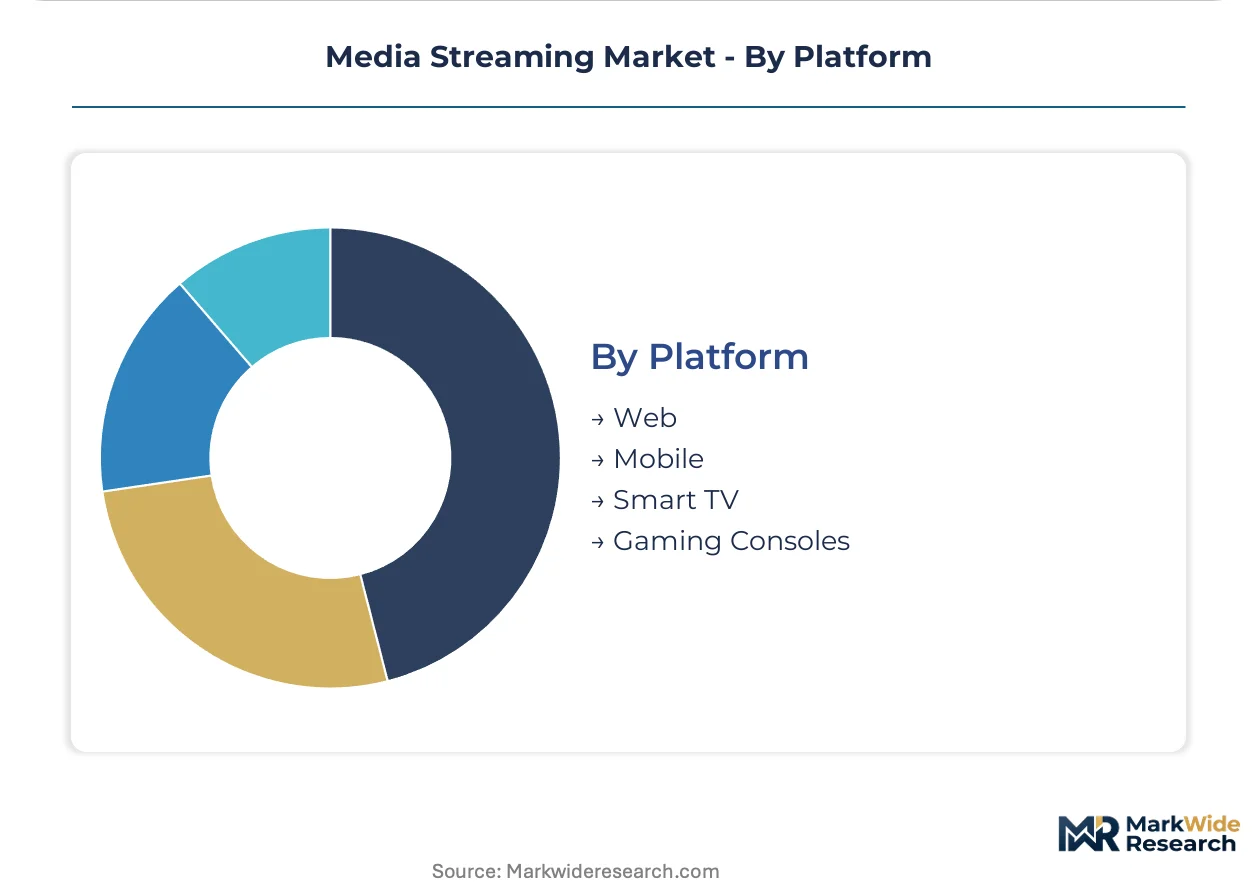
Platform:
Hardware-software integration depth and network dependency create diverging user experience constraints and partnership requirements.
- Web:Browser-based access offers universal reach without application store gatekeeping but struggles with DRM robustness and offline functionality. Desktop enterprise training deployments in financial services and healthcare maintain steady demand.
- Mobile:Smartphone-first consumption dominates in India, Indonesia, and Nigeria where cellular data plans substitute for fixed broadband. Low-bandwidth optimization and download-for-offline features are critical technical investments here.
- Smart TV:Pre-installed applications on Samsung, LG, and TCL operating systems reduce acquisition friction and extend average session duration through lean-back viewing habits. German and South Korean telecommunications operators are deploying edge nodes aggressively to support quality of service.
- Gaming Consoles:Sony PlayStation and Microsoft Xbox hardware bases deliver affluent, engaged demographics with 4K HDR display capabilities and low-latency expectations.
Engagement duration favors Smart TV. Infrastructure cost intensity runs highest on Mobile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates subscriber growth through regional language originals and mobile-first consumption patterns, while the United States and Germany anchor enterprise education deployments and regulatory compliance investments.
United States
Enterprise learning management systems and corporate training departments drive platform procurement across financial services and healthcare sectors. The FCC enforces net neutrality principles affecting bandwidth prioritization and streaming quality of service. Silicon Valley clusters anchor recommendation algorithm development and cloud infrastructure engineering talent.
Germany
Smart TV platform penetration and telecommunications operator edge computing deployments expand addressable infrastructure investment. The KBA and national media regulators enforce content rating frameworks and age-gating requirements shaping editorial decisions. Berlin-Brandenburg hosts compliance tooling vendors serving EU Digital Services Act mandates.
India
Regional language originals and low-bandwidth optimization unlock subscriber growth in tier-2 and tier-3 cities beyond metropolitan centers. TRAI and emerging data protection rules under the Digital Personal Data Protection Act fragment content libraries and complicate cross-border personalization. Mumbai and Bangalore concentrate platform content commissioning and technology development operations.
South Korea
Telecommunications operators deploy aggressive edge node infrastructure to support quality of service for 4K HDR streaming. The MFDS and national broadcast regulators shape content localization requirements for platform market entry. Seoul Capital Area anchors both platform headquarters and smart TV manufacturing partnerships with Samsung and LG.
United Kingdom
Subscription hopping behavior among 18-34 demographics compresses customer lifetime value calculations and forces event-driven retention tactics. Ofcom content rating frameworks and post-Brexit data adequacy negotiations complicate cross-border algorithm operations. London anchors European headquarters for multiple global platforms and compliance audit services.
Media Streaming Market Competitive Environment
Exclusive content investment dominates the current landscape as platforms defend retention through original programming rather than technical differentiation alone. The market structures around three tiers: integrated technology-entertainment conglomerates, pure-play streaming specialists, and telecommunications-backed regional platforms. Strategic archetypes include hardware-software ecosystem builders, ad-supported tier expanders, and enterprise education specialists. M&A activity concentrates on content library acquisitions and sports rights portfolios, while strategic partnerships with smart TV manufacturers reduce customer acquisition friction.
Among integrated technology conglomerates, Netflix Inc. and Amazon.com Inc. exemplify divergent ecosystem strategies, with the former representing pure-play content investment scale and the latter anchoring streaming within broader membership economics. Apple Inc. occupies the premium-tier position through hardware-software integration and original content budgets. These three entities collectively represent the competitive tension between standalone entertainment economics and platform ecosystem lock-in.
| Leading Market Players |
|---|
| Netflix Inc. |
| Amazon.com Inc. |
| Alphabet Inc. |
| The Walt Disney Company |
| Apple Inc. |
| Warner Bros. Discovery Inc. |
| Tencent Holdings Ltd. |
| iQIYI Inc. |
| Comcast Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive in-house production networks across Netflix, Amazon, and Apple anchor supply positions and pricing power by reducing third-party licensing dependency while enabling exclusive content windowing. This vertical integration choice compresses marginal content costs and supports premium subscription tiers against ad-supported competitors.
Pricing Analysis
Service-bundling unbundles technical infrastructure from content libraries across subscription tiers. Three-tier pricing structure across premium, standard, and economy levels differentiates by concurrent stream count and video quality grade, with 4K HDR commanding brand premium. Price differentiation stems from sports rights inflation and regional content commissioning costs. Cost compression in ad-supported tiers is intensifying because platform margin pressure from minimum guarantee escalation. Price-sensitive audiences in Southeast Asia and Latin America drive ad-tier expansion, while enterprise learning management systems show least sensitivity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale platform demand through pre-installed application deals with Samsung, LG, and TCL smart TV operating systems. Geographic supply concentrates in the United States for cloud infrastructure engineering, South Korea for edge node deployment, and India for low-bandwidth optimization development. Raw material dependencies rest on hyperscale CDN capacity, telecommunications partnership agreements, and content production facilities. Single-source vulnerability runs through three hyperscale cloud providers controlling critical edge delivery infrastructure. Distribution runs through smart TV OS bundling, mobile application stores, and browser-based web access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around content spending scale as minimum guarantee inflation forces weaker platforms toward acquisition or exit. Sports rights concentration and original programming costs create exit pressure for sub-scale operators.
For Market Incumbents: Lock in exclusive sports franchise windows and regional language commissioning to defend against subscription hopping behavior. Deepen backward integration into production facilities across Mumbai, Berlin-Brandenburg, and Seoul Capital Area. Threat from telecommunications-backed regional platforms with captive distribution requires preemptive smart TV OS partnership renewal.
For New Entrants and Emerging Players: The mid-tier price-point gap between premium subscription and free ad-supported tiers creates white-space opportunity. Enterprise education deployments in Germany and South Korea offer penetrable procurement cycles with learning management system integration. Live commerce convergence with shoppable video captures retail media budgets outside incumbent entertainment positioning.
For Investors and Strategic Acquirers: Exit pathways concentrate in content library acquisitions and sports rights portfolio rollup. Long-term viability favors platforms with demonstrated subscriber retention mechanics and regional commissioning capability. Acquisition target archetype: mid-tier platforms with strong local language content pipelines and undermonetized ad inventory. Signal to watch is sequential subscription behavior conversion to simultaneous multi-platform holding.
| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Sports Rights Acquisition | Live event appointment-viewing locks in advertiser commitment and reduces churn. |
| Regional Original Content Commissioning | India's tier-2 city expansion requires Hindi, Tamil, and Telugu language investments. |
| Smart TV OS Pre-installation Partnership | Samsung and LG bundling reduces customer acquisition friction and extends session duration. |
| Edge Computing Infrastructure Deployment | German and South Korean telecommunications operators automate real-time encoding decisions. |
| Ad-Supported Tier Geographic Expansion | Southeast Asian smartphone penetration unlocks price-sensitive subscriber segments. |
Study Parameters
SEC filings, App Annie mobile engagement data, and hyperscaler capex disclosures formed the secondary backbone for market sizing and competitive positioning. Primary interviews with platform content commissioning executives, telecommunications partnership directors, enterprise learning management procurement officers, and smart TV manufacturer strategy leads combined with secondary validation through bottom-up and top-down triangulation.
Historical trendline analysis across subscription revenue trajectories, content spending patterns, and regional subscriber growth rates established baseline momentum. Segmentation modeling covered service type, content format, end-user procurement authority, and platform hardware-software integration depth across the projection horizon. CAGRs derived from regression analysis against broadband penetration curves, smartphone adoption thresholds, and content production capacity expansion.
Inputs from regulatory filing databases and platform transparency reports were available through the study window; gaps in private content licensing contract terms introduce uncertainty bands around minimum guarantee projections. Forecasts reflect documented assumptions regarding net neutrality enforcement continuity and EU AI Act implementation pacing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Video-On-Demand [Vod] Market
Video Streaming (OTT) Services
Video on Demand Market
Video Streaming (OTT) Services
Game Streaming Market
Video Streaming (OTT) Services
United States OTT Market
Video Streaming (OTT) Services
Live Streaming Market
Video Streaming (OTT) Services
Asia Pacific Video Streaming Market
Video Streaming (OTT) Services
Latin America OTT Platform Market
Video Streaming (OTT) Services
Global Svod Market
Video Streaming (OTT) Services
Global Cloud Video Streaming Market
Video Streaming (OTT) Services
Live Streaming Pay-Per-View Market
Video Streaming (OTT) Services
OTT Content Market
Video Streaming (OTT) Services
Global Over-The-Top Content Market
Video Streaming (OTT) Services
Sports Streaming Platform Market
Video Streaming (OTT) Services
Online Video Platform Market
Video Streaming (OTT) Services
E-Sports and Games Streaming Market
Video Streaming (OTT) Services
Online Streaming Service Market