
 Online Video Platform Market | 2026-2036
Online Video Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Online Video Platform Market Analysis
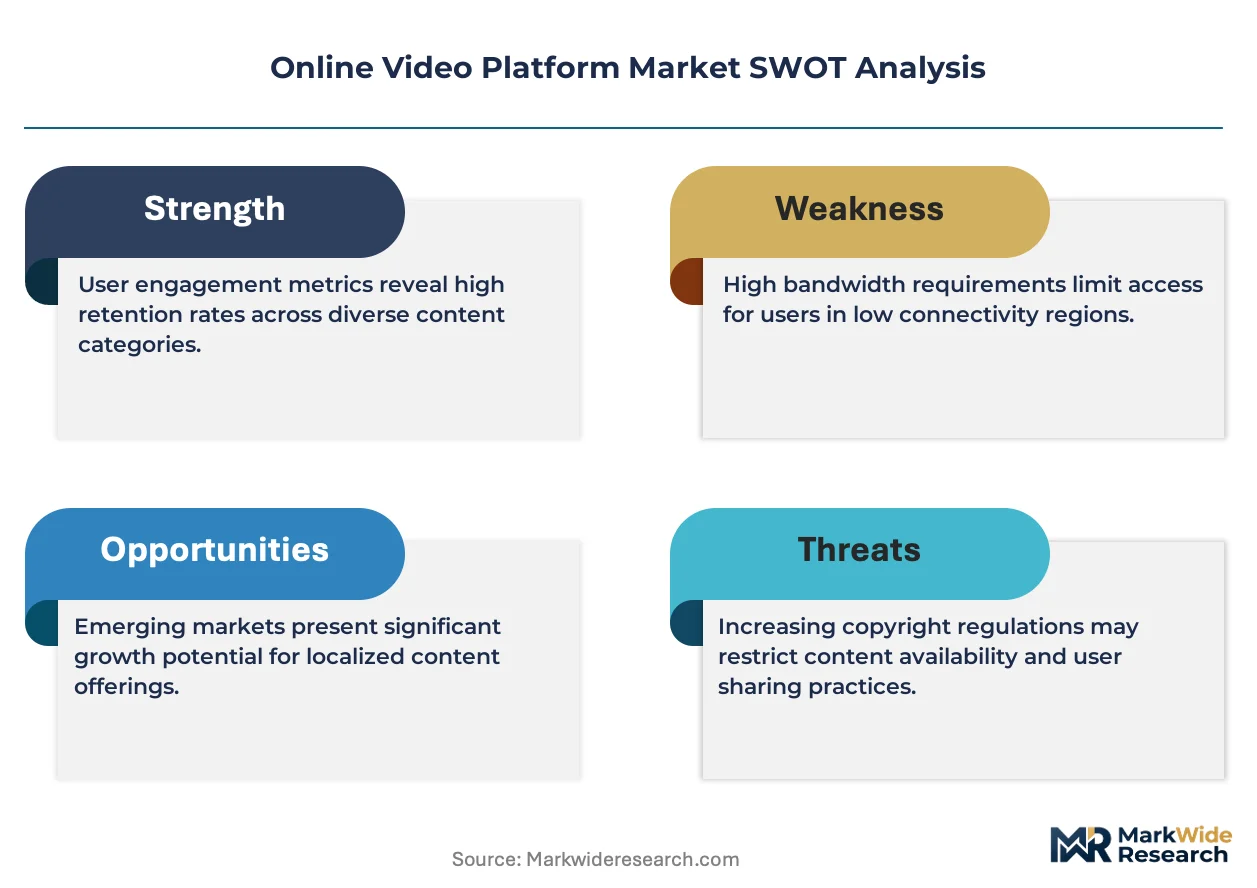
Asset-light SaaS subscription models is narrowing the capital barrier for new entrants in online video platform delivery. Brightcove leverages its established enterprise client base to sustain recurring revenue stability across North American media verticals. Kaltura anchors its competitive position through deep specialization in educational and institutional deployments. Wowza competes on technical differentiation in live streaming infrastructure for developers and broadcast integrators.
An online video platform constitutes a cloud-native software system that ingests, transcodes, stores, and distributes video content across devices via adaptive bitrate streaming protocols such as HLS and DASH. Its primary commercial purpose centers on enabling content owners to reach audiences at scale while monetizing through subscription, advertising, or direct payment mechanisms. Subscription-Based service types command the dominant revenue share as consumers prioritize predictable access over per-transaction friction. Ad-Supported models are expanding fastest among price-sensitive user segments and emerging market demographics where payment infrastructure remains less penetrated. Live Streaming content types concentrate margin pools around premium sports and event broadcasting rights where exclusivity commands advertiser willingness to pay.
FCC oversight of broadband infrastructure and net neutrality principles shapes platform delivery economics and interconnection cost structures in the United States. GDPR compliance requirements in Europe impose data governance and cross-border content restriction costs that influence platform architecture decisions. Content rating frameworks and child protection standards administered by national regulators in multiple jurisdictions directly affect platform content moderation investments and age-gating feature requirements. Stakeholders must monitor evolving AI-generated content disclosure mandates and their downstream implications for platform liability and authentication technology procurement.
Market Dynamics
Cloud-native transcoding pipelines and edge caching architectures are compressing delivery costs while enabling 4K and live streaming at mass scale. The shift from on-premise encoding farms to serverless media processing functions is redistributing competitive advantage toward software-defined infrastructure operators.
Growth Catalysts
- 5G network densification:Mobile carriers in South Korea and urban China are deploying millimeter-wave infrastructure that reduces live streaming latency to sub-500ms thresholds. Broadcasters are leveraging this for real-time sports wagering integration.
- GDPR Article 17 compliance tooling:European content platforms face mandatory right-to-erasure automation. Vendors supplying automated metadata scrubbing and CDN cache invalidation workflows are capturing replacement cycles.
- Enterprise L&D digitization:Fortune 500 manufacturers are retiring classroom training in favor of searchable microlearning libraries. SCORM-compatible video platforms are displacing legacy LMS video modules.
Market Restraints
- Content licensing cost concentration:Premium sports rights in the United States and United Kingdom consume 60-70% of platform operating budgets, compressing margin for mid-tier distributors.
- Codec royalty stacking:HEVC, VVC, and AV1 patent pools impose per-stream licensing obligations that escalate with resolution tiers, creating legal exposure for high-volume live events.
- Interconnection fee asymmetry:Last-mile ISPs in fragmented European markets impose unregulated peering charges that inflate egress costs for independent video platforms relative to vertically integrated competitors.
Strategic Opportunities
- AI-generated content disclosure mandates:The EU AI Act's transparency requirements for synthetic media create demand for automated provenance watermarking and forensic detection APIs.
- Interactive live commerce integration:Chinese retail platforms demonstrate shoppable livestream monetization. Western fashion and beauty verticals represent underpenetrated adaptation opportunities.
- Low-earth orbit satellite backhaul:Starlink and OneWeb constellations enable streaming delivery to maritime, aviation, and rural African markets previously unreachable via terrestrial fiber.
Industry Challenges
- Real-time encoding engineer scarcity:Expertise in GPU-accelerated transcoding and CMAF low-latency packaging commands premium compensation. Platforms compete for talent against hyperscale cloud providers.
- Multi-CDN failover orchestration:Maintaining seamless viewer experience across geographically distributed origin servers requires sophisticated traffic engineering that strains mid-market operations teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Video Platform Market |
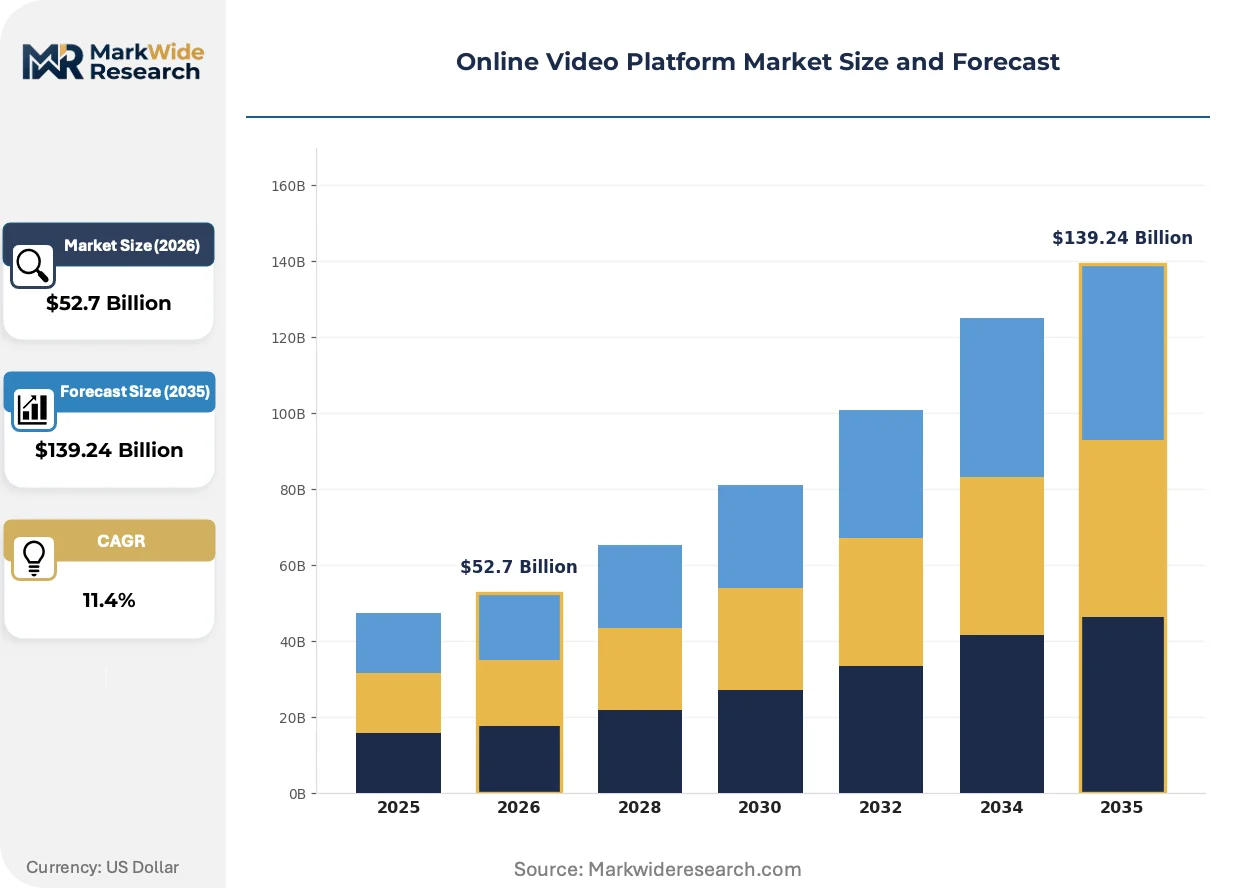
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $139.24 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Subscription-Based, Ad-Supported, Transactional, Freemium User Type: Professionals, Students, General Public, Businesses Monetization Model: Pay-Per-View, Advertising, Sponsorship, Premium Membership Content Type: Live Streaming, Video on Demand, User-Generated Content, Educational Videos |
| Companies Covered | Wowza, EnterpriseTube, Brightcove, Muvi, IBM Video Streaming, Kaltura, Panopto, Dacast, Vimeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Video Platform Market Emerging Trajectories
Video infrastructure is converging with AI moderation, blockchain attribution, and immersive formats in ways that redefine platform architecture. The competitive frontier has shifted from playback reliability to intelligent content lifecycle management.
Server-side ad insertion (SSAI) technology is migrating from broadcast-originated workflows to programmatic digital environments. Media companies operating direct-to-consumer services are replacing client-side ad stitching to circumvent ad blockers and improve fill rates. This migration from browser-based execution to cloud-rendered personalization is compressing CPM variance and enabling frame-accurate competitive separation in live sports.
The EU Digital Services Act's systemic risk assessment obligations for very large online platforms are forcing algorithmic recommendation transparency. Video services exceeding 45 million monthly active users must submit audit-ready documentation of content ranking logic. French and German regulators are prioritizing enforcement against opacity in youth-targeted recommendation systems, compelling platforms to architect explainable ML pipelines.
Enterprise procurement of video platforms is consolidating around integrated communication suites rather than standalone solutions. Microsoft Teams, Zoom, and Slack are absorbing video hosting into bundled collaboration contracts. IT buyers in financial services and healthcare verticals are deprecating point-product evaluations in favor of unified vendor relationships with existing security certification. This pattern is most pronounced in North American and Australian markets where SaaS consolidation mandates dominate CIO agendas.
Online Video Platform Market Segmentation
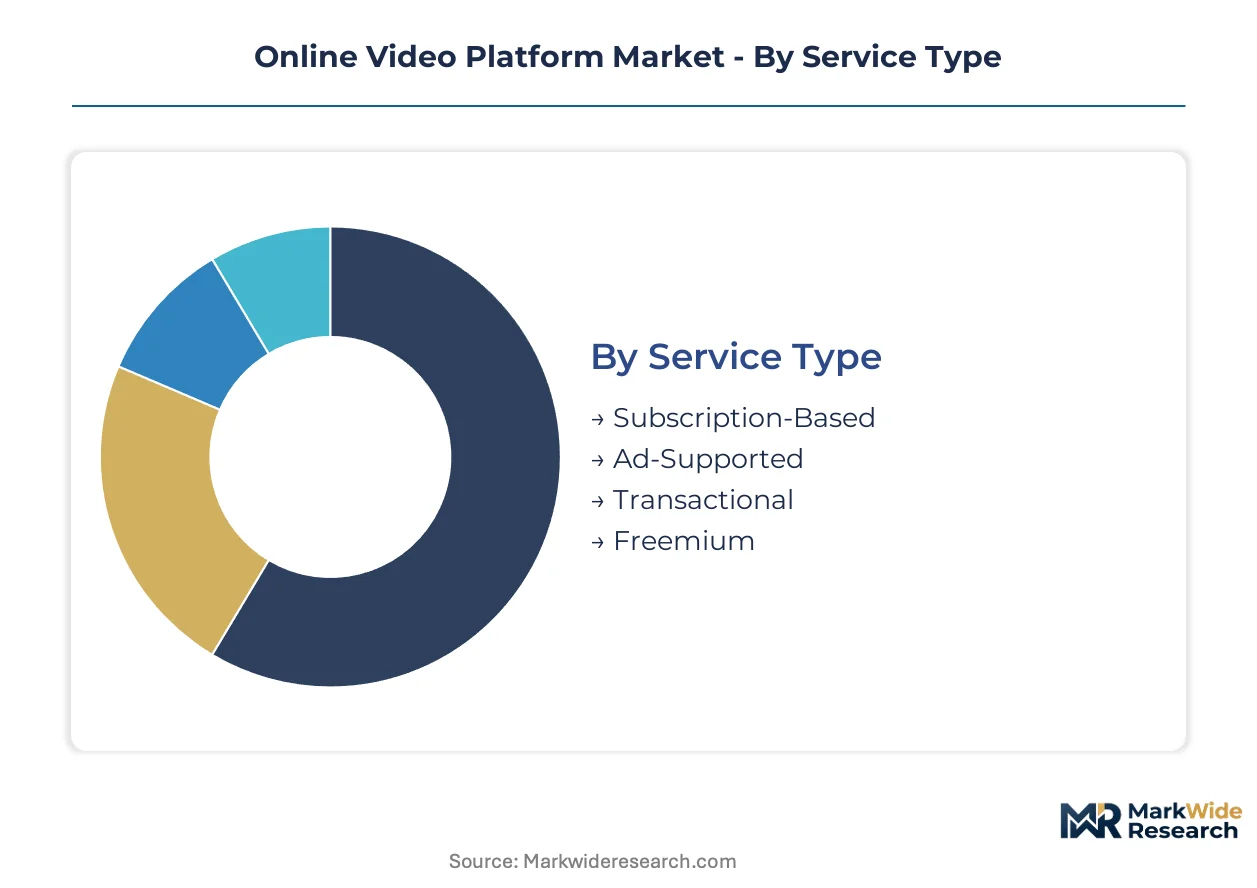
Platform architecture diverges sharply across monetization mechanics and audience composition. Each segmentation axis reveals distinct infrastructure requirements, from subscription billing integration to real-time encoding pipelines for live events.
Service Type:
Use-case spectrum spans predictable recurring access to impulse-driven single transactions.
- Subscription-Based:Cloud-native entitlement systems manage tiered access rights across device ecosystems. Enterprise L&D departments in the United States and Germany prioritize predictable budgeting for workforce training libraries.
- Ad-Supported:Server-side ad insertion architectures replace client-side stitching to circumvent blockers. Price-sensitive demographics in Brazil and Indonesia drive expansion where payment infrastructure penetration lags.
- Transactional:Per-content licensing with time-bound access windows suits premium event distribution. Sports leagues deploy this for pay-per-view championship broadcasts.
- Freemium:Tiered feature gating converts free users through watermark removal or resolution upgrades. Music education platforms leverage this for instrument tutorial marketplaces.
Established volume favors Subscription-Based; emerging adoption favors Ad-Supported.
User Type:
Customer archetypes dictate divergent UX complexity and compliance requirements.
- Professionals:Creators and broadcasters demand API-first platforms with granular analytics. Media production houses in Los Angeles and London require frame-accurate collaboration tools.
- Students:SCORM compatibility and accessibility standards dominate procurement. University systems across Australia standardize on platforms integrating with existing LMS infrastructure.
- General Public:Consumer-grade interfaces prioritize discovery algorithms and social sharing. Mobile-first design dominates engagement metrics in urban India.
- Businesses:SSO integration and audit logging satisfy IT security mandates. Financial services firms in Singapore require SOC-2 certified hosting environments.
Procurement concentration favors Businesses; engagement scale favors General Public.
Monetization Model:
Revenue architecture determines platform engineering investment priorities.
- Pay-Per-View:Time-limited access tokens with geographic enforcement suit exclusive live events. Boxing promoters leverage this for championship bout distribution.
- Advertising:Programmatic inventory integration with demand-side platforms maximizes fill rates. Connected TV apps in the United States optimize around addressable audience segments.
- Sponsorship:Branded content integration and native placement workflows serve influencer economy participants. Beauty verticals in South Korea deploy shoppable livestream sponsorships.
- Premium Membership:Loyalty tiering with exclusive early access or behind-the-scenes content retains high-value subscribers. Anime streaming services in Japan structure annual membership cycles around seasonal release calendars.
Revenue stability favors Premium Membership; CPM expansion favors Advertising.
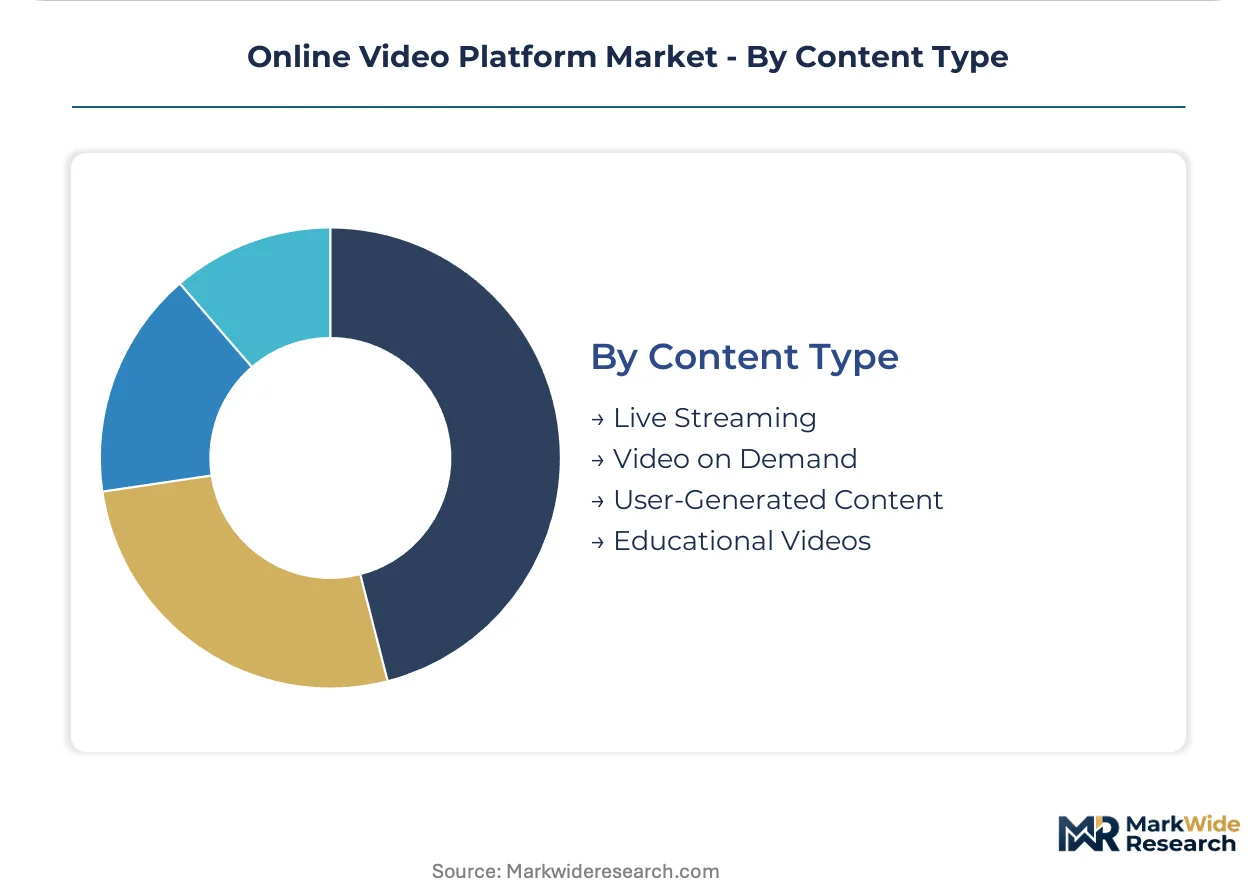
Content Type:
Delivery modality dictates encoding pipeline architecture and edge distribution topology.
- Live Streaming:Sub-500ms latency protocols enable real-time wagering and interactive polling. 5G millimeter-wave deployments in Seoul and Shanghai support broadcast-grade mobile live production.
- Video on Demand:Multi-codec transcoding ladders optimize storage efficiency across device capabilities. Studios in Burbank and Mumbai manage petabyte-scale content libraries with automated quality control.
- User-Generated Content:Automated moderation pipelines and copyright fingerprinting manage upload scale. Short-form platforms in São Paulo and Jakarta process millions of daily uploads through AI classification.
- Educational Videos:Searchable transcript generation and knowledge-check embedding satisfy pedagogical requirements. Corporate training divisions in Toronto and Sydney index microlearning modules by competency framework.
Margin concentration favors Live Streaming; volume scale favors Video on Demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise learning departments and media conglomerates drive platform procurement across concentrated metropolitan technology corridors. Buyer archetypes cluster around financial services hubs, university systems, and broadcast production centers where workforce training digitization and content monetization requirements converge.
United States
Fortune 500 manufacturers in Detroit and Houston are retiring classroom training for searchable microlearning libraries. FCC net neutrality principles shape interconnection economics for streaming delivery. Los Angeles media production houses maintain the densest concentration of broadcast-originated platform deployments.
Germany
Automotive OEMs in Stuttgart and Munich prioritize SCORM-compatible video platforms for compliance training standardization. GDPR Article 17 mandates automated right-to-erasure workflows that scrub metadata and invalidate CDN caches. Berlin's startup ecosystem incubates specialized educational technology vendors.
China
Urban carriers in Shanghai and Beijing deploy millimeter-wave 5G infrastructure enabling sub-500ms live streaming latency for real-time sports wagering. MIIT cloud service regulations govern cross-border content distribution licensing. Shenzhen hardware integrators supply edge encoding appliances for broadcasters.
United Kingdom
Premium sports rights consumption in London consumes 60-70% of platform operating budgets for mid-tier distributors. Ofcom content rating frameworks mandate age-gating investments for youth-targeted recommendation systems. Manchester's media city cluster hosts broadcast technology integration specialists.
South Korea
Beauty verticals in Seoul deploy shoppable livestream sponsorships demonstrating interactive commerce integration. MFDS data governance requirements influence platform architecture for health-related content distribution. Busan-Ulsan manufacturing conglomerates adopt enterprise video for supply chain training standardization.
Online Video Platform Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Hyperscale cloud providers and integrated communication suites absorb mid-market procurement through bundled security certifications. Pure-play video platform vendors defend position through technical differentiation in live streaming infrastructure and educational specialization. Strategic moves concentrate on serverless media processing migration and AI-powered content moderation tooling procurement.
Within the enterprise-specialist tier, Kaltura exemplifies deep institutional learning management integration, while Brightcove anchors recurring revenue stability across North American media verticals. Wowza occupies a position at the developer-facing infrastructure end, competing on technical differentiation for broadcast integrators requiring low-latency packaging protocols.
| Leading Market Players |
|---|
| Wowza |
| EnterpriseTube |
| Brightcove |
| Muvi |
| IBM Video Streaming |
| Kaltura |
| Panopto |
| Dacast |
| Vimeo |
| Others |
Supply Flow & Price Mechanics
Shenzhen's edge encoding appliance manufacturing clusters feed global platform infrastructure demand, concentrating component sourcing power among hardware integrators who dictate downstream SaaS pricing tiers through volume-based component cost leverage.
Pricing Analysis
Cost-plus contracts with cloud infrastructure providers index compute and storage to hyperscaler rate cards, creating predictable unit economics for platform operators. Three-tier pricing structure across premium, standard, and economy levels separates enterprise broadcasters from mid-market creators from individual developers. Pricing pressure stems from hyperscale cloud providers absorbing mid-market procurement through bundled collaboration suites. General public consumers exhibit highest price sensitivity, while financial services firms in Singapore demonstrate lowest sensitivity due to security certification requirements.
Supply Chain Analysis
Upstream feedstock for video infrastructure draws from Taiwan's GPU foundry capacity, South Korea's memory fabrication, and China's server assembly ecosystems. Critical components include NVIDIA accelerators, high-bandwidth memory modules, and precision cooling systems. Single-source vulnerability concentrates in advanced GPU architectures where foundry capacity constraints create allocation bottlenecks. Distribution runs through direct hyperscaler relationships for enterprise deployments and channel partners for mid-market accessibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated IT procurement functions at Fortune 500 manufacturers, fragmenting point-product vendor access as enterprise learning departments lose independent budget authority.
For Market Incumbents: Insulate recurring revenue stability by deepening SCORM-compatible integrations with existing LMS infrastructure at university systems across Australia and Germany. Threaten emerging hyperscale bundled offerings with specialized live streaming latency guarantees below 500 milliseconds. Prioritize certification investment in SOC-2 and GDPR Article 17 compliance tooling to maintain procurement access against integrated communication suites.
For New Entrants and Emerging Players: Rural African markets previously unreachable via terrestrial fiber represent underpenetrated white-space opportunity through Starlink and OneWeb satellite backhaul integration. Western fashion and beauty verticals demonstrate adaptation lag for shoppable livestream monetization compared to Seoul deployments. Go-to-market angle should target mid-tier boxing promoters and sports leagues with pay-per-view championship distribution lacking technical infrastructure.
For Investors and Strategic Acquirers: Carve-out targets emerge from media conglomerates spinning off non-core video platform assets under portfolio rationalization pressure. Long-term viability frames toward software-defined infrastructure operators capturing serverless media processing migration cycles. Acquisition target archetype: developer-facing infrastructure specialists with CMAF low-latency packaging protocols. Signal to watch: FCC net neutrality enforcement shifts altering interconnection cost structures for independent distributors.
| Strategic Initiative | Industry Significance |
|---|---|
| Serverless Media Processing Migration | Redistributes competitive advantage toward software-defined infrastructure operators away from on-premise encoding farms. |
| AI-Powered Content Moderation Tooling Procurement | Addresses EU Digital Services Act algorithmic transparency mandates for platforms exceeding 45 million monthly active users. |
| Interactive Live Commerce Integration | Captures Western fashion and beauty vertical adaptation opportunities demonstrated by Chinese retail platforms. |
| Automated Provenance Watermarking Deployment | Satisfies EU AI Act synthetic media disclosure requirements for AI-generated content authentication. |
| Low-Earth Orbit Satellite Backhaul Partnership | Enables streaming delivery to maritime, aviation, and rural African markets beyond terrestrial fiber reach. |
Methodological Framework
A spread of perspectives from platform engineering directors, enterprise IT procurement officers, broadcast technology integrators, and educational technology administrators converged on the working assumptions underlying this analysis. Primary interviews combined with secondary validation against SEC filings from hyperscale cloud providers, App Annie mobile engagement data, hyperscaler capex disclosures, and FCC broadband deployment reports. Bottom-up demand modeling triangulated against top-down market sizing across service type, user type, and content type segmentation dimensions.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Modeled segmentation dimensions included deployment model, organization size, vertical specialization, integration complexity, and regional adoption pattern. CAGRs derived from historical trajectory analysis adjusted for technology substitution effects and regulatory inflection points. Industry-specific forecast inputs incorporated 5G millimeter-wave deployment timelines and enterprise L&D digitization penetration curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscale bundled communication suite providers would shift outcomes beyond modeled ranges. Cross-checking against hyperscaler earnings call commentary on media and entertainment vertical revenue attribution is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Streaming Media Services Market
Video Streaming (OTT) Services
Media Streaming Market
Video Streaming (OTT) Services
Global Transactional Video on Demand Market
Video Streaming (OTT) Services
Global Over-The-Top Content Market
Video Streaming (OTT) Services
Mexico OTT TV and Video Market
Video Streaming (OTT) Services
Sports Streaming Platform Market
Video Streaming (OTT) Services
Live Streaming Pay-Per-View Market
Video Streaming (OTT) Services
Streaming Spending Market
Video Streaming (OTT) Services
Video Streaming Market
Video Streaming (OTT) Services
Latin America OTT Platform Market
Video Streaming (OTT) Services
Global Cloud Video Streaming Market
Video Streaming (OTT) Services
United States Online Video Platform Market
Video Streaming (OTT) Services
Global Live Streaming Video Platform Market
Video Streaming (OTT) Services
Advertising-Based Video on Demand Market
Video Streaming (OTT) Services
Asia Pacific Video Streaming Market
Video Streaming (OTT) Services
Game Streaming Market