
 Enterprise Streaming Media Market | 2026-2036
Enterprise Streaming Media Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Streaming Media Market Analysis
Enterprise video engineering talent is reorganizing around cloud-native architectures and edge delivery protocols, tightening the labor pool for on-premises specialists. Microsoft Corporation leverages its Teams- Azure integration to dominate unified communications streaming, while Amazon Web Services anchors enterprise-grade live event infrastructure through Elemental MediaLive. Cisco Systems differentiates through hardened security certifications that sustain government and financial services demand.
Enterprise streaming media encompasses the technologies, platforms, and services that enable organizations to capture, encode, distribute, and analyze live and on-demand video content across internal and external audiences, typically requiring sub-five-second latency for interactive use cases and adaptive bitrate protocols for variable network conditions. The technology dimension shows cloud-based solutions leading deployment preferences as corporations retire data center investments, while edge computing represents the fastest-growing sub-segment as latency-sensitive applications expand. Service type segmentation reveals live streaming commands the largest revenue pool, though video on demand sustains higher gross margins through lower concurrent infrastructure costs.
Enterprise streaming platforms face overlapping compliance obligations from the EU AI Act's transparency requirements for automated content moderation, GDPR's data residency rules for viewer analytics, and FCC regulations governing closed captioning accessibility for US federal contractors. ISO 27001 certification has become a baseline procurement filter for enterprise buyers evaluating vendor security postures. Stakeholders must monitor how sovereign cloud mandates in Germany, France, and Australia reshape data routing architectures and vendor selection criteria.
Market Dynamics
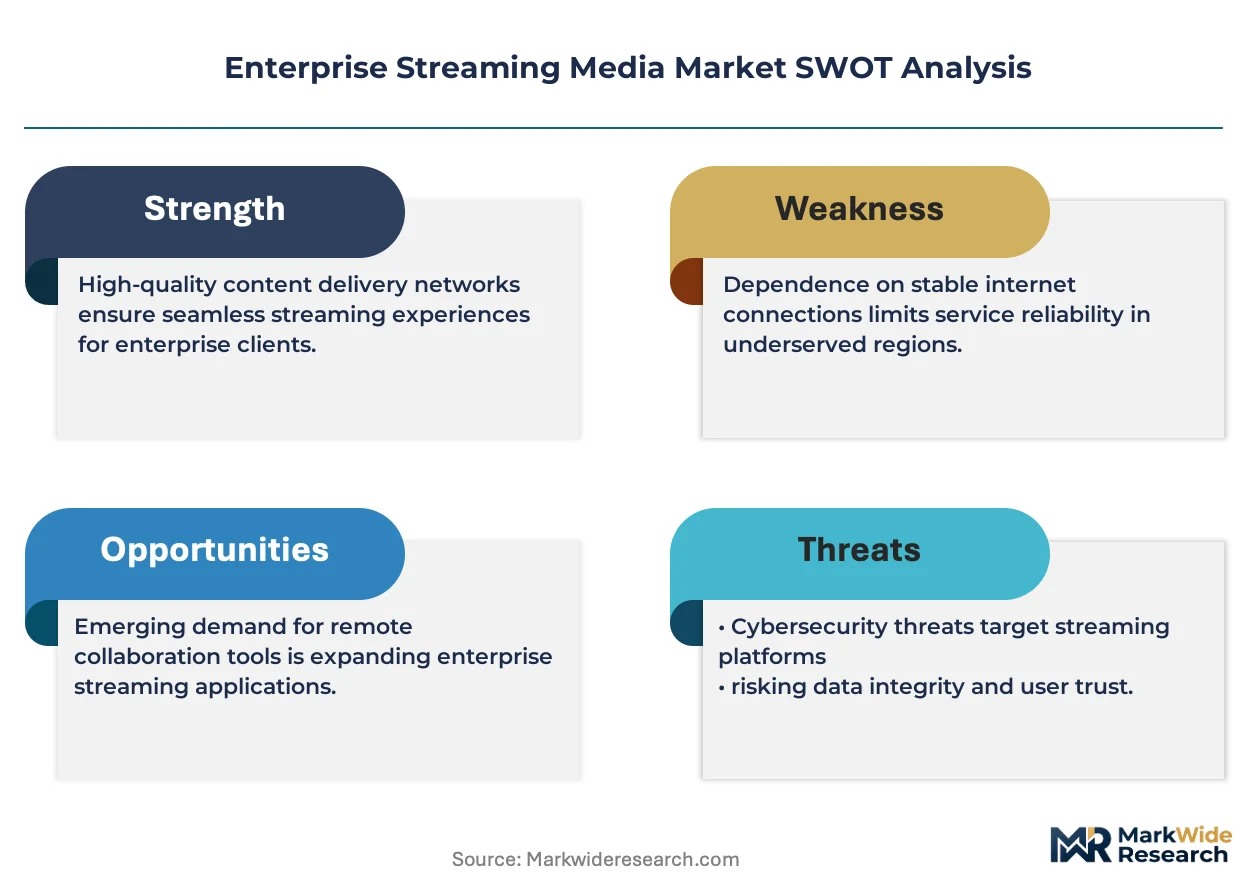
Cloud migration mandates from the EU AI Act and GDPR compliance requirements are forcing enterprises to retire legacy on-premises video infrastructure, creating structural demand for certified, residency-compliant streaming platforms.
Growth Catalysts
- EU AI Act transparency mandates:Automated content moderation requirements in Europe are compelling enterprises to upgrade streaming stacks with audit-ready AI governance layers.
- Hybrid work persistence:Corporate training departments are expanding live streaming budgets as distributed workforce models become permanent operational fixtures.
- Edge computing protocols:Sub-five-second latency requirements for interactive use cases are accelerating deployment of WebRTC and SRT-based delivery architectures.
Market Restraints
- Specialized talent scarcity:Cloud-native video engineering expertise is tightening labor availability for legacy on-premises codec and multicast specialists.
- Data residency costs:GDPR and sovereign cloud mandates in Germany, France, and Australia are fragmenting infrastructure deployment and multiplying compliance overhead.
- Bandwidth asymmetry:Enterprise upload capacity limitations constrain simultaneous high-bitrate outbound streams from distributed branch locations.
Strategic Opportunities
- Japan manufacturing vertical:Precision engineering and automotive sectors in Japan remain underpenetrated for immersive training streaming applications.
- ISO 27001 procurement filter:Security certification is becoming a baseline vendor qualification, creating first-mover advantage for certified platform providers.
- Real-time analytics convergence:Integration of viewer engagement telemetry with CRM systems is opening new revenue attribution models for enterprise marketing teams.
Industry Challenges
- Multi-cloud orchestration complexity:Enterprises struggle to maintain consistent streaming quality across hybrid Azure-AWS-GCP deployments without specialized platform engineering.
- Closed captioning compliance timelines:FCC accessibility requirements for federal contractors impose rigid certification deadlines that compress vendor onboarding cycles.
- Legacy codec deprecation:Migration from H.264 to AV1 and VVC codecs requires substantial transcoding infrastructure reinvestment with uncertain ROI timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Streaming Media Market |
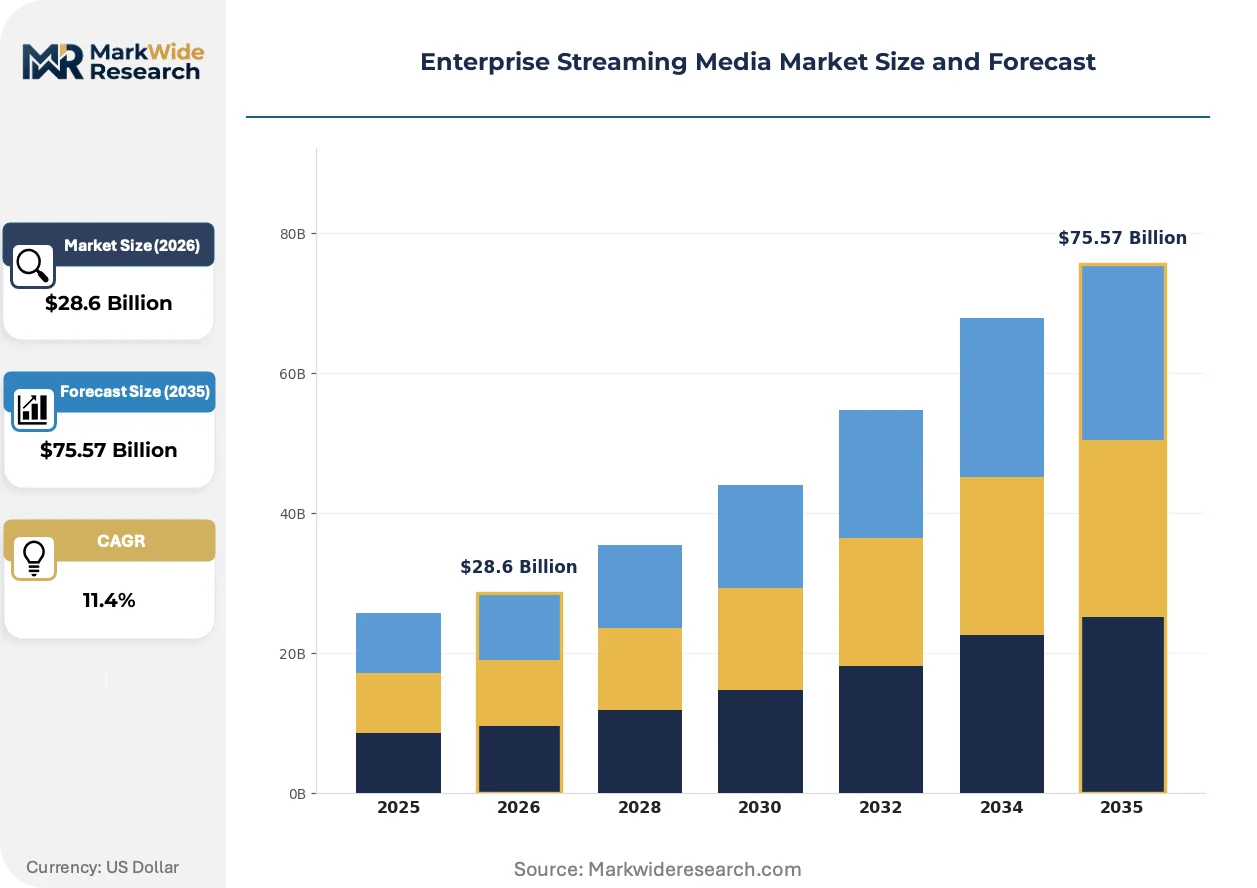
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Distribution Channel: Direct Sales, Online Marketplaces, Resellers, Managed Service Providers End User: Corporations, Educational Institutions, Government Agencies, Media Companies Service Type: Live Streaming, Video On Demand, Webinars, Podcasting Technology: Cloud-Based Solutions, On-Premises Solutions, Hybrid Solutions, Edge Computing |
| Companies Covered | Microsoft Corporation, Cisco Systems, Inc., Adobe Inc., Apple Inc., Google LLC (Alphabet Inc.), Amazon Web Services, Inc., IBM Corporation, Haivision Systems Inc., Vimeo, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Streaming Media Market Emerging Trajectories
Edge-native delivery architectures are fragmenting traditional cloud-centric streaming topologies, while regulatory pressure on AI-mediated content is reshaping platform procurement criteria across regulated industries.
WebRTC-based real-time streaming is fragmenting the dominance of traditional HTTP-based adaptive bitrate protocols. Financial services trading floors and telemedicine providers are adopting it for sub-second latency requirements. This fragmentation is compressing infrastructure consolidation strategies among vendors who built around segmented CDN hierarchies.
The EU AI Act's transparency requirements for automated content moderation are mandating explainable AI layers in enterprise streaming stacks. Platform providers must now document decision logic for content flagging and recommendation algorithms. German and French enterprises are responding by prioritizing vendors with pre-certified compliance documentation.
Subscription fatigue among corporate buyers is driving unbundling of all-in-one streaming suites into modular, API-first components. Procurement teams in United States healthcare and Japan manufacturing are selecting best-of-breed encoders, CDNs, and analytics tools separately. This pattern is most pronounced in mid-market enterprises with dedicated platform engineering functions.
Enterprise Streaming Media Market Segmentation
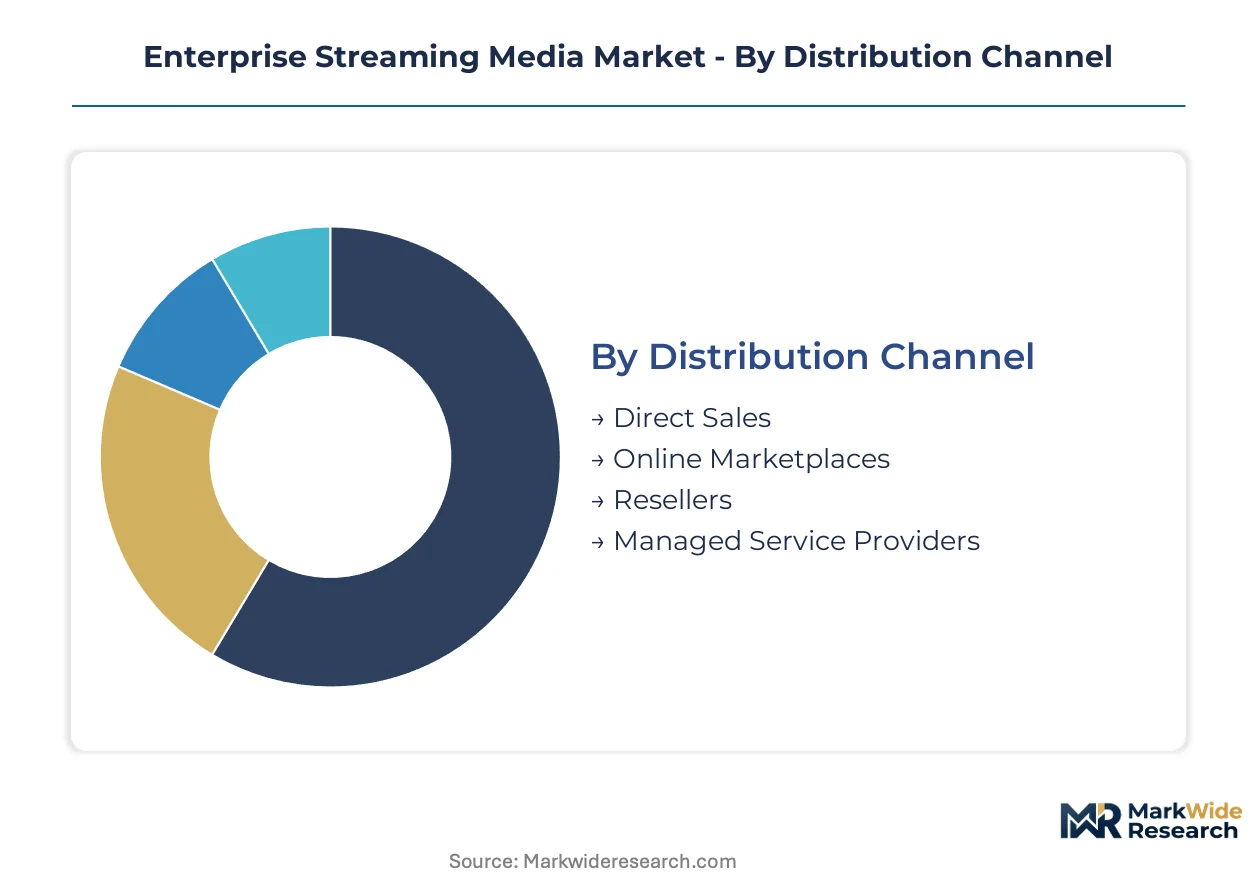
Enterprise streaming procurement channels diverge sharply by buyer sophistication and compliance burden. Direct relationships dominate security-conscious verticals, while self-service platforms capture mid-market volume.
Distribution Channel:
Channel selection tracks directly with buyer IT maturity and data sovereignty requirements, creating distinct service models across the enterprise spectrum.
- Direct Sales:Field-led engagements with dedicated solution architects handle complex multi-region deployments and custom SLA negotiations. Financial services and government buyers in Germany and Japan mandate direct contracting for GDPR and METI compliance documentation.
- Managed Service Providers:Outsourced platform operations bundle encoding, CDN management, and 24/7 event support under fixed monthly fees. Healthcare systems in the United States prefer MSP delivery to offload HIPAA technical safeguards liability.
- Resellers:Systems integrators and telecom carriers white-label streaming infrastructure for vertical-specific packaging.
- Online Marketplaces:Self-service procurement through cloud vendor marketplaces accelerates deployment for development teams and mid-market buyers.
Direct sales dominates installed base. Managed Service Providers is where expansion concentrates.
End User:
User type determines latency requirements, security certification needs, and content moderation complexity.
- Corporations:Hybrid workforce training and executive town halls drive concurrent viewer scale into six-figure peaks. Multinational enterprises in the United States and Germany are consolidating fragmented point solutions onto unified platforms with ISO 27001 certification.
- Government Agencies:Classified and unclassified streaming tiers require FedRAMP or equivalent national security accreditation. Closed captioning compliance for federal contractors imposes rigid FCC certification deadlines that compress vendor selection cycles.
- Educational Institutions:Lecture capture and remote degree programs balance cost constraints with accessibility mandates.
- Media Companies:Broadcast-grade quality requirements and DRM protection for premium content distinguish this segment.
Corporations anchor current revenue. Government Agencies is climbing the fastest on security-driven upgrade cycles.
Service Type:
Service architecture shapes infrastructure economics and margin structure through concurrency patterns and storage intensity.
- Live Streaming:Real-time encoding and edge distribution for executive broadcasts, product launches, and virtual events commands the largest revenue pool. Corporate training departments in Japan and the United States are expanding live budgets as hybrid work persists.
- Video On Demand:Pre-recorded content libraries sustain higher gross margins through lower concurrent infrastructure costs and longer content amortization. Compliance training archives and onboarding modules in Germany leverage VOD for GDPR-documented completion tracking.
- Webinars:Interactive registration, polling, and Q&A workflows integrate with CRM systems for lead attribution.
- Podcasting:Audio-first enterprise communications and internal radio formats serve mobile-first workforces.
Live Streaming commands revenue scale. Video On Demand delivers superior unit economics.
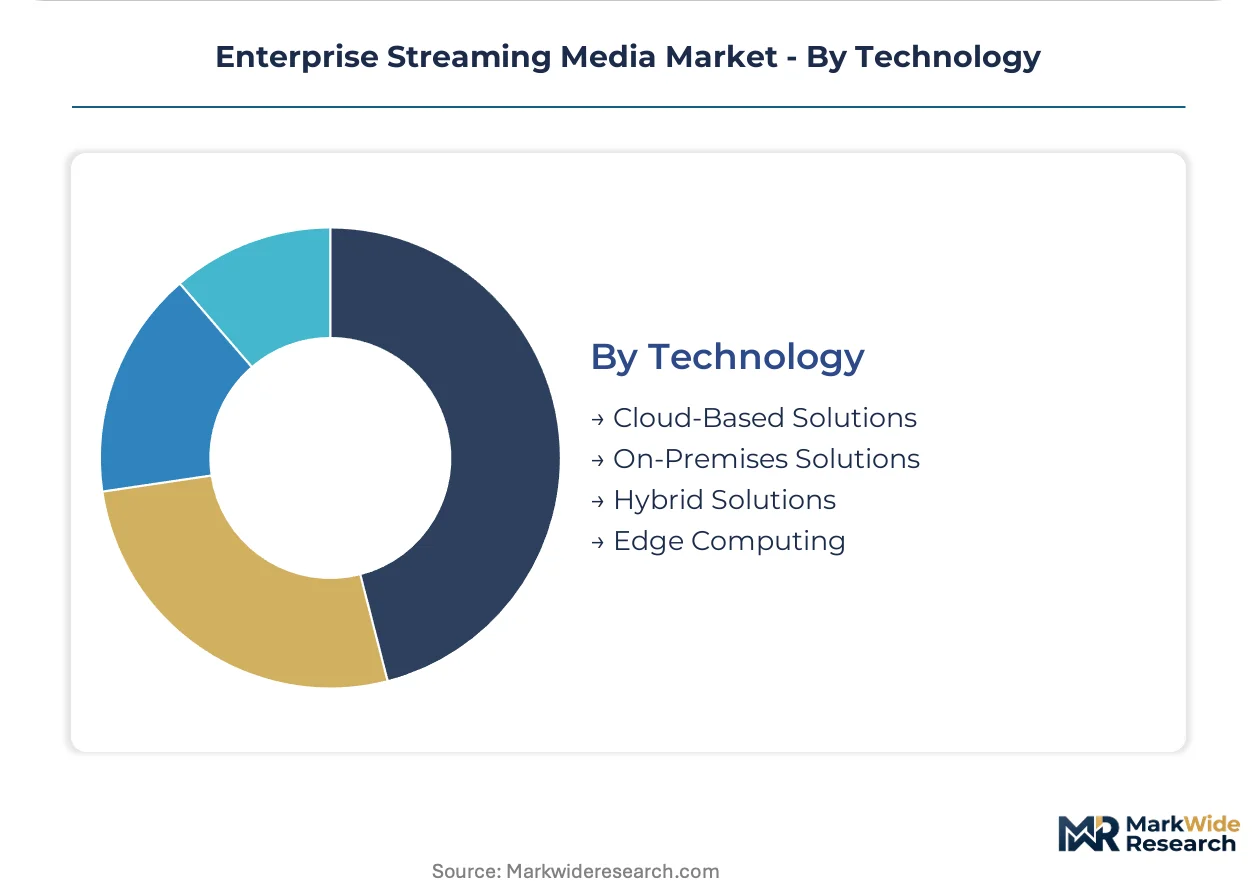
Technology:
Deployment model selection reflects data residency mandates, latency requirements, and legacy infrastructure retirement timelines.
- Cloud-Based Solutions:Fully managed SaaS platforms with automatic scaling and zero hardware maintenance are displacing data center investments. EU AI Act transparency mandates and GDPR residency rules are accelerating cloud migration in France and Germany.
- Edge Computing:Sub-five-second latency through WebRTC and SRT protocols at network periphery is gaining share fastest for telemedicine and financial trading floors. Japanese automotive manufacturers deploy edge nodes for immersive training simulations.
- Hybrid Solutions:Split architectures keep sensitive content on-premises while leveraging cloud burst capacity for peak events.
- On-Premises Solutions:Air-gapped deployments persist in classified environments and legacy codec-dependent workflows.
Cloud-Based Solutions dominates new deployments. Edge Computing is where vendor R&D concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC closed captioning mandates and GDPR data residency rules are fragmenting procurement patterns across the United States, Germany, and Japan. Enterprises in these markets face divergent compliance timelines that reshape vendor selection criteria and infrastructure deployment architectures.
United States
Hybrid workforce training and executive town halls drive six-figure concurrent viewer peaks for corporate streaming platforms. FCC regulations impose rigid closed captioning certification deadlines on federal contractors that compress vendor onboarding cycles. Technology clusters in Seattle and Silicon Valley anchor cloud-native platform engineering talent pools that vendors aggressively recruit.
Germany
Automotive manufacturers and precision engineering firms in Bavaria and Baden-Württemberg deploy edge nodes for immersive training simulations with sub-five-second latency requirements. GDPR sovereign cloud mandates fragment infrastructure deployment and multiply compliance overhead for multinational platform providers. Berlin-Brandenburg hosts specialized consultancies that bridge EU AI Act transparency requirements with legacy enterprise video stacks.
Japan
METI compliance documentation requirements mandate direct contracting relationships for enterprise streaming procurement in financial services and government sectors. Automotive manufacturers in the Chubu region around Nagoya pioneer WebRTC-based delivery for factory-floor training applications. Tokyo's dense corporate headquarters concentration sustains premium pricing for broadcast-grade live event infrastructure.
United Kingdom
Financial services trading floors in the City of London adopt sub-second latency streaming protocols for real-time market data visualization. Post-Brexit data adequacy negotiations with the EU complicate cross-border viewer analytics residency for multinational enterprises. Cambridge technology clusters incubate specialized encoding optimization startups that incumbent platforms acquire for talent.
France
ANSM and CNIL regulatory guidance shapes pharmaceutical and healthcare enterprise streaming deployments with strict audit trail requirements for training completion. Île-de-France headquarters of luxury conglomerates demand DRM-protected executive broadcast infrastructure for geographically dispersed brand teams. Lyon-based systems integrators white-label streaming infrastructure for mid-market manufacturing verticals.
Enterprise Streaming Media Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the enterprise streaming media market. Cloud hyperscalers leverage existing data center footprints and identity management integrations to capture unified communications workloads. Security-certified incumbents and API-first modular specialists occupy distinct competitive positions based on buyer compliance burden and IT maturity. M&A activity concentrates on edge computing protocol startups and AI governance layer providers, while strategic partnerships between encoding specialists and regional telecom carriers expand addressable markets.
Among technology conglomerates with unified communications ecosystems, Microsoft Corporation exemplifies the integrated-platform archetype through Teams-Azure infrastructure bundling. Amazon Web Services, Inc. anchors enterprise-grade live event delivery through its elemental media processing lineage. Cisco Systems, Inc. occupies a position within the security-certified tier that sustains government and financial services demand through hardened accreditation documentation.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Cisco Systems, Inc. |
| Adobe Inc. |
| Apple Inc. |
| Google LLC (Alphabet Inc.) |
| Amazon Web Services, Inc. |
| IBM Corporation |
| Haivision Systems Inc. |
| Vimeo, Inc. |
| Others |
Supply Flow & Price Mechanics
ISO 27001 certification gates both vendor qualification and price differentiation simultaneously, forcing uncertified providers into discount positioning while accredited platforms command premium SaaS tiers across financial services and government procurement in Germany and Japan.
Pricing Analysis
Long-term enterprise offtake contracts dominate procurement for multinational corporations with six-figure concurrent viewer requirements, while project-based event pricing serves mid-market buyers with episodic streaming needs. Price differentiation separates FedRAMP-authorized platforms from standard commercial tiers, with customization for GDPR data residency adding substantial premiums. Cost compression in self-service cloud marketplace tiers is intensifying because hyperscaler bundling reduces standalone encoder margins. Mid-market platform engineering teams exhibit highest price sensitivity, while government agencies prioritize compliance documentation over cost.
Supply Chain Analysis
The United States and Germany anchor cloud-native platform engineering talent pools that vendors aggressively recruit, while Japan hosts specialized edge hardware fabrication for low-latency streaming appliances. Raw material dependencies center on semiconductor components for encoding hardware, optical fiber infrastructure for backbone transmission, and rare earth elements for edge server manufacturing. Single-source vulnerability concentrates in Taiwan-based chip fabrication for video processing ASICs. Distribution runs through direct sales field organizations for security-conscious verticals and hyperscaler marketplaces for developer-led procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise streaming platforms benefit from substantial switching costs embedded in multi-year compliance documentation and integrated workflow architectures, creating durable defensive moats against displacement.
For Market Incumbents: Consolidate fragmented point solutions through API-first platform engineering acquisitions that deepen vertical integration into edge encoding hardware. Threat from modular best-of-breed specialists is accelerating as procurement teams unbundle all-in-one suites. Priority lever rests on preemptive ISO 27701 certification for privacy information management ahead of EU AI Act enforcement waves.
For New Entrants and Emerging Players: Real-time analytics convergence with CRM systems represents a service-layer gap where incumbents under-serve marketing attribution requirements. Japan manufacturing verticals remain underpenetrated for immersive training applications with sub-five-second latency specifications. Go-to-market angle should target platform engineering functions at mid-market enterprises with dedicated DevOps teams through self-service marketplace listings.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed edge computing protocol startups holding WebRTC and SRT optimization patents. Long-term viability favors platforms with sovereign cloud deployment capabilities across Germany, France, and Australia regulatory clusters. Signal to watch is acceleration in METI compliance documentation mandates forcing direct contracting relationships in Japan financial services.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Protocol Acquisition | WebRTC and SRT patent portfolios secure sub-second latency positioning for financial trading floors. |
| Sovereign Cloud Infrastructure Deployment | GDPR-resident data centers in Germany and France unlock government and automotive procurement channels. |
| AI Governance Layer Certification | EU AI Act transparency documentation becomes mandatory filter for European enterprise RFPs. |
| API-First Platform Unbundling | Modular encoder and analytics components capture mid-market buyers rejecting bundled suites. |
| Healthcare MSP Partnership | HIPAA technical safeguards liability offload attracts United States hospital system procurement. |
Methodological Framework
The analysis maps cloud-based deployment architectures, edge computing protocols, and hybrid infrastructure configurations, each validated through chief technology officers, IT procurement officers, platform engineers, and channel partners. Primary fieldwork combined with secondary validation from SEC filings of hyperscaler streaming divisions, hyperscaler capex disclosures, FCC regulatory dockets, and EU AI Act implementation guidance. Bottom-up sizing of encoder, CDN, and analytics module revenues triangulates against top-down enterprise IT budget allocation surveys.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity, and regional regulatory adoption pattern. CAGRs were derived through trend extrapolation of cloud migration timelines and compliance-driven upgrade cycles, with inputs from corporate training budget expansion rates and sovereign cloud mandate implementation schedules.
Underlying assumptions cover persistent hybrid work models, continued EU regulatory enforcement, and stable hyperscaler pricing, with deviation risk concentrated in bandwidth infrastructure investment delays and legacy codec deprecation timelines. Recalibration cycles align with material shifts in EU AI Act transparency requirement enforcement and sovereign cloud mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Subscription Video on Demand (Svod) Market
Video Streaming (OTT) Services
Asia Pacific Video Streaming Market
Video Streaming (OTT) Services
Streaming Media Services Market
Video Streaming (OTT) Services
Global Cloud Video Streaming Market
Video Streaming (OTT) Services
Latin America OTT Platform Market
Video Streaming (OTT) Services
India Smart TV and OTT Market
Video Streaming (OTT) Services
Streaming Spending Market
Video Streaming (OTT) Services
Sports Streaming Platform Market
Video Streaming (OTT) Services
Global Over-The-Top Market
Video Streaming (OTT) Services
Video-On-Demand [Vod] Market
Video Streaming (OTT) Services
Indonesia OTT Market
Video Streaming (OTT) Services
Game Streaming Market
Video Streaming (OTT) Services
Video Streaming Market
Video Streaming (OTT) Services
Global Transactional Video on Demand Market
Video Streaming (OTT) Services
Media Streaming Market
Video Streaming (OTT) Services
United States Online Video Platform Market