
 Adhesive Transfer Tape Market | 2026-2036
Adhesive Transfer Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Adhesive Transfer Tape Market Intelligence
The push for low-VOC materials, driven by regulations like the EU's REACH framework, is expanding the market for advanced adhesive formulations. 3M leverages its extensive R&D in polymer science to offer compliant solutions for the automotive sector. Tesa specializes in high-performance tapes for electronics assembly, where miniaturization demands precise bonding. Avery Dennison competes on a global scale with a broad portfolio targeting industrial and medical applications.
Adhesive transfer tape consists of a thin layer of pressure-sensitive adhesive pre-applied to a flexible release liner, lacking a carrier material. This unsupported design allows for precise application and bonding of irregular or dissimilar surfaces in industrial assembly. Acrylic-based materials command the largest share due to their versatility and resistance to temperature extremes. Within applications, the electronics segment represents the fastest-growing area, driven by the need for lightweight bonding in portable devices.
Product formulation is governed by chemical safety regulations, including the EU's REACH framework and substance limits set by the US EPA. In China, manufacturers must comply with national GB standards for adhesive products, impacting material sourcing. Future competitive advantage will hinge on developing solvent-free adhesives that meet both performance specifications and evolving environmental mandates.
Market Dynamics
The central tension shaping the adhesive transfer tape market is the conflict between the escalating performance requirements of electronics miniaturization and the tightening global chemical safety regulations. This dynamic forces material science innovation toward formulations that satisfy both the EU's REACH framework and the precise bonding needs of compact devices.
Growth Catalysts
- Electronics Miniaturization:The continuous drive for thinner, lighter smartphones and wearable devices creates persistent demand for unsupported adhesive tapes for component assembly in manufacturing centers across Vietnam and China.
- Automotive Lightweighting:Fuel efficiency standards compel automakers to use transfer tapes for bonding dissimilar lightweight materials, such as aluminum body panels and composite interior components, reducing overall vehicle mass.
- Solvent-Free Formulations:Mandates like the EU Green Deal and US EPA volatile organic compound (VOC) limits are accelerating the switch to advanced acrylic and silicone adhesives that eliminate harmful solvents from industrial processes.
Market Restraints
- Raw Material Volatility:The pricing of acrylic acid monomers, a primary feedstock, is subject to fluctuations based on petrochemical market dynamics, creating cost instability for adhesive manufacturers.
- Low Surface Energy Substrates:Adhesion to untreated low surface energy (LSE) plastics like polypropylene and polyethylene remains a significant technical barrier, often requiring costly surface preparation or specialized primers.
- Regulatory Compliance Burden:Navigating and certifying products against multiple, sometimes conflicting, substance control lists from ECHA in Europe and the EPA in the United States increases R&D costs and time-to-market.
Strategic Opportunities
- Bio-Based Adhesives:Developing pressure-sensitive adhesives from renewable, non-petroleum feedstocks presents an opportunity to meet corporate sustainability mandates and differentiate products in environmentally-conscious markets.
- Medical Wearable Devices:A growing application space exists for biocompatible, skin-contact-approved transfer tapes in disposable diagnostic tools, continuous glucose monitors, and other wearable health sensors.
- Thermally Conductive Tapes:Integrating ceramic or graphite fillers into adhesive films creates high-value products for heat dissipation in EV battery modules, LED lighting, and high-density printed circuit boards.
Industry Challenges
- Formulation Expertise Gap:A persistent shortage of polymer chemists and material scientists skilled in developing high-performance, solvent-free pressure-sensitive adhesives constrains new product development.
- Release Liner Sourcing:Dependence on a concentrated group of suppliers for specialized silicone-coated release liners creates potential supply chain vulnerabilities and limits negotiation leverage.
- Application-Specific Testing:The absence of universal standards for testing adhesion under dynamic, real-world conditions forces costly and time-consuming custom validation for each new end-use application.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adhesive Transfer Tape Market |
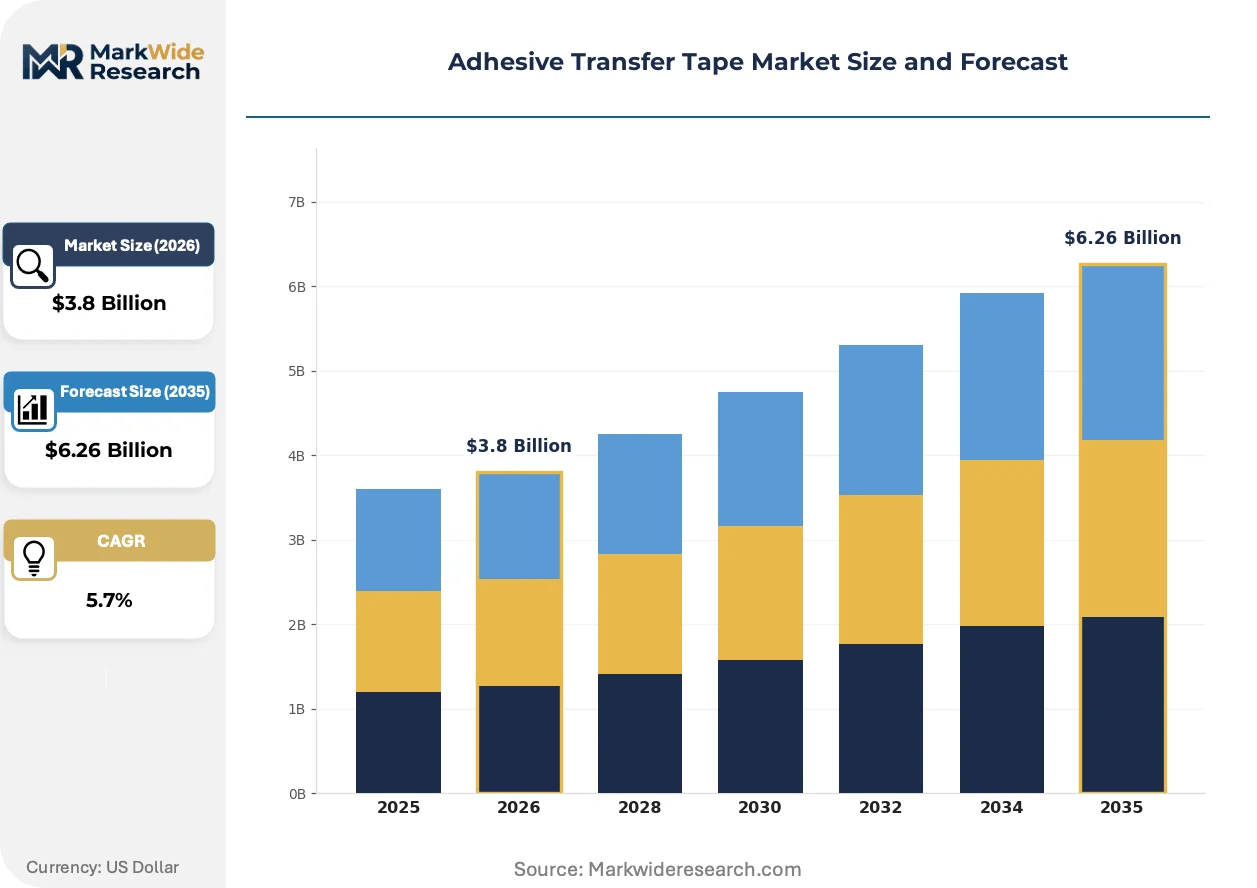
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Multipurpose, Specialty Material: Acrylic, Rubber, Silicone, Polyethylene Application: Automotive Assembly, Electronics, Building & Construction, Medical Devices End User: Manufacturers, Contractors, Hospitals, Retailers |
| Companies Covered | 3M, Avery Dennison, Tesa, Nitto Denko, Intertape Polymer Group, Lintec, Shurtape Technologies, Henkel, Lohmann, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adhesive Transfer Tape Market Strategic Shifts & Innovations
Material science innovation is advancing beyond simple bonding to deliver integrated functionality. The market's evolution is defined by a push towards tapes that solve specific engineering challenges, from electrical conductivity to environmental compliance, directly within the adhesive layer.
Technology and Product Evolution
Electrically conductive adhesives (ECAs) are a class of transfer tapes filled with metallic particles to provide electrical interconnection. The consumer electronics sector is rapidly adopting ECAs for electromagnetic interference (EMI) shielding and component grounding in compact devices. This technology is modularizing product design by combining bonding and electrical functions into a single, thin layer, simplifying assembly processes.
Regulatory and Policy Shifts
Europe's Restriction of Hazardous Substances (RoHS) directive strictly limits specific materials in electronic equipment, including certain flame retardants and heavy metals. This regulation directly impacts adhesive formulation, compelling manufacturers to certify their products as compliant for use in electronics assembly. Consequently, acrylic and silicone-based tapes that are inherently free of restricted substances are displacing older formulations in the EU market.
Demand-Side and Behavioral Shifts
A move toward specification-driven selection is replacing traditional purchasing models in high-performance industrial sectors. Engineers in the aerospace and automotive fields now select tapes based on certified performance data for shear strength and temperature resistance, often bypassing generalist distributors. This behavior is most visible within Germany's automotive supply chain and the United States' defense and aerospace industries.
Adhesive Transfer Tape Market Segmentation
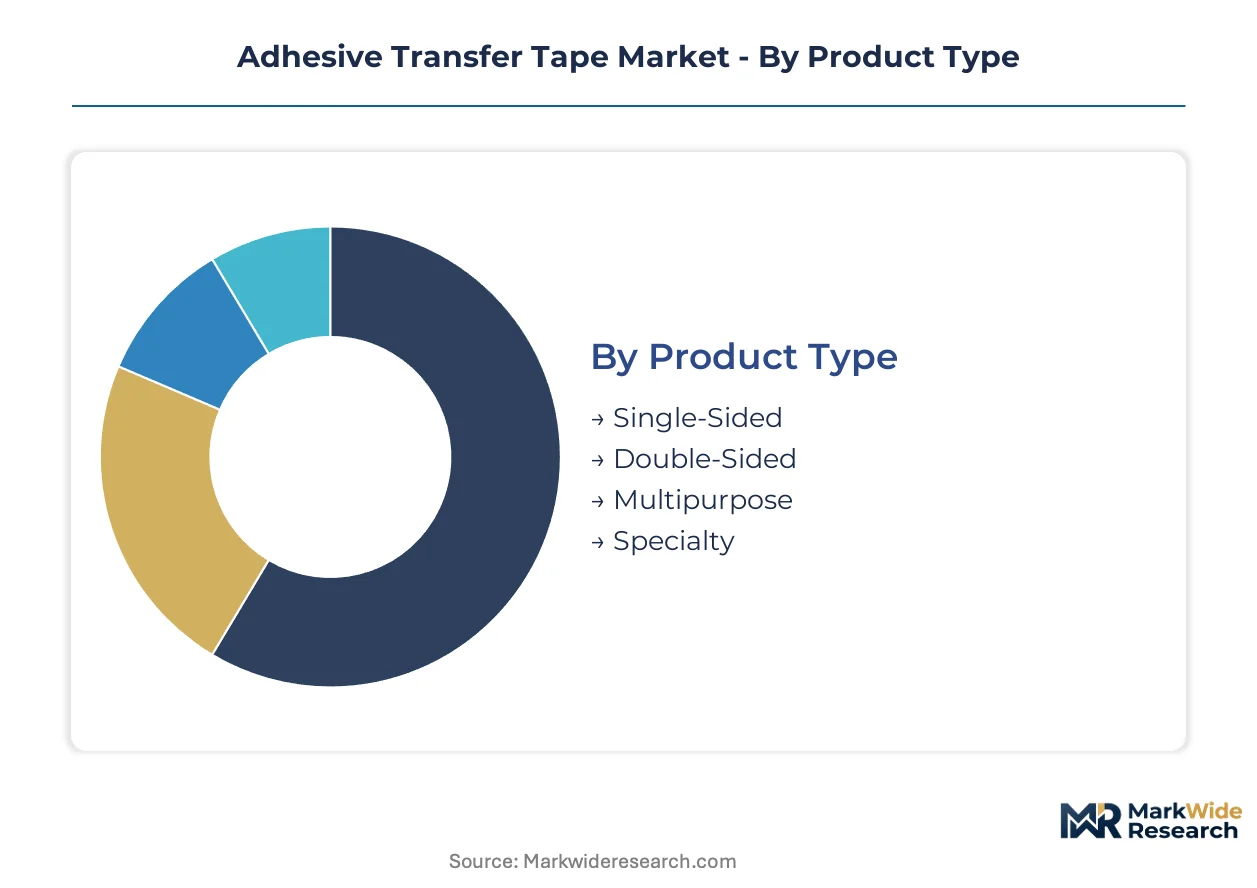
The Adhesive Transfer Tape Market is segmented to provide a granular understanding of product performance across diverse industrial applications. This segmentation highlights the specific material science advancements and application-specific demands that shape market development.
Product Type:
Buyers in the adhesive transfer tape market differentiate their product selection based on the specific bonding requirements of their assembly processes.
- Double-Sided:These tapes feature adhesive on both sides, typically with a release liner in between, enabling strong, permanent bonds between two surfaces. Double-sided transfer tapes are widely used in electronics manufacturing for attaching components and in automotive interiors for trim attachment.
- Specialty:Specialty tapes are engineered for unique performance characteristics, such as high thermal conductivity, electrical insulation, or specific resistance to chemicals or extreme temperatures. Demand for these advanced formulations is rising in electric vehicle battery modules and medical diagnostic devices.
- Single-Sided:Single-sided transfer tapes feature adhesive on one face, often used for temporary fixturing, masking, or specific surface protection applications in general industrial settings.
- Multipurpose:Multipurpose tapes offer balanced performance characteristics suitable for a broad range of general bonding and mounting tasks across various commercial and consumer product assemblies.
Double-Sided tapes lead volumes today; Specialty formulations are gaining share fastest.
Material:
Material selection for adhesive transfer tapes is often driven by performance specifications and environmental resistance requirements.
- Acrylic:Acrylic-based adhesives offer excellent resistance to UV light, temperature extremes, and chemicals, providing long-term durability and strong adhesion to many substrates. These materials are prevalent in demanding automotive and outdoor signage applications.
- Silicone:Silicone adhesives maintain flexibility and adhesion across very wide temperature ranges, from cryogenic to high heat, making them ideal for high-performance electronics and medical device manufacturing. They also adhere well to low surface energy materials.
- Rubber:Rubber-based adhesives provide high initial tack and good shear strength, commonly used for general-purpose bonding where immediate adhesion is critical and long-term environmental resistance is less stringent.
- Polyethylene:Polyethylene-based tapes are often used for protective films and temporary masking applications due to their conformability and ease of removal without leaving residue.
Acrylic materials dominate the market due to their versatility, while Silicone-based tapes address niche high-temperature applications.
Application:
The diverse application landscape for adhesive transfer tapes reflects varying industrial requirements and regulatory landscapes.
- Electronics:This segment involves bonding sensitive components within smartphones, tablets, and wearable devices, requiring thin, precise, and often electrically conductive or insulating tapes. Miniaturization in consumer electronics necessitates advanced bonding solutions for compact devices manufactured in China and Vietnam.
- Medical Devices:Transfer tapes in this sector must be biocompatible, sterilizable, and conformable for use in wearable health sensors, wound care, and disposable diagnostic equipment. Adherence to FDA and EMA regulations is paramount for these specialized products.
- Automotive Assembly:Tapes are used for bonding interior trim, emblems, wire harnessing, and lightweighting components, requiring high shear strength and resistance to temperature fluctuations. European automakers increasingly specify solvent-free acrylic tapes for interior applications.
- Building & Construction:Applications include mounting, insulation, and sealing in residential and commercial structures, where tapes provide weather resistance and long-term adhesion for various building materials.
Electronics applications drive significant volume, with Medical Devices exhibiting rapid expansion.
End User:
End-user segments for adhesive transfer tapes are defined by their operational scale and specific procurement needs.
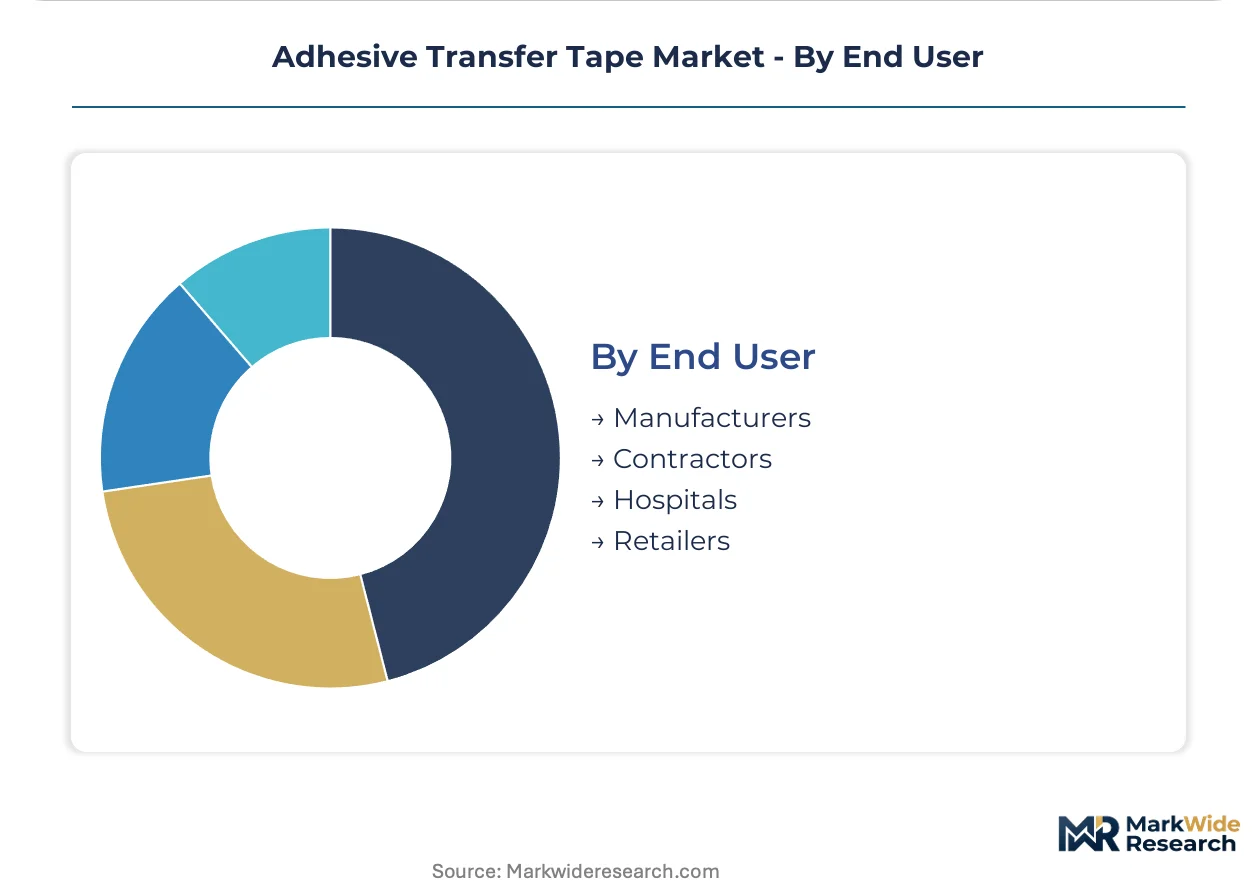
- Manufacturers:Industrial manufacturers, including those in electronics, automotive, and general assembly, consume the largest volume of transfer tapes for high-speed, automated production lines. Their purchasing decisions are driven by performance specifications and supply chain reliability.
- Hospitals:Healthcare facilities utilize transfer tapes for medical device assembly, patient care, and various clinical applications, prioritizing biocompatibility, sterility, and skin-friendly adhesion. Procurement is often influenced by national health regulations and patient safety standards.
- Contractors:Construction and installation contractors use transfer tapes for mounting, sealing, and temporary fixing in building projects, valuing ease of application and durability in diverse environmental conditions.
- Retailers:Retailers and consumers use transfer tapes for household repairs, crafts, and light-duty mounting tasks, with product accessibility and general-purpose utility being key purchasing factors.
Industrial Manufacturers represent the largest consumer base, while Hospitals are increasing their tape procurement for specialized uses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The adhesive transfer tape industry originated and scaled significantly in industrialized nations like the United States and Germany, driven by early advancements in polymer chemistry and manufacturing. These regions established foundational research and production capabilities for diverse industrial applications. Today, market expansion is increasingly influenced by evolving global manufacturing hubs.
United States
The United States market experiences demand from automotive lightweighting initiatives and the expanding medical wearable devices sector. US EPA volatile organic compound (VOC) limits compel manufacturers to adopt solvent-free adhesive formulations. Industrial clusters in Silicon Valley support electronics applications, while Detroit remains central to automotive adhesive advancements.
Germany
Germany's robust automotive assembly and industrial machinery sectors drive demand for high-performance adhesive transfer tapes. The EU's REACH framework and Green Deal mandates shape material selection for compliant products. Bavaria and Baden-Württemberg host significant automotive and advanced materials manufacturing, fostering adhesive innovation.
China
China's electronics manufacturing sector fuels substantial demand for adhesive transfer tapes, particularly for miniaturized devices. National GB standards for adhesive products dictate material sourcing and formulation requirements. The Yangtze River Delta region is a major hub for electronics production, concentrating tape consumption for component assembly.
Vietnam
Vietnam is emerging as a critical hub for consumer electronics assembly, generating significant demand for unsupported adhesive tapes. The country's environmental protection laws and participation in various trade agreements influence material compliance. Ho Chi Minh City and Hanoi regions are central to electronic component production and assembly operations.
Adhesive Transfer Tape Market Key Industry Players
Premium-margin players sit above commodity-margin players across product innovation and application-specific performance. The market structure is tiered, with specialized firms focusing on high-value applications and larger conglomerates offering broad portfolios. Strategic archetypes include innovation-driven specialists and scale-oriented generalists. Companies are pursuing portfolio diversification and strategic partnerships to expand their market reach.
Within the high-performance segment, 3M, a diversified global corporation, and Tesa, a German-based specialist, exemplify innovation-driven approaches. They leverage extensive R&D capabilities to develop advanced adhesive formulations for demanding applications. Avery Dennison, a global materials science company, represents a scale-oriented generalist, offering a broad portfolio that spans industrial, medical, and consumer applications. These firms collectively anchor market development through continuous material science advancements and strategic application focus across diverse end-use sectors.
| Leading Market Players |
|---|
| 3M |
| Avery Dennison |
| Tesa |
| Nitto Denko |
| Intertape Polymer Group |
| Lintec |
| Shurtape Technologies |
| Henkel |
| Lohmann |
Cost & Logistics Intelligence
Acrylic acid monomer price volatility, driven by petrochemical market dynamics, cascades through the adhesive transfer tape supply chain, directly impacting manufacturing costs and end-product pricing tiers. This cost instability forces manufacturers to optimize sourcing strategies and manage inventory levels carefully.
Pricing Analysis
Pricing stratifies across premium, standard, and economy tiers, reflecting product performance, certification levels, and brand reputation. Price differentiation is primarily driven by quality grade, adherence to regulations like EU REACH, and volume scale for industrial buyers. Pricing pressure stems from raw material cost fluctuations and the increasing burden of regulatory compliance across multiple geographies. Retailers and general-purpose consumers exhibit higher price sensitivity compared to electronics and automotive manufacturers requiring certified, application-specific solutions.
Supply Chain Analysis
Dual-sourcing requirements are increasingly mandated by major electronics and automotive OEMs to mitigate supply chain risks for critical components. Geographic supply concentration for adhesive transfer tapes centers on China and Vietnam for electronics assembly, and Germany for advanced automotive applications. Raw material dependencies include acrylic acid monomers and specialized silicone-coated release liners, which are sourced from a concentrated supplier base. Raw material volatility, particularly in petrochemicals, represents a significant structural risk. Distribution runs through direct sales channels for high-performance, application-specific tapes, while general-purpose tapes utilize broader industrial distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is evolving into a late-cycle quality story, driven by the named demand-shift toward precise bonding solutions required for electronics miniaturization and automotive lightweighting.
For Market Incumbents: Lock in long-term supply agreements for critical raw materials, especially acrylic acid monomers, to mitigate price volatility. Invest heavily in R&D for solvent-free and bio-based adhesive formulations to meet tightening environmental regulations like the EU Green Deal. Consolidate market share in high-growth application segments such as medical wearables, offsetting margin pressure from commodity-grade tapes. Secure certifications for new products against evolving chemical safety standards from regulators like the US EPA.
For New Entrants and Emerging Players: Advanced polymer science expertise offers a technology-first wedge into niche, high-value applications. Target underpenetrated segments like medical wearable devices, where biocompatible and skin-contact-approved tapes command premium pricing. Focus on developing thermally conductive tapes for electric vehicle battery modules, leveraging specific engineering challenges. A go-to-market strategy emphasizing certified performance data and application-specific solutions will allow differentiation from established generalists.
For Investors and Strategic Acquirers: Consolidation pressure builds where formulation expertise gaps persist and regulatory compliance costs are high. Long-term viability hinges on companies with robust R&D pipelines for next-generation, environmentally compliant adhesives. Identify acquisition targets specializing in bio-based adhesives or advanced silicone formulations for medical and high-temperature applications. The signal to watch is patent filings for novel solvent-free or electrically conductive adhesive technologies, indicating future market leadership.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Compliant Formulations | Increases supply of environmentally friendly adhesives for global electronics and automotive manufacturing. |
| R&D in Bio-Based Adhesives | Addresses corporate sustainability mandates and differentiates products in environmentally conscious markets. |
| Strategic Partnerships with Electronics OEMs | Secures long-term demand for high-performance tapes in miniaturized devices. |
| Acquisition of Thermally Conductive Tape Specialists | Expands portfolio into high-value applications for EV batteries and LED lighting. |
| Investment in Polymer Chemist Training Programs | Mitigates the persistent formulation expertise gap constraining new product development. |
Research Approach
Direct dialogue with R&D directors, procurement managers, regulatory affairs specialists, and polymer chemists across key industries formed the qualitative grounding for this study. This primary research was rigorously validated through secondary data analysis, ensuring a comprehensive market perspective. Key secondary sources included EU REACH and RoHS directives, US EPA reports, national GB standards from China, and publications from leading industry associations. Bottom-up and top-down triangulation ensured data integrity.
The analytical lens utilized a hybrid bottom-up and top-down approach to construct market sizing and forecasts across the analysis window. Segmentation dimensions modeled included product type, material, application, end user, and regional manufacturing hubs such as the Yangtze River Delta. Compound annual growth rates were derived from historical data analysis and projected demand trends, factoring in electronics miniaturization trends and automotive lightweighting mandates as key forecast inputs.
The model holds under current regulatory frameworks and anticipated technological advancements; deviation in raw material price volatility, new chemical safety regulations, or unforeseen technological breakthroughs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Wire Harness Tape Market
Tapes
Global UV-Cured Acrylic Adhesive Tapes Market
Tapes
Glue Tape Market
Tapes
Double Coated Film Tapes Market
Tapes
Splicing Tapes Market
Tapes
Utility Grade Duct Tapes Market
Tapes
Tape Unwinder Market
Tapes
Strapping Supplies Market
Tapes
Tabbing Tapes Market
Tapes
Washi Tapes Market
Tapes
Tape Dispenser Market
Tapes
Correction Tapes Market
Tapes
Self-Fusing Silicone Tapes Market
Tapes
Tape Backing Materials Market
Tapes
Packaging Tapes Market
Tapes
Carbon Tapes Market