
 Global UV-Cured Acrylic Adhesive Tapes Market | 2026-2036
Global UV-Cured Acrylic Adhesive Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Global UV-Cured Acrylic Adhesive Tapes Market Foresight
Asset-light leasing models for UV curing equipment is reconfiguring capital barriers for mid-sized tape converters and specialty coaters. 3M Company leverages captive resin synthesis to sustain margin control across its adhesive portfolio. H.B. Fuller Company anchors North American supply through integrated acrylic polymer production. Nitto Denko Corporation dominates precision coating capabilities for electronics-grade transfer tapes in East Asia.
Global UV-cured acrylic adhesive tapes are pressure-sensitive tapes manufactured from photoinitiator-doped acrylic formulations that polymerize upon exposure to ultraviolet radiation in the 200-400 nanometer range, delivering instant handling strength without thermal aging of substrates. These systems bond dissimilar materials in temperature-sensitive assemblies where solvent evaporation or heat activation would damage components. Double-sided tapes capture the largest volume share due to permanent lamination demand in display stack bonding, while UV-LED curing technology leads growth trajectory as mercury lamp phase-outs accelerate under RoHS and Minamata Convention obligations. Transfer tapes concentrate margin pools in aerospace bonding applications where FAA certification requirements limit qualified suppliers.
EPA oversight of volatile organic compound emissions shapes U.S. formulation standards, while REACH registration in the European Union restricts certain photoinitiator chemistries and drives reformulation cycles. ECHA substance evaluations on acrylate monomers are tightening toxicological thresholds, compelling tape manufacturers to validate alternative oligomer structures. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate qualification costs and secure multi-region product registrations before specification lock-in at major OEMs.
Market Dynamics
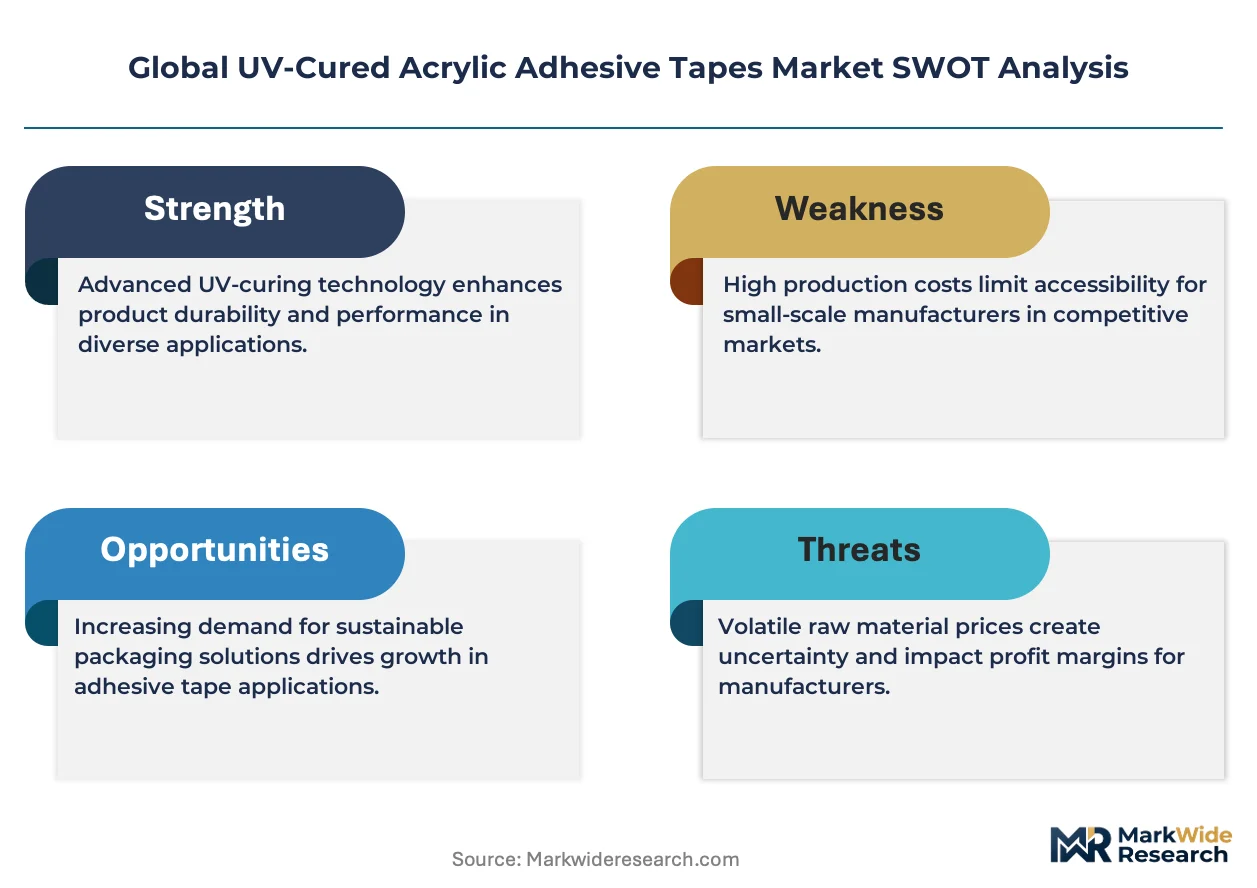
UV-LED curing systems are compressing energy costs and floor space requirements for tape converters, while REACH and RoHS mandates accelerate mercury lamp phase-outs across European and East Asian electronics corridors.
Growth Catalysts
- Mercury lamp bans under RoHS and the Minamata Convention:Electronics assemblers in South Korea and Japan are retrofitting lines to UV-LED curing to preempt compliance deadlines, pulling demand for compatible acrylic formulations.
- Display stack bonding in Guangdong province:Contract manufacturers for smartphones and tablets are standardizing double-sided UV-cured tapes for OLED lamination, creating concentrated procurement volume.
- Thermal substrate protection:Aerospace and medical device producers specify radiation-cured acrylics where heat-activated adhesives would damage temperature-sensitive components.
Market Restraints
- Photoinitiator supply concentration:Specialty photoinitiator production clusters in German and Chinese chemical corridors, exposing formulators to input volatility and qualification delays.
- ECHA acrylate monomer evaluations:REACH substance assessments are tightening toxicological thresholds for oligomer structures, forcing reformulation cycles before registration renewals.
- Heat-cured epoxy substitution in heavy industrial bonding:Structural applications requiring load-bearing permanence still default to thermal curing systems, capping UV-cured penetration in automotive chassis assembly.
Strategic Opportunities
- Asset-light UV equipment leasing:Mid-sized tape converters in Vietnam and Mexico are accessing curing lines through rental models, lowering capital barriers to specialty coating entry.
- FAA-certified aerospace transfer tapes:Qualified supplier scarcity in aviation structural bonding creates margin pools for manufacturers completing multiyear certification cycles.
- EU Green Deal procurement incentives:Public sector and defense contractors are weighting solvent-free adhesive systems in technical specifications, redirecting specification engineer attention toward radiation-cured options.
Industry Challenges
- Photochemistry formulation expertise scarcity:The intersection of acrylic polymer science and UV reactivity kinetics requires specialized talent that tape manufacturers struggle to recruit outside Basel and Osaka technical corridors.
- Multi-jurisdiction registration synchronization:Divergent EPA VOC thresholds, REACH substance restrictions, and GB standards in China force parallel qualification tracks that extend product launch timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global UV-Cured Acrylic Adhesive Tapes Market |
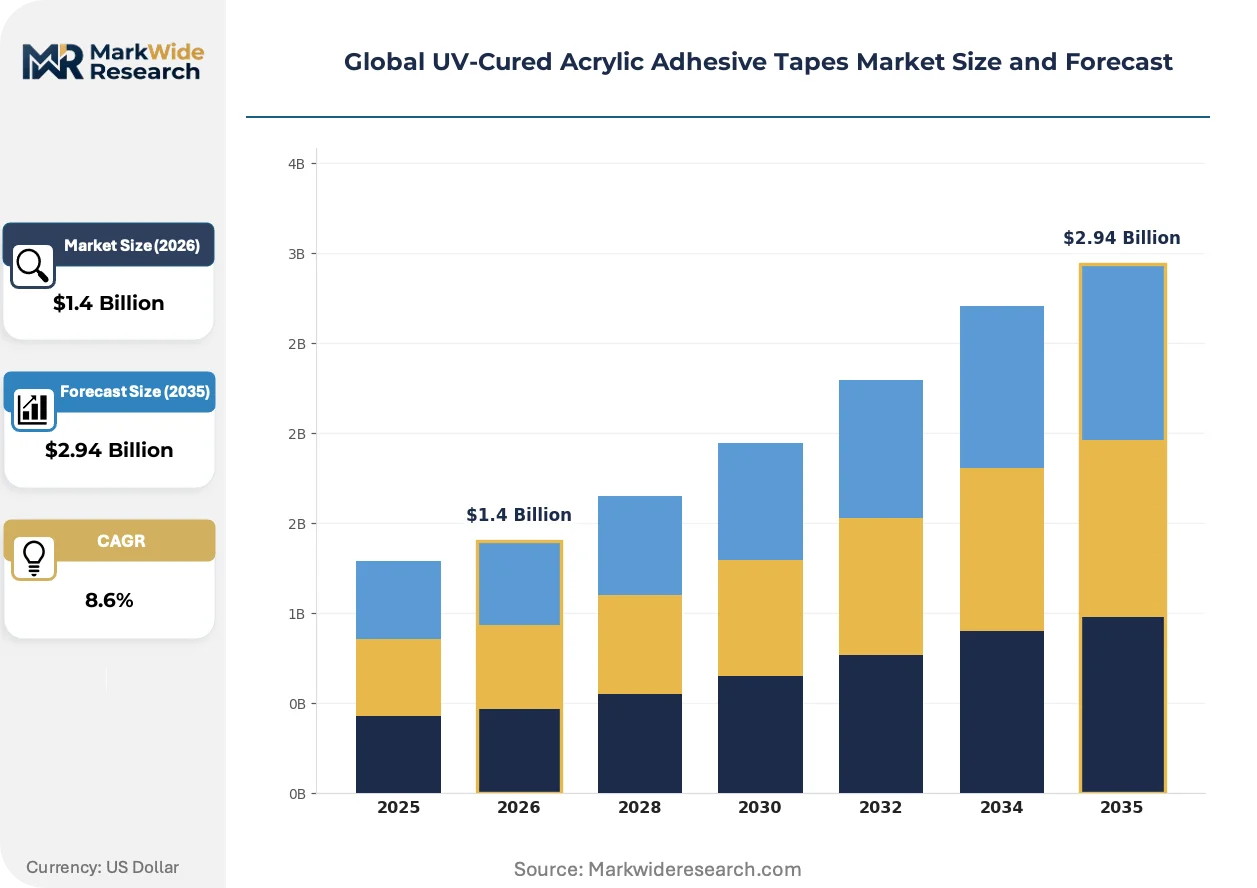
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Transfer Tape, Foil Tape Technology: UV-LED Curing, Mercury Lamp, Broadband UV, Vacuum UV Application: Electronics Assembly, Aerospace Bonding, Frame Sealing, Signage Mounting End User: Consumer Electronics Manufacturers, Aerospace OEMs, Packaging Firms, Advertising Agencies |
| Companies Covered | H.B. Fuller Company, tesa SE, 3M Company, Lintec Corporation, Scapa Group plc, Nitto Denko Corporation, Henkel AG & Company KGaA, Shin-Etsu Chemical Co. Ltd, Avery Dennison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global UV-Cured Acrylic Adhesive Tapes Market Shifts & Advancements
Formulation chemistry and curing hardware are converging to eliminate thermal processing steps, while regulatory phase-outs of legacy chemistries compress supplier qualification windows.
UV-LED curing hardware operating at 365-405 nanometers is rendering obsolete mercury vapor lamp systems across Japanese and South Korean electronics assembly floors. Display manufacturers in Osaka and Seoul are retrofitting bonding lines at pace to capture energy savings and eliminate hazardous waste disposal liabilities. The technology shift is compressing capital equipment replacement cycles from seven-year horizons to three-year refresh schedules.
REACH restrictions on specific photoinitiator chemistries are compelling European formulators to validate alternative oligomer structures ahead of ECHA substance evaluation deadlines. Tape manufacturers serving automotive and medical device OEMs face specification lock-in risks if multi-region registrations lag regulatory divergence. The friction concentrates in transfer tape categories where toxicological thresholds intersect with precision coating requirements.
Specification engineers in consumer electronics are consolidating adhesive vendor lists to three qualified suppliers per substrate combination, compressing switching cycles and raising barriers for second-tier formulators. Procurement teams in Shenzhen and Taipei are unbundling technical service from material supply, forcing tape manufacturers to price coatings and application engineering separately. The behavioral shift is most visible in Guangdong province where contract manufacturers centralize adhesive qualification across multiple OEM programs.
Global UV-Cured Acrylic Adhesive Tapes Market Segmentation
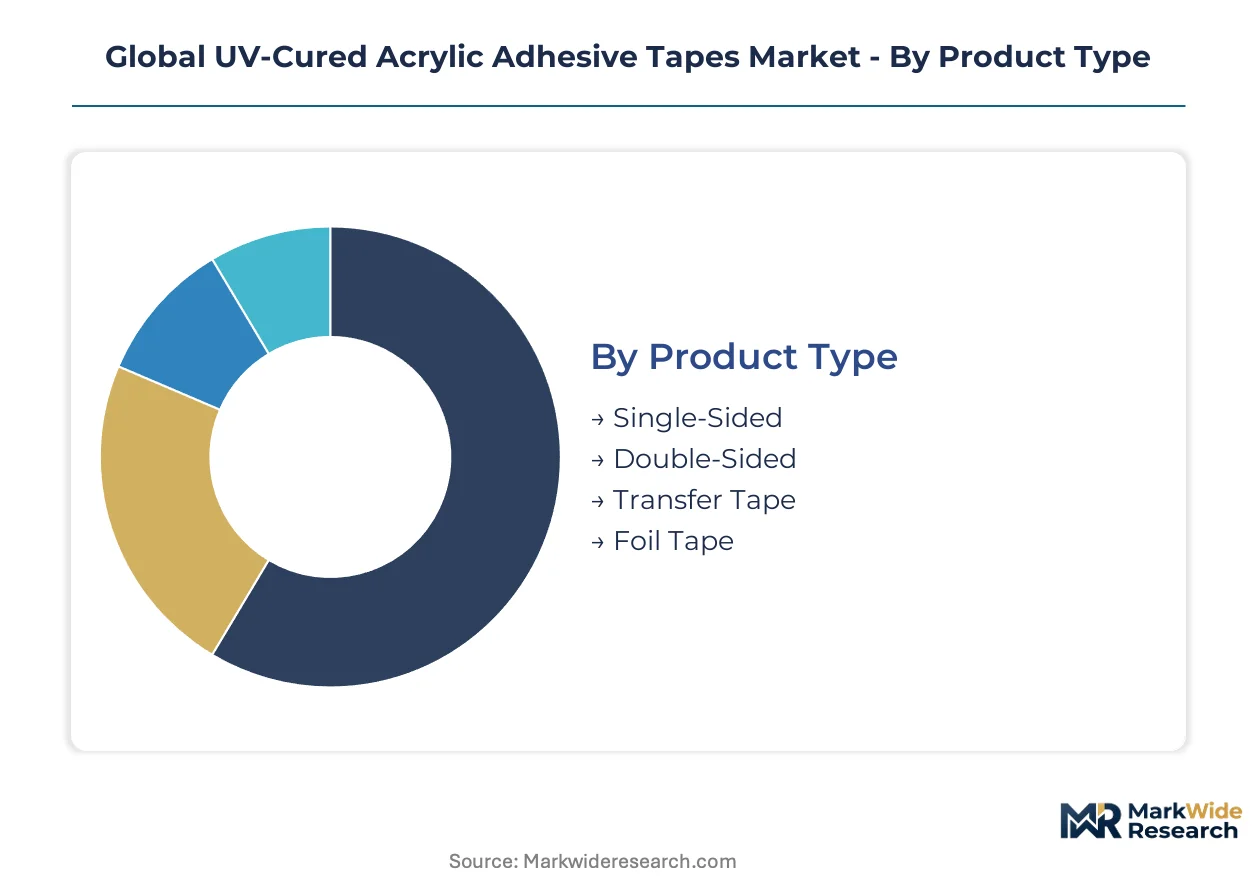
UV-cured acrylic adhesive tapes segment across bonding configurations, curing wavelengths, and precision requirements. Specification engineers match tape architecture to substrate sensitivity, line speed, and regulatory constraints in electronics and aerospace corridors.
Product Type:
The use-case spectrum spans permanent structural lamination to temporary process aids, with bond line thickness and removability driving specification choices.
- Double-Sided:Acrylic adhesive coats both sides of a carrier film, enabling permanent lamination of dissimilar substrates without mechanical fasteners. Display stack bonding in Guangdong province concentrates procurement volume as OLED manufacturers standardize these tapes for thin-film lamination where thermal activation would damage components.
- Transfer Tape:Adhesive layer dispenses without carrier substrate, delivering micron-level bond line control for aerospace precision bonding. FAA certification requirements limit qualified suppliers, creating margin concentration for manufacturers completing multiyear qualification cycles in structural aviation applications.
- Single-Sided:One adhesive face with exposed backing serves masking, temporary holding, and surface protection roles in electronics assembly workflows.
- Foil Tape:Metalized carrier provides EMI shielding and thermal management alongside adhesive bonding in high-frequency electronics enclosures.
Established volume favors Double-Sided; emerging adoption favors Transfer Tape.
Technology:
Cost tier differentiation separates legacy mercury systems from LED retrofits, with energy economics and hazardous waste liability reshaping capital allocation.
- UV-LED Curing:Solid-state emitters at 365-405 nanometers eliminate warm-up cycles and mercury disposal costs while compressing floor space requirements. Electronics assemblers in South Korea and Japan are retrofitting bonding lines to capture energy savings and preempt RoHS compliance deadlines.
- Mercury Lamp:Broadband vapor arc systems dominate installed base but face phase-out pressure under Minamata Convention obligations and EU waste directives.
- Broadband UV:Multi-wavelength output accommodates mixed photoinitiator formulations for specialty coaters serving diverse OEM specifications.
- Vacuum UV:Short-wavelength systems below 200 nanometers enable surface activation prior to adhesive deposition in ultra-clean electronics environments.
Mercury Lamp retains installed-base revenue; UV-LED Curing climbs the fastest on new line specifications.
Application:
Customer type concentration varies by certification burden, with aerospace and medical device producers paying premiums for qualified supplier scarcity.
- Electronics Assembly:Surface-mount component bonding and display lamination dominate procurement volume, with contract manufacturers in Shenzhen and Taipei consolidating vendor lists to three qualified suppliers per substrate combination.
- Aerospace Bonding:Structural adhesive applications require FAA certification and traceable lot documentation, limiting competition and sustaining margin pools for qualified tape manufacturers.
- Frame Sealing:Picture frame and display bezel mounting applications prioritize clean removability and residue-free performance in furniture and retail fixture production.
- Signage Mounting:Outdoor advertising and architectural graphics installation demands weathering resistance and rapid handling strength for installation productivity.
Electronics Assembly commands procurement volume; Aerospace Bonding commands specification premiums.
End User:
Supply concentration maps to manufacturing cluster geography, with procurement centralization in Guangdong province and Osaka-Seoul electronics corridors.
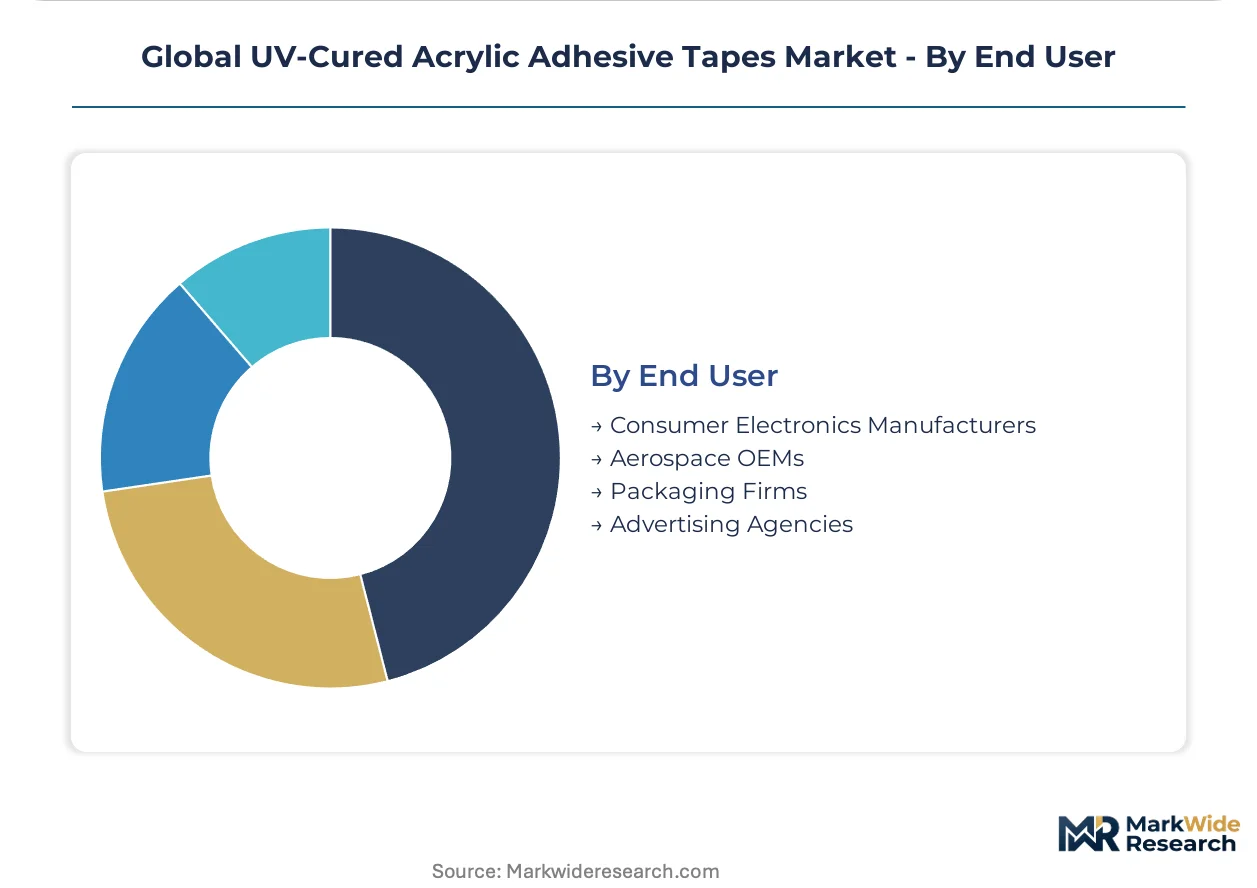
- Consumer Electronics Manufacturers:Smartphone, tablet, and wearable producers in China's Guangdong province drive standardization of UV-cured tapes for OLED lamination and component bonding, creating concentrated demand pull for compatible formulations.
- Aerospace OEMs:Boeing, Airbus, and tier-1 suppliers specify radiation-cured acrylics for temperature-sensitive assemblies where heat-activated adhesives would compromise composite integrity.
- Packaging Firms:Premium label and folding carton producers adopt UV-cured systems for heat-sensitive film substrates in food and cosmetic packaging lines.
- Advertising Agencies:Large-format graphics installers specify high-tack, weather-resistant tapes for outdoor signage mounting and vehicle wrap applications.
Consumer Electronics Manufacturers anchor volume demand; Aerospace OEMs anchor margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances favor East Asian manufacturing clusters, while North American and European markets absorb specialty grades for aerospace and medical applications. China runs substantial tape trade surpluses through Guangdong province operations. Germany and Japan maintain adhesive formulation technology deficits against tape finishing capacity.
China
Consumer electronics contract manufacturers in Guangdong province drive procurement volume for UV-cured double-sided tapes used in OLED lamination. GB standards under SAMR oversight regulate photoinitiator thresholds in adhesive formulations. Shenzhen and Dongguan industrial corridors concentrate tape converting capacity serving Apple, Huawei, and Xiaomi supply chains.
United States
Aerospace OEMs in Washington state and California specify radiation-cured acrylics for composite bonding where thermal curing risks substrate damage. EPA VOC emission thresholds shape formulation standards for domestic tape production. The Pacific Northwest corridor hosts precision coaters serving Boeing structural adhesive requirements.
Germany
Automotive suppliers in Baden-Württemberg adopt UV-cured systems for interior trim lamination on temperature-sensitive polymer substrates. REACH registration through ECHA restricts specific photoinitiator chemistries, compelling reformulation cycles. The Rhine-Neckar metropolitan region clusters specialty chemical formulators serving Continental and Bosch specifications.
Japan
Electronics assemblers in Osaka and Nagoya retrofit bonding lines to UV-LED curing to capture energy savings and preempt RoHS compliance deadlines. METI industrial policy supports mercury lamp phase-out acceleration through subsidy programs. The Kansai industrial corridor dominates precision coating capabilities for display stack applications.
South Korea
Display panel manufacturers in Gyeonggi province standardize UV-cured transfer tapes for flexible OLED production lines. MFDS regulates adhesive constituents in medical device applications, creating qualification barriers for imported formulations. The Seoul capital area concentrates Samsung and LG procurement operations driving regional specification standards.
Global UV-Cured Acrylic Adhesive Tapes Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in resin synthesis and precision coating segments. The market structure concentrates around multinational chemical conglomerates with captive acrylic polymer production and specialized tape converters serving electronics and aerospace verticals. Three archetypes dominate: integrated resin-to-tape manufacturers, precision coating specialists, and regional converters accessing UV equipment through leasing models. Capacity expansion and strategic partnerships constitute the dominant competitive vectors as firms secure photoinitiator supply agreements and multi-region registration portfolios.
Among integrated chemical producers, 3M Company, H.B. Fuller Company, and Nitto Denko Corporation exemplify distinct strategic positions. 3M represents the captive resin synthesis archetype, maintaining margin control through backward integration into acrylic polymer production. H.B. Fuller anchors North American supply chain configuration through integrated manufacturing assets. Nitto Denko occupies the precision coating specialist tier, serving electronics-grade transfer tape demand from East Asian industrial corridors. These three firms illustrate how geographic origin and corporate structure shape competitive positioning without determining specific market outcomes.
| Leading Market Players |
|---|
| H.B. Fuller Company |
| tesa SE |
| 3M Company |
| Lintec Corporation |
| Scapa Group plc |
| Nitto Denko Corporation |
| Henkel AG & Company KGaA |
| Shin-Etsu Chemical Co. Ltd |
| Avery Dennison Corporation |
| Others |
Supply & Pricing Matrix
Photoinitiator supply concentration in German and Chinese chemical corridors determines both pricing tier spreads and supply chain shape, as specialty chemical bottlenecks cascade through formulation costs and converter qualification timelines. Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with aerospace-grade transfer tapes commanding substantial premiums for FAA certification while commodity double-sided variants face compression from Guangdong contract manufacturers. Price differentiation separates certified aerospace supply from electronics-grade formulations, with volume scale and after-sales technical service bundling as secondary drivers. Cost compression in standard-grade electronics tapes is intensifying because Shenzhen procurement teams are unbundling engineering support from material supply. Consumer electronics manufacturers exhibit highest price sensitivity, whereas aerospace OEMs prioritize qualification security over unit economics.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with aerospace-grade transfer tapes commanding substantial premiums for FAA certification while commodity double-sided variants face compression from Guangdong contract manufacturers. Price differentiation separates certified aerospace supply from electronics-grade formulations, with volume scale and after-sales technical service bundling as secondary drivers. Cost compression in standard-grade electronics tapes is intensifying because Shenzhen procurement teams are unbundling engineering support from material supply. Consumer electronics manufacturers exhibit highest price sensitivity, whereas aerospace OEMs prioritize qualification security over unit economics.
Supply Chain Analysis
Export-control restrictions on specialty photoinitiator chemistries limit technology flows between German formulators and East Asian converters, compressing supplier qualification windows. Production concentrates in China, Germany, and Japan, with acrylic monomer synthesis anchored in the Rhine-Neckar region and precision coating capacity clustering in Osaka-Seoul corridors. Raw material flows draw from petrochemical feedstocks, photoinitiator specialties, and carrier film substrates. Single-source vulnerability concentrates in photoinitiator supply where ECHA substance evaluations threaten reformulation cycles. Distribution runs through direct OEM supply agreements for aerospace and medical tiers, with electronics volumes flowing through Shenzhen and Taipei distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery phase driven by mercury lamp phase-outs under RoHS and Minamata Convention obligations, which compress capital equipment replacement cycles and pull demand for compatible formulations.
For Market Incumbents: Insulate margin pools by securing captive photoinitiator supply agreements ahead of ECHA registration deadlines, while accelerating UV-LED formulation qualification across multiple OEM vendor lists to preempt specification lock-in. Backward integration into acrylic polymer production sustains cost control against volatile monomer inputs. For New Entrants and Emerging Players: Pursue asset-light leasing models for UV curing equipment in Vietnam and Mexico industrial corridors, where mid-sized converters seek lower capital barriers to specialty coating entry. Aerospace transfer tapes offer the most penetrable white-space given qualified supplier scarcity, with FAA certification investment as the critical go-to-market angle. For Investors and Strategic Acquirers: The market sits at an early-cycle expansion phase that favors precision coating specialists with established electronics-grade capabilities and multi-region registration portfolios. Long-term viability over the coming decade hinges on photochemistry formulation expertise scarcity in Basel and Osaka technical corridors. Watch for ECHA substance evaluation timelines as the inflection signal for reformulation-driven M&A activity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Polymer Production | H.B. Fuller and 3M sustain margin control through captive resin synthesis against volatile monomer inputs. |
| UV-LED Equipment Leasing Partnership | Mid-sized Vietnamese and Mexican converters access curing lines without seven-year capital commitment cycles. |
| FAA Certification Completion | Qualified supplier scarcity in aerospace structural bonding creates durable margin pools for certified transfer tape manufacturers. |
| Multi-Jurisdiction Registration Synchronization | Parallel EPA, REACH, and GB standard qualification tracks secure specification lock-in at major OEMs. |
| Photoinitiator Supply Agreement | Long-term contracts with German and Chinese specialty chemical producers hedge against ECHA-driven reformulation volatility. |
Research Methodology
Desk research of trade customs data, ECHA substance evaluation filings, and SEC chemical company disclosures preceded structured interviews with adhesive formulation chemists, procurement directors at Guangdong contract manufacturers, and precision coating line engineers. Primary fieldwork with tape converters in Osaka, Seoul, and Shenzhen validated secondary findings on UV-LED retrofit timelines and specification consolidation patterns. Bottom-up demand modeling from individual OEM programs triangulated against top-down chemical industry production data.
Assumptions held fixed include RoHS mercury lamp phase-out deadlines and ECHA substance evaluation timelines, while variables included UV-LED equipment adoption rates and photoinitiator supply disruptions. The analytical framework modeled segmentation across bonding configuration, curing wavelength technology, and end-use industry vertical throughout the projection horizon. CAGRs derived from installed base conversion rates and new line specifications across electronics assembly corridors. Forecast inputs incorporated SAMR GB standard evolution and METI subsidy program disbursements.
Sensitivities concentrate around ECHA acrylate monomer toxicological threshold revisions and photoinitiator supply disruptions from German chemical corridor production constraints. Forecasts reflect these assumptions alongside baseline demand from OLED lamination standardization in Guangdong province. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Filament Tapes Market
Tapes
Holographic Tear Tape Market
Tapes
Pouch Tapes Market
Tapes
Carton Sealing Tape Market
Tapes
Adhesive Transfer Tape Market
Tapes
Mastic Tapes Market
Tapes
Self-Fusing Silicone Tapes Market
Tapes
Packaging Tape Printing Market
Tapes
Masking Tape Market
Tapes
Invisible Tapes Market
Tapes
UV Cured Acrylic Foam Tapes Market
Tapes
Wire Harness Tape Market
Tapes
Pre-Printed Tape Market
Tapes
High Bond Tape Market
Tapes
Freezer Tape Market
Tapes
Gummed Tapes Market