
 Self-Fusing Silicone Tapes Market | 2026-2036
Self-Fusing Silicone Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Fusing Silicone Tapes Market Analytics
EU REACH restrictions on halogenated flame retardants is hardening demand for silicone-based electrical insulation across European manufacturing. 3M Company leverages its materials science portfolio to sustain leadership in high-temperature bonding applications. Illinois Tool Works anchors North American supply through specialized industrial distribution channels. Nitto Denko Corporation competes on precision coating capabilities for thin-film electrical tapes.
Self-fusing silicone tapes comprise cross-linked polydimethylsiloxane layers that bond to themselves without adhesive when stretched and wrapped, typically rated for continuous operating temperatures from -60°C to 200°C and dielectric strengths exceeding 20 kV/mm. Electrical insulation products dominate value capture given OEM specification lock-in and recertification costs for alternative materials. Sealant applications in pipe repair represent the fastest-growing segment as utilities prioritize in-situ rehabilitation over full replacement. DIY users through online retail channels show expanding volume contribution though at thinner margins than contractor-direct sales.
FDA compliance for food-contact applications, EPA standards for volatile organic compound emissions, and OSHA electrical safety requirements collectively shape product formulation and market access thresholds in the United States. The EU RoHS Directive and CE marking obligations enforce material purity disclosures that favor established suppliers with certified supply chains. Stakeholders must monitor evolving automotive electrification standards and utility infrastructure resilience mandates as the primary demand pivot points.
Market Dynamics
REACH and RoHS compliance deadlines are compressing specification cycles across European aerospace and automotive wire harnessing, forcing rapid material transitions from halogenated insulation to silicone-based alternatives with certified supply chains.
Growth Catalysts
- EU REACH Phase-Out:Restrictions on halogenated flame retardants in electrical insulation are mandating silicone tape adoption across German automotive tier-one suppliers.
- Aerospace Electrification:OEMs face recertification timelines for next-generation aircraft wiring systems that demand thermal performance above 180°C continuous operation.
- Utility Infrastructure Rehabilitation:Water and gas utilities across the United States are prioritizing in-situ pipe repair over full replacement, accelerating sealant tape specification.
Market Restraints
- Silicone Feedstock Volatility:Polydimethylsiloxane precursor costs fluctuate with energy-intensive chlorosilane production concentrated in Chinese manufacturing zones.
- Specialized Coating Equipment:Precision thin-film deposition requires capital-intensive vacuum coating lines that concentrate supply among established Japanese and European producers.
- Fluoropolymer Substitution:PTFE and FEP tapes retain specification lock-in for ultra-high-frequency applications above 200°C where silicone dielectric losses prove prohibitive.
Strategic Opportunities
- Indian Industrial Electrification:BIS certification requirements for electrical insulation are creating first-mover advantages for suppliers establishing local testing partnerships.
- Offshore Wind Cable Splicing:Subsea connector sealing applications combine silicone's hydrophobicity with self-fusing properties for maintenance-free 25-year service life.
- Amazon Industrial Supply:Contractor-direct e-procurement platforms are compressing distributor margins while expanding volume access to mid-sized electrical contractors.
Industry Challenges
- Formulation Chemistry Expertise:Cross-linking density control for dielectric strength above 20 kV/mm requires polymer scientists with specialized silicone elastomer experience that concentrates at legacy suppliers.
- Multi-Agency Certification Overlap:Simultaneous FDA food-contact, EPA VOC, and OSHA electrical safety approvals extend product development timelines by 18-24 months for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Fusing Silicone Tapes Market |
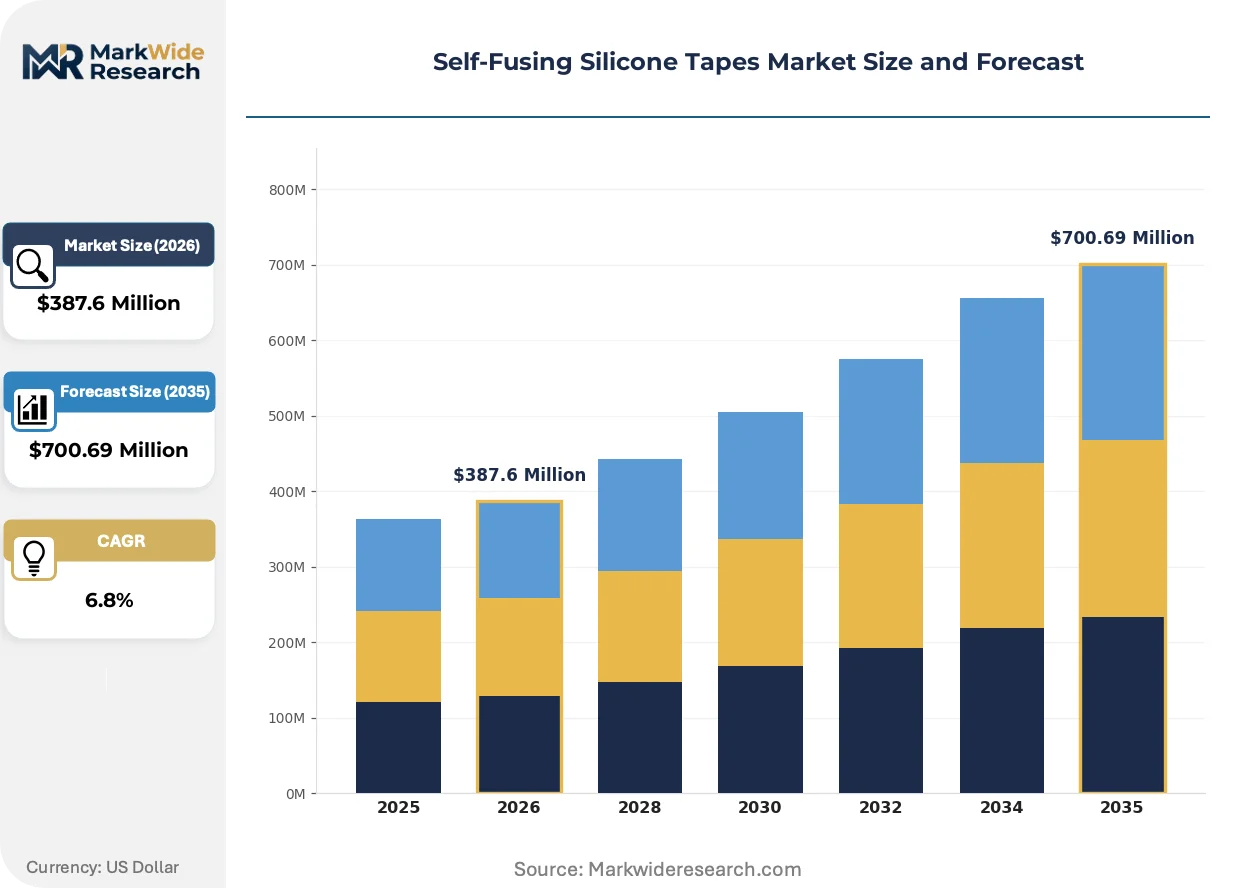
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrical Insulation, HVAC, Automotive, Industrial Application: Sealant, Pipe Repair, Electrical Repair, Sports Equipment End User: Manufacturers, DIY Users, Contractors, Maintenance Services Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | 3M Company, Avery Dennison Corporation, Illinois Tool Works, Scapa Group, Denka Company Limited, Nitto Denko Corporation, Parafix Tapes & Conversions, Lynvale Limited, ORAFOL Europe GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Fusing Silicone Tapes Market Evolving Landscape
Material science advances and regulatory pressure are converging to reshape specification patterns across high-temperature electrical insulation, with automation and compliance transparency emerging as decisive competitive differentiators.
Laser-guided tape application systems are automating wire harness wrapping in aerospace final assembly lines, cutting labor content by half while ensuring consistent stretch ratios for dielectric integrity. Boeing and Airbus tier suppliers in Toulouse and Hamburg are piloting these robotic cells for A320 and 737 successor programs. The technology is automating quality documentation for FAA and EASA traceability requirements.
ECHA's SCIP database obligations under the EU Waste Framework Directive are forcing full material disclosure for silicone tapes containing filler additives or pigment systems. Suppliers must now submit granular composition data for every SKU sold into the European Economic Area. German automotive harness manufacturers are responding by consolidating supplier bases to those with pre-certified SCIP entries.
Electrical contractors are unbundling after-sales technical support from product procurement, purchasing self-fusing silicone tapes through Amazon Business and Grainger while sourcing application training separately from manufacturer field engineers. This behavior is most pronounced among mid-sized commercial construction firms in Texas and Florida where project-based purchasing dominates.
Self-Fusing Silicone Tapes Market Segmentation
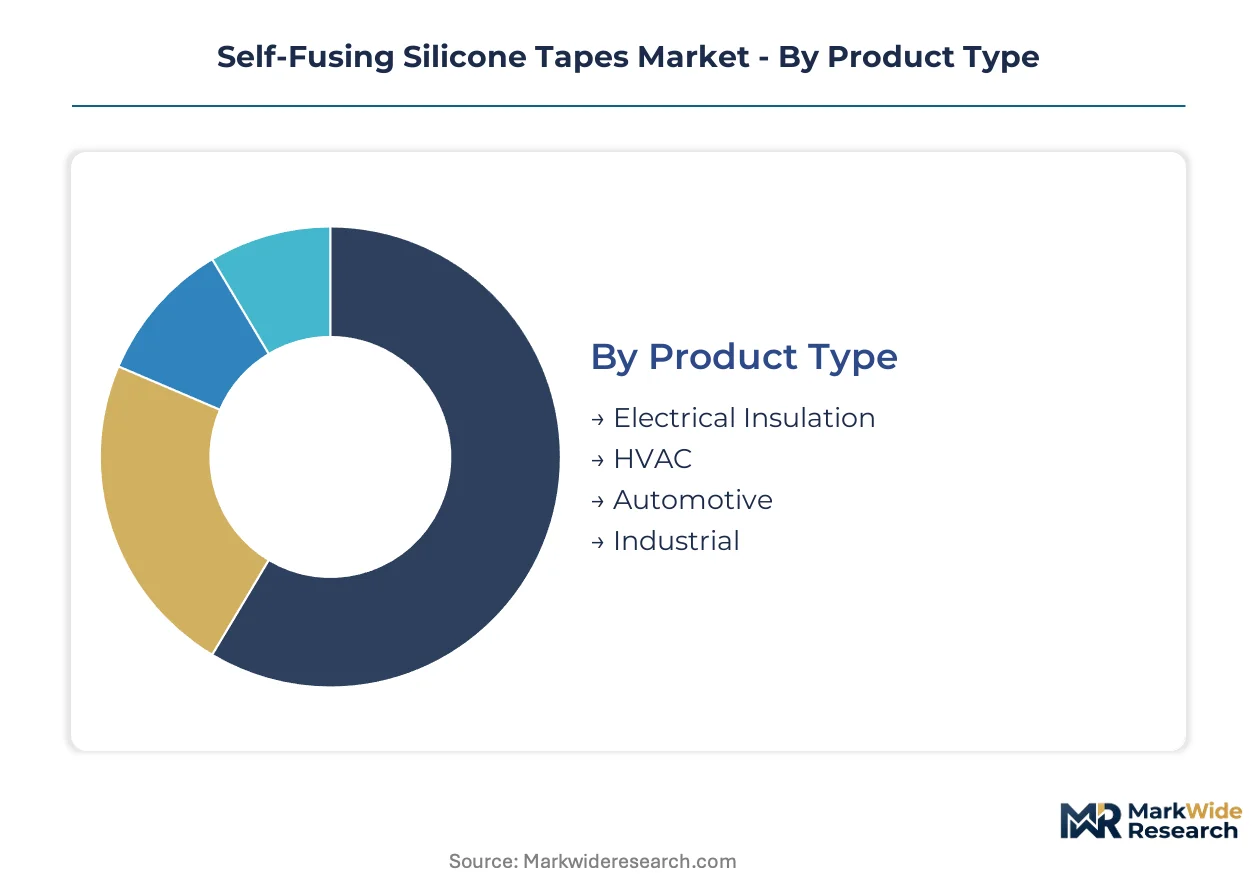
Self-fusing silicone tapes serve divergent technical requirements across electrical, thermal, and mechanical bonding applications. Specification lock-in varies dramatically by integration depth, from standalone consumer repairs to embedded aerospace harness systems requiring full certification traceability.
Product Type:
Integration depth separates standalone consumables from specification-critical embedded materials, with certification burden and margin structure diverging accordingly.
- Electrical Insulation:Cross-linked polydimethylsiloxane layers rated for dielectric strengths exceeding 20 kV/mm dominate OEM specification sheets. Aerospace wire harnessing in Toulouse and Hamburg production clusters drives demand for continuous 180°C thermal performance under EASA traceability requirements.
- Automotive:German tier-one suppliers retrofit production lines with halogen-free silicone solutions as REACH compliance deadlines compress material transition timelines. Thermal and chemical resistance specifications now exclude legacy halogenated alternatives across EV powertrain harnessing.
- HVAC:Compressor terminal sealing and ductwork gasketing utilize silicone's hydrophobic stability across freeze-thaw cycles.
- Industrial:Pump and valve sealing in chemical processing plants leverages solvent resistance without adhesive degradation.
Electrical Insulation leads volumes today; Automotive is gaining share fastest.
Application:
Functional deployment separates infrastructure rehabilitation from discrete repair work, with contract value and procurement channel diverging sharply.
- Pipe Repair:Water and gas utilities across Texas and Florida prioritize in-situ rehabilitation over full replacement, accelerating sealant tape specification for trenchless infrastructure renewal. Twenty-five-year service life requirements match silicone's hydrophobic stability against soil chemistry variation.
- Sealant:Subsea connector sealing for offshore wind cable splicing combines self-fusing properties with maintenance-free durability. North Sea and Gulf of Mexico installations specify silicone for 25-year submersion without degradation.
- Electrical Repair:Emergency motor and transformer rewinding in industrial maintenance relies on field-applied dielectric restoration.
- Sports Equipment:Hockey stick grips and baseball bat handles exploit silicone's friction properties without adhesive residue.
Pipe Repair leads volumes today; Sealant is expanding most quickly.
End User:
Procurement sophistication separates specification-driven manufacturers from price-sensitive discretionary purchasers, with technical support requirements scaling accordingly.
- Manufacturers:Aerospace OEMs and automotive harness producers demand batch-level SCIP database compliance for ECHA Waste Framework Directive adherence. Full material disclosure for filler additives and pigment systems now gates European Economic Area market access.
- Contractors:Mid-sized electrical firms in Texas and Florida unbundle after-sales technical support from product procurement, purchasing through Amazon Business while sourcing application training separately from manufacturer field engineers.
- Maintenance Services:Utility infrastructure crews require field-proven stretch ratios for dielectric integrity under OSHA electrical safety protocols.
- DIY Users:Online retail channels show expanding volume contribution though at thinner margins than contractor-direct sales.
Manufacturers lead volumes today; Contractors are climbing the fastest.
Distribution Channel:
Channel economics separate high-touch specification sales from automated procurement, with margin compression accelerating in transactional segments.
- Distributors:Illinois Tool Works anchors North American supply through specialized industrial distribution channels serving automotive and aerospace clusters. Technical field support and application engineering justify premium positioning against commoditized alternatives.
- Direct Sales:OEM specification lock-in and recertification costs for alternative materials sustain manufacturer-direct relationships for electrical insulation grades. Boeing and Airbus tier suppliers in Toulouse and Hamburg source through qualified supplier programs with full traceability documentation.
- Online Retail:Amazon Industrial Supply compresses distributor margins while expanding volume access to mid-sized electrical contractors.
- Wholesale:Volume aggregation for maintenance services and smaller contractors operates on thinner technical support inclusion.
Distributors lead volumes today; Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer chemists and aerospace wire harness engineers concentrate in Germany's industrial belt and the US Gulf Coast, anchoring regional demand clusters for high-temperature electrical insulation materials.
United States
Utility infrastructure rehabilitation and aerospace electrification drive specification volume. OSHA electrical safety protocols and EPA volatile organic compound standards enforce formulation compliance. Houston-based energy contractors deploy self-fusing silicone tapes for subsea connector sealing in Gulf of Mexico offshore wind projects.
Germany
Automotive tier-one suppliers retrofit EV powertrain harnessing lines with halogen-free insulation solutions. REACH Phase-Out deadlines for halogenated flame retardants compress material transition timelines. Stuttgart and Wolfsburg production clusters source through qualified supplier programs with full ECHA SCIP database traceability.
China
Chlorosilane precursor manufacturing concentrates energy-intensive silicone feedstock production in Jiangsu and Zhejiang provinces. GB standards for electrical insulation materials shape domestic certification requirements. Yangtze River Delta industrial zones supply polydimethylsiloxane layers for regional electrical tape fabricators.
Japan
Precision coating capabilities for thin-film electrical tapes concentrate among established producers. METI industrial standards govern high-temperature bonding material specifications. Nagoya and Osaka manufacturing clusters serve aerospace and automotive OEMs across Asia-Pacific supply chains.
India
BIS certification requirements for electrical insulation create compliance barriers for imported silicone tapes. Central Electricity Authority regulations enforce dielectric performance standards for grid infrastructure materials. Maharashtra and Gujarat industrial corridors attract first-mover suppliers establishing local testing partnerships.
Self-Fusing Silicone Tapes Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the self-fusing silicone tapes market. The supplier base organizes into three tiers: diversified materials conglomerates with certified supply chains, specialized industrial tape fabricators with precision coating assets, and regional converters serving price-sensitive maintenance segments. Consolidation pressures intensify as ECHA SCIP database obligations and multi-agency certification requirements extend product development timelines by 18-24 months, favoring incumbents with established compliance infrastructure. Dominant competitive moves include strategic partnerships for aerospace qualification programs and geographic expansion through local testing partnerships in emerging industrial electrification markets.
Among diversified materials conglomerates, 3M Company and Illinois Tool Works occupy positions anchored by specialized industrial distribution channels and materials science portfolios. Nitto Denko Corporation represents the precision coating archetype, with Japanese producers concentrating supply of vacuum deposition equipment for thin-film electrical tapes. These three entities exemplify how certification burden and specification lock-in sustain incumbent positioning against commoditized alternatives.
| Leading Market Players |
|---|
| 3M Company |
| Avery Dennison Corporation |
| Illinois Tool Works |
| Scapa Group |
| Denka Company Limited |
| Nitto Denko Corporation |
| Parafix Tapes & Conversions |
| Lynvale Limited |
| ORAFOL Europe GmbH |
| Others |
Value Network & Pricing Analysis
Polydimethylsiloxane precursor costs anchor pricing tiers from Chinese chlorosilane production through German automotive tier-one procurement, with energy-intensive feedstock volatility compressing margins at mid-grade converters while premium aerospace grades capture specification premiums through EASA traceability documentation.
Pricing Analysis
Bundled technical support and unbundled product procurement now split the market into divergent pricing models. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified grades with full SCIP database compliance from industrial maintenance volumes and DIY retail strips. Price differentiation rests on certification grade and after-sales engineering inclusion. Cost compression in mid-grade industrial segments is intensifying because Amazon Business and Grainger are disintermediating traditional distributors. DIY users through online retail channels show the highest price sensitivity, while Boeing and Airbus tier suppliers in Toulouse and Hamburg demonstrate minimal elasticity due to recertification cost barriers.
Supply Chain Analysis
Chlorosilane feedstock supply rests on energy-intensive manufacturing concentrated in Jiangsu and Zhejiang provinces of China. Cross-linked polydimethylsiloxane layers draw from these precursors, with precision thin-film deposition equipment anchored in Japanese and European producer bases. Single-source vulnerability concentrates at vacuum coating line manufacturers serving thin-film electrical tape specifications. Distribution runs through specialized industrial channels anchored by Illinois Tool Works in North America and qualified supplier programs serving German automotive clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance costs in Europe run substantially higher than BIS certification investments in India, creating geographic-arbitrage opportunities for suppliers establishing local testing partnerships ahead of accelerating industrial electrification demand.
For Market Incumbents: Extend certification infrastructure advantages by deepening ECHA SCIP database capabilities and consolidating supplier relationships with German automotive harness manufacturers facing compressed material transition timelines. Fluoropolymer substitution threats in ultra-high-frequency applications above 200°C demand accelerated R&D investment in low-dielectric-loss silicone formulations. Backward integration into chlorosilane precursor supply buffers feedstock volatility exposure. For New Entrants and Emerging Players: Laser-guided tape application systems offer a technology-first wedge into aerospace automation procurement cycles as Boeing and Airbus tier suppliers pilot robotic wrapping cells for next-generation programs. Indian industrial electrification presents the most penetrable geography given BIS certification barriers for imported alternatives. Contractor-direct e-procurement platforms provide a channel-native go-to-market angle for mid-sized electrical firms unbundling technical support from product purchase. For Investors and Strategic Acquirers: Roll-up economics work for regional converters with established local testing partnerships because multi-agency certification overlap extends product development timelines by 18-24 months, favoring incumbents with pre-approved supply chains. Target asset-light designers with specialized coating capabilities rather than capital-heavy precursor manufacturers. Watch for ECHA regulatory expansion beyond halogenated flame retardants as the inflection indicator for accelerated consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosilane Feedstock | Captive supply of polydimethylsiloxane precursors insulates margin compression from Chinese energy price volatility. |
| ECHA SCIP Database Pre-Certification | Full material disclosure for filler additives gates European Economic Area access for aerospace harness suppliers. |
| Laser-Guided Application System Partnerships | Robotic cell integration with Boeing and Airbus tier suppliers automates quality documentation for FAA traceability. |
| Indian BIS Testing Partnership Establishment | Local certification capabilities capture first-mover positioning in Maharashtra and Gujarat industrial corridors. |
| Offshore Wind Cable Splicing Qualification | Subsea connector sealing specifications in North Sea and Gulf of Mexico projects lock in 25-year service life demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with polymer scientists at legacy silicone elastomer producers, procurement leads at German automotive tier-one suppliers, distribution channel partners in North American industrial supply, and technical R&D directors at precision coating equipment manufacturers. Secondary validation drew from ECHA SCIP database filings, SEC 10-K disclosures from diversified materials conglomerates, customs and trade data on chlorosilane precursor flows, and aerospace qualified supplier program documentation. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates across electrical insulation, automotive, and sealant application categories.
Comparable-period anchoring linked projection assumptions to historical specification cycle patterns in aerospace wire harnessing and automotive electrification transitions. The analytical framework modeled demand across product type, application function, end-user procurement sophistication, and distribution channel structure throughout the forecast period. CAGRs derived from segment-level growth drivers weighted by OEM specification lock-in intensity and recertification cost barriers. Key inputs included REACH Phase-Out compliance timelines, utility infrastructure rehabilitation project pipelines, and offshore wind installation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to silicone feedstock energy cost volatility, fluoropolymer substitution advances in high-frequency applications, and regulatory expansion of ECHA material disclosure requirements. Forecasts reflect documented assumptions on specification cycle durations and certification burden trajectories. A small set of triggers—REACH enforcement acceleration, Chinese chlorosilane capacity constraints, and aerospace automation adoption rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Twist Tube Market
Tapes
Pipe Marking Tape Market
Tapes
High Bond Tape Market
Tapes
Strapping Supplies Market
Tapes
Adhesive Transfer Tape Market
Tapes
Reflective Tape Market
Tapes
UV Cured Acrylic Foam Tapes Market
Tapes
Paper Masking Tapes Market
Tapes
Flocking Tape Market
Tapes
Spacer Tapes Market
Tapes
Release Tape Market
Tapes
Automotive Tapes Market
Tapes
Global UV-Cured Acrylic Adhesive Tapes Market
Tapes
Carbon Tapes Market
Tapes
Pouch Tapes Market
Tapes
Global Pressure Sensitive Tapes Market