
 Glue Tape Market | 2026-2036
Glue Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Glue Tape Market Analytics
China's expanded acrylic adhesive production capacity is narrowing the cost gap with solvent-based alternatives across Asia-Pacific industrial corridors. 3M Company leverages its patent portfolio in high-temperature bonding films to sustain premium positioning in electrical assembly. Avery Dennison Corporation anchors North American supply through integrated film-coating operations in Ohio and California. Nitto Denko Corporation specializes in ultra-thin carrier technologies for electronics miniaturization, occupying a defensible niche in semiconductor packaging.
Glue tape comprises pressure-sensitive adhesive films laminated onto flexible backings such as polypropylene, cellulose acetate, or washi paper, engineered for temporary or permanent bonding without liquid activation. Double-sided variants command the highest value per meter due to precision alignment requirements in automotive trim and display assembly. Clear tapes dominate volume throughput in retail packaging channels where optical transparency preserves branded graphics. Industrial applications generate the strongest margin pools, as manufacturing buyers prioritize tensile strength and temperature resistance over unit cost.
EPA regulations in the United States restrict volatile organic compound emissions from tape coating operations, pushing manufacturers toward water-based and hot-melt adhesive platforms. REACH compliance in Europe mandates disclosure of Substances of Very High Concern in adhesive formulations, reshaping supplier qualification protocols for brands exporting into EU member states. China's MEE enforces dual carbon targets that penalize coal-derived solvent recovery systems in Shandong and Jiangsu production zones. Stakeholders must weigh regulatory compliance investments against regional cost advantages when siting new coating capacity.
Market Dynamics
Water-based adhesive formulations are displacing solvent platforms as regulatory enforcement tightens across major manufacturing zones, compressing legacy coating margins while rewarding capital-intensive retooling investments.
Growth Catalysts
- China's dual carbon enforcement:MEE penalties on coal-derived solvent recovery in Shandong and Jiangsu are accelerating water-based acrylic conversions among domestic tape coaters.
- E-commerce fulfillment expansion:Automated packaging lines in North American and European distribution centers are standardizing pressure-sensitive tape specifications for throughput consistency.
- Semiconductor packaging miniaturization:Ultra-thin carrier demand from chip assembly operations in Taiwan and South Korea is pulling specialty film lamination capacity.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene backing resin and acrylic monomer prices fluctuate with crude oil indices, squeezing converter margins on fixed-price contracts.
- Coating capacity concentration:Tape adhesive production clusters in China's coastal provinces create geographic supply risk during regional environmental compliance shutdowns.
- Hot-melt performance ceiling:Temperature resistance limitations below 80°C exclude hot-melt platforms from automotive under-hood and electronics soldering applications.
Strategic Opportunities
- India industrial corridor buildout:PLI scheme incentives for electronics manufacturing are creating first-mover advantage for tape suppliers qualifying under BIS adhesive standards.
- Biodegradable backing films:Cellulose and polylactic acid substrates aligned with EU Green Deal circular economy mandates open premium positioning in European consumer packaging.
- Direct-to-factory digital procurement:B2B platform integration with automotive and appliance OEMs is compressing distributor layers and capturing margin.
Industry Challenges
- REACH SVHC disclosure complexity:European chemical substance tracking requirements extend qualification timelines for new adhesive formulations by 12-18 months.
- Legacy coating line retrofit costs:Water-based and UV-curable platform conversion demands capital outlays that strain mid-tier converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glue Tape Market |
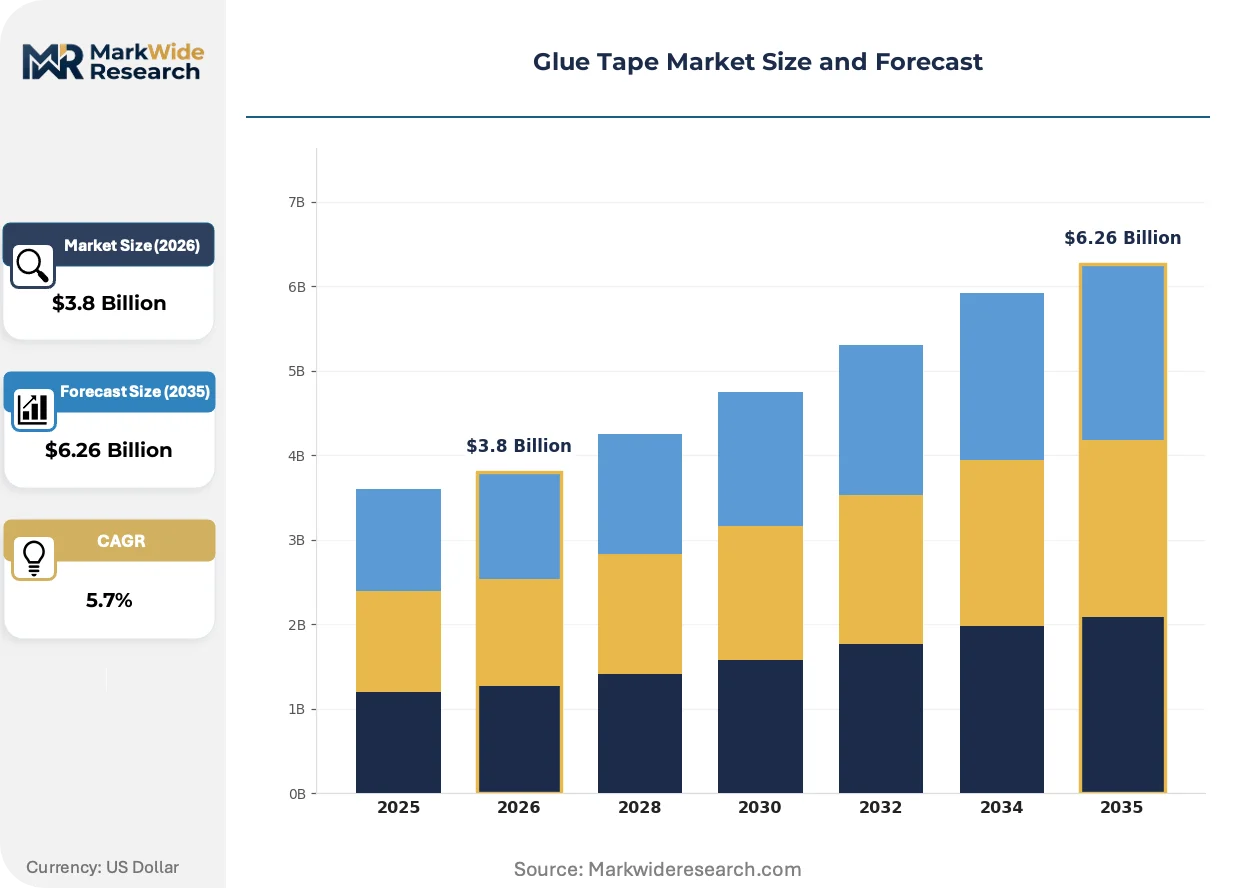
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-Sided, Clear, Washi, Kraft Application: Crafting, Packaging, Industrial, Electrical End User: Retail, Education, Manufacturing, Hobbyists Distribution Channel: Online, Supermarket, Stationery Store, Wholesale |
| Companies Covered | 3M Company, Avery Dennison Corporation, Nitto Denko Corporation, tesa SE, Intertape Polymer Group, Berry Global Inc., Lintec Corporation, Lohmann GmbH & Co. KG, Shurtape Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glue Tape Market Evolving Landscape
Smart manufacturing integration and regulatory chemistry restrictions are converging to reshape how adhesive films are specified, produced, and procured across industrial value chains.
RFID-embedded tape technologies are digitizing inventory tracking and authentication workflows. Pharmaceutical and high-value electronics manufacturers in Germany and Switzerland are piloting chip-integrated carrier films for supply chain visibility. This convergence of adhesion and data infrastructure is digitizing what has historically been a commodity procurement category.
REACH authorization requirements for phthalate plasticizers and certain acrylic monomers are forcing formulation redesigns across European supply chains. Tape coaters serving automotive and medical device exporters must now maintain dual stock-keeping units: REACH-compliant grades for EU-bound shipments and legacy formulations for less regulated markets. The regulatory burden falls heaviest on small-batch specialty converters lacking in-house toxicology resources.
Consolidated buying desks at major e-commerce platforms are compressing supplier counts and standardizing performance specifications. Amazon, Alibaba, and regional fulfillment operators now issue unified tape tenders covering billions of meters annually, displacing fragmented purchasing across individual warehouses. This concentration is most visible in North American and European logistics corridors where packaging standardization directly feeds automated sortation throughput metrics.
Glue Tape Market Segmentation
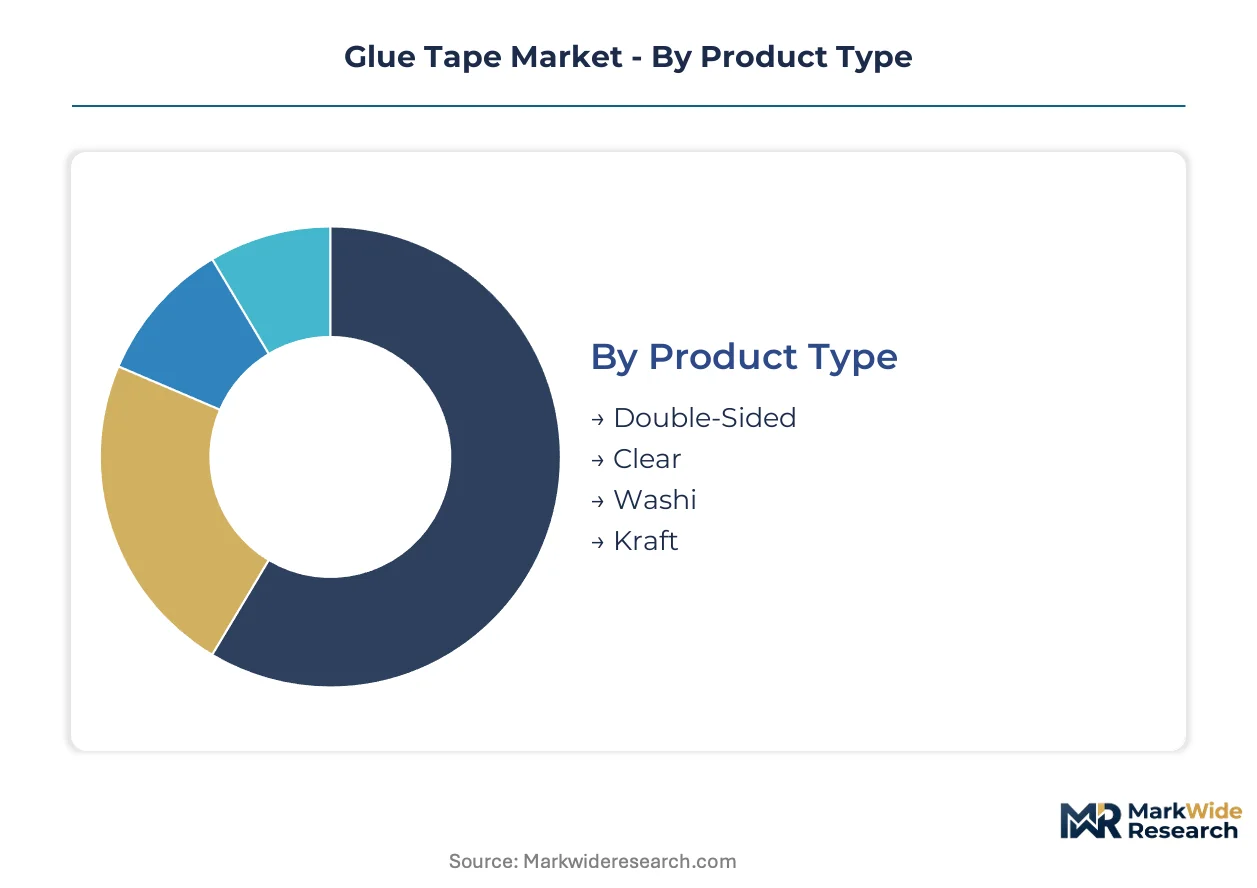
Segmentation in the glue tape market reveals how adhesive performance requirements diverge sharply across end-use contexts, from temperature-resistant industrial bonding to aesthetic crafting applications. Understanding these splits allows suppliers to align coating investments with margin pools rather than chasing undifferentiated volume.
Product Type:
Mature commodity formats dominate unit throughput while emerging specialty constructions capture expanding value share in precision assembly.
- Double-Sided:Pressure-sensitive adhesive layers on both faces of polypropylene or polyester carriers enable invisible bonding in automotive trim and display assembly. German industrial manufacturing corridors generate concentrated demand as OEMs specify these tapes for interior panel attachment where mechanical fasteners would compromise surface aesthetics.
- Clear:Optical-grade acrylic adhesives laminated onto biaxially oriented polypropylene film preserve branded graphics in retail packaging. E-commerce fulfillment centers in the United States and Europe standardize clear tape specifications to maintain barcode scanability through automated sortation systems.
- Washi:Traditional Japanese paper backing with low-tack repositionable adhesive serves decorative and masking applications in craft and stationery channels.
- Kraft:Paper-based backing with hot-melt or water-based adhesive provides economical sealing for corrugated shipping boxes in logistics operations.
Clear tape handles the majority of throughput; double-sided constructions are climbing the fastest as automotive and electronics assembly specifications tighten.
Application:
Cost tier stratification separates high-specification industrial grades from commodity packaging and consumer formats.
- Industrial:High-tensile, temperature-resistant formulations bonded to reinforced backings meet assembly line requirements for permanent structural attachment. Taiwan and South Korea semiconductor packaging operations pull ultra-thin carrier technologies for chip miniaturization workflows.
- Packaging:Standard acrylic or hot-melt adhesives on polypropylene film secure corrugated containers across automated fulfillment lines. China's expanding e-commerce logistics infrastructure drives volume procurement through consolidated buying desks.
- Crafting:Decorative washi and repositionable tapes prioritize color range and clean removal over bond strength in hobbyist and educational markets.
- Electrical:PVC or acetate film backings with solvent-resistant adhesive formulations insulate and bundle wiring in appliance and automotive harness assembly.
Packaging commands absolute volume; industrial applications are expanding most quickly on value per meter.
End User:
Customer type determines procurement modality, with institutional buyers driving standardization and fragmented hobbyist demand supporting premium niche positioning.
- Manufacturing:Automotive, electronics, and appliance OEMs issue direct specifications for tape performance characteristics including shear strength and thermal cycling resistance. REACH SVHC disclosure requirements from ECHA extend qualification timelines for European-bound shipments.
- Retail:Supermarket and big-box chains stock consumer-grade clear and washi tapes for household and small-business consumption.
- Education:School districts and institutional purchasers procure bulk quantities of general-purpose tapes for classroom and administrative use.
- Hobbyists:Individual crafters and DIY enthusiasts purchase premium decorative formats through specialty channels and online marketplaces.
Manufacturing absorbs the highest-value tonnage; hobbyist segments are gaining share fastest in premium pricing tiers.
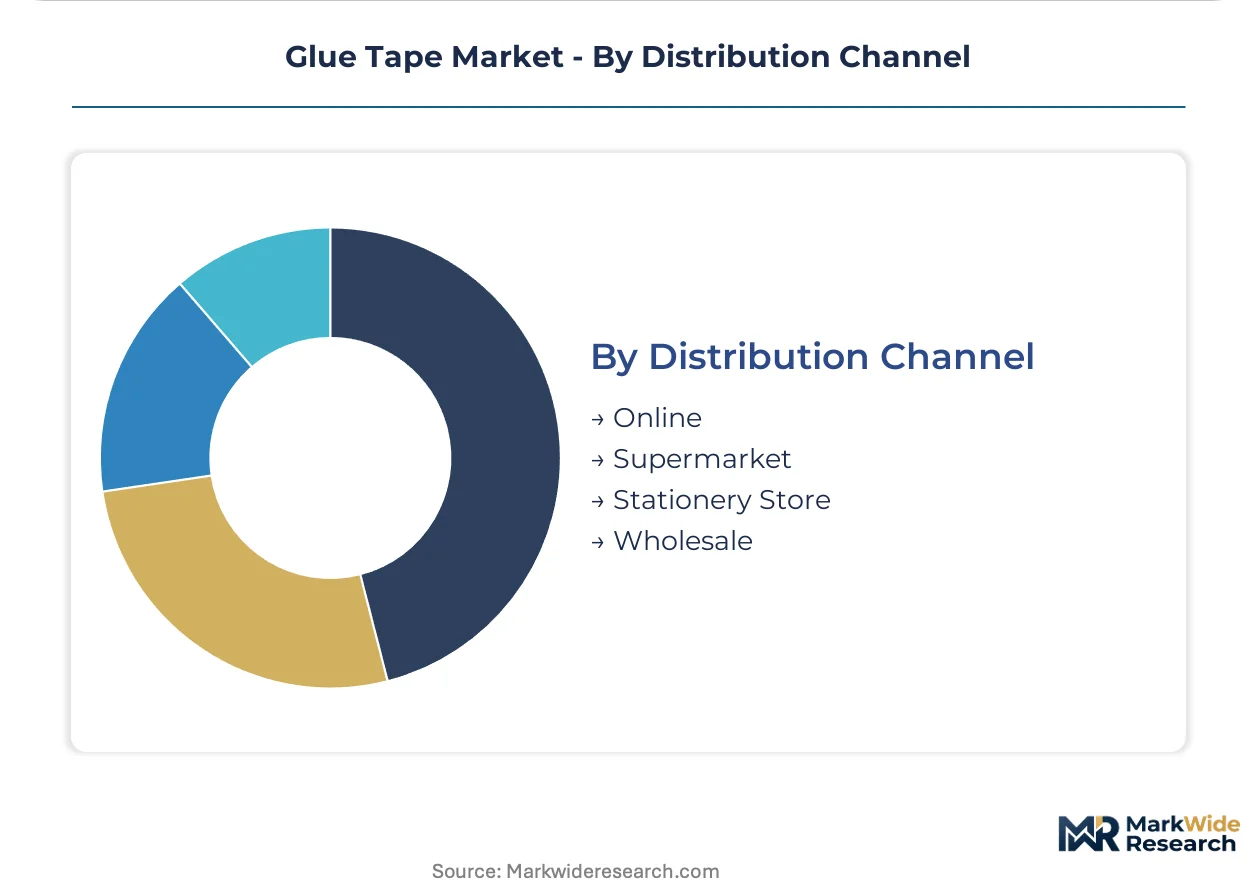
Distribution Channel:
Volume concentration favors wholesale and direct procurement while online penetration reshapes access for fragmented end users.
- Wholesale:Industrial distributors and packaging suppliers move palletized quantities to manufacturing and logistics operators under annual contract frameworks.
- Online:B2B platforms and e-commerce marketplaces compress distributor layers for mid-size manufacturing buyers and enable direct-to-factory procurement integration.
- Supermarket:Mass retail channels serve household consumers and micro-businesses with limited SKU breadth in standard widths and lengths.
- Stationery Store:Specialty retailers stock decorative washi and crafting formats targeting hobbyist and educational purchasers.
Wholesale channels handle the majority of industrial throughput; online distribution is expanding most quickly in mid-market manufacturing procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE enforcement of dual carbon targets in China is restructuring adhesive coating capacity across Asia-Pacific industrial corridors. Regional tape demand splits between precision assembly specifications in East Asian electronics clusters and logistics-driven packaging procurement in North American and European distribution networks.
China
Shandong and Jiangsu province coating operations face MEE penalties on coal-derived solvent recovery systems, accelerating water-based acrylic conversions among domestic tape manufacturers. GB standards compliance now gates market access for adhesive formulations used in export-bound electronics packaging. Yangtze River Delta tape coaters are retooling lines to serve semiconductor assembly demand from Shanghai and Suzhou wafer fabrication facilities.
Germany
Industrial manufacturing corridors along the Rhine and in Bavaria generate concentrated demand for double-sided automotive trim bonding tapes. REACH SVHC disclosure requirements from ECHA extend qualification timelines for adhesive formulations bound for EU automotive OEMs. Stuttgart and Munich metropolitan areas anchor precision tape specification for electric vehicle battery module assembly.
United States
EPA restrictions on volatile organic compound emissions from tape coating operations push manufacturers toward water-based and hot-melt adhesive platforms. Automated e-commerce fulfillment centers in Ohio, Pennsylvania, and Texas standardize pressure-sensitive tape specifications for automated sortation throughput. Midwest industrial distributors consolidate procurement under annual contract frameworks serving appliance and automotive assembly plants.
Japan
METI industrial standards govern adhesive performance specifications for electronics and automotive applications in the domestic market. Nitto Denko Corporation and Lintec Corporation anchor domestic ultra-thin carrier technology production for semiconductor packaging miniaturization. Kansai and Chubu regional manufacturing clusters pull specialty film lamination capacity for chip assembly workflows.
South Korea
MFDS and national industrial standards regulate adhesive formulations used in medical device and electronics applications. Busan-Ulsan and Seoul Capital Area semiconductor packaging operations drive demand for ultra-thin carrier films in advanced chip miniaturization. Domestic electronics manufacturers specify high-temperature-resistant bonding tapes for display and memory module assembly.
Glue Tape Market Competitive Landscape
Integrated multinational chemical conglomerates and specialized regional coating specialists split the market across technology tiers. Market structure consolidates around patent-protected premium formulations while fragmenting in commodity packaging grades. Three archetypes dominate: diversified materials science conglomerates with adhesive film divisions, precision coating specialists serving electronics miniaturization, and regional converters focused on logistics packaging volume. Competitive dynamics center on coating line retooling for regulatory compliance and direct procurement platform integration with automotive and appliance OEMs.
Among diversified materials science conglomerates, 3M Company and Avery Dennison Corporation exemplify the patent-anchored premium tier with integrated film-coating operations. Nitto Denko Corporation occupies a defensible position in ultra-thin carrier technologies for semiconductor packaging applications. These three entities represent distinct strategic postures: diversified technology licensing, integrated North American supply chain control, and precision miniaturization specialization respectively.
| Leading Market Players |
|---|
| 3M Company |
| Avery Dennison Corporation |
| Nitto Denko Corporation |
| tesa SE |
| Intertape Polymer Group |
| Berry Global Inc. |
| Lintec Corporation |
| Lohmann GmbH & Co. KG |
| Shurtape Technologies |
| Others |
Value Network & Pricing Analysis
Coastal Chinese coating clusters in Shandong and Jiangsu province concentrate polypropylene backing resin and acrylic monomer supply, anchoring margin pools in precision double-sided tape grades where temperature resistance commands premium positioning over commodity packaging formats.
Pricing Analysis
Asia-Pacific industrial corridors price water-based acrylic formulations at a discount to solvent-based alternatives, while German automotive OEM specifications sustain premium tiers for REACH-compliant grades. Three-tier pricing structure across premium, standard, and economy levels separates semiconductor-grade ultra-thin carriers from logistics packaging volumes. Cost compression in commodity clear tape intensifies as e-commerce buying desks consolidate procurement under billion-meter annual tenders. Small-batch specialty converters exhibit lowest price sensitivity due to qualification barriers, while fulfillment operators drive hardest bargain on standardized specifications.
Supply Chain Analysis
Export-control restrictions on advanced coating equipment and semiconductor-grade carrier substrates limit technology transfer to emerging tape manufacturers. Supply concentrates in China, Japan, and Germany for precision lamination equipment and formulated adhesive resins. Raw material flows draw from Saudi Arabian petrochemical feedstocks for polypropylene, South Korean acrylic monomer production, and Japanese polyester film substrates. Single-source vulnerability concentrates in ultra-thin carrier technologies below 25 micrometers. Distribution runs through integrated industrial distributors in North America and direct mill relationships in East Asian electronics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based formulation conversion cycles and RFID-embedded authentication technologies indicate early-cycle expansion in specialty adhesive film penetration, with regulatory chemistry shifts creating first-mover advantages for qualified suppliers.
For Market Incumbents: Build regulatory compliance moats through REACH SVHC disclosure infrastructure and MEE-aligned water-based coating capacity. Secure automotive OEM direct procurement integration before distributor consolidation accelerates. Defend against Asian specialty coaters by anchoring North American supply through captive Ohio and California film-coating operations. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-scheme electronics manufacturing corridor where BIS adhesive standard qualification creates qualification barriers for established players. Target biodegradable cellulose and polylactic acid backing films for EU Green Deal circular economy mandates. Pursue direct-to-factory digital procurement platform integration with mid-tier appliance OEMs to bypass distributor layers. For Investors and Strategic Acquirers: Capital is best deployed toward precision coating specialists with semiconductor packaging miniaturization capabilities and defensible patent positions in high-temperature bonding films. Five-to-ten year viability hinges on water-based and UV-curable platform conversion completion ahead of solvent-based phase-outs. Watch for MEE enforcement intensity in Shandong and Jiangsu as inflection signal for regional cost structure disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Coating Line Conversion | MEE dual carbon penalties in Shandong and Jiangsu accelerate capital retooling cycles among domestic coaters. |
| RFID-Embedded Carrier Development | Pharmaceutical and electronics manufacturers in Germany pilot chip-integrated films for supply chain authentication. |
| Direct-to-Factory Procurement Integration | B2B platform connectivity with automotive OEMs compresses distributor margins and captures volume. |
| Biodegradable Backing Film Scale-Up | Cellulose and polylactic acid substrates align with EU Green Deal circular economy procurement mandates. |
| Semiconductor Packaging Qualification | Taiwan and South Korea chip assembly operations pull ultra-thin carrier capacity for miniaturization workflows. |
Research Methodology
A standing panel of coating line operations managers, automotive OEM procurement directors, electronics assembly engineers, and industrial distribution channel heads provided ongoing calibration against secondary validation from customs trade databases, SEC 10-K filings of listed adhesive film producers, ACC and Cefic chemical industry reports, and EPA emission disclosure records. Bottom-up volume estimates from regional coating capacity utilization triangulated with top-down demand aggregation across end-use segments.
Scenario-bracketing around water-based conversion timelines, petrochemical feedstock volatility bands, and regulatory enforcement intensity variations shaped projections across the analysis window. Segmentation dimensions modeled include product construction type, adhesive chemistry platform, backing substrate material, end-use application tier, and regional production hub cluster. CAGRs derived from elasticity-adjusted demand curves incorporating semiconductor packaging miniaturization rates and e-commerce logistics infrastructure buildout trajectories.
Stress conditions across acrylic monomer price spikes, MEE enforcement intensity gradients, and REACH SVHC list expansion timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on coating line retrofit completion rates and OEM qualification timeline stability. Material shifts in China's dual carbon enforcement stringency or sudden REACH authorization list expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Packaging Tapes Market
Tapes
UV Tapes Market
Tapes
Acoustic Tape Market
Tapes
Tape Banding Machine Market
Tapes
Wire Harness Tape Market
Tapes
Water Activated Tape Dispensers Market
Tapes
Mastic Tapes Market
Tapes
Pressure Sensitive Adhesive Tapes Market
Tapes
Foil Tapes Market
Tapes
Utility Grade Duct Tapes Market
Tapes
Global Printed Tape Market
Tapes
Sterilization Indicator Tape Market
Tapes
Thermal Release Tapes Market
Tapes
Carton Sealing Tape Market
Tapes
Vinyl Electrical Tapes Market
Tapes
Edge Band Tapes Market