
 Antioxidant Beverages Market | 2026-2036
Antioxidant Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Antioxidant Beverages Market Analysis
North American production capacity is fragmenting as multiple brands scale antioxidant beverage manufacturing independently. PepsiCo leverages its bottling infrastructure to sustain national distribution density. The Coca-Cola Company anchors its position through Honest Tea and other wellness-aligned portfolios. Ocean Spray competes on cranberry-polyphenol specialization, while Tohi Ventures differentiates through aronia berry sourcing control.
Antioxidant beverages are non-alcoholic drinks formulated with bioactive compounds—polyphenols, flavonoids, carotenoids, and vitamins C and E—typically extracted via cold-press or gentle pasteurization to preserve oxidative-stress-mitigating activity; they serve commercial purposes in preventive health, athletic recovery, and aging-related wellness positioning. Teas and functional drinks represent the fastest-expanding product type categories, with teas benefiting from established consumption rituals and functional drinks capturing premium shelf space through novel delivery formats. The ingredient source dimension shows fruits dominating volume while herbs command margin premiums in specialty channels.
USDA organic certification, FDA GRAS determinations for novel botanical extracts, and EFSA health claim authorization frameworks collectively determine which antioxidant compounds achieve permissible marketing language and retail access across major jurisdictions. Stakeholders must monitor evolving substantiation thresholds for structure-function claims, as regulatory divergence between FDA notification requirements and EFSA scientific opinion processes creates compliance complexity for multinational portfolios. Companies that pre-validate bioactive efficacy through standardized ORAC or Folin-Ciocalteu methodologies will secure faster market access as claim scrutiny intensifies.
Market Dynamics
Clean-label formulation mandates from EFSA and FDA are forcing antioxidant beverage manufacturers to requalify entire ingredient portfolios, compressing reformulation timelines while opening premium positioning for verified botanical supply chains.
Growth Catalysts
- Athletic Recovery Positioning:Functional drink adoption is accelerating among athlete segments seeking oxidative-stress mitigation post-exercise, creating dedicated shelf space in sports nutrition channels.
- EFSA Health Claim Framework:Scientific opinion processes for polyphenol substantiation are clarifying permissible marketing language, enabling compliant brands to differentiate on verified bioactivity.
- Botanical Sourcing Control:Aronia berry and cranberry polyphenol supply chains in North America are consolidating under captive cultivation models, securing raw material traceability.
Market Restraints
- Cold-Press Equipment Capital Intensity:Gentle pasteurization infrastructure requires specialized stainless-steel processing lines that carry 18-24 month depreciation schedules.
- GRAS Determination Timelines:FDA notification requirements for novel botanical extracts create 12-18 month approval windows that delay product launches.
- Polyphenol Degradation Risk:Oxidative stability limitations in ambient distribution constrain shelf-life claims and geographic reach for non-refrigerated formats.
Strategic Opportunities
- German Health Store Networks:Exceptional penetration of botanical-infused products through specialized retail creates template for Austria and Switzerland expansion.
- ORAC Standardization:Pre-validation through standardized antioxidant capacity methodologies is compressing regulatory review timelines for early adopters.
- Tea Ritual Format Innovation:Established consumption rituals in East Asian markets enable premium functional positioning through novel delivery formats.
Industry Challenges
- Bioanalytical Talent Scarcity:Folin-Ciocalteu and ORAC methodology expertise resides in limited contract research organizations, creating bottlenecks for claim substantiation.
- Dual Jurisdiction Compliance:Divergent FDA notification and EFSA scientific opinion processes force parallel regulatory strategies that multiply documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antioxidant Beverages Market |
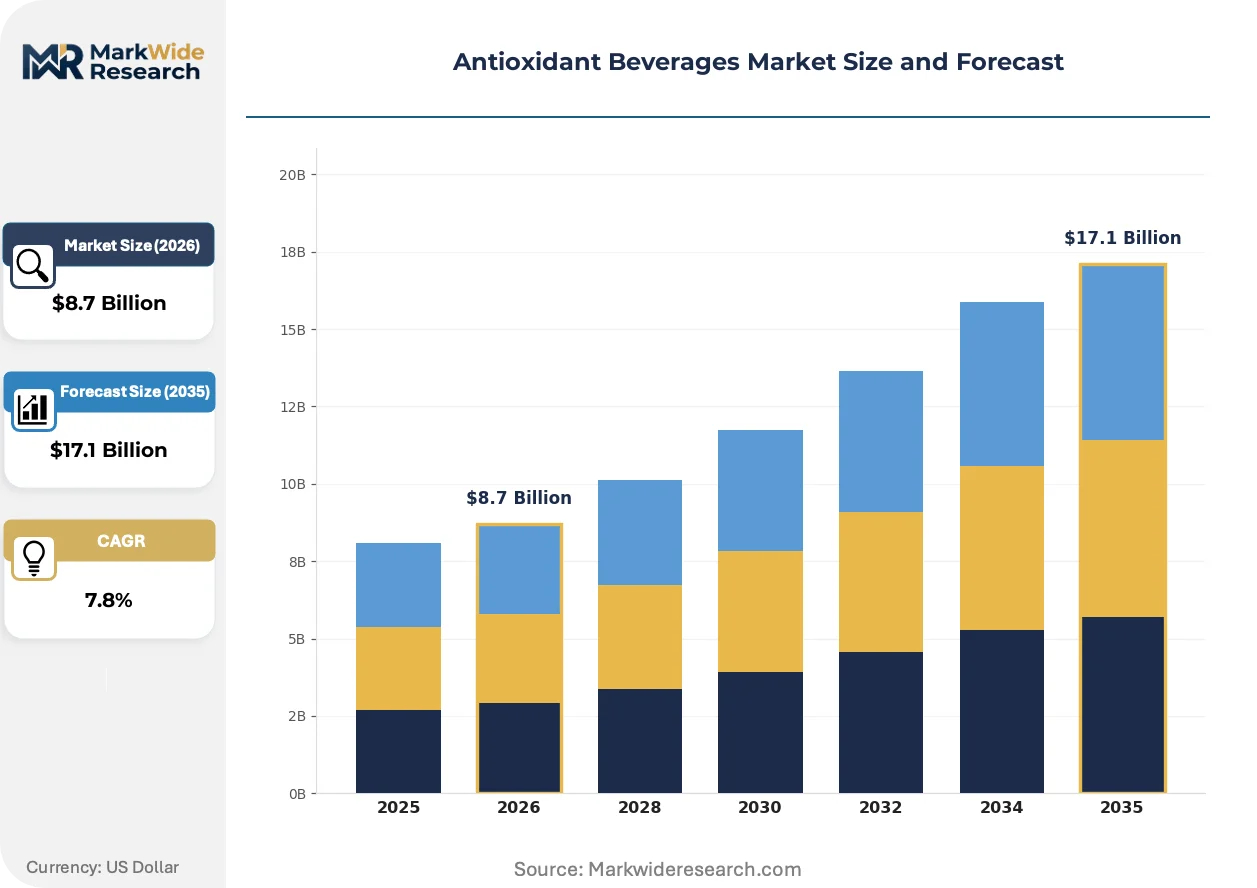
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Juices, Teas, Smoothies, Functional Drinks Ingredient Source: Fruits, Vegetables, Herbs, Spices Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops End User: Health Conscious Consumers, Athletes, Seniors, Families |
| Companies Covered | Hain Celestial Group, Naked Juice, PepsiCo, Ocean Spray, POM Wonderful, The Coca-Cola Company, Unilever, Tohi Ventures, Keurig Dr Pepper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antioxidant Beverages Market Emerging Trajectories
Antioxidant beverage production is digitizing at multiple points in the value chain, from precision agriculture monitoring of polyphenol content to blockchain-enabled provenance verification that satisfies clean-label audit requirements.
Blockchain-enabled supply chain verification is digitizing provenance documentation for botanical ingredients. German health store buyers and North American natural channel distributors are adopting these tools at accelerating rates. The technology is digitizing compliance workflows that previously required manual batch record review, compressing audit timelines from weeks to hours.
EFSA's evolving substantiation thresholds for structure-function claims are tightening marketing language requirements for polyphenol beverages. Manufacturers must now submit standardized bioactivity data before authorized health claims receive approval. Specialty tea and functional drink segments in Germany and France are responding by front-loading clinical validation investments.
Direct-to-subscription models are displacing traditional distributor relationships in premium antioxidant beverage segments. Sports nutrition channels and aging-wellness verticals are bypassing conventional retail slotting fees through recurring delivery platforms. This pattern is most visible in North American urban markets where subscription penetration exceeds conventional health store growth rates.
Antioxidant Beverages Market Segmentation
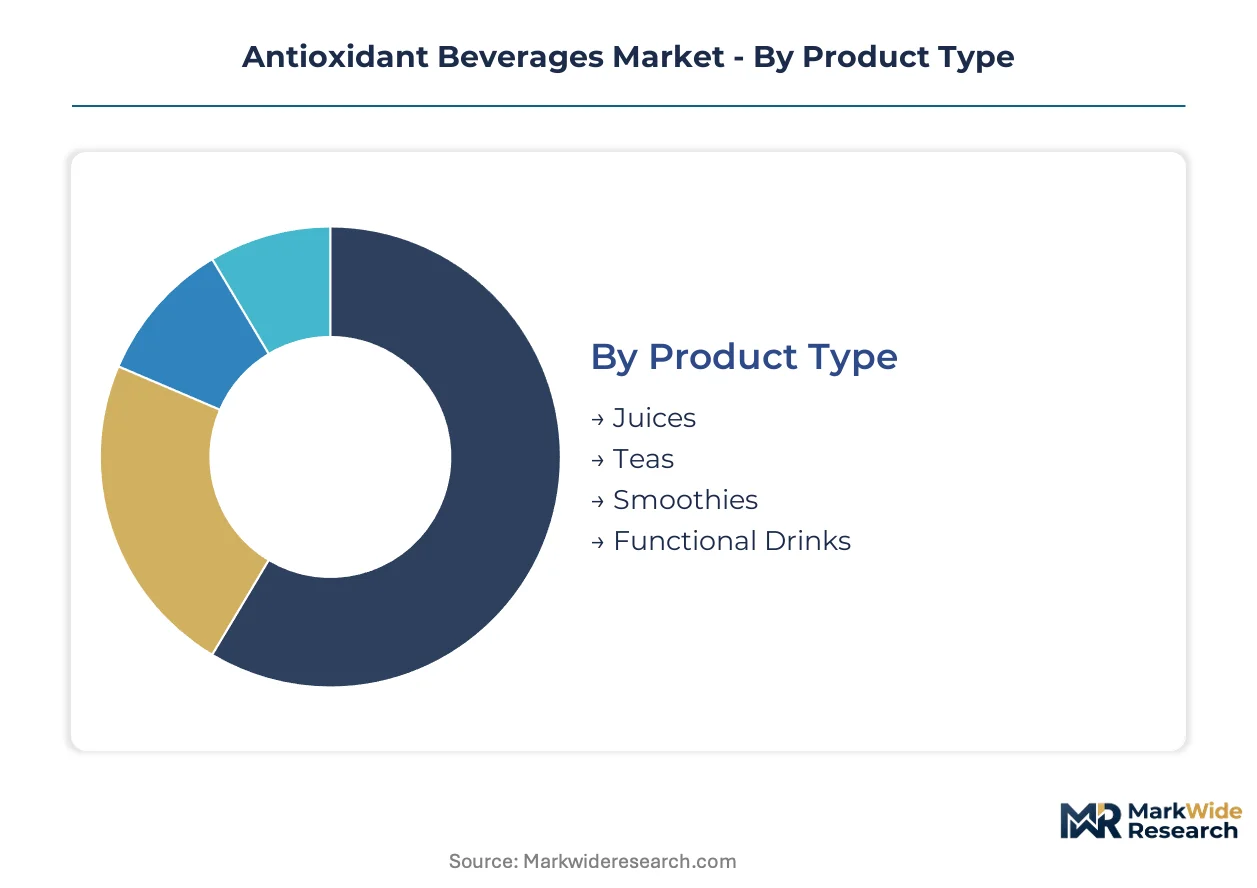
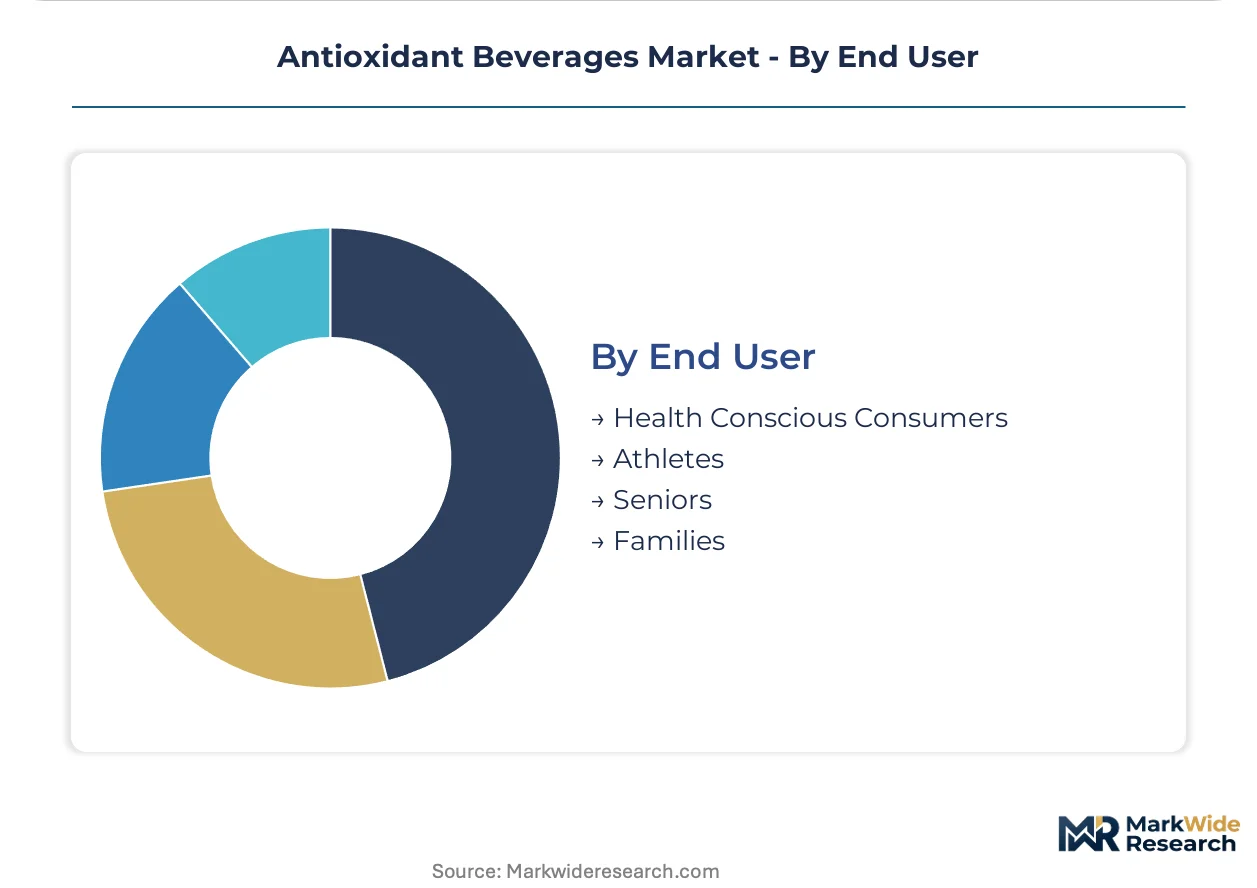
Antioxidant beverage manufacturers must align formulation, sourcing, and channel strategies with distinct consumer motivations. Each segment demands tailored bioactive profiles, packaging formats, and retail positioning to capture willingness-to-pay premiums.
Product Type:
After-sales engagement intensity varies sharply across formats, with subscription replenishment and loyalty programs driving lifetime value most aggressively in functional drinks and smoothies.
- Juices:Cold-pressed fruit and vegetable extracts retain polyphenol activity through minimal thermal processing. Demand clusters in German health store networks where clean-label verification commands shelf space premiums.
- Teas:Established consumption rituals in East Asian markets enable functional positioning through novel delivery formats. Green tea catechins and herbal infusions leverage existing preparation behaviors to lower trial barriers.
- Smoothies:Blended formats combining multiple antioxidant sources target meal-replacement occasions. Athletes seeking post-exercise recovery represent the primary volume concentration.
- Functional Drinks:Novel delivery formats including shots and enhanced waters capture premium positioning. Sports nutrition channels dedicate expanding shelf space to oxidative-stress mitigation claims.
Juices hold the largest share; momentum sits with functional drinks.
Ingredient Source:
Margin structure stratifies sharply by sourcing complexity, with herbs and spices commanding specialty channel premiums while fruits anchor volume scale.
- Fruits:Cranberry, aronia berry, and pomegranate polyphenols dominate commercial formulations. North American captive cultivation models are consolidating supply chain traceability under single-source control.
- Vegetables:Beetroot and carrot carotenoids serve aging-wellness positioning with lower per-unit bioactive concentration. Ambient distribution constraints limit geographic reach for non-refrigerated formats.
- Herbs:Standardized ORAC validation compresses regulatory review timelines for EFSA health claim submissions. Specialty tea segments in France and Germany front-load clinical validation investments.
- Spices:Turmeric curcuminoids and gingerol extracts require GRAS notification for novel concentration levels. FDA approval windows create 12-18 month launch delays.
Fruits anchor volume leadership; herbs are climbing the fastest on margin expansion.
Distribution Channel:
Channel selection determines compliance burden intensity, with health stores and specialty shops demanding blockchain-enabled provenance documentation that supermarkets currently waive.
- Online Retail:Direct-to-subscription models bypass conventional slotting fees in North American urban markets. Recurring delivery platforms displace traditional distributor relationships.
- Supermarkets:Mass-market penetration requires refrigerated supply chain investment that constrains regional expansion. Clean-label mandates from EFSA and FDA are forcing ingredient portfolio requalification.
- Health Stores:German distribution networks achieved exceptional penetration for botanical-infused products. Blockchain verification tools compress audit timelines from weeks to hours.
- Specialty Shops:Sports nutrition and aging-wellness verticals prioritize bioanalytical substantiation over price competition. Folin-Ciocalteu methodology expertise resides in limited contract research organizations.
Supermarkets hold the largest share; momentum sits with online retail.
End User:
Customer lifetime value potential diverges by segment, with athletes and seniors showing highest subscription retention and cross-sell acceptance.
- Health Conscious Consumers:Broad demographic seeking preventive wellness through daily consumption habits. Clean-label formulation standards reshape ingredient sourcing requirements across all channels.
- Athletes:Functional drink adoption accelerates among segments seeking oxidative-stress mitigation post-exercise. Dedicated shelf space in sports nutrition channels creates premium positioning opportunities.
- Seniors:Aging-related wellness positioning targets cognitive and cardiovascular health claims. EFSA substantiation thresholds require standardized bioactivity data before authorized health claims receive approval.
- Families:Volume-driven segment prioritizing palatability and convenience over bioactive concentration. USDA organic certification determines permissible marketing language in mass retail.
Health conscious consumers hold the largest share; athletes are gaining share fastest on recovery positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German consumers favor botanical-infused teas through specialized health store networks, while US buyers gravitate toward functional drinks in sports nutrition channels. This consumption-mix differential shapes formulation priorities and distribution investments across major markets.
Germany
Health store penetration for botanical beverages exceeds other European markets, with specialized retailers demanding blockchain-enabled provenance documentation. EFSA health claim authorization frameworks determine which polyphenol formulations achieve permissible marketing language. Bavaria and Baden-Württemberg host concentrated processing facilities serving domestic and Austrian export markets.
United States
Athletic recovery positioning drives functional drink adoption through direct-to-subscription platforms and sports nutrition channels. FDA GRAS determinations for novel botanical extracts create 12-18 month approval windows that delay product launches. California and the Pacific Northwest anchor cold-press processing infrastructure with captive aronia berry cultivation.
France
Specialty tea segments front-load clinical validation investments to meet tightening EFSA substantiation thresholds for structure-function claims. ANSM and CNIL oversight intersects with food safety and data protection requirements for digital distribution platforms. The Île-de-France region concentrates premium formulation R&D alongside Paris-based natural channel headquarters.
Japan
Established green tea consumption rituals enable functional positioning through novel delivery formats with lower trial barriers. METI standards and PMDA guidance shape import requirements for bioactive compound concentrates. The Kanto region around Tokyo anchors both traditional tea processing and emerging functional beverage innovation clusters.
United Kingdom
Clean-label mandates from post-Brexit regulatory alignment discussions reshape ingredient sourcing requirements for antioxidant beverage portfolios. The Food Standards Agency maintains parallel review processes with EFSA scientific opinion frameworks. London and the Southeast concentrate brand headquarters and subscription-platform operations serving urban health-conscious demographics.
Antioxidant Beverages Market Vendor Landscape
Capability concentration sits with specialized botanical extractors and cold-press processors; scale advantage sits with multinational beverage conglomerates leveraging existing bottling infrastructure. The market exhibits tiered structure with captive supply chain operators, premium functional drink specialists, and mass-market wellness portfolio holders. Three archetypes dominate: polyphenol sourcing controllers, clean-label certification leaders, and direct-to-consumer platform builders. Competitive moves center on backward integration into raw material cultivation and strategic partnerships with contract research organizations for bioanalytical validation.
Among North American specialists, Tohi Ventures occupies a position within the captive cultivation archetype through aronia berry supply chain control. PepsiCo and The Coca-Cola Company exemplify scale-driven portfolio diversification, with the former leveraging bottling infrastructure and the latter anchoring wellness positioning through tea holdings. These three represent distinct strategic postures rather than direct segment overlap.
| Leading Market Players |
|---|
| Hain Celestial Group |
| Naked Juice |
| PepsiCo |
| Ocean Spray |
| POM Wonderful |
| The Coca-Cola Company |
| Unilever |
| Tohi Ventures |
| Keurig Dr Pepper |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on North American aronia berry cultivation determines both premium-mid-economy pricing differentiation and the geographic clustering of cold-press processing infrastructure. Tariff exposure on imported botanical extracts compresses margins for non-vertically integrated brands while amplifying pricing power for captive supply chain operators.
Pricing Analysis
German health store networks command 15-25% shelf space premiums over US mass-market positioning for identical polyphenol formulations. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade—USDA organic and EFSA health claim authorization separate tiers—and volume scale. Cost compression in the standard tier is intensifying because refrigerated distribution requirements expand geographic reach constraints. Families represent the most price-sensitive segment, while athletes seeking oxidative-stress mitigation show lowest elasticity.
Supply Chain Analysis
Extended payment terms from German health store buyers and supply-chain finance facilities from North American distributors are restructuring working capital requirements for botanical extractors. Raw material sourcing concentrates in the United States, Germany, and Japan—drawing from aronia berry cultivars, green tea catechins, and functional mushroom mycelium respectively. Single-source vulnerability in cold-press equipment manufacturing creates 18-24 month capacity expansion bottlenecks. Distribution runs through direct-to-subscription platforms displacing conventional slotting-fee relationships in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label formulation mandates are fragmenting competitive positions, creating niches for verified botanical supply chains and specialized bioanalytical validation services.
For Market Incumbents: Insulate market position through backward integration into aronia berry captive cultivation and accelerated ORAC pre-validation investments. EFSA substantiation threshold tightening threatens brands lacking standardized bioactivity data. Channel control through health store exclusivity agreements in Germany and Austria provides defensive moats against direct-to-subscription entrants. For New Entrants and Emerging Players: Pursue white-space opportunities in French specialty tea segments and Japanese functional delivery format innovation. Sports nutrition channels in North American urban markets show penetrable gaps where subscription retention exceeds conventional retail growth. Go-to-market execution should anchor on blockchain-enabled provenance verification that compresses audit timelines for clean-label certification. For Investors and Strategic Acquirers: FDA GRAS determination backlogs reshape the acquisition landscape toward targets with existing novel botanical extract approvals. Long-term viability centers on contract research organization partnerships securing Folin-Ciocalteu methodology expertise. The signal to monitor is EFSA scientific opinion publication velocity for polyphenol health claims.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Botanical Cultivation | Captive aronia berry supply chains in the Pacific Northwest secure raw material traceability against price volatility. |
| ORAC Standardization Investment | Pre-validation through standardized antioxidant capacity methodologies compresses EFSA health claim review timelines. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models in North American urban markets bypass conventional health store slotting fees. |
| Blockchain Provenance Verification | German health store buyers adopt digitized compliance workflows that reduce audit timelines from weeks to hours. |
| Sports Nutrition Channel Expansion | Dedicated shelf space for oxidative-stress mitigation claims captures athlete segment willingness-to-pay premiums. |
Methodological Framework
Desk research of EFSA scientific opinion databases, FDA GRAS notification filings, and USDA organic certification records preceded structured interviews with antioxidant beverage brand managers, cold-press processing facility operators, German health store category buyers, and contract research organization bioanalytical directors. Secondary validation drew from customs trade data for botanical extract imports, Nielsen retail audit information, and SEC filings from multinational beverage conglomerates. Bottom-up volume modeling triangulated against top-down market sizing across ingredient source and distribution channel dimensions.
Assumptions held EFSA and FDA regulatory frameworks stable across the analysis window while varying clean-label adoption rates and cold-press capacity expansion timelines. Segmentation modeling incorporated product type, ingredient source, distribution channel, and end-user motivation dimensions. CAGRs derived from regression analysis of historical volume trajectories and elasticity-adjusted price projections. Industry-specific inputs included polyphenol degradation curves under ambient distribution and subscription retention benchmarks from sports nutrition verticals.
Sensitivities concentrate around regulatory approval velocity for novel botanical extracts and cold-press equipment lead time fluctuations. Forecasts reflect documented assumptions regarding EFSA health claim authorization timelines and German health store network expansion patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Prebiotic Fiber Market
Functional Food and Beverage
Health and Wellness Foods Market
Functional Food and Beverage
Oat Beta-Glucan Market
Functional Food and Beverage
GCC Functional Food & Beverage Market
Functional Food and Beverage
Vegan Brain Food Market
Functional Food and Beverage
Keto Diet Market
Functional Food and Beverage
Functional Flavor Market
Functional Food and Beverage
Europe Medical Foods Market
Functional Food and Beverage
Global CBD Beverages Market
Functional Food and Beverage
Low Fat Product Market
Functional Food and Beverage
Functional Coffee Market
Functional Food and Beverage
Flavored and Functional Water Market
Functional Food and Beverage
Yeast Beta Glucan Market
Functional Food and Beverage
RTD Protein Beverages Market
Functional Food and Beverage
Low-Fat and Low Cholesterol Diet Market
Functional Food and Beverage
Low Fat Smoothies Market