
 Vegan Brain Food Market | 2026-2036
Vegan Brain Food Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Brain Food Market Analysis
Registered dietitian specialization in plant-based cognitive nutrition is reorganizing how manufacturers formulate and certify products. Garden of Life leverages its USDA Organic supply chain to sustain premium positioning in retail channels. NOW Health Group, Inc. anchors the practitioner and professional segments through practitioner-exclusive distribution. Sunwarrior competes in the sports-adjacent vegan protein space with algae-derived omega formulations.
Vegan brain food encompasses plant-derived nutrients formulated to support neurotransmitter function, cerebral blood flow, and synaptic plasticity, typically standardized for DHA from algal oil, phosphatidylserine from sunflower lecithin, or anthocyanins from blueberry extract. Powder formulations dominate unit volume due to scalability in smoothie and functional beverage applications, while capsule formats command higher per-unit margins among traveling professionals. The superfoods category within product type segments leads absolute dollar contribution, though organic ingredient sourcing creates the steepest price premiums across all formulation channels.
The FDA oversees structure-function claims and New Dietary Ingredient notifications, while USDA Organic and Non-GMO Project verification shape shelf access in mainstream retail. EFSA novel food authorizations in Europe restrict certain adaptogenic ingredients until safety dossiers complete review. Stakeholders must monitor evolving substantiation thresholds for cognitive health claims as class-action litigation against supplement brands intensifies.
Market Dynamics
Clean-label certification requirements are compressing formulation flexibility as manufacturers reformulate around EFSA novel food authorizations and USDA Organic supply chain constraints. Algal oil DHA standardization costs are rising while university wellness programs and corporate cognitive performance initiatives expand procurement volumes.
Growth Catalysts
- Corporate cognitive performance initiatives:Silicon Valley tech employers and Northeast academic corridors are institutionalizing plant-based nootropics in employee benefit structures.
- EU Novel Food Regulation:Tightening ingredient transparency standards in Germany and France are accelerating clean-label investment and third-party verification adoption.
- Algae-derived omega technologies:Advances in photobioreactor cultivation are reducing DHA production costs and improving supply security for powder formulations.
Market Restraints
- Organic ingredient sourcing premiums:Sunflower lecithin phosphatidylserine and certified organic blueberry extract carry 40-60% input cost premiums over conventional alternatives.
- EFSA novel food authorization timelines:Adaptogenic ingredient safety dossiers face 18-36 month review windows, freezing product pipeline expansion.
- Single-source algal oil concentration:DHA supply concentrates among three major fermentation facilities, creating geographic concentration risk.
Strategic Opportunities
- Practitioner-exclusive distribution channels:Registered dietitian specialization in plant-based cognitive nutrition opens direct-to-clinician sales models bypassing retail margin compression.
- Capsule format premiumization:Traveling professionals represent underserved demand for portable, high-margin delivery formats beyond powder saturation.
- Non-GMO Project verification:Clean-label certification gaps in mass-market retail create shelf access advantages for early movers.
Industry Challenges
- Structure-function claim substantiation:Class-action litigation against supplement brands is elevating FDA compliance costs and legal reserve requirements.
- Formulation talent scarcity:Registered dietitians with plant-based cognitive nutrition expertise command premium compensation, constraining R&D team scaling.
- New Dietary Ingredient notification timelines:FDA review backlogs extend time-to-market for novel vegan nootropic compounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Brain Food Market |
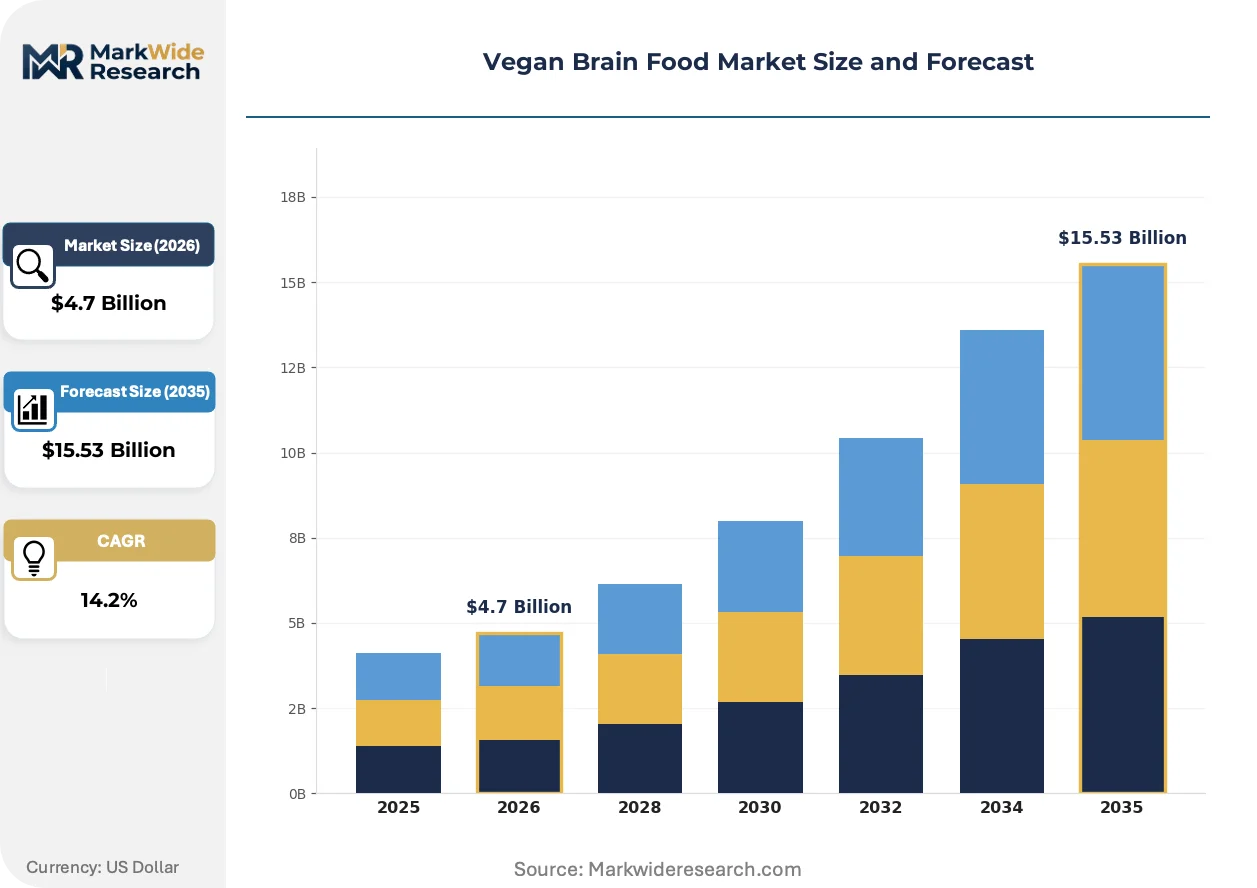
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nuts, Seeds, Superfoods, Oils Ingredient Source: Organic, Non-GMO, Raw, Local Formulation: Powder, Bar, Beverage, Capsule Consumer Type: Health Enthusiasts, Students, Professionals, Athletes |
| Companies Covered | Nestlé S.A., NOW Health Group, Inc., Garden of Life, Sunwarrior, Eden Foods, NutraBlast, Alpro, Beyond Meat, Ora Organic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Brain Food Market Emerging Trajectories
Formulation science is pivoting toward synaptic plasticity targeting as manufacturers differentiate beyond generic omega-3 positioning. Three forces are reshaping competitive architecture.
Precision fermentation for algal oil DHA is decomposing traditional marine sourcing economics. Biotech ingredient suppliers are capturing contract volumes from pharmaceutical-grade fish oil refiners. This technology is decomposing price premiums that historically protected marine-derived cognitive ingredients.
EFSA novel food authorizations are restricting adaptogenic ingredient deployment across European formulations. Manufacturers are shelving ashwagandha and lion's mane SKUs pending safety dossier completion. German and French brands are pivoting toward GRAS-affirmed alternatives to maintain EU market access.
University wellness programs are consolidating vendor relationships around certified organic supply chains. Procurement teams are mandating USDA Organic and Non-GMO Project verification as baseline qualification criteria. Northeast academic corridors are piloting outcome-based purchasing tied to student cognitive performance metrics.
Vegan Brain Food Market Segmentation
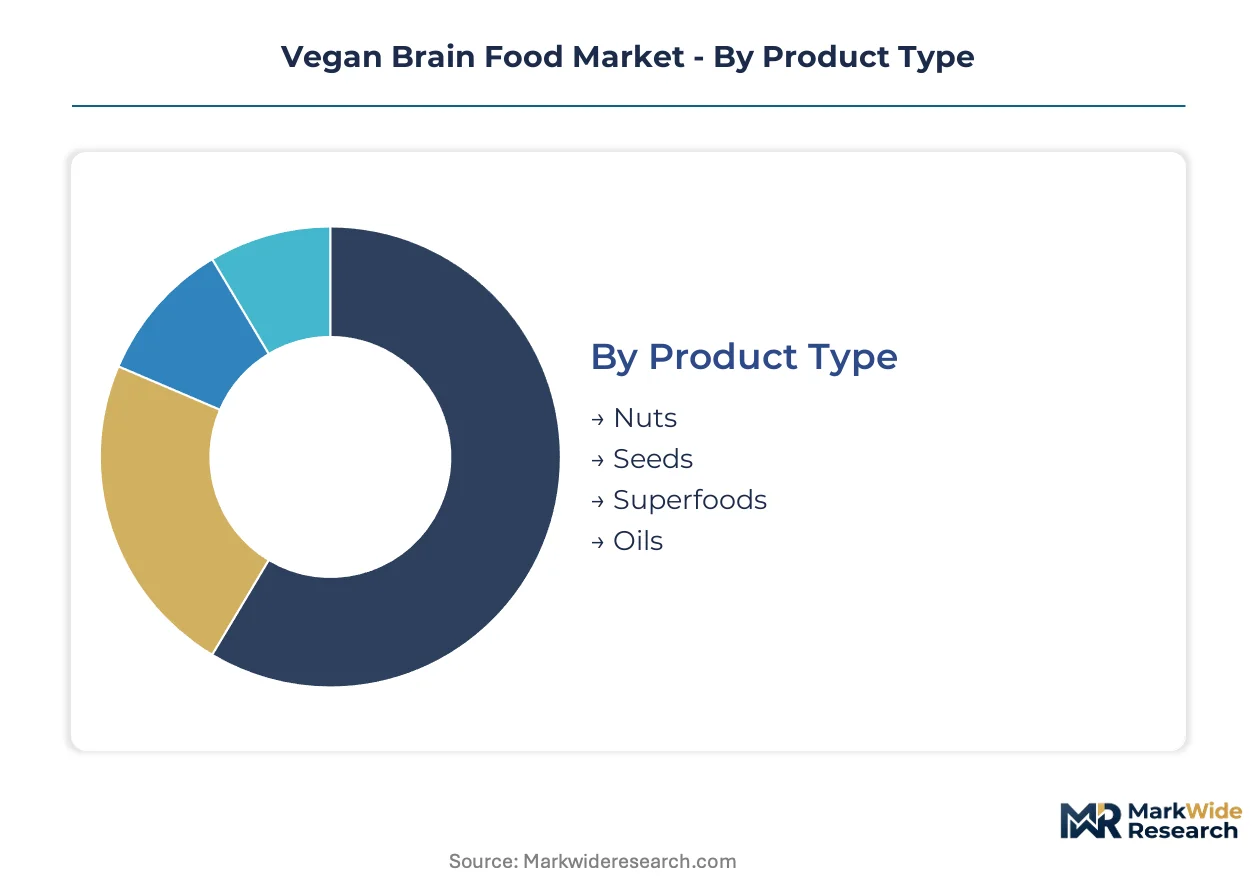
Vegan brain food segmentation reflects divergent supply chain architectures and certification thresholds across product categories. Procurement patterns from university wellness programs and corporate cognitive initiatives favor distinct formulation and sourcing profiles.
Product Type:
Domestic consumption concentrates in shelf-stable formats while export-led demand flows through ingredient-grade concentrates and bulk superfoods.
- Superfoods:Standardized extracts from blueberry, lion's mane, and ashwagandha deliver anthocyanin and hericenone concentrations for synaptic plasticity support. Northeast academic corridors and Silicon Valley tech employers are consolidating vendor relationships around certified organic supply chains for this segment. Superfoods command the steepest price premiums across all formulation channels due to organic ingredient sourcing requirements.
- Oils:Algal oil DHA formulations from photobioreactor cultivation provide phospholipid-bound omega-3 for neurotransmitter function. German and French manufacturers face EFSA novel food authorization constraints that compress formulation flexibility for adaptogenic oil blends. Algal oil standardization costs are rising while supply concentrates among three major fermentation facilities.
- Nuts:Raw and activated varieties targeting cerebral blood flow through arginine and vitamin E content.
- Seeds:Hemp, chia, and flax derivatives supplying ALA precursors for endogenous DHA conversion.
Superfoods commands the established base. The steepest expansion runs through Oils.
Ingredient Source:
Cost tier stratification separates premium-certified inputs from conventional alternatives, with margin compression most severe at the organic tier.
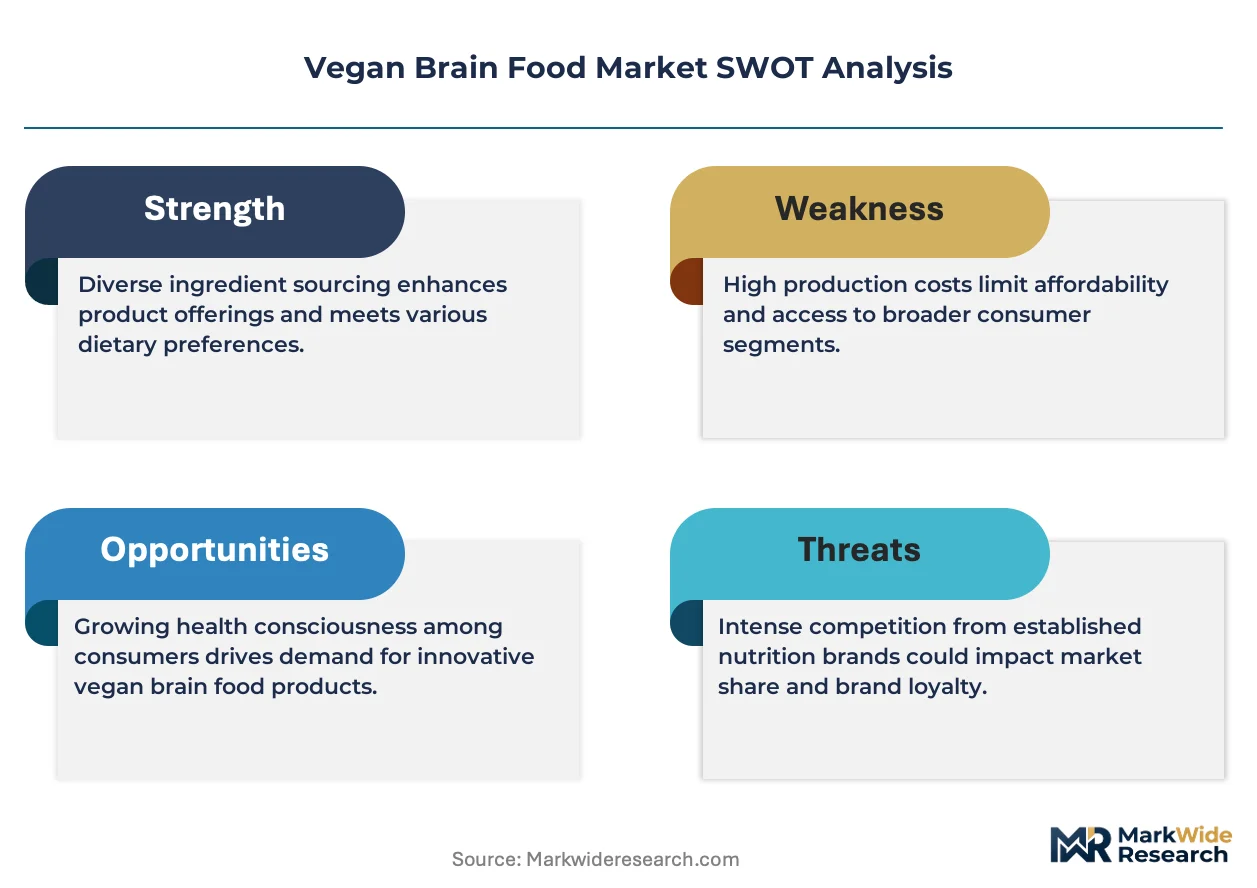
- Organic:USDA Organic and EU Organic certification mandates 40-60% input cost premiums over conventional alternatives for sunflower lecithin phosphatidylserine and certified organic blueberry extract. University wellness programs are mandating organic verification as baseline qualification criteria for procurement contracts.
- Non-GMO:Non-GMO Project verification shapes shelf access in mainstream US retail, creating first-mover advantages for brands completing third-party validation. Clean-label certification gaps in mass-market retail amplify competitive positioning for verified suppliers.
- Raw:Unprocessed ingredient preservation targeting enzyme activity and heat-sensitive compound retention.
- Local:Regionally sourced inputs reducing transport emissions and supporting shorter supply chain traceability.
Organic captures the revenue concentration. Non-GMO is climbing the fastest as certification adoption accelerates.
Formulation:
Volume scale differentiates mass-market powder applications from premium portable formats serving traveling professionals.
- Powder:Scalable formulations dominating unit volume through smoothie and functional beverage applications. NOW Health Group, Inc. anchors practitioner and professional segments through powder distribution in clinical settings.
- Capsule:Portable delivery formats commanding higher per-unit margins among traveling professionals and corporate cognitive performance initiatives. Capsule format premiumization represents an underserved demand pocket beyond powder saturation.
- Bar:Shelf-stable convenience formats targeting on-the-go consumption in academic and corporate environments.
- Beverage:Ready-to-drink functional beverages requiring cold chain infrastructure and shorter shelf life management.
Powder holds the volume base. Capsule is gaining share fastest through professional channel expansion.
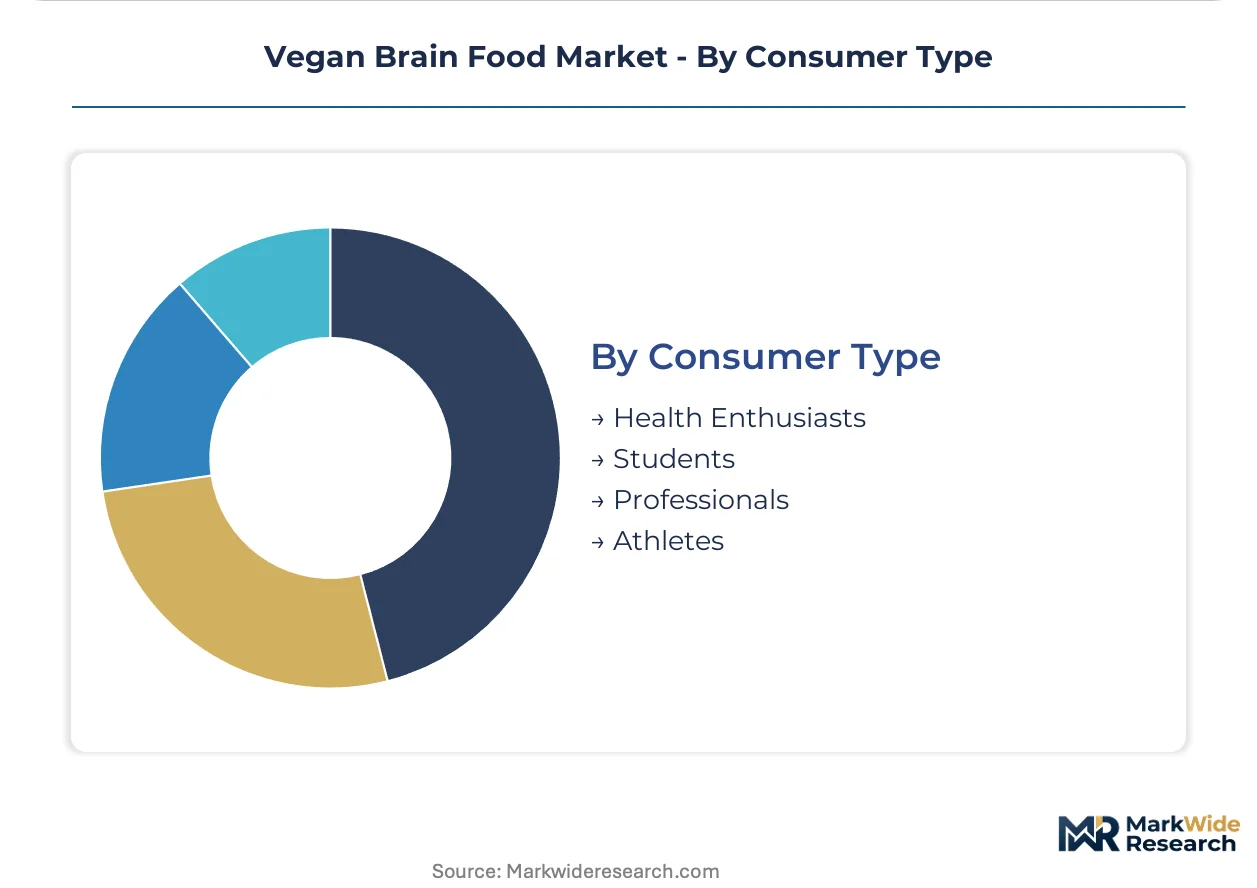
Consumer Type:
Application intensity varies by cognitive performance requirements and institutional procurement integration.
- Professionals:Traveling professionals and Silicon Valley tech employees drive demand for portable, high-margin delivery formats through corporate benefit structures. Corporate cognitive performance initiatives are institutionalizing plant-based nootropics in employee wellness programs.
- Students:University wellness programs in Northeast academic corridors are piloting outcome-based purchasing tied to cognitive performance metrics. Procurement teams mandate USDA Organic and Non-GMO Project verification for student-facing products.
- Health Enthusiasts:Early adopters prioritizing clean-label certification and practitioner-guided supplementation protocols.
- Athletes:Sports-adjacent demand for algae-derived omega formulations competing in vegan protein adjacent spaces.
Professionals anchor the premium tier. Students represent the steepest expansion trajectory through institutional procurement scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers favor powder formats for smoothie integration, while German and French procurement teams prioritize certified organic capsules for corporate benefit structures, creating distinct consumption archetypes across Atlantic markets.
United States
Silicon Valley tech employers and Northeast academic corridors institutionalize plant-based nootropics through employee wellness programs and student-facing procurement. FDA structure-function claim oversight shapes substantiation protocols for domestic manufacturers. California-based photobioreactor facilities supply algal oil DHA to powder formulation specialists serving the functional beverage channel.
Germany
Corporate cognitive performance initiatives in Berlin and Munich drive demand for clean-label certified products through worksite wellness contracts. EFSA novel food authorizations restrict adaptogenic ingredient deployment, compressing formulation flexibility for local brands. Bavarian organic ingredient distributors consolidate supply chains for sunflower lecithin phosphatidylserine serving premium capsule manufacturers.
France
University wellness programs in the Paris-Saclay cluster pilot outcome-based purchasing tied to student cognitive performance metrics. ANSM and EFSA dual oversight elevates compliance costs for novel vegan nootropic compounds entering the French market. Lyon-based superfood extractors scale anthocyanin production from certified organic blueberry supply chains for export-grade formulations.
United Kingdom
Health enthusiast segments in London and the Southeast prioritize practitioner-guided supplementation through registered dietitian channels. MHRA borderline product classifications create uncertainty for adaptogenic oil blends targeting neurotransmitter function claims. Manchester-area contract manufacturers expand capsule capacity for traveling professional segments underserved by powder saturation.
Canada
Health Canada Natural Health Product regulations mandate site licensing for vegan brain food formulations entering the domestic market. Toronto and Vancouver wellness program procurement teams adopt USDA Organic equivalency standards for institutional purchasing. Prairie province hemp and flax processors supply ALA precursor seeds to domestic powder blenders competing in North American export channels.
Vegan Brain Food Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the vegan brain food market. Tier-one players control photobioreactor-derived algal oil supply chains and certified organic ingredient sourcing networks. Three strategic archetypes dominate: biotechnology-anchored ingredient suppliers, practitioner-channel specialists, and retail-certified organic brands. Competitive moves concentrate on backward integration into algae cultivation capacity and exclusive distribution partnerships with registered dietitian networks.
Within the certified organic retail tier, Garden of Life exemplifies supply chain control through USDA Organic verification, while NOW Health Group, Inc. anchors practitioner-exclusive positioning. Sunwarrior occupies a sports-adjacent specialization bridging vegan protein and algae-derived omega formulations. These three entities represent distinct competitive vectors—organic certification depth, professional channel density, and performance nutrition crossover—rather than overlapping market contestation.
| Leading Market Players |
|---|
| Nestlé S.A. |
| NOW Health Group, Inc. |
| Garden of Life |
| Sunwarrior |
| Eden Foods |
| NutraBlast |
| Alpro |
| Beyond Meat |
| Ora Organic |
| Others |
Supply Flow & Price Mechanics
Precision fermentation for algal oil DHA is displacing traditional marine sourcing economics, simultaneously shifting production gravity toward California-based photobioreactor facilities and compressing price premiums that historically protected fish oil refiners. This substitution dynamic redraws cost structures across powder and capsule formulations while concentrating supply leverage among biotechnology-anchored ingredient suppliers.
Pricing Analysis
Long-term offtake contracts dominate procurement between major algal oil fermentation facilities and powder formulation specialists, insulating volume buyers from spot market volatility in sunflower lecithin phosphatidylserine. Three-tier pricing structure across premium certified-organic, standard non-GMO, and economy conventional tiers reflects 40-60% input cost premiums for organic verification. Pricing pressure stems from EFSA novel food authorization delays freezing adaptogenic SKU pipelines. Corporate cognitive performance initiatives show lowest price sensitivity, while student-facing procurement through university wellness programs demands aggressive volume discounts.
Supply Chain Analysis
Inventory lead times for certified organic blueberry extract and phosphatidylserine inputs extend 18-36 months due to EFSA safety dossier review windows and organic certification crop cycles. Supply concentrates in the United States for algal oil DHA fermentation, Germany for sunflower lecithin processing, and France for superfood extraction. Raw material dependencies center on photobioreactor-derived algae, certified organic sunflower crops, and cold-chain anthocyanin preservation. Single-source vulnerability runs through three major fermentation facilities supplying DHA. Distribution runs through practitioner-exclusive channels for capsule premium tiers and mass retail for powder volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photobioreactor cultivation advances are disrupting marine-derived omega economics, creating a high-growth inflection as EFSA novel food authorizations simultaneously constrain European formulation flexibility and reward early movers with GRAS-affirmed alternatives.
For Market Incumbents: Shield USDA Organic positioning by locking multi-year contracts with Bavarian sunflower lecithin distributors before input cost premiums widen further. Defend against biotechnology-anchored ingredient suppliers by backward integration into captive algae cultivation capacity in California. Prioritize registered dietitian network exclusivity to bypass retail margin compression from powder saturation.
For New Entrants and Emerging Players: Non-GMO Project verification fast-track offers shelf access advantages in mass-market retail gaps left by incumbent certification lags. Target traveling professionals through capsule format premiumization as the most penetrable white-space beyond powder-dominated channels. Pursue direct-to-clinician sales models leveraging registered dietitian specialization in plant-based cognitive nutrition.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors biotechnology-anchored ingredient suppliers with photobioreactor capacity over traditional marine oil refiners. Long-term viability over the next decade hinges on controlling upstream algae cultivation rather than downstream formulation. Watch EFSA novel food authorization completion rates as the critical inflection signal for European market access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Photobioreactor Capacity Expansion | Captive algal oil DHA production reduces dependency on three-facility supply concentration. |
| Non-GMO Project Verification Fast-Track | Third-party validation unlocks shelf access in mass-market retail ahead of incumbent certification. |
| Registered Dietitian Network Exclusivity | Practitioner-exclusive distribution bypasses retail margin compression in powder-saturated channels. |
| EFSA Novel Food Authorization Diversification | GRAS-affirmed alternatives maintain EU market access while adaptogenic dossiers pend review. |
| Corporate Wellness Program Direct Contracting | Silicon Valley tech employers and Northeast academic corridors consolidate vendor relationships. |
Methodological Framework
A standing panel of registered dietitians specializing in plant-based cognitive nutrition, procurement managers at university wellness programs, formulation scientists at certified organic manufacturers, and distribution heads at practitioner-exclusive channels provided ongoing calibration across the study. Primary interviews combined with secondary validation from FDA structure-function claim filings, USDA Organic certification databases, EFSA novel food authorization registries, and corporate wellness program RFP documents. Bottom-up volume triangulation against top-down value estimates anchored forecast robustness.
Consistency checks validated volume and value outputs against external benchmarks including customs data for algal oil concentrate trade flows and retail audit data for powder versus capsule format splits. The analytical framework segmented across product type, ingredient source certification tier, formulation format, and consumer archetype throughout the projection horizon. CAGRs derived from regression analysis of procurement scaling at corporate cognitive performance initiatives and university wellness programs, with sensitivity testing around EFSA authorization timeline scenarios.
Underlying assumptions cover photobioreactor yield improvements, organic crop availability, and EFSA review completion rates, with deviation risk concentrated in single-source algal oil concentration and adaptogenic ingredient regulatory status. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Low Fat Protein Market
Functional Food and Beverage
Ready-To-Drink (RTD) Protein Beverages Market
Functional Food and Beverage
Vegan Protein Bars Market
Functional Food and Beverage
Europe Prebiotics Market
Functional Food and Beverage
Functional Water Market
Functional Food and Beverage
Europe Functional Beverages Market
Functional Food and Beverage
Functional Coffee Market
Functional Food and Beverage
Protein Water Market
Functional Food and Beverage
Functional Food and Beverage Market
Functional Food and Beverage
Low Carb and Low Fat Diet Market
Functional Food and Beverage
Beauty Drinks Market
Functional Food and Beverage
Vitamin Functional Water Market
Functional Food and Beverage
North America Functional Beverage Market
Functional Food and Beverage
GCC Functional Food Market
Functional Food and Beverage
Low Fat Product Market
Functional Food and Beverage
Functional Beverage Market