
 Europe Lysosomal Disease Treatment Market | 2026-2036
Europe Lysosomal Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Lysosomal Disease Treatment Market Insights
Gene therapy platform development is tilting the clinical pipeline toward one-time interventions rather than chronic infusion regimens. Sanofi leverages its established rare disease infrastructure to anchor European distribution networks for lysosomal therapies. BioMarin Pharmaceutical Inc specializes in enzyme manufacturing scale-up, while Amicus Therapeutics Inc competes on chaperone platform differentiation.
Lysosomal disease treatment encompasses therapeutic interventions targeting inherited metabolic disorders caused by enzyme deficiencies that disrupt cellular waste processing, requiring intravenous biologic delivery or oral small-molecule modulation to restore substrate clearance. Enzyme Replacement Therapy dominates current revenue pools due to established reimbursement pathways, though Gene Therapy represents the fastest-expanding segment as viral vector manufacturing matures. Substrate Reduction Therapy occupies a narrower niche for patients ineligible for enzyme infusions, while Gaucher Disease and Fabry Disease applications command the largest patient-addressable bases among treated indications.
The EMA orphan drug framework shapes market access through protocol assistance and fee waivers, while the EU AI Act introduces compliance requirements for diagnostic algorithms used in patient identification. REACH regulations govern chemical substrates in small-molecule manufacturing, and the EU Green Deal pressures suppliers to decarbonize biologics production chains. Stakeholders must weigh manufacturing location decisions against evolving ESG disclosure rules under the CSRD.
Market Dynamics
Gene therapy platform maturation is compressing treatment paradigms from chronic infusion regimens toward one-time interventions, forcing incumbent enzyme manufacturers to defend reimbursement positions while viral vector suppliers scramble for capacity.
Growth Catalysts
- EMA Orphan Drug Framework:Fee waivers and protocol assistance accelerate clinical trial design for ultra-rare indications, compressing development timelines for sponsors targeting patient populations below 50,000 across the EU.
- Newborn Screening Expansion:France, Germany, and the Netherlands are widening heel-prick panels to detect Gaucher and Pompe variants at birth, expanding the addressable presymptomatic patient base.
- Substrate Reduction Platforms:Oral small-molecule chaperones are opening treatment pathways for patients with neutralizing antibodies to infused enzymes, addressing a previously excluded cohort.
Market Restraints
- Viral Vector Supply Concentration:Manufacturing capacity for AAV serotypes clusters in Belgium, Massachusetts, and North Carolina, creating single-source dependencies for European gene therapy sponsors.
- Reimbursement Heterogeneity:Germany's G-BA assessment diverges from France's HAS and England's NICE on value thresholds, forcing parallel health technology appraisal submissions.
- Substrate Cost Volatility:Rare sugar precursors for enzyme manufacturing face price swings tied to agricultural commodity markets and fermentation yield variability.
Strategic Opportunities
- Central and Eastern Europe Penetration:Poland, Czech Republic, and Hungary show widening newborn screening coverage with underdeveloped treatment center density, creating first-mover infrastructure opportunities.
- EU Green Deal Alignment:Biologics manufacturers can secure preferential procurement positioning by decarbonizing fermentation and purification operations ahead of CSRD disclosure mandates.
- Companion Diagnostic Integration:Genotyping platforms paired with therapy selection are reshaping prescriber workflows in Fabry and Pompe disease management.
Industry Challenges
- Viral Vector Manufacturing Talent Scarcity:Cell culture specialists with AAV suspension experience command premium compensation, constraining scale-up timelines for gene therapy candidates.
- Multi-Jurisdiction Regulatory Synchronization:Divergent EMA national competent authority requirements for post-authorization safety studies fragment pharmacovigilance operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Lysosomal Disease Treatment Market |
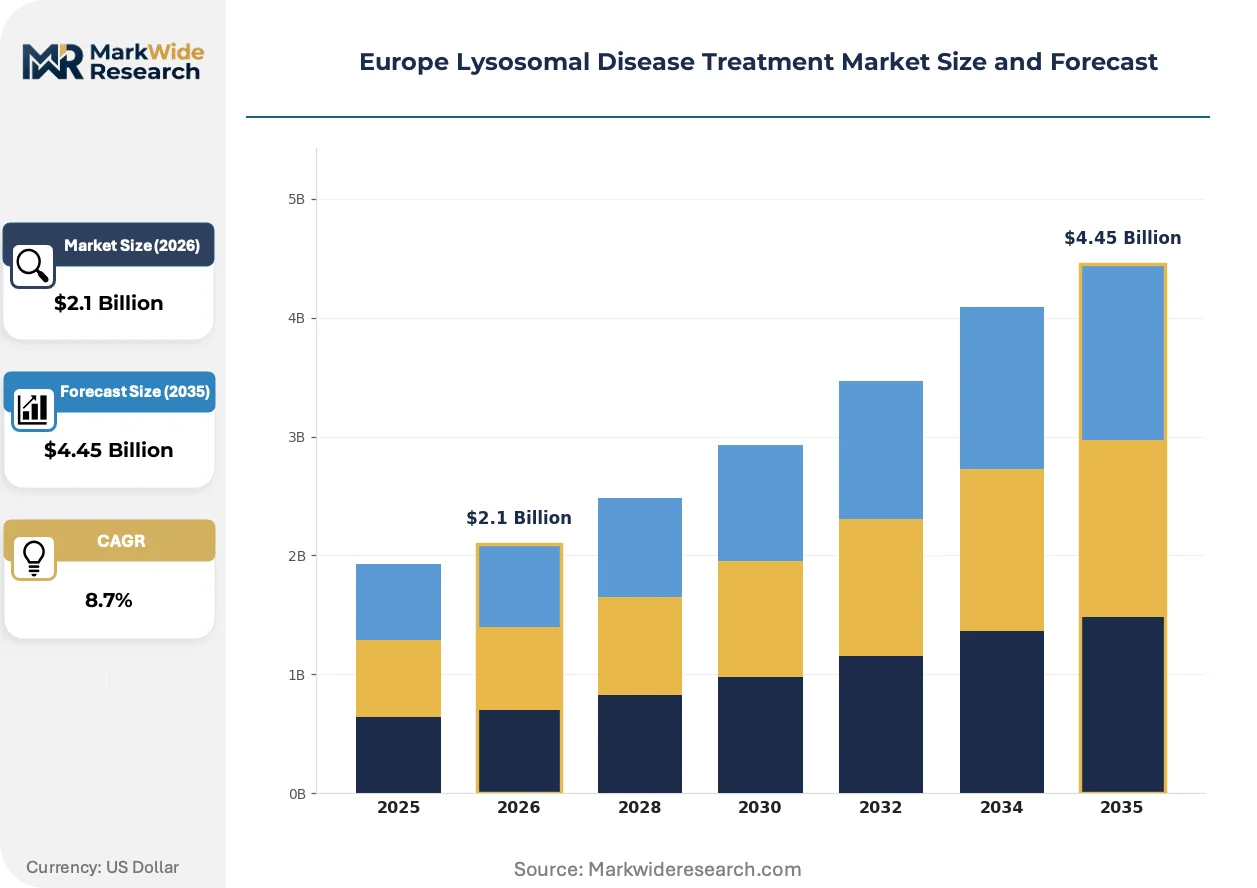
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Replacement Therapy, Substrate Reduction Therapy, Chaperone Therapy, Gene Therapy Application: Gaucher Disease, Fabry Disease, Pompe Disease, Mucopolysaccharidosis Treatment Setting: Hospitals, Specialized Clinics, Home Care, Pharmacies End User: Pediatric Patients, Adult Patients, Healthcare Providers, Research Institutions |
| Companies Covered | Sanofi, Pfizer Inc, Takeda Pharmaceutical Company Limited, BioMarin Pharmaceutical Inc, Amicus Therapeutics Inc, Johnson & Johnson, Actelion Ltd, Protalix Biotherapeutics Inc, Raptor Pharmaceutical Corp, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Lysosomal Disease Treatment Market Trends and Innovations
Digital infrastructure is embedding itself across the lysosomal disease value chain, from patient identification algorithms to manufacturing process control, compressing decision cycles and enabling precision targeting.
Artificial intelligence diagnostic tools are screening retinal and cardiac imaging patterns to flag Fabry and Gaucher patients earlier in disease progression. Tertiary referral centers in Munich, Paris, and London are deploying these platforms to prioritize genetic testing queues. The EU AI Act is digitizing compliance requirements for these algorithms, forcing developers to document training data provenance and performance benchmarks across demographic subgroups.
REACH regulation amendments are tightening disclosure obligations for chemical substrates used in small-molecule chaperone synthesis, particularly iminosugar derivatives. Manufacturers must now submit extended safety data dossiers for import authorization renewals. Substrate reduction therapy suppliers are responding by qualifying alternative fermentation-derived feedstocks to reduce synthetic chemical dependencies.
Patient advocacy organizations are consolidating purchasing influence through centralized registries that track treatment outcomes and device adverse events. These networks in Germany and the United Kingdom are negotiating directly with manufacturers on behalf of dispersed patient cohorts. Regional payer contracts are increasingly contingent on real-world evidence submissions drawn from these curated databases rather than traditional clinical trial endpoints.
Europe Lysosomal Disease Treatment Market Segmentation
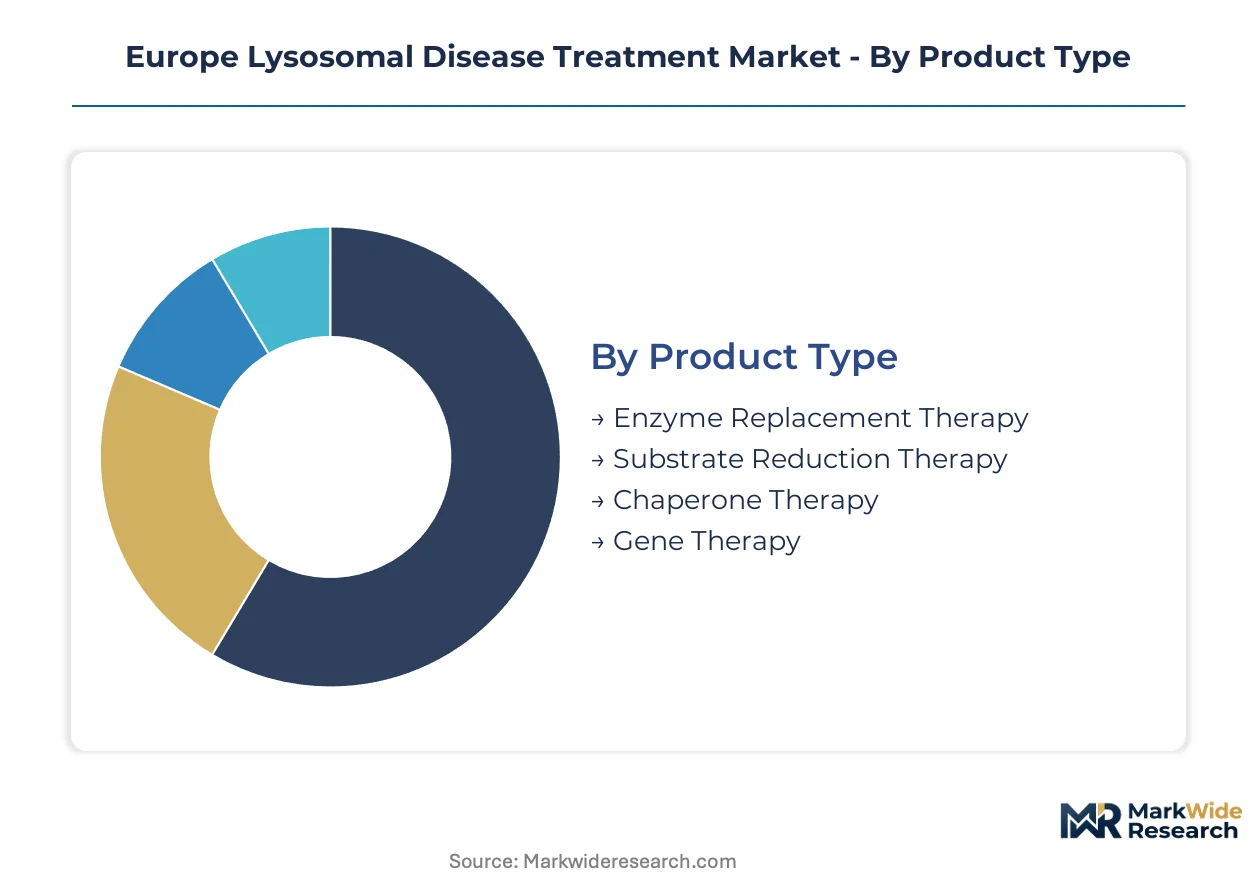
Lysosomal disease treatment markets fragment across therapeutic modality, disease indication, and care delivery setting. Each segmentation axis carries distinct reimbursement logic, patient journey characteristics, and manufacturing requirements that shape commercial strategy.
Product Type:
Cycle times vary dramatically across modalities, with chronic infusion platforms turning over inventory weekly while gene therapy batches require months from viral vector production to patient administration.
- Enzyme Replacement Therapy:Intravenous biologic infusions restore functional enzyme levels in deficient patients. German and French hospital networks concentrate demand for Gaucher and Fabry ERT products, though reimbursement pressure intensifies as gene therapy alternatives advance through EMA review.
- Gene Therapy:One-time viral vector interventions target underlying genetic defects rather than managing symptoms. Belgium's manufacturing clusters and England's early access schemes are accelerating adoption for presymptomatic pediatric cases identified through expanded newborn screening.
- Substrate Reduction Therapy:Oral small-molecule inhibitors limit substrate accumulation in patients with milder phenotypes or enzyme-neutralizing antibodies.
- Chaperone Therapy:Pharmacological chaperones stabilize misfolded enzymes for select genotypes, occupying a narrow niche in Fabry variant management.
Enzyme Replacement Therapy anchors the volume base while Gene Therapy gains share at the steepest rate.
Application:
Cost tiers stratify sharply across indications, with Gaucher and Fabry therapies commanding premium pricing due to larger addressable populations while Pompe and Mucopolysaccharidosis treatments serve narrower ultra-rare cohorts.
- Gaucher Disease:Glucocerebrosidase deficiency produces the most commercially developed indication, with established ERT protocols and emerging gene therapy candidates. French and Dutch newborn screening expansion is shifting treatment initiation earlier in disease progression.
- Fabry Disease:Alpha-galactosidase deficiency affects renal, cardiac, and nervous systems with variable penetrance. English and German specialized centers are deploying AI-assisted cardiac imaging to identify late-onset variants in adult populations.
- Pompe Disease:Acid alpha-glucosidase deficiency requires lifelong ERT or emerging gene therapy, with infantile-onset forms showing the most severe clinical course.
- Mucopolysaccharidosis:Heterogeneous enzyme deficiencies spanning multiple subtypes present formulation and dosing challenges that fragment the commercial landscape.
Gaucher Disease generates the largest revenue pool while Fabry Disease applications expand most quickly through improved diagnostic capture.
Treatment Setting:
Patient risk stratification and therapy complexity determine site-of-care allocation, with high-risk infusions concentrating in tertiary centers while stable patients migrate toward home administration.
- Hospitals:Acute care facilities manage initial enzyme loading doses, adverse event protocols, and multi-organ complications. Munich, Paris, and London university hospitals anchor referral networks for complex cases requiring coordinated specialty input.
- Specialized Clinics:Dedicated metabolic disease centers coordinate longitudinal care and clinical trial access. German and UK networks are consolidating purchasing leverage through outcome-based contracting with manufacturers.
- Home Care:Subcutaneous enzyme formulations and portable infusion pumps enable domiciliary administration for stable patients.
- Pharmacies:Oral substrate reduction therapies and chaperone prescriptions flow through retail and specialty pharmacy channels.
Hospitals capture the highest acuity cases while Specialized Clinics are consolidating influence over therapy selection and patient routing.
End User:
Demographic and professional segments exhibit divergent price sensitivity, with pediatric populations triggering distinct reimbursement pathways and research institutions driving clinical trial enrollment.
- Pediatric Patients:Presymptomatic identification through newborn screening is compressing time-to-treatment and expanding addressable cohorts. French heel-prick panel expansion and German screening pilots are reshaping patient capture dynamics.
- Adult Patients:Late-onset phenotypes in Fabry and Gaucher diseases often present through cardiac or hematologic referral pathways, with diagnostic delays limiting treatment windows.
- Healthcare Providers:Metabolic specialists, cardiologists, and hematologists share prescribing influence depending on presenting symptoms and disease subtype.
- Research Institutions:Academic medical centers in England, Germany, and the Netherlands dominate gene therapy trial enrollment and natural history study execution.
Pediatric Patients represent the strategic priority for pipeline sponsors while Adult Patients constitute the larger treated population base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports enzyme replacement therapies to France, the Netherlands, and Austria through established hospital supply corridors. Belgian viral vector manufacturing clusters feed gene therapy candidates into English and German early-access schemes. Cross-border patient referral networks concentrate demand in Munich, Paris, and London metabolic centers.
Germany
Newborn screening pilots in Bavaria and North Rhine-Westphalia are expanding presymptomatic Gaucher and Pompe detection. The G-BA assessment framework sets reimbursement value thresholds that diverge from French and English standards. Munich and Hamburg university hospitals anchor referral networks for complex multi-organ cases requiring coordinated specialty input.
France
Heel-prick panel expansion now captures Fabry and Gaucher variants at birth, compressing time-to-treatment for pediatric cohorts. ANSM and HAS coordinate on post-authorization safety study requirements for gene therapy candidates. Paris metropolitan treatment centers deploy AI-assisted cardiac imaging to identify late-onset Fabry presentations in adult populations.
United Kingdom
NICE value appraisals create distinct reimbursement logic from continental European frameworks, forcing parallel submission strategies. The MHRA operates under retained EU legislation while developing independent gene therapy guidance. London and Manchester specialized clinics consolidate purchasing leverage through outcome-based contracting with enzyme manufacturers.
Netherlands
Rotterdam and Amsterdam academic medical centers dominate European gene therapy trial enrollment for presymptomatic pediatric cases. The Dutch newborn screening program leads EU member states in Pompe disease detection coverage. Leiden viral vector manufacturing infrastructure supplies AAV serotypes to German and English sponsors.
Belgium
Wallonia and Flanders host concentrated AAV suspension manufacturing capacity that European gene therapy sponsors depend upon for clinical and commercial supply. EMA centralized procedures route through Brussels for orphan drug designation approvals. Ghent and Liège biomanufacturing clusters face talent scarcity pressures as viral vector demand outpaces specialist workforce expansion.
Europe Lysosomal Disease Treatment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across enzyme replacement, gene therapy, and small-molecule modalities. The vendor base concentrates around established rare disease infrastructure holders and emerging viral vector platform developers. Three archetypes dominate: integrated pharmaceutical conglomerates with metabolic disease portfolios, dedicated enzyme manufacturers with fermentation scale-up capabilities, and gene therapy platform specialists with AAV engineering expertise. Incumbents defend reimbursement positions through real-world evidence generation while challengers secure manufacturing partnerships to bypass capacity constraints.
Within the integrated pharmaceutical tier, Sanofi and Takeda Pharmaceutical Company Limited occupy positions anchored by established European distribution networks and hospital formulary relationships. BioMarin Pharmaceutical Inc exemplifies the enzyme manufacturing specialist archetype with fermentation-derived glucocerebrosidase production capabilities. Amicus Therapeutics Inc represents the pharmacological chaperone platform segment, competing on oral small-molecule differentiation for select genotypes ineligible for intravenous enzyme infusion.
| Leading Market Players |
|---|
| Sanofi |
| Pfizer Inc |
| Takeda Pharmaceutical Company Limited |
| BioMarin Pharmaceutical Inc |
| Amicus Therapeutics Inc |
| Johnson & Johnson |
| Actelion Ltd |
| Protalix Biotherapeutics Inc |
| Raptor Pharmaceutical Corp |
| Others |
Pricing and Supply Chain Analysis
Viral vector supply concentration in Belgium and Massachusetts creates single-source dependencies that widen pricing spreads between gene therapy candidates and established enzyme replacement platforms while forcing European sponsors into premium procurement contracts for AAV manufacturing slots.
Pricing Analysis
Next-generation gene therapy platforms command substantial premiums over chronic infusion regimens due to one-time administration economics, while prior-generation enzyme products face compression as viral vector alternatives advance through EMA review. Three-tier pricing structure across premium gene therapy, standard enzyme replacement, and economy substrate reduction levels reflects reimbursement heterogeneity across Germany's G-BA, France's HAS, and England's NICE frameworks. Cost compression in the enzyme tier is intensifying because gene therapy candidates threaten formulary positioning for Gaucher and Fabry indications. Pediatric patient populations identified through newborn screening show lowest price sensitivity due to urgency of presymptomatic intervention, while adult late-onset cohorts trigger payer scrutiny over value thresholds.
Supply Chain Analysis
Tariff exposure between the United States and European Union complicates viral vector import logistics for gene therapy sponsors dependent on trans-Atlantic manufacturing partnerships. AAV suspension production clusters in Belgium, North Carolina, and Massachusetts, with fermentation-derived enzyme manufacturing anchored in Germany and Ireland. Rare sugar precursors for substrate reduction therapy draw from agricultural commodity markets in France and the Netherlands, creating feedstock price volatility. Single-source vulnerability concentrates in Belgian AAV capacity where European sponsors compete for limited manufacturing slots. Distribution runs through hospital pharmacy networks in Munich, Paris, and London for infused products, while oral therapies flow through specialized pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe lysosomal disease treatment market sits in early-cycle expansion as newborn screening protocols across France, Germany, and the Netherlands widen presymptomatic patient capture and compress time-to-treatment initiation.
For Market Incumbents: Pre-empt gene therapy displacement by locking in long-term outcome-based contracts with German and English specialized clinic networks before viral vector alternatives secure reimbursement. Deepen backward integration into viral vector manufacturing through partnerships with Belgian suspension capacity holders to secure supply positions for pipeline candidates. Invest in real-world evidence generation from curated patient registries to defend formulary positioning against one-time intervention economics. For New Entrants and Emerging Players: Build out Central and Eastern European infrastructure in Poland, Czech Republic, and Hungary where newborn screening coverage expands ahead of treatment center density. Target presymptomatic pediatric cohorts as the most penetrable segment given diagnostic protocol expansion and urgency-driven prescribing. Pursue EMA orphan drug designation early to secure fee waivers and protocol assistance that compress development timelines against established competitors. For Investors and Strategic Acquirers: EMA centralized approval pathways for gene therapy candidates reshape the acquisition landscape by validating platform technologies ahead of national reimbursement negotiations. The 5-10 year viability window favors sponsors with manufacturing partnerships already secured rather than those still building viral vector capabilities. Acquisition target archetype: Belgian or Dutch gene therapy platforms with demonstrated AAV scale-up and early-access scheme enrollment in England or Germany. Signal to watch: NICE technology appraisal decisions on gene therapy alternatives as inflection indicator for reimbursement velocity across European markets.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Belgian AAV capacity expansion secures supply positions for EMA-approved gene therapy candidates. |
| Regulatory Approval Pathway | EMA orphan drug designation accelerates clinical trial design through protocol assistance and fee waivers. |
| Long-term Supply Agreement | Fermentation feedstock contracts with Dutch agricultural suppliers reduce substrate cost volatility exposure. |
| Strategic Partnership | AI diagnostic platform alliances with Munich and Paris referral centers prioritize genetic testing queues. |
| Reimbursement Strategy | Outcome-based contracting with German G-BA and English NICE secures formulary positioning ahead of gene therapy competition. |
Research Methodology
The analysis maps enzyme replacement, gene therapy, substrate reduction, and chaperone platforms, each validated through metabolic disease specialists, regulatory affairs leads at EMA-experienced sponsors, hospital formulary directors in Germany and England, and payer access specialists across national health technology appraisal bodies. Primary interviews combined with secondary validation against EMA submission databases, ClinicalTrials.gov enrollment records, national newborn screening protocol documentation, and hospital procurement database extracts. Bottom-up patient cohort sizing triangulated against top-down revenue estimates from disclosed tender awards and formulary placement records.
Assumptions held fixed include current EMA orphan drug framework provisions, existing newborn screening panel compositions, and observed reimbursement value thresholds across G-BA, HAS, and NICE processes. Variables included gene therapy approval timelines, viral vector manufacturing capacity expansion rates, and AI diagnostic algorithm adoption curves across tertiary referral networks. Segmentation dimensions modeled encompass therapeutic modality, disease indication, treatment setting, and patient age cohort. CAGRs derived from patient flow projections tied to screening expansion schedules and therapy transition rates from chronic to one-time administration paradigms. Industry-specific inputs included AAV serotype manufacturing yield assumptions and fermentation titer improvements for enzyme production.
The forecast holds incumbent behavior within observed patterns; aggressive manufacturing partnership moves by mid-cap gene therapy specialists or accelerated NICE value appraisal shifts would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Global Leukapheresis Market
Medical Treatment
Rabies Treatment Market
Medical Treatment
Malaria Treatment Market
Medical Treatment
Monkeypox Treatment Market
Medical Treatment
Birch Allergy Treatment Market
Medical Treatment
Menstrual Cramps Treatment Market
Medical Treatment
Histiocytosis Treatment Market
Medical Treatment
Radiotherapy Induced Oral Mucositis Treatment Market
Medical Treatment
Ventral Hernia Treatment Market
Medical Treatment
Laser Therapy Market
Medical Treatment
Refsum Disease Treatment Market
Medical Treatment
Pompe Disease Treatment Market
Medical Treatment
Global Systemic Lupus Erythematosus Treatment Market
Medical Treatment
Allergy Treatment Market
Medical Treatment
Paresthesia Treatment Market
Medical Treatment
Hereditary Amyloidosis Treatment Market