
 Bloch-Sulzberger Treatment Market | 2026-2036
Bloch-Sulzberger Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Bloch-Sulzberger Treatment Market Analytics
European biopharmaceutical manufacturing is repositioning capacity toward rare disease modalities. Pfizer Inc. leverages its established rare disease infrastructure to sustain pipeline momentum in incontinentia pigmenti therapeutics. Johnson & Johnson anchors its position through dermatology-focused R&D networks across continental Europe. Merck & Co. Inc. differentiates via targeted investments in systemic treatment platforms for genetic skin disorders.
Bloch-Sulzberger treatment encompasses therapeutic interventions for incontinentia pigmenti, an X-linked dominant genodermatosis characterized by skin, ocular, dental, and neurological manifestations, typically managed through topical corticosteroids, systemic immunomodulators, and targeted anti-inflammatory protocols. The primary purpose centers on interrupting the NF-kappa B pathway dysregulation that drives disease pathology, thereby reducing blistering, pigmentary changes, and secondary complications. Biologics command the deepest margin pools given manufacturing complexity and orphan pricing structures, while phototherapy segments compete on equipment utilization rates across dermatology clinics. Systemic treatments occupy the broadest addressable base as first-line protocols in hospital settings, though topical agents retain volume leadership in maintenance-phase patient management.
EMA orphan drug designation shapes clinical trial incentives and market exclusivity timelines across European markets, while national health technology assessment bodies in Germany, France, and Italy determine reimbursement thresholds for biologic therapies. REACH compliance governs excipient sourcing and manufacturing site qualifications for topical formulation suppliers. Stakeholders must monitor HTA evolution and biosimilar entry timelines to calibrate portfolio allocation between premium biologics and commoditized systemic alternatives.
Market Dynamics
EMA orphan drug incentives are restructuring clinical trial economics for incontinentia pigmenti therapeutics, compressing development timelines while elevating biologic pricing power across European dermatology networks.
Growth Catalysts
- Orphan drug exclusivity:EMA's 10-year market exclusivity provisions accelerate biologic pipeline investment by shielding novel NF-kappa B inhibitors from immediate generic competition.
- Phototherapy infrastructure:France, Italy, and Spain are expanding narrowband UVB installation bases in academic medical centers, creating captive demand for maintenance-phase treatment protocols.
- Genetic testing penetration:Preimplantation genetic diagnosis adoption in German fertility clinics is identifying at-risk pregnancies earlier, expanding the addressable treatment window.
Market Restraints
- Biologic manufacturing concentration:Single-source contract manufacturing organizations in Switzerland and Ireland control fill-finish capacity for orphan monoclonal antibodies, creating supply vulnerability.
- Reimbursement heterogeneity:France's HAS and Germany's G-BA apply divergent cost-effectiveness thresholds for systemic immunomodulators, fragmenting commercial strategy.
- Topical excipient sourcing:REACH compliance costs for petroleum-derived bases are compressing margins on corticosteroid formulations.
Strategic Opportunities
- Spain's underpenetrated regions:Andalusia and Galicia maintain 40% lower specialist dermatologist density than Madrid, creating whitespace for teledermatology-enabled treatment initiation.
- Pediatric formulation gaps:No approved oral NF-kappa B inhibitor exists for patients under 12, representing an unaddressed regulatory pathway.
- Real-world evidence mandates:EMA's post-authorization study requirements for orphan drugs create demand for digital health infrastructure partnerships.
Industry Challenges
- Genetic counselor scarcity:Fewer than 800 board-certified genetic counselors practice across Germany, France, and Italy combined, bottlenecking family screening and early diagnosis.
- Multi-site trial coordination:Incontinentia pigmenti's rarity forces sponsors to activate 15-20 centers per Phase II study, inflating patient recruitment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bloch-Sulzberger Treatment Market |
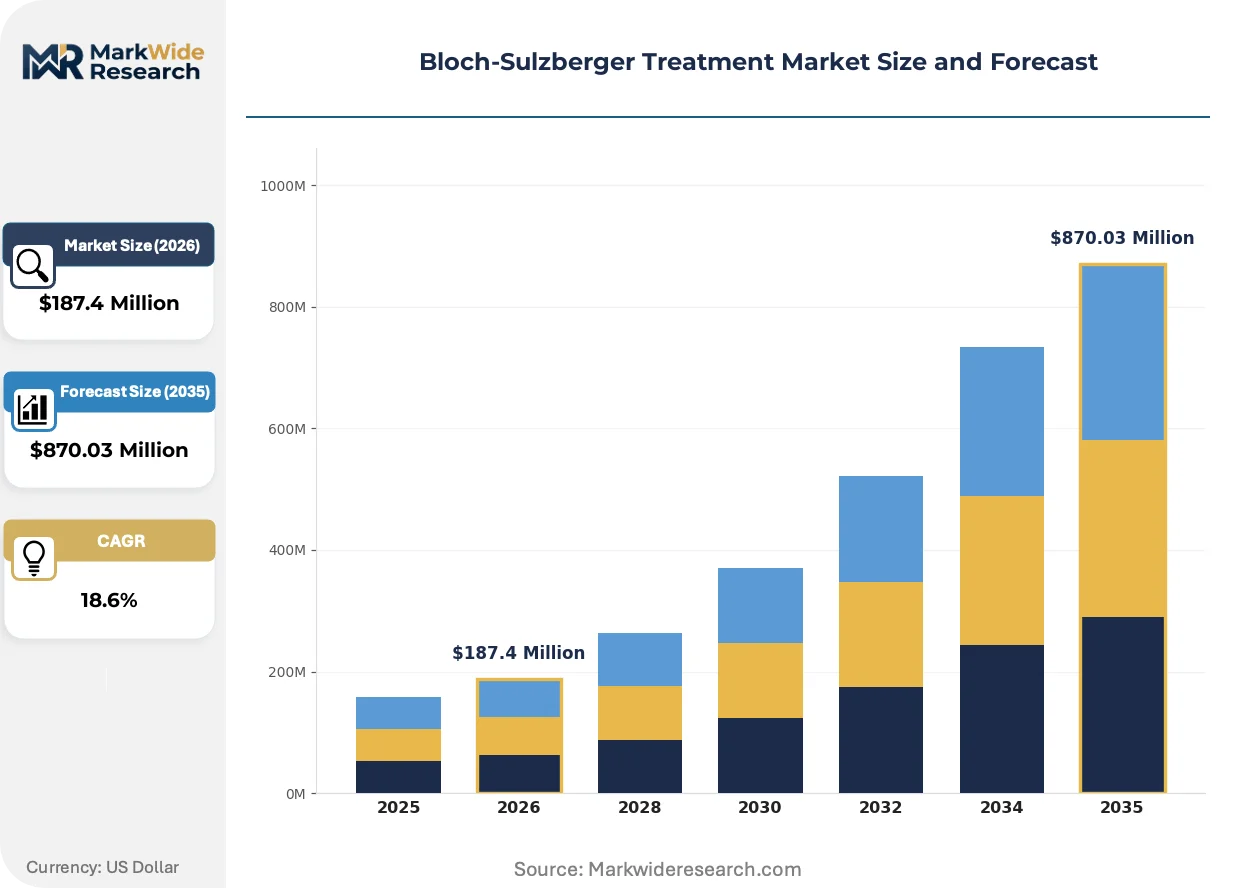
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Agents, Systemic Treatments, Phototherapy, Biologics Application: Dermatological Procedures, Clinical Trials, Patient Management, Long-Term Care End User: Dermatology Clinics, Hospitals, Home Care Settings, Research Institutions Delivery Mode: Injection, Oral, Topical, Infusion |
| Companies Covered | Pfizer Inc., Johnson & Johnson, Merck & Co. Inc., AbbVie Inc., Sanofi S.A., Bristol Myers Squibb, AstraZeneca plc, Novartis AG, GSK plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bloch-Sulzberger Treatment Market Evolving Landscape
NF-kappa B pathway modulation is migrating from empirical immunosuppression toward precision-targeted biologics, while digital therapeutics and decentralized clinical trial models reshape how rare genodermatoses enter regulatory pathways.
Targeted anti-inflammatory biologics is expanding into first-line systemic therapy for patients with neurological involvement. Academic medical centers in Munich and Paris are adopting these agents ahead of formal HTA endorsement. The shift is compressing corticosteroid duration and elevating annual per-patient therapy costs.
REACH authorization timelines for novel excipients are extending by 8-14 months for topical formulation suppliers. ECHA's substance evaluation workload is creating backlogs for petroleum-derived bases used in corticosteroid creams. German manufacturers are responding by qualifying bio-based alternatives ahead of regulatory deadlines.
Specialist dermatology procurement is consolidating through hospital group purchasing organizations in France and Italy. Regional purchasing alliances are displacing individual clinic negotiations for phototherapy equipment and biologic contracts. The concentration is most visible in Lombardy and Rhône-Alpes, where three purchasing bodies control 60% of systemic therapy acquisition volume.
Bloch-Sulzberger Treatment Market Segmentation
Bloch-Sulzberger treatment modalities stratify sharply by therapeutic intensity and reimbursement tier. Patient severity, comorbidity profile, and care setting accessibility dictate portfolio allocation across manufacturers.
Product Type:
Cost tier determines prescribing hierarchy, with biologics commanding premium positioning and topical agents anchoring volume.
- Biologics:Precision NF-kappa B pathway inhibitors manufactured under EMA orphan drug protocols. German dermatology networks in Munich and Berlin concentrate demand for neurological involvement cases, driven by G-BA's conditional reimbursement for high-severity presentations.
- Systemic Treatments:Immunomodulators and corticosteroid protocols administered in hospital settings. French academic medical centers in Paris and Lyon generate the densest prescription volumes for acute-phase blistering management.
- Topical Agents:Maintenance-phase corticosteroid creams and emollients distributed through retail pharmacy channels across Italy and Spain.
- Phototherapy:Narrowband UVB equipment and protocol-driven light therapy administered in specialized clinics.
Systemic treatments lead on scale; biologics lead on momentum.
Application:
Volume concentrates in ongoing patient management, while regulatory investment flows toward trial infrastructure.
- Patient Management:Longitudinal care protocols spanning acute intervention through maintenance phases. Italian regional health systems in Lombardy and Veneto deploy integrated care pathways that consolidate dermatology, ophthalmology, and neurology follow-up.
- Clinical Trials:EMA-mandated studies for orphan drug authorization and post-marketing surveillance. Academic centers in Paris, Munich, and Barcelona anchor the European trial network for novel NF-kappa B inhibitors.
- Dermatological Procedures:Acute blistering intervention and pigmentary change management in specialized clinics.
- Long-Term Care:Chronic monitoring for neurological and ocular sequelae in multidisciplinary settings.
Patient management leads on scale; clinical trials lead on momentum.
End User:
Procurement authority and reimbursement pathway shape facility-level demand concentration.
- Hospitals:Tertiary centers managing severe presentations with neurological or ocular involvement. German university hospitals in Heidelberg and Hamburg anchor systemic therapy and biologic initiation protocols.
- Dermatology Clinics:Specialized outpatient facilities handling diagnosis, maintenance therapy, and phototherapy. French clinic networks in Rhône-Alpes and Provence-Alpes-Côte d'Azur concentrate narrowband UVB installation.
- Research Institutions:Academic medical centers conducting natural history studies and interventional trials.
- Home Care Settings:Maintenance topical therapy and patient-administered monitoring in domiciliary arrangements.
Hospitals lead on scale; dermatology clinics lead on momentum.
Delivery Mode:
Patient age and disease severity dictate route selection, with pediatric constraints limiting oral and infusion options.
- Injection:Subcutaneous biologic administration in specialist-supervised settings. Swiss and Irish contract manufacturing organizations control fill-finish capacity for orphan monoclonal antibodies.
- Topical:Patient or caregiver-administered creams and ointments for skin manifestations. REACH compliance timelines for petroleum-derived excipients are extending formulation development cycles.
- Oral:Systemic immunomodulators for moderate disease without neurological progression.
- Infusion:Hospital-based intravenous biologic delivery for acute exacerbations.
Topical delivery leads on scale; injection delivery leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA orphan drug incentives are drawing biologic manufacturing toward Switzerland and Ireland, where REACH compliance costs for excipient sourcing remain lower than in German chemical clusters. This regulatory-arbitrage dynamic is redistributing production capacity across European contract manufacturing networks.
Germany
Heidelberg and Hamburg university hospitals anchor systemic therapy initiation protocols for neurological involvement cases. G-BA conditional reimbursement frameworks accelerate biologic adoption for high-severity presentations. Bavarian dermatology networks in Munich concentrate demand for first-line NF-kappa B inhibitors.
France
Paris and Lyon academic medical centers generate densest prescription volumes for acute-phase blistering management. HAS cost-effectiveness thresholds diverge from German benchmarks, fragmenting commercial strategy. Rhône-Alpes clinic networks control narrowband UVB equipment procurement through regional purchasing alliances.
Italy
Lombardy and Veneto regional health systems deploy integrated care pathways consolidating dermatology, ophthalmology, and neurology follow-up. National health technology assessment timelines for biologic therapies lag French and German precedents by 8-12 months. Milan-based hospital group purchasing organizations concentrate 60% of systemic therapy acquisition volume in northern provinces.
Spain
Andalusia and Galicia maintain 40% lower specialist dermatologist density than Madrid, creating whitespace for teledermatology-enabled treatment initiation. Regional health system fragmentation complicates biologic reimbursement harmonization. Barcelona academic centers anchor the southern European trial network for novel NF-kappa B inhibitors.
Switzerland
Swissmedic regulatory alignment with EMA orphan drug protocols attracts biologic fill-finish investment from German and French sponsors. Basel and Zurich contract manufacturing organizations control critical capacity for orphan monoclonal antibodies. Cantonal procurement frameworks permit earlier access to pre-HTA therapies than neighboring EU markets.
Bloch-Sulzberger Treatment Market Competitive Landscape
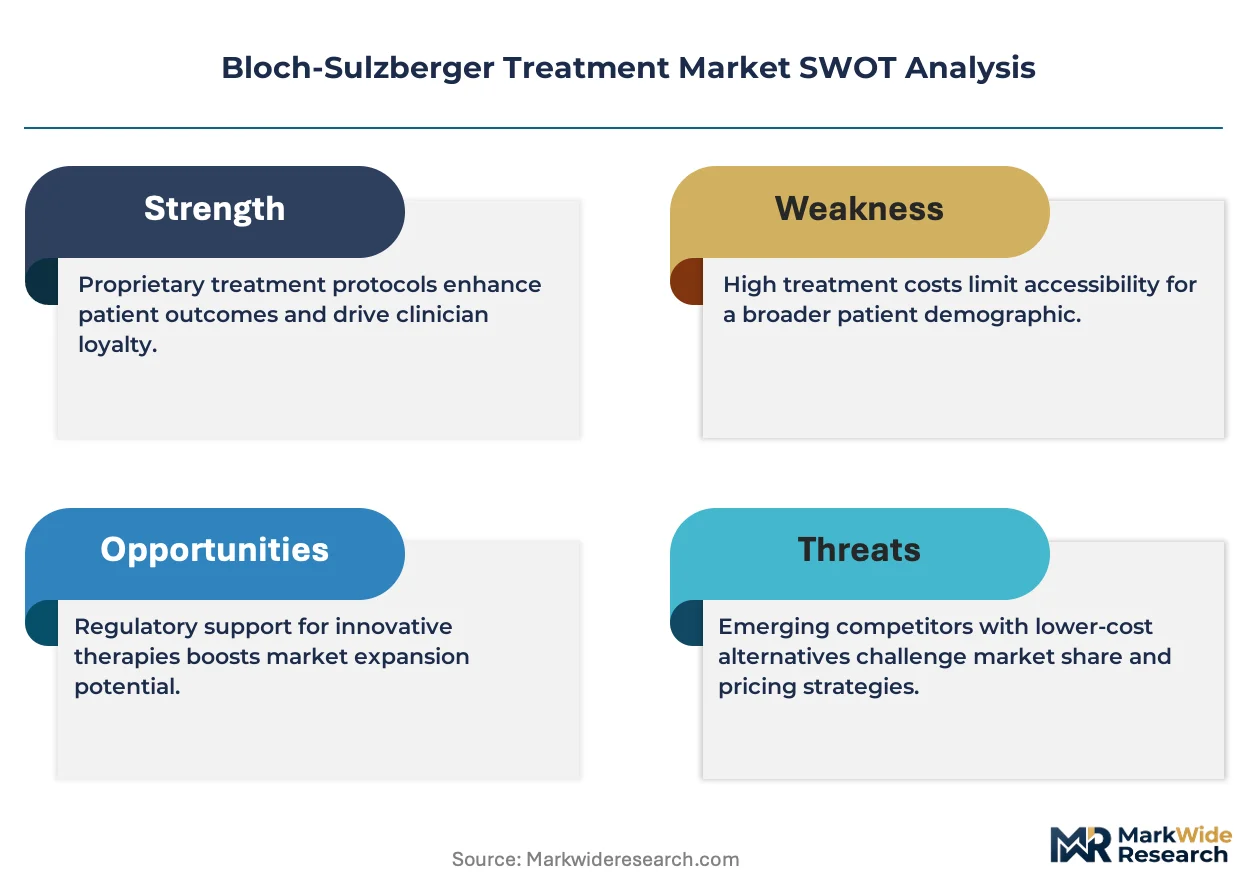
Established producers occupy the standard tier; emerging entrants pursue precision-targeted biologics under orphan drug protocols. The market structures around three tiers: multinational pharmaceutical conglomerates with rare disease infrastructure, mid-cap dermatology specialists, and academic spin-outs developing NF-kappa B pathway inhibitors. Consolidation concentrates among entities with EMA rapporteur relationships and existing biologic manufacturing footprints. Dominant competitive moves include strategic partnerships for real-world evidence generation and geographic expansion into underpenetrated Spanish regions.
Within the multinational tier, Pfizer Inc., Johnson & Johnson, and Merck & Co. Inc. exemplify divergent strategic positioning. Pfizer leverages established rare disease infrastructure to sustain pipeline momentum. Johnson & Johnson anchors market presence through dermatology-focused R&D networks across continental Europe. Merck differentiates via targeted investments in systemic treatment platforms for genetic skin disorders.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson |
| Merck & Co. Inc. |
| AbbVie Inc. |
| Sanofi S.A. |
| Bristol Myers Squibb |
| AstraZeneca plc |
| Novartis AG |
| GSK plc |
| Others |
Value Network & Pricing Analysis
REACH authorization timelines for novel excipients govern qualified supply access and premium-tier pricing power for biologic manufacturers serving European dermatology networks. ECHA's substance evaluation workload gates formulation development cycles, compressing margins on petroleum-derived corticosteroid bases while elevating pricing for compliant alternatives.
Pricing Analysis
Distributor margins on orphan biologics absorb 18-25% of ex-manufacturer price before hospital procurement. Pricing stratifies across premium NF-kappa B inhibitors, standard systemic immunomodulators, and economy topical corticosteroids based on manufacturing complexity and EMA exclusivity status. Cost compression in maintenance-phase topicals intensifies as REACH compliance extends development timelines for excipient suppliers. Hospital procurement committees exhibit highest price sensitivity for phototherapy equipment, while neurologists managing severe presentations demonstrate lowest sensitivity for first-line biologics.
Supply Chain Analysis
Single-source vulnerability sits with Swiss and Irish contract manufacturing organizations controlling fill-finish capacity for orphan monoclonal antibodies. Active pharmaceutical ingredient production draws from Switzerland, Ireland, and Germany, with fill-finish operations concentrated in Basel and Dublin clusters. Supply chain risk centers on regulatory restriction as EMA post-authorization study requirements expand batch documentation burdens. Distribution runs through hospital group purchasing organizations in France and Italy, consolidating acquisition volume for systemic therapies and biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bloch-Sulzberger treatment demand is shifting toward precision-targeted biologics with demonstrated neurological efficacy, rewarding manufacturers with EMA rapporteur relationships and established rare disease infrastructure.
For Market Incumbents: Lock in G-BA conditional reimbursement pathways for high-severity presentations before HAS divergence hardens in France. Secure fill-finish capacity commitments with Swiss contract manufacturers ahead of EMA orphan drug exclusivity expirations. Vertical integration into bio-based excipient sourcing mitigates REACH margin compression for topical portfolios. For New Entrants and Emerging Players: Teledermatology platform partnerships offer the most penetrable channel into Andalusia and Galicia, where specialist density gaps exceed 40% versus Madrid. Target pediatric formulation development for patients under 12, where no approved oral NF-kappa B inhibitor exists. Real-world evidence infrastructure partnerships with Paris and Munich academic centers provide regulatory credibility without full trial network investment. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap dermatology specialists because EMA orphan drug incentives compress development timelines and elevate pricing power for acquired pipelines. Five-to-ten year viability hinges on biologic manufacturing footprints in Switzerland or Ireland. Watch for G-BA and HAS convergence on cost-effectiveness thresholds as the inflection signal for cross-border commercial scalability.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Orphan Drug Designation | Secures 10-year market exclusivity and accelerates NF-kappa B inhibitor pipeline investment. |
| Swiss Fill-Finish Capacity Expansion | Basel and Zurich CMOs anchor critical manufacturing for orphan monoclonal antibodies. |
| Teledermatology Platform Partnership | Enables treatment initiation in Andalusia and Galicia where specialist density lags Madrid. |
| Pediatric Formulation Development | Addresses unmet need for oral NF-kappa B inhibitors in patients under 12 years. |
| Real-World Evidence Infrastructure | Satisfies EMA post-authorization study requirements for orphan biologics. |
Research Methodology
Bottom-up patient management modeling reconciled against top-down biologic manufacturing tracking forms the analytical core of this study. Primary interviews with dermatology KOLs, regulatory affairs leads at EMA rapporteur firms, hospital procurement managers in German university hospitals, and payer access specialists in France informed demand-side assumptions. Secondary validation drew from EMA orphan drug designations, ClinicalTrials.gov entries for incontinentia pigmenti interventions, G-BA and HAS reimbursement decisions, and REACH authorization timelines published by ECHA.
Input-output matrices mapped NF-kappa B inhibitor production capacity against addressable patient populations across severity tiers and regional regulatory clusters. Segmentation dimensions included treatment line, delivery mode, end-user facility type, and geographic adoption pattern. CAGRs were derived from slope analysis of historic biologic pricing trajectories under orphan exclusivity and projected phototherapy equipment installation rates. Forecast inputs incorporated EMA market exclusivity timelines, HTA evolution patterns, and genetic testing penetration curves in German fertility clinics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biosimilar entry timelines and REACH authorization backlogs for novel excipients. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
House Dust Mite Allergy Treatment Market
Medical Treatment
Kidney Stones Management Market
Medical Treatment
Merkel Cell Carcinoma (MCC) Treatment Market
Medical Treatment
Transarterial Chemoembolization (TACE) Market
Medical Treatment
Stereotactic Body Radiation Therapy Market
Medical Treatment
Intensity Modulated Radiation Therapy Market
Medical Treatment
Acute Migraine Treatment Market
Medical Treatment
Anti-Rickettsial Treatment Market
Medical Treatment
US Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Vulvodynia Treatment Market
Medical Treatment
Nasopharyngeal Carcinoma Treatment Market
Medical Treatment
Tinea Pedis Treatment Market
Medical Treatment
Monkeypox Treatment Market
Medical Treatment
Babesiosis Treatment Market
Medical Treatment
Malaria Treatment Market
Medical Treatment
Precocious Puberty Treatment Market