
 Vulvovaginal Candidiasis Treatment Market | 2026-2036
Vulvovaginal Candidiasis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Vulvovaginal Candidiasis Treatment Market Intelligence
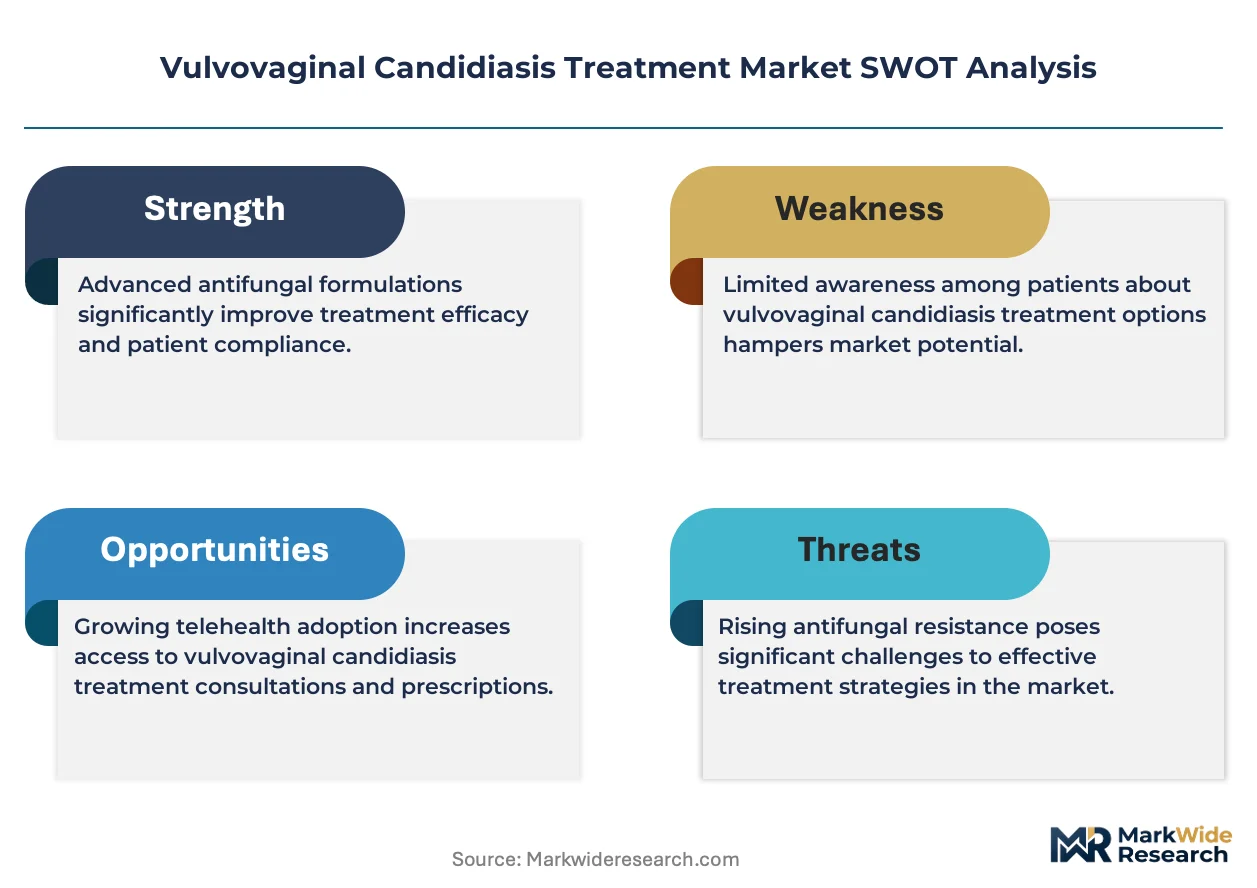
Combination therapy bundling is realigning how prescribers and patients evaluate treatment value against standalone oral or topical options. Bayer AG leverages its consumer health division to sustain shelf presence across pharmacy and retail channels. Pfizer, Inc. anchors hospital formulary access through its established infectious disease portfolio. Mycovia Pharmaceuticals, Inc. differentiates via novel mechanism antifungals targeting recurrent infection populations.
Vulvovaginal candidiasis treatment encompasses pharmaceutical interventions designed to eliminate Candida albicans and non-albicans species from the vaginal mucosa, with azole-class agents inhibiting fungal ergosterol synthesis at therapeutic concentrations. These therapies serve to resolve acute symptomatic episodes, suppress recurrence, and restore normal vaginal microbiome balance in affected patients. Oral antifungals capture the largest volume share due to single-dose convenience and high patient compliance rates, while combination therapies command premium positioning by addressing both immediate clearance and recurrence prevention in refractory cases. Probiotics represent the fastest-growing dosage adjunct as clinicians integrate microbiome restoration into maintenance protocols.
The FDA oversees prescription-to-OTC switches for topical azoles, directly expanding patient self-selection and pharmacy channel volume. EMA's MDR and pharmacovigilance requirements shape clinical evidence standards for new molecular entities seeking European market access. WHO inclusion of essential antifungal medicines influences national procurement policies across low- and middle-income health systems. Stakeholders must monitor regulatory divergence between self-care empowerment and prescription-gated novel therapies when allocating R&D and commercialization resources.
Market Dynamics
The FDA's accelerated OTC switch pathways for topical azoles are compressing prescription volumes while expanding pharmacy self-selection, fundamentally restructuring how patients access first-line therapy and where manufacturers compete for shelf space.
Growth Catalysts
- Homecare Self-Administration:Patients increasingly prefer private, convenient treatment without clinical visits. Pharmacy chains now dedicate expanded shelf space to vaginal health products.
- REACH Compliance Standards:European chemical safety frameworks drive formulation upgrades that manufacturers leverage for premium positioning across EU markets.
- Microbiome Restoration Protocols:Clinicians integrate probiotic adjuncts into maintenance regimens. Lactobacillus-based supplements gain formulary inclusion as recurrence prevention tools.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Azole API production clusters in specific Asian manufacturing hubs. Single-source dependencies create supply vulnerability during regulatory inspections.
- Antifungal Resistance Surveillance:CDC tracking identifies rising non-albicans Candida species with reduced azole susceptibility. Treatment failures in recurrent cases limit standard therapy effectiveness.
- OTC Price Compression:Pharmacy private-label topical azoles undercut branded equivalents. Margin erosion pressures R&D reinvestment for novel mechanisms.
Strategic Opportunities
- Direct-to-Consumer Subscription Models:Telehealth platforms bundle diagnostic testing with recurring treatment shipments. Recurrent infection patients accept automated delivery for maintenance dosing.
- Novel Mechanism Pipelines:Investigational agents targeting fungal cell wall synthesis bypass existing resistance pathways. Clinical-stage candidates address refractory populations underserved by azoles.
- India PLI Scheme Incentives:Production-linked incentives for active pharmaceutical ingredients attract contract manufacturing investments. Cost-competitive API supply strengthens generic formulation economics.
Industry Challenges
- Clinical Trial Recruitment Complexity:Vaginal health studies require specialized investigator networks. Patient retention suffers from stigma-related dropout rates.
- Formulation Stability Requirements:Vaginal delivery systems demand precise moisture and pH control. Shelf-life validation extends development timelines.
- Reimbursement Coding Fragmentation:OTC-status products lack consistent insurance coverage. Patients absorb full cost for premium formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vulvovaginal Candidiasis Treatment Market |
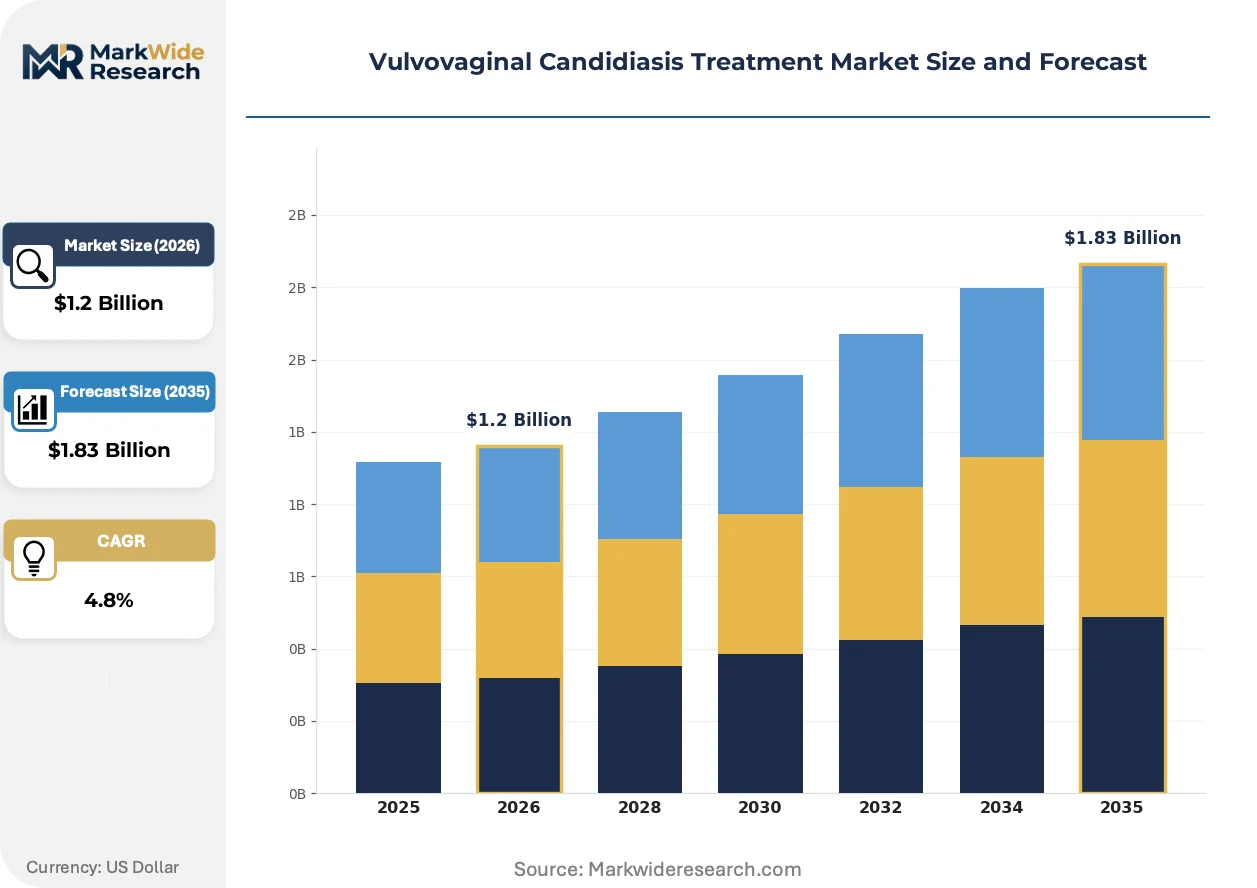
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $1.83 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Antifungals, Oral Antifungals, Combination Therapies, Probiotics End User: Hospitals, Clinics, Homecare Settings, Pharmacies Dosage Form: Creams, Tablets, Capsules, Suppositories Treatment Duration: Short-Term, Long-Term, Maintenance, Acute |
| Companies Covered | Astellas Pharma Inc., Mycovia Pharmaceuticals, Inc., Bayer AG, Basilea Pharmaceutica Ltd., Scynexis, Inc., Grupo Ferrer Internacional S.A., Pfizer, Inc., Bristol-Myers Squibb Company, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vulvovaginal Candidiasis Treatment Market Strategic Shifts & Innovations
Treatment paradigms are fragmenting across convenience-driven self-care and clinically supervised recurrence management, with technology and regulatory forces pulling development in divergent directions.
Single-dose oral fluconazole formulations are overtaking multi-day topical regimens in patient preference surveys. Busy working-age women select pharmacy pickup over prescription fulfillment delays. The shift compresses brand loyalty windows and rewards immediate-availability distribution.
EMA's Medical Device Regulation reclassifies certain drug-device combination products, requiring additional clinical evidence for intravaginal delivery systems. Manufacturers with existing CE-marked portfolios face retrospective compliance costs. European launch timelines for novel applicator technologies extend by twelve to eighteen months.
Subscription-based telehealth platforms are displacing traditional gynecology referrals for initial diagnosis. Younger patients in urban United States markets complete asynchronous consultations and receive same-day treatment delivery. This channel bypasses formulary restrictions and captures lifetime value through recurrence prevention programs.
Vulvovaginal Candidiasis Treatment Market Segmentation
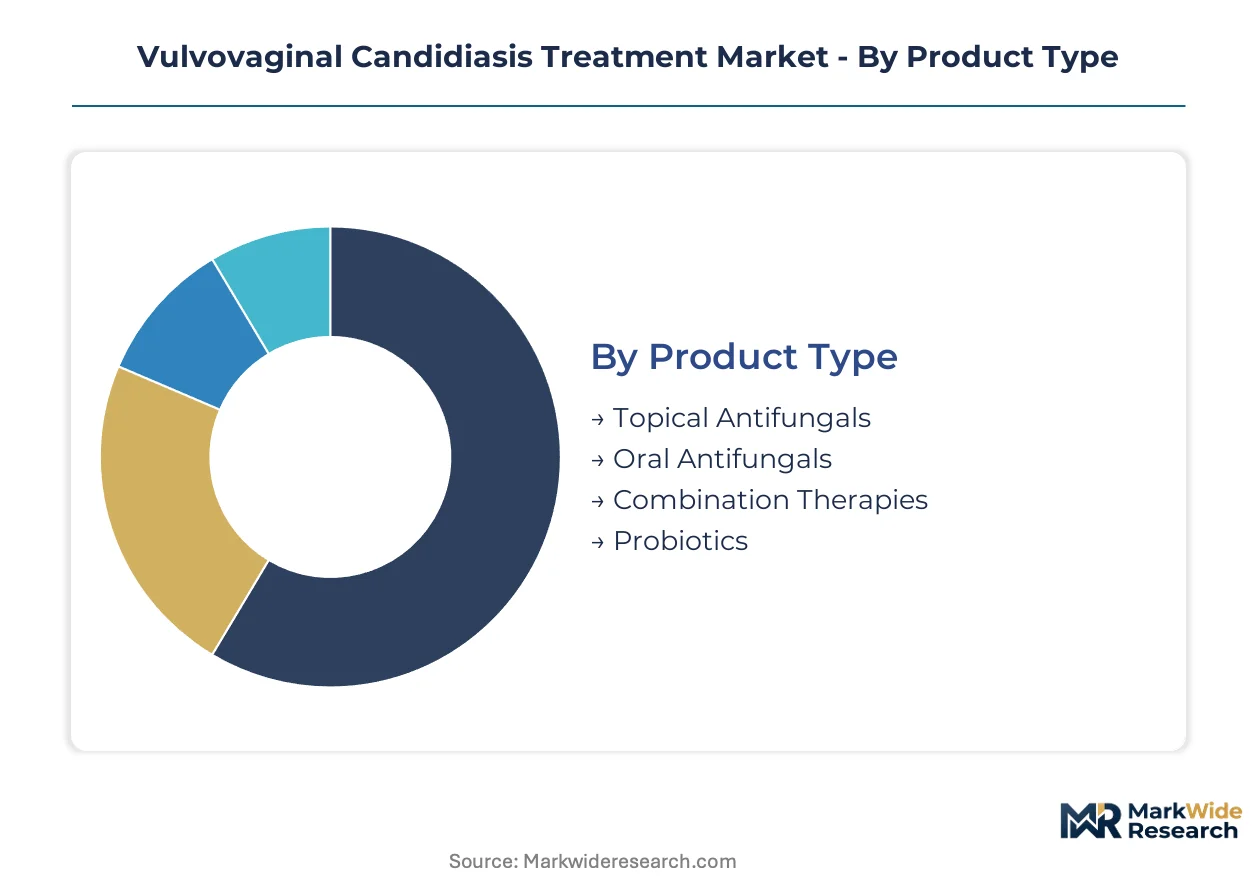
Treatment modality selection in vulvovaginal candidiasis hinges on recurrence patterns, patient autonomy preferences, and reimbursement channel access. Manufacturers configure portfolio breadth across these intersecting dimensions to capture lifetime patient value.
Product Type:
Supply concentration tilts toward azole API manufacturers with fermentation capacity in India and China, conditioning competitive dynamics across finished dosage forms.
- Topical Antifungals:Clotrimazole, miconazole, and tioconazole formulations deliver localized ergosterol inhibition via vaginal creams or suppositories. Demand concentrates in United States pharmacy self-selection channels where FDA OTC switches eliminated prescription friction.
- Oral Antifungals:Fluconazole single-dose tablets achieve systemic Candida clearance through hepatic metabolism. Patient compliance advantages drive preference among working-age women in urban United States markets seeking convenience over multi-day regimens.
- Combination Therapies:Bundled oral plus topical protocols address refractory infections.
- Probiotics:Lactobacillus-based microbiome restoration products.
Today's leader: Oral Antifungals. Tomorrow's challenger: Probiotics.
End User:
Channel cost structures diverge sharply between reimbursed clinical settings and cash-pay self-care environments.
- Homecare Settings:Self-administered regimens bypass clinical visit costs entirely. Telehealth platforms in United States urban centers now bundle asynchronous diagnosis with direct-to-patient delivery, capturing recurrent infection populations.
- Pharmacies:Brick-and-mortar and e-commerce channels stock expanded vaginal health assortments. Shelf space allocation in United States chains like CVS and Walgreens reflects OTC azole volume concentration.
- Hospitals:Inpatient antifungal stewardship programs.
- Clinics:Gynecology and urgent care diagnostic confirmation.
Homecare Settings expand most quickly. Pharmacies defend the revenue base.
Dosage Form:
Formulation stability requirements and patient handling preferences shape manufacturing investment priorities.
- Tablets:Oral fluconazole solid dosage forms dominate by volume. United States FDA-approved single-dose 150mg specifications command formulary inclusion through infectious disease portfolio relationships.
- Creams:Topical azole emulsions require precise pH buffering and moisture control. EMA MDR compliance costs extend European launch timelines for novel applicator technologies.
- Capsules:Oral delivery alternatives.
- Suppositories:Intravaginal solid dosage forms.
Tablets capture volume leadership. Creams face regulatory headwinds.
Treatment Duration:
Reimbursement coding and patient adherence patterns stratify across acute versus maintenance paradigms.
- Acute:Single-dose or short-course regimens resolve symptomatic episodes. United States direct-to-consumer channels prioritize immediate availability for first-time patients.
- Maintenance:Suppressive weekly dosing prevents recurrence in refractory cases. Subscription telehealth models in United States markets automate delivery for this chronic population.
- Short-Term:1-3 day therapeutic courses.
- Long-Term:Extended protocols for complex cases.
Acute treatment commands current spend. Maintenance protocols build recurring revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vulvovaginal candidiasis treatment markets trace their commercial origins to postwar pharmaceutical development in the United States and Germany, where azole chemistry first reached clinical scale. Distribution patterns now reflect divergent regulatory philosophies on self-care access versus prescription control.
United States
Direct-to-consumer pharmacy channels and telehealth subscription models drive volume concentration. FDA OTC switch pathways for topical azoles eliminated prescription friction, expanding self-selection at CVS, Walgreens, and Amazon Pharmacy. Boston and San Francisco anchor digital health platform development for asynchronous diagnosis and automated recurrence prevention delivery.
Germany
Pharmacy-only distribution rules sustain higher-margin positioning for branded formulations. EMA MDR compliance requirements extend timelines for novel intravaginal delivery systems. The Rhine-Ruhr corridor concentrates API finishing operations serving EU-wide generic supply.
India
Domestic fermentation capacity for azole active pharmaceutical ingredients conditions export economics. CDSCO streamlined approval pathways for fixed-dose combinations accelerate local product registration. Hyderabad and Ahmedabad host contract manufacturing organizations supplying finished dosage forms to African and Southeast Asian markets.
Japan
Hospital-centered antifungal stewardship programs prioritize oral fluconazole formulary placement. PMDA pharmacovigilance requirements shape post-market surveillance for recurrent infection populations. The Kanto region maintains concentrated specialist gynecology clinic networks.
Brazil
Unified health system procurement policies influence national essential medicines lists for azole coverage. ANVISA bioequivalence standards for generic topical formulations tighten quality differentiation. São Paulo state concentrates private pharmacy chain expansion and direct-to-consumer marketing investment.
Vulvovaginal Candidiasis Treatment Market Key Industry Players
Premium-margin players sit above commodity-margin players across regulatory access and formulation complexity. The vendor base organizes into three tiers: multinational pharmaceutical conglomerates with infectious disease portfolios, consumer health specialists with pharmacy channel dominance, and clinical-stage developers targeting refractory populations. Consolidation pressures concentrate among mid-cap generic manufacturers facing API cost volatility. Strategic moves center on prescription-to-OTC switch execution and microbiome adjacency expansion through probiotic partnerships.
Within the conglomerate tier, Bayer AG and Pfizer, Inc. occupy positions spanning prescription hospital access and consumer self-care channels. Mycovia Pharmaceuticals, Inc. exemplifies the development-stage archetype focused on novel mechanism candidates for azole-resistant populations. These three entities represent distinct strategic postures: shelf-space leverage, formulary anchoring, and clinical differentiation respectively.
| Leading Market Players |
|---|
| Astellas Pharma Inc. |
| Mycovia Pharmaceuticals, Inc. |
| Bayer AG |
| Basilea Pharmaceutica Ltd. |
| Scynexis, Inc. |
| Grupo Ferrer Internacional S.A. |
| Pfizer, Inc. |
| Bristol-Myers Squibb Company |
| GlaxoSmithKline plc |
| Others |
Cost & Logistics Intelligence
Azole API commodity indices in India and China cascade through fermentation contract rates into finished dosage pricing tiers, compressing margins for generic topical manufacturers while preserving premium positioning for novel mechanism developers with captive synthesis capabilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates patented oral antifungals from branded topical azoles and pharmacy private-label equivalents. Price differentiation hinges on FDA regulatory tier status and brand heritage in pharmacy channels. Cost compression in economy-tier topical creams is intensifying because private-label substitution at CVS and Walgreens undercuts branded equivalents by substantial margins. Cash-pay homecare patients exhibit highest price sensitivity, while hospital formulary managers prioritize clinical efficacy over unit cost.
Supply Chain Analysis
Regional distribution centers in the United States Midwest and Germany's Rhine-Ruhr corridor manage hub-and-spoke patterns for finished dosage deployment. Active pharmaceutical ingredient production draws from India, China, and limited European fermentation capacity. Key inputs include imidazole chemical precursors, specialized fermentation media, and vaginal applicator polymers. Single-source vulnerability in azole API synthesis creates exposure during CDSCO or FDA facility inspections. Distribution runs through pharmacy wholesale networks and direct-to-patient telehealth platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturers can exploit geographic-arbitrage by locating API fermentation in India under PLI scheme incentives while positioning premium formulation finishing in Germany for EMA MDR-compliant European access, capturing cost-regulatory spread between jurisdictions.
For Market Incumbents: Cement formulary anchoring through infectious disease portfolio breadth while accelerating prescription-to-OTC switch execution for mature topical azoles. Threat from novel mechanism developers like Mycovia Pharmaceuticals demands defensive R&D investment in recurrence prevention protocols. Backward integration into azole API fermentation insulates against supply disruption. For New Entrants and Emerging Players: Enter via telehealth subscription models for maintenance dosing populations in United States urban markets, the most penetrable segment given asynchronous diagnosis acceptance among younger patients. White-space exists in probiotic-microbiome combination protocols and azole-resistant Candida targeting. Go-to-market leverage centers on direct-to-patient automated delivery bypassing pharmacy shelf competition. For Investors and Strategic Acquirers: Asymmetric upside sits with clinical-stage developers possessing novel mechanism candidates for refractory infection populations. Long-term viability over the next decade hinges on regulatory approval velocity and formulary access depth. Acquisition target archetype: developers with Phase II assets bypassing azole resistance pathways. Signal to watch: CDC antifungal resistance surveillance updates indicating non-albicans species prevalence inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Prescription-to-OTC Switch Execution | FDA streamlined pathways expand pharmacy self-selection and compress prescription volume dependency. |
| Novel Mechanism Pipeline Advancement | Clinical-stage candidates targeting fungal cell wall synthesis address azole-resistant patient populations. |
| Telehealth Platform Integration | Asynchronous diagnosis and automated recurrence delivery bypass formulary restrictions in United States markets. |
| Backward Integration into API Synthesis | Captive azole fermentation capacity under India's PLI scheme insulates against single-source supply vulnerability. |
| Probiotic Adjunct Formulation | Lactobacillus-based microbiome restoration products capture fastest-growing dosage segment for maintenance protocols. |
Research Approach
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers; secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases; plus customs and trade flow records — were reconciled through bottom-up patient-flow modeling and top-down pharmaceutical market sizing triangulation.
Historical prescription volume trajectories were cross-referenced against panel input from infectious disease specialists and pharmacy channel planners to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include treatment modality, dosage form, end-user channel, and regional regulatory cluster. CAGRs were derived from patient epidemiology trends, pricing elasticity coefficients, and channel shift assumptions for self-care migration.
Inputs from FDA approval databases and EMA centralized procedure records were available through the study window; gaps in real-time telehealth platform transaction data introduce uncertainty bands around direct-to-consumer channel estimates. Forecasts reflect documented assumptions regarding OTC switch velocity and resistance surveillance trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Global Rotator Cuff Treatment Market
Medical Treatment
Dengue Fever Treatment Market
Medical Treatment
Infertility Treatment Market
Medical Treatment
Cholera Treatment Market
Medical Treatment
Gunshot Injuries Treatment Market
Medical Treatment
Familial Hypercholesterolemia Treatment Market
Medical Treatment
Merkel Cell Carcinoma (MCC) Treatment Market
Medical Treatment
Brazilian Hemorrhagic Fever (Bzhf) Treatment Market
Medical Treatment
House Dust Mite Allergy Treatment Market
Medical Treatment
Allergy Treatment Market
Medical Treatment
Bloch-Sulzberger Treatment Market
Medical Treatment
Laser Therapy Market
Medical Treatment
Europe Lysosomal Disease Treatment Market
Medical Treatment
Burns Treatment Market
Medical Treatment
Thyroid Gland Disorders Treatment Market
Medical Treatment
Global Plasma Therapy Market