
 Global Pheochromocytoma Market | 2026-2036
Global Pheochromocytoma Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pheochromocytoma Market Foresight
Modular bundling of diagnostic kits with imaging agents is hardening as the dominant procurement configuration across European outpatient centers. Pfizer leverages its manufacturing scale to supply integrated testing workflows for catecholamine-secreting tumors. Novartis anchors its position through specialized therapeutic compounds targeting adrenal medulla malignancies. Bayer differentiates via radioisotope imaging agents that pair with surgical planning protocols.
Pheochromocytoma constitutes a catecholamine-producing neuroendocrine tumor arising from chromaffin cells of the adrenal medulla, typically diagnosed through plasma metanephrine assays and iodine-123 metaiodobenzylguanidine scintigraphy with surgical resection as definitive treatment. Therapeutic drugs command the deepest margin pools due to orphan pricing dynamics and extended treatment durations for metastatic cases. Diagnostic laboratories represent the fastest-growing end user segment as decentralized testing reduces referral bottlenecks for hypertensive crisis workups. Imaging agents sustain steady demand from the radioisotope imaging delivery mode, where supply chain concentration for isotopes creates procurement rigidity.
The FDA's orphan drug program shapes therapeutic development economics by granting market exclusivity and tax incentives for rare adrenal tumor indications. EMA's MDR framework elevates validation requirements for surgical instruments used in minimally invasive adrenalectomy, filtering lower-capability device suppliers from European markets. Japan's PMDA accelerates conditional approvals for novel radiopharmaceuticals through its Sakigake designation pathway. Stakeholders must monitor isotope supply chain resilience and evolving reimbursement thresholds for companion diagnostic pairings.
Market Dynamics
Orphan drug economics are restructuring competitive incentives in pheochromocytoma therapeutics, with FDA exclusivity windows and EMA pediatric investigation plans compressing development timelines for rare adrenal malignancies. This regulatory architecture is redrawing how manufacturers prioritize pipeline assets across diagnostic and therapeutic categories.
Growth Catalysts
- Radioisotope imaging protocols:German specialty clinics are integrating iodine-123 metaiodobenzylguanidine scintigraphy into standard hypertension workups, accelerating detection rates for catecholamine-secreting tumors.
- Japan's METI-funded precision medicine initiatives:Molecular diagnostic integration into standard care pathways is expanding addressable patient pools for targeted therapeutic interventions.
- FDA orphan drug designation incentives:Market exclusivity provisions and tax credits are pulling venture capital into rare adrenal tumor therapeutic development.
Market Restraints
- Isotope supply chain concentration:Molybdenum-99 production dependence on aging research reactors creates procurement rigidity for diagnostic imaging agents.
- EMA MDR validation requirements:Elevated clinical evidence standards for minimally invasive adrenalectomy instruments are filtering lower-capability device suppliers from European markets.
- Extended treatment duration economics:Metastatic pheochromocytoma cases require chronic therapeutic management, straining reimbursement thresholds in single-payer systems.
Strategic Opportunities
- Decentralized diagnostic laboratory expansion:Point-of-care plasma metanephrine testing is reducing referral bottlenecks in community hypertension management settings.
- PMDA Sakigake pathway for radiopharmaceuticals:Japan's conditional approval framework is accelerating novel imaging agent commercialization timelines.
- Companion diagnostic pairing models:Integrated test-and-treat protocols are creating new revenue architecture linking molecular profiling to targeted therapy selection.
Industry Challenges
- Specialized surgical talent scarcity:Laparoscopic adrenalectomy requires advanced endocrine surgery training, constraining procedure volume growth in secondary markets.
- Reimbursement coding fragmentation:Molecular diagnostic tests lack standardized CPT classification, creating payment uncertainty for integrated diagnostic workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pheochromocytoma Market |
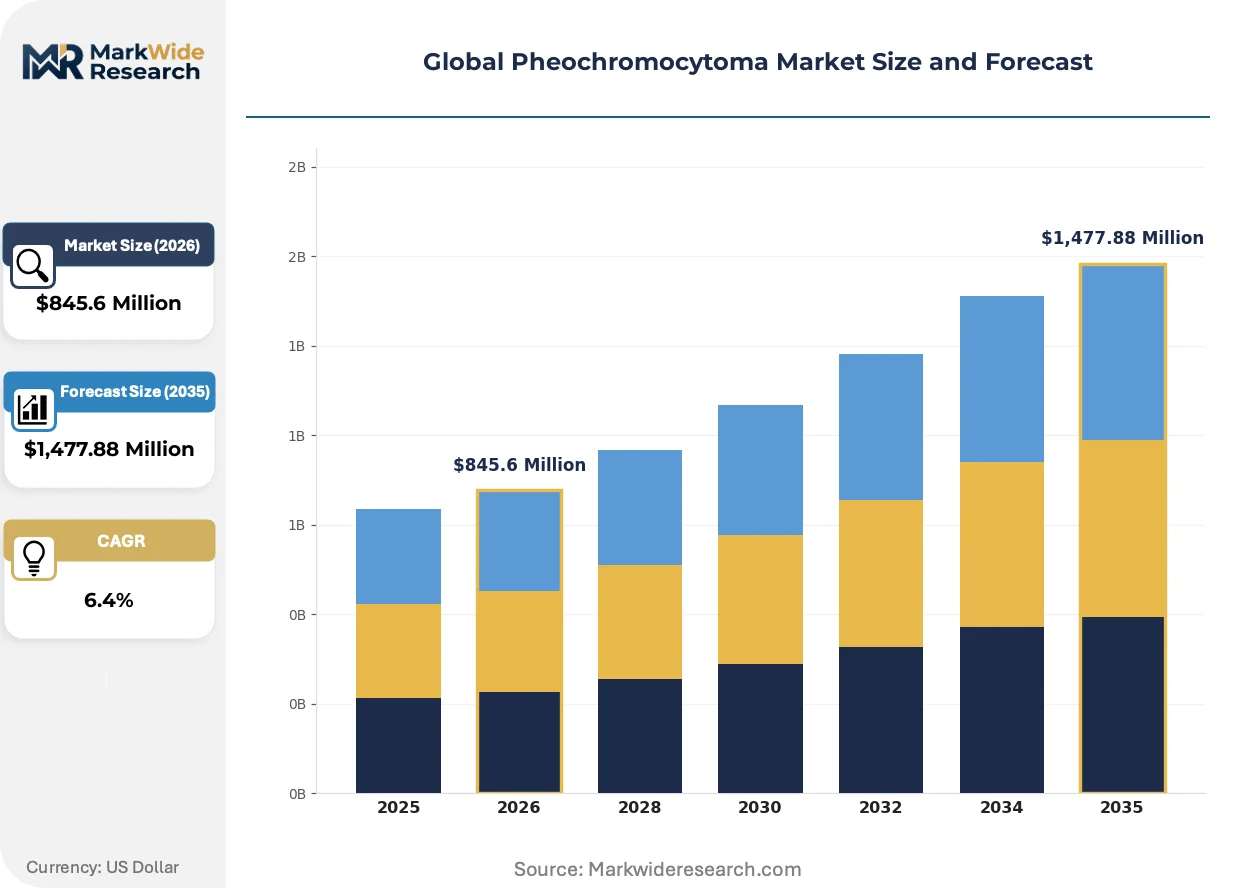
| Market Size in 2026 | $845.6 Million |
| Market Size in 2035 | $1,477.88 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
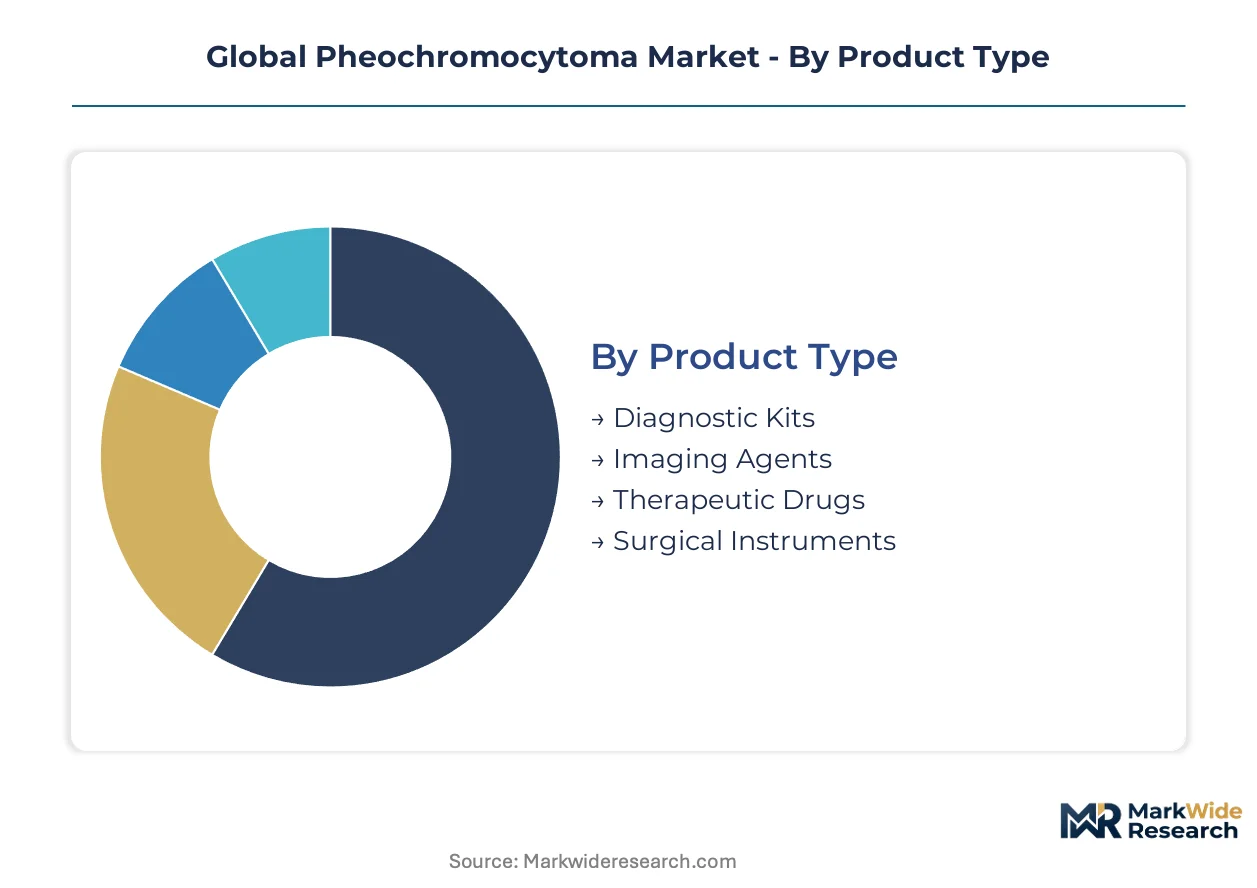
| Segmentation | Product Type: Diagnostic Kits, Imaging Agents, Therapeutic Drugs, Surgical Instruments Therapy Area: Endocrine Disorders, Neuroendocrine Tumors, Hypertension Management, Adrenal Gland Disorders End User: Specialty Clinics, Diagnostic Laboratories, Outpatient Centers, Research Institutes Delivery Mode: Oral Administration, Intravenous, Radioisotope Imaging, Minimally Invasive Surgery |
| Companies Covered | Pfizer, Novartis, Sanofi, Merck, AstraZeneca, Johnson & Johnson, Bristol-Myers Squibb, Eli Lilly, Bayer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pheochromocytoma Market Shifts & Advancements
Modular diagnostic kit bundling is compressing procurement cycles across European outpatient centers, with imaging agents and biochemical assays merging into single-vendor contracts. This integration is redrawing competitive boundaries between pharmaceutical and diagnostic manufacturers.
Positron emission tomography with fluorodopamine is expanding into surgical planning protocols for metastatic pheochromocytoma cases. Academic medical centers in the United States are adopting this modality for preoperative staging at accelerating rates. The technology is expanding into territory previously dominated by conventional scintigraphy, compressing the addressable market for older imaging agents.
EMA's Medical Device Regulation is elevating post-market surveillance requirements for radio-guided surgical instruments used in adrenal tumor resection. Manufacturers must now maintain active implantable device-level documentation for previously Class IIa instruments. German and French hospital procurement consortia are responding by consolidating vendor panels to reduce compliance overhead.
Integrated test-and-treat procurement models are displacing standalone diagnostic purchasing in Japanese university hospitals. Bundled contracts linking molecular profiling to therapeutic selection are replacing transactional reagent buying. This behavioral shift is most visible in Tokyo and Osaka metropolitan clusters, where precision medicine pilot programs have created reference site effects for regional adoption.
Global Pheochromocytoma Market Segmentation
Pheochromocytoma management spans discrete diagnostic workflows and integrated therapeutic pathways. Segment boundaries blur where molecular profiling links directly to treatment selection, reshaping how procurement contracts bundle across product categories.
Product Type:
Standalone diagnostic consumables operate alongside capital-intensive imaging systems and chronic therapeutic regimens, creating divergent margin profiles and replacement cycles across the value chain.
- Diagnostic Kits:Plasma metanephrine and chromogranin A assays dominate biochemical confirmation workflows. German outpatient centers are consolidating reagent procurement into multi-year single-source agreements to secure volume discounts for hypertension screening programs.
- Imaging Agents:Iodine-123 metaiodobenzylguanidine and fluorodopamine radiopharmaceuticals enable functional tumor localization. Supply chain concentration for molybdenum-99 creates procurement rigidity for nuclear medicine departments in Japan and the United States.
- Therapeutic Drugs:Alpha-blockers, beta-blockers, and targeted agents for metastatic disease command orphan pricing premiums. Extended treatment durations for malignant cases generate recurring revenue streams exceeding acute intervention economics.
- Surgical Instruments:Laparoscopic and retroperitoneoscopic adrenalectomy tools require EMA MDR compliance documentation. French and Italian hospital consortia are narrowing vendor panels to reduce post-market surveillance overhead.
Diagnostic kits lead volumes today; therapeutic drugs are gaining share fastest.
Therapy Area:
Application focus shifts from acute symptom management toward precision stratification of hereditary versus sporadic tumor presentations.
- Endocrine Disorders:Primary aldosteronism and Cushing syndrome differentiation protocols drive biochemical testing demand. Academic medical centers in the United States are embedding genetic counseling into adrenal incidentaloma workups.
- Neuroendocrine Tumors:Functional imaging distinguishes pheochromocytoma from paraganglioma subtypes. PMDA Sakigake approvals are accelerating novel radiopharmaceutical entry for metastatic staging in Japanese university hospitals.
- Hypertension Management:Resistant hypertension screening protocols expand addressable testing pools. Community clinics in Germany are adopting point-of-care metanephrine assays to reduce referral delays.
- Adrenal Gland Disorders:Adrenal incidentaloma evaluation protocols integrate CT density analysis with hormonal testing. Tokyo metropolitan hospitals are piloting AI-assisted nodule characterization to streamline surgical candidacy decisions.
Hypertension management anchors current procedure volumes; neuroendocrine tumor applications are expanding most quickly.
End User:
Site-of-care migration reshapes purchasing authority, with decentralized laboratories capturing volume previously concentrated in tertiary referral centers.
- Specialty Clinics:Dedicated endocrine and hypertension centers perform initial biochemical screening and patient stabilization. Bavarian clinic networks are standardizing preoperative alpha-blockade protocols across affiliated surgical sites.
- Diagnostic Laboratories:Centralized and reference labs process high-complexity assays requiring mass spectrometry. Decentralized point-of-care testing is displacing send-out volumes in North American health systems.
- Outpatient Centers:Ambulatory surgical facilities perform elective adrenalectomy for small, biochemically confirmed tumors. Japanese day-surgery centers are expanding minimally invasive adrenal procedures under revised reimbursement schedules.
- Research Institutes:Academic centers conduct natural history studies and therapeutic trials for succinate dehydrogenase-mutant subtypes. NIH-funded consortia in the United States are building longitudinal biomarker repositories.
Specialty clinics dominate current service delivery; diagnostic laboratories are climbing the fastest.
Delivery Mode:
Route of administration and procedural approach determine reimbursement coding, supply chain requirements, and clinical training investments.
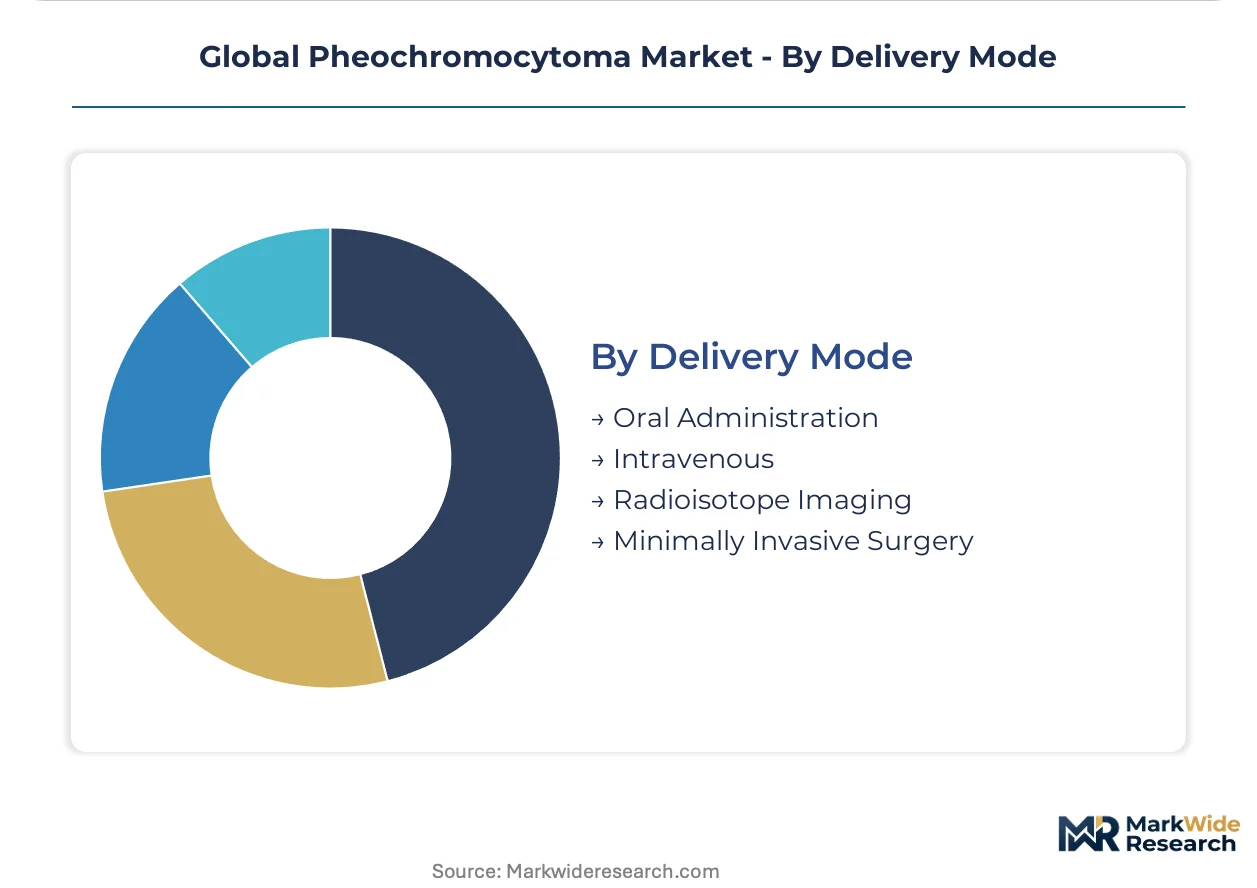
- Oral Administration:Phenoxybenzamine and doxazosin tablets enable preoperative catecholamine blockade. Generic substitution pressures are compressing margins for chronic alpha-blockade maintenance therapy.
- Intravenous:Parenteral agents manage hypertensive crises and intraoperative hemodynamic instability. Anesthesiology departments in French teaching hospitals are standardizing nitroprusside and phentolamine protocols.
- Radioisotope Imaging:Functional scintigraphy and PET modalities guide surgical planning and metastasis surveillance. Cyclotron-produced tracers are reducing dependence on reactor-based isotope supply in German nuclear medicine departments.
- Minimally Invasive Surgery:Laparoscopic and robot-assisted adrenalectomy reduce recovery times versus open resection. EMA MDR technical documentation requirements are elevating compliance costs for instrument manufacturers serving European markets.
Radioisotope imaging sustains the steepest expansion trajectory; oral administration retains the largest patient volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pheochromocytoma diagnostic protocols originated in European academic centers during the 1950s, with Germany and France pioneering catecholamine biochemical assays. Japan subsequently advanced functional imaging techniques, while the United States scaled commercial therapeutic development through orphan drug frameworks.
United States
Academic medical centers in Boston and Houston drive PET-fluorodopamine adoption for metastatic staging. FDA orphan drug exclusivity windows compress therapeutic development timelines for rare adrenal malignancies. NIH-funded consortia across the Midwest are building longitudinal biomarker repositories for succinate dehydrogenase-mutant subtypes.
Germany
Bavarian specialty clinics integrate iodine-123 metaiodobenzylguanidine scintigraphy into standard hypertension workups. EMA MDR validation requirements filter lower-capability surgical instrument suppliers from European markets. Munich and Berlin hospital procurement consortia consolidate vendor panels to reduce post-market surveillance overhead.
Japan
Tokyo metropolitan hospitals pilot AI-assisted adrenal nodule characterization to streamline surgical candidacy. METI-funded precision medicine initiatives embed molecular diagnostics into standard care pathways. Osaka university hospitals adopt bundled test-and-treat procurement models linking molecular profiling to therapeutic selection.
France
Lyon and Paris teaching hospitals standardize parenteral nitroprusside protocols for intraoperative hemodynamic instability. ANSM post-market surveillance elevates documentation requirements for radio-guided surgical instruments. French hospital consortia narrow laparoscopic adrenalectomy vendor panels to manage compliance costs.
Global Pheochromocytoma Market Competitive Landscape
Premium-margin players sit above commodity-margin players across therapeutic pricing tiers, with orphan-designated drugs commanding exclusivity premiums while generic alpha-blockers face substitution pressure. The vendor base stratifies into three tiers: multinational pharmaceutical conglomerates with integrated diagnostic-therapeutic portfolios, specialized radiopharmaceutical manufacturers with isotope supply chain control, and regional diagnostic laboratory service providers. Dominant competitive moves include backward integration into isotope production capacity and strategic partnerships bundling imaging agents with surgical planning protocols.
Within the multinational pharmaceutical tier, Pfizer and Novartis exemplify divergent strategic positioning. Pfizer leverages manufacturing scale to supply integrated testing workflows, while Novartis anchors its position through specialized therapeutic compounds. Bayer occupies a distinct position among radiopharmaceutical specialists, differentiating via radioisotope imaging agents that pair with surgical planning protocols. These three companies represent the primary competitive anchors shaping procurement dynamics across German, Japanese, and United States hospital systems.
| Leading Market Players |
|---|
| Pfizer |
| Novartis |
| Sanofi |
| Merck |
| AstraZeneca |
| Johnson & Johnson |
| Bristol-Myers Squibb |
| Eli Lilly |
| Bayer |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up diagnostic laboratory networks in Germany and the United States have concentrated procurement authority, hardening volume-based pricing discipline while squeezing reagent suppliers into multi-year exclusive contracts that lock in margin compression for biochemical assay manufacturers.
Pricing Analysis
Orphan drug exclusivity premiums for metastatic pheochromocytoma therapeutics anchor the top tier, while generic alpha-blocker substitution erodes maintenance therapy margins. Three-tier pricing structure across premium, standard, and economy levels separates FDA-designated rare disease compounds from branded chronic management drugs and commoditized preoperative blockade agents. Cost compression in the generic tier is intensifying because pharmacy benefit managers in North American health systems are tightening formulary placement criteria. Community hypertension clinics exhibit the highest price sensitivity, whereas academic medical centers purchasing integrated test-and-treat bundles demonstrate greater willingness to absorb premium positioning.
Supply Chain Analysis
Domestic-content mandates for radiopharmaceutical production in Japan and Germany are reshaping sourcing patterns, compelling imaging agent manufacturers to establish regional cyclotron networks rather than depend on centralized reactor isotope supply. Molybdenum-99 production concentrates in Belgium, the Netherlands, and South Africa, with iodine-123 and fluorodopamine precursor chemicals drawing from specialized chemical synthesis facilities in Switzerland and the United States. Single-source vulnerability for reactor-based isotope supply creates procurement rigidity when scheduled maintenance outages coincide with clinical demand surges. Distribution runs through hospital-owned nuclear medicine pharmacies in Japan and third-party radiopharmacy networks in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on chronic therapy duration extension for malignant cases and companion diagnostic pairing premiums that capture value upstream of therapeutic selection.
For Market Incumbents: Deepen backward integration into cyclotron-produced isotope capacity to reduce dependence on aging research reactor infrastructure in Belgium and South Africa. Secure exclusive hospital system partnerships for bundled test-and-treat protocols before EMA MDR compliance costs filter smaller surgical instrument competitors from European vendor panels. Lock in molecular diagnostic laboratory acquisitions to control patient identification upstream of therapeutic prescribing.
For New Entrants and Emerging Players: Begin with point-of-care plasma metanephrine testing platforms targeting community hypertension clinics in Bavaria and North American health systems where referral bottlenecks create immediate demand pull. The most penetrable white space sits in decentralized diagnostic laboratories displacing centralized send-out volumes. A direct-to-clinic reagent subscription model with embedded clinical decision support software bypasses entrenched hospital procurement consortia.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional diagnostic service providers lacking integrated therapeutic linkages. Long-term viability favors assets with captive patient identification infrastructure and orphan-designated therapeutic pipelines addressing succinate dehydrogenase-mutant subtypes. Watch FDA breakthrough therapy designation grants for metastatic pheochromocytoma compounds as the signal indicating inflection in therapeutic development economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA exclusivity windows compress development timelines and secure seven-year market protection for rare adrenal malignancies. |
| Cyclotron Network Expansion | Regional isotope production in Germany and Japan reduces supply chain vulnerability to Belgian reactor maintenance schedules. |
| Companion Diagnostic Development | Molecular profiling integration with therapeutic selection creates bundled revenue architecture in Japanese university hospitals. |
| Point-of-Care Testing Platform Launch | Decentralized metanephrine assays capture hypertension screening volumes previously concentrated in tertiary referral centers. |
| EMA MDR Compliance Investment | Enhanced technical documentation for laparoscopic adrenalectomy instruments filters lower-capability competitors from French and Italian markets. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with endocrine surgeons, nuclear medicine physicians, hospital procurement managers, and regulatory affairs specialists at orphan drug developers with secondary validation against FDA orphan drug designations, EMA MDR technical documentation filings, PMDA Sakigake approval records, and hospital procurement database extracts. Bottom-up patient volume modeling triangulates against top-down therapeutic market sizing.
Rate-of-change decomposition separates volume expansion in diagnostic testing from value-per-patient growth in therapeutic segments across the projection horizon. Segmentation dimensions include product type, therapy area, end user site of care, and delivery mode, with regional regulatory cluster effects explicitly modeled. CAGRs derive from fitted growth curves applied to procedure volume and pricing trajectories, incorporating METI precision medicine funding disbursements and NIH consortium grant allocations as demand-side inputs.
Several conditions sit outside the modeled scope, including unannounced regulatory pathway changes, isotope supply disruptions from geopolitical events, and reimbursement coding revisions for molecular diagnostic tests. Forecasts reflect documented assumptions regarding orphan drug exclusivity period utilization and EMA MDR implementation timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Hepatic Encephalopathy Treatment Market
Specialty Medicine
Complement 3 Glomerulopathy (C3G) Market
Specialty Medicine
Global Childhood Absence Epilepsy Treatment Market
Specialty Medicine
Kaposi Sarcoma Market
Specialty Medicine
Low-Grade Glioma Therapeutics Market
Specialty Medicine
Advance Renal Cell Carcinoma Therapeutics Market
Specialty Medicine
Marfan Syndrome Treatment Market
Specialty Medicine
Idiopathic Thrombocytopenic Purpura Therapeutics Market
Specialty Medicine
Disruptive Behavior Disorders Market
Specialty Medicine
Ankylosing Spondylitis Market
Specialty Medicine
Global Hypoparathyroidism Treatment Market
Specialty Medicine
TMJ Disorders Market
Specialty Medicine
Global Alcoholic Hepatitis Therapeutics Market
Specialty Medicine
Aflatoxicosis Treatment Market
Specialty Medicine
Wet Age-Related Macular Degeneration (Wet AMD) Market
Specialty Medicine
Global Pemphigus Vulgaris Market