
 Global Graft Polyols Market | 2026-2036
Global Graft Polyols Market Size, Share, and Industry Trends Forecast 2026-2036
Global Graft Polyols Market Foresight
Advanced controlled polymerization architectures is reconfiguring how graft polyol producers engineer molecular weight distribution and functional group density for targeted foam performance. BASF leverages its Ludwigshafen integrated site to sustain captive supply of specialty polyether backbones for automotive interior applications. Dow anchors North American production through its Freeport, Texas manufacturing complex, competing on scale in conventional flexible foam feedstocks. Wanhua Chemical dominates Asia-Pacific volume, extending its Ningbo operations into high-performance CASE applications.
Graft polyols are polyether or polyester backbone polymers with vinyl monomer side chains grafted via free-radical or controlled polymerization, typically containing styrene-acrylonitrile copolymer domains at 5-45 weight percent to enhance load-bearing capacity and dimensional stability in polyurethane foam systems. Polyether polyols occupy the largest production volume position due to their hydrolysis resistance and processing latitude in flexible slabstock and molded foams, while aromatic polyols command premium positioning in rigid insulation and flame-retardant formulations where thermal performance requirements are stringent. Graft copolymerization technology leads growth in the technology dimension, as manufacturers seek precise control over particle size distribution and graft efficiency to reduce cell collapse and improve foam breathability in automotive seating and mattress applications.
EPA regulations under the Toxic Substances Control Act govern styrene and acrylonitrile monomer handling in US graft polyol production, while REACH registration requirements in the European Union mandate full substance characterization for SAN-grafted polyols imported or manufactured above one tonne annually. China's Ministry of Ecology and Environment enforces GB standards limiting VOC emissions from polyurethane foam products, directly influencing graft polyol formulation choices for domestic construction and furniture markets. Stakeholders must monitor evolving chemical hazard classifications under these frameworks, as reclassification of grafted styrene content could trigger additional testing obligations or restrict market access in key jurisdictions.
Market Dynamics
Controlled polymerization architectures are compressing formulation development cycles while REACH and China's GB standards force simultaneous reformulation for compliance, creating a dual squeeze on R&D resource allocation.
Growth Catalysts
- Automotive interior mandates:Seating manufacturers in Germany and China are expanding procurement of high-resilience foam intermediates to meet comfort and durability specifications for electric vehicle platforms.
- GB standard enforcement:China's Ministry of Ecology and Environment is tightening volatile organic compound emission limits, accelerating replacement of conventional polyols with low-VOC graft alternatives in domestic construction.
- Integrated supply chains:East China's chemical manufacturing corridor has developed captive polyol-to-foam production networks that reduce logistics costs and improve batch consistency for appliance makers.
Market Restraints
- Styrene-acrylonitrile cost volatility:SAN monomer prices fluctuate with crude oil derivatives, compressing margins for producers unable to pass through input cost swings to foam compounders.
- Production concentration risk:Asia-Pacific volume dominance by integrated petrochemical giants limits second-tier access to specialty polyether backbones at competitive scale.
- REACH registration burden:Full substance characterization requirements for SAN-grafted polyols above one tonne annually impose fixed compliance costs that disproportionately affect smaller formulation houses.
Strategic Opportunities
- CASE application expansion:Coatings, adhesives, sealants and elastomers represent underpenetrated end-uses where graft polyol load-bearing properties can displace conventional systems.
- Rigid insulation premiumization:Aromatic polyol formulations command price premiums in flame-retardant building insulation where thermal performance requirements are tightening.
- EU Green Deal alignment:Circular economy content mandates and recycled feedstock incentives create regulatory tailwinds for producers developing bio-based polyether backbones.
Industry Challenges
- Polymerization control expertise:Free-radical grafting chemistry requires specialized knowledge in particle size distribution management that competes for talent with broader materials science sectors.
- Multi-jurisdiction compliance synchronization:Simultaneous EPA Toxic Substances Control Act, REACH and GB standard adherence demands dedicated regulatory affairs capacity that strains mid-scale producers.
- Legacy foam system integration:Reformulated graft polyols must maintain processing latitude on existing high-pressure mixing equipment without triggering cell collapse or dimensional instability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Graft Polyols Market |
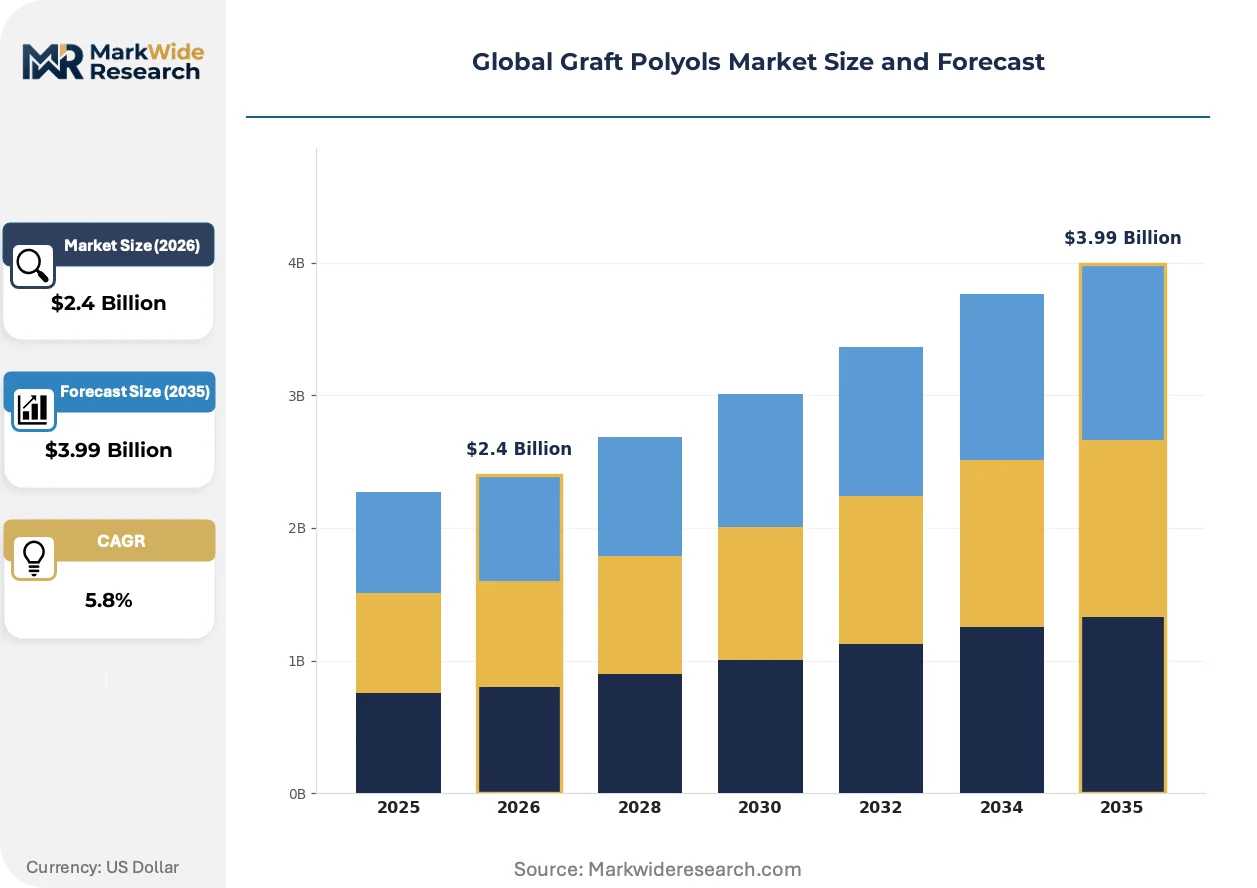
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyether Polyols, Polyester Polyols, Aromatic Polyols, Aliphatic Polyols Technology: Free Radical Polymerization, Graft Copolymerization, Anionic Polymerization, Controlled/Living Polymerization Application: Flexible Foams, Coatings, Adhesives, Sealants, Elastomers End User Industry: Footwear Manufacturers, Construction Materials, Electrical Equipment Producers, Furniture Fabricators |
| Companies Covered | BASF, Dow, Mitsui Chemicals, Evonik, Wanhua Chemical, Huntsman, SABIC, Repsol, Jilin Shenhua Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Graft Polyols Market Shifts & Advancements
Polyurethane foam chemistry is undergoing architectural revision as molecular engineering precision, regulatory hazard reclassification and procurement consolidation simultaneously reshape competitive requirements for graft polyol suppliers.
Controlled radical polymerization is collapsing the traditional tradeoff between graft efficiency and particle size distribution control. This technology enables precise styrene-acrylonitrile domain placement along polyether backbones. Automotive seating compounders in Germany are adopting these systems to reduce cell collapse rates while improving foam breathability. The structural consequence is collapsing differentiation between specialty and commodity graft polyol tiers as precision becomes table stakes.
REACH is driving substance-level transparency deeper into supply chains. ECHA's evolving hazard classifications for grafted styrene content trigger additional testing obligations or market access restrictions. Foam producers serving EU construction and furniture markets are responding by demanding full substance characterization from polyol suppliers. This regulatory pressure is compressing formulation flexibility as producers lock compositions to avoid re-registration costs.
Buyer concentration among automotive Tier 1 seating suppliers is reshaping contract structures. Procurement teams at major German and Chinese manufacturers are consolidating supplier panels and demanding captive supply commitments. Direct sourcing relationships are displacing distributor-mediated transactions. This pattern is most visible in East China's chemical corridor where integrated polyol-to-foam operations serve domestic appliance and construction markets with dedicated volume allocations.
Global Graft Polyols Market Segmentation
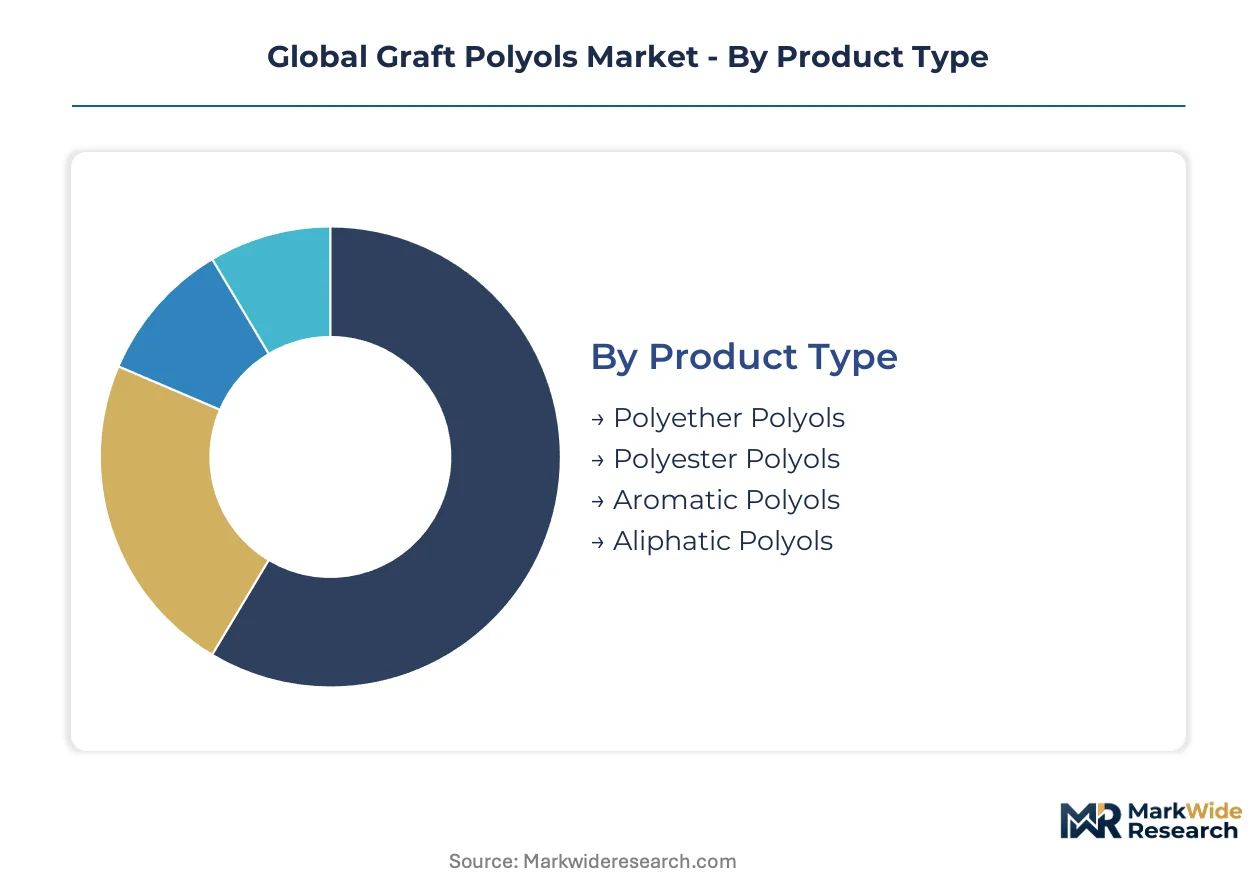
Graft polyol producers engineer molecular architectures around specific performance thresholds. Segment boundaries reflect tradeoffs between hydrolysis resistance, thermal stability, and processing latitude that determine formulation choices across automotive, construction, and consumer goods applications.
Product Type:
Cost tier differentiation separates commodity volume positions from premium thermal performance grades.
- Polyether Polyols:These backbones incorporate ethylene oxide or propylene oxide repeat units with superior hydrolytic stability and low-temperature flexibility. Demand concentrates in Germany's automotive seating supply chain where high-resilience molded foam specifications require consistent cell structure control.
- Polyester Polyols:Ester-linked backbones deliver higher tensile strength and oil resistance than ether alternatives. Furniture fabricators in East China's manufacturing corridor specify these grades for load-bearing applications where dimensional stability under compression matters.
- Aromatic Polyols:Benzene-ring structures enhance thermal insulation performance in rigid foam systems. Construction materials producers specify these for flame-retardant building envelope applications.
- Aliphatic Polyols:Saturated carbon chains provide UV stability and color retention in coatings. Electrical equipment producers favor these for encapsulation compounds requiring long-term optical clarity.
Polyether polyols hold installed capacity. Aromatic polyols are rotating up the share rankings.
Technology:
Application requirements determine polymerization architecture selection based on particle size precision needs.
- Graft Copolymerization:This architecture grafts styrene-acrylonitrile domains onto polyether backbones with tunable particle size distribution. Automotive seating compounders in Germany adopt these systems to reduce cell collapse while improving foam breathability on electric vehicle platforms.
- Controlled/Living Polymerization:Reversible deactivation mechanisms enable precise molecular weight control and narrow polydispersity. Coatings formulators specify these for CASE applications requiring consistent viscosity and cure kinetics.
- Free Radical Polymerization:Conventional initiator-driven grafting remains cost-competitive for commodity flexible foam feedstocks. Footwear manufacturers in Asia-Pacific rely on these systems for mid-tier polyurethane midsole production.
- Anionic Polymerization:Strong-base initiation produces high-molecular-weight backbones with low unsaturation. Sealants producers specify these for moisture-cure systems requiring extended pot life.
Free radical polymerization holds installed capacity. Controlled/living polymerization is rotating up the share rankings.
Application:
Volume concentration tracks end-use durability requirements and regulatory exposure intensity.
- Flexible Foams:Slabstock and molded foam systems consume the largest graft polyol volumes for cushioning applications. China's GB standard enforcement on VOC emissions is accelerating replacement of conventional polyols with low-emission graft alternatives in domestic mattress production.
- Coatings:Surface protection systems leverage graft polyol load-bearing properties for abrasion resistance. Industrial maintenance applications in Germany specify these for chemical-resistant tank linings.
- Adhesives:Structural bonding compounds require controlled rheology and substrate wetting. Construction materials producers specify these for panel lamination in prefabricated building systems.
- Sealants:Gap-filling applications demand elastic recovery and weathering resistance. Electrical equipment producers specify these for enclosure sealing in outdoor infrastructure.
- Elastomers:Cast and thermoplastic polyurethane systems require precise hard-soft segment phase separation. Footwear manufacturers specify these for high-performance outsole compounds.
Flexible foams hold installed capacity. Elastomers are rotating up the share rankings.
End User Industry:
Customer type determines formulation service intensity and technical support requirements.
- Construction Materials:Insulation board and spray foam producers specify rigid aromatic polyol systems. China's Ministry of Ecology and Environment GB standards are tightening emission limits for polyurethane foam products used in building envelopes.
- Furniture Fabricators:Mattress and upholstered seating manufacturers prioritize processing latitude on high-pressure mixing equipment. German producers specify high-resilience grades for premium comfort applications.
- Footwear Manufacturers:Midsole and outsole compounders balance density reduction with abrasion resistance. East China's integrated supply chains serve domestic athletic footwear production with dedicated volume allocations.
- Electrical Equipment Producers:Encapsulation and cable jacketing applications demand thermal stability and dielectric properties. These specifications command premium positioning over commodity foam grades.
Construction materials hold installed capacity. Furniture fabricators are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive seating manufacturers in Germany and China drive procurement concentration for high-resilience foam intermediates, while construction materials producers across multiple jurisdictions respond to tightening emission standards with reformulated graft polyol specifications.
Germany
Electric vehicle platform mandates from BMW and Mercedes-Benz accelerate demand for load-bearing foam systems in premium seating applications. ECHA's REACH registration requirements impose full substance characterization obligations on SAN-grafted polyols above one tonne annually. The Ludwigshafen chemical complex anchors captive production networks serving automotive interior supply chains with dedicated specialty polyether backbone capacity.
China
Domestic appliance and construction markets absorb expanding volumes from integrated polyol-to-foam operations along the East China manufacturing corridor. The Ministry of Ecology and Environment enforces GB standards limiting VOC emissions from polyurethane foam products, forcing reformulation of conventional systems. Ningbo operations extend into high-performance CASE applications as Wanhua Chemical consolidates regional volume leadership.
United States
Flexible foam compounders serving mattress and furniture markets specify graft polyols with tunable particle size distribution for consistent cell structure control. EPA regulations under the Toxic Substances Control Act govern styrene and acrylonitrile monomer handling in domestic production facilities. The Freeport, Texas manufacturing complex competes on scale in conventional flexible foam feedstocks for North American distribution.
Japan
Electronics encapsulation and precision coating applications demand aliphatic polyol grades with UV stability and color retention specifications. METI oversees chemical substance management frameworks influencing import and manufacturing compliance structures. Osaka-based formulators serve electrical equipment producers with dedicated volume allocations for moisture-cure sealant systems requiring extended pot life.
Saudi Arabia
Construction materials producers specify rigid aromatic polyol systems for flame-retardant building envelope applications in high-temperature climates. SAMR-aligned standards through bilateral recognition frameworks affect import certification pathways for polyurethane intermediates. The Eastern Province petrochemical corridor develops downstream conversion capacity linking cracker outputs to specialty polyol derivatives for regional insulation board manufacturers.
Global Graft Polyols Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Integrated petrochemical giants with captive backbones command volume positions in automotive and construction feedstocks. Mid-scale formulation houses occupy specialty niches requiring polymerization control expertise. Technology licensors and catalyst suppliers enable third-party grafting capacity without direct material production. Dominant competitive moves include backward integration into polyether backbone production and strategic partnerships with automotive Tier 1 seating suppliers for dedicated volume allocations.
Among diversified chemical conglomerates, BASF, Dow, and Wanhua Chemical exemplify distinct geographic anchoring strategies. Ludwigshafen-based BASF represents European integrated production archetypes with captive specialty backbone supply. Midland-based Dow occupies North American scale positions in conventional flexible foam intermediates. Ningbo-headquartered Wanhua Chemical anchors Asia-Pacific volume concentration with extension into high-performance application segments. Each exemplifies how regional production gravity shapes competitive positioning without converging on identical capability profiles.
| Leading Market Players |
|---|
| BASF |
| Dow |
| Mitsui Chemicals |
| Evonik |
| Wanhua Chemical |
| Huntsman |
| SABIC |
| Repsol |
| Jilin Shenhua Group |
| Others |
Supply & Pricing Matrix
East China's chemical manufacturing corridor concentrates polyether backbone production, anchoring margin pools with automotive Tier 1 seating suppliers in Germany and China who negotiate dedicated volume allocations. SAN monomer cost volatility propagates through formulation houses unable to index contracts to crude derivatives, compressing returns in mid-tier flexible foam feedstocks.
Pricing Analysis
Cost-plus contracts with styrene-acrylonitrile indexation dominate procurement between integrated petrochemical producers and automotive seating compounders. Price differentiation rests on graft efficiency grades and REACH registration status, with fully-characterized SAN-grafted polyols commanding premiums over commodity alternatives. Pricing pressure intensifies as China's GB standard enforcement forces simultaneous reformulation for VOC compliance, stretching R&D budgets across smaller formulation houses. Volume-scale buyers in East China's integrated polyol-to-foam networks exhibit lowest price sensitivity, while independent furniture fabricators in fragmented regional markets face acute margin compression.
Supply Chain Analysis
Upstream propylene oxide and ethylene oxide feedstocks draw from integrated petrochemical complexes in China, Germany, and the United States. Styrene and acrylonitrile monomers, specialty polyether backbones, and controlled polymerization catalysts constitute critical input dependencies. Single-source vulnerability concentrates in high-performance CASE application grades where Wanhua Chemical and BASF maintain captive backbone production. Distribution runs through direct sourcing relationships with automotive Tier 1 suppliers, displacing distributor-mediated transactions in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Graft polyol penetration in CASE applications represents early-cycle expansion, with coatings and elastomer formulators only now adopting load-bearing polyurethane systems for abrasion-resistant industrial maintenance.
For Market Incumbents: Entrench position through backward integration into specialty polyether backbone production and captive supply commitments to BMW and Mercedes-Benz seating platforms. BASF's Ludwigshafen model demonstrates how integrated sites defend against SAN cost volatility. Prioritize REACH registration lock-in to raise compliance barriers for emerging formulation houses. For New Entrants and Emerging Players: Saudi Arabia's Eastern Province petrochemical corridor offers underpenetrated access to rigid aromatic polyol demand for flame-retardant building envelope applications. Target construction materials producers serving high-temperature climates with localized formulation support. Enter through technology licensing partnerships with catalyst suppliers to bypass capital-intensive grafting capacity buildout. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-scale formulation houses in Europe struggling under REACH registration burden consolidation. Five-to-ten year viability hinges on successful CASE application diversification beyond commoditized flexible foam feedstocks. Monitor ECHA hazard reclassification timelines for grafted styrene content as inflection indicator for additional testing obligation costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyether Backbones | BASF's Ludwigshafen captive supply model insulates automotive seating compounders from SAN monomer volatility. |
| Long-term Supply Agreement with Tier 1 Seating Suppliers | Mercedes-Benz and BMW procurement consolidation favors producers with dedicated volume allocation commitments. |
| Green Manufacturing Transition | EU Green Deal circular economy mandates create regulatory tailwinds for bio-based polyether backbone development. |
| Joint Venture in East China Chemical Corridor | Wanhua Chemical's Ningbo operations demonstrate how integrated polyol-to-foam networks reduce logistics costs. |
| Technology Licensing for Controlled Polymerization | Specialist catalyst suppliers enable third-party grafting capacity without direct material production capital requirements. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers at graft polyol production facilities, procurement leads at automotive Tier 1 seating suppliers, and technical R&D directors at polyurethane foam compounders; and secondary validation through customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings from diversified chemical conglomerates. Bottom-up volume modeling across product type, technology, application, and end-use industry segments was triangulated against top-down macroeconomic indicators.
Forecast inputs considered capacity utilization rates at named production complexes, REACH and GB standard implementation timelines, and electric vehicle platform rollout schedules across the analysis window. Segmentation dimensions included polyol backbone chemistry, polymerization architecture, foam system application, and customer industry vertical. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory inflection points and substitution elasticity estimates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by integrated petrochemical giants or accelerated bio-based backbone commercialization would shift outcomes beyond modeled ranges. Cross-checking against ECHA substance registration databases and Chinese customs export statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Asia-Pacific Polyamide Market
Polymers & Resins
Middle East Fluoropolymer Market
Polymers & Resins
Modified Epoxy Resins Market
Polymers & Resins
Global Emulsion Polymer Market
Polymers & Resins
Water Soluble Polymers Market
Polymers & Resins
Chelating Resins Market
Polymers & Resins
Polymer Antioxidants Market
Polymers & Resins
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Polycarbonate Glazing Market
Polymers & Resins
Global Polypropylene Homopolymer (PPH) Market
Polymers & Resins
Fluorinated Polyimide Market
Polymers & Resins
Phthalonitrile Resin Market
Polymers & Resins
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Flame Retardant Thermoplastics Market
Polymers & Resins
Synthetic and Bio Thermosets Market
Polymers & Resins
Polyolefin Foam Market