
 Melamine Formaldehyde Resin Powder Market | 2026-2036
Melamine Formaldehyde Resin Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Melamine Formaldehyde Resin Powder Market Analysis
Urea-formaldehyde substitution toward melamine-based systems is shifting product economics across decorative panel applications. BASF SE leverages its European production network to sustain supply reliability for laminate producers facing stricter emission protocols. Hexion Inc. anchors North American distribution through integrated resin-to-adhesive channels. INEOS Melamines GmbH competes on technical grade purity standards demanded by electrical insulation compounders.
Melamine formaldehyde resin powder constitutes a thermosetting amino resin synthesized from melamine and formaldehyde condensation, typically yielding products with nitrogen content exceeding 66% by weight and curing temperatures between 130°C and 180°C for hardened, heat-resistant surfaces. Spray dried grades dominate volume throughput due to faster dissolution kinetics in adhesive formulations, while powder coated variants command premium positioning in automotive interior applications where surface finish uniformity is critical. Molding compounds for electrical end users represent the fastest-expanding application segment as flame-retardant specifications intensify across appliance and connector markets.
EPA TSCA Title VI, ECHA REACH restrictions on formaldehyde release, and China's GB standards for indoor air quality collectively elevate compliance costs for resin manufacturers while accelerating R&D into low-emission formulations. These regulatory pressures reshape market access thresholds, particularly for distributors serving furniture exporters to the European Union under CE-marked product requirements. Stakeholders must monitor evolving substance restriction timelines and position captive testing capabilities ahead of notified body certification bottlenecks.
Market Dynamics
EPA TSCA Title VI emission limits are compressing urea-formaldehyde substitution timelines across North American laminate production, forcing resin specification upgrades at manufacturing scale.
Growth Catalysts
- Formaldehyde emission protocols:EPA TSCA Title VI and ECHA REACH restrictions are accelerating specification shifts toward melamine-based systems in furniture and construction panels.
- Electrical insulation demand:Appliance and connector manufacturers are specifying flame-retardant molding compounds for compliance with tightened safety standards.
- Southeast Asian furniture clusters:Chinese capacity expansion is redirecting trade flows toward Vietnam and Indonesia, creating localized resin demand surges.
Market Restraints
- Formaldehyde feedstock volatility:Methanol price swings and natural gas cost pressures compress resin producer margins unpredictably.
- Chinese supply concentration:Over half of global melamine crystal capacity sits in Shandong and Sichuan provinces, exposing buyers to regional disruption risks.
- Technical curing limitations:Standard melamine formaldehyde systems require 130°C to 180°C processing temperatures, restricting adoption in heat-sensitive substrate applications.
Strategic Opportunities
- Indian laminate manufacturing:BIS certification requirements and domestic furniture production incentives are opening import substitution channels for technical-grade resin suppliers.
- Automotive interior finishing:Powder-coated melamine variants are penetrating dashboard and trim applications where surface uniformity specifications exceed traditional coating capabilities.
- EU Green Deal alignment:CE-marked product requirements and CSRD disclosure mandates are creating premium positioning for low-emission formulation producers serving furniture exporters.
Industry Challenges
- Notified body certification bottlenecks:EU CE marking timelines for construction products extend 12 to 18 months, delaying market access for reformulated low-emission grades.
- Legacy adhesive system integration:Laminate producers face production line reconfiguration costs and cure-parameter revalidation when transitioning from urea-formaldehyde to melamine-based binders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Melamine Formaldehyde Resin Powder Market |
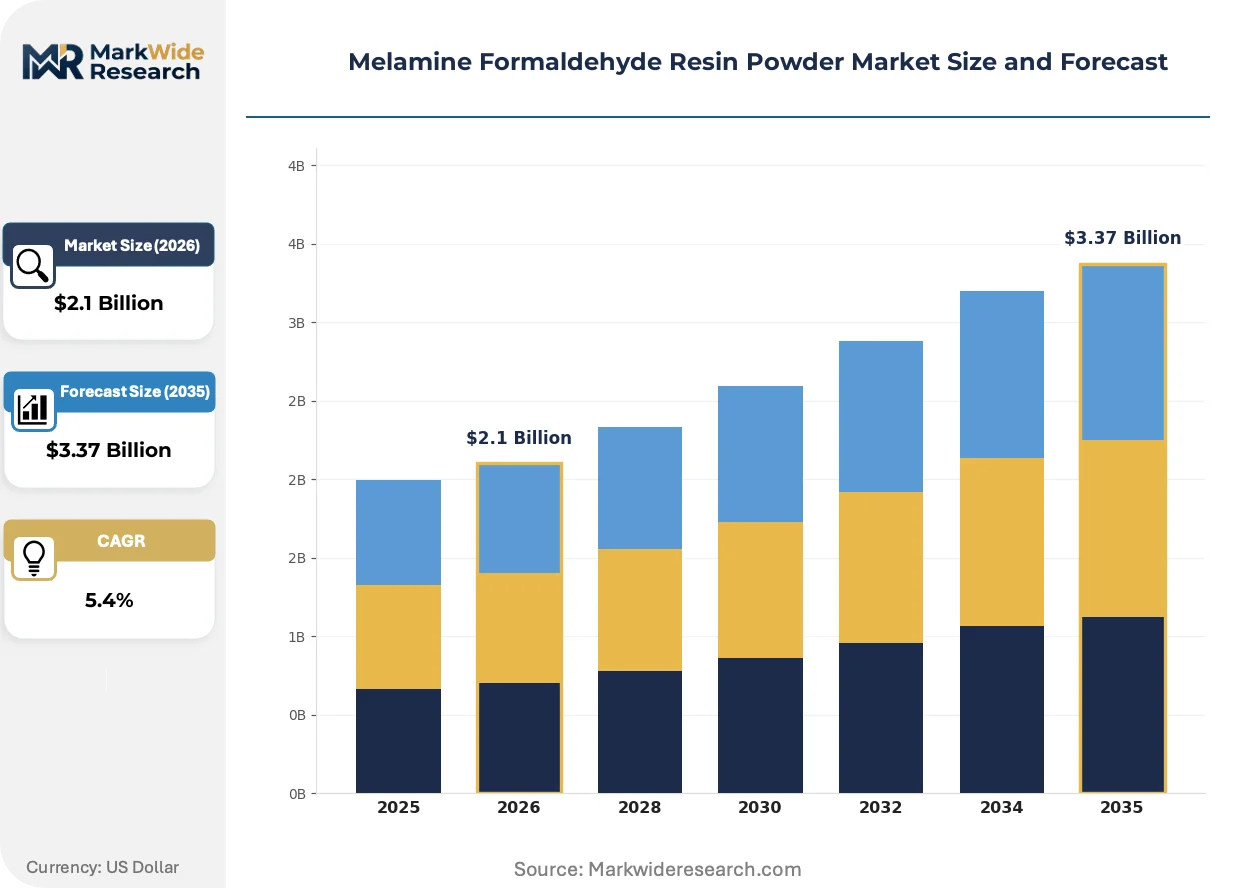
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Spray Dried, Powder Coated, Technical Grade Application: Adhesives, Coatings, Laminates, Molding Compounds End User: Construction, Automotive, Furniture, Electrical Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | SABIC, Hexza Corporation Berhad, BASF SE, Allnex Belgium S.A., INEOS Melamines GmbH, Hexion Inc., Mitsubishi Gas Chemical Company, Arclin Inc., Kronospan Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Melamine Formaldehyde Resin Powder Market Emerging Trajectories
Low-emission formulation chemistry is overtaking conventional resin specifications as the baseline for market access, with spray-dried dissolution kinetics and powder-coat surface engineering emerging as parallel technical fronts.
Spray-dried melamine formaldehyde resin powder is overtaking agglomerated grades in high-throughput adhesive operations. Laminate producers in Germany and the United States are specifying faster dissolution kinetics to compress press cycle times. This shift is enabling just-in-time resin batching and reducing working capital requirements for mid-scale panel manufacturers.
REACH formaldehyde release restrictions are tightening testing protocols for imported furniture and construction materials entering the European Union. German notified bodies are expanding laboratory capacity to handle CE marking backlog for decorative panel producers. Laminate manufacturers serving IKEA and HAY supply chains are accelerating reformulation timelines to maintain shelf placement.
Specification-driven procurement is consolidating resin supplier rosters among tier-one laminate producers. Furniture OEMs in Vietnam and Poland are reducing qualified vendor lists from twelve to four sources per resin grade. This concentration is most visible in automotive interior programs where surface finish uniformity requirements exceed 0.5 gloss unit variation across production lots.
Melamine Formaldehyde Resin Powder Market Segmentation
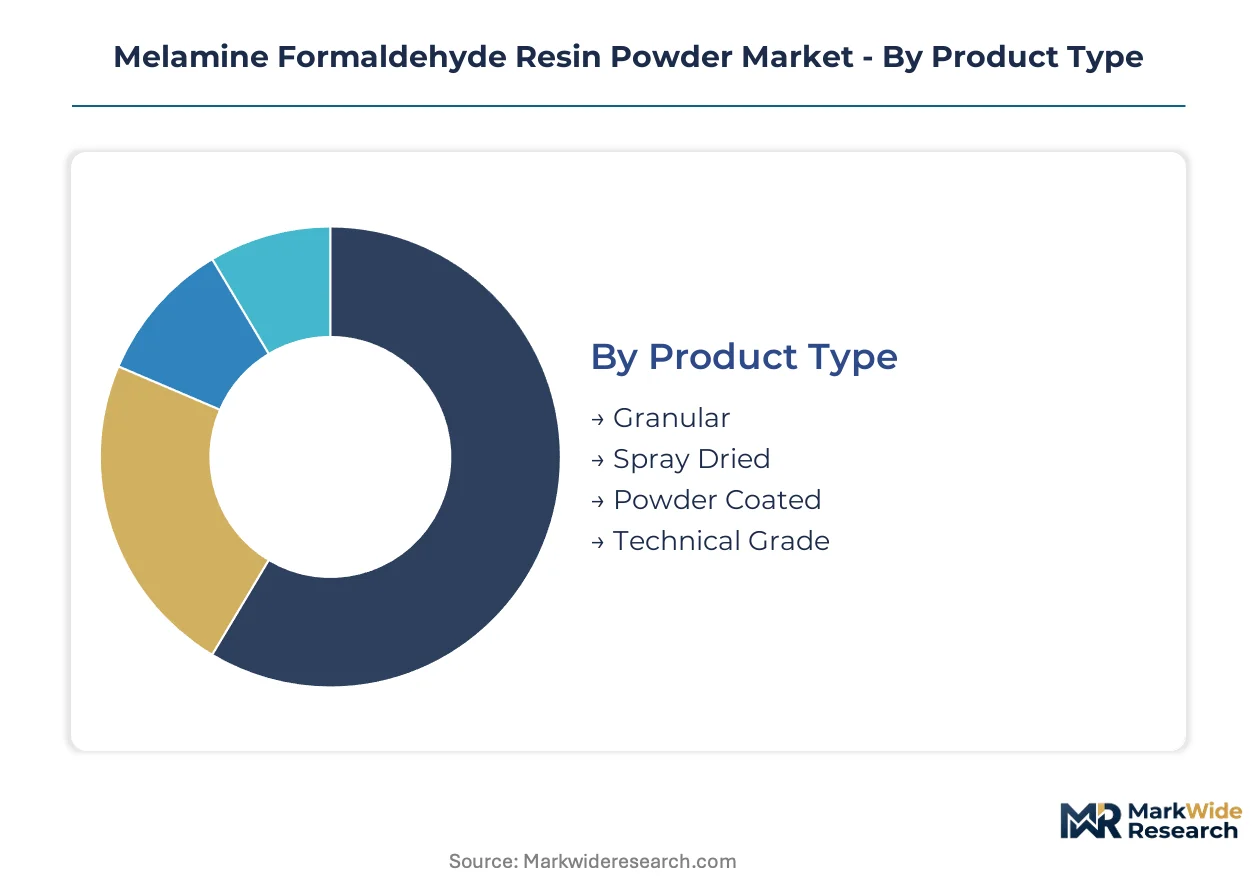
Melamine formaldehyde resin powder specifications diverge sharply across processing requirements and end-use performance thresholds. Procurement decisions hinge on dissolution kinetics, curing parameters, and emission compliance profiles rather than commodity pricing alone.
Product Type:
Particle morphology and surface engineering define processing economics and application suitability across manufacturing workflows.
- Spray Dried:Rapid dissolution kinetics enable just-in-time batching for high-throughput laminate presses in Germany and the United States. German panel manufacturers specify spray-dried grades to compress press cycle times and reduce working capital requirements. This grade dominates volume throughput due to superior flow characteristics in automated adhesive blending systems.
- Powder Coated:Surface-engineered particles deliver uniform film formation for automotive interior applications where gloss variation must stay below 0.5 units across production lots. Dashboard and trim suppliers in Germany and Poland are qualifying powder-coated variants for premium OEM programs. Heat-resistant surface finishes distinguish this grade from conventional coating alternatives.
- Granular:Slower dissolution profiles suit batch adhesive operations with longer mixing cycles and lower automation levels.
- Technical Grade:Elevated purity standards serve electrical insulation compounders requiring precise nitrogen content control above 66% by weight.
Mature deployment sits with spray-dried grades across European and North American laminate manufacturing. Newer deployment is concentrated in powder-coated variants penetrating automotive finishing specifications.
Application:
End-use performance requirements drive specification fragmentation across thermal, mechanical, and emission compliance dimensions.
- Laminates:Decorative panel producers face EPA TSCA Title VI and ECHA REACH reformulation deadlines, accelerating melamine-for-urea substitution timelines. Residential construction demand concentrates in China, Germany, and the United States as formaldehyde emission standards tighten. Press cycle optimization and surface durability requirements dominate procurement criteria.
- Molding Compounds:Flame-retardant specifications for appliance housings and electrical connectors are climbing the fastest across appliance and automotive connector markets. Compounding operations in Germany and Japan specify tight particle size distribution for injection molding consistency. Thermal stability above 150°C distinguishes melamine-based systems from alternative amino resins.
- Adhesives:Wood panel bonding applications consume standard-grade resin powder for interior-grade plywood and particleboard.
- Coatings:Surface finishing applications leverage crosslinking density for hardness and chemical resistance in industrial equipment.
Specification intensity peaks in molding compounds where safety certification requirements multiply testing protocols. Volume concentration remains in laminates serving residential construction and furniture manufacturing.
End User:
Industry-specific compliance frameworks and performance benchmarks reshape procurement patterns across downstream sectors.
- Construction:Laminate flooring and decorative panel demand tracks residential building permits and renovation cycles in China, Germany, and the United States. EPA TSCA Title VI certification requirements filter supplier rosters to qualified resin sources with documented emission testing. German notified body capacity constraints extend CE marking timelines for panel exporters.
- Furniture:IKEA and HAY supply chain qualification pressures are compressing reformulation timelines for Vietnam and Poland-based manufacturers. BIS certification requirements in India are opening import substitution channels for technical-grade suppliers. Surface finish uniformity specifications exceed 0.5 gloss unit variation across qualified vendor programs.
- Automotive:Interior trim applications specify powder-coated grades for dashboard and door panel finishing.
- Electrical:Insulation compounders demand nitrogen content precision and flame-retardant performance for connector and appliance applications.
Procurement consolidation is most advanced in furniture supply chains reducing qualified vendor lists from twelve to four sources per resin grade. Construction maintains broader supplier bases due to regional production fragmentation.
Distribution Channel:
Supply chain configuration varies with order scale, technical service requirements, and geographic proximity to manufacturing clusters.
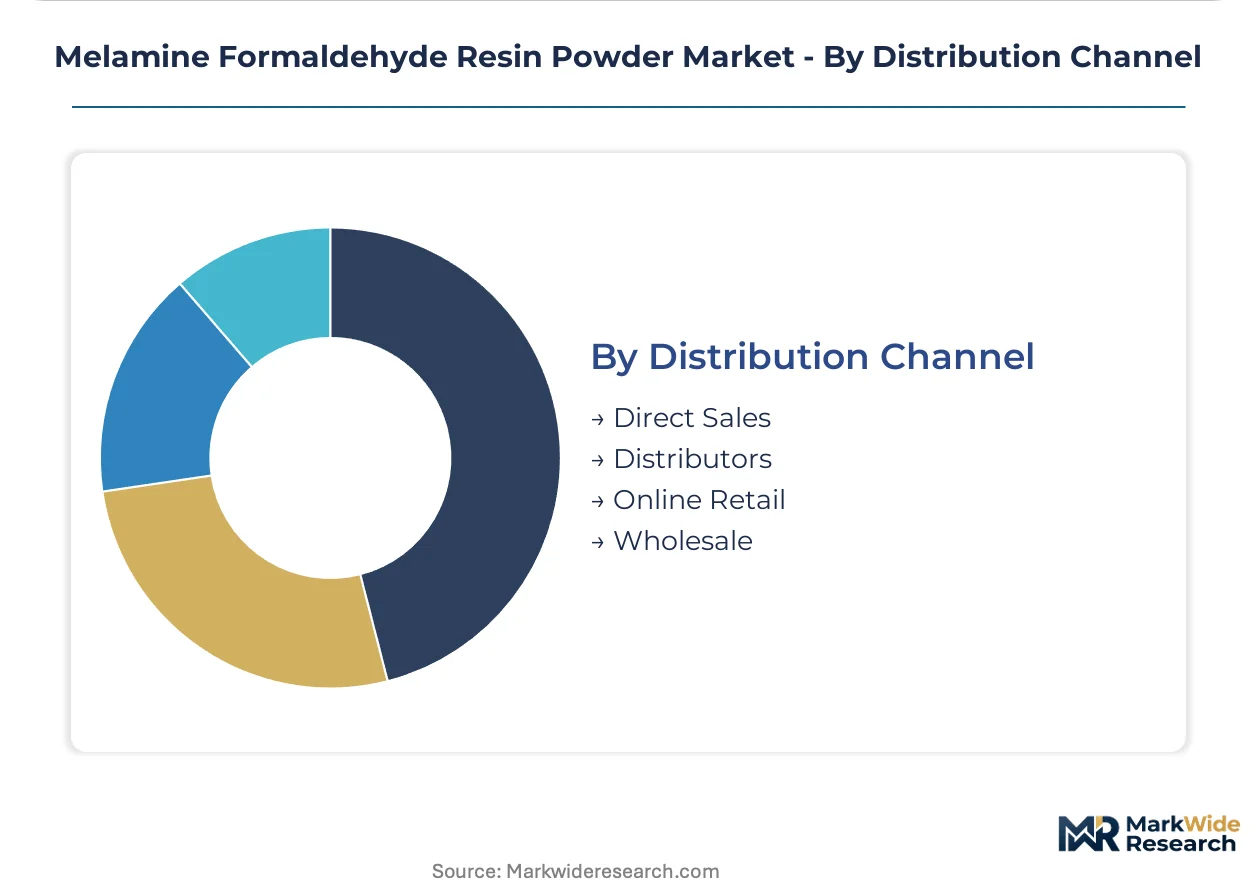
- Direct Sales:Tier-one laminate producers and automotive OEMs negotiate annual contracts with technical service provisions and joint formulation development. BASF SE and Hexion Inc. anchor direct relationships through integrated resin-to-adhesive channels. Specification-driven procurement favors direct channels for high-volume, technically demanding accounts.
- Distributors:Mid-scale panel manufacturers and regional compounders rely on distributor inventory for just-in-time delivery and smaller lot sizes. Southeast Asian furniture clusters in Vietnam and Indonesia source through distributors redirecting Chinese capacity expansion. Local technical support and customs clearance services add value beyond logistics.
- Wholesale:Standard-grade resin moves through bulk handlers serving commodity adhesive operations with limited specification requirements.
- Online Retail:Small-lot technical grade purchases for R&D and specialty compounding sample through digital channels.
Channel concentration follows customer scale and specification complexity. Direct sales capture high-value molding compound and automotive programs. Distributors serve fragmented furniture manufacturing across Southeast Asian expansion zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for melamine formaldehyde resin powder concentrates in China, Germany, and the United States, where laminate manufacturing and electrical compounding drive procurement volumes. Regulatory divergence across these markets is fragmenting formulation requirements and reshaping supplier access conditions.
China
Shandong and Sichuan provinces host over half of global melamine crystal capacity, supplying domestic laminate producers and redirecting resin powder exports toward Vietnam and Indonesia. GB standards for indoor air quality are tightening formaldehyde emission thresholds for furniture sold domestically. Ningbo and Dongguan furniture clusters are absorbing expanded resin output as manufacturers relocate from higher-cost coastal zones.
Germany
Decorative panel producers in North Rhine-Westphalia and Bavaria specify spray-dried grades to compress press cycle times and reduce working capital. ECHA REACH restrictions on formaldehyde release are accelerating reformulation timelines for CE-marked construction products. Cologne-based notified bodies are expanding laboratory capacity to handle certification backlogs from laminate exporters serving IKEA and HAY supply chains.
United States
EPA TSCA Title VI emission limits are compressing urea-formaldehyde substitution timelines across laminate production in the Southeast and Pacific Northwest. Residential construction demand tracks building permit cycles in Texas, Florida, and California. Hexion Inc. anchors North American distribution through integrated resin-to-adhesive channels serving tier-one panel manufacturers.
India
BIS certification requirements and domestic furniture production incentives are opening import substitution channels for technical-grade resin suppliers. Maharashtra and Gujarat laminate manufacturers are qualifying new resin sources to serve organized retail expansion. Mumbai-Pune industrial corridor compounders are specifying elevated purity grades for electrical insulation applications.
Japan
METI safety standards are tightening flame-retardant specifications for appliance housings and electrical connectors. Osaka and Nagoya molding compounders demand precise nitrogen content control above 66% by weight for thermal stability. Kansai-region resin distributors are consolidating qualified vendor lists as procurement patterns shift toward specification-driven sourcing.
Melamine Formaldehyde Resin Powder Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation expertise commanding premium positioning in electrical and automotive applications. The vendor base organizes into three tiers: integrated chemical conglomerates with captive melamine supply, regional resin compounders serving laminate clusters, and technical-grade specialists focused on electrical insulation purity standards. Competitive dynamics center on M&A activity consolidating distribution networks and capacity expansion projects redirecting trade flows toward Southeast Asian furniture manufacturing zones.
Within the integrated chemical tier, BASF SE leverages its European production network to sustain supply reliability for laminate producers facing stricter emission protocols. Hexion Inc. anchors North American distribution through integrated resin-to-adhesive channels. INEOS Melamines GmbH competes on technical grade purity standards demanded by electrical insulation compounders in Germany and Japan.
| Leading Market Players |
|---|
| SABIC |
| Hexza Corporation Berhad |
| BASF SE |
| Allnex Belgium S.A. |
| INEOS Melamines GmbH |
| Hexion Inc. |
| Mitsubishi Gas Chemical Company |
| Arclin Inc. |
| Kronospan Holdings |
| Others |
Supply Flow & Price Mechanics
EPA TSCA Title VI certification requirements gate qualified supply access and premium-tier pricing for resin suppliers serving North American laminate manufacturers. Buyers without documented emission testing capabilities face exclusion from tier-one procurement programs while certified producers command margin premiums.
Pricing Analysis
Volume throughput concentrates in spray-dried grades where margin compression runs deepest, while powder-coated variants retain pricing power through automotive qualification barriers. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked low-emission grades from commodity adhesive grades and technical-grade electrical compounds. Price differentiation hinges on certification tier and volume scale, with EPA TSCA Title VI and REACH-compliant grades carrying 15-25% premiums over standard formulations. Cost compression in standard grades is intensifying because Chinese capacity expansion redirects export volumes into Southeast Asian spot markets. Mid-scale panel manufacturers exhibit highest price sensitivity, whereas automotive OEMs prioritize surface finish uniformity over unit economics.
Supply Chain Analysis
India's BIS certification requirements and domestic-content mandates are reshaping sourcing patterns for Maharashtra and Gujarat laminate manufacturers. Raw material flows draw from Shandong and Sichuan melamine crystal capacity, methanol feedstocks tied to natural gas pricing, and formaldehyde supply anchored in regional chemical clusters. Single-source vulnerability concentrates in Chinese melamine crystal production, where over half of global capacity sits in two provinces exposed to regional disruption risks. Distribution runs through direct sales channels for tier-one laminate producers and automotive OEMs, with distributors serving fragmented Southeast Asian furniture clusters in Vietnam and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around specification-driven procurement, with REACH and EPA emission deadlines forcing sub-scale compounders and undifferentiated resin traders toward exit. Regulatory compliance investments are becoming the primary filter separating viable suppliers from distressed sellers.
For Market Incumbents: Deepen backward integration into melamine crystal supply to secure feedstock cost stability against methanol volatility. BASF SE and Hexion Inc. demonstrate the defensive value of captive resin-to-adhesive channels that lock in tier-one laminate accounts. Prioritize CE marking capacity expansion ahead of notified body bottlenecks to capture reformulation demand from IKEA and HAY supply chains. For New Entrants and Emerging Players: Enter via technical-grade purity specialization for electrical insulation compounders in Germany and Japan, where INEOS Melamines GmbH has proven premium positioning可行性. India's BIS certification gap offers the most penetrable geography, with Maharashtra laminate manufacturers actively qualifying new resin sources. Pursue joint formulation development agreements with automotive interior tier suppliers seeking powder-coated grade alternatives. For Investors and Strategic Acquirers: Notified body laboratory capacity expansion in Cologne is the leading indicator that CE marking bottlenecks will persist, extending premium capture windows for qualified low-emission formulation producers. Acquisition targets should concentrate on regional resin compounders with documented EPA TSCA Title VI testing capabilities and established automotive qualification records. Monitor Chinese capacity utilization rates as the inflection signal for spot price volatility and margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Melamine Crystal Supply | Captive feedstock secures margin stability against Shandong supply disruption risks. |
| CE Marking Capacity Expansion | Cologne notified body partnerships accelerate market access for REACH-compliant grades. |
| Joint Venture with Southeast Asian Distributors | Local inventory positions capture Vietnamese furniture cluster demand surges. |
| Technical Grade Purity Investment | Nitrogen content precision above 66% unlocks electrical insulation compounder premiums. |
| Long-term Supply Agreement with Tier-One Laminators | Annual contracts with press cycle optimization services reduce customer churn. |
Methodological Framework
Trade statistics from customs databases, SEC 10-K filings from chemical conglomerates, and industry association reports from ACC and Cefic formed the secondary backbone for demand modeling. Primary interviews with plant managers at German and U.S. laminate manufacturers, procurement leads at Vietnamese furniture OEMs, distribution channel partners in Southeast Asia, and technical R&D directors at electrical insulation compounders validated supply-side assumptions. Bottom-up and top-down triangulation reconciled particle-grade production estimates with end-use consumption patterns across construction and automotive segments.
Bottom-up volume builds aggregated spray-dried, powder-coated, and technical-grade shipments by application, while top-down checks cross-referenced resin consumption against laminate press capacity and molding compounder output across the analysis window. Segmentation dimensions modeled include product morphology, end-use industry, and regional regulatory cluster. CAGRs were derived from regression analysis against residential construction permits and appliance production indices, with formaldehyde emission protocol timelines serving as step-change inputs for substitution elasticity assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Chinese environmental enforcement actions or methanol price spikes. Forecasts reflect assumptions about REACH implementation timelines and EPA certification penetration rates without claiming predictive certainty. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Soil Release Polymer Market
Polymers & Resins
Soft PVC Sealing Strip Market
Polymers & Resins
Polyolefin Wax Market
Polymers & Resins
Europe Polyamide Market
Polymers & Resins
Bio-Based Epoxy Resin Market
Polymers & Resins
Modified Epoxy Resins Market
Polymers & Resins
Polypropylene and High-Impact Polystyrene Market
Polymers & Resins
Polybutene-1 Market
Polymers & Resins
Biobased Polypropylene PP Size Market
Polymers & Resins
Rosin Resin Market
Polymers & Resins
Extruded Polystyrene Market
Polymers & Resins
Global Protein a Resin Market
Polymers & Resins
South America Polymer Emulsion Market
Polymers & Resins
Global Ultra-High Molecular Weight Polyethylene Market
Polymers & Resins
China Geopolymer Market
Polymers & Resins
Starch Polymer Market