
 Global Acrylic Emulsions Market | 2026-2036
Global Acrylic Emulsions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acrylic Emulsions Market Intelligence
High-performance, low-VOC (Volatile Organic Compound) formulations are rotating the market toward premium applications and higher-value product mixes. BASF SE leverages its extensive R&D infrastructure to lead in specialty acrylics for automotive coatings. Dow Inc. competes on manufacturing scale and supply chain efficiency across multiple end-use industries. Arkema SA differentiates through its focus on advanced materials for construction and adhesives, positioning itself in high-margin segments.
Acrylic emulsions are stable dispersions of acrylic polymer microparticles in water, created through emulsion polymerization. These water-based systems serve as critical film-forming components and binders, providing adhesion, durability, and water resistance. The paints and coatings application remains the largest consumer, driven by architectural and industrial uses. Within product types, pure acrylic emulsions command higher price points due to superior weatherability, while styrene acrylics offer a cost-effective alternative for interior applications.
Regulations like Europe's REACH framework and US EPA standards for volatile organic compounds directly influence product formulation. In parallel, China's GB standards for building materials and coatings mandate specific performance and safety criteria, steering local production. Future success will depend on developing cost-effective, bio-based or recycled-content emulsions that meet evolving performance and environmental benchmarks.
Market Dynamics
The global acrylic emulsions market is defined by a structural shift toward water-based formulations, driven by stringent environmental regulations. Mandates from the US EPA on VOC emissions and directives under the EU Green Deal are compelling the paints and coatings industry to abandon solvent-based systems, making acrylic emulsions the default binder technology.
Growth Catalysts
- Chinese Construction Standards:China's GB standards for building materials create immense, non-negotiable demand for compliant acrylic emulsions in its vast architectural and infrastructure sectors.
- Automotive Refinishing Demand:The automotive refinishing industry's transition to waterborne basecoats and clearcoats to reduce VOCs pulls demand for high-performance acrylics that offer superior weatherability and adhesion.
- Cost-Effective Alternatives:The development of styrene-acrylic emulsions provides a cost-efficient option for large-volume interior paint and adhesive applications, broadening the market's addressable base.
Market Restraints
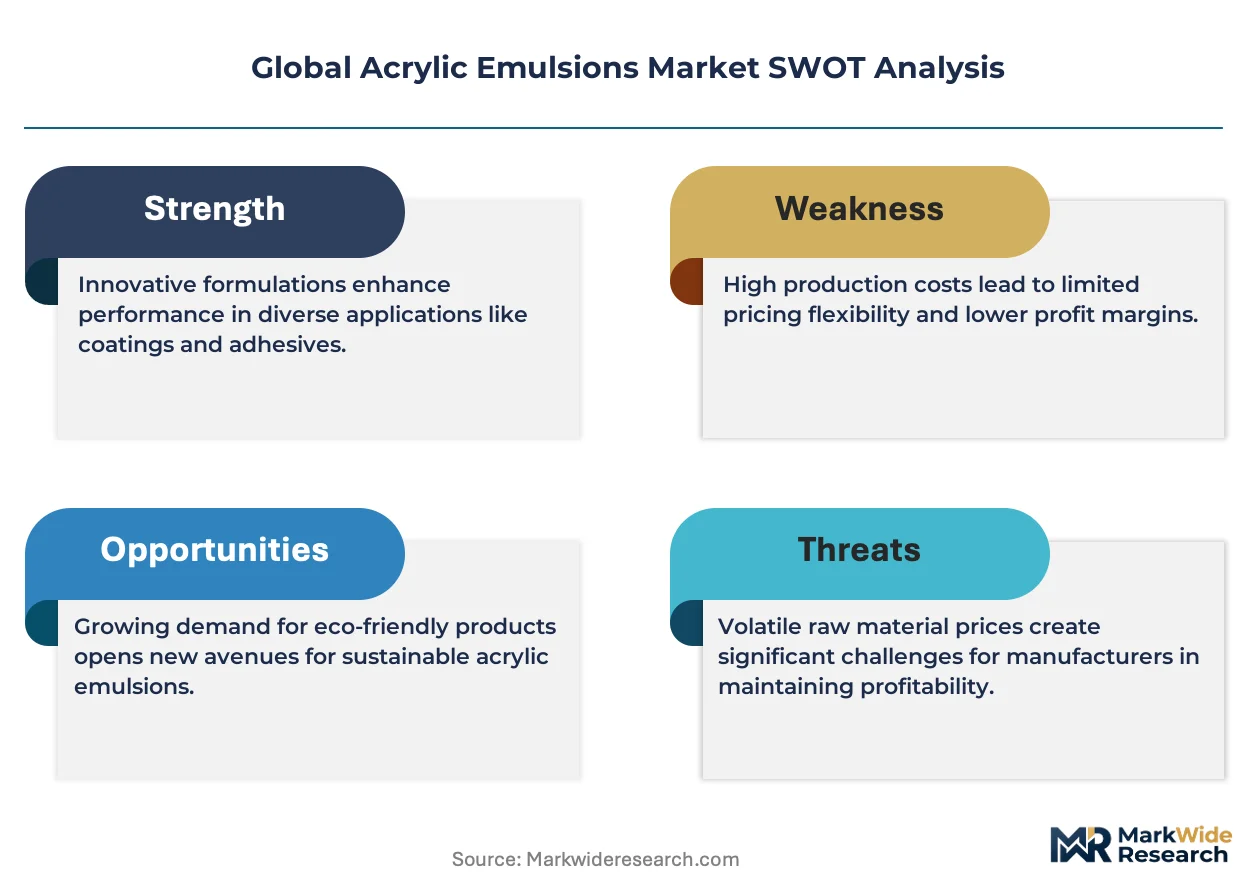
- Feedstock Price Volatility:The market is exposed to price fluctuations in key petrochemical-derived raw materials, specifically acrylic acid and styrene monomers, which can compress manufacturer margins.
- Performance Gaps in Industrial Uses:In certain heavy-duty industrial applications, water-based acrylic emulsions still struggle to match the extreme chemical and abrasion resistance of traditional solvent-borne epoxy or polyurethane systems.
- Substitution from Other Chemistries:In lower-end applications like interior wall paints and some adhesives, acrylic emulsions face competition from other water-based binders like vinyl acetate ethylene (VAE) emulsions, which can offer a lower cost basis.
Strategic Opportunities
- Bio-Based Formulations:Developing emulsions from bio-based or recycled monomers presents a significant opportunity to meet corporate sustainability mandates and command a premium with environmentally conscious customers.
- Functional Coating Additives:Incorporating nanomaterials or specialty additives to create functional acrylic emulsions for self-cleaning, anti-microbial, or thermal insulating coatings opens new high-margin segments.
- Expansion in Southeast Asia:Rapid urbanization and infrastructure development in countries like Vietnam and Indonesia create new growth fronts for architectural coatings, where water-based systems are gaining traction.
Industry Challenges
- Complex Regulatory Compliance:Formulators face the operational challenge of ensuring a single product can meet a complex web of disparate international standards, including Europe's REACH, US EPA rules, and China's GB standards.
- Formulation Expertise Scarcity:A persistent shortage of polymer chemists and technicians with deep expertise in developing high-performance, water-based systems hinders innovation and slows the replacement of solvent-borne products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acrylic Emulsions Market |
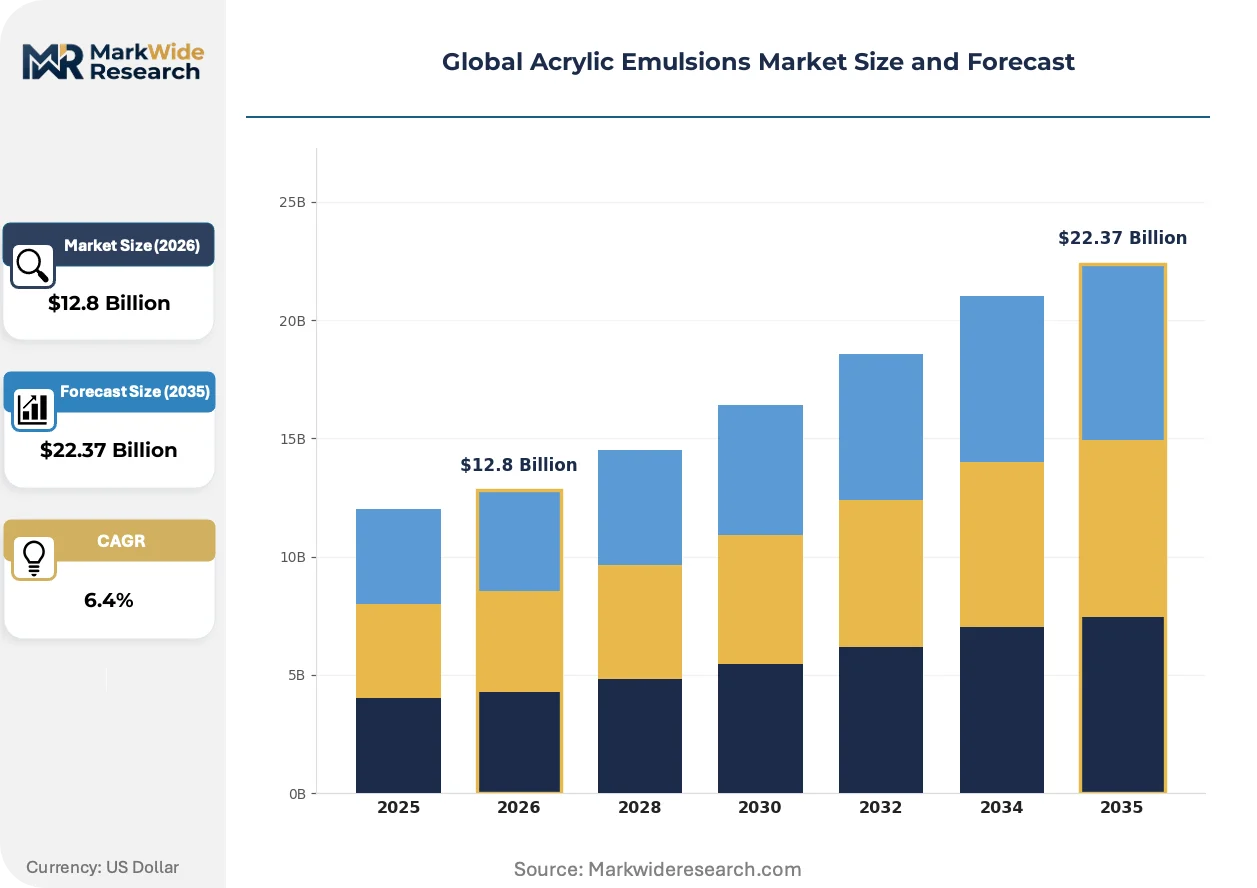
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Styrene Acrylic, Pure Acrylic, Vinyl Acrylic, Ethylene Acrylic, Others Application: Adhesives, Textile Finishing, Paints & Coatings, Paper Coating, Construction Chemicals, Leather Finishing End User Industry: Building & Infrastructure, Textile Manufacturing, Packaging, Automotive Components, Household Products Packaging Type: Drums, Bulk Containers, Bags, Totes |
| Companies Covered | BASF SE, Dow Inc., Arkema SA, Synthomer PLC, Celanese Corporation, Lubrizol Corporation, DIC Corporation, Mitsubishi Chemical Corporation, AkzoNobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acrylic Emulsions Market Strategic Shifts & Innovations
Innovation in the acrylic emulsions market is centered on achieving higher performance within the constraints of environmental compliance. The primary focus is on developing formulations that enhance durability, adhesion, and water resistance while simultaneously reducing VOC content and overall environmental footprint, responding directly to regulatory pressures and end-user demands.
Specialty co-polymers and functional monomers are being engineered to deliver specific performance attributes like enhanced UV stability or improved dirt pick-up resistance. Manufacturers of premium exterior architectural coatings and automotive finishes are rapidly adopting these advanced emulsion technologies. This targeted functionalization is fragmenting the once-monolithic market for pure acrylics into a collection of application-specific, higher-value product categories.
Europe's REACH framework continuously tightens restrictions on certain monomers and additives used in emulsion polymerization, forcing ongoing reformulation efforts. This regulatory pressure directly incentivizes research into safer, more sustainable chemical building blocks and production processes. The adhesives and sealants segment is particularly impacted, needing to validate new formulations without compromising bond strength or application properties.
A significant change in buying behavior is evident as large-scale paint and coatings producers demand greater transparency into the lifecycle impact of their raw materials. This trend is marginalizing suppliers who compete solely on price, favoring emulsion manufacturers who can provide certified Environmental Product Declarations (EPDs). This shift is most pronounced in the North American and European architectural coatings markets.
Global Acrylic Emulsions Market Segmentation
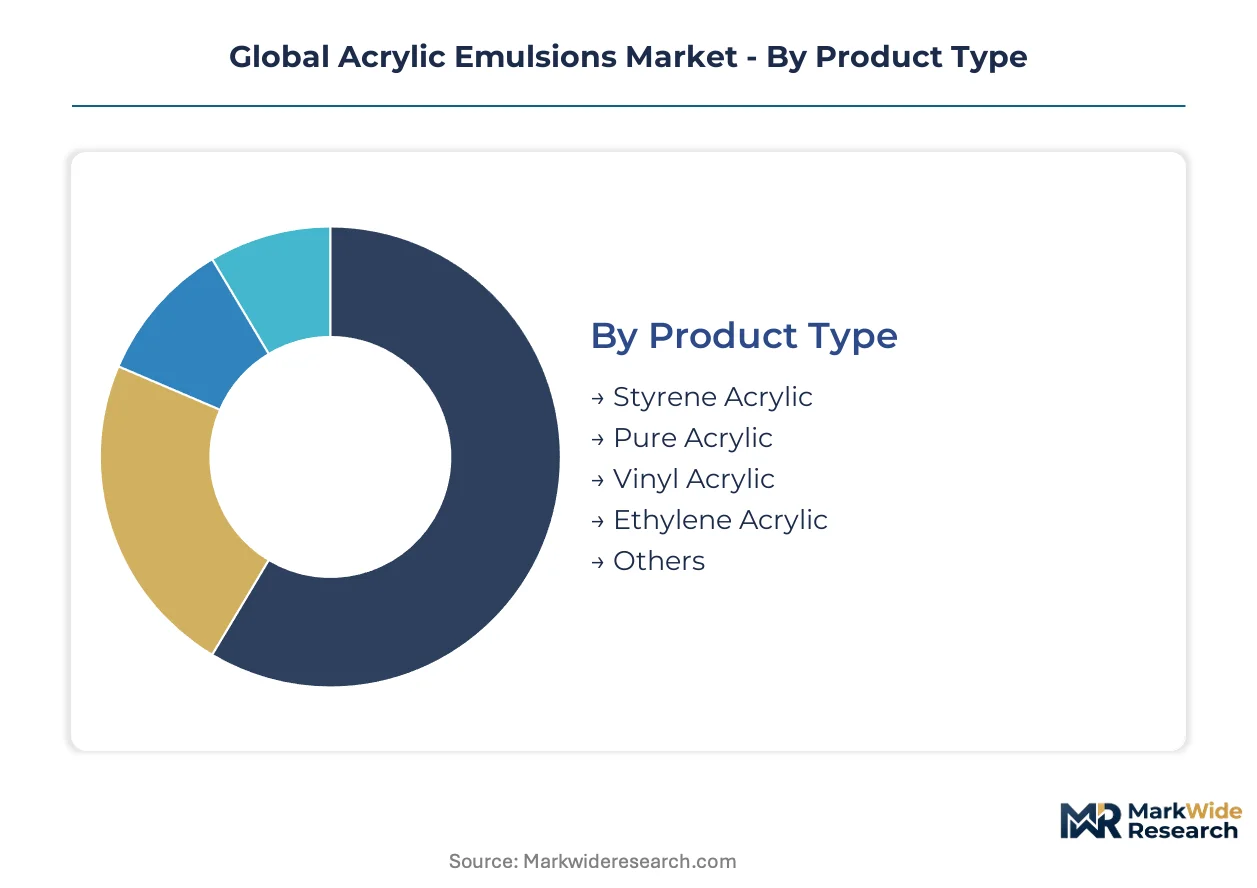
The acrylic emulsions market categorizes by product chemistry, application, and end-use industries. This segmentation highlights the diverse performance requirements and regulatory pressures influencing material selection. Understanding these distinctions is crucial for manufacturers to tailor formulations and optimize supply chains.
Product Type:
Regulatory compliance often dictates the selection of specific acrylic emulsion product types, influencing their adoption across various industries.
- Styrene Acrylic:These emulsions combine styrene and acrylic monomers, offering a cost-effective solution with good adhesion and water resistance. Demand concentrates in interior architectural paints and lower-cost adhesive formulations, driven by broad applicability.
- Pure Acrylic:Composed solely of acrylic monomers, these emulsions deliver superior weatherability, UV resistance, and durability for demanding applications. Demand concentrates in premium exterior architectural coatings and high-performance automotive finishes, driven by stringent performance requirements.
- Vinyl Acrylic:Vinyl acrylic emulsions offer a balanced performance profile and cost-effectiveness for architectural coatings and sealants.
- Ethylene Acrylic:Ethylene acrylic emulsions provide flexibility and adhesion, finding use in textile binders and non-woven applications.
- Others:This category encompasses specialized co-polymers and functional monomers designed for niche performance attributes.
Established volume favors Styrene Acrylic; emerging adoption favors advanced pure acrylic formulations.
Application:
The diverse application landscape for acrylic emulsions reflects their versatility as binders and film-forming components.
- Paints & Coatings:Acrylic emulsions serve as critical binders for a wide range of architectural, industrial, and specialty paints and coatings. Demand concentrates in the architectural and automotive sectors, driven by the global shift towards water-based systems and VOC reduction mandates.
- Adhesives:These emulsions provide strong bonding capabilities for various substrates, including paper, wood, and plastics, across diverse industries. Demand concentrates in packaging and construction, driven by the need for durable and environmentally compliant bonding solutions.
- Textile Finishing:Textile finishing utilizes acrylic emulsions for improved hand, durability, and printability in fabric treatments.
- Paper Coating:Paper coating applications benefit from acrylic emulsions for enhanced gloss, print receptivity, and water resistance.
- Construction Chemicals:Construction chemicals incorporate acrylic emulsions for improved mortar flexibility, concrete protection, and sealant performance.
- Leather Finishing:Leather finishing employs acrylic emulsions to impart durability, flexibility, and aesthetic appeal to leather products.
Paints & Coatings maintains the largest volume, with Construction Chemicals gaining share fastest driven by infrastructure projects.
End User Industry:
Significant volume demand for acrylic emulsions originates from industries with extensive manufacturing and construction activities.
- Building & Infrastructure:This sector utilizes acrylic emulsions in architectural coatings, sealants, concrete admixtures, and roofing materials. Demand concentrates heavily in China and Southeast Asia, driven by rapid urbanization and stringent local GB standards for building materials.
- Automotive Components:Acrylic emulsions are integral to automotive coatings, primers, clearcoats, and interior trim adhesives. Demand concentrates in both automotive OEM and refinishing markets, driven by the industry's transition to waterborne systems and performance requirements.
- Textile Manufacturing:Textile manufacturing integrates acrylic emulsions for fabric binders, non-wovens, and specialized coatings.
- Packaging:Packaging applications leverage acrylic emulsions for barrier coatings, adhesives, and print finishes on various substrates.
- Household Products:Household products utilize acrylic emulsions in formulations for floor polishes, detergents, and consumer adhesives.
Building & Infrastructure accounts for the largest consumption, while Automotive Components command higher value due to specialized performance needs.
Packaging Type:
The choice of packaging for acrylic emulsions directly impacts logistics efficiency and suitability for various customer scales.
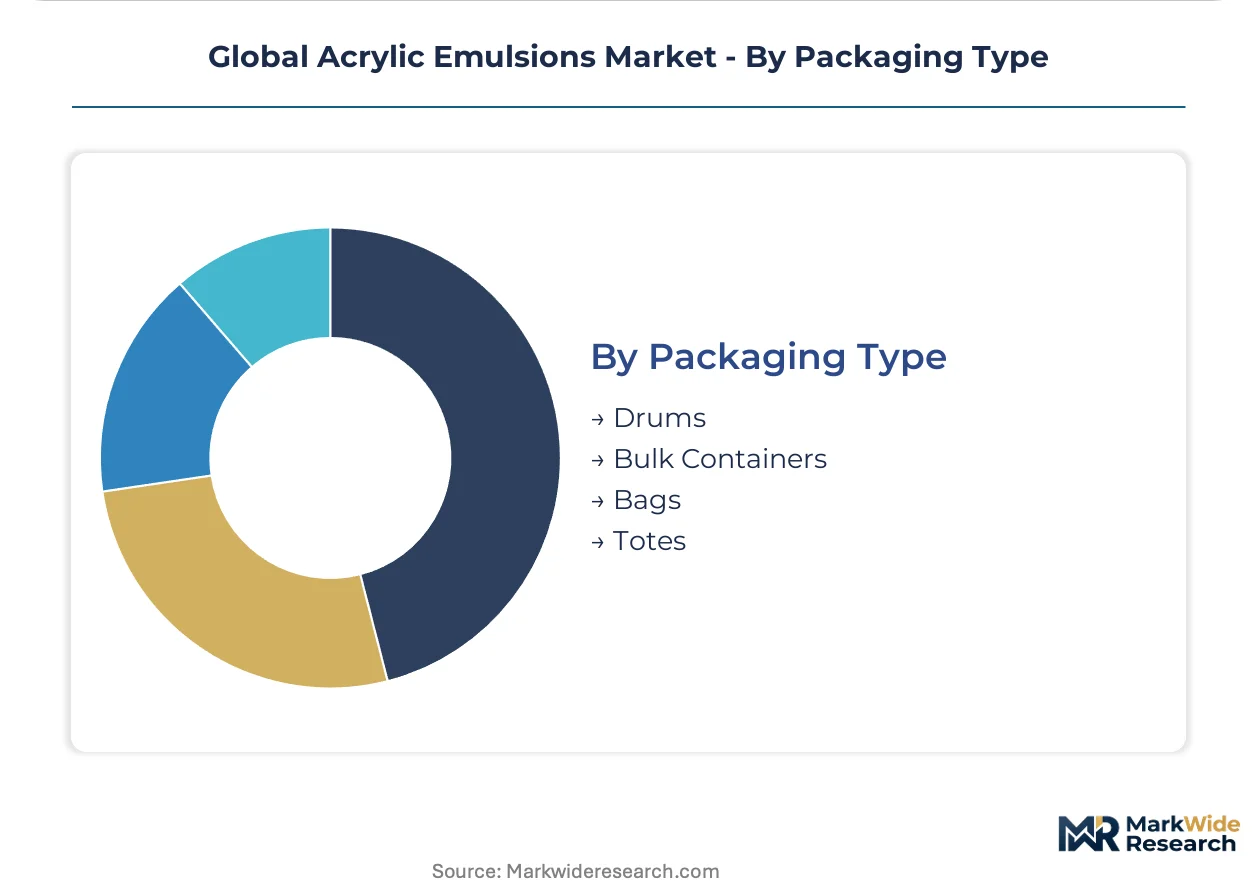
- Bulk Containers:These large-capacity vessels facilitate industrial-scale delivery, minimizing handling and transportation costs for high-volume users. Demand concentrates among large paint manufacturers and major construction chemical producers, driven by economic efficiency.
- Drums:Standard 200-liter drums serve as a common industrial packaging solution for moderate volumes of acrylic emulsions. Demand concentrates among mid-sized manufacturers and distributors, driven by ease of handling and storage flexibility.
- Bags:Bags are used for dry powder acrylic polymers or small-batch liquid formulations, offering convenience for specific applications.
- Totes:Totes provide an intermediate volume solution between drums and bulk containers, suitable for flexible industrial deliveries.
Bulk Containers dominate for large-scale industrial users, while Drums cater to a broader range of mid-volume customers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentration of acrylic emulsion production and consumption is pronounced in regions undergoing significant industrialization and infrastructure development. This geographic clustering reflects both raw material availability and proximity to major end-use markets. Regulatory landscapes also play a substantial role in shaping regional demand patterns for these critical binders.
China
China's vast building and infrastructure projects create immense demand for compliant acrylic emulsions. The country's GB standards for building materials mandate specific performance and safety criteria, steering local production. Major industrial hubs like the Yangtze River Delta actively develop and consume water-based coatings for urban development.
United States
The United States market for acrylic emulsions is propelled by stringent environmental regulations, particularly US EPA rules on VOC emissions. This regulatory pressure drives the shift towards water-based architectural and industrial coatings. Chemical manufacturing clusters in Texas and Louisiana focus on feedstock supply and emulsion production.
Germany
Germany's demand for high-performance acrylic emulsions originates from its advanced automotive and specialty coatings sectors. Directives under the EU Green Deal compel manufacturers to adopt low-VOC formulations. The Rhine-Ruhr region, a major chemical industry hub, innovates in bio-based and sustainable emulsion technologies.
India
India's rapid urbanization and infrastructure development drive significant demand for architectural coatings and construction chemicals. Government initiatives promoting sustainable building practices influence material selection. Industrial zones around Mumbai and Chennai are expanding production capacities for water-based paint binders.
Vietnam
Vietnam's expanding construction sector and growing manufacturing base represent a key growth front for acrylic emulsions in Southeast Asia. The country's evolving environmental policies are gradually encouraging the adoption of water-based systems. Urban centers like Ho Chi Minh City experience rising demand for modern architectural finishes.
Global Acrylic Emulsions Market Key Industry Players
Concentration sits with integrated chemical conglomerates that leverage extensive R&D and global supply chains. The market exhibits a tiered structure, with large multinational players dominating premium segments and numerous regional manufacturers competing on cost-effectiveness. Key strategic archetypes include specialty innovators, scale-driven producers, and regional niche providers. These entities primarily engage in portfolio diversification and strategic partnerships to expand their market reach and technological capabilities, alongside targeted capacity expansions.
Among global chemical giants, BASF SE represents a leader in specialty acrylics, leveraging its extensive research and development infrastructure for advanced formulations. Dow Inc., a major US-based chemical company, exemplifies a scale-driven producer, competing on manufacturing efficiency and broad supply chain reach across multiple end-use industries. Arkema SA, a French multinational, occupies a position focused on advanced materials, differentiating through specialized acrylic emulsions for construction and adhesives in high-margin segments. These major players anchor the market's innovation and production capacity, influencing technological trajectories and market standards.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Arkema SA |
| Synthomer PLC |
| Celanese Corporation |
| Lubrizol Corporation |
| DIC Corporation |
| Mitsubishi Chemical Corporation |
| AkzoNobel N.V. |
Cost & Logistics Intelligence
Long-term supply agreements for key raw materials like acrylic acid and styrene monomer lock in both supply access and price visibility for major acrylic emulsion producers. This contractual stability helps mitigate the impact of inherent commodity price volatility within the petrochemical sector.
Pricing Analysis
Europe's REACH framework dictates the pricing tier structure for specialty acrylic emulsions, particularly for formulations requiring specific monomer exclusions. The dominant pricing model is a hybrid of contract-based long-term offtake and transactional spot purchases for smaller volumes. Price differentiation stems from quality grade, with pure acrylics commanding higher value, and certified compliance with environmental standards like US EPA rules. Cost compression in standard styrene acrylic grades is intensifying due to competition from vinyl acetate ethylene (VAE) emulsions. Mid-sized architectural paint manufacturers exhibit the most price sensitivity, while automotive OEM suppliers demonstrate the least.
Supply Chain Analysis
Container availability and port congestion on key Asia-Europe trade lanes impact inbound logistics costs for acrylic emulsion raw materials. Geographic supply concentration for critical feedstocks like acrylic acid primarily centers in China, the United States, and Germany. The market relies heavily on petrochemical-derived raw materials, including acrylic acid and styrene monomers, making commodity price volatility a structural supply chain risk. Distribution runs through direct sales channels to large-scale manufacturers and through regional distributors for mid-sized and specialized end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acrylic emulsions market is experiencing a significant buyer-power shift, driven by consolidation among large paint and coatings producers.
For Market Incumbents:Compound R&D investments into high-performance, bio-based acrylic emulsions to counter the threat of tightening environmental regulations. Deepen vertical integration into specialty monomers to mitigate feedstock price volatility and secure supply. Invest in certified Environmental Product Declarations (EPDs) to meet evolving procurement demands from large architectural coatings customers. This focus helps defend against substitution from other chemistries like VAE emulsions.
For New Entrants and Emerging Players:Technical support gaps for integrating advanced functional additives present an opportunity for new entrants. Target niche construction chemical applications in rapidly urbanizing regions like Southeast Asia, where specialized performance is valued. Focus on offering bespoke formulation expertise alongside products to penetrate segments underserved by larger, scale-focused incumbents. Providing tailored solutions for specific performance attributes, such as anti-microbial or self-cleaning properties, can create market white space.
For Investors and Strategic Acquirers:Mid-sized specialty chemical companies with proprietary bio-based emulsion technologies represent attractive acquisition targets. The long-term viability of the sector remains strong for players aligned with sustainability trends over the next decade. Investors should prioritize targets demonstrating robust intellectual property in low-VOC and recycled-content formulations. The accelerated adoption of certified Environmental Product Declarations (EPDs) in architectural coatings serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Addresses rising demand from rapid urbanization and infrastructure development in Vietnam and India. |
| Backward Integration into Specialty Monomers | Secures critical raw material supply and mitigates price volatility for advanced formulations. |
| Green Manufacturing Transition | Aligns production processes with stringent environmental regulations and corporate sustainability mandates. |
| Long-term Supply Agreements with Bio-Monomer Producers | Ensures access to sustainable feedstocks for developing next-generation emulsions. |
| Joint Venture for Functional Coating Additives | Accelerates innovation in high-margin segments like self-cleaning or thermal insulating coatings. |
Research Approach
Operator-level perspectives from R&D directors, procurement leads, plant managers, and sustainability officers anchored the qualitative base for this analysis. Primary interviews were conducted with industry stakeholders across the value chain, complemented by secondary validation from industry association reports, patent filings, corporate financial disclosures, and trade statistics. This approach allowed for bottom-up and top-down triangulation of market data.
Sensitivity analysis was applied to key market variables, enabling scenario-based projections across the analysis window. The analytical framework modeled market dynamics across segmentation dimensions including product chemistry, application, end-use industry, and regional regulatory adherence. Compound annual growth rates were derived from historical data and projected market drivers, with petrochemical feedstock prices and regional construction spending serving as key forecast inputs.
Forecasts assume regulatory continuity in EU Green Deal directives, US EPA rules, and China GB standards; material policy shifts would require re-modeling. The analysis reflects assumptions regarding technological advancements and market adoption rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polyanionic Cellulose (PAC) Market
Polymers & Resins
Polymer Modifiers Market
Polymers & Resins
Global Blow Molding Resins Market
Polymers & Resins
Transparent Polyamides Market
Polymers & Resins
Poly (Butylene Adipate-Co-Terephthalate) Market
Polymers & Resins
Europe Fluoropolymer Market
Polymers & Resins
Polylactic Acid Market
Polymers & Resins
Bio-Based Polycarbonate Market
Polymers & Resins
Polymer Excipients Market
Polymers & Resins
Poly Alpha Olefin (PAO) Market
Polymers & Resins
South America Engineering Plastics Market
Polymers & Resins
Basic Methacrylate Copolymer Market
Polymers & Resins
UV Cure Resins Market
Polymers & Resins
Fire Resins Market
Polymers & Resins
Global Fluoropolymer Market
Polymers & Resins
Asia-Pacific Flooring Resins Market