
 Marine Anti Fouling Coatings Market | 2026-2036
Marine Anti Fouling Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Anti Fouling Coatings Market Intelligence
REACH is restructuring compliance costs across European supply chains, forcing reformulation investments that favor established producers with in-house toxicology labs. Akzo Nobel N.V. leverages its Rotterdam R&D campus to fast-track copper-free biocide alternatives. Hempel A/S anchors Nordic market share through deep relationships with Maersk and other Copenhagen-headquartered fleet operators. Jotun A/S dominates Southeast Asian shipyard supply via localized manufacturing in Korea and Vietnam.
Marine anti fouling coatings are specialized protective layers applied to submerged hull surfaces, typically incorporating copper oxide, zinc pyrithione, or silicone-based foul-release polymers to prevent biofouling accumulation. These formulations reduce hydrodynamic drag, cutting fuel consumption by maintaining smooth surface topology across saltwater exposure cycles. Biocidal product types still occupy the largest revenue pool, though non-biocidal segments are gaining fastest as operators pre-empt regulatory phase-outs. Water-based formulations lead environmental positioning, while solvent-based systems sustain share in deep-sea and ice-class applications where film durability requirements remain stringent.
EMA and ECHA jointly govern biocide authorization timelines across Europe, extending product registration cycles and raising capital barriers for new entrants. IMO's Anti-Fouling Systems Convention shapes global baseline standards, with member states incorporating treaty obligations into port-state control inspection protocols. Stakeholders must monitor regulatory divergence between EU hazard-classification expansions and Asia-Pacific enforcement gaps that create competitive arbitrage opportunities for formulation sourcing.
Market Dynamics
IMO's Anti-Fouling Systems Convention is compressing biocide authorization timelines, forcing reformulation cycles that favor producers with captive toxicology infrastructure and integrated hull-performance testing capabilities.
Growth Catalysts
- Fleet renewal mandates:Commercial vessel operators face escalating fuel-efficiency targets under EU Green Deal shipping provisions, accelerating hull coating replacement cycles in European-flagged fleets.
- REACH biocide restrictions:ECHA's accelerating hazard reclassifications are eliminating legacy copper-heavy formulations, creating replacement demand for copper-free alternatives in North Sea and Baltic trade routes.
- Silicone foul-release chemistry:Advanced polydimethylsiloxane-based systems now deliver drag-reduction performance competitive with biocidal coatings, penetrating cruise and yacht segments where speed optimization commands premium positioning.
Market Restraints
- Copper price volatility:Raw material exposure to London Metal Exchange copper fluctuations squeezes margin predictability for conventional biocidal product lines.
- Korean supply concentration:Deep-sea solvent-based formulation capacity clusters around Ulsan and Geoje shipyard corridors, creating single-source vulnerability for ice-class coating procurement.
- Film durability limitations:Water-based systems fail to meet mechanical abrasion standards for polar-class hulls operating in ice-infested waters, constraining environmental transition in Arctic shipping lanes.
Strategic Opportunities
- Brazilian offshore expansion:Petrobras pre-salt development and local content requirements are opening dedicated coating specification channels for FPSO newbuild programs.
- Remote hull monitoring integration:Convergence of ultrasonic fouling sensors with predictive maintenance platforms enables condition-based recoating contracts, shifting revenue from product to service.
- Indian shipyard scaling:Cochin Shipyard and Mazagon Dock expansion under PLI scheme incentives creates unserved demand for localized technical service presence.
Industry Challenges
- Formulation toxicology expertise scarcity:EMA and ECHA data requirements demand specialized regulatory affairs capabilities that outpace academic training pipeline output.
- Application certification bottlenecks:NORSOK M-501 and PSPC compliance testing backlog at accredited laboratories extends product qualification timelines.
- Shipyard integration complexity:Coating specification must synchronize with block construction schedules and blast-cleaning capacity, requiring real-time inventory coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Anti Fouling Coatings Market |
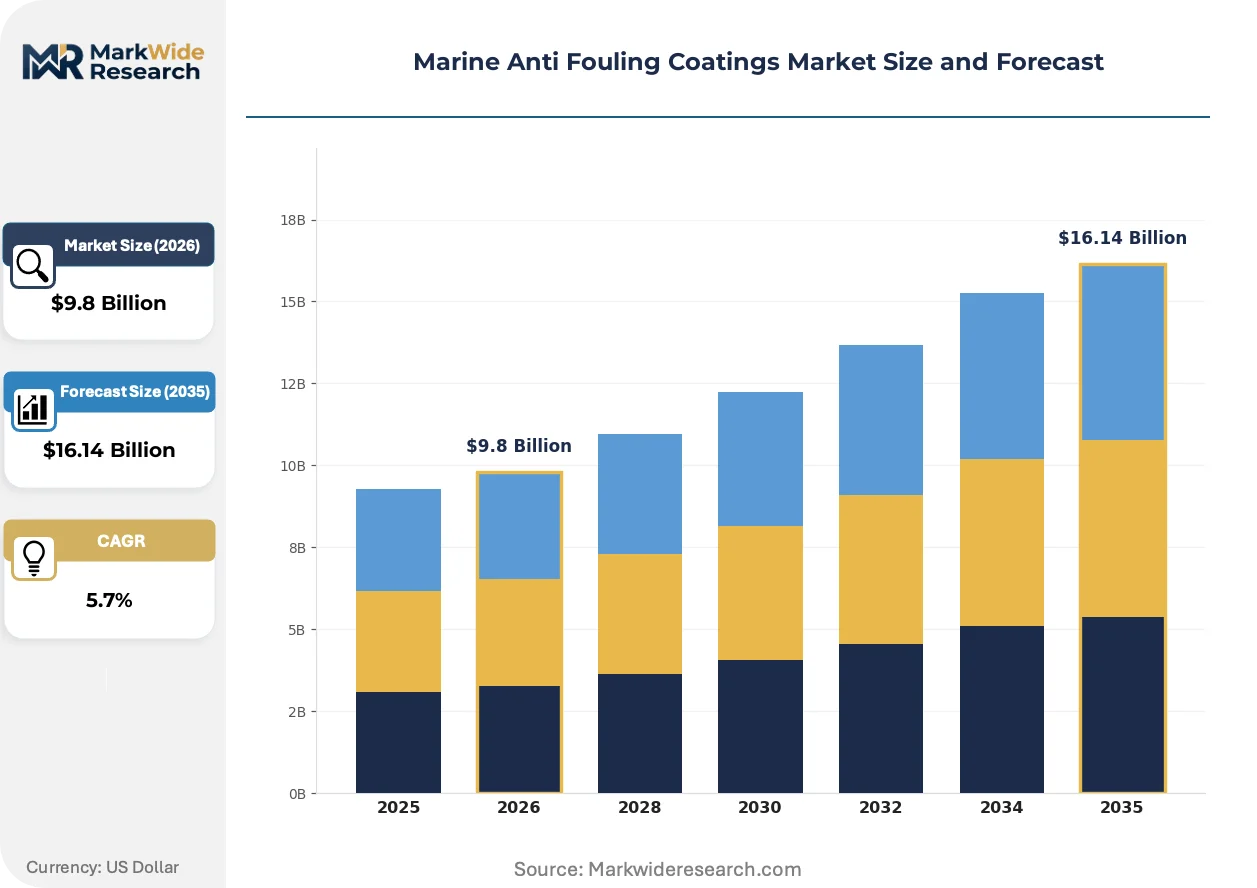
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $16.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Cleaning, Biocidal, Non-Biocidal, Special Purpose Formulation: Water-Based, Solvent-Based, Hybrid, Nano End User: Commercial Vessels, Recreational Boats, Offshore Structures, Yachts Application: Shipbuilding, Repair, Maintenance, Racing |
| Companies Covered | Akzo Nobel N.V., Hempel A/S, Jotun A/S, PPG Industries Inc., Chugoku Marine Paints, Ltd., Nippon Paint Marine, The Sherwin-Williams Company, Kansai Paint Co., Ltd., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Anti Fouling Coatings Market Strategic Shifts & Innovations
Formulation chemistry is bifurcating between biocide-free silicone systems and next-generation hybrid coatings, while digital hull performance monitoring redefines buyer value metrics.
Electroconductive graphene-enhanced coatings are electrifying hull protection architectures. These nanocomposite layers deliver active antifouling through low-voltage surface polarization, eliminating biocide payload entirely. Norwegian offshore supply vessel operators are piloting installations at commercial scale. The technology is electrifying competitive positioning by collapsing the historical trade-off between environmental compliance and operational performance.
REACH authorization timelines are restructuring European supply economics. ECHA's cumulative assessment of copper metabolites is extending registration dossier requirements beyond legacy toxicology datasets. Biocidal product manufacturers face capital-intensive endpoint studies for reproductive toxicity and endocrine disruption. Deep-sea tanker operators operating under EU port-state control are accelerating silicone foul-release trials to preempt authorization denial risks.
Charter rate transparency is compressing coating specification cycles. Container line procurement departments now integrate hull roughness penalties into vessel hire agreements, transferring performance risk from operator to owner. This contractual evolution is fragmenting purchasing authority away from technical superintendents toward fleet-wide category managers. The shift is most visible in Singapore and Hamburg headquarters clusters where major tonnage providers centralize supplier negotiations.
Marine Anti Fouling Coatings Market Segmentation
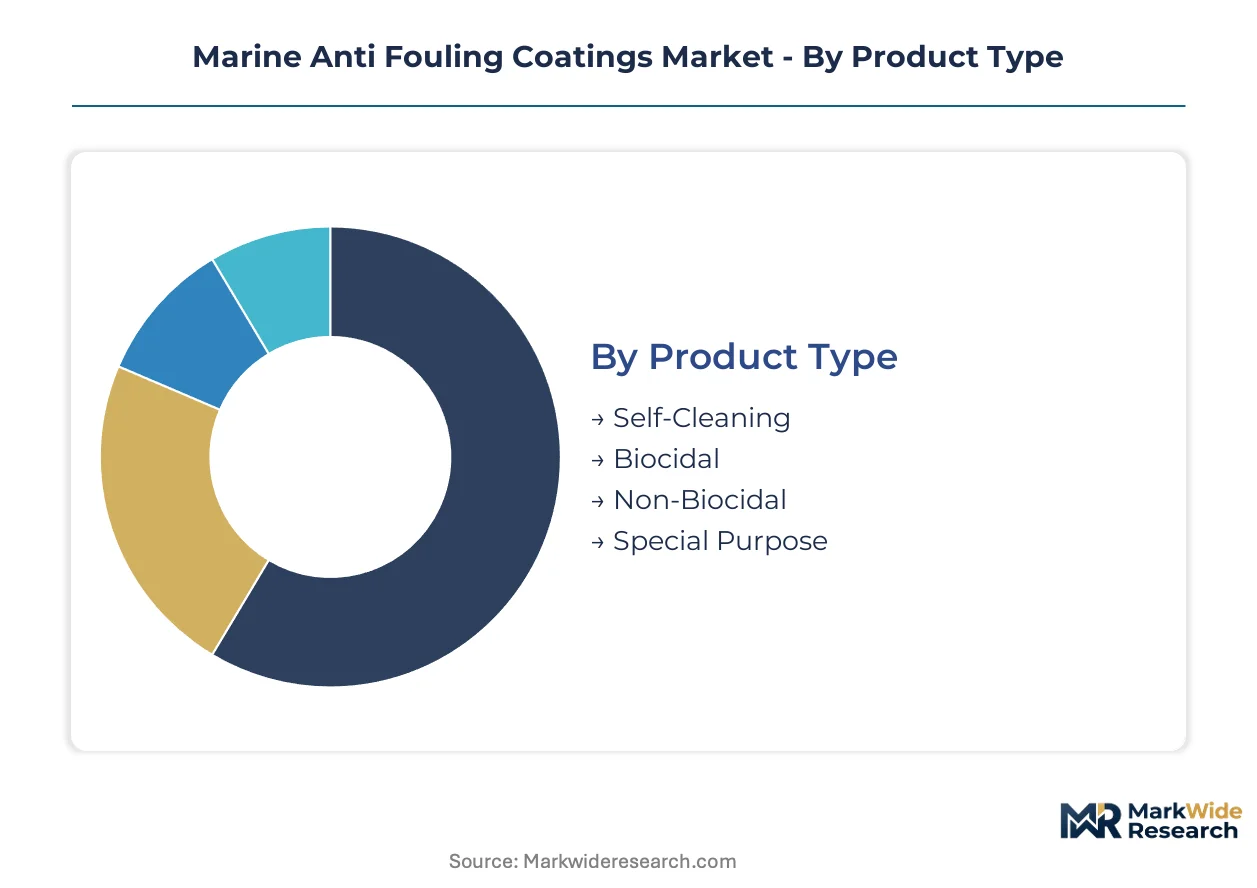
Segmentation in marine anti fouling coatings determines specification authority, margin structure, and regulatory exposure across vessel lifecycle decisions. Buyers optimize across performance tier, application environment, and compliance jurisdiction rather than selecting on unit cost alone.
Product Type:
Customization intensity varies sharply across this category, from commoditized commodity biocidal formulations to engineered silicone systems requiring hull-specific application protocols.
- Biocidal:Copper oxide and zinc pyrithione formulations dominate deep-sea commercial fleets where regulatory grandfathering persists. Demand concentrates in Mediterranean and Black Sea routes where EU port-state control maintains phased enforcement timelines for legacy chemistries.
- Non-Biocidal:Silicone foul-release polymers eliminate biocide payload entirely through surface energy modification. Cruise operators in Norwegian fjords and Alaskan waters are migrating fastest to preempt ECHA authorization denials and charter rate penalties tied to hull roughness.
- Self-Cleaning:Hydrophilic surface technologies respond to water flow velocity for dynamic fouling release.
- Special Purpose:Ice-class and polar-rated formulations withstand mechanical abrasion from pack ice.
Leading the category by volume: Biocidal. Growing fastest: Non-Biocidal.
Formulation:
Cost tier separation aligns with application environment severity and regulatory jurisdiction stringency.
- Solvent-Based:Epoxy and polyurethane carriers deliver film integrity under thermal cycling and mechanical stress. Arctic LNG carriers and icebreaker fleets specify these systems exclusively, accepting VOC emissions trade-offs for durability in sub-zero hull flex conditions.
- Water-Based:Acrylic and urethane dispersions reduce solvent exposure during yard application. Southeast Asian shipyards in Vietnam and Indonesia are converting spray booths to capture regulatory arbitrage from EU Green Deal supply chain due diligence requirements.
- Hybrid:Dual-cure systems combine water-borne base coats with solvent-borne topcoats.
- Nano:Graphene and carbon nanotube additives modify surface conductivity and mechanical properties.
Highest margin capture: Solvent-Based. Steepest expansion trajectory: Water-Based.
End User:
Customer type determines specification complexity, with fleet operators centralizing procurement while individual owners retain technical authority.
- Commercial Vessels:Container lines, bulk carriers, and tankers drive volume through dry-docking cycles synchronized with charter market conditions. Operators headquartered in Singapore and Hamburg are consolidating coating procurement across 500+ vessel fleets, extracting performance guarantees tied to ISO 19030 speed-power curves.
- Offshore Structures:FPSO hulls, platforms, and subsea equipment require specialized immersion-grade systems. Brazilian pre-salt development and West African field expansions are opening specification channels where local content requirements favor technical service presence over product shipment.
- Recreational Boats:Pleasure craft under 24 meters with seasonal haul-out patterns.
- Yachts:Superyacht newbuild and refit programs with aesthetic finish requirements.
Dominant procurement scale: Commercial Vessels. Fastest contract value growth: Offshore Structures.
Application:
Maturity gradient separates capital-intensive newbuild programs from fragmented maintenance spending.
- Repair:Unscheduled hull damage remediation and coating failure correction. Demand clusters around Rotterdam, Singapore, and Dubai where emergency dry-docking capacity supports tramp trade vessels with unpredictable routing.
- Maintenance:Scheduled in-water cleaning and touch-up between dry-dock intervals. Remote hull monitoring via ultrasonic sensors is compressing recoating decision cycles, enabling condition-based contracts that shift revenue from product volume to service outcomes.
- Shipbuilding:Newbuild block coating at construction stage.
- Racing:High-performance yacht applications with speed-optimized surface preparation.
Highest service attach rate: Maintenance. Greatest pricing pressure: Shipbuilding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates shipyard output for newbuild coating demand, while European regulatory pressure and Southeast Asian maintenance capacity reshape procurement geography across vessel lifecycle stages.
China
Jiangsu and Zhejiang shipyards dominate global container vessel contracting, driving specification authority for deep-sea biocidal formulations. The country's Ministry of Ecology and Environment enforces dual carbon goals that tighten VOC emissions standards at yard level. Shanghai and Ningbo clusters are converting spray booth infrastructure to capture EU Green Deal supply chain compliance premiums.
South Korea
Ulsan and Geoje corridors anchor ice-class solvent-based formulation capacity for LNG carrier newbuild programs. The national chemical regulator aligns biocide authorization timelines with IMO convention ratification schedules. Busan maintenance yards are integrating ultrasonic hull monitoring to compress recoating decision cycles for tramp trade vessels.
Germany
Hamburg and Bremen headquarters clusters centralize procurement for container line fleets exceeding 500 vessels. REACH authorization extensions through ECHA are eliminating legacy copper-heavy formulations from North Sea trade routes. The country's toxicology infrastructure supports fast-track reformulation for copper-free alternatives serving Baltic and Mediterranean operators.
United States
Gulf Coast offshore vessel operators and Great Lakes bulk carriers sustain demand for abrasion-resistant specialty coatings. EPA registration requirements for antifouling biocides create parallel compliance tracks distinct from EU hazard classifications. Houston and New Orleans service hubs are expanding technical presence to capture FPSO maintenance contracts from Brazilian pre-salt development.
Brazil
Petrobras pre-salt field expansion is opening specification channels for FPSO hull coating programs with local content requirements. The national petroleum regulator mandates environmental impact assessments that favor low-biocide formulations in sensitive Atlantic marine zones. Rio de Janeiro and Espírito Santo shipyards are scaling block construction capacity under domestic content incentives.
Marine Anti Fouling Coatings Market Key Industry Players
European producers anchor the premium formulation tier; East Asian specialists hold volume positions in shipyard supply. The vendor base stratifies across integrated chemical conglomerates, dedicated marine coating houses, and regional application service providers. Three archetypes dominate: toxicology-capable reformulation leaders, yard-embedded technical service operators, and commodity biocide suppliers defending grandfathered positions. Competitive moves concentrate on captive R&D infrastructure expansion and predictive maintenance platform integration.
Among the integrated chemical majors, Akzo Nobel N.V. and BASF SE occupy positions defined by in-house toxicology capabilities and multi-regional registration expertise. Dedicated marine specialists including Hempel A/S and Jotun A/S exemplify the yard-embedded service model through localized manufacturing and technical presence at major shipbuilding clusters. Japanese and Korean paint manufacturers including Chugoku Marine Paints, Ltd. and Kansai Paint Co., Ltd. represent the Asia-Pacific supply concentration, leveraging proximity to Ulsan, Geoje, and Imabari shipyard corridors for specification influence.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| Hempel A/S |
| Jotun A/S |
| PPG Industries Inc. |
| Chugoku Marine Paints, Ltd. |
| Nippon Paint Marine |
| The Sherwin-Williams Company |
| Kansai Paint Co., Ltd. |
| BASF SE |
| Others |
Cost & Logistics Intelligence
EU Green Deal shipping provisions gate qualified supply and premium-tier pricing access, restricting formulation authorization to producers with captive toxicology infrastructure while copper-free biocide alternatives command 15-25% premia over legacy chemistries in North Sea and Baltic trade routes.
Pricing Analysis
Short lead-time premiums of 8-12% apply to spot solvent-based formulation orders from Ulsan and Geoje corridors, while inventory liquidation discounts emerge for water-based systems facing ECHA authorization uncertainty. Three-tier pricing structure across premium silicone foul-release, standard copper-free biocidal, and economy copper-heavy formulations separates specification tiers by IMO compliance trajectory and hull-performance guarantee terms. Price differentiation hinges on REACH registration status and ISO 19030 speed-power curve verification. Cost compression in economy-tier biocidal lines is intensifying because Brazilian and Indian shipyards are consolidating procurement around certified suppliers with in-service performance data. Charter rate penalties tied to hull roughness make container lines the least price-sensitive buyers, while tramp bulk operators operating unpredictable routes exhibit highest sensitivity to unit coating costs.
Supply Chain Analysis
Reverse-logistics flows for spent blast media and coating residues are emerging as compliance cost centers, with Rotterdam and Singapore yards investing in closed-loop abrasive recovery to meet EU Green Deal supply chain due diligence requirements. Raw material supply concentrates in China for copper oxide and zinc pyrithione precursors, South Korea for silicone polymer feedstocks, and Germany for epoxy resin specialty grades. Formulation production draws from these inputs with single-source vulnerability around Korean ice-class solvent-based capacity serving Arctic LNG carrier programs. Tariff exposure on Chinese biocide precursors is restructuring procurement toward Indian and Vietnamese alternative suppliers. Distribution runs through shipyard-embedded technical service teams rather than merchant distributors, with Akzo Nobel, Hempel, and Jotun maintaining direct application support at Jiangsu, Ulsan, and Hamburg clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Toxicology laboratory capacity constraints are propping premium-tier pricing, as ECHA authorization timelines extend beyond 36 months and only established producers maintain in-house reproductive toxicity and endocrine disruption testing capabilities.
For Market Incumbents: Acquire specialized toxicology service providers to compress registration dossier preparation timelines and defend against graphene-enhanced coating substitutes electrifying hull protection architectures. Consolidate backward integration into copper oxide precursor supply to offset London Metal Exchange volatility squeezing conventional biocidal margins. Deepen technical service presence at Cochin Shipyard and Mazagon Dock to preempt PLI scheme-driven localization requirements. For New Entrants and Emerging Players: Begin with ultrasonic hull monitoring platform development to capture condition-based recoating contract transitions shifting revenue from product volume to service outcomes. Target Brazilian FPSO maintenance channels where Petrobras local content requirements favor technical service presence over established product relationships. Pursue go-to-market partnerships with Indian shipyard expansion programs under PLI incentives rather than competing directly for newbuild specification at Chinese or Korean yards. For Investors and Strategic Acquirers: First ECHA copper metabolite authorization denial for a major biocidal formulation is the leading indicator that silicone foul-release penetration will accelerate beyond cruise and yacht segments into deep-sea commercial fleets. Over the projection horizon, coating houses with integrated hull-performance testing and predictive maintenance platforms represent the most defensible acquisition archetype. Monitor IMO member state incorporation of Anti-Fouling Systems Convention obligations into port-state control inspection protocols for early signals of regulatory enforcement divergence creating competitive arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Precursor Supply | Captive sourcing from Chilean and Peruvian mining operations insulates margin from LME volatility. |
| Graphene-Enhanced Coating Commercialization | Norwegian offshore supply vessel pilots validate active antifouling through low-voltage surface polarization. |
| Remote Hull Monitoring Platform Deployment | Ultrasonic sensor integration with predictive maintenance compresses recoating decision cycles for tramp trade vessels. |
| Indian Technical Service Expansion | Localized presence at Cochin Shipyard and Mazagon Dock captures PLI scheme-driven coating demand. |
| Brazilian FPSO Specification Channel Development | Petrobras pre-salt local content requirements favor coating houses with Rio de Janeiro technical infrastructure. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews spanning coating R&D directors, shipyard procurement managers, fleet technical superintendents, and marine classification society surveyors. ECHA biocide authorization databases, IMO convention ratification tracking, and EU port-state control inspection reports provided compliance trajectory validation. Bottom-up vessel fleet modeling and top-down chemical consumption estimates were triangulated against shipyard output data from Jiangsu, Zhejiang, Ulsan, and Geoje clusters.
Data-stream reconciliation across formulation chemistry segmentation, end-use vessel categories, and application lifecycle stages shaped the analytical framework over the projection horizon. Product type splits across biocidal, non-biocidal, and hybrid systems were modeled alongside formulation technology tiers and regional regulatory cluster stringency. CAGRs were derived from dry-docking cycle frequency, fleet renewal mandates, and ECHA authorization timeline assumptions. Key inputs included charter rate transparency effects on coating specification authority and ultrasonic hull monitoring adoption curves.
Underlying measurement precision varies by segment; non-biocidal silicone systems carry tighter precision than legacy biocidal categories facing authorization uncertainty. Forecasts reflect assumptions around REACH enforcement consistency and IMO convention ratification schedules. Practitioners should monitor ECHA cumulative copper metabolite assessments and Brazilian ANVISA environmental impact mandate expansions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
FEVE Fluoropolymer Coatings Market
Coatings
Marine Coatings Market
Coatings
Mexico Industrial Wood Coatings Market
Coatings
Egyptian Protective Coatings Market
Coatings
Global Anti-Smudge Coatings Market
Coatings
Clear Coatings Market
Coatings
Egypt Automotive OEM Coatings Market
Coatings
Spain Automotive OEM Coatings Market
Coatings
Sol Gel Nanocoating Market
Coatings
Corrosion Protective Coatings and Acid Proof Lining Market
Coatings
North America Superhydrophobic Coating Market
Coatings
Europe Thermal Spray Market
Coatings
Biopolymer Coatings Market
Coatings
France Protective Coatings Market
Coatings
Energy Efficient Powder Coatings Market
Coatings
Acrylic Coating Market