
 Wire Enamels Market | 2026-2036
Wire Enamels Market Size, Share, and Industry Trends Forecast 2026-2036
Wire Enamels Market Intelligence
The performance gap between high-temperature enamels for specialized motors and general-purpose commodity grades is consolidating market share among technically advanced suppliers. Elantas specializes in high-performance insulation systems for demanding applications like electric vehicle traction motors. In contrast, Superior Essex leverages its global manufacturing scale to serve the high-volume power transformer segment. Hitachi-Chem differentiates through its focus on fine wire enamels for sophisticated electronic components.
Wire enamels are polymer-based liquid coatings applied to copper or aluminum wire, creating a durable layer of electrical insulation. These coatings are cured to achieve specific dielectric strengths and thermal ratings, often exceeding 200°C, which prevents short circuits in wound coils. While Polyurethane and Polyester enamels form the largest product segments by volume, demand from electrical equipment manufacturers for high-performance epoxy formulations is expanding. This shift is notable in applications like generators for renewable energy firms.
Product formulation is heavily influenced by environmental and safety regulations. The European Union's REACH and RoHS directives restrict specific solvents and heavy metals, pushing for safer chemistries. Concurrently, China's GB standards and US EPA rules impose stringent limits on volatile organic compound (VOC) emissions during application. Navigating this diverging set of regional chemical compliance mandates while maintaining performance is the central challenge for manufacturers.
Market Dynamics
The wire enamels market is shaped by the fundamental tension between the demand for higher thermal and dielectric performance, driven by electrification, and the intensifying global pressure for environmentally compliant, low-VOC formulations. This dual requirement accelerates innovation while consolidating the market around suppliers with advanced polymer chemistry capabilities.
Growth Catalysts
- Electric Vehicle Expansion:The proliferation of electric vehicles directly stimulates demand for high-temperature resistant wire enamels, specifically polyesterimides and polyamide-imides, for use in traction motors, onboard chargers, and auxiliary power units.
- Renewable Energy Infrastructure:Government incentives for clean energy are expanding the installation of wind turbines and solar farms, which require large generators and transformers wound with durable, high-performance enameled wires.
- Electronics Miniaturization:Continuous demand for smaller, more powerful consumer electronics and telecommunication devices drives the need for fine and ultra-fine enameled wires with superior insulation properties for micro-coils and sensors.
Market Restraints
- Raw Material Price Volatility:The market is sensitive to price fluctuations in key petrochemical feedstocks, such as cresols, xylenols, and isocyanates, as well as base metals like copper, impacting formulation costs and final product pricing.
- Diverging Regulatory Standards:Manufacturers face significant compliance burdens navigating the patchwork of regional chemical regulations, including the EU's REACH, China's GB standards, and US EPA rules, which often have conflicting substance restrictions.
- Technical Hurdles in Formulation:Developing water-based or high-solids enamel systems that match the performance characteristics of traditional solvent-based products, particularly in thermal stability and adhesion, remains a significant technical challenge.
Strategic Opportunities
- High-Frequency Applications:The rollout of 5G technology and advancements in power electronics create opportunities for specialized enamels designed to mitigate corona discharge and skin effect in high-frequency transformers and inductors.
- Bio-Based Polymer Development:Investment in R&D for wire enamels derived from renewable, bio-based feedstocks presents an opportunity to meet corporate sustainability goals and appeal to environmentally conscious customers in the electrical equipment sector. * Self-Bonding Enamels: Formulations that incorporate a thermoplastic or thermosetting adhesive overcoat offer an opportunity to eliminate varnishing steps, reducing manufacturing time and energy consumption for coil producers in the appliance and automotive industries.
Industry Challenges
- Solvent Substitution Complexity:Reformulating products to replace restricted solvents like NMP, as mandated by ECHA, requires extensive testing and re-qualification, a time-consuming and costly process that can disrupt established supply chains.
- Energy-Intensive Curing Process:The curing of wire enamels is an energy-intensive process requiring large ovens, and rising energy costs, particularly in Europe, present a significant operational challenge for wire manufacturers.
- Application Process Optimization:Maintaining consistent coating thickness and quality at high application speeds to meet the demands of large-scale motor and transformer production is a persistent operational challenge requiring sophisticated process controls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wire Enamels Market |
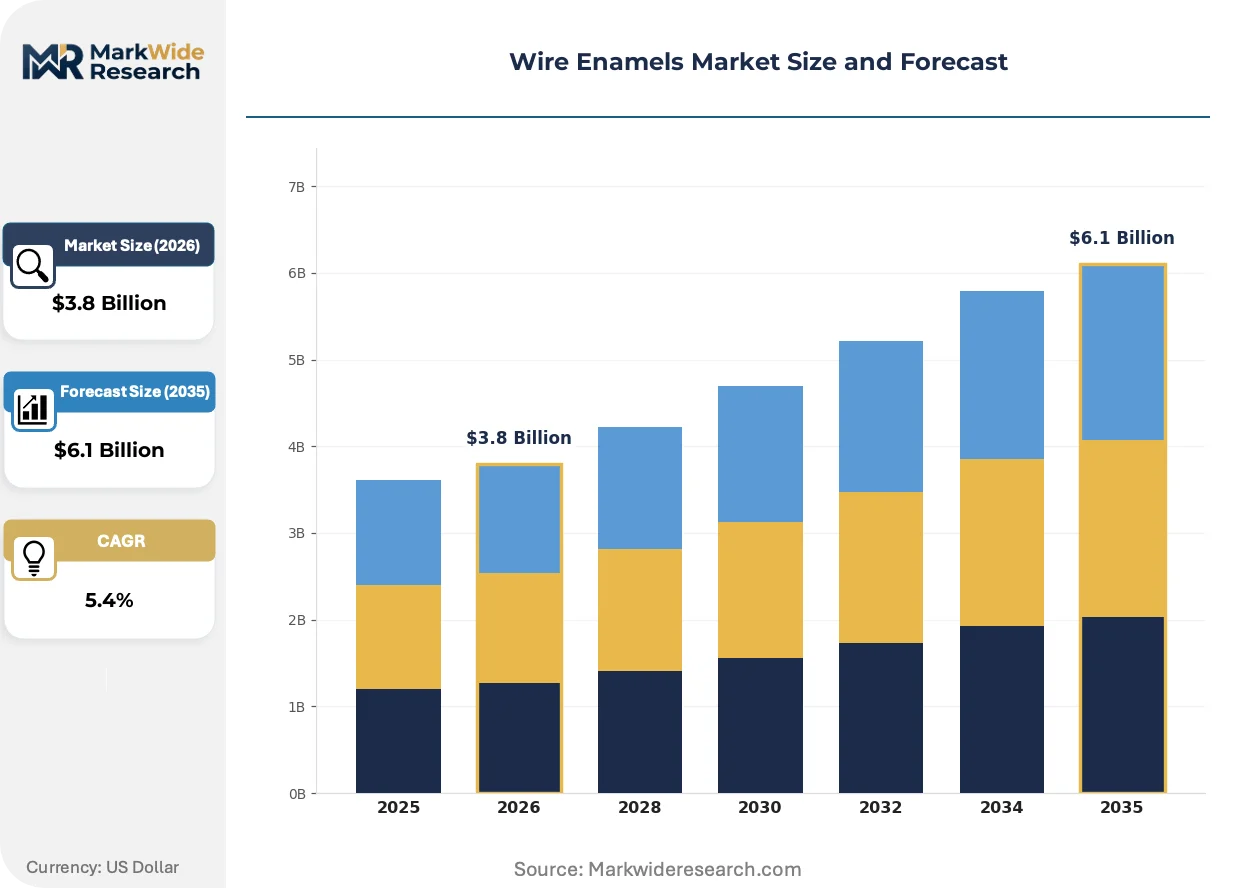
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC Enamel, Polyester Enamel, Polyurethane Enamel, Epoxy Enamel, Acrylic Enamel Application: Power Transformers, Electric Motors, Generators, Inductors, Transformers End User: Electrical Equipment Manufacturers, Renewable Energy Firms, HVAC Producers, Consumer Appliance Makers, Telecommunications Providers Packaging Type: Drums, Cans, Tins, Pails, Carboys |
| Companies Covered | Superior Essex, Elantas, Axalta, Hitachi-Chem, Totoku Toryo, Huber Group, Kyocera, Xianda, Zhejiang Electronic Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wire Enamels Market Strategic Shifts & Innovations
Innovation in the wire enamels market is driven by the parallel needs for enhanced performance in demanding electrical applications and adherence to stricter environmental health and safety standards. This is pushing development towards more complex polymer systems and smarter application processes that reduce environmental impact without compromising reliability.
Nano-modified enamels incorporate inorganic nanoparticles to improve critical properties like thermal endurance and partial discharge resistance. Electrical motor manufacturers, especially in the aerospace and EV sectors, are early adopters of these advanced materials for compact, high-power-density designs. This evolution is decentralizing performance gains away from bulk polymer chemistry and towards a more integrated material science approach combining organic and inorganic components.
The European Union’s RoHS directive, restricting hazardous substances in electrical equipment, directly influences enamel formulation. It prohibits the use of certain heavy metal-based catalysts and pigments, compelling suppliers to find effective, compliant alternatives. The consumer electronics and appliance segments are most affected, forcing a rapid shift in formulations to ensure continued market access across the EU.
A clear behavioral shift is occurring as original equipment manufacturers (OEMs) increasingly specify wire enamels based on process efficiency gains rather than just material cost. This re-prioritization favors enamels that offer faster curing times, superior surface lubricity for higher winding speeds, and lower solvent content to reduce abatement costs. This trend is most prominent among high-volume automotive component producers in Japan and Germany seeking to optimize automated production lines.
Wire Enamels Market Segmentation
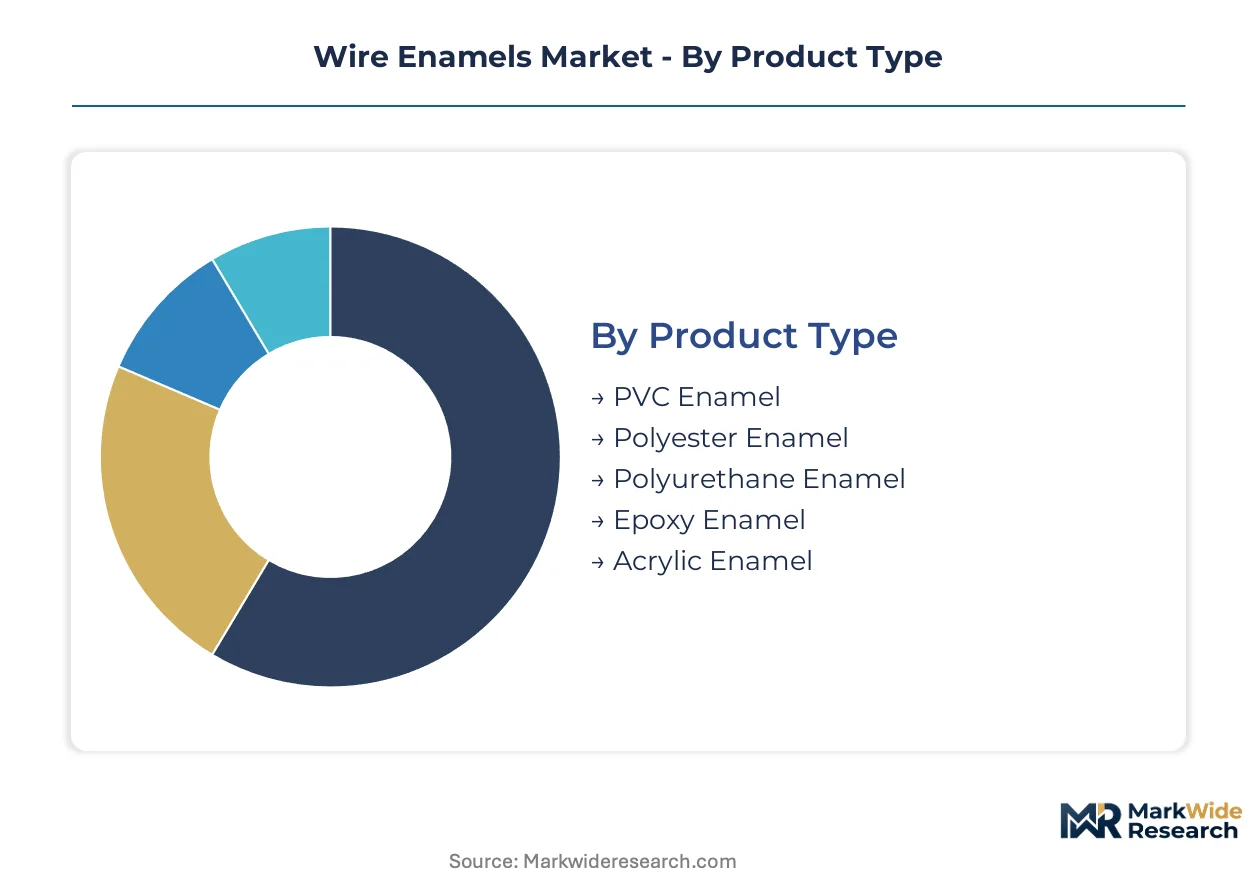
The wire enamels market segmentation highlights the diverse material science and application requirements driving product differentiation. Understanding these distinct segments helps manufacturers tailor formulations for specific performance needs and regulatory compliance. This granular view reveals where innovation and demand concentration truly lie.
Product Type:
The product type segmentation underscores the varying certification burdens and performance specifications required by different end-use applications.
- Polyester Enamel:These enamels offer excellent thermal stability and mechanical strength, making them suitable for general-purpose motors and transformers. Demand concentrates in high-volume industrial motors across China.
- Polyurethane Enamel:Known for their solderability at lower temperatures, polyurethane enamels simplify winding processes in fine wire applications. This segment sees significant demand from consumer electronics producers in Japan.
- Epoxy Enamel:Epoxy formulations provide superior chemical resistance and adhesion, increasingly specified for generators in renewable energy systems.
- PVC Enamel:PVC enamels offer good flexibility and dielectric strength but are less common due to lower thermal ratings.
- Acrylic Enamel:Acrylic enamels are generally used for their good adhesion and flexibility in applications with lower thermal requirements.
Polyester Enamel sits at the top of the volume ranking, with Epoxy Enamel climbing the fastest.
Application:
Application-based segmentation reflects the functional demands and operating environments that dictate enamel performance characteristics.
- Electric Motors:This segment requires enamels with high thermal endurance and dielectric strength to withstand operational stresses. Demand expands rapidly in electric vehicle traction motors and industrial automation systems in Germany.
- Power Transformers:Large power transformers necessitate enamels with exceptional thermal aging resistance and partial discharge endurance for grid infrastructure reliability. Procurement is robust in India, supporting its expanding electricity grid.
- Generators:Enamels used in generators must endure high temperatures and mechanical vibrations for stable power generation.
- Inductors:Inductor applications require fine wire enamels with precise coating thickness for efficient energy storage.
- Transformers:General transformers utilize a broad range of enamels depending on specific power and size requirements.
Electric Motors command the largest share of high-performance enamel consumption, while Generators are exhibiting strong growth due to renewable energy projects.
End User:
The end-user segmentation illustrates how different industry verticals drive specific performance requirements and procurement patterns for wire enamels.
- Electrical Equipment Manufacturers:This largest consumer segment requires diverse enamel types for components from industrial machinery to consumer appliances. Demand is influenced by global manufacturing trends and regulatory shifts in China.
- Renewable Energy Firms:These firms specify high-performance enamels for wind turbine generators and solar inverter transformers, prioritizing durability and efficiency. Investment is strong across Europe, driven by decarbonization goals.
- Consumer Appliance Makers:Appliance manufacturers seek cost-effective enamels for motors in refrigerators and washing machines.
- HVAC Producers:HVAC systems utilize enamels for motors and coils, demanding resistance to temperature fluctuations.
- Telecommunications Providers:This segment requires specialized fine wire enamels for high-frequency coils in communication infrastructure.
Electrical Equipment Manufacturers maintain the largest procurement volume, with Renewable Energy Firms showing accelerated demand for advanced formulations.
Packaging Type:
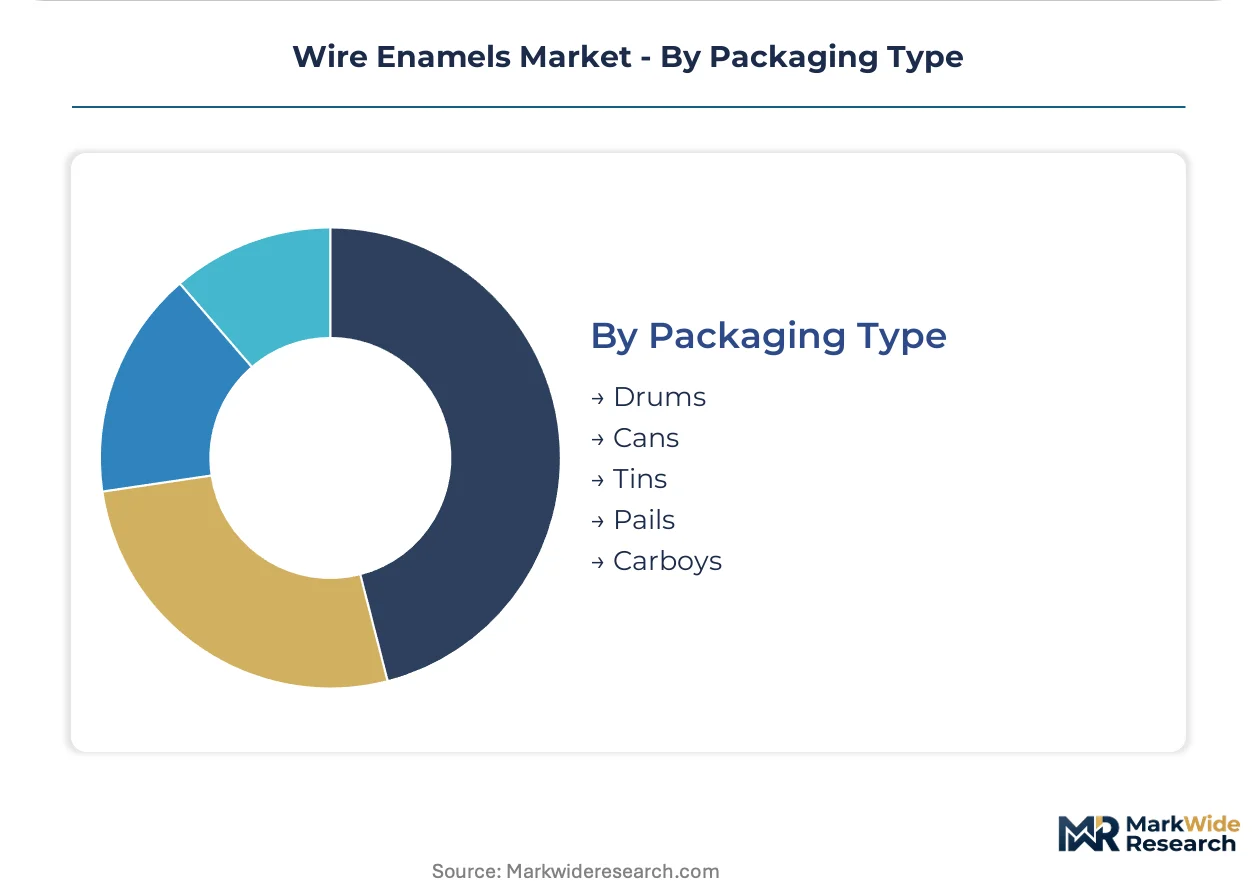
Packaging type segmentation reflects the logistical considerations and volume requirements for transporting and handling wire enamels.
- Drums:Drums are the predominant packaging for bulk quantities of wire enamels, facilitating efficient transport and storage for large-scale wire manufacturers. These are widely used by major producers in industrial regions like Germany.
- Pails:Pails offer a convenient medium-volume packaging solution, suitable for mid-sized operations or specialized enamel batches. This format is preferred by smaller wire producers in the US.
- Cans:Cans typically hold smaller quantities, often used for sampling or very low-volume applications.
- Tins:Similar to cans, tins provide secure packaging for smaller volumes, ensuring product integrity.
- Carboys:Carboys are specialized containers, usually for corrosive chemicals, less common for general wire enamel distribution.
Drums represent the primary bulk packaging format, while Pails are gaining traction for their flexibility in smaller production runs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The wire enamels market features a highly skilled engineering and manufacturing workforce concentrated in key industrial regions globally. These specialized talents drive innovation in polymer chemistry and application techniques for high-performance electrical insulation. This expertise is crucial for meeting the evolving demands of electrification and miniaturization across diverse end-use sectors.
China
Demand for wire enamels in China stems from its vast electronics and electric vehicle manufacturing. China's GB standards impose stringent limits on VOC emissions, influencing local product development. The Yangtze River Delta region, particularly Shanghai, drives significant production and consumption for automotive and industrial applications.
Germany
High-performance enamel consumption in Germany is propelled by its advanced automotive industry, especially electric vehicle traction motors. The European Union's REACH regulation mandates safer, low-VOC formulations, impacting German manufacturers. Bavaria, with its strong engineering and automotive clusters, leads in developing specialized insulation systems.
Japan
Consumer electronics producers in Japan generate significant demand for fine wire enamels due to miniaturization trends. METI guidelines encourage energy efficiency and material innovation in electrical components. The Kanto region, including Tokyo, remains a hub for sophisticated electronic component manufacturing requiring precise enamel formulations.
India
India's expanding electricity grid and renewable energy projects stimulate demand for durable wire enamels in power transformers. The PLI scheme supports domestic manufacturing, encouraging local production of electrical equipment. Maharashtra, particularly Mumbai, sees robust procurement for grid infrastructure and industrial motors.
United States
The United States market for wire enamels sees demand from industrial automation and specialized electronics. US EPA rules impose stringent limits on VOC emissions during application, pushing for compliant solutions. The Midwest, with its automotive and industrial base, utilizes wire enamels for various motor and transformer applications.
Wire Enamels Market Key Industry Players
Top-tier vendors anchor the specialized, high-performance segment, while mid-sized and regional players often compete on cost and volume for general-purpose grades. The market structure is tiered, reflecting diverse application requirements from electric vehicles to consumer electronics. Strategic archetypes include high-performance specialists, global volume producers, and niche innovators focusing on fine wire or specific material chemistries. Competitive moves involve strategic partnerships for technology co-development and targeted capacity expansion in high-growth regions.
On the premium-tier vector, Elantas exemplifies a focus on high-performance insulation systems for demanding applications like electric vehicle traction motors. At the scale-driven end, Superior Essex represents a global manufacturing footprint serving the high-volume power transformer segment. Hitachi-Chem occupies a position as a specialist in fine wire enamels, catering to sophisticated electronic components and miniaturization trends. These companies collectively demonstrate the market's differentiation across performance, scale, and specialization.
| Leading Market Players |
|---|
| Superior Essex |
| Elantas |
| Axalta |
| Hitachi-Chem |
| Totoku Toryo |
| Huber Group |
| Kyocera |
| Xianda |
| Zhejiang Electronic Materials |
| Others |
Cost & Logistics Intelligence
European Union's REACH regulation gates access to premium-tier wire enamel markets by mandating safer, low-VOC formulations. This compliance requirement elevates production costs and restricts the pool of qualified suppliers.
Pricing Analysis
Bundled after-sales service and technical support influence pricing for specialized wire enamels, while commodity grades operate on a transactional, per-unit basis. Pricing stratifies across premium, standard, and economy tiers, driven by thermal rating and regulatory certifications like REACH compliance. Raw material price volatility, particularly for petrochemical feedstocks, creates cost compression for general-purpose formulations. Consumer appliance makers exhibit the highest price sensitivity, contrasting with electric vehicle manufacturers prioritizing performance over cost.
Supply Chain Analysis
Dual-sourcing requirements for critical wire enamels are increasingly mandated by major automotive and electronics OEMs to mitigate supply disruptions. Supply concentrates heavily in industrial regions of China, Germany, and Japan, reflecting their advanced manufacturing bases. The market relies on key petrochemical feedstocks like cresols and isocyanates, making it susceptible to raw material price volatility. Distribution runs primarily through direct channels to large-scale wire manufacturers and specialized coil producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wire enamels market presents a geographic-arbitrage opportunity driven by significant energy cost differentials for curing processes between Europe and Asia. Strategic players can leverage regional manufacturing cost advantages while navigating diverse regulatory landscapes.
For Market Incumbents: Deploy advanced polymer chemistry R&D to maintain a performance edge in high-temperature applications. Incumbents should invest in nano-modified enamel development to meet demand from aerospace and EV sectors, mitigating the threat of performance gaps. Securing certifications for low-VOC and solvent-free formulations across multiple regions, such as EU's REACH and China's GB standards, will also reinforce market access against regulatory shifts.
For New Entrants and Emerging Players: Capture niche segments by specializing in bio-based polymer development for wire enamels, appealing to environmentally conscious customers. New entrants can target the fine wire enamels segment in Japan, leveraging demand from miniaturization trends in consumer electronics. Offering self-bonding enamel formulations provides a go-to-market angle focused on process efficiency and energy savings for appliance and automotive coil producers.
For Investors and Strategic Acquirers: Roll-up economics work for specialized wire enamel producers because diverging regulatory landscapes create regional expertise silos. Long-term viability is strong, driven by electrification and renewable energy infrastructure build-out over the next decade. Investors should target mid-sized firms with proprietary low-VOC formulations or established compliance records in key markets like Europe. The signal to watch is an acceleration of M&A activity among fine wire enamel specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Addresses growing demand from electric vehicle and electronics manufacturing in China. |
| R&D for Water-Based Systems | Meets stringent environmental regulations and reduces VOC emissions in application. |
| Strategic Partnership with OEMs | Ensures product development aligns with specific high-performance motor requirements. |
| Acquisition of Fine Wire Specialist | Expands product portfolio for miniaturized electronic components in Japan. |
| Certification Investment (REACH/GB) | Secures market access and compliance for premium-tier formulations in Europe and China. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to inform the wire enamels market analysis. Primary research involved discussions with R&D directors, procurement leads at wire manufacturers, and regulatory compliance officers across key regions. Secondary data sources included industry association publications, patent filings for polymer formulations, and company financial disclosures. This approach ensured robust bottom-up data collection, triangulated with top-down market trend validation.
Forecasts were anchored to a comparable historical period, establishing baseline growth rates across the analysis window. The analytical framework modeled market dynamics by product type, application, end user, packaging type, and regional regulatory compliance. Compound Annual Growth Rates were derived from an assessment of historical trends and projected demand drivers. Key industry-specific inputs included electric vehicle production forecasts and renewable energy infrastructure development targets.
Underlying measurement precision varies by segment; high-volume polyester and polyurethane enamels carry tighter precision than specialized nano-modified formulations. Forecasts reflect assumptions regarding raw material stability and regulatory enforcement. Deviation in global petrochemical prices or unexpected regulatory changes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
2K Coatings Market
Coatings
Russia Architectural Coatings Market
Coatings
Global Solar Panel Coatings Market
Coatings
Europe Protective Coatings Market
Coatings
Thailand Architectural Coatings Market
Coatings
Japan Protective Coatings Market
Coatings
Mold Release Coatings Market
Coatings
Self-Cleaning Coatings Market
Coatings
Powder Coating Booth Market
Coatings
Italy Protective Coatings Market
Coatings
Breathable Antimicrobial Coatings Market
Coatings
Global Fire-Resistant Coating Market
Coatings
Europe Powder Coatings Market
Coatings
Anti-Friction Coatings Market
Coatings
Automotive Refinish Coatings Market
Coatings
Epoxy Surface Coatings Market