
 Global Polybutene Market | 2026-2036
Global Polybutene Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polybutene Market Foresight
Technical support and formulation customization is broadening the commercial relationship between polybutene suppliers and industrial buyers beyond transactional resin sales. INEOS Group leverages its European crackers and polymerization assets to sustain captive feedstock access across the butene value chain. LyondellBasell Industries Holdings B.V. anchors its position through large-scale solution-phase production technology. Mitsui Chemicals, Inc. specializes in high-purity grades for pharmaceutical and cosmetic applications where impurity thresholds are stringent.
Polybutene comprises a family of liquid or semi-liquid oligomers and polymers synthesized from butene monomers, with molecular weights ranging from approximately 300 to over 3,000 g/mol and viscosity grades spanning 3 to 4,000 cSt at standard conditions; manufacturers employ cationic polymerization of mixed C4 refinery streams or purified 1-butene feedstocks to produce materials serving as tackifiers, sealants, lubricant additives, and polyolefin modifiers. Homopolymer grades command the deepest margin pools in personal care and pharmaceutical formulations where batch consistency and low color are non-negotiable. Copolymer architectures are gaining share in adhesive applications where tailored peel strength and temperature resistance justify formulation complexity. PB-1 resin occupies a mature but stable position in pressurized hot water pipe systems, particularly in Asian construction markets.
REACH registration requirements and RoHS substance restrictions in Europe compel polybutene producers to document full supply chain substance identities and eliminate restricted phthalate co-additives from lubricant formulations. FDA food-contact notification protocols and EPA TSCA Section 5 reviews in the United States govern which molecular weight fractions and catalyst residues may migrate into packaged food matrices. Stakeholders must monitor how evolving per- and polyfluoroalkyl substance regulations in multiple jurisdictions could redirect demand toward polybutene-based barrier coatings as fluoropolymer alternatives face restriction.
Market Dynamics
REACH registration requirements and evolving FDA food-contact standards are compressing formulation flexibility while simultaneously creating premium positioning for compliant producers. Suppliers now compete on documentation depth rather than resin price alone.
Growth Catalysts
- Hot water pipe infrastructure:China's municipal heating retrofits and India's residential construction surge are accelerating PB-1 resin consumption in pressurized piping systems.
- Fluoropolymer displacement:Per- and polyfluoroalkyl substance restrictions across multiple jurisdictions are redirecting barrier coating demand toward polybutene-based alternatives.
- Seal integrity mandates:Tightening food packaging specifications in North America and Europe are expanding polybutene adoption in multilayer film structures.
Market Restraints
- C4 feedstock volatility:Refinery stream availability fluctuations directly compress margin predictability for producers dependent on mixed butene supply.
- Homopolymer production concentration:High-purity grade manufacturing remains concentrated among specialized European and Japanese producers, creating supply vulnerability.
- Isotactic polypropylene substitution:Lower-cost polyolefin alternatives are capturing share in non-critical adhesive and sealant applications.
Strategic Opportunities
- Pharmaceutical-grade expansion:India's CDSCO and China's NMPA are tightening impurity thresholds, creating entry points for certified high-purity suppliers.
- Cosmetic formulation convergence:Polybutene-1 is integrating with silicone alternatives in color cosmetic vehicles as brands reformulate for clean-label positioning.
- Extended producer responsibility frameworks:EU packaging waste directives are incentivizing mono-material designs where polybutene seal layers simplify recycling streams.
Industry Challenges
- Catalyst residue documentation:FDA food-contact notification protocols require extensive migration testing timelines, delaying new grade commercialization by 18-24 months.
- Solution-phase process expertise:Large-scale production technology requires specialized engineering talent that remains scarce outside established manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polybutene Market |
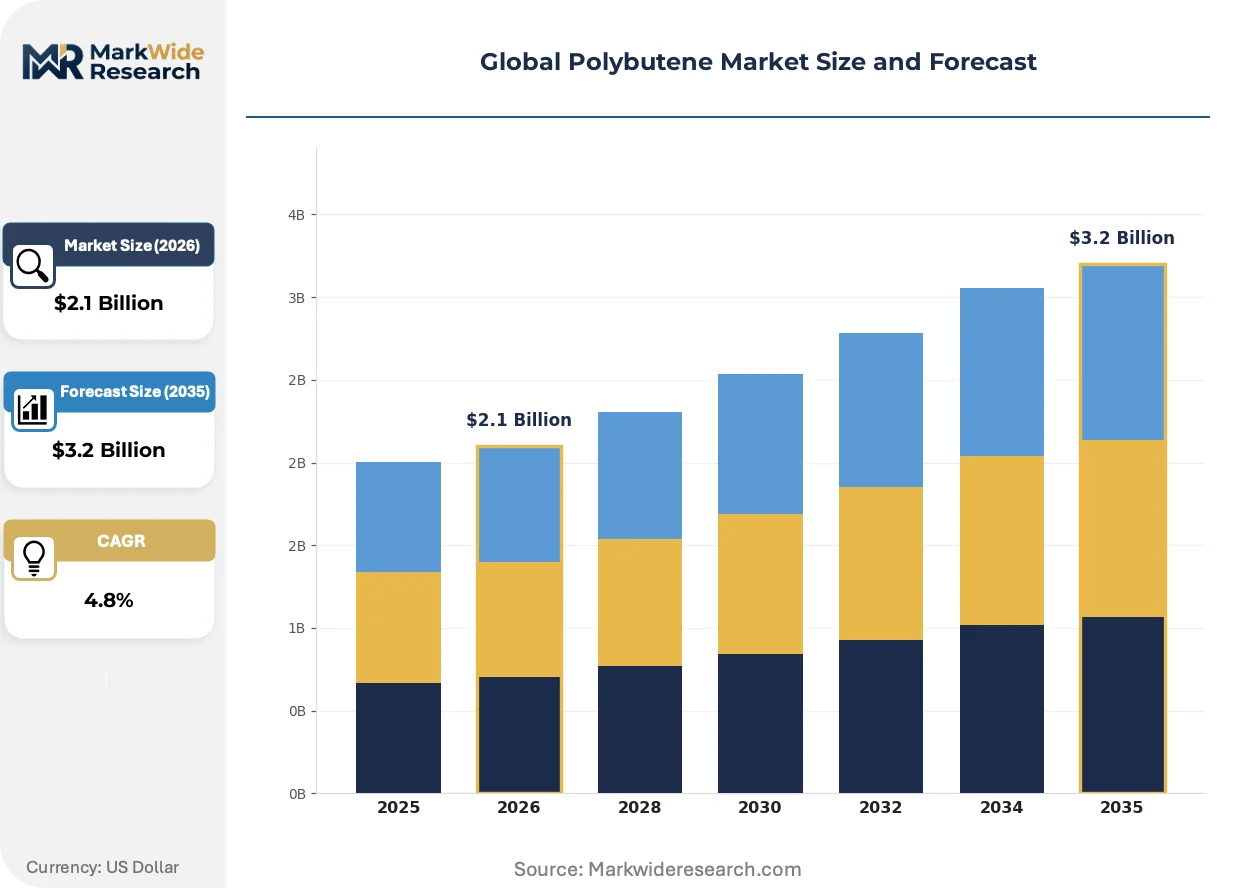
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PB-1, PB-2, Copolymer, Homopolymer Application: Hot Water Pipes, Adhesives, Sealants, Lubricants, Packaging Films End User Industry: Construction, Personal Care, Food Packaging, Automotive OEMs, Electronics Packaging Type: Granules, Pellets, Powder, Liquid, Masterbatch |
| Companies Covered | INEOS Group, Dongfang Hongye Limited Company, LyondellBasell Industries Holdings B.V., Lubrizol Corporation, Braskem, BASF SE, DAELIM, TPC Group, Mitsui Chemicals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polybutene Market Shifts & Advancements
Formulation science is converging with regulatory documentation requirements to reshape how polybutene suppliers structure technical service relationships. Three developments are compressing traditional transactional models.
Metallocene catalyst systems are integrating into polybutene-1 production lines to narrow molecular weight distribution and reduce color bodies. European compounders serving cosmetic and pharmaceutical sectors are adopting these grades fastest, with specification lock-ins now extending to 5-7 year supply agreements. This technology is integrating quality consistency into contract structures that previously traded on spot resin pricing.
REACH Article 33 substance disclosure obligations are forcing full supply chain transparency for butene-derived materials. European formulators must now document every catalyst residue and process additive down to 0.1% concentration thresholds. Adhesive manufacturers serving automotive interiors are most affected, with several reformulating away from phthalate co-additives entirely.
Buyers in packaging and construction sectors are consolidating supplier panels and demanding integrated formulation support rather than commodity resin transactions. Technical service teams now co-develop seal layer architectures and pipe compound specifications directly with end-users. This pattern is most visible in China's state-led infrastructure procurement, where qualified supplier lists have compressed from 12-15 to 4-6 approved sources per project tier.
Global Polybutene Market Segmentation
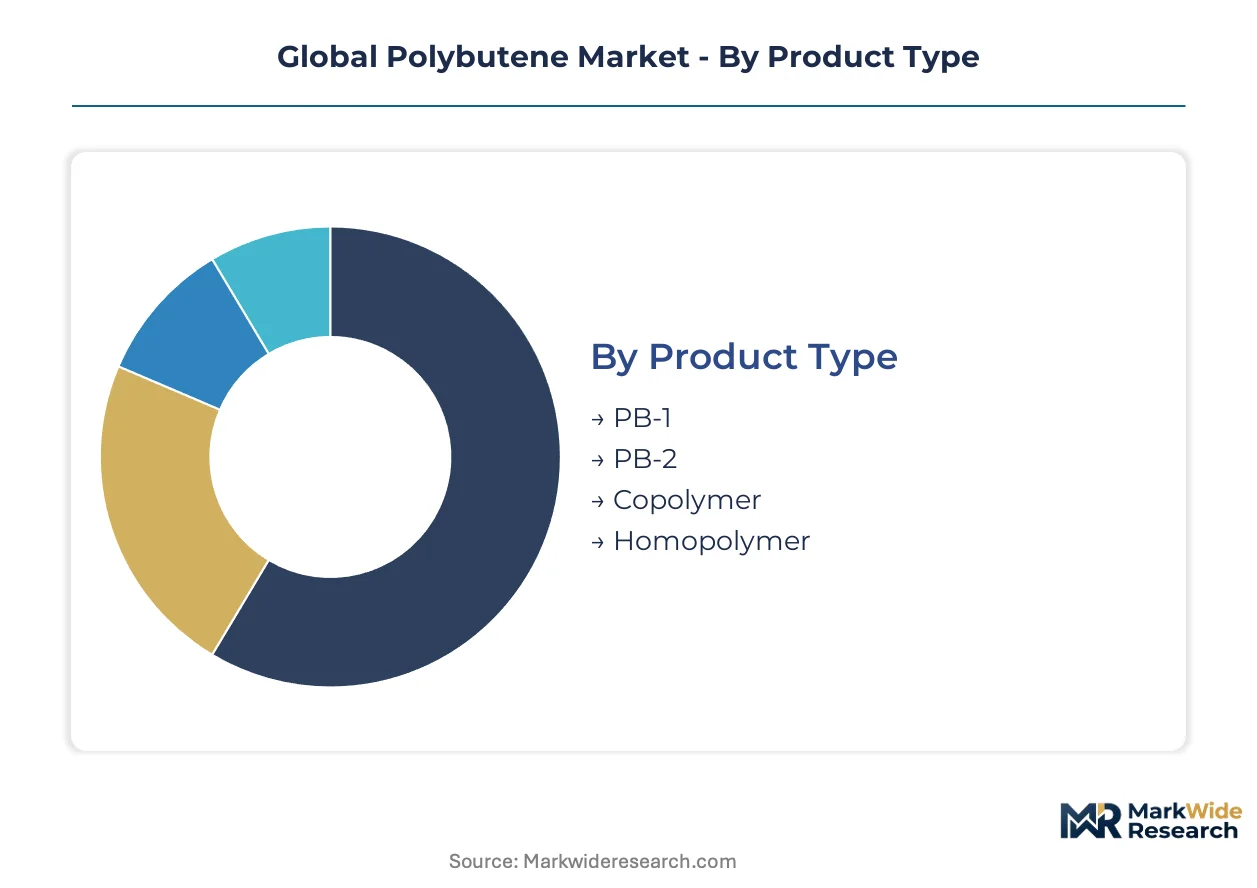
Polybutene's molecular weight range and viscosity grades create distinct performance tiers that map directly to end-use specifications. Upgrade cycles in pipe infrastructure and reformulation mandates in packaging are reshaping how buyers match product categories to application requirements.
Product Type:
Replacement cycles in hot water piping systems and cosmetic formulation standards are driving specification upgrades across molecular weight grades.
- Homopolymer:High-purity grades with narrow molecular weight distribution serve pharmaceutical and cosmetic applications where batch consistency and low color are mandatory. European compounders and Japanese manufacturers have locked in 5-7 year supply agreements for these specifications.
- Copolymer:Tailored architectures with controlled comonomer incorporation deliver peel strength and temperature resistance for adhesive formulations. Demand concentrates in automotive interior bonding where REACH Article 33 disclosure obligations are forcing reformulation away from restricted additives.
- PB-1:Isotactic resin dominates pressurized hot water pipe systems across Asian construction markets.
- PB-2:Lower molecular weight fractions serve lubricant additive applications with faster formulation turnover.
Homopolymer sits at the top of the volume ranking, with copolymer climbing the fastest as adhesive specifications tighten.
Application:
Cost tier differentiation separates commodity resin sales from formulation partnerships that bundle technical service.
- Hot Water Pipes:PB-1 resin specifications govern municipal heating retrofits in China and residential construction in India. State-led procurement in China has compressed qualified supplier lists from 12-15 to 4-6 approved sources per project tier.
- Packaging Films:Multilayer seal layers incorporate polybutene for integrity under tightening FDA food-contact and EU packaging waste directives. Mono-material designs are gaining preference as extended producer responsibility frameworks incentivize simplified recycling streams.
- Adhesives:Tackifier applications compete with isotactic polypropylene substitution in non-critical bonding.
- Sealants:Construction-grade formulations balance cost against weathering performance.
- Lubricants:Viscosity index modifiers face margin pressure from C4 feedstock volatility.
Hot water pipes command the largest volume position, with packaging films expanding most quickly on regulatory tailwinds.
End User Industry:
Customer type segmentation reveals how procurement consolidation is favoring suppliers with integrated formulation capabilities.
- Construction:Infrastructure spending in China and India anchors PB-1 resin demand for pressurized piping. Project developers now require direct technical collaboration on pipe compound specifications rather than commodity transactions.
- Food Packaging:FDA food-contact notification protocols and evolving migration standards govern molecular weight fraction approval. Notification timelines of 18-24 months delay new grade commercialization.
- Personal Care:Clean-label positioning is driving reformulation toward polybutene-1 as silicone alternatives in color cosmetic vehicles.
- Automotive OEMs:Interior adhesive specifications are tightening under REACH substance disclosure requirements.
- Electronics:Barrier coating applications are redirecting demand as per- and polyfluoroalkyl substance restrictions limit fluoropolymer alternatives.
Construction holds the volume lead, with food packaging gaining share fastest on seal integrity mandates.
Packaging Type:
Supply concentration in high-purity production clusters shapes availability across physical form factors.
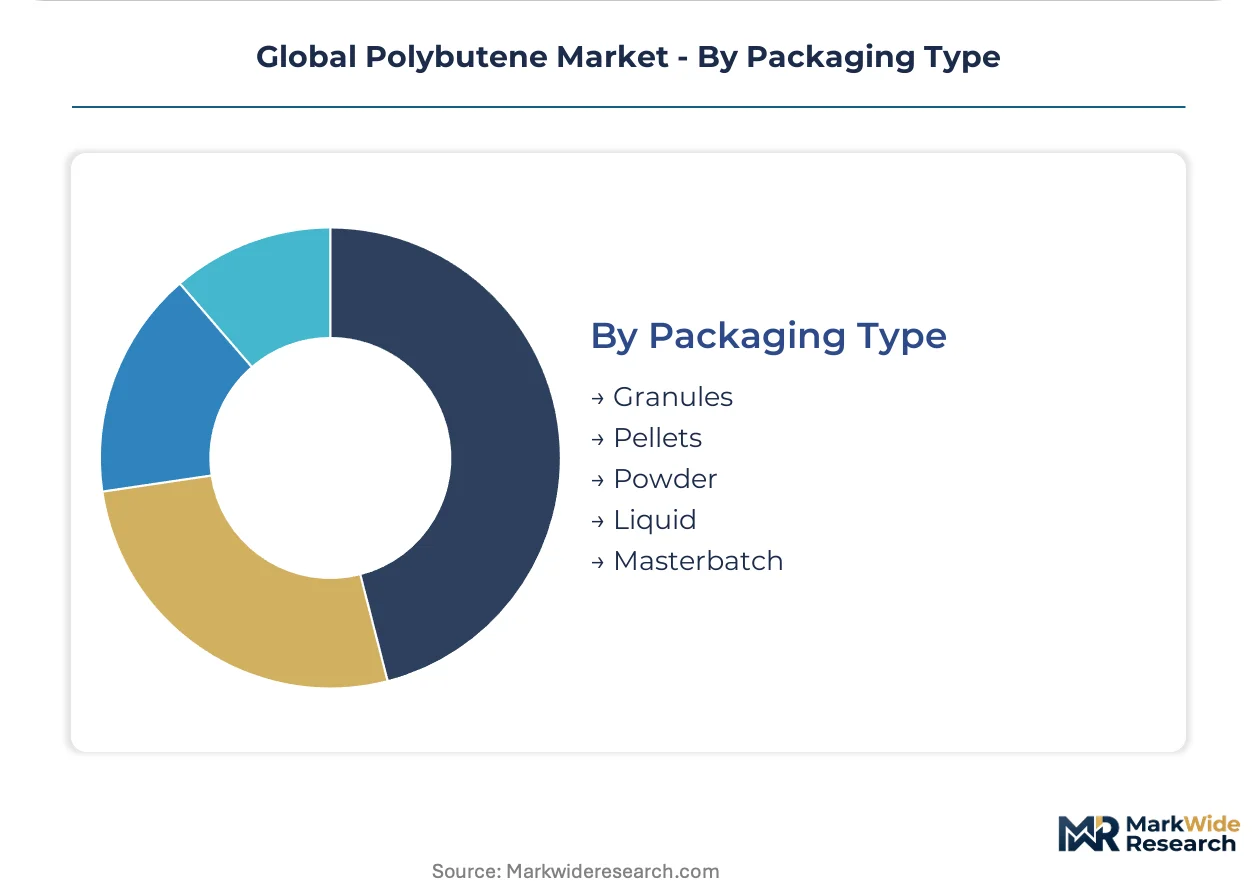
- Pellets:Standard extrusion feedstock for pipe and film processing with established handling infrastructure.
- Granules:Bulk delivery format for large-volume compounders with integrated grinding capacity.
- Liquid:Direct-use form for lubricant blending and cosmetic formulation bypassing melt processing.
- Masterbatch:Concentrated additive carriers for customized compound development.
- Powder:Niche applications in specialized coating and sintering processes.
Pellets occupy the top volume position, with liquid formats climbing fastest on cosmetic and lubricant formulation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's municipal heating retrofits consume more PB-1 resin than India's entire residential construction pipeline, yet both countries face tightening impurity standards that favor certified suppliers. Germany's REACH documentation requirements exceed those in the United States, creating asymmetric compliance costs across Atlantic supply chains. Japan maintains the narrowest molecular weight distribution specifications for pharmaceutical-grade material.
China
State-led infrastructure procurement anchors PB-1 resin demand for pressurized hot water piping systems in municipal heating retrofits across northern provinces. SAMR's evolving GB standards for construction materials now require migration testing documentation that mirrors EU REACH protocols. The Yangtze River Delta cluster hosts compounders supplying pipe specifications directly to state-owned developers who have compressed qualified supplier lists from 12-15 to 4-6 approved sources per project tier.
India
Residential construction surges in Mumbai and Bangalore are accelerating hot water pipe installations that specify polybutene seal layers. CDSCO's tightening impurity thresholds for pharmaceutical-grade material are creating entry points for certified high-purity suppliers previously excluded from formulation supply chains. The Gujarat chemical belt houses domestic compounders reformulating adhesive grades to meet automotive interior specifications under REACH-equivalent disclosure obligations.
Germany
Automotive adhesive manufacturers in Stuttgart and Munich are reformulating away from phthalate co-additives under ECHA's REACH Article 33 substance disclosure requirements. The country's national chemical regulator mandates 0.1% concentration thresholds for catalyst residue documentation across butene-derived materials. The Ruhr industrial corridor sustains solution-phase production expertise that remains scarce outside established European manufacturing clusters.
United States
Multilayer food packaging film producers in the Midwest are expanding polybutene seal layer capacity under FDA food-contact notification protocols. EPA TSCA Section 5 reviews govern which molecular weight fractions may migrate into packaged food matrices, with notification timelines delaying new grade commercialization by 18-24 months. The Gulf Coast petrochemical corridor leverages mixed C4 refinery stream access to supply tackifier and lubricant additive markets.
Japan
Cosmetic formulators in Osaka and Tokyo are integrating polybutene-1 with silicone alternatives in color cosmetic vehicles as brands reformulate for clean-label positioning. METI's guidance on per- and polyfluoroalkyl substance alternatives is redirecting barrier coating demand toward polybutene-based materials. The Chubu region hosts specialized producers of high-purity grades where batch consistency and low color are non-negotiable for pharmaceutical applications.
Global Polybutene Market Competitive Landscape
Top-tier vendors anchor premium-grade production, while mid-scale compounders compete on formulation service bundling. The market structure concentrates high-purity homopolymer manufacturing among specialized European and Japanese producers, creating supply vulnerability for buyers seeking pharmaceutical and cosmetic grades. Three strategic archetypes dominate: integrated petrochemical majors with captive C4 feedstock access, specialized polymer producers with solution-phase technology expertise, and regional compounders offering customized sealant and adhesive formulations. Competitive moves center on backward integration into refinery stream sourcing and five-to-seven-year specification lock-in contracts with cosmetic and pharmaceutical formulators.
Within the integrated petrochemical tier, INEOS Group and LyondellBasell Industries Holdings B.V. exemplify producers leveraging European crackers and large-scale solution-phase assets to sustain captive feedstock control. Mitsui Chemicals, Inc. occupies a position among specialized high-purity manufacturers serving pharmaceutical and cosmetic applications where impurity thresholds are most stringent. These three companies represent the dominant competitive vectors: feedstock security, production scale, and specification-grade purity certification.
| Leading Market Players |
|---|
| INEOS Group |
| Dongfang Hongye Limited Company |
| LyondellBasell Industries Holdings B.V. |
| Lubrizol Corporation |
| Braskem |
| BASF SE |
| DAELIM |
| TPC Group |
| Mitsui Chemicals, Inc. |
| Others |
Supply & Pricing Matrix
Homopolymer-to-copolymer grade divergence creates a bifurcated margin structure where pharmaceutical and cosmetic specifications command substantial premiums over commodity adhesive grades, with this tier separation reinforced by solution-phase production expertise clustering in Germany and Japan against commodity-scale operations along the US Gulf Coast. REACH documentation depth and FDA food-contact certification timelines now function as pricing gates that filter suppliers into long-term specification lock-ins or spot-market resin transactions.
Pricing Analysis
Capacity additions in China are reshaping price floors for PB-1 pipe resin as state-led procurement consolidates around 4-6 qualified suppliers per project tier. Pricing stratifies across premium, standard, and economy tiers based on molecular weight distribution narrowness and catalyst residue documentation completeness. Cost compression in standard-grade lubricant additives is intensifying because C4 refinery stream volatility feeds directly into margin unpredictability. Construction sector buyers exhibit highest price sensitivity, while pharmaceutical formulators prioritize batch consistency over unit cost.
Supply Chain Analysis
Solution-phase process engineering talent scarcity in the Ruhr corridor and Chubu region constrains expansion of high-purity homopolymer capacity. Manufacturing concentrates in Germany, Japan, and the United States, with feedstock drawn from European crackers, Asian refinery streams, and Gulf Coast mixed C4 outputs. Single-source vulnerability persists for pharmaceutical-grade material where specialized producers maintain tight specification control. Distribution runs through qualified supplier lists in China's state infrastructure procurement and direct technical service relationships with European compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance costs in Europe exceed FDA notification burdens in the United States, creating asymmetric margin capture opportunities for suppliers with dual-continent certification infrastructure.
For Market Incumbents: To counter isotactic polypropylene substitution in non-critical adhesive applications, deepen captive feedstock control through European cracker integration and secure 5-7 year specification lock-ins with cosmetic formulators reformulating for clean-label positioning. Prioritize metallocene catalyst deployment to narrow molecular weight distribution and defend premium positioning.
For New Entrants and Emerging Players: Enter via India's CDSCO-certified pharmaceutical-grade supply gap, where tightening impurity thresholds exclude incumbent commodity producers. Target white-space in barrier coating applications as per- and polyfluoroalkyl substance restrictions redirect demand from fluoropolymers. Pursue direct technical collaboration with China's state-owned developers as qualified supplier lists compress.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized high-purity manufacturers possessing solution-phase technology expertise and existing pharmaceutical certification infrastructure. Long-term viability hinges on regulatory documentation capabilities rather than scale economics. Watch for ECHA substance restriction expansions that would accelerate fluoropolymer displacement as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into C4 Feedstock | Captive refinery stream access insulates margin predictability against raw material volatility in mixed butene supply. |
| Metallocene Catalyst System Deployment | Narrow molecular weight distribution grades command specification lock-ins with European cosmetic and pharmaceutical formulators. |
| REACH Article 33 Compliance Investment | Full supply chain substance disclosure capabilities qualify suppliers for automotive interior adhesive reformulation mandates. |
| Long-term Technical Service Agreements | Integrated formulation partnerships with China's state-owned developers replace transactional resin sales in infrastructure procurement. |
| Pharmaceutical-grade Capacity Expansion | CDSCO and NMPA certification creates entry points into high-margin formulation supply chains previously closed to commodity producers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with polymer plant managers, procurement leads at downstream packaging OEMs, lubricant blenders, and cosmetic formulation directors with secondary validation from customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA substance registration databases. Bottom-up grade-level volume estimates and top-down end-use demand aggregation were triangulated against refinery stream utilization data.
Segment-weighting approaches modeled homopolymer, copolymer, PB-1, and PB-2 product tiers across construction, food packaging, personal care, automotive, and electronics end-use industries, with geographic production hub and packaging format dimensions integrated throughout. CAGRs were derived from regression analysis of historical grade-level consumption patterns and projected infrastructure spending trajectories across the analysis window. Forecast inputs incorporated SAMR evolving GB standards documentation requirements and EPA TSCA Section 5 notification timelines.
Inputs from ECHA registration databases and FDA food-contact notification records were available through the study window; gaps in real-time C4 refinery stream pricing transparency introduce uncertainty bands around margin forecasts for commodity-grade producers. Material deviation in per- and polyfluoroalkyl substance regulatory expansion timelines or REACH substance restriction scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Microcellular Plastics Market
Polymers & Resins
Polyetherketoneketone (PEKK) Market
Polymers & Resins
Bio-Based Polycarbonate Market
Polymers & Resins
Global Engineering Plastic Market
Polymers & Resins
Global High Temperature Resin Market
Polymers & Resins
Global Polycarbonate Market
Polymers & Resins
Italy Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
North America Polyurethane Market
Polymers & Resins
Global Polyolefin Powders Market
Polymers & Resins
GCC Vinyl Flooring Market
Polymers & Resins
Middle East Polycarbonate (PC) Market
Polymers & Resins
Resin Intermediate Market
Polymers & Resins
Bio-Based PVC Market
Polymers & Resins
Global Protein a Resin Market
Polymers & Resins
Middle East Fluoropolymer Market
Polymers & Resins
Global Synthetic Polymers Market