
 Asia-Pacific Thermoplastics Market | 2026-2036
Asia-Pacific Thermoplastics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Thermoplastics Market Outlook
Multi-source resin procurement is decoupling from the traditional petrochemical nexus across Southeast Asian manufacturing hubs. BASF SE leverages its Ludwigshafen technology base to sustain high-performance polyamide supply chains into Chinese automotive tier-ones. LG Chem anchors domestic polyethylene capacity through integrated Daesan crackers, while Mitsubishi Engineering-Plastics Corporation specializes in engineering-grade compounds for Japanese electronics OEMs.
Thermoplastics are polymers that soften upon heating and solidify when cooled, enabling repeated melt-processing without significant chemical degradation; most commercial grades melt between 120°C and 340°C depending on backbone structure and crystallinity. Polypropylene dominates volume flows across Asia-Pacific packaging applications due to its balance of stiffness, chemical resistance, and recyclability. Polyamide commands premium positioning in automotive under-hood segments where heat resistance and dimensional stability justify higher compound costs. Injection molding remains the primary conversion route for precision components, though 3D printing adoption is expanding for prototyping and low-volume tooling in Japanese and South Korean electronics clusters.
China's MEE enforces dual carbon emission thresholds that restrict high-carbon polyolefin expansions and favor recycled-content mandates. Japan's METI oversees JIS standards for automotive plastics that dictate flame-retardancy and VOC specifications for interior applications. India's BIS certification requirements for food-contact polyethylene and polypropylene create compliance barriers for unqualified importers. Stakeholders must track how carbon-border adjustments and extended-producer-responsibility frameworks will reshape raw-material sourcing economics and regional trade corridors.
Market Dynamics
China's MEE dual carbon goals are forcing a structural pivot away from virgin polyolefin capacity toward recycled-content and bio-based polyamide platforms, compressing traditional petrochemical margins while opening specialized compounder niches.
Growth Catalysts
- Automotive lightweighting mandates:Thailand and Vietnam OEMs are expanding thermoplastics consumption for under-hood and structural components to meet fuel-efficiency targets.
- MEE dual carbon thresholds:China's emission restrictions favor bio-based polyamide development and recycled-content mandates across packaging and automotive supply chains.
- Electronics miniaturization:Japanese and South Korean OEM clusters are driving engineering-grade compound demand for precision connectors and thermal management housings.
Market Restraints
- Naphtha feedstock volatility:Cracker economics across Northeast Asia remain exposed to crude-linked naphtha price swings, compressing polyethylene margin stability.
- Korean-Chinese supply concentration:Integrated Daesan and Ningbo crackers control regional polyethylene volume, creating single-source vulnerability for Southeast Asian converters.
- High-temperature polyamide technical ceiling:Standard grades face substitution from thermoset composites in powertrain applications exceeding 200°C continuous service.
Strategic Opportunities
- India packaging corridor expansion:Mumbai and Gujarat industrial zones offer underpenetrated demand for food-contact polyethylene with BIS-compliant domestic supply.
- 3D printing tooling convergence:Fused filament fabrication and selective laser sintering are converging with injection molding for low-volume electronics prototyping in Osaka and Seoul clusters.
- Extended producer responsibility tailwinds:Japan's METI circular economy frameworks mandate recycled-content ratios that favor compounders with post-consumer feedstock access.
Industry Challenges
- Polymer processing skill scarcity:Southeast Asian converters face shortages of mold flow simulation engineers and process technicians for multi-material overmolding.
- BIS certification timeline friction:India's food-contact polyethylene approval cycles create 12-18 month barriers for unqualified importers seeking packaging market entry.
- Legacy equipment retrofit complexity:Chinese recyclers struggle to reconfigure single-screw extruders for post-consumer polypropylene with variable melt-flow indices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Thermoplastics Market |
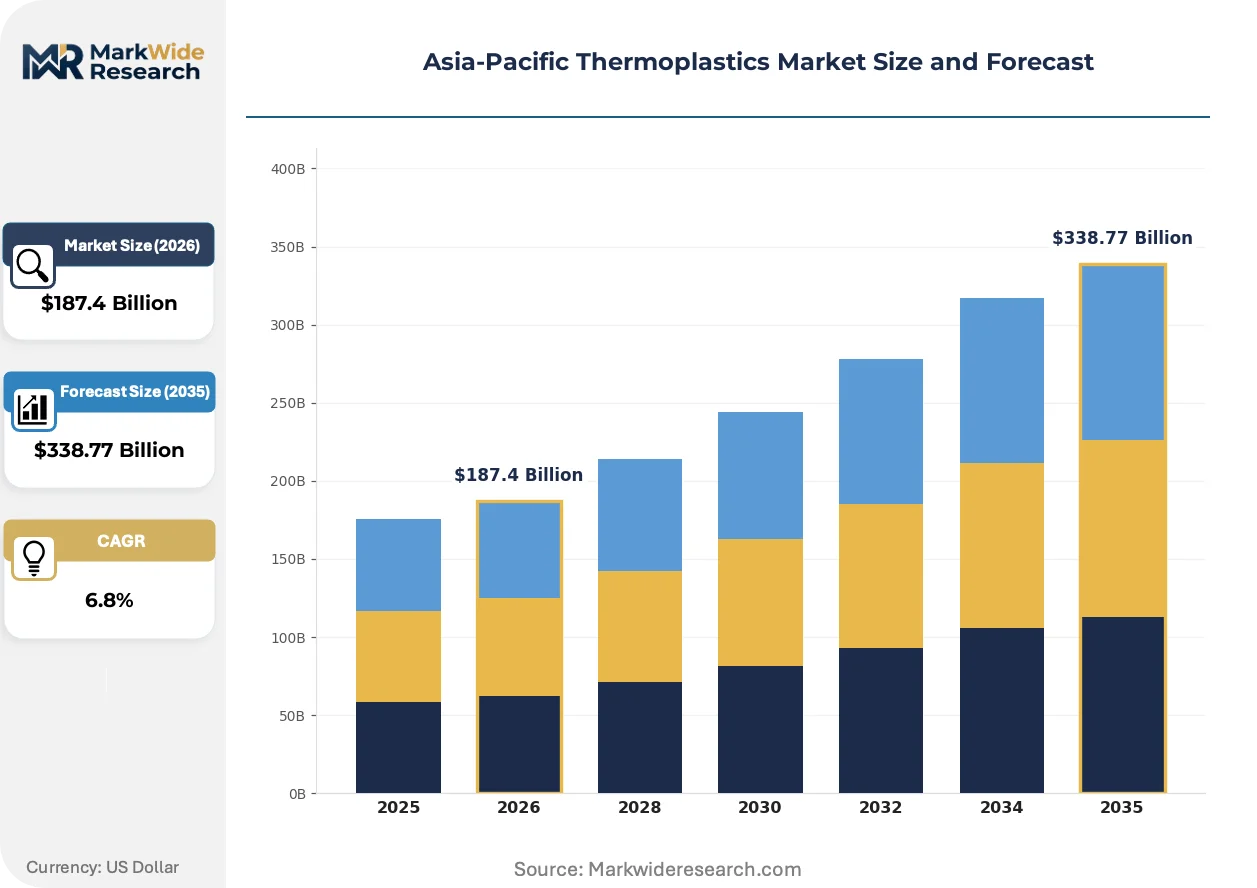
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyethylene, Polycarbonate, Polyamide End User: Automotive Manufacturers, Consumer Goods, Electronics, Packaging Application: Injection Molding, Extrusion, Blow Molding, 3D Printing Form: Granular, Pellets, Sheets, Films |
| Companies Covered | Asahi Kasei Corporation, LG Chem, Mitsubishi Engineering-Plastics Corporation, TEIJIN LIMITED, DuPont, BASF SE, Arkema, Celanese Corporation, Polyplastics Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Thermoplastics Market Strategic Shifts
Bio-based feedstock integration, regulatory carbon accounting, and distributed recycling infrastructure are reshaping how thermoplastics flow through Asia-Pacific value chains.
Long-chain bio-polyamides derived from castor oil are expanding into automotive fuel-line and air-intake manifolds where heat resistance and moisture stability matter. Tier-one suppliers in Shanghai and Nagoya are qualifying these grades at commercial scale. The technology is expanding into segments previously locked by petroleum-based PA6 and PA66 supply contracts.
Japan's METI has tightened JIS K 6911 flame-retardancy and VOC emission standards for automotive interior plastics, forcing compounders to reformulate halogen-free additive packages. Interior trim suppliers in Toyota City and Yokohama are accelerating low-emitting polypropylene deployment. Chinese automotive exporters to Japan now face parallel certification burdens under both GB and JIS regimes.
Brand-led recycled-content procurement is compressing traditional spot-market resin buying across Mumbai and Bangkok packaging clusters. Major FMCG distributors are mandating post-consumer polyethylene percentages that bypass commodity traders. This pattern is most visible in India's Western industrial corridor where converters negotiate direct offtake with mechanical recyclers.
Asia-Pacific Thermoplastics Market Segmentation
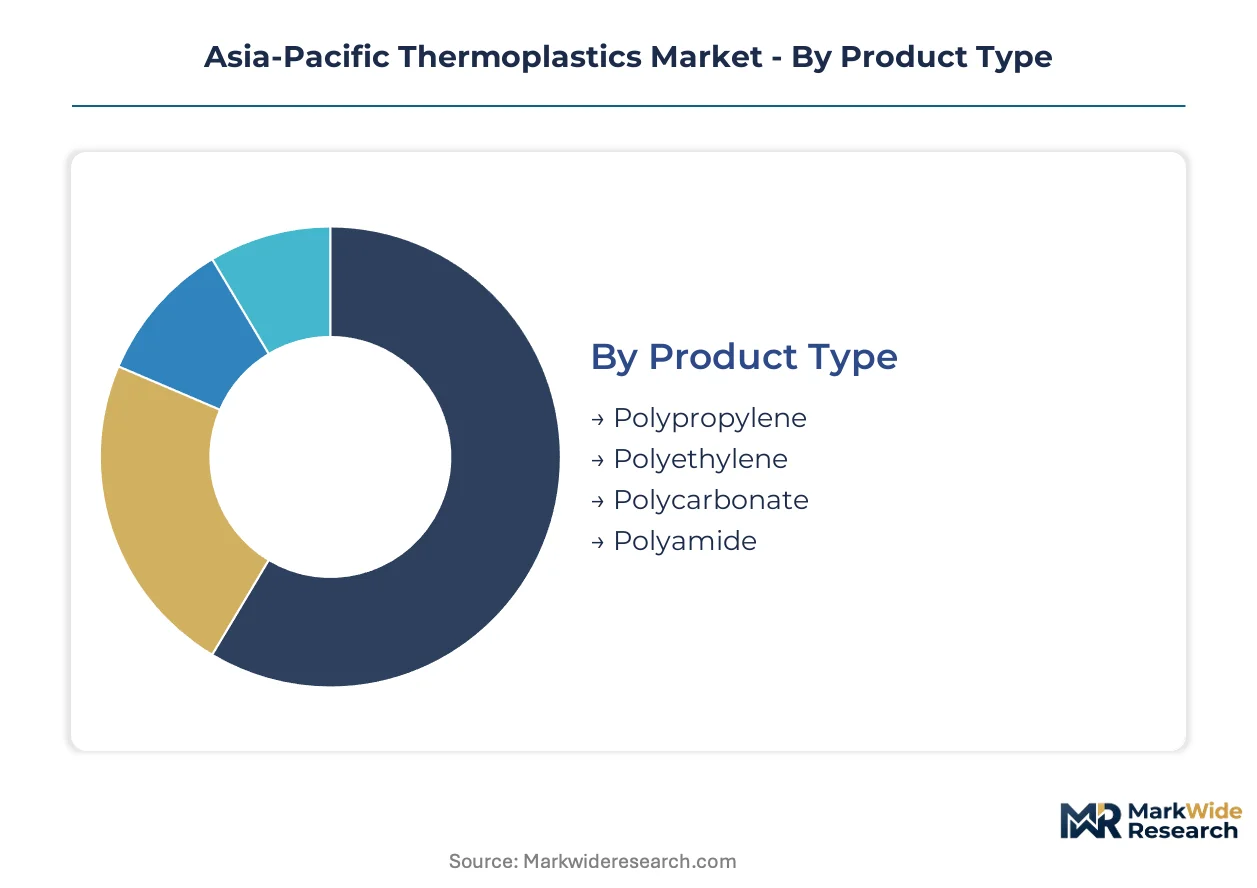
Thermoplastics flow through Asia-Pacific value chains along four distinct axes that determine pricing power, technical specifications, and regulatory exposure. Product chemistry dictates heat resistance and mechanical performance thresholds. End-use concentration shapes volume procurement patterns across automotive clusters and packaging corridors.
Product Type:
Polymer backbone structure determines melt-processing windows, crystallinity rates, and end-use suitability across temperature and load-bearing requirements.
- Polypropylene:Semi-crystalline polymer with melting points between 160°C and 171°C depending on isotacticity grade. Demand concentrates in India's Mumbai-Gujarat packaging corridor where BIS-compliant food-contact grades face supply bottlenecks.
- Polyethylene:Linear and branched variants span density gradients from 0.91 to 0.96 g/cm³, with high-density grades penetrating automotive fuel tanks across Thailand's Eastern Economic Corridor. Daesan and Ningbo crackers control regional volume allocation.
- Polycarbonate:Amorphous engineering thermoplastic with glass transition near 147°C, serving electronics housings in Osaka and Seoul precision manufacturing clusters.
- Polyamide:Hydrogen-bonded crystalline structures deliver continuous service above 150°C, with bio-based long-chain variants penetrating Shanghai automotive fuel-line applications under MEE dual carbon procurement mandates.
Polyethylene leads on scale; polyamide leads on momentum.
End User:
Customer procurement sophistication varies sharply between specification-driven automotive tier-ones and price-sensitive commodity packaging converters.
- Automotive Manufacturers:Thailand and Vietnam OEMs specify heat-stabilized glass-filled compounds for under-hood components, with JIS flame-retardancy compliance required for exports to Japanese assembly plants.
- Consumer Goods:Durable appliance housings and furniture components drive acrylonitrile-butadiene-styrene and polypropylene consumption across China's Yangtze River Delta manufacturing belt.
- Electronics:Miniaturized connectors and thermal management housings in Nagoya and Suwon clusters demand engineering-grade compounds with tight dimensional tolerances and low outgassing specifications.
- Packaging:Flexible film and rigid container applications across Bangkok and Jakarta processing hubs concentrate polyethylene and polypropylene demand, with recycled-content ratios rising under brand-led procurement mandates.
Packaging dominates volume throughput; electronics commands premium pricing.
Application:
Conversion technology selection locks in capital equipment requirements, cycle economics, and workforce skill profiles.
- Injection Molding:High-pressure clamping systems with precision screw designs dominate automotive and electronics component fabrication, requiring mold flow simulation expertise scarce across Southeast Asian converter bases.
- Extrusion:Single and twin-screw configurations produce continuous profiles and films, with Chinese recyclers struggling to reconfigure legacy equipment for post-consumer polypropylene with variable melt-flow indices.
- Blow Molding:Parison programming controls wall thickness distribution in fuel tanks and industrial containers, concentrated in Thai automotive supply chains.
- 3D Printing:Fused filament fabrication and selective laser sintering converge with conventional tooling for low-volume electronics prototyping in Osaka and Seoul innovation clusters.
Injection molding anchors installed capacity; 3D printing expands most quickly.
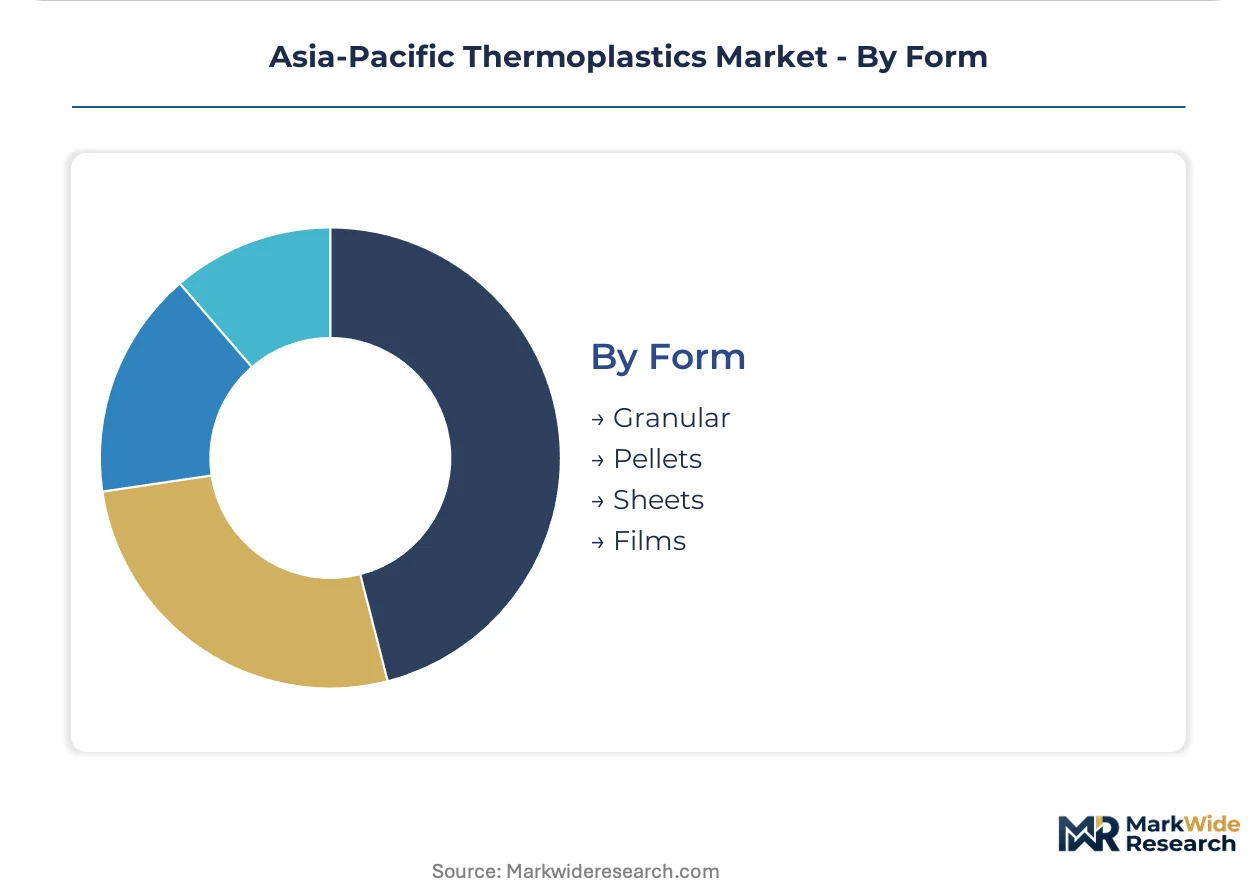
Form:
Physical presentation determines handling logistics, storage requirements, and downstream processing compatibility.
- Granular:Irregular particle morphology suits bulk pneumatic conveying systems at high-volume Chinese polyolefin plants serving domestic compounders.
- Pellets:Uniform cylindrical dimensions enable precise dosing in automated injection molding cells across Japanese electronics subcontractor networks.
- Sheets:Calendered and extruded flat stock feeds thermoforming operations for appliance liners and automotive interior trim in Korean manufacturing zones.
- Films:Biaxially oriented and cast variants serve flexible packaging laminations, with Mumbai converters negotiating direct offtake from mechanical recyclers to meet post-consumer content mandates.
Pellets standardize precision manufacturing; films capture sustainability-driven specification shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting thermoplastics investment toward jurisdictions with lower carbon-compliance costs, while MEE dual carbon enforcement in China pushes bio-based capacity development into Vietnam and Thailand manufacturing corridors.
China
Automotive tier-ones in Shanghai and Ningbo are qualifying long-chain bio-polyamides for fuel-line applications under MEE procurement mandates. The dual carbon framework restricts virgin polyolefin expansions while favoring recycled-content ratios in packaging supply chains. Yangtze River Delta compounders are retrofitting extrusion lines for post-consumer polypropylene with variable melt-flow indices.
Japan
METI-enforced JIS K 6911 standards for flame-retardancy and VOC emissions are reformulating automotive interior compounds across Toyota City and Yokohama clusters. Electronics OEMs in Nagoya and Osaka demand engineering-grade materials with tight dimensional tolerances for miniaturized connectors. Japanese recyclers are scaling distributed infrastructure to meet circular economy recycled-content mandates.
India
BIS certification requirements for food-contact polyethylene create 12-18 month entry barriers for unqualified importers targeting Mumbai-Gujarat packaging corridors. Domestic converters are negotiating direct offtake with mechanical recyclers to satisfy brand-led post-consumer content mandates. Process technician shortages constrain multi-material overmolding adoption across Western industrial zones.
Thailand
OEMs in the Eastern Economic Corridor are expanding glass-filled polyamide consumption for under-hood lightweighting to meet fuel-efficiency targets. High-density polyethylene grades penetrate automotive fuel tank applications alongside blow-molding capacity expansion. Mold flow simulation engineer scarcity limits precision component fabrication for Japanese export supply chains.
South Korea
LG Chem's integrated Daesan crackers anchor domestic polyethylene supply for electronics subcontractor networks in Suwon and Seoul. Engineering-grade compound demand concentrates in precision thermal management housings for semiconductor equipment. Fused filament fabrication and selective laser sintering are converging with injection molding for low-volume prototyping in Seoul innovation clusters.
Asia-Pacific Thermoplastics Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue bio-based specialization and recycled-content compounding. The market structure reflects moderate consolidation around integrated petrochemical majors and differentiated engineering-plastics specialists. Three archetypes dominate: integrated crackers with captive monomer supply, regional compounders with formulation expertise, and sustainability-focused innovators with post-consumer feedstock access. Capacity expansion and strategic partnerships represent the dominant competitive vectors as players secure raw-material access and qualification relationships with automotive tier-ones.
Among Asia-Pacific-based material suppliers, Asahi Kasei Corporation, LG Chem, and Mitsubishi Engineering-Plastics Corporation exemplify distinct strategic positions. Asahi Kasei represents the diversified chemical conglomerate archetype with cross-segment polymer capabilities. LG Chem anchors the integrated petrochemical model with domestic cracker infrastructure. Mitsubishi Engineering-Plastics Corporation occupies the engineering-grade specialization tier serving precision electronics and automotive applications. BASF SE and DuPont exemplify multinational technology licensors leveraging Ludwigshafen and Wilmington R&D bases to sustain high-performance polyamide supply chains into Chinese automotive OEMs. TEIJIN LIMITED, Arkema, and Celanese Corporation sit within the advanced materials tier with carbon-fiber-reinforced and high-heat polymer portfolios. Polyplastics Co., Ltd. represents the focused engineering-compound specialist archetype concentrated in Japanese electronics clusters.
| Leading Market Players |
|---|
| Asahi Kasei Corporation |
| LG Chem |
| Mitsubishi Engineering-Plastics Corporation |
| TEIJIN LIMITED |
| DuPont |
| BASF SE |
| Arkema |
| Celanese Corporation |
| Polyplastics Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Automotive tier-one procurement clusters in Shanghai and Nagoya anchor contract-based long-term offtake pricing for engineering-grade polyamides, compressing spot-market liquidity for commodity polyolefins across Southeast Asian converter bases. This buyer concentration forces compounders to absorb naphtha feedstock volatility through formula pricing clauses tied to regional cracker margins.
Pricing Analysis
Distributor margins on standard-grade polypropylene in Bangkok and Jakarta clusters absorb the primary pricing pressure from volatile naphtha feedstock costs. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified automotive compounds from BIS-compliant food-contact grades and generic packaging resins. Cost compression in standard polyolefins is intensifying because Chinese recyclers are flooding secondary markets with post-consumer pellets. Packaging converters in Mumbai-Gujarat corridors exhibit highest price sensitivity, while Japanese electronics OEMs prioritize dimensional tolerance over unit cost.
Supply Chain Analysis
Post-consumer polypropylene collection and mechanical reprocessing flows are reconfiguring raw-material sourcing economics across Yangtze River Delta compounders. Primary resin production concentrates in China, South Korea, and Thailand, with Daesan and Ningbo crackers controlling regional polyethylene volume allocation. Supply chains draw from crude-linked naphtha, bio-based castor oil feedstocks, and post-industrial scrap streams. Single-source vulnerability pervades Southeast Asian converter bases dependent on Korean-Chinese cracker output. Distribution runs through integrated petrochemical majors, regional compounders with formulation expertise, and sustainability-focused innovators with mechanical recycling access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific thermoplastics market functions as a stable compounder anchored by MEE dual carbon enforcement that locks in decade-long demand for bio-based and recycled-content platforms.
For Market Incumbents: Deepen backward integration into bio-based feedstock supply through castor oil offtake partnerships in India and Southeast Asia to defend margin position against petroleum-based PA66 substitution. Accelerate JIS K 6911 certification investment for halogen-free automotive interior compounds to preempt regulatory exclusion from Toyota City and Yokohama supply chains. For New Entrants and Emerging Players: Distributed recycling infrastructure with variable melt-flow indexing capability offers the most penetrable white-space target, addressing Chinese recycler equipment retrofit failures and Indian BIS certification timeline friction. Pursue direct converter relationships in Mumbai-Gujarat packaging corridors through brand-led post-consumer content mandates, bypassing commodity trader intermediaries. For Investors and Strategic Acquirers: Integrated petrochemical majors with captive cracker infrastructure are the most active acquirer in this space, seeking engineering-grade formulation capabilities to diversify beyond commodity polyolefin exposure. Target compounders with post-consumer feedstock access and automotive tier-one qualification relationships. Monitor MEE recycled-content mandate enforcement thresholds as the inflection signal for bio-based polyamide demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | Castor oil supply partnerships in India secure long-chain polyamide raw material independence from petroleum price cycles. |
| JIS K 6911 Certification Investment | Halogen-free compound qualification opens Toyota City and Yokohama automotive interior supply chain access. |
| Mechanical Recycling Capacity Expansion | Post-consumer polypropylene reprocessing addresses MEE dual carbon mandates and brand-led procurement requirements. |
| Long-term Supply Agreement with Automotive Tier-ones | Fuel-line and under-hood component contracts with Shanghai OEMs lock in bio-polyamide volume commitments. |
| Joint Venture with Regional Compounders | Formulation expertise partnerships in Thailand and Vietnam accelerate lightweighting component localization. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with polymer plant managers, procurement leads at automotive tier-ones, distribution channel partners, and technical R&D directors with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and vehicle production databases. Bottom-up resin volume modeling and top-down end-use demand estimation provided cross-check triangulation.
Segment-weighting across product chemistry, end-use concentration, conversion technology, and physical form dimensions drove value allocation throughout the projection horizon. CAGRs were derived from trend extrapolation of historical trade flows and capacity expansion announcements, incorporating MEE dual carbon enforcement timelines, JIS standard revision cycles, and BIS certification throughput constraints as industry-specific forecast inputs.
The model holds under stable naphtha-cracker margin relationships and sustained MEE regulatory enforcement; deviation in crude price volatility spikes or recycled-content mandate delays would shift compounder profitability assumptions. Practitioners should monitor castor oil harvest yields and mechanical recycling equipment import tariffs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polymer Seals Market
Polymers & Resins
North America Polyamide Market
Polymers & Resins
Polydicyclopentadiene (Pdcpd) Market
Polymers & Resins
Vinyl Acetate Ethylene (VAE) Market
Polymers & Resins
Extruded Polystyrene Market
Polymers & Resins
Canada Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Europe Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Polyethersulfone (PES) Market
Polymers & Resins
PEKK Market
Polymers & Resins
Asia-Pacific Fluoropolymer Market
Polymers & Resins
Polymer Memory Market
Polymers & Resins
Polyvinyl Alcohol Resins Market
Polymers & Resins
Filled Fluoropolymer Market
Polymers & Resins
PET Foam Market
Polymers & Resins
Global Polyphenylene Market
Polymers & Resins
China Engineering Plastics Market