
 Acacia Gum Market | 2026-2036
Acacia Gum Market Size, Share, and Industry Trends Forecast 2026-2036
Acacia Gum Market Analysis
Wild acacia tapping expertise across the African Sahel is collapsing as younger generations migrate to urban centers, constraining raw material flows from Sudan and Chad. Nexira anchors its supply security through backward integration into farmer cooperatives across the gum belt. Alland & Robert differentiates via proprietary spray-drying technology for instantized beverage applications. Agrigum International Limited dominates bulk pharmaceutical-grade shipments to European excipient buyers.
Acacia gum is a complex polysaccharide exudate harvested from Acacia senegal and Acacia seyal trees, comprising arabinogalactan proteins with molecular weights spanning 300 to 800 kDa, functioning primarily as an emulsifier, stabilizer, and film-forming agent across food and pharmaceutical matrices. The organic gum segment captures premium pricing from European clean-label formulators, while the dietary supplements application records the fastest volume expansion as prebiotic fiber claims proliferate in North American nutraceutical SKUs. Food grade classifications still occupy the largest value pool, though industrial grade volumes face displacement from synthetic hydrocolloid alternatives in non-food adhesive applications.
FDA food additive regulations under 21 CFR 172.780 govern acacia gum's GRAS status for U.S. market access, while EFSA purity specifications and the EU Food Additive Regulation (EC) No 1333/2008 enforce residual solvent and microbiological limits for European imports. Sudan's national gum council applies export licensing and quality grading protocols that directly shape global spot pricing and lot traceability. Stakeholders must monitor whether Sahelian climate volatility and shifting generational labor preferences will force a decisive pivot toward cultivated acacia plantations or accelerated synthetic biopolymer substitution.
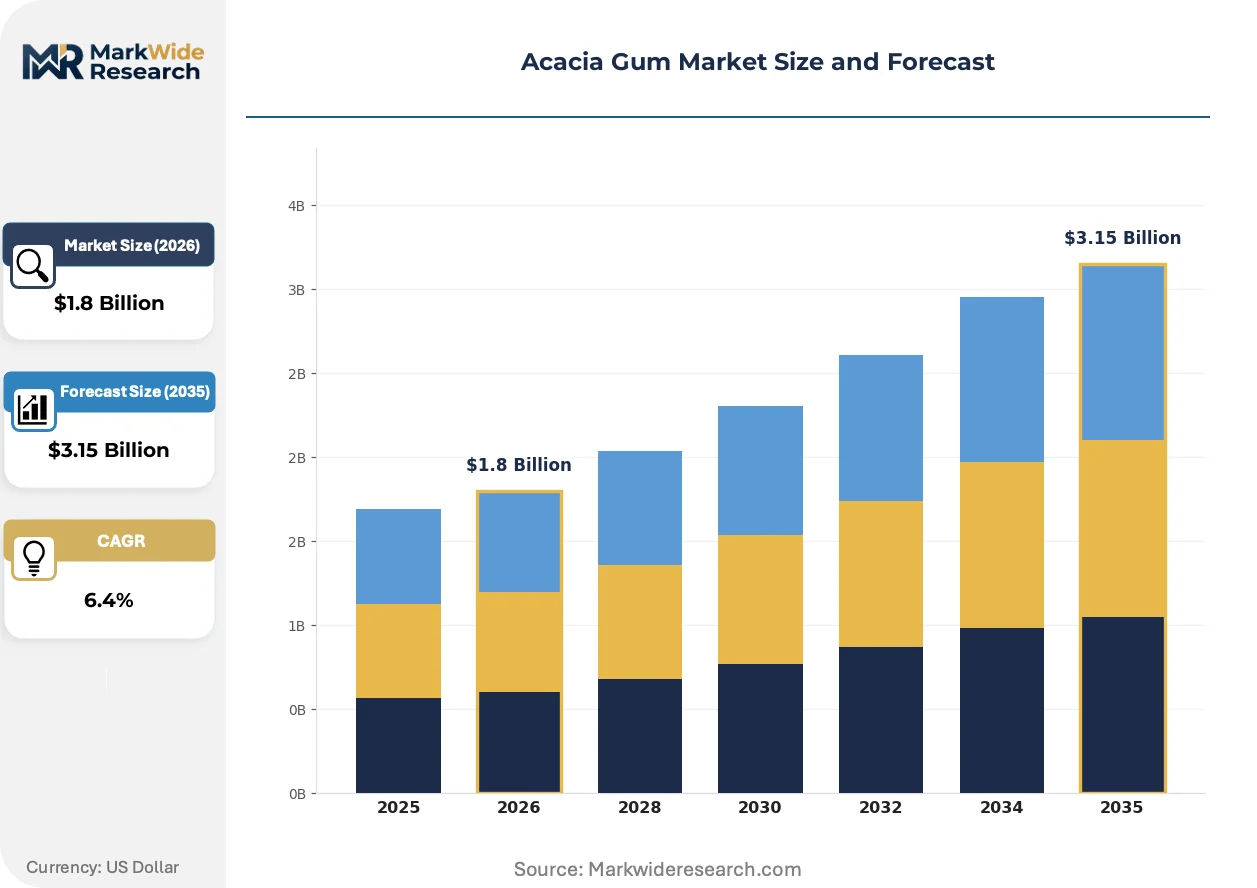
Market Dynamics
Generational abandonment of wild acacia tapping across the Sahel is compressing raw material flows faster than plantation alternatives can scale, forcing buyers into long-term offtake contracts with verified cooperatives.
Growth Catalysts
- EU Food Additive Regulation (EC) No 1333/2008:Updated purity benchmarks for acacia senegal and acacia seyal derivatives are locking synthetic emulsifiers out of clean-label formulations across French and German food manufacturing.
- Prebiotic fiber claims:North American nutraceutical formulators are expanding dietary supplement SKUs with acacia gum's soluble fiber credentials, driving volume pull through functional food channels.
- Sudan-Chad gum belt concentration:Verified sourcing corridors through farmer cooperatives are securing traceable supply for pharmaceutical-grade excipient buyers facing EFSA microbiological limits.
Market Restraints
- Sahelian labor migration:Urbanization among younger generations in Sudan and Chad is collapsing wild tapping expertise, constraining harvest volumes regardless of price signals.
- Synthetic hydrocolloid substitution:Modified starches and cellulose derivatives are displacing industrial-grade acacia gum in non-food adhesive applications where purity requirements are minimal.
- Climate volatility:Erratic rainfall patterns across the African Sahel are introducing harvest unpredictability that spot pricing mechanisms cannot adequately hedge.
Strategic Opportunities
- Cultivated acacia plantations:Controlled cultivation models in Senegal and Mali offer supply security alternatives to wild harvesting as generational labor pools contract.
- Instantized beverage applications:Spray-drying technology convergence with cold-water soluble gum variants opens premium positioning in ready-to-drink and sports nutrition formats.
- Pharmaceutical excipient certification:USP-NF and EP compliance for acacia gum in tablet binding and controlled-release matrices commands price premiums from generic drug manufacturers.
Industry Challenges
- Traceability system integration:Lot-level verification from Sahelian harvest points through European processing facilities requires capital-intensive digital infrastructure that fragmented supplier bases struggle to fund.
- Residual solvent compliance:Meeting EFSA specifications for microbiological and solvent limits demands processing upgrades that stretch mid-tier gum processors in Sudan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acacia Gum Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Gum, Natural Resin, Food Grade, Industrial Grade Application: Beverages, Bakery, Confectionery, Dietary Supplements End User: Food Manufacturers, Pharmaceutical Companies, Cosmetic Brands, Nutraceutical Firms Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Agrigum International Limited, Alland & Robert, Nexira, Foodchem International, Ingredion Incorporated, Kerry Group, Farbest Brands, Ashland Inc., TIC Gums, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acacia Gum Market Emerging Trajectories
Acacia gum processing is bifurcating between artisanal wild-harvest supply chains and technology-intensive purification systems, with regulatory enforcement determining which pathway captures margin.
Enzymatic hydrolysis of high-molecular-weight arabinogalactan proteins is decomposing traditional spray-drying economics for instantized applications. Beverage manufacturers in France and Germany are adopting these modified fractions for enhanced cold-water solubility. The technology is decomposing barriers between commodity food-grade supply and premium nutraceutical positioning.
EFSA's 2023 updated specifications on acacia gum purity are tightening residual solvent and microbiological thresholds for European imports. Sudan's national gum council has responded with mandatory export licensing protocols that align grading standards to EU benchmarks. French and German excipient buyers now require documentary evidence of compliance before contract execution.
Direct procurement from farmer cooperatives is displacing layered trader networks across the gum belt. European food manufacturers are establishing multi-year offtake agreements with verified Sudanese and Chadian suppliers. This pattern concentrates most visibly among French clean-label formulators seeking supply security beyond spot market volatility.
Acacia Gum Market Segmentation
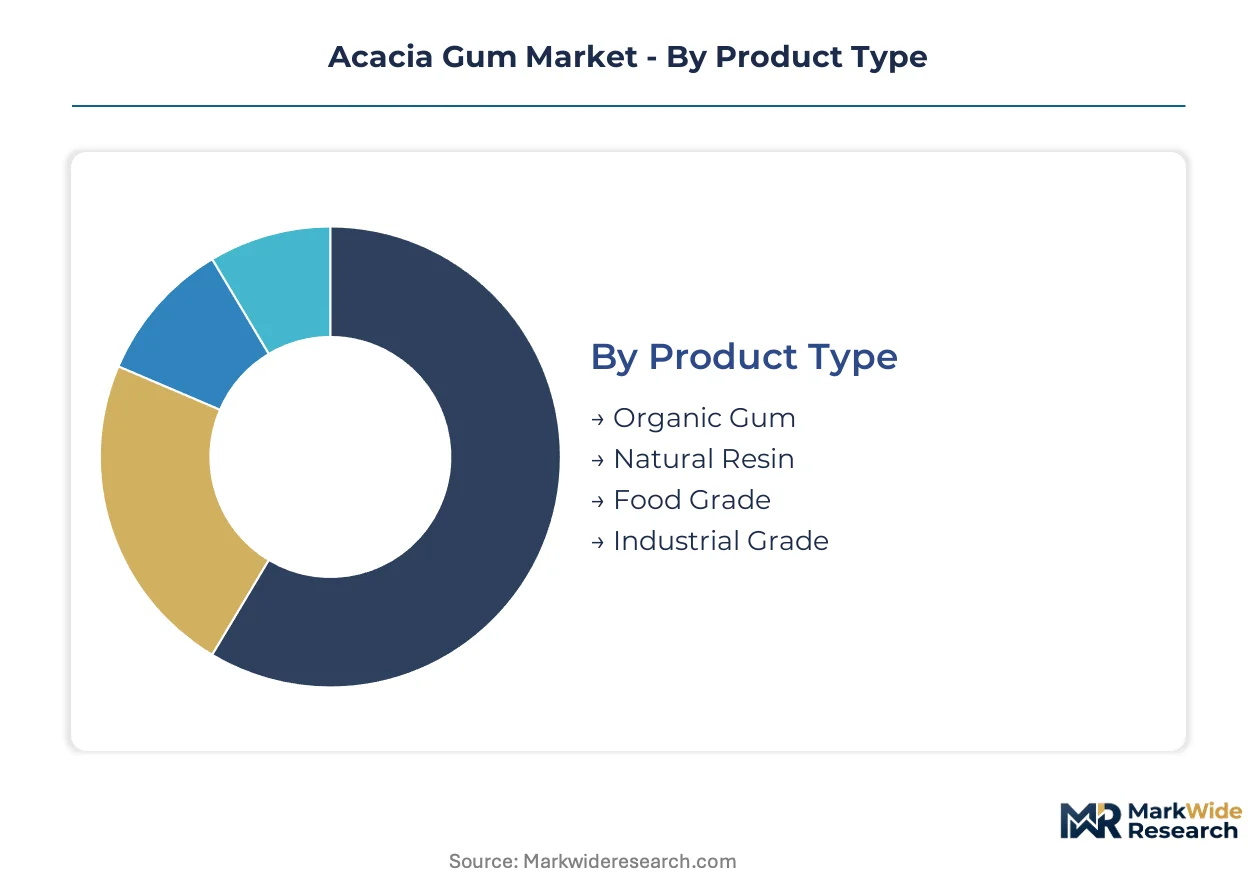
Acacia gum flows through distinct commercial channels depending on purity grade and end-use certification. Each segment carries different margin profiles and regulatory compliance burdens that reshape procurement strategies across food, pharmaceutical, and nutraceutical buyers.
Product Type:
Food-grade and industrial-grade volumes move primarily through distributor networks, while organic gum and natural resin command direct sales relationships with premium formulators.
- Organic Gum:Harvested from certified pesticide-free Acacia senegal stands across Sudan and Chad, this grade carries traceability documentation required by EFSA and EU organic certification bodies. French and German clean-label manufacturers absorb premium pricing to secure verified supply chains for infant nutrition and organic beverage applications. By volume, Food Grade leads. By growth pace, Organic Gum is ahead.
- Natural Resin:Raw exudate with minimal post-harvest processing retains higher arabinogalactan protein content for traditional pharmaceutical applications. Sudan's national gum council grades these lots for export licensing to European excipient buyers seeking USP-NF compliance for tablet binding matrices.
- Food Grade:Standardized through spray-drying and powder classification for emulsification in soft drinks, dairy alternatives, and processed foods. This segment channels through regional distributors serving mid-tier bakery and confectionery manufacturers.
- Industrial Grade:Lower-purity fractions with broader viscosity tolerances supply adhesive, textile sizing, and ceramic binder applications where synthetic hydrocolloid substitution is accelerating.
Organic certification creates the steepest price escalation, while industrial-grade buyers face the most aggressive substitution pressure from modified starches.
Application:
Application mix varies sharply by solubility requirements and regulatory claim potential, with instantized formats commanding technology premiums.
- Beverages:Cold-water soluble spray-dried fractions dominate ready-to-drink and sports nutrition formulations. French beverage manufacturers specify enzymatically hydrolyzed variants for enhanced dispersibility in functional drinks carrying prebiotic fiber claims.
- Dietary Supplements:Prebiotic positioning in North American nutraceutical SKUs drives volume expansion through capsule and powder formats. FDA GRAS status under 21 CFR 172.780 enables fiber content claims that differentiate against inulin and psyllium competitors.
- Bakery:Emulsification and moisture retention in gluten-free and clean-label bread applications. This segment channels through ingredient distributors serving regional bakery chains.
- Confectionery:Film-forming and sugar-crystallization control in chewing gum and pan-coated candies. Lower regulatory barriers allow broader supplier participation compared to pharmaceutical-grade segments.
Beverage applications generate the highest per-kilogram pricing, though dietary supplements are expanding most quickly.
End User:
Procurement sophistication divides end users between those requiring lot-level traceability and those purchasing on specification alone.
- Food Manufacturers:Large-scale bakery, beverage, and processed food producers negotiate annual contracts with verified cooperatives. EFSA microbiological compliance and residual solvent documentation are mandatory for European market access.
- Pharmaceutical Companies:Generic drug manufacturers source USP-NF and EP-compliant acacia gum for tablet binding, controlled-release matrices, and suspension stabilizers. Sudan-Chad supply corridors dominate this segment due to established certification protocols.
- Cosmetic Brands:Film-forming and emulsifying applications in skincare and haircare formulations. This segment tolerates broader origin sourcing compared to pharmaceutical buyers.
- Nutraceutical Firms:Prebiotic fiber and clean-label positioning in functional foods and supplements. North American buyers prioritize soluble fiber content claims over geographic origin verification.
Pharmaceutical buyers impose the strictest qualification requirements, while nutraceutical firms offer the most flexible procurement terms.
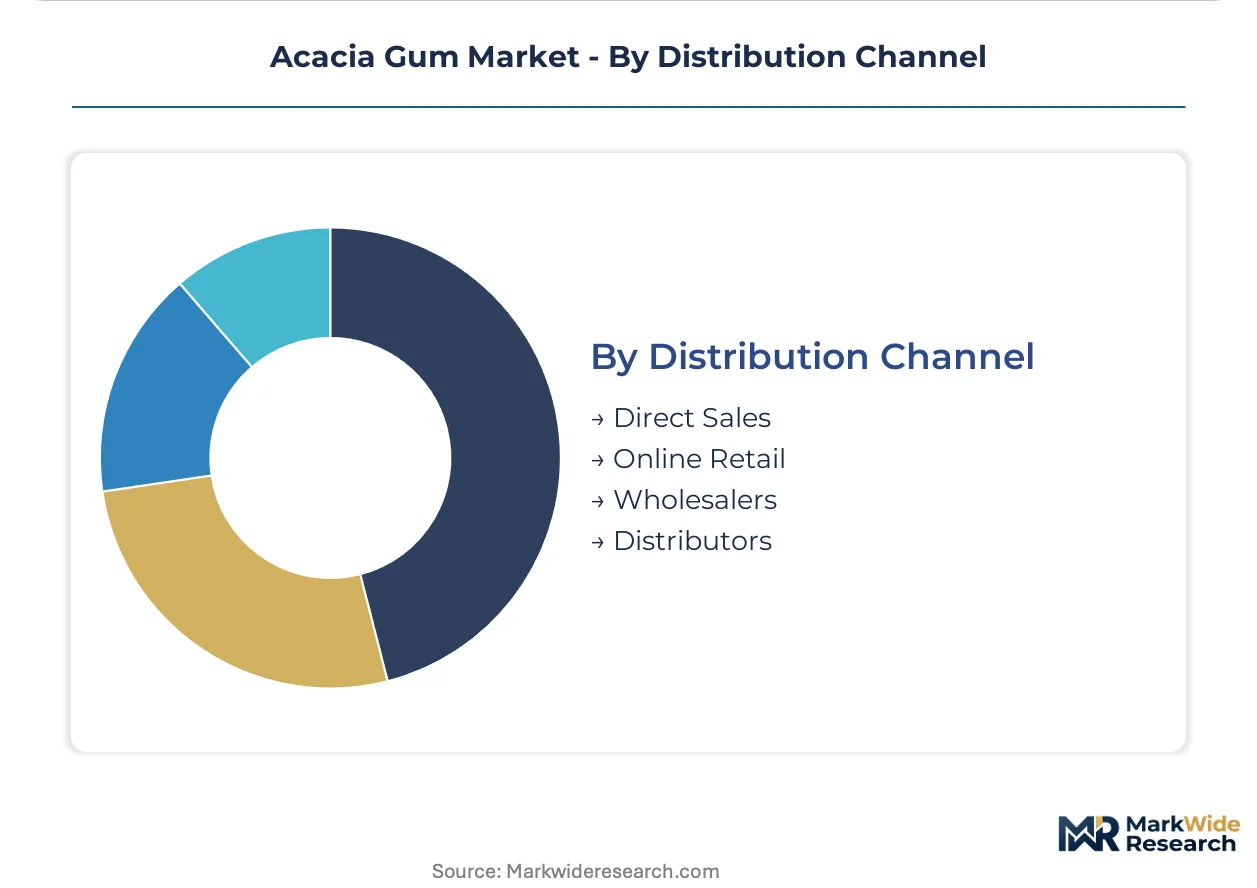
Distribution Channel:
Channel selection tracks shipment size, certification complexity, and buyer technical capability.
- Direct Sales:Multi-year offtake agreements between European food manufacturers and Sudanese farmer cooperatives eliminate trader margins. Nexira and Alland & Robert anchor supply security through backward integration into gum belt sourcing corridors.
- Distributors:Regional chemical and ingredient distributors serve mid-tier food and industrial buyers lacking technical qualification resources. This channel carries inventory risk and provides blending services.
- Wholesalers:Bulk commodity flows to industrial adhesive and textile sizing applications where purity requirements are minimal. Price competition from synthetic alternatives compresses margins in this channel.
- Online Retail:Small-lot sales to artisanal food producers, research institutions, and cosmetic formulators. Limited to non-pharmaceutical grades due to documentation requirements.
Distributors handle the largest aggregate tonnage, though direct sales are gaining share fastest among certified organic and pharmaceutical-grade buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA purity specifications under EU Food Additive Regulation (EC) No 1333/2008 anchor European demand for verified acacia senegal and acacia seyal derivatives, while FDA GRAS status under 21 CFR 172.780 governs U.S. market access protocols.
France
French clean-label formulators in infant nutrition and organic beverage applications drive premium organic gum procurement. ANSM enforces microbiological compliance documentation for pharmaceutical-grade imports. Paris-based excipient buyers now require multi-year offtake agreements with Sudanese cooperatives to bypass spot market volatility.
Germany
German beverage manufacturers specify enzymatically hydrolyzed acacia fractions for enhanced cold-water solubility in functional drinks. EFSA residual solvent thresholds shape import qualification protocols. Cologne-Düsseldorf industrial clusters concentrate spray-drying capacity for instantized sports nutrition formats.
United States
North American nutraceutical firms expand dietary supplement SKUs leveraging FDA GRAS prebiotic fiber claims. FTC advertising standards govern soluble fiber content assertions on product labels. New Jersey and California formulation hubs channel demand through direct importer relationships with gum belt cooperatives.
Sudan
Sudan's national gum council applies export licensing and quality grading protocols that directly shape global spot pricing. The country's Sahelian wild harvesting corridors supply pharmaceutical-grade raw material to European excipient buyers. Khartoum processing facilities face capital constraints meeting EFSA microbiological upgrade requirements.
India
Indian pharmaceutical manufacturers source USP-NF compliant acacia gum for generic drug tablet binding applications. CDSCO excipient quality guidelines align with EP certification standards for import substitution. Mumbai and Hyderabad formulation clusters concentrate domestic demand for controlled-release matrix applications.
Acacia Gum Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward integration into Sahelian sourcing corridors separating premium-positioned players from commodity distributors. The structure concentrates around three archetypes: gum belt-integrated processors with farmer cooperative networks, technology-intensive refiners specializing in instantized fractions, and diversified hydrocolloid portfolios using acacia as a line extension. Competitive moves center on multi-year offtake contracting with verified Sudanese and Chadian suppliers, plus spray-drying capacity expansion for cold-water soluble variants.
Among French integrated processors, Nexira and Alland & Robert exemplify the cooperative-backed sourcing model, with the former anchoring supply security through upstream control over gum belt farmer networks. Agrigum International Limited represents the pharmaceutical-grade specialization archetype, occupying a position aligned with European excipient certification requirements. These three entities collectively illustrate how traceability infrastructure and processing technology differentiate positioning across food, pharmaceutical, and nutraceutical demand vectors.
| Leading Market Players |
|---|
| Agrigum International Limited |
| Alland & Robert |
| Nexira |
| Foodchem International |
| Ingredion Incorporated |
| Kerry Group |
| Farbest Brands |
| Ashland Inc. |
| TIC Gums |
| Others |
Supply Flow & Price Mechanics
EFSA purity specifications under EU Food Additive Regulation (EC) No 1333/2008 gate both supply qualification and price differentiation simultaneously, forcing Sudanese processors to absorb compliance costs while European buyers pay premiums for documented traceability. This regulatory threshold bifurcates the market into certified premium tiers and commodity spot alternatives.
Pricing Analysis
Khartoum-to-Paris price spreads widen during Sahelian harvest disruptions, with organic-certified acacia senegal commanding substantial premiums over standard food-grade fractions. Contract-based long-term offtake agreements dominate pharmaceutical-grade procurement, while spot pricing persists for industrial adhesive applications. Price differentiation hinges on microbiological compliance documentation and enzymatic hydrolysis processing for cold-water solubility. Cost compression in industrial-grade tiers is intensifying because modified starches and cellulose derivatives erode volume share. Mid-tier bakery manufacturers exhibit highest price sensitivity; infant nutrition formulators in France show least.
Supply Chain Analysis
Port congestion at Port Sudan and container availability constraints on Red Sea-Suez trade lanes inflate inbound logistics costs for European excipient buyers. Wild harvesting corridors in Sudan, Chad, and northern Nigeria concentrate raw gum supply, with Khartoum processing facilities drawing from Sahelian cooperative networks. Raw material flows rest on generational tapping expertise, arabinogalactan protein content variability, and EFSA-compliant solvent removal capacity. Single-source vulnerability runs through Sudan's national gum council export licensing protocols. Distribution runs through direct sales for certified organic grades and regional distributors for standard food volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic hydrocolloid substitution threatens incumbent positioning across industrial-grade applications, demanding defensive moves to secure higher-value certification tiers. Incumbents must navigate this substitute pressure while capturing premium positioning in pharmaceutical and organic food channels.
For Market Incumbents: Fortify supply security through backward integration into Senegalese and Malian cultivated plantation networks as wild harvesting labor pools contract. Anchor pharmaceutical-grade margins by investing in USP-NF and EP compliance infrastructure ahead of EFSA microbiological threshold tightening. Prioritize spray-drying capacity expansion for enzymatically hydrolyzed cold-water soluble variants targeting German beverage manufacturers.
For New Entrants and Emerging Players: Differentiate on instantized sports nutrition applications where enzymatic hydrolysis technology barriers remain penetrable. Target North American dietary supplement white space where FDA GRAS prebiotic fiber claims enable rapid SKU proliferation without European traceability documentation burdens. Pursue direct importer relationships with gum belt cooperatives, bypassing layered trader networks.
For Investors and Strategic Acquirers: EFSA's 2023 updated purity specifications reshape the acquisition landscape toward processors with existing compliance infrastructure and cooperative-backed supply networks. Long-term viability across the analysis window favors vertically integrated specialists with demonstrated traceability systems over commodity distributors facing synthetic substitution. Monitor Sudan-Chad political stability and Sahelian rainfall patterns as inflection indicators for raw material flow disruptions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivated Plantations | Senegalese and Malian controlled cultivation models reduce dependency on collapsing wild tapping expertise across the Sahel. |
| Enzymatic Hydrolysis Capacity Expansion | Cold-water soluble fraction production captures German and French beverage manufacturer demand for instantized formats. |
| Pharmaceutical Excipient Certification Investment | USP-NF and EP compliance unlocks generic drug manufacturer contracts with stringent documentary requirements. |
| Direct Cooperative Procurement Agreements | Multi-year offtake contracts with Sudanese farmer networks eliminate trader margins and secure traceable supply. |
| Spray-Drying Technology Upgrade | Enhanced powder classification enables premium positioning in ready-to-drink and sports nutrition applications. |
Methodological Framework
Operator-level perspectives from gum cooperative managers, European excipient procurement directors, Sudanese export licensing officials, French clean-label formulators, and North American nutraceutical product developers anchored the qualitative base. Primary fieldwork combined with secondary validation from EU Food Additive Regulation filings, EFSA scientific opinions, Sudan national gum council export records, and US FDA GRAS notification databases. Bottom-up volume modeling across product grades and applications triangulated against top-down trade flow analysis.
Sensitivity analysis tested forecast robustness across alternative scenarios for Sahelian labor migration rates and synthetic hydrocolloid substitution velocity. Segmentation dimensions modeled included purity grade tier, end-use application, certification level, and regional regulatory cluster. CAGRs derived from historical price-volume relationships projected forward across the analysis window. Key inputs encompassed EFSA compliance cost trajectories and enzymatic hydrolysis technology adoption curves.
Material uncertainties — generational labor abandonment, climate volatility, and regulatory threshold revisions — sit outside the modeled envelope. Forecasts reflect assumptions regarding cooperative network stability and pharmaceutical certification maintenance. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cold Water Swelling Starch Market
Ingredients
Asia-Pacific Yeast Market
Ingredients
Vitamin and Mineral Premixes Market
Ingredients
L-Arabinose Market
Ingredients
Wheat Starch Derivative Market
Ingredients
Plant Extracts Market
Ingredients
Mediterranean Women’s Cycle Support Ingredient Systems Market
Ingredients
Pulses Ingredients Market
Ingredients
Calendula Oil Market
Ingredients
Bromelain Ingredient Market
Ingredients
Thinned Starch Market
Ingredients
Dry Mixes Market
Ingredients
Cocoa Solids Market
Ingredients
Europe Potato Protein Market
Ingredients
Mustard Oil Market
Ingredients
Insect-Based Ingredients Market