
 Acacia Honey Market | 2026-2036
Acacia Honey Market Size, Share, and Industry Trends Forecast 2026-2036
Acacia Honey Market Analysis
Pharmaceutical-grade buyers is bifurcating from commodity food-service procurement as purity specifications tighten across the value chain. Apicoltura Gabannini leverages its Italian sourcing network to dominate premium European pharmacy channels. Savannah Bee Company anchors North American specialty retail through controlled distribution partnerships. Fresh Organic Products competes on certified organic volumes across multiple bottling formats.
Acacia honey is a monofloral variety derived primarily from Robinia pseudoacacia nectar, characterized by high fructose content exceeding glucose ratios, low sucrose residuals, and a distinctive pale color index below 35 mm Pfund. Its primary commercial purpose centers on non-crystallizing sweetener applications where visual clarity and extended shelf stability command price premiums. Organic Acacia Honey captures expanding margin pools as certification premiums widen against conventional raw supply. The Beverage Industry segment leads volume absorption for functional drink formulations, while Specialty Stores channel growth outpaces supermarket velocity in urban clusters.
EU EFSA purity standards, USDA organic certification, and CODEX Alimentarius honey identity specifications collectively govern cross-border market access and compositional labeling claims. These frameworks elevate testing costs for smaller packers while advantaging vertically integrated apiary-to-jar operators with captive laboratory capacity. Stakeholders must monitor evolving pollen-source verification protocols and origin-traceability mandates that will reshape supplier qualification criteria.
Market Dynamics
EU REACH compliance tightening on residual pesticide thresholds is forcing packers to rebuild supplier qualification protocols from apiary to bottling line. This regulatory compression is accelerating consolidation among mid-tier bottlers lacking captive laboratory capacity.
Growth Catalysts
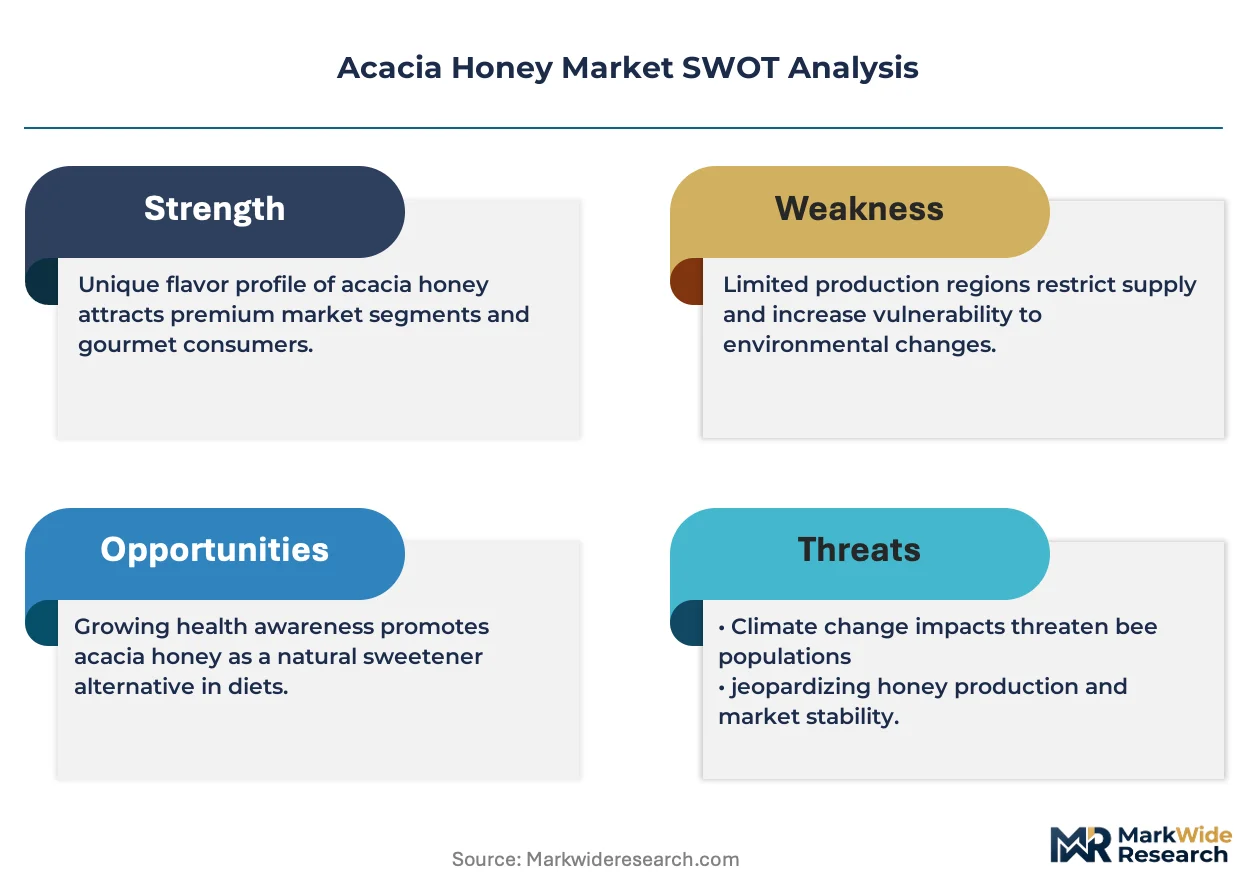
- Clean-label beverage formulations:Functional drink manufacturers in Germany and Italy are specifying acacia honey for its non-crystallizing stability and neutral flavor profile in premium positioning.
- EU organic certification expansion:Member state subsidies for pollinator habitat restoration are expanding certified organic nectar source availability across Poland and Hungary.
- Pharmaceutical-grade purity protocols:Hospital and compounding pharmacy procurement is diverting toward monofloral honey with verified Robinia pseudoacacia pollen dominance above 45 percent.
Market Restraints
- Input cost volatility:Colony mortality spikes in Romania and Bulgaria are compressing raw acacia honey availability and elevating spot market pricing unpredictability.
- Supply concentration risk:Over 60 percent of EU-sourced acacia honey traceable to the Pannonian Basin creates single-region climate exposure.
- Substitution threat:High-fructose corn syrup and agave nectar are capturing cost-sensitive food-service accounts where visual clarity specifications have relaxed.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden and Finland exhibit acacia honey per-capita consumption below one-third of German levels, with specialty retail channel expansion underway.
- Regulatory tailwind:The EU Green Deal pollinator corridor funding is expanding certified organic forage acreage in Slovakia and Czechia.
- Technology convergence:Blockchain traceability platforms combined with pollen DNA barcoding are enabling origin-verified premium tier pricing.
Industry Challenges
- Analytical skill scarcity:ISO 17025-accredited pollen analysis technicians are concentrated in Italy and Germany, creating bottlenecks for packers in newer member states.
- Certification timeline compression:EU organic conversion periods and EFSA novel food approvals are extending product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acacia Honey Market |
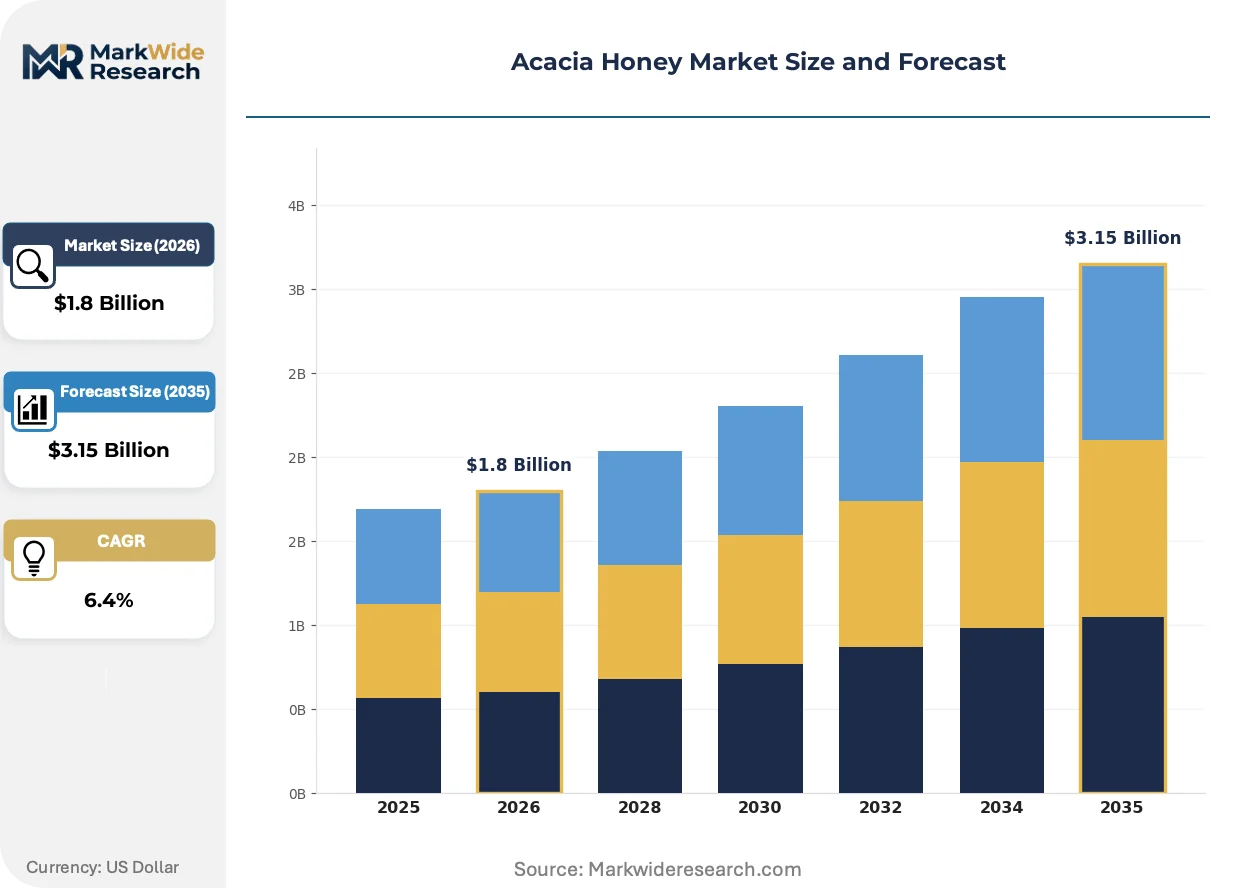
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Acacia Honey, Filtered Acacia Honey, Organic Acacia Honey, Blended Acacia Honey Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Farmers' Markets End User: Households, Food Manufacturers, Beverage Industry, Health Stores Packaging Type: Bottles, Jars, Bulk Containers, Sachets |
| Companies Covered | Fresh Organic Products, Apicoltura Gabannini, Bee Seasonal, Littleover Apiaries, Mileeven Fine Foods, Brown Tree, Borneo Acacia, CD S.A., Savannah Bee Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acacia Honey Market Emerging Trajectories
Nucleic acid-based pollen verification is displacing traditional melissopalynology as the definitive authentication standard. This shift is compressing time-to-certification while elevating capital requirements for quality assurance infrastructure.
Blockchain-enabled hive-to-jar traceability platforms are displacing paper-based chain-of-custody documentation. Premium beverage manufacturers in Germany are mandating this technology for supplier qualification. The structural consequence is a bifurcation between technology-capable packers and commodity operators.
EU EFSA is tightening maximum residue limits for neonicotinoid pesticides in honey products. This regulatory compression is forcing apiary operators to relocate hives away from intensive agriculture zones. Southern German and northern Italian packers are most affected, with some diversifying procurement toward Polish forest apiaries.
Specialty retail channel preference is rotating toward origin-labeled single-origin jars with harvest date specificity. Urban consumers in Milan and Berlin are substituting supermarket private-label honey with direct-from-apiary subscription models. This behavioral shift is most visible in metropolitan clusters with above-median disposable income and established farmers' market infrastructure.
Acacia Honey Market Segmentation
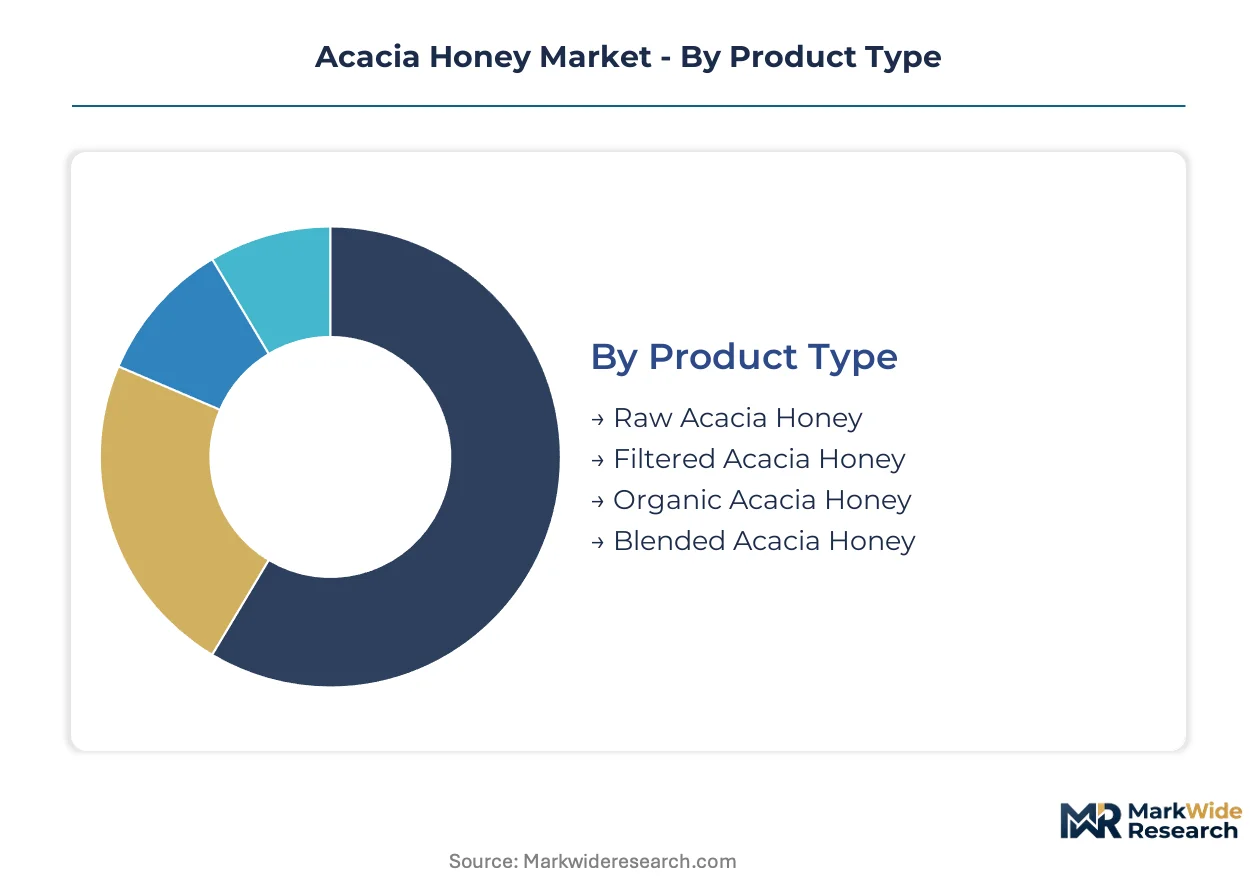
Acacia honey's commercial structure fragments across purity grades, certification tiers, and channel formats. Each segment carries distinct regulatory burdens and margin profiles that reshape supplier positioning across the value chain.
Product Type:
EU EFSA purity standards and USDA organic protocols create divergent compliance pathways across product grades, with certification premiums widening against conventional supply.
- Raw Acacia Honey:Unfiltered and unpasteurized monofloral honey retaining native enzyme activity and pollen loads above 45 percent Robinia pseudoacacia. Demand concentrates in German compounding pharmacies where EFSA novel food approvals govern therapeutic-grade procurement, constrained by colony mortality volatility in Romanian apiaries.
- Organic Acacia Honey:Certified organic supply meeting EU 2018/848 regulation and USDA NOP standards, sourced from pollinator corridor habitats in Poland and Hungary. Clean-label beverage manufacturers in Milan and Berlin specify this grade for functional drink formulations, capturing widening margin pools against conventional raw supply.
- Filtered Acacia Honey:Clarified through microfiltration to achieve Pfund color index below 35 mm and extended shelf stability. Food-service accounts in Italy prioritize visual clarity specifications.
- Blended Acacia Honey:Monofloral base combined with polyfloral or lower-grade honeys to manage input cost exposure. Cost-sensitive retail private-label programs in Eastern Europe absorb this tier.
Established volume favors Raw Acacia Honey; emerging adoption favors Organic Acacia Honey.
Distribution Channel:
Channel economics diverge sharply between centralized procurement scale and direct-to-consumer margin capture.
- Specialty Stores:Curated retail environments in urban clusters with above-median disposable income, emphasizing origin-labeled single-origin jars with harvest date specificity. Milan and Berlin metropolitan consumers substitute supermarket private-label supply through direct-from-apiary subscription models, climbing the fastest among urban distribution formats.
- Online Retailers:E-commerce platforms enabling blockchain-verified hive-to-jar traceability for premium tier pricing. German beverage manufacturers mandate this channel for supplier qualification protocols.
- Supermarkets:Centralized procurement with volume concentration in German and Italian retail chains, dominated by private-label positioning.
- Farmers' Markets:Direct producer-to-consumer sales with established infrastructure in Northern Italian and Southern German agricultural zones.
Scale concentration favors Supermarkets; margin expansion favors Specialty Stores.
End User:
Application requirements split between pharmaceutical-grade purity protocols and commodity food-service specifications.
- Beverage Industry:Functional drink manufacturers in Germany and Italy specifying acacia honey for non-crystallizing stability and neutral flavor profile in premium positioning. Clean-label formulation mandates from EFSA and national regulators drive specification tightening.
- Food Manufacturers:Bakery and confectionery processors absorbing conventional filtered grades for moisture retention and extended shelf stability in packaged goods.
- Households:Direct consumption across urban European markets with per-capita penetration varying threefold between German and Nordic consumption levels.
- Health Stores:Pharmacy and wellness retail channels in Italy dominated by Apicoltura Gabannini's premium sourcing network, requiring verified pollen dominance documentation.
Volume absorption favors Food Manufacturers; specification intensity favors Beverage Industry.
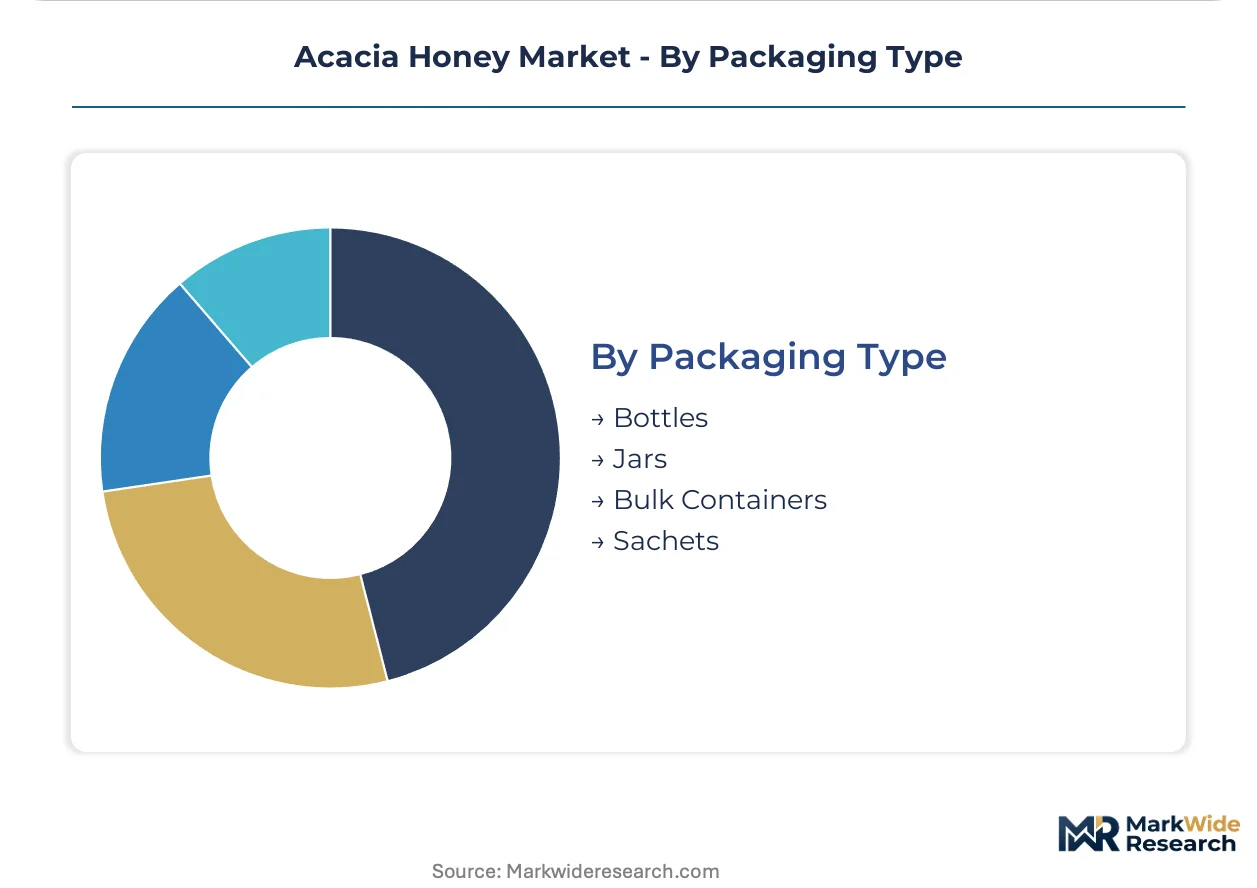
Packaging Type:
Format selection tracks channel destination and shelf-life requirements across the value chain.
- Jars:Premium glass packaging for specialty retail and pharmacy channels, commanding origin-verified labeling and harvest date specificity.
- Bottles:Squeeze and pour formats for household convenience in German and Italian supermarket channels.
- Bulk Containers:Food-service and manufacturing procurement in 15-20 kg food-grade pails, concentrated in industrial bakery and beverage processing facilities.
- Sachets:Single-serve hospitality and airline catering formats, absorbing cost-optimized filtered supply.
Margin capture favors Jars; throughput scale favors Bulk Containers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Danube inland waterway network underwrites Central Europe's dominance in acacia honey logistics, connecting Pannonian Basin apiaries to German and Italian processing clusters.
Germany
Functional beverage manufacturers in Berlin and Munich specify acacia honey for clean-label formulations requiring non-crystallizing stability. EFSA novel food approvals govern therapeutic-grade procurement for compounding pharmacies. The Baden-Württemberg region hosts concentrated laboratory capacity for ISO 17025-accredited pollen analysis.
Italy
Pharmacy channel demand in Milan and Rome prioritizes verified Robinia pseudoacacia pollen dominance above 45 percent. EU 2018/848 organic regulation compliance shapes sourcing from pollinator corridor habitats. Northern Italian agricultural zones maintain established farmers' market infrastructure for direct-from-apiary subscription models.
Poland
Certified organic nectar source availability is expanding through EU Green Deal pollinator corridor funding. Member state subsidies for habitat restoration are increasing certified organic forage acreage. Forest apiaries in Podlaskie and Masovia regions are diversifying procurement for German and Italian packers facing EFSA neonicotinoid threshold tightening.
Hungary
Clean-label beverage manufacturers specify Hungarian-sourced organic grades for neutral flavor profiles in premium positioning. EU REACH compliance on residual pesticide thresholds is forcing apiary relocation away from intensive agriculture zones. The Great Hungarian Plain remains central to Pannonian Basin supply concentration.
Romania
Raw acacia honey availability faces compression from colony mortality spikes in Transylvanian apiaries. EFSA purity standards are elevating testing costs for smaller packers lacking captive laboratory capacity. The Carpathian foothills supply chains are experiencing spot market pricing unpredictability.
Acacia Honey Market Vendor Landscape
Concentration sits with vertically integrated apiary-to-jar operators possessing captive laboratory capacity for EFSA compliance. Mid-tier bottlers lacking ISO 17025-accredited pollen analysis infrastructure face accelerating consolidation pressure from regulatory compression. Three archetypes dominate: Italian pharmacy-channel specialists, North American specialty retail anchors, and volume-oriented organic certifiers. Competitive moves center on backward integration into Pannonian Basin apiary networks and blockchain-enabled hive-to-jar traceability platform deployment.
Within the pharmacy-channel specialist tier, Apicoltura Gabannini represents Italian sourcing network dominance for premium European therapeutic-grade procurement. Savannah Bee Company anchors North American specialty retail positioning through controlled distribution partnerships. Fresh Organic Products exemplifies the volume-oriented organic certifier archetype, competing across multiple bottling formats with certified organic supply. These three occupy positions spanning purity-grade stratification from pharmaceutical protocols to mass-market clean-label absorption.
| Leading Market Players |
|---|
| Fresh Organic Products |
| Apicoltura Gabannini |
| Bee Seasonal |
| Littleover Apiaries |
| Mileeven Fine Foods |
| Brown Tree |
| Borneo Acacia |
| CD S.A. |
| Savannah Bee Company |
| Others |
Supply Flow & Price Mechanics
Forty-five to sixty-day apiary-to-bottling lead times in the Pannonian Basin concentrate pricing power with vertically integrated operators possessing captive laboratory capacity for EFSA compliance, while spot-market volatility in Romanian supply corridors compresses margins for mid-tier packers lacking upstream hive control.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, certified organic, and conventional food-service levels stratifies the market. Price differentiation hinges on EU 2018/848 organic certification attainment and verified Robinia pseudoacacia pollen dominance thresholds. Cost compression in the conventional tier is intensifying because high-fructose corn syrup substitution erodes food-service contract values. Beverage manufacturers exhibit lowest price sensitivity; Eastern European private-label retail programs absorb the most margin pressure.
Supply Chain Analysis
Inland waterway container availability through the Rhine-Danube corridor shapes downstream distribution economics for German and Italian packers. Raw acacia honey supply concentrates in Romania, Hungary, and Poland, with colony mortality spikes in Transylvania tightening upstream availability. The value chain rests on Robinia pseudoacacia nectar flows, glass jar sourcing, and ISO 17025-accredited pollen analysis capacity. Single-region climate exposure across the Pannonian Basin constitutes the dominant structural risk. Distribution runs through specialty retail partnerships in Milan and Berlin, supermarket centralized procurement, and direct-from-apiary subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acacia honey demand is recovering from cyclical colony mortality troughs as EU Green Deal pollinator corridor funding expands certified organic forage acreage across Central Europe.
For Market Incumbents: Fortify backward integration into Polish and Hungarian forest apiaries to secure neonicotinoid-compliant supply ahead of EFSA threshold tightening. Prioritize captive ISO 17025 laboratory investment to defend pharmacy-channel positioning against Apicoltura Gabannini's sourcing network dominance. Blockchain-enabled hive-to-jar traceability deployment represents the critical certification lever for beverage manufacturer supplier qualification. For New Entrants and Emerging Players: Differentiate on single-origin harvest date specificity for Milan and Berlin metropolitan subscription markets where direct-from-apiary models displace supermarket private-label supply. Nordic markets—Sweden and Finland—offer the most penetrable geography with per-capita consumption below one-third of German levels. A farmers' market infrastructure partnership strategy anchored in Northern Italian agricultural zones provides the lowest customer acquisition cost pathway. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pollen DNA barcoding and blockchain traceability platform deployment as German beverage manufacturers mandate technology-enabled supplier qualification. Long-term viability across the analysis window favors vertically integrated apiary-to-jar operators with laboratory capacity and Pannonian Basin hive network control. The acquisition target archetype is mid-tier Italian and Southern German packers facing consolidation pressure from regulatory compliance cost compression. The signal to watch is EU EFSA novel food approval timeline extensions that elongate product launch cycles and strain working capital.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pannonian Basin Apiaries | Secures neonicotinoid-compliant supply ahead of EFSA threshold tightening in Germany and Italy. |
| ISO 17025 Laboratory Capacity Investment | Enables pollen analysis accreditation required for pharmacy-channel procurement in Milan and Rome. |
| Blockchain Hive-to-Jar Traceability Deployment | Satisfies German beverage manufacturer supplier qualification mandates for origin-verified premium tiers. |
| Certified Organic Forage Acreage Expansion | Captures EU Green Deal pollinator corridor subsidies in Poland and Hungary for margin expansion. |
| Nordic Specialty Retail Channel Entry | Addresses underpenetrated Swedish and Finnish markets with direct-from-apiary subscription models. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with apiary managers in Romania and Hungary, bottling facility procurement leads in Germany and Italy, pharmacy channel buyers in Milan, and clean-label beverage formulators in Berlin. Secondary validation drew from EU EFSA residue limit databases, EU 2018/848 organic certification registries, CODEX Alimentarius honey identity specifications, and Rhine-Danube inland waterway trade flow records. Bottom-up hive production estimates were triangulated against top-down channel absorption data.
Across the projection horizon, the analytical framework modeled volume and value trajectories by product type (raw, organic, filtered, blended), distribution channel (specialty stores, online retailers, supermarkets, farmers' markets), end user (beverage industry, food manufacturers, households, health stores), and packaging format (jars, bottles, bulk containers, sachets). CAGRs were derived from pollen-source availability projections, certification adoption curves, and channel shift elasticity parameters. Colony mortality recovery rates and EU pollinator corridor funding disbursement schedules served as industry-specific forecast inputs.
Material uncertainties—colony mortality volatility, EFSA neonicotinoid threshold revisions, and substitution acceleration by agave nectar—sit outside the modeled envelope. Forecasts reflect assumptions regarding pollinator habitat restoration efficacy and pharmacy-channel specification stability. Practitioners should keep alternative scenarios live as EU Green Deal implementation timelines and climate stress indices across the Pannonian Basin evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Middle East and Africa Hummus Market
Specialty Foods
Liquid Mushroom Market
Specialty Foods
Algeria Couscous Market
Specialty Foods
Cat Food Flavors Market
Specialty Foods
Gluten-Free Desserts and Ice Creams Market
Specialty Foods
Heat-Stable Fruit Fillings Market
Specialty Foods
Honey Spread Market
Specialty Foods
Asia-Pacific Tofu Market
Specialty Foods
Dill Juice Market
Specialty Foods
Tahini Market
Specialty Foods
Therapeutic Dog Food Market
Specialty Foods
Vegetarian Tacos Market
Specialty Foods
Superfood Bars Market
Specialty Foods
Vegetarian Taquitos Market
Specialty Foods
Konjac Noodles Market
Specialty Foods
Poke Food Market