
 Arabinogalactan Powder Market | 2026-2036
Arabinogalactan Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Arabinogalactan Powder Market Analytics
Plant-based prebiotic fibers is realigning formulation economics across immune health and gut microbiome applications. Lonza Group AG leverages its pharmaceutical-grade extraction capabilities to supply high-purity arabinogalactan for clinical nutrition. Larex Inc. specializes in larch-derived sourcing, anchoring its position in North American botanical supply chains. Ametis JSC competes through Siberian larch vertical integration, controlling raw material access across Eurasian forests.
Arabinogalactan powder denotes a water-soluble polysaccharide extracted primarily from larch trees, composed of galactose and arabinose units in a 6:1 ratio with molecular weights ranging from 10,000 to 120,000 Daltons, functioning as a dietary fiber and immunomodulatory agent in nutraceutical and pharmaceutical formulations. The organic product type segment commands premium positioning among clean-label formulators, while modified variants target enhanced solubility for beverage applications. Pharmaceutical-grade specifications concentrate margin pools around endotoxin-controlled production, whereas dietary supplement applications dominate volume throughput across direct-to-consumer channels.
FDA dietary supplement cGMP standards and EFSA novel food evaluations shape product qualification timelines and cross-border market access for arabinogalactan suppliers. REACH registration requirements and USDA organic certification protocols further segment competitive positioning between synthetic and botanical-derived offerings. Stakeholders must monitor evolving immunomodulatory health claim substantiation standards across multiple jurisdictions to anticipate reformulation requirements and channel eligibility shifts.
Market Dynamics
Clean-label ingredient mandates under the EU Green Deal and FDA dietary supplement frameworks are compressing qualification timelines, forcing suppliers to consolidate extraction capabilities and traceability systems ahead of regulatory enforcement waves.
Growth Catalysts
- Immune health formulation expansion:Dietary supplement manufacturers in Minneapolis and Salt Lake City production corridors are scaling arabinogalactan sourcing for prebiotic fiber blends targeting gut microbiome support.
- REACH registration acceleration:ECHA compliance deadlines for novel food ingredients are pulling forward investment in pharmaceutical-grade endotoxin-controlled production lines.
- Larch biomass utilization:Siberian and North American forestry operations are redirecting pulp byproduct streams toward high-value polysaccharide extraction, improving raw material economics.
Market Restraints
- Botanical supply concentration:Overreliance on Larix sibirica and Larix occidentalis species creates single-source vulnerability to forest pest outbreaks and climate stress in Eurasian and Pacific Northwest harvesting zones.
- Extraction cost structure:Hot-water extraction and ethanol precipitation processes consume substantial thermal energy, exposing margin pools to natural gas price volatility.
- Acacia gum substitution:Formulators in beverage applications can pivot to acacia senegal fiber at lower input costs with comparable emulsification properties.
Strategic Opportunities
- Clinical nutrition penetration:Enteral and parenteral nutrition manufacturers represent an underdeveloped channel for immunomodulatory fiber fortification in post-surgical recovery protocols.
- USDA organic certification gap:Premium positioning awaits suppliers achieving certified organic status for wild-harvested larch sources, commanding price multiples in direct-to-consumer channels.
- Microencapsulation convergence:Integration with spray-drying and lipid-coating technologies enables arabinogalactan stability in functional beverage matrices previously inaccessible to polysaccharide ingredients.
Industry Challenges
- Analytical chemistry talent scarcity:Few laboratories maintain in-house capabilities for molecular weight distribution analysis and monosaccharide ratio verification required by EFSA novel food dossiers.
- cGMP facility retrofitting:Dietary supplement manufacturers face capital-intensive upgrades to meet FDA 21 CFR Part 111 standards for identity testing and contamination control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arabinogalactan Powder Market |
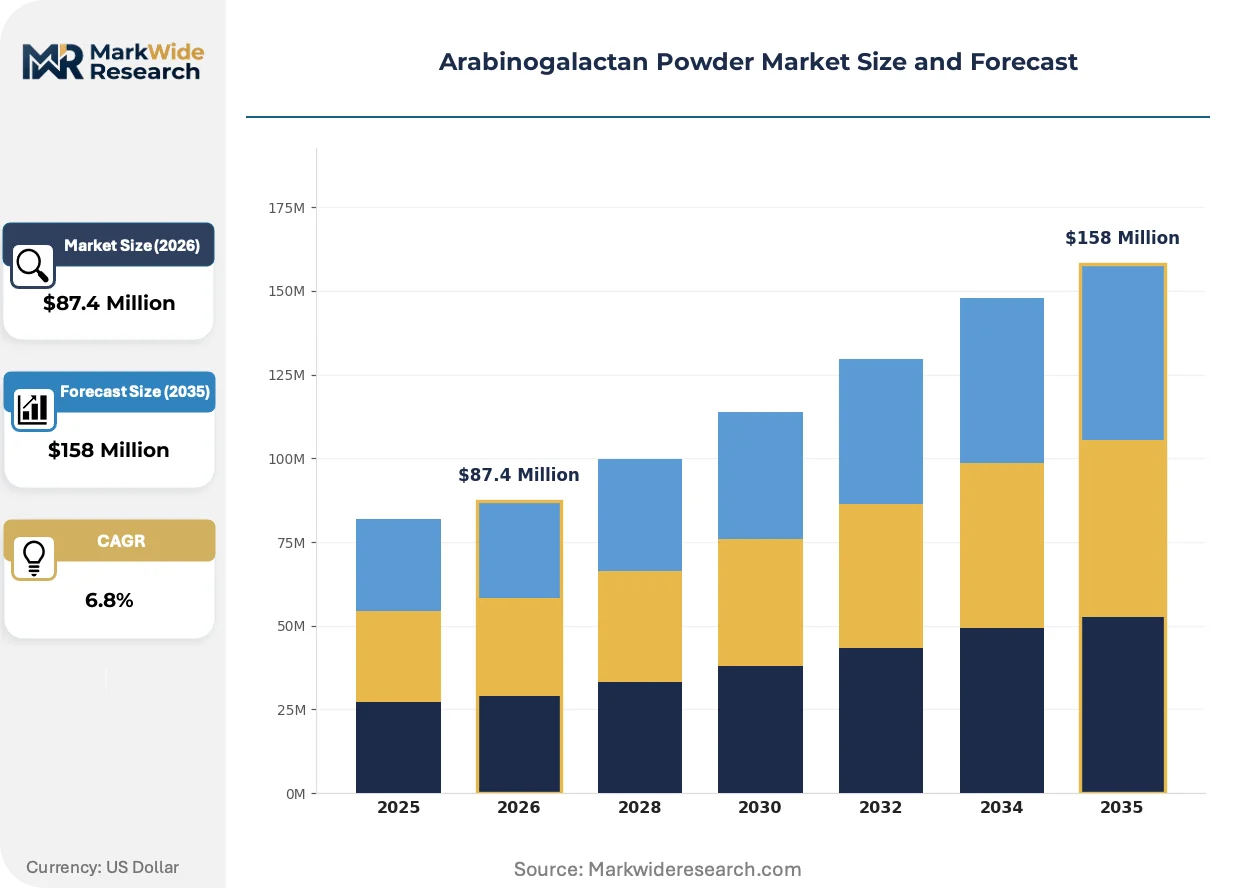
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Non-Organic, Modified, Natural Application: Dietary Supplement, Food Additive, Pharmaceutical, Cosmetics Distribution Channel: Online Retail, Specialty Stores, Wholesalers, Direct Sales End User: Manufacturers, Retailers, Health Professionals, Consumers |
| Companies Covered | Lonza Group AG, Ametis JSC, Jilin Forest Industry, Larex Inc., Ingredion Incorporated, Archer Daniels Midland Company, Cargill Incorporated, Robios, Pure Encapsulations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arabinogalactan Powder Market Evolving Landscape
Formulation science and regulatory science are converging to redefine how arabinogalactan suppliers qualify for cross-border market access, with extraction technology and health claim substantiation moving in lockstep.
Membrane filtration technology is modularizing downstream purification workflows. Nutraceutical contract manufacturers in Utah and Minnesota are adopting tangential flow filtration systems to replace traditional ethanol precipitation, reducing solvent recovery costs by half while tightening endotoxin control. This modularization is compressing capital requirements for pharmaceutical-grade production entry.
EFSA novel food evaluations are extending qualification timelines for non-traditional larch sources. The regulatory friction is redirecting supplier investment toward dossier-ready Siberian larch supply chains with established consumption histories, disadvantaging North American wildcrafting operations without grandfathered status. European formulators are responding by consolidating supplier relationships ahead of enforcement windows.
Direct-to-consumer subscription models are displacing traditional ingredient broker channels. Specialty supplement brands are building captive arabinogalactan supply agreements with extraction facilities, bypassing wholesale distributors. This channel compression is most visible in North American immune health verticals, where vertically integrated brands capture margin pools previously allocated to intermediaries.
Arabinogalactan Powder Market Segmentation
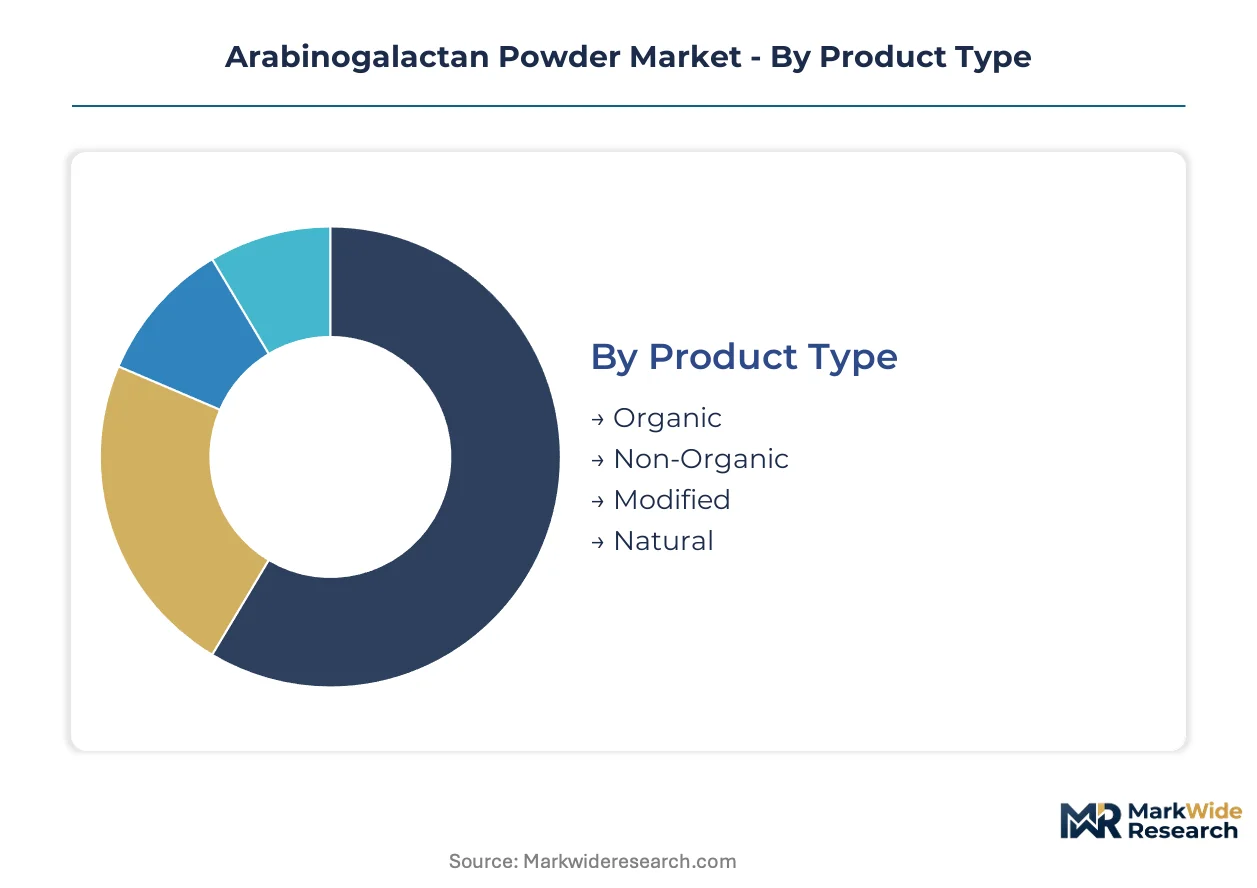
Arabinogalactan powder segmentation reflects divergent purity requirements and channel economics across nutraceutical and pharmaceutical end-uses. Each dimension captures distinct margin structures, from wild-harvested organic premiums to modified variants engineered for beverage solubility.
Product Type:
Supply concentration among larch-derived extraction facilities favors vertically integrated producers controlling Siberian and North American forest access.
- Organic:Wild-harvested larch sources meeting USDA organic certification command premium positioning in direct-to-consumer immune health formulations. Minneapolis and Salt Lake City manufacturing clusters drive concentrated demand for certified organic inputs as clean-label mandates tighten under FDA dietary supplement frameworks.
- Modified:Chemically or enzymatically altered variants enhance solubility profiles for functional beverage matrices previously inaccessible to native polysaccharides. EFSA novel food evaluations are extending qualification timelines for modified structures, redirecting supplier investment toward dossier-ready formulations.
- Non-Organic:Conventionally harvested larch sources serve cost-sensitive dietary supplement manufacturers prioritizing volume throughput over certification premiums.
- Natural:Unmodified native extracts retain the 6:1 galactose-arabinose ratio and molecular weight distribution preferred by clinical nutrition formulators.
Today's leader: Organic. Tomorrow's challenger: Modified.
Application:
Cost tier stratification separates pharmaceutical-grade endotoxin-controlled production from commodity dietary supplement volumes.
- Dietary Supplement:Prebiotic fiber blends targeting gut microbiome support dominate volume throughput across direct-to-consumer channels. Utah and Minnesota contract manufacturers are scaling tangential flow filtration adoption to replace ethanol precipitation, compressing capital requirements for pharmaceutical-grade entry.
- Pharmaceutical:Enteral and parenteral nutrition applications require endotoxin-controlled specifications with molecular weight verification, concentrating margin pools among extraction facilities with cGMP certification. FDA 21 CFR Part 111 compliance timelines are forcing capital-intensive facility upgrades.
- Food Additive:Functional food fortification in North American production corridors leverages arabinogalactan's emulsification properties, though acacia senegal fiber substitution threatens cost-sensitive beverage applications.
- Cosmetics:Topical formulations exploit the polysaccharide's humectant properties in premium skincare, representing a niche but expanding channel.
Volume concentrates in Dietary Supplement. Steepest expansion trajectory: Pharmaceutical.
Distribution Channel:
Customer type differentiation separates vertically integrated brands from traditional ingredient broker networks.
- Direct Sales:Specialty supplement brands are building captive supply agreements with extraction facilities, bypassing wholesale distributors to capture margin pools previously allocated to intermediaries. This channel compression is most visible in North American immune health verticals.
- Online Retail:E-commerce platforms enable small-batch formulators to access pharmaceutical-grade arabinogalactan without minimum order constraints imposed by traditional wholesalers.
- Specialty Stores:Health food retailers curate premium organic variants for discerning consumers, though shelf space competition from established prebiotic fibers limits expansion.
- Wholesalers:Traditional ingredient brokers face displacement as direct-to-consumer subscription models consolidate supplier relationships ahead of regulatory enforcement windows.
Incumbent dominance: Wholesalers. Fastest share gain: Direct Sales.
End User:
Maturity gradients separate established manufacturer demand from emerging health professional prescribing patterns.
- Manufacturers:Dietary supplement and functional food producers in Minneapolis and Salt Lake City production corridors anchor procurement volumes, with REACH registration acceleration pulling forward investment in pharmaceutical-grade capacity.
- Health Professionals:Clinical nutritionists and integrative medicine practitioners represent an underdeveloped channel for immunomodulatory fiber fortification in post-surgical recovery protocols.
- Retailers:Health food and specialty supplement stores curate organic-certified SKUs for clean-label consumers, though private-label compression limits margin expansion.
- Consumers:Direct purchasing through subscription models is displacing traditional retail discovery, with vertically integrated brands capturing lifetime value through recurring revenue structures.
Established anchor: Manufacturers. Emerging vector: Health Professionals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis and Salt Lake City manufacturing corridors concentrate North American arabinogalactan procurement for immune-support formulations. FDA dietary supplement cGMP standards and EFSA novel food evaluations shape cross-border qualification timelines. REACH registration deadlines pull investment toward pharmaceutical-grade endotoxin-controlled production.
United States
Dietary supplement manufacturers in Minneapolis and Salt Lake City production corridors scale arabinogalactan sourcing for prebiotic fiber blends. FDA 21 CFR Part 111 compliance timelines force capital-intensive facility upgrades for identity testing and contamination control. Utah contract manufacturers adopt tangential flow filtration systems to replace ethanol precipitation, compressing capital requirements for pharmaceutical-grade entry.
Germany
EFSA novel food evaluations extend qualification timelines for non-traditional larch sources, redirecting supplier investment toward dossier-ready supply chains. REACH registration requirements under ECHA compliance deadlines segment competitive positioning between synthetic and botanical-derived offerings. Bavarian extraction facilities consolidate capabilities ahead of regulatory enforcement waves under EU Green Deal mandates.
China
Domestic nutraceutical producers expand arabinogalactan incorporation into functional food fortification for gut microbiome applications. NMPA dietary supplement frameworks tighten purity and traceability requirements for polysaccharide ingredients. Yangtze River Delta manufacturing clusters develop membrane filtration capabilities to serve both domestic demand and export qualification.
Russia
Siberian larch vertical integration controls raw material access across Eurasian forests for immunomodulatory fiber production. Eurasian Economic Union technical regulations harmonize with REACH standards for cross-border market access into European Union. Siberian forestry operations redirect pulp byproduct streams toward high-value polysaccharide extraction, improving raw material economics.
Canada
Health Canada Natural Health Product regulations govern arabinogalactan qualification for immune health claims in dietary supplements. British Columbia and Alberta larch harvesting operations face climate stress vulnerability from forest pest outbreaks in Pacific Northwest zones. Prairie Provinces extraction facilities target USDA organic certification gaps for wild-harvested sources to command premium positioning in direct-to-consumer channels.
Arabinogalactan Powder Market Competitive Landscape
Capacity expansion dominates the current landscape as extraction facilities retrofit for pharmaceutical-grade endotoxin-controlled production. The vendor base organizes around three tiers: vertically integrated forest-to-facility operators, contract extraction specialists serving multiple brands, and regional botanical processors. Two strategic archetypes predominate: Siberian and North American larch controllers with captive raw material access, and nutraceutical-grade purification specialists with cGMP certification. Competitive intensity concentrates in M&A activity targeting traceable supply chains and technology licensing for membrane filtration modularization.
Among Swiss-headquartered pharmaceutical-grade suppliers, Lonza Group AG exemplifies the vertically integrated archetype with extraction capabilities anchored in clinical nutrition positioning. Ametis JSC represents Siberian-based forest controllers leveraging Eurasian raw material access for supply security. Larex Inc. occupies the North American botanical specialist tier with larch-derived sourcing concentration. These three anchors illustrate how geographic control over Larix species and qualification for endotoxin-controlled production separate margin pools from commodity dietary supplement volumes.
| Leading Market Players |
|---|
| Lonza Group AG |
| Ametis JSC |
| Jilin Forest Industry |
| Larex Inc. |
| Ingredion Incorporated |
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Robios |
| Pure Encapsulations |
| Others |
Value Network & Pricing Analysis
Clean-label procurement mandates from Minneapolis and Salt Lake City manufacturing clusters are compressing supplier qualification timelines, forcing extraction facilities to consolidate cGMP certification and organic traceability systems ahead of FDA enforcement waves, which in turn concentrates pricing power among qualified tier-one suppliers.
Pricing Analysis
Natural gas cost pass-through from hot-water extraction and ethanol precipitation processes exposes margin pools to thermal energy volatility, compressing returns for facilities without membrane filtration retrofit. Three-tier pricing structure across pharmaceutical-grade endotoxin-controlled, certified organic wild-harvested, and conventional dietary supplement grades separates buyers by qualification burden and channel positioning. Pricing pressure stems from acacia senegal fiber substitution in beverage applications, where comparable emulsification properties trade at lower input costs. Cost-sensitive commodity dietary supplement manufacturers exhibit highest price elasticity, while clinical nutrition formulators absorbing endotoxin-controlled premiums show lowest sensitivity.
Supply Chain Analysis
USDA organic certification and EFSA novel food dossier readiness gate supply chain participation, segmenting competitive positioning between dossier-ready Siberian larch controllers and North American wildcrafting operations without grandfathered status. Raw material access draws from Larix sibirica across Eurasian forests, Larix occidentalis in Pacific Northwest zones, and Larix laricina in Canadian boreal regions. Single-source vulnerability to forest pest outbreaks and climate stress in concentrated harvesting zones threatens supply continuity. Distribution runs through vertically integrated direct-to-consumer subscription channels displacing traditional ingredient broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Eurasian raw material abundance and North American regulatory premium capture, with EFSA novel food qualification timelines creating cost differentials that favor established Siberian supply chains over unqualified North American entrants.
For Market Incumbents: Lock in Siberian and North American forest access through long-term harvesting concessions or backward integration into larch biomass utilization, insulating against raw material concentration risk. Accelerate tangential flow filtration adoption to halve solvent recovery costs and defend margin position against commodity-grade competitors. Prioritize cGMP facility certification ahead of FDA 21 CFR Part 111 enforcement waves to maintain pharmaceutical-grade pricing tiers. For New Entrants and Emerging Players: Begin with USDA organic certification for wild-harvested larch sources, exploiting the premium positioning gap in direct-to-consumer immune health channels where certified organic commands price multiples. Target clinical nutrition penetration for enteral and parenteral nutrition applications, an underdeveloped channel with steepest expansion trajectory and lowest incumbent saturation. Deploy microencapsulation technology partnerships as go-to-market angle to unlock functional beverage matrices previously inaccessible to polysaccharide ingredients. For Investors and Strategic Acquirers: Asymmetric upside sits with extraction facilities combining Siberian or North American forest control with pharmaceutical-grade endotoxin-controlled production capabilities, positioned to capture margin migration from commodity dietary supplement volumes. Long-term viability across the 5-10 year window hinges on regulatory qualification moats deepening under EFSA and FDA frameworks. Watch for EFSA novel food evaluation acceleration as inflection indicator signaling qualification timeline compression and supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Larch Forestry | Captive raw material access insulates against Larix species supply concentration and climate vulnerability. |
| Membrane Filtration Technology Adoption | Tangential flow filtration retrofit halves solvent recovery costs and tightens endotoxin control for pharmaceutical-grade entry. |
| USDA Organic Certification Achievement | Certified organic wild-harvested status commands premium positioning in Minneapolis and Salt Lake City manufacturing corridors. |
| Clinical Nutrition Channel Penetration | Enteral and parenteral nutrition manufacturers represent underdeveloped margin pool for immunomodulatory fiber fortification. |
| Direct-to-Consumer Subscription Model Buildout | Vertically integrated brands bypass wholesale distributors to capture lifetime value through recurring revenue structures. |
Research Methodology
Bottom-up dietary supplement and pharmaceutical application modeling reconciled against top-down larch biomass extraction and forest harvesting tracking forms the analytical core of this study. Primary interviews with extraction facility operators, dietary supplement formulators, clinical nutrition procurement managers, and regulatory affairs specialists at EFSA and FDA converge with secondary validation from REACH registration databases, USDA organic certification records, customs trade data for polysaccharide imports, and SEC filings from publicly traded nutraceutical ingredient suppliers.
Historical trendline analysis of larch-derived polysaccharide pricing and volume trajectories informs the projection framework across the analysis window. Segmentation dimensions span product type tiers, application grade specifications, distribution channel structures, and end-user maturity gradients. CAGRs derive from fitted growth curves calibrated against immunomodulatory health claim substantiation progress and clean-label regulatory enforcement intensity. Industry-specific forecast inputs include EFSA novel food evaluation pipeline status and FDA cGMP facility certification velocity.
Caveats apply where EFSA novel food qualification acceleration, forest pest outbreak severity in Pacific Northwest or Eurasian zones, or natural gas price volatility could materially shift the outlook. Forecasts reflect assumptions regarding regulatory timeline stability and larch biomass yield consistency. A model refresh is warranted upon material change in EFSA dossier approval rates or FDA enforcement priority shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Omega-3 Fish Oils Market
Nutritional Supplements
Australia Nutraceuticals Market
Nutritional Supplements
Nutritional Supplements Market
Nutritional Supplements
Calcium Supplements Market
Nutritional Supplements
Europe Dietary Supplements Market
Nutritional Supplements
Nutraceutical Oral Thin Films Market
Nutritional Supplements
Grass Fed Protein Market
Nutritional Supplements
Energy Supplements Market
Nutritional Supplements
Digestive Health Supplements Market
Nutritional Supplements
Whey Protein Market
Nutritional Supplements
Global Antioxidant Market
Nutritional Supplements
Raspberry Ketones Market
Nutritional Supplements
Global Proanthocyanidins Market
Nutritional Supplements
Ketogenic Diet Market
Nutritional Supplements
Middle East Protein Market
Nutritional Supplements
Australia Collagen Peptides Market