
 Asia-Pacific Yeast Market | 2026-2036
Asia-Pacific Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Yeast Market Outlook
Soy-based leavening alternatives is consolidating share in cost-sensitive baking segments across Vietnam and Indonesia. Angel Yeast Co., Ltd. leverages captive molasses supply and integrated fermentation capacity to anchor pricing power in China's interior provinces. Lesaffre Group sustains technical service networks that dominate artisan bakery channels across Japan and South Korea. Lallemand Inc. competes through specialized active dry formulations tailored to tropical humidity conditions.
Yeast comprises single-celled fungi of the Saccharomyces genus, typically containing 40-55% protein by dry weight and cultivated through aerobic fermentation on molasses or starch hydrolysate substrates. Its primary commercial purpose centers on metabolizing sugars to produce carbon dioxide for dough leavening, ethanol for beverage alcohol, or biomass for nutritional supplementation. Baker's yeast occupies the largest revenue pool across the region's fragmented bakery sector, while nutritional yeast extracts command premium positioning within Japan's functional food and pharmaceutical channels. Animal feed applications represent the fastest-expanding application segment as Southeast Asian livestock producers seek antibiotic alternatives.
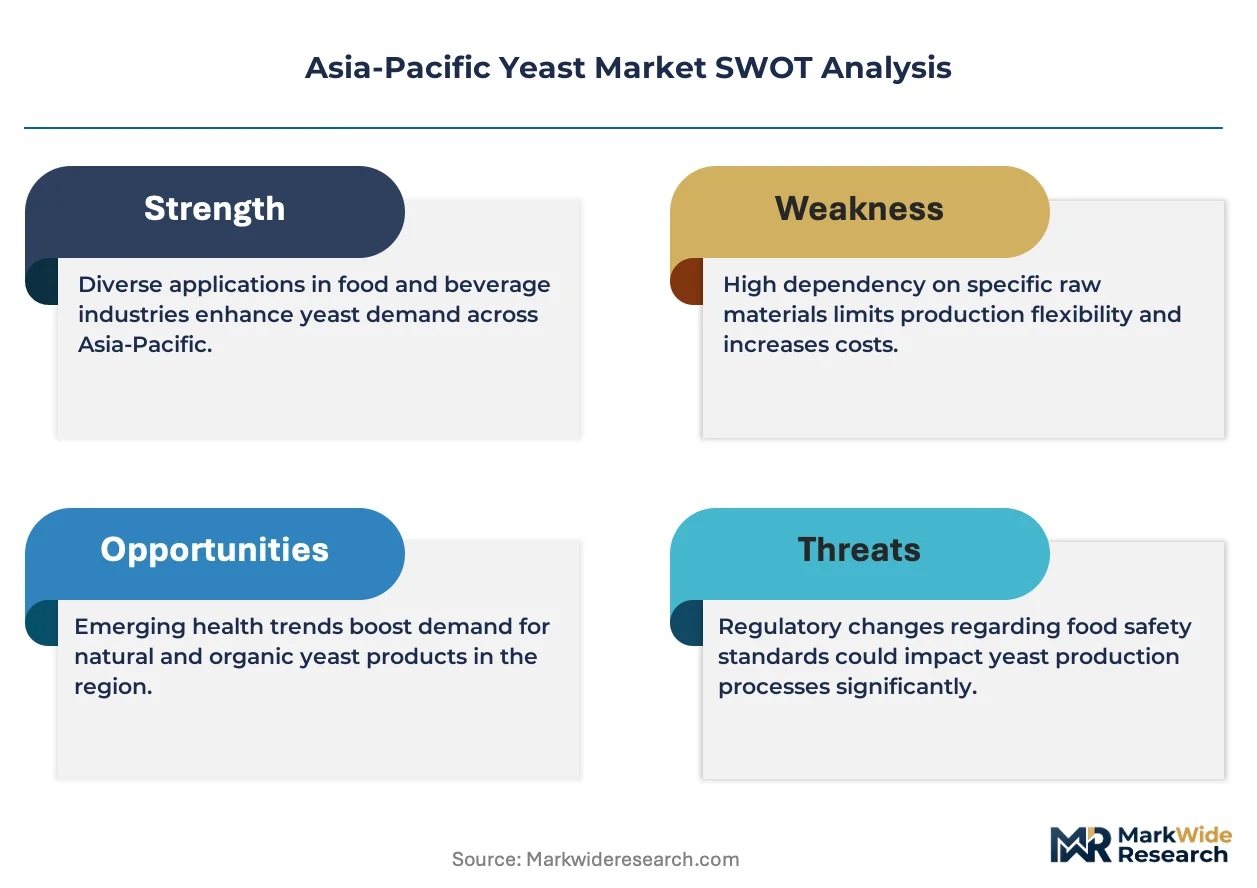
China's SAMR enforces GB standards for yeast product purity and additive disclosure that determine market access for imported biomass. Japan's METI and FSSAI in India each maintain distinct microbial strain approval frameworks that fragment cross-border product registration requirements. The EU Green Deal's indirect influence on ASEAN trade alignment is reshaping sustainability expectations for regional yeast manufacturers. Stakeholders must monitor evolving strain patent landscapes and molasses supply volatility as dual determinants of competitive positioning.
Market Dynamics
China's GB food safety standards are compressing formulation flexibility for yeast manufacturers while simultaneously fragmenting import pathways through stricter additive disclosure mandates and microbial strain approval requirements.
Growth Catalysts
- Processed Food Corridor Expansion:India's concentrated bakery and snack manufacturing clusters around Mumbai and Pune are pulling industrial baker's yeast volumes upward through dedicated supply contracts with fermentation facilities.
- EU Green Deal Alignment:ASEAN trade policy recalibration toward sustainability benchmarks is creating preferential access for yeast biomass producers with verified low-carbon molasses sourcing and renewable energy integration.
- Antibiotic-Free Feed Mandates:Southeast Asian livestock producers are substituting nutritional yeast extracts for growth-promoting antibiotics, opening dedicated fermentation capacity for Saccharomyces cerevisiae biomass in Vietnam and Thailand.
Market Restraints
- Molasses Supply Volatility:Sugar crop fluctuations in India and Thailand concentrate input cost risk for fermentation-based yeast producers without captive cane processing operations.
- Strain Patent Fragmentation:Proprietary Saccharomyces cerevisiae variants locked under cross-licensing agreements between Japanese and South Korean biotechnology firms restrict new market entrants from deploying optimized ethanol-tolerant strains.
- Soy-Based Substitution:Cost-sensitive commercial bakeries in Vietnam and Indonesia are displacing conventional yeast with fermented soy leavening agents where protein content specifications allow formulation flexibility.
Strategic Opportunities
- Tropical Formulation Gaps:Active dry yeast variants engineered for high-humidity storage conditions remain underdeveloped for Indonesia's archipelago distribution challenges, creating first-mover space for humidity-stable product lines.
- Functional Food Premiumization:Japan's METI-approved microbial strain registry enables yeast extract positioning in pharmaceutical and nutraceutical channels at price multiples exceeding standard baker's yeast by an order of magnitude.
- Artisan Channel Technical Service:South Korea's independent bakery sector lacks localized fermentation troubleshooting support, opening service-based differentiation for producers willing to deploy regional application laboratories.
Industry Challenges
- Cross-Border Registration Complexity:Divergent microbial strain approval frameworks between Japan's PMDA, China's SAMR, and India's FSSAI force redundant safety dossier preparation for multi-country yeast product launches.
- Fermentation Talent Scarcity:Industrial microbiology and aerobic process engineering expertise concentrates in legacy state-owned enterprises, constraining capacity expansion for private fermentation facility operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Yeast Market |
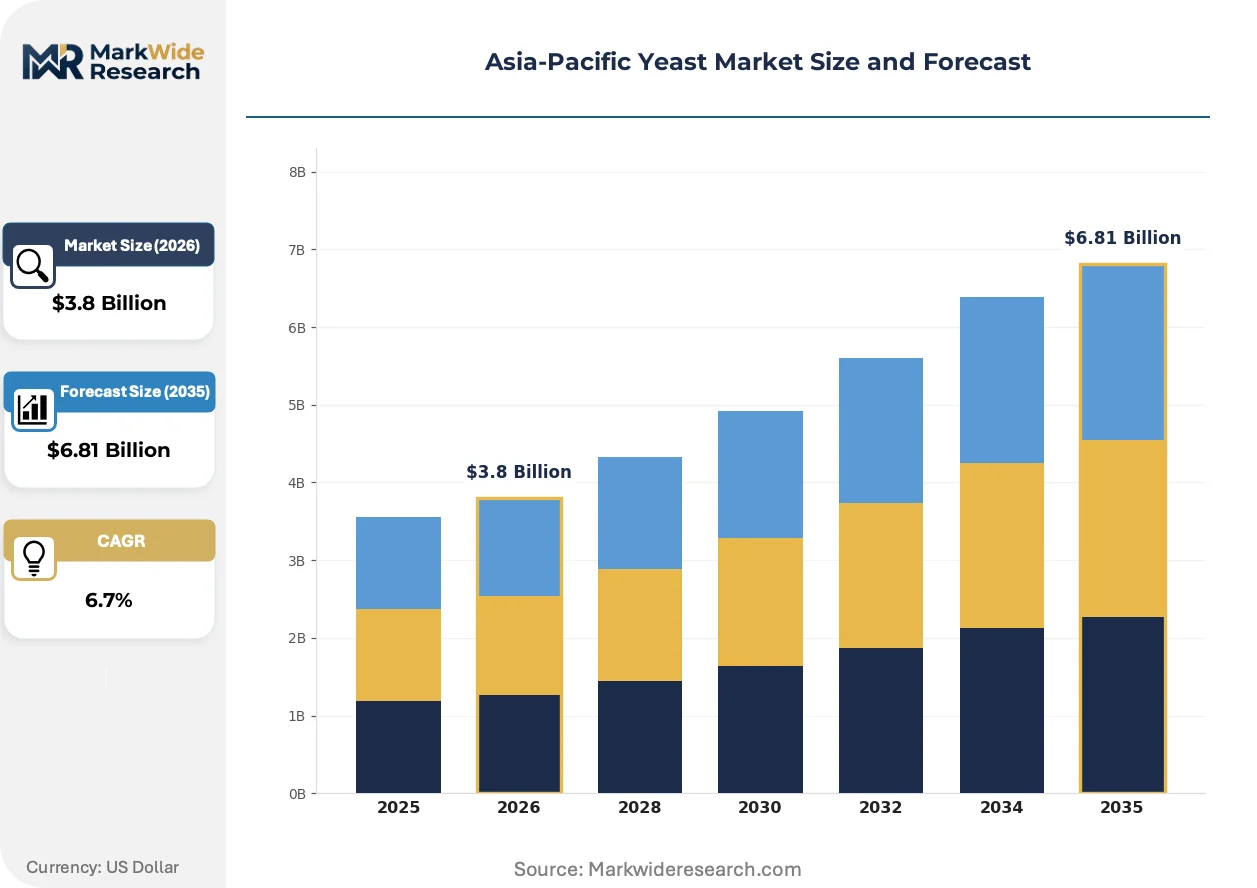
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baker's Yeast, Brewer's Yeast, Nutritional Yeast, Specialty Yeast Application: Baking, Brewing, Animal Feed, Fermentation Form: Liquid, Dry, Instant, Active Dry End User: Food Industry, Beverage Industry, Animal Nutrition, Pharmaceuticals |
| Companies Covered | Angel Yeast Co., Ltd., Lesaffre Group, Associated British Foods PLC, Lallemand Inc., Archer Daniels Midland Company, Nutreco N.V., Koninklijke DSM NV, Kerry Group plc, Alltech, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Yeast Market Strategic Shifts
Yeast production technology is fragmenting around distributed fermentation architectures, regulatory disclosure requirements are hardening traceability obligations, and buyer procurement patterns are compressing supplier consolidation timelines across the Asia-Pacific bakery and feed sectors.
Cell-cultured yeast biomass propagation is decentralizing production geography through modular bioreactor systems that slash capital intensity for mid-scale fermentation operations. Regional bakery cooperatives in Malaysia and the Philippines are piloting these containerized units to bypass molasses transport costs and cold-chain dependencies. This distributed architecture is compressing the historical advantage of centralized megafacilities with captive raw material supply.
China's SAMR enforcement of GB standards for yeast product purity and additive disclosure is forcing reformulation of imported biomass to meet domestic labeling requirements. Manufacturers must now segregate production lines for China-bound versus regional-export product variants. The compliance burden falls heaviest on nutritional yeast extract categories where fortification additive disclosure triggers mandatory re-registration.
Commercial bakery procurement in Southeast Asia is consolidating around annual volume tenders with penalty clauses for supply interruption, displacing the spot-market purchasing that historically dominated fragmented retail bakery channels. This contractual shift is compressing supplier margins while privileging fermentation operators with redundant production sites. The pattern is most visible in Vietnam's Ho Chi Minh City industrial baking cluster where three distributors now control over half of institutional yeast offtake.
Asia-Pacific Yeast Market Segmentation
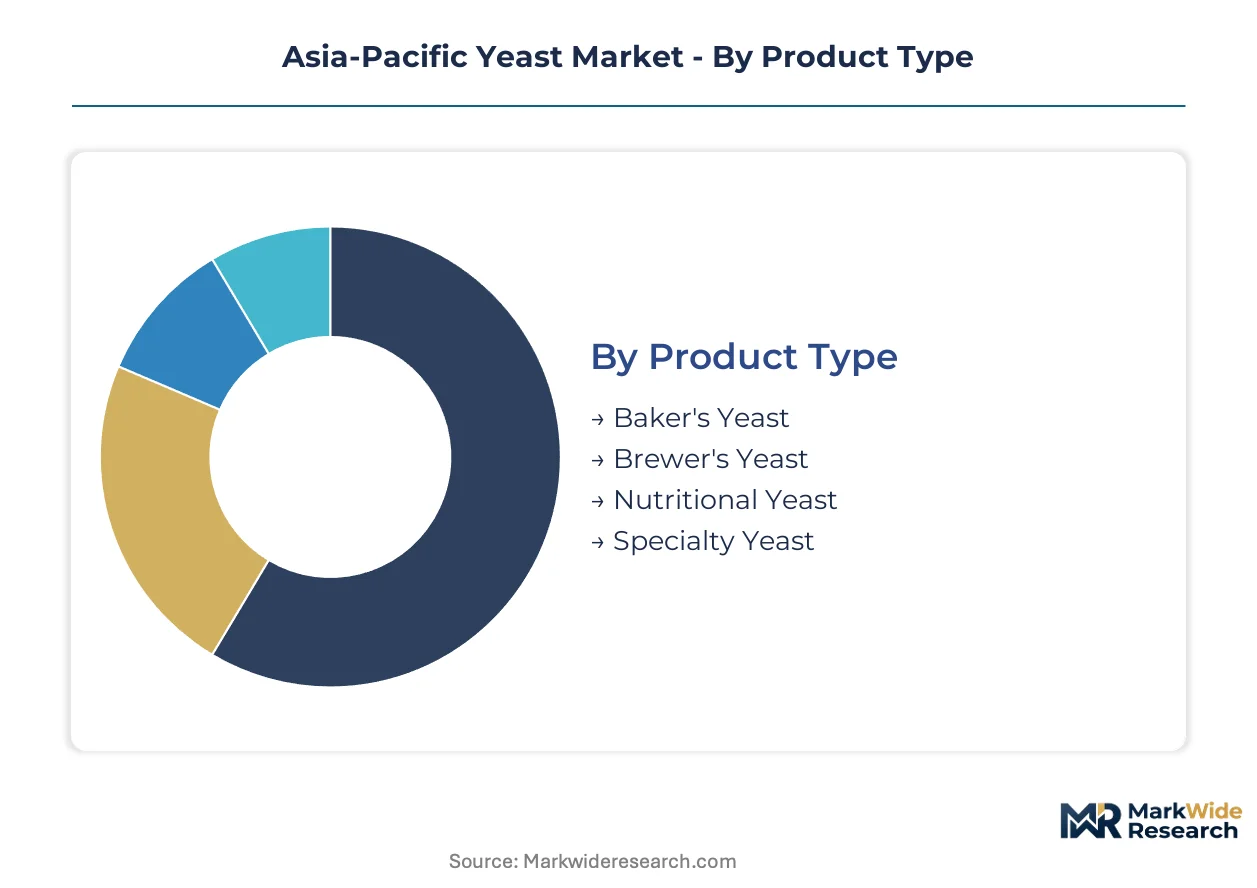
Yeast segmentation across the Asia-Pacific region reflects divergent fermentation economics, regulatory strain approvals, and humidity-driven formulation requirements that reshape procurement patterns for bakery, feed, and pharmaceutical channels.
Product Type:
Standardization dominates commodity-grade strains while specialty variants command formulation flexibility premiums across Japan's nutraceutical and South Korea's pharmaceutical channels.
- Baker's Yeast:Saccharomyces cerevisiae cultivated on molasses substrate with 40-55% protein content by dry weight. Demand concentrates in India's Mumbai-Pune processed food corridor where commercial bakeries execute dedicated supply contracts with fermentation facilities.
- Brewer's Yeast:Spent biomass recovered from beer fermentation with elevated B-vitamin complexes and bitter flavor profiles. China's interior provinces anchor procurement through Angel Yeast's captive molasses supply and integrated fermentation capacity.
- Nutritional Yeast:Inactivated whole-cell biomass fortified with B12 for vegan dietary supplementation.
- Specialty Yeast:Proprietary strain variants engineered for specific metabolic outputs including enhanced glutathione or beta-glucan content.
Most installed capacity flows through Baker's Yeast. Expansion is steepest in Nutritional Yeast.
Application:
Volume scale separates industrial baking from premium fermentation while feed applications climb fastest on antibiotic-free mandates.
- Baking:Carbon dioxide production for dough leavening across commercial and artisan bread operations. Vietnam and Indonesia see cost-sensitive displacement by soy-based alternatives where protein specifications permit formulation substitution.
- Brewing:Ethanol fermentation for beer production with strain selection optimizing attenuation and flavor compound profiles.
- Animal Feed:Saccharomyces cerevisiae biomass as antibiotic growth promoter replacement. Southeast Asian livestock producers in Vietnam and Thailand drive dedicated fermentation capacity expansion for yeast extract supplementation.
- Fermentation:Industrial ethanol and biochemical production utilizing high-tolerance strain variants.
Revenue concentration sits with Baking. Steepest expansion trajectory belongs to Animal Feed.
Form:
Cold-chain infrastructure determines liquid yeast viability while humidity resistance separates tropical-viable dry formulations from temperate-market standards.
- Liquid:Cream yeast with 18-20% solids content requiring refrigerated distribution. Japan and South Korea's dense cold-chain networks sustain technical service networks for artisan bakery channels.
- Dry:Vacuum-packed compressed yeast blocks with extended ambient stability.
- Instant:Rapid-dissolving granulated formulations eliminating rehydration steps for commercial bakery throughput optimization.
- Active Dry:Low-moisture granules with 24-month shelf life. Indonesia's archipelago distribution challenges remain underdeveloped for humidity-stable variants, creating first-mover space for tropical-formulation product lines.
Procurement volume concentrates in Liquid yeast. Active Dry formulations expand most quickly on tropical market penetration.
End User:
Regulatory approval complexity fragments pharmaceutical entry while food industry procurement consolidates around annual volume tenders with supply interruption penalties.
- Food Industry:Commercial bakeries and processed food manufacturers across Southeast Asia's consolidating procurement landscape. Vietnam's Ho Chi Minh City cluster sees three distributors controlling over half of institutional yeast offtake through penalty-clad annual contracts.
- Beverage Industry:Beer and spirits producers with strain-specific fermentation requirements.
- Animal Nutrition:Livestock and aquaculture feed compounders substituting yeast extracts for antibiotic growth promoters.
- Pharmaceuticals:Yeast-derived beta-glucans, nucleotides, and glutathione for therapeutic applications. Japan's METI-approved microbial strain registry enables price multiples exceeding standard baker's yeast through PMDA-registered product positioning.
Food Industry commands the largest revenue pool. Pharmaceuticals delivers the steepest margin expansion on functional ingredient premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai-Pune processed food corridor anchors industrial baker's yeast demand through dedicated fermentation supply contracts with commercial baking clusters.
China
Angel Yeast's captive molasses supply and integrated fermentation capacity anchor pricing power across interior provinces. SAMR enforces GB standards for yeast product purity and additive disclosure that determine market access for imported biomass. Yangtze River Delta manufacturers segregate production lines for domestic versus export-bound product variants.
India
Commercial bakeries around Mumbai and Pune execute dedicated supply contracts pulling industrial baker's yeast volumes upward. FSSAI maintains distinct microbial strain approval frameworks that fragment cross-border product registration requirements. Gujarat fermentation facilities face molasses supply volatility from sugar crop fluctuations without captive cane processing operations.
Japan
METI-approved microbial strain registry enables yeast extract positioning in pharmaceutical and nutraceutical channels at premium price multiples. PMDA registration requirements create specialized entry barriers for functional food applications. Kanto region technical service networks dominate artisan bakery channels through localized fermentation troubleshooting support.
Vietnam
Cost-sensitive commercial bakeries displace conventional yeast with fermented soy leavening agents where protein content specifications permit formulation flexibility. Antibiotic-free feed mandates drive dedicated fermentation capacity expansion for Saccharomyces cerevisiae biomass in livestock operations. Ho Chi Minh City industrial baking cluster sees procurement consolidating around annual volume tenders with supply interruption penalty clauses.
Indonesia
Archipelago distribution challenges remain underdeveloped for humidity-stable active dry yeast variants, creating first-mover space for tropical-formulation product lines. Soy-based leavening alternatives consolidate share in cost-sensitive baking segments across commercial operations. Java-based bakery cooperatives pilot modular bioreactor systems to bypass molasses transport costs and cold-chain dependencies.
Asia-Pacific Yeast Market Competitive Environment
Capacity expansion dominates the current landscape as fermentation operators build redundant production sites to meet contractual supply obligations with penalty clauses. The vendor base organizes around three strategic archetypes: integrated molasses processors with captive raw material supply, technical service specialists anchoring artisan channels, and tropical formulation innovators addressing humidity-stable distribution gaps. M&A activity concentrates on acquiring regional strain patent portfolios, while geographic expansion targets Vietnam and Thailand feed applications through dedicated biomass fermentation facilities.
Within the integrated supply tier, Angel Yeast Co., Ltd. exemplifies backward integration into captive molasses sourcing, while Lesaffre Group occupies a position emphasizing technical service networks. Lallemand Inc. represents the specialized formulation archetype, anchoring competitive positioning through product development tailored to environmental conditions. These three companies collectively illustrate the strategic segmentation between raw material control, service-based differentiation, and climate-adapted innovation that defines current competitive dynamics.
| Leading Market Players |
|---|
| Angel Yeast Co., Ltd. |
| Lesaffre Group |
| Associated British Foods PLC |
| Lallemand Inc. |
| Archer Daniels Midland Company |
| Nutreco N.V. |
| Koninklijke DSM NV |
| Kerry Group plc |
| Alltech, Inc. |
| Others |
Value Chain & Pricing Dynamics
Annual volume tenders with supply interruption penalty clauses in Vietnam's Ho Chi Minh City industrial baking cluster are compressing supplier margins and forcing fermentation operators toward redundant production sites with captive molasses supply. This procurement consolidation feeds back into pricing power concentration among integrated producers with upstream cane processing control.
Pricing Analysis
Molasses cost pass-through dominates pricing architecture across commodity-grade baker's yeast, with sugar crop fluctuations in India and Thailand transmitting directly to fermentation facility gate prices. Three-tier pricing structure across pharmaceutical-grade extracts, standard industrial biomass, and economy feed formulations separates Japan's METI-registered functional ingredients from commodity baker's yeast. Cost compression in Vietnam and Indonesia's commercial baking segments is intensifying because fermented soy leavening alternatives displace conventional yeast where protein specifications permit formulation flexibility. Animal feed compounders exhibit highest price sensitivity due to volume scale and substitution availability, while pharmaceutical channels in Japan show lowest sensitivity given strain registration barriers and functional ingredient premiums.
Supply Chain Analysis
Direct-to-industrial-bakery channels handle hyperscale demand from India's Mumbai-Pune processed food corridor, while distributor networks with technical service capabilities serve Japan and South Korea's artisan bakery segments. Supply concentration rests in China, India, and Thailand, with Yangtze River Delta and Gujarat fermentation facilities anchoring regional capacity. Raw material dependencies center on sugarcane molasses, starch hydrolysate substrates, and specialized nitrogen sources for high-cell-density propagation. Single-source vulnerability concentrates around molasses supply from non-captive cane processing operations without backward integration. Distribution runs through cold-chain dependent liquid yeast networks in Japan and South Korea, contrasted with ambient-stable active dry formulations for Indonesia's archipelago logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in this market hinge on pharmaceutical-grade yeast extract premiumization and captive molasses supply integration that insulates producers from sugar crop volatility.
For Market Incumbents: Acquire regional strain patent portfolios locked under cross-licensing agreements between Japanese and South Korean biotechnology firms to neutralize proprietary Saccharomyces cerevisiae variant access barriers. Deploy application laboratories in South Korea's independent bakery sector to anchor service-based differentiation against technical service networks. Build redundant fermentation capacity in Vietnam and Thailand to meet contractual supply obligations with penalty clauses from consolidating procurement patterns. For New Entrants and Emerging Players: Artisan bakeries in South Korea lacking localized fermentation troubleshooting support represent the most penetrable buyer archetype for technical service-based entry. Modular bioreactor systems for distributed yeast biomass propagation offer white-space positioning in Malaysia and Philippines bakery cooperatives seeking to bypass molasses transport costs. Humidity-stable active dry yeast variants for Indonesia's archipelago distribution challenges enable tropical-formulation first-mover positioning without competing against established cold-chain networks. For Investors and Strategic Acquirers: Asymmetric upside sits with fermentation operators possessing captive molasses supply and integrated strain development capabilities rather than toll-manufacturing dependent facilities. Long-term viability over a multi-year horizon favors producers with verified low-carbon molasses sourcing aligned to ASEAN sustainability benchmark recalibration. Watch for EU Green Deal alignment signals in regional trade policy as inflection indicators for preferential market access positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Molasses Supply | Angel Yeast's interior China pricing power demonstrates insulation from sugar crop volatility. |
| Regional Strain Patent Acquisition | Cross-licensing agreements between Japanese and South Korean biotechnology firms restrict new entrant strain deployment. |
| Modular Bioreactor Deployment | Malaysia and Philippines bakery cooperatives pilot containerized units to bypass cold-chain dependencies. |
| Pharmaceutical-Grade Extract Registration | Japan's METI-approved microbial strain registry enables price multiples exceeding standard baker's yeast. |
| Tropical Formulation Development | Indonesia's archipelago distribution challenges remain underdeveloped for humidity-stable active dry variants. |
Study Parameters
Coverage spans China, India, Japan, South Korea, Vietnam, Indonesia, Thailand, Malaysia, and the Philippines, with primary inputs from each market's fermentation facility operators, commercial bakery procurement managers, animal feed compounders, and regulatory affairs specialists. Secondary validation draws from SAMR GB standards filings, FSSAI microbial strain registration databases, METI-approved strain registries, customs and trade data for molasses and yeast biomass flows, and ASEAN trade policy documentation. Bottom-up capacity and consumption modeling triangulates against top-down GDP-elasticity approaches for cross-verification.
Granularity-level modeling disaggregates volume and value outputs by product type, application, form, and end user across the projection horizon, with additional dimensioning by regulatory approval cluster and humidity-zone formulation requirement. CAGRs derive from segment-specific elasticity modeling against macro drivers including processed food corridor expansion, antibiotic-free feed mandate adoption, and EU Green Deal alignment progression. Industry-specific forecast inputs incorporate molasses supply volatility indices, strain patent expiration timelines, and cold-chain infrastructure development trajectories.
Underlying measurement precision varies by segment; pharmaceutical-grade yeast extracts with PMDA registration requirements carry tighter precision than commodity baker's yeast subject to spot-market substitution. Forecasts reflect assumptions around regulatory strain approval harmonization, sugar crop yield stability, and fermentation talent availability that could revise trajectory if SAMR enforcement intensifies or molasses supply shocks materialize. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
US Choline Bitartrate Market
Ingredients
Protein Hydrolysate Market
Ingredients
Microparticulated Egg White Protein Market
Ingredients
Pulses Ingredients Market
Ingredients
Global Pregelatinized Starch Market
Ingredients
Low Calorie Cooking Oil Market
Ingredients
Bay Leaf Oil Market
Ingredients
Baobab Powder Market
Ingredients
Pine Needle Oil Market
Ingredients
Caramel Malt Market
Ingredients
Egg White Powder Market
Ingredients
Encapsulated Ingredients Market
Ingredients
South America Vegetable Oil Market
Ingredients
India Starch and Starch Derivative Market
Ingredients
Rennet Market
Ingredients
Potato Protein Market