
 AAV Contract Development and Manufacturing Organizations Market | 2026-2036
AAV Contract Development and Manufacturing Organizations Market Size, Share, and Industry Trends Forecast 2026-2036
AAV Contract Development and Manufacturing Organizations Market Intelligence
Plasmid DNA is restructuring upstream economics in AAV manufacturing as producers seek to reduce reliance on costly transient transfection workflows. Lonza Group leverages its global manufacturing network to anchor large-scale viral vector capacity across multiple continents. Thermo Fisher Scientific sustains competitive positioning through integrated analytical testing and process development services that span the full gene therapy value chain. Samsung Biologics competes aggressively on manufacturing scale, occupying substantial bioreactor capacity dedicated to viral vector production.
Adeno-associated viral vectors are recombinant, non-enveloped parvoviruses approximately 25 nanometers in diameter, engineered to deliver therapeutic genetic material into target cells without pathogenic integration, serving as the predominant delivery vehicle for in vivo gene therapy applications. AAV Contract Development and Manufacturing Organizations provide specialized process development, analytical testing, manufacturing, and quality assurance services across viral vector and plasmid DNA platforms. Manufacturing services command the largest revenue share within service type segmentation due to capital-intensive cleanroom requirements and lengthy batch timelines. Gene therapy applications dominate demand within the application dimension, while vaccine development represents an emerging growth vector as mRNA-adjacent viral vector platforms advance through clinical pipelines.
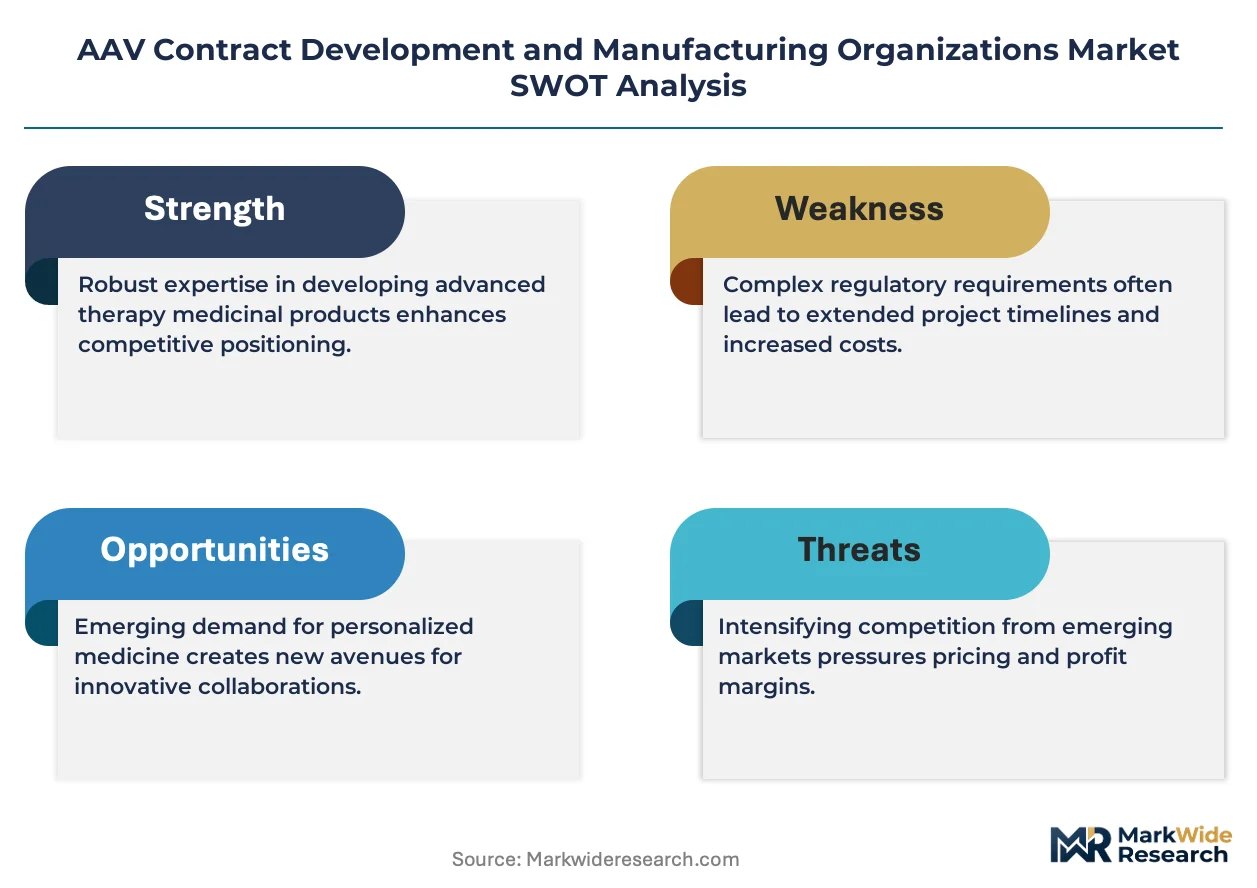
FDA gene therapy guidance, EMA advanced therapy medicinal products regulation, and ISO 14644 cleanroom standards collectively dictate facility design, batch release criteria, and cross-border market access for AAV manufacturers. These frameworks elevate compliance costs while simultaneously creating barriers that favor established CDMOs with validated quality systems and regulatory track records. Stakeholders must monitor how evolving potency assay requirements and comparability protocols reshape outsourcing decisions between integrated platform providers and specialized viral vector boutiques.
Market Dynamics
Plasmid DNA substitution for transient transfection is compressing upstream manufacturing costs while tightening quality specifications across AAV production workflows, forcing CDMOs to revalidate platform economics or risk margin erosion.
Growth Catalysts
- EMA Advanced Therapy Medicinal Products framework:Harmonized batch release standards accelerate cross-border commercialization for European gene therapy sponsors, expanding addressable contract manufacturing demand.
- HEK293 suspension adaptation:Serum-free, high-density cell culture platforms reduce per-batch raw material costs and shorten turnaround timelines for clinical-grade viral vector supply.
- Boston-San Diego biotech corridor concentration:Clustered gene therapy headquarters create localized demand pull for integrated analytical and manufacturing services within single-day logistics radius.
Market Restraints
- Plasmid DNA supply concentration:Three dominant suppliers control GMP-grade backbone inventory, exposing AAV producers to input cost volatility and allocation rationing during demand surges.
- FDA potency assay variability:Evolving guidance on infectious titer versus capsid titer ratios creates regulatory friction, delaying IND approvals and forcing redundant method development.
- Cleanroom capex intensity:ISO 14644 Grade B filling suites require USD 50-80 million per suite investment, elevating minimum efficient scale and excluding mid-tier entrants.
Strategic Opportunities
- India CDMO emergence:BIS-aligned GMP infrastructure and 40% lower skilled labor costs position Indian manufacturers to capture overflow clinical manufacturing from capacity-constrained Western facilities.
- Gene editing convergence:CRISPR-directed in vivo editing protocols require novel AAV serotype engineering, opening specialized process development contracts beyond standard gene replacement.
- Japan PMDA regenerative medicine fast-track:Sakigake designation accelerates review timelines, incentivizing Japanese pharma sponsors to outsource AAV manufacturing to CDMOs with prior PMDA inspection history.
Industry Challenges
- Cell line engineering expertise scarcity:Qualified bioprocess scientists capable of stable producer line development command 35% salary premiums, constraining CDMO hiring velocity.
- Multi-attribute method validation timelines:Mass spectrometry-based potency assays require 18-24 month qualification cycles, compressing project windows for accelerated approval pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AAV Contract Development and Manufacturing Organizations Market |
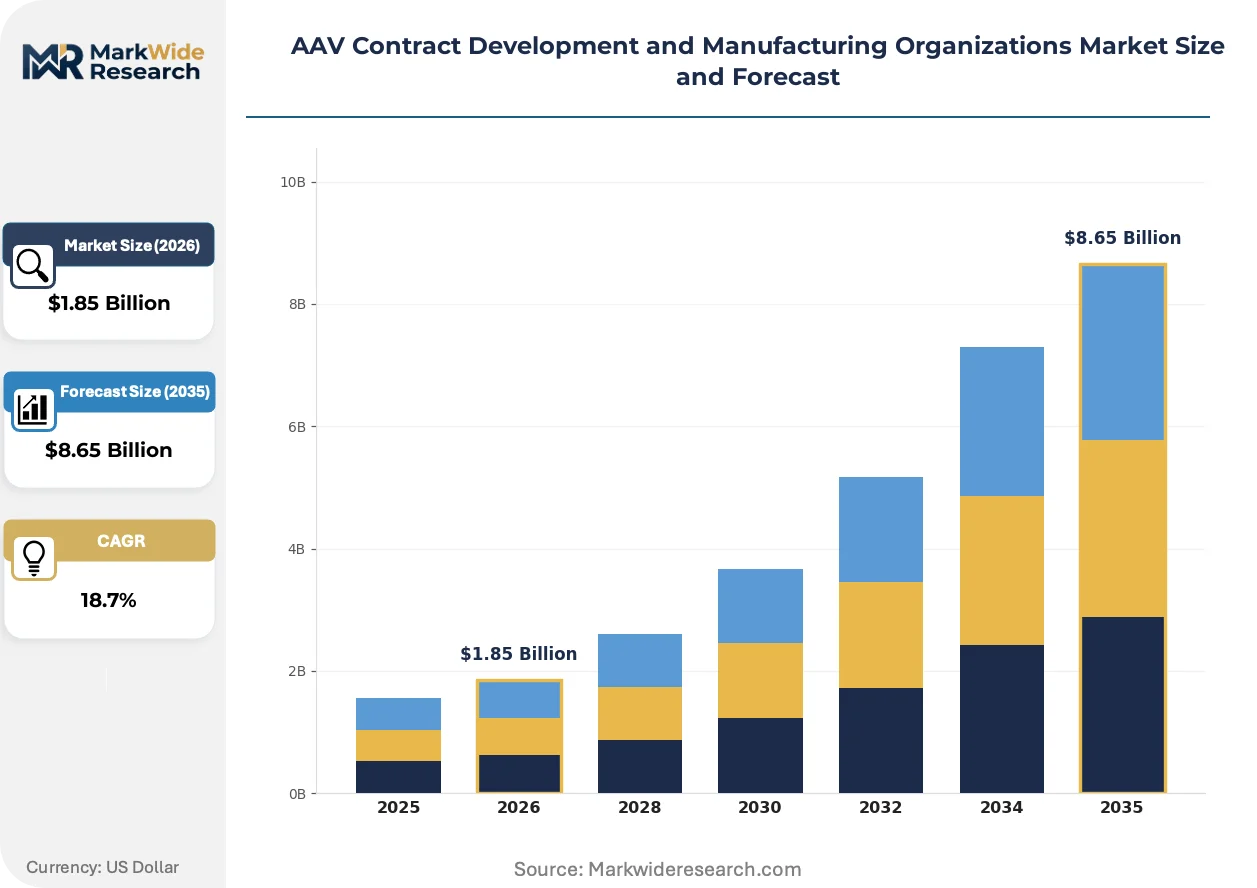
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.65 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Process Development, Analytical Testing, Manufacturing, Quality Assurance Product Type: Adeno-Associated Viral Vectors, Lentiviral Vectors, Plasmid DNA, Others End User: Biotechnology Companies, Pharmaceutical Companies, Research Institutions, Gene Therapy Firms Application: Gene Therapy, Vaccine Development, Cell Therapy, Genetic Research |
| Companies Covered | Lonza Group, Thermo Fisher Scientific, Catalent, Samsung Biologics, WuXi Biologics, Siegfried, Fujifilm Biotechnologies, Charles River Laboratories International, Recipharm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AAV Contract Development and Manufacturing Organizations Market Strategic Shifts & Innovations
Continuous bioprocessing modalities and analytical platform standardization are restructuring how AAV manufacturers balance capital efficiency against regulatory defensibility, with early adopters capturing sponsor preference in competitive bidding.
Suspension-based HEK293 platforms with chemically defined media are displacing adherent cell culture in commercial AAV manufacturing, halving facility footprint requirements while doubling batch titers. Large-capacity gene therapy sponsors in the United States are mandating suspension compatibility in CDMO selection criteria. This technology convergence with single-use bioreactor systems is compressing facility construction timelines from thirty-six to eighteen months.
FDA's evolving guidance on comparability protocols for post-approval manufacturing changes is elevating analytical burden on AAV producers, requiring extended stability data packages for site transfers. Sponsors now demand CDMOs maintain dedicated regulatory affairs staff with prior FDA meeting experience. Gene therapy applications with accelerated approval designations face the steepest compliance cost inflation under this framework.
Biotech sponsors are unbundling analytical testing from manufacturing contracts, establishing direct relationships with specialized testing laboratories to reduce single-source dependency. This channel fragmentation concentrates bargaining power with reference-standard holders. The United States exhibits the most pronounced unbundling, where Boston-based gene therapy firms maintain parallel qualification of two analytical vendors per program.
AAV Contract Development and Manufacturing Organizations Market Segmentation
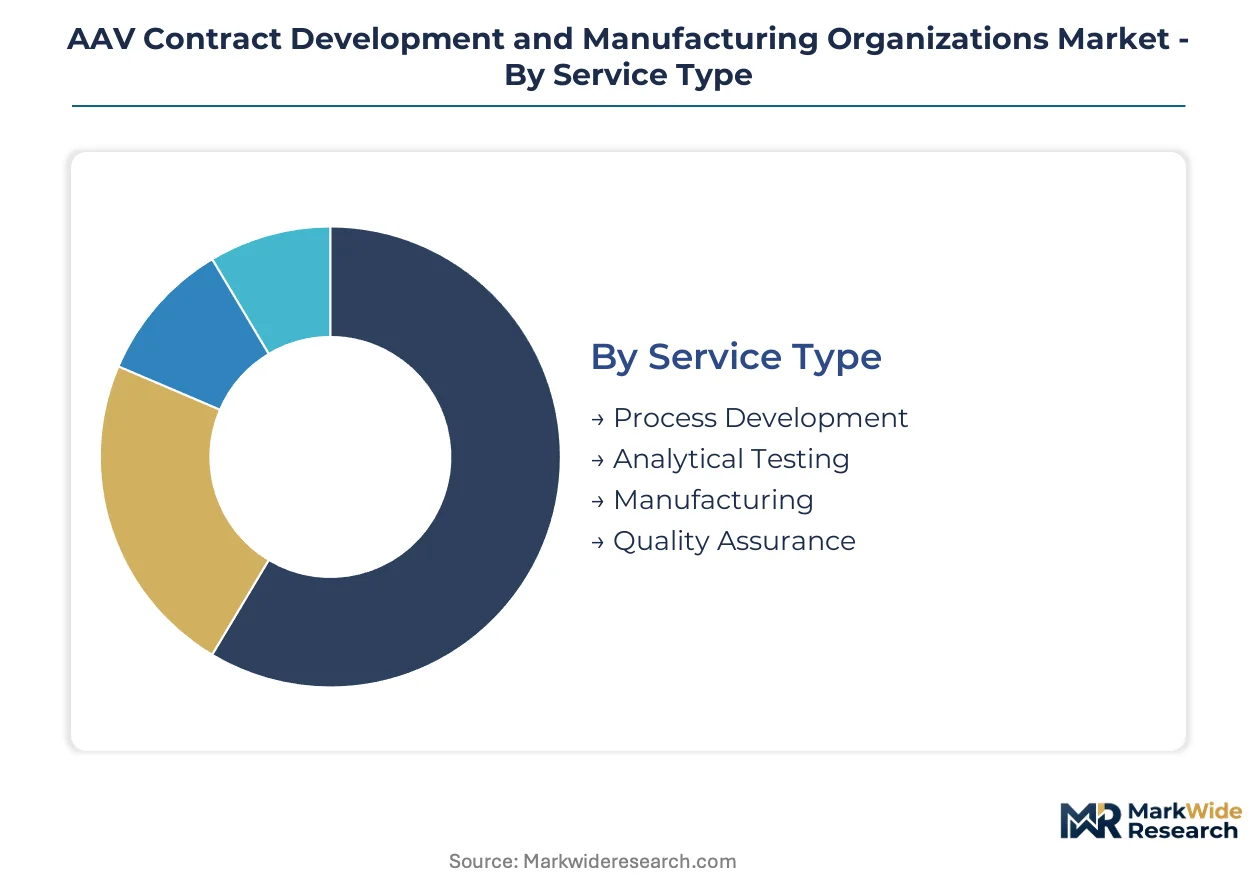
CDMO selection criteria diverge sharply between early-stage sponsors prioritizing speed and commercial-stage firms demanding scale. Segmentation reveals where capital concentrates and which service lines command pricing power.
Service Type:
Manufacturing commands volume premiums while analytical testing extracts margin through specialized expertise.
- Manufacturing:GMP-grade viral vector production requires ISO 14644 Grade B suites with single-use bioreactor systems. Demand clusters in Boston and San Diego where gene therapy sponsors require single-day logistics radius for time-sensitive batch releases.
- Analytical Testing:Potency assay development, mass spectrometry characterization, and stability testing constitute the highest-margin service tier. Sponsors increasingly unbundle testing from manufacturing contracts to reduce single-source dependency.
- Process Development:Cell line engineering and suspension platform optimization contracts precede manufacturing scale-up.
- Quality Assurance:Regulatory submission support and batch release documentation services anchor compliance workflows.
Today's leader: Manufacturing. Tomorrow's challenger: Analytical Testing.
Product Type:
Platform maturity determines cost structure and competitive intensity across vector categories.
- Adeno-Associated Viral Vectors:Recombinant non-enveloped parvoviruses approximately 25 nanometers in diameter, engineered for therapeutic gene delivery without pathogenic integration. United States gene therapy firms drive demand concentration as FDA gene therapy guidance tightens manufacturing standards.
- Plasmid DNA:Circular DNA constructs serving as transfection reagents or direct therapeutics. Supply concentrates among three dominant GMP-grade backbone suppliers, exposing AAV producers to input cost volatility during demand surges.
- Lentiviral Vectors:Enveloped RNA retroviruses for ex vivo cell modification applications.
- Others:Adenoviral vectors, baculovirus systems, and emerging synthetic delivery platforms.
AAV dominates current revenue; plasmid DNA is climbing fastest as transient transfection substitution accelerates.
End User:
Customer scale dictates contract structure, with large pharma demanding dedicated capacity and biotechs seeking flexible access.
- Gene Therapy Firms:Pure-play developers lacking internal manufacturing infrastructure constitute the most outsourcing-dependent customer segment. FDA accelerated approval pathways compress their CDMO selection timelines.
- Biotechnology Companies:Diversified therapeutic developers with partial internal capabilities.
- Pharmaceutical Companies:Established sponsors with legacy biologics infrastructure seeking viral vector capability gaps.
- Research Institutions:Academic and government laboratories with preclinical and Phase I manufacturing requirements.
Gene therapy firms anchor present demand; pharmaceutical companies represent the steepest expansion trajectory as in-house programs mature.
Application:
Clinical stage and regulatory pathway shape manufacturing specifications and pricing tolerance.
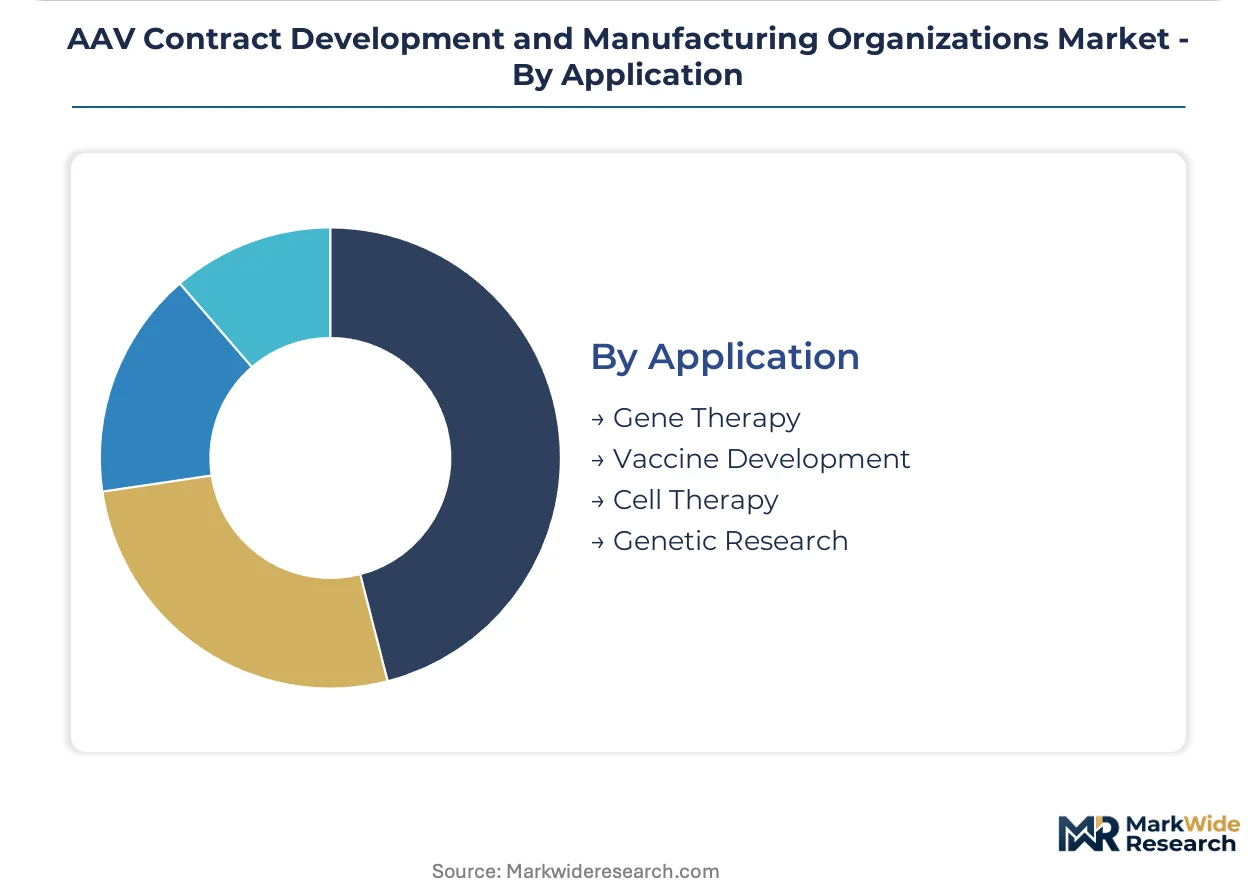
- Gene Therapy:In vivo genetic replacement and editing applications requiring high-purity, high-potency AAV supply. EMA advanced therapy medicinal products framework harmonizes batch release standards, accelerating cross-border commercialization.
- Vaccine Development:Viral vector platforms for infectious disease prophylaxis represent an emerging growth vector as mRNA-adjacent technologies advance through clinical pipelines.
- Cell Therapy:Ex vivo genetic modification supporting CAR-T and stem cell applications.
- Genetic Research:Preclinical and discovery-stage vector supply with relaxed GMP requirements.
Gene therapy commands current capacity allocation; vaccine development is gaining share fastest as pandemic preparedness investments persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston and San Diego anchor the AAV Contract Development and Manufacturing Organizations Market through clustered gene therapy headquarters demanding localized manufacturing capacity. FDA gene therapy guidance tightens manufacturing standards while EMA advanced therapy medicinal products frameworks harmonize batch release across borders. Capacity expansion concentrates where sponsor density meets regulatory stringency.
United States
FDA accelerated approval pathways compress CDMO selection timelines for gene therapy sponsors. The agency's evolving potency assay guidance creates regulatory friction requiring redundant method development. Boston and San Diego biotech corridors drive localized demand pull for integrated analytical and manufacturing services within single-day logistics radius.
Germany
EMA advanced therapy medicinal products framework harmonizes batch release standards, accelerating cross-border commercialization for European sponsors. The country's national pharmaceutical regulator enforces ISO 14644 cleanroom standards that elevate facility design requirements. Frankfurt and Munich host concentrated viral vector manufacturing infrastructure serving continental demand.
Switzerland
Swissmedic maintains stringent GMP inspection protocols that favor established CDMOs with validated quality systems. The regulator's alignment with EMA frameworks facilitates mutual recognition for batch release across European markets. Basel and Zurich anchor contract manufacturing clusters serving global pharma sponsors.
Japan
PMDA's Sakigake designation accelerates review timelines for regenerative medicine products, incentivizing outsourcing to CDMOs with prior inspection history. The national pharmaceutical regulator tightens manufacturing standards for in vivo gene therapy applications. Tokyo and Osaka metropolitan areas concentrate demand from domestic pharma sponsors expanding viral vector programs.
India
BIS-aligned GMP infrastructure and lower skilled labor costs position Indian manufacturers to capture overflow clinical manufacturing from Western facilities. The national standards body enforces quality specifications that qualify facilities for international sponsor audits. Hyderabad and Bangalore emerging as viral vector production hubs serving cost-sensitive development programs.
AAV Contract Development and Manufacturing Organizations Market Key Industry Players
Global majors compete with regional champions across manufacturing scale and regulatory track record. The market structures around three tiers: integrated platform providers with multi-continent networks, specialized viral vector boutiques with deep process expertise, and emerging scale players in lower-cost geographies. Strategic moves concentrate on capacity expansion through greenfield facilities and technology licensing for suspension-based platforms. M&A activity targets analytical testing capabilities as sponsors unbundle services.
Within the integrated platform tier, Lonza Group and Thermo Fisher Scientific exemplify archetypes spanning process development through commercial manufacturing. Samsung Biologics occupies a position among scale-driven competitors leveraging substantial bioreactor capacity. These three represent contrasting geographic anchors—Swiss, American, and Korean respectively—each sitting within distinct regulatory inspection histories that shape sponsor preferences.
| Leading Market Players |
|---|
| Lonza Group |
| Thermo Fisher Scientific |
| Catalent |
| Samsung Biologics |
| WuXi Biologics |
| Siegfried |
| Fujifilm Biotechnologies |
| Charles River Laboratories International |
| Recipharm |
| Others |
Cost & Logistics Intelligence
GMP-grade plasmid DNA spot pricing cascades through AAV manufacturing tiers, compressing margins for transient transfection-dependent producers while elevating cost premiums for suspension-platform CDMOs with captive supply.
Pricing Analysis
Input-cost pass-through from plasmid DNA suppliers concentrates pricing pressure on clinical-grade manufacturing tiers, where three dominant backbone vendors command allocation leverage during demand surges. A three-tier pricing structure separates commercial-scale GMP batches from Phase I clinical supply and preclinical research grade, with differentiation anchored in ISO 14644 cleanroom certification level and FDA prior-approval inspection history. Pricing pressure stems from HEK293 suspension platform standardization, which halves per-dose production costs and forces legacy adherent-platform CDMOs into defensive discounting. Gene therapy firms with accelerated approval designations exhibit lowest price sensitivity, prioritizing batch release speed over per-unit cost; research institutions show highest elasticity, migrating to BIS-aligned Indian manufacturers for preclinical supply.
Supply Chain Analysis
Freight costs for cryogenic viral vector shipment constrain site selection, anchoring manufacturing capacity within single-day logistics radius of Boston and San Diego gene therapy clusters. Supply concentrates in the United States, Switzerland, and Germany, where FDA, Swissmedic, and EMA inspection histories anchor sponsor qualification decisions. Raw material dependencies center on GMP-grade plasmid DNA, chemically defined media, and single-use bioreactor consumables. Single-source vulnerability runs through plasmid DNA supply, where three vendors control GMP backbone inventory. Distribution runs through dedicated cold-chain logistics partnerships with validated temperature monitoring, bypassing general freight networks for clinical and commercial batches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with gene therapy sponsors demanding prior-approval inspection history and validated potency assays over lowest-bid procurement.
For Market Incumbents: Cement regulatory moats by investing in dedicated FDA regulatory affairs staff with prior Type B meeting experience, while expanding suspension-platform capacity in Switzerland or Germany to capture EMA advanced therapy medicinal products framework demand. Threat concentration sits with Indian CDMOs capturing overflow clinical manufacturing through BIS-aligned GMP infrastructure at 40% labor cost deltas; defensive leverage requires embedding into sponsor supply chains through dedicated capacity contracts rather than spot-market competition. For New Entrants and Emerging Players: EMA advanced therapy medicinal products framework harmonization opens a window for European entrants to capture cross-border commercialization contracts from sponsors seeking batch release mutual recognition. White-space targets include analytical testing unbundling, where Boston-based gene therapy firms maintain parallel vendor qualification, and Japan PMDA Sakigake pathway support for regenerative medicine fast-track applications. Go-to-market positioning should emphasize prior PMDA inspection history and dedicated regulatory submission support staff. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized viral vector boutiques possessing stable producer cell line engineering capabilities and mass spectrometry-based potency assay validation. Long-term viability favors CDMOs with demonstrated FDA accelerated approval pathway support and established relationships with reference standard holders. Acquisition target archetype: mid-scale suspension-platform operators with validated HEK293 high-density culture systems. Signal to watch: sponsor unbundling velocity of analytical testing from manufacturing contracts, indicating channel fragmentation and bargaining power concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Suspension Platform Technology Licensing | HEK293 chemically defined media adaptation halves facility footprint and doubles batch titers for commercial supply. |
| Regulatory Affairs Staff Expansion | Dedicated FDA Type B meeting experience anchors sponsor preference in accelerated approval pathway selection. |
| Analytical Testing Capability Acquisition | Mass spectrometry potency assay validation captures unbundled testing contracts from gene therapy sponsors. |
| Indian Greenfield Manufacturing Investment | BIS-aligned GMP infrastructure positions for overflow clinical manufacturing from capacity-constrained Western facilities. |
| Japan PMDA Inspection History Development | Prior Sakigake pathway support opens regenerative medicine fast-track outsourcing contracts from domestic pharma sponsors. |
Research Approach
Coverage spans the United States, Germany, Switzerland, Japan, and India, with primary inputs from each market combining structured interviews with gene therapy development executives, regulatory affairs leads, CDMO procurement managers, and analytical testing laboratory directors alongside secondary validation. Secondary sources include FDA gene therapy guidance documents, EMA advanced therapy medicinal products framework publications, ClinicalTrials.gov pipeline tracking, and ISO 14644 cleanroom standard certifications. Bottom-up triangulation across service type, product type, and end user segmentation dimensions reconciles with top-down market sizing.
Rate-of-change decomposition separates volume expansion from pricing trajectory across the projection horizon, with analytical framework modeling manufacturing capacity utilization, plasmid DNA supply concentration effects, and regulatory inspection history premiums. Segmentation dimensions include service type tier, viral vector platform maturity, gene therapy versus vaccine application, and sponsor scale archetype. CAGRs derive from sponsor pipeline velocity, capacity expansion announcements, and cross-border commercialization framework adoption rates.
Revisions become necessary when FDA potency assay guidance shifts materially, plasmid DNA supply concentration breaks through new vendor entry, or EMA advanced therapy medicinal products mutual recognition agreements expand to additional geographies. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
Global Human Liver Models Market
Medical Research
Europe AMH Market
Medical Research
Chromatin Immunoprecipitation Sequencing Market
Medical Research
Global in Vitro Lung Model Market
Medical Research
Health Economics and Outcomes Research (HEOR) Services Market
Medical Research
Preventive Medicine Market
Medical Research
Placenta Market
Medical Research
Europe Induced Pluripotent Stem Cells (Ipscs) Market
Medical Research
Lab Automation in Drug Discovery Market
Medical Research
Clinical Genomics Market
Medical Research
US Academic Medical Centers Market
Medical Research
Malaria Vaccine Market
Medical Research
Human Osteoblasts Market
Medical Research
FFPE Tissue Samples Market
Medical Research
Methicillin-Resistant Staphylococcus Aureus (MRSA) Drugs Market
Medical Research
Forensic Medicine Market