
 Placenta Market | 2026-2036
Placenta Market Size, Share, and Industry Trends Forecast 2026-2036
Placenta Market Analysis
Human-derived biological matrices are replacing synthetic collagen in premium wound care, a shift that is realigning raw material procurement across the placenta supply chain. Regeneron Pharmaceuticals anchors its position through captive sourcing of placental tissues for cell-line development. Organogenesis Holdings dominates chronic wound applications with amnion-derived graft portfolios. Japan Bio Products sustains market presence through JIS-certified extraction protocols that command premium pricing in Asian dermatology clinics.
Placenta comprises the transient organ formed during gestation, rich in growth factors, cytokines, and extracellular matrix proteins including collagen types IV and VII, laminin, and fibronectin; processors isolate these bioactive fractions through decellularization, cryopreservation, or enzymatic digestion for therapeutic and cosmetic deployment. The product type dimension shows placenta extracts commanding the value pool due to pharmaceutical-grade purification requirements, while placenta capsules expand fastest through nutraceutical direct-to-consumer channels with lower regulatory barriers than injectable formats. Among end users, cosmetic manufacturers capture margin through branded anti-aging serums, whereas healthcare providers generate volume in chronic wound management where reimbursement codes support amniotic membrane grafts.
FDA biologics regulations govern placental tissue as human cells, tissues, and cellular and tissue-based products, requiring donor screening and current Good Tissue Practice compliance that limits supplier entry. EMA's Advanced Therapy Medicinal Products framework imposes batch-release testing on placenta-derived cell therapies, extending development timelines for European applicants. Japan's PMDA maintains distinct approval pathways for cosmetic versus pharmaceutical placenta claims, creating dual-track market architecture that shapes company portfolio strategy. Stakeholders must monitor evolving definitions of minimal manipulation across regulators, as reclassification would shift competitive requirements for topical versus injectable formats.
Market Dynamics
Human-derived biological matrices are displacing synthetic collagen in premium wound care, forcing processors to reconfigure raw material procurement around JIS-certified extraction protocols and FDA donor-screening requirements.
Growth Catalysts
- MFDS cosmetic ingredient approvals:South Korean regulators accelerated clearance timelines for placenta-derived anti-aging actives, enabling domestic brands to expand serum portfolios faster than injectable competitors.
- Chronic wound management protocols:Reimbursement codes for amniotic membrane grafts in US outpatient clinics are pulling hospital procurement toward biological matrices over synthetic alternatives.
- Direct-to-consumer nutraceutical channels:Chinese e-commerce platforms bypass traditional pharmacy distribution, allowing domestic capsule brands to scale with lower regulatory friction than pharmaceutical formats.
Market Restraints
- Donor tissue scarcity:FDA current Good Tissue Practice requirements limit qualified suppliers, concentrating viable placental sourcing among a narrow base of accredited tissue banks.
- EMA batch-release testing:Advanced Therapy Medicinal Products framework extends development timelines for European cell therapy applicants, compressing first-mover advantages.
- Synthetic collagen cost parity:Recombinant production methods for type I collagen are narrowing price gaps with human-derived matrices in standard wound care applications.
Strategic Opportunities
- Japan's dual-track PMDA pathways:Distinct cosmetic versus pharmaceutical approval routes allow portfolio segmentation between premium dermatology clinics and mass-market channels.
- Decellularization technology convergence:Integration of cryopreservation with enzymatic digestion protocols enables cleaner extracellular matrix isolation for orthobiologics applications.
- India's CDSCO biologics framework:Emerging regulatory clarity for placental-derived products creates first-entry positioning for processors establishing local manufacturing partnerships.
Industry Challenges
- Specialized tissue-processing talent:Shortage of technicians trained in aseptic decellularization and cryopreservation protocols constrains expansion beyond existing processing facilities.
- Current Good Tissue Practice compliance timelines:FDA facility inspections and donor-screening documentation requirements create 18-24 month certification backlogs for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Placenta Market |
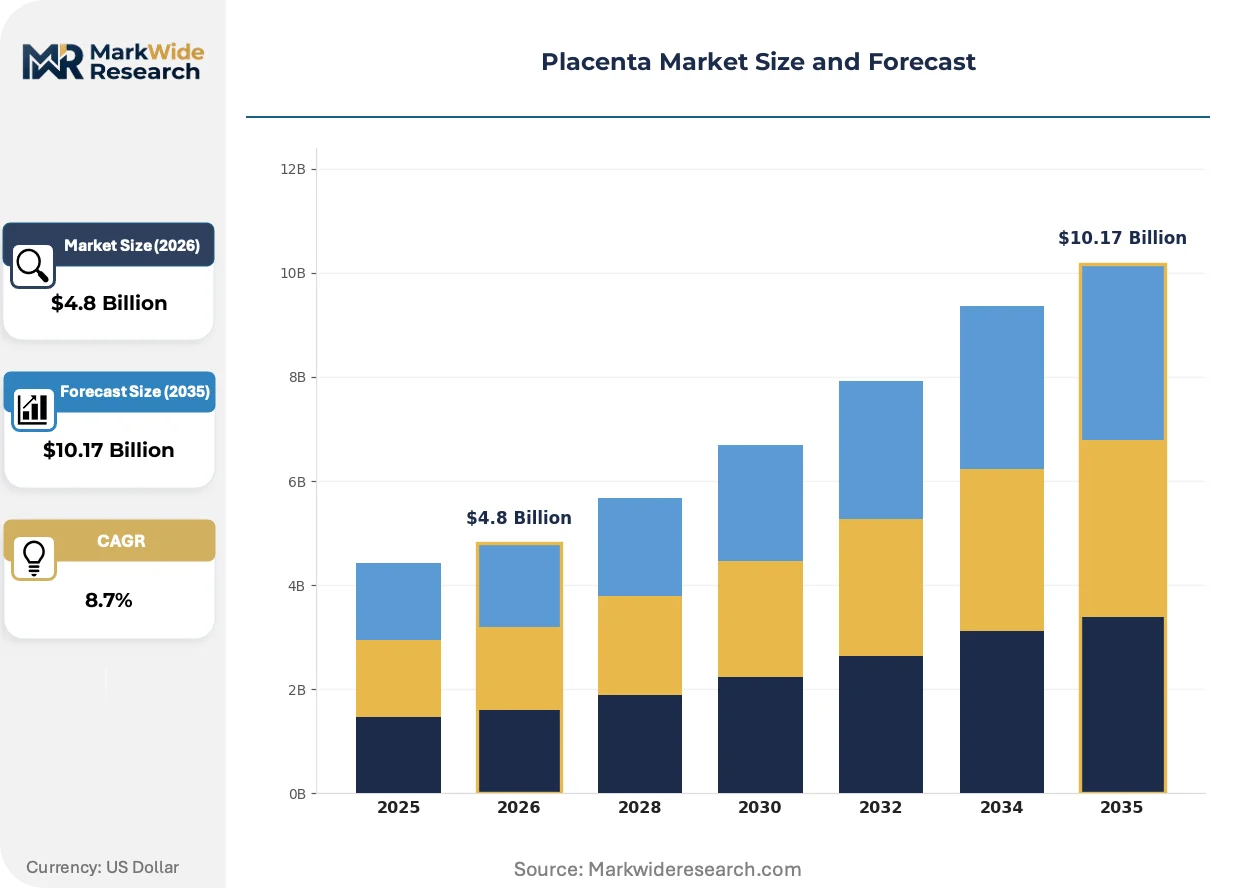
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Placenta Extracts, Placenta Capsules, Placenta Creams, Placenta Powders End User: Healthcare Providers, Cosmetic Manufacturers, Research Institutions, Nutraceutical Companies Delivery Mode: Topical, Oral, Injectable, Bulk Application: Anti-Aging, Nutritional Supplement, Skin Healing, Therapeutic Treatment |
| Companies Covered | Regeneron Pharmaceuticals Inc., ReNeuron Group plc, Japan Bio Products Co., Ltd., Smith and Nephew, Pluristem Therapeutics Inc., Japan Natural Laboratories Co., Ltd., MediWound Ltd., Organogenesis Holdings Inc., MIMEDX Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Placenta Market Emerging Trajectories
Processing technology is fragmenting into modular, application-specific workflows that decouple cosmetic-grade extraction from pharmaceutical purification, enabling tiered market entry strategies.
Lyophilized amnion products are modularizing the supply chain by separating tissue preservation from final formulation, allowing dermatology clinics to reconstitute grafts on-site rather than relying on centralized pharmacy compounding. Wound care centers in the US are adopting these formats to reduce cold-chain logistics costs. This modularity is compressing the traditional three-tier distributor model into direct manufacturer-to-provider relationships.
Japan's PMDA tightened cosmetic versus pharmaceutical claim boundaries, forcing brands to reformulate marketing language or pursue full drug approval for anti-aging injectables. Domestic manufacturers are splitting portfolios between clinic-exclusive pharmaceutical lines and over-the-counter cosmetic serums. South Korean exporters face heightened documentation requirements for placenta capsule imports labeled with functional health claims.
Hospital procurement committees are consolidating vendor lists around dual-source biological matrix suppliers, displacing single-source contracts that dominated pre-2020 wound care purchasing. Group purchasing organizations in the US are bundling amniotic grafts with orthopedic biologics, forcing smaller processors to affiliate with larger tissue bank networks. This concentration is most visible in California and Texas outpatient surgery markets where integrated delivery networks control reimbursement flows.
Placenta Market Segmentation
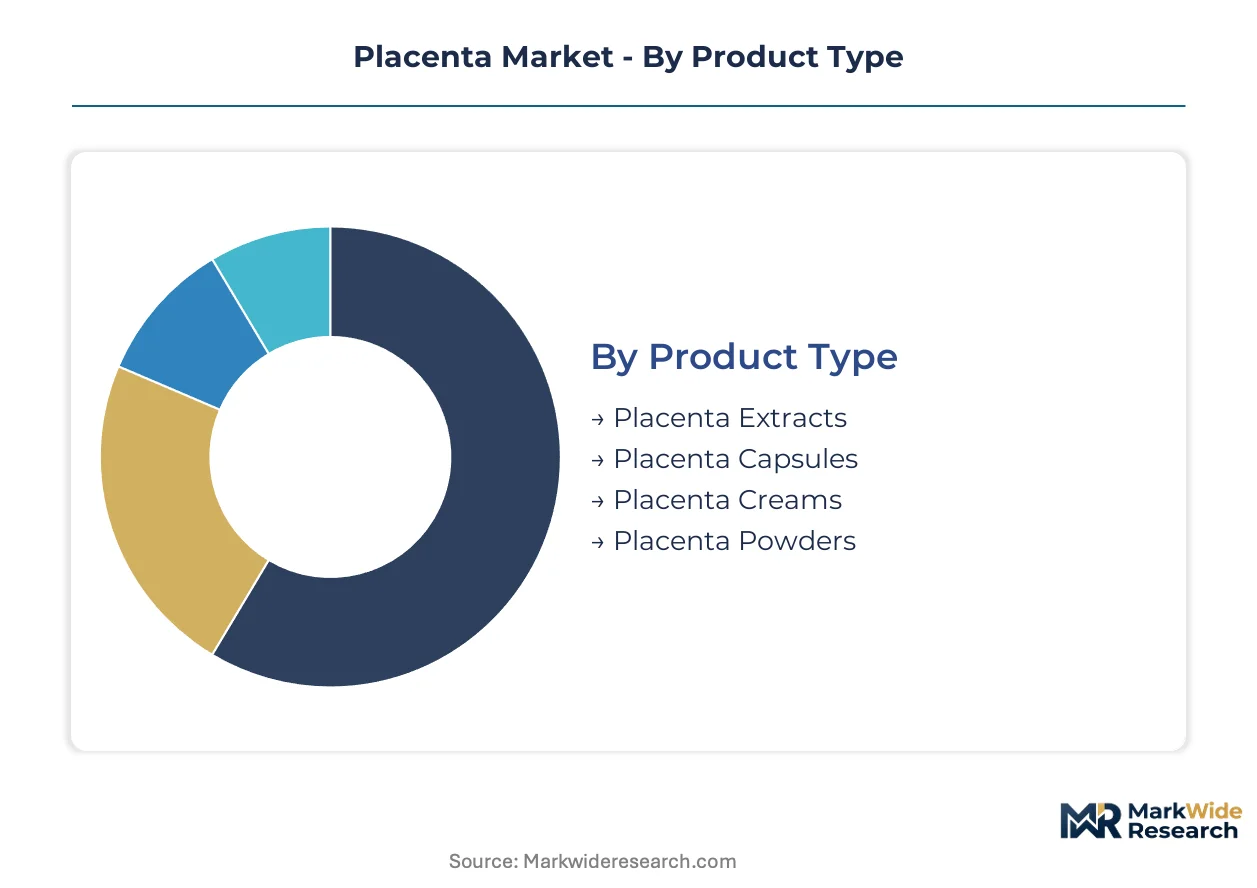
Segmentation in the placenta market reflects divergent regulatory thresholds and margin structures across pharmaceutical, cosmetic, and nutraceutical channels. Product format and delivery mode determine compliance burden, while end-user concentration shapes procurement scale and pricing power.
Product Type:
Buyers in this category separate by purification grade required and the regulatory pathway each format must navigate.
- Placenta Extracts:Pharmaceutical-grade bioactive fractions isolated through decellularization or enzymatic digestion, rich in growth factors and extracellular matrix proteins. Demand concentrates in South Korean cosmetic manufacturing clusters where MFDS ingredient approvals enable faster serum formulation launches than injectable competitors.
- Placenta Capsules:Lyophilized or desiccated placental tissue in oral dosage forms, typically positioned as nutritional supplements with lower regulatory barriers than parenteral formats. Chinese e-commerce platforms drive volume expansion as domestic nutraceutical brands bypass traditional pharmacy distribution.
- Placenta Creams:Topical emulsions incorporating placental extracts for dermatological and cosmetic applications. Japanese PMDA cosmetic-versus-pharmaceutical claim boundaries force reformulation of marketing language for anti-aging positioning.
- Placenta Powders:Dehydrated raw or processed placental material for industrial compounding and bulk formulation. Research institutions and contract manufacturers in India source these through emerging CDSCO biologics framework pathways.
Placenta extracts lead volumes today; placenta capsules are gaining share fastest.
End User:
Procurement scale and technical specification intensity distinguish customers across this dimension.
- Healthcare Providers:Hospitals, wound care centers, and outpatient clinics utilizing amniotic membrane grafts for chronic wound management. US reimbursement codes for biological matrices pull procurement away from synthetic alternatives in Texas and California integrated delivery networks.
- Cosmetic Manufacturers:Premium skincare brands formulating anti-aging serums and creams with placenta-derived actives. South Korean manufacturers dominate this segment through accelerated MFDS clearance timelines for topical ingredients.
- Research Institutions:Academic and commercial laboratories developing cell-line applications and regenerative therapies. Regeneron Pharmaceuticals anchors demand through captive sourcing for biologics development.
- Nutraceutical Companies:Direct-to-consumer supplement brands marketing placenta capsules through e-commerce channels. Chinese domestic brands expand most aggressively through platform-native distribution models.
Healthcare providers generate the largest procurement volumes; nutraceutical companies are expanding most quickly.
Delivery Mode:
Regulatory classification and cold-chain requirements create sharp cost and compliance differentiation.
- Topical:Creams, serums, and wound dressings applied to skin or mucous membranes. PMDA in Japan maintains distinct cosmetic versus pharmaceutical approval routes that shape portfolio segmentation between clinic-exclusive and mass-market channels.
- Oral:Capsules, tablets, and powders for systemic delivery through gastrointestinal absorption. Chinese e-commerce platforms enable scale with minimal regulatory friction compared to injectable formats.
- Injectable:Parenteral formulations requiring sterile manufacturing and advanced therapy medicinal product classification. EMA batch-release testing extends European development timelines and compresses first-mover advantages.
- Bulk:Unformulated raw material for downstream processing and compounding. Tissue banks with FDA current Good Tissue Practice certification control supply concentration.
Topical delivery dominates current revenue; oral formats show the steepest expansion trajectory.
Application:
Clinical evidence requirements and reimbursement availability determine addressable market size.
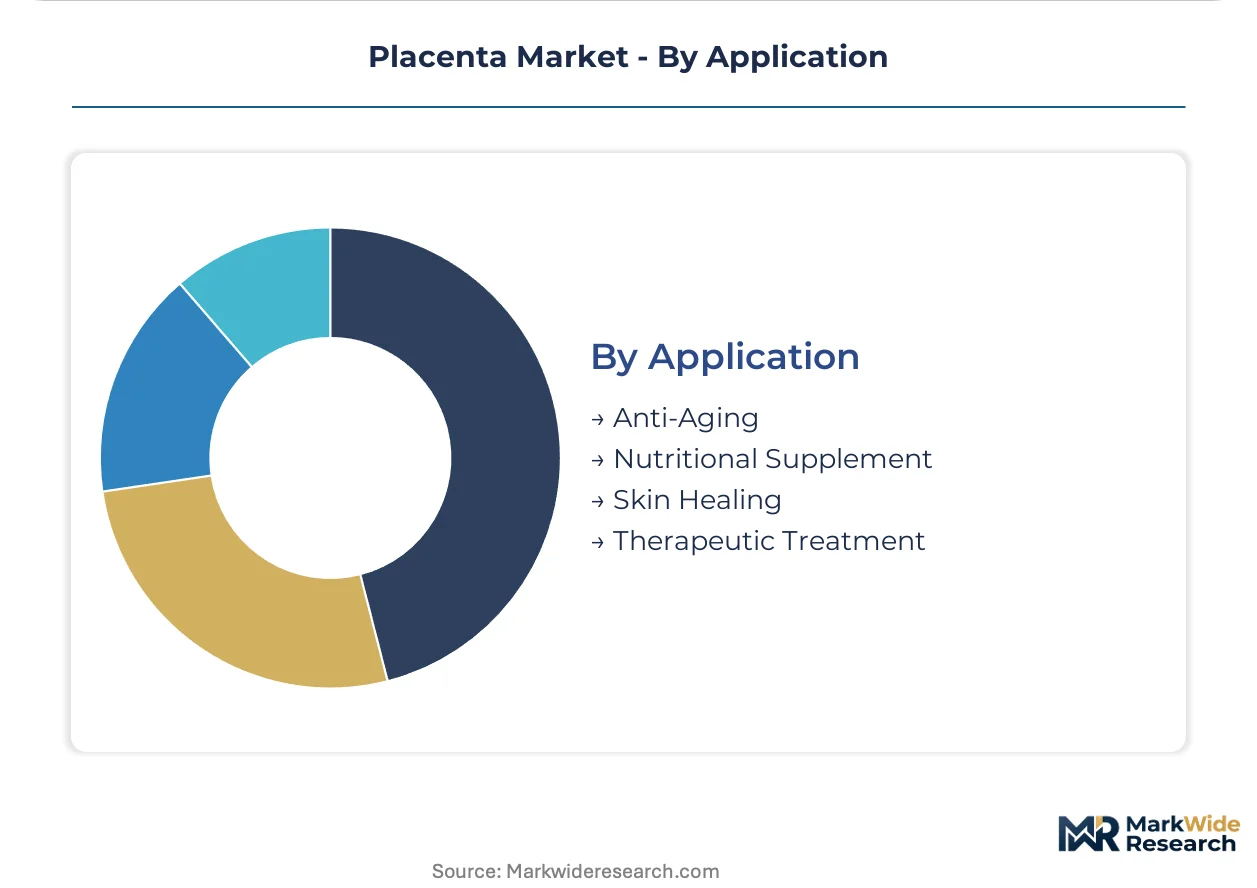
- Anti-Aging:Cosmetic and dermatological applications targeting skin rejuvenation and wrinkle reduction. South Korean serum portfolios command premium pricing through branded positioning in Asian dermatology clinics.
- Nutritional Supplement:Oral products positioned for general wellness, immune support, or hormonal balance. Direct-to-consumer channels in China bypass traditional pharmacy markups.
- Skin Healing:Wound care applications leveraging amniotic membrane grafts for chronic and surgical wounds. Organogenesis Holdings dominates US outpatient clinic procurement through lyophilized product formats.
- Therapeutic Treatment:Regenerative medicine and cell therapy applications requiring advanced purification. FDA donor-screening requirements limit qualified suppliers and concentrate viable sourcing.
Anti-aging applications anchor current value; therapeutic treatment is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul Capital Area cosmetic manufacturing clusters drive South Korean placenta extract demand through accelerated MFDS ingredient approvals. Japanese PMDA dual-track pathways segment portfolios between clinic-exclusive pharmaceuticals and mass-market cosmetics. Chinese e-commerce platforms expand nutraceutical capsule distribution beyond traditional pharmacy channels.
United States
Texas and California integrated delivery networks consolidate wound care procurement around biological matrix suppliers. FDA current Good Tissue Practice requirements limit qualified tissue banks, concentrating viable placental sourcing among accredited suppliers. Organogenesis Holdings anchors chronic wound applications through lyophilized amnion graft portfolios in outpatient surgery markets.
Japan
Tokyo dermatology clinics command premium pricing for JIS-certified extraction protocols in anti-aging applications. PMDA tightened cosmetic versus pharmaceutical claim boundaries, forcing brands to reformulate marketing language or pursue full drug approval. Osaka-based manufacturers split portfolios between clinic-exclusive pharmaceutical lines and over-the-counter cosmetic serums.
China
Domestic nutraceutical brands expand placenta capsule lines through direct-to-consumer e-commerce channels with lower regulatory friction than pharmaceutical formats. SAMR oversight of functional health claims shapes import documentation requirements for South Korean exporters. Shanghai and Beijing processing hubs concentrate lyophilized product manufacturing for regional distribution.
South Korea
MFDS accelerated clearance timelines for placenta-derived anti-aging actives enable faster serum formulation launches than injectable competitors. Seoul cosmetic manufacturing clusters drive adoption of placenta-derived formulations in premium skincare brands. Busan-Ulsan biologics processing facilities support export-oriented production for Asian dermatology markets.
India
CDSCO emerging regulatory clarity for placental-derived products creates first-entry positioning for processors establishing local manufacturing partnerships. Mumbai and Hyderabad research institutions source dehydrated placental powders for cell-line development applications. Contract manufacturers leverage lower-cost processing infrastructure to serve regional pharmaceutical and cosmetic formulators.
Placenta Market Vendor Landscape
Global majors compete with regional champions across regulatory compliance and tissue-processing certification dimensions. Market structure concentrates around dual-source biological matrix suppliers displacing single-source contracts that dominated pre-2020 wound care purchasing. Three archetypes dominate: pharmaceutical-grade extract purifiers serving regulated therapeutic channels, cosmetic-grade processors leveraging accelerated topical ingredient approvals, and nutraceutical capsule suppliers scaling through direct-to-consumer platforms. Competitive moves center on M&A to secure accredited tissue bank networks and geographic expansion into emerging regulatory jurisdictions.
Among US-based biologics developers, Regeneron Pharmaceuticals exemplifies captive sourcing strategies for placental tissue in cell-line development. Organogenesis Holdings occupies a position within the wound care matrix tier through lyophilized graft portfolios. Japan Bio Products Co., Ltd. represents the premium extraction protocol segment with JIS-certified processes commanding dermatology clinic pricing power.
| Leading Market Players |
|---|
| Regeneron Pharmaceuticals Inc. |
| ReNeuron Group plc |
| Japan Bio Products Co., Ltd. |
| Smith and Nephew |
| Pluristem Therapeutics Inc. |
| Japan Natural Laboratories Co., Ltd. |
| MediWound Ltd. |
| Organogenesis Holdings Inc. |
| MIMEDX Group, Inc. |
| Others |
Supply Flow & Price Mechanics
Captive sourcing arrangements among US biologics developers anchor both supply security and pricing power in pharmaceutical-grade placental tissue, while South Korean cosmetic manufacturers exploit outsourced ingredient networks to compress procurement costs for anti-aging actives.
Pricing Analysis
Input-cost pass-through from JIS-certified extraction protocols and FDA donor-screening requirements shapes contract-based long-term offtake pricing for pharmaceutical-grade extracts. Price differentiation centers on certification tier and volume scale, with MFDS-approved cosmetic actives commanding premiums over nutraceutical capsules. Pricing pressure intensifies in standard wound care as recombinant collagen narrows cost gaps with human-derived matrices. Nutraceutical capsule buyers exhibit highest price sensitivity, while regenerative therapy developers accept elevated costs for validated tissue provenance.
Supply Chain Analysis
Placental tissue supply rests on accredited tissue banks in the United States, South Korea, and Japan, with secondary processing nodes emerging in India and China. Raw material dependencies center on donor screening infrastructure, cryopreservation capacity, and enzymatic digestion reagents. Single-source vulnerability concentrates in FDA-certified facilities facing 18-24 month certification backlogs. Distribution runs through direct manufacturer-to-provider relationships for lyophilized grafts, bypassing traditional three-tier pharmaceutical distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The placenta market functions as a regulatory compounder where FDA biologics classification and EMA Advanced Therapy Medicinal Products batch-release requirements continuously elevate compliance barriers that favor incumbent scale.
For Market Incumbents: Cement tissue bank network control through exclusive sourcing agreements with accredited US facilities, insulating against donor scarcity that threatens smaller competitors. Invest in modular decellularization capacity to serve both cosmetic and pharmaceutical grades from shared processing infrastructure, capturing margin across dual-track regulatory pathways.
For New Entrants and Emerging Players: Direct-to-consumer nutraceutical channels in China offer the most penetrable entry vector, bypassing FDA and EMA pharmaceutical compliance timelines entirely. Target oral capsule formats with functional health claims through platform-native e-commerce distribution, leveraging lower regulatory friction than injectable or topical pharmaceutical alternatives.
For Investors and Strategic Acquirers: Roll-up economics work for regional tissue processors because fragmented certification requirements create local moats that resist global consolidation. Prioritize targets with established CDSCO or MFDS pathways in India and South Korea, where emerging regulatory clarity enables first-entry positioning. Watch PMDA cosmetic-versus-pharmaceutical claim boundary enforcement as the inflection indicator for portfolio resegmenting moves.
| Strategic Initiative | Industry Significance |
|---|---|
| Accredited Tissue Bank Acquisition | Captive sourcing secures FDA-compliant donor networks against 18-24 month certification delays. |
| Dual-Track Regulatory Filing | Parallel PMDA cosmetic and pharmaceutical pathways enable portfolio segmentation across clinic and mass channels. |
| Lyophilized Product Format Launch | Modular graft reconstitution reduces cold-chain logistics costs for US outpatient surgery centers. |
| CDSCO Manufacturing Partnership | Local Indian processing infrastructure captures emerging biologics framework clarity before competitors. |
| Direct-to-Consumer Platform Integration | E-commerce native distribution bypasses pharmacy markups for Chinese nutraceutical capsule scaling. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tissue bank procurement officers, cosmetic formulation chemists, regulatory affairs specialists at biologics developers, and hospital wound care purchasing managers with secondary validation against FDA 510(k) filings, EMA Advanced Therapy Medicinal Products submissions, MFDS ingredient approval databases, and customs trade records. Bottom-up product-format volume estimates and top-down regional market sizing were triangulated to anchor projections.
Segment-weighting approaches distributed value across product type, end user, delivery mode, and application dimensions, with additional granularity for regulatory pathway clusters. CAGRs were derived from fitted growth curves applied to base-year estimates, incorporating patent expiration timelines for competing synthetic matrices and reimbursement code expansion trajectories for amniotic grafts as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for recombinant collagen production would alter the outlook for human-derived matrix demand. Forecasts reflect documented assumptions around regulatory classification stability and donor tissue availability. A small set of triggers—PMDA claim boundary shifts, EMA batch-release timeline changes, and synthetic collagen cost parity milestones—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
Cancer Mouse Models Market
Medical Research
FFPE Tissue Samples Market
Medical Research
Lab Automation in Drug Discovery Market
Medical Research
Organoids and Spheroids Market
Medical Research
Life Science R&D Infrastructure Outsourcing Market
Medical Research
India Computer-Aided Drug Discovery Market
Medical Research
Mice Model Technologies Market
Medical Research
Asia-Pacific Computer-Aided Drug Discovery Market
Medical Research
Global in Vitro Lung Model Market
Medical Research
US Academic Medical Centers Market
Medical Research
Preventive Medicine Market
Medical Research
AAV Contract Development and Manufacturing Organizations Market
Medical Research
North America Biobanks Market
Medical Research
Chromatin Immunoprecipitation Sequencing Market
Medical Research
Epigenetics Market
Medical Research
Methicillin-Resistant Staphylococcus Aureus (MRSA) Drugs Market