
 Chromatin Immunoprecipitation Sequencing Market | 2026-2036
Chromatin Immunoprecipitation Sequencing Market Size, Share, and Industry Trends Forecast 2026-2036
Chromatin Immunoprecipitation Sequencing Market Outlook
Direct-to-laboratory distribution is reshaping how ChIP-seq reagents and platforms reach end users, bypassing traditional multi-tier distribution. Thermo Fisher Scientific leverages its end-to-end workflow portfolio to anchor supply relationships with major academic sequencing centers. Illumina dominates the instrument layer with its NovaSeq and NextSeq platforms that standardize ChIP-seq readout protocols. Qiagen N.V. competes through specialized chromatin preparation kits that integrate with third-party sequencing workflows.
Chromatin Immunoprecipitation Sequencing is a molecular biology technique that crosslinks proteins to DNA, fragments chromatin, immunoprecipitates target protein-DNA complexes with specific antibodies, and sequences the associated DNA to map protein-binding sites across the genome with single-nucleotide resolution. The method enables researchers to identify transcription factor binding patterns, histone modification landscapes, and regulatory element architecture for functional genomics studies. Reagents and kits constitute the largest product segment due to recurring consumable demand, while next-generation sequencing technology captures the fastest expansion as library preparation costs decline. Academic research remains the dominant end-user channel, though pharmaceutical companies represent the highest-margin application segment for targeted drug development programs.
FDA oversight of laboratory-developed tests and clinical-grade sequencing workflows shapes product validation requirements for ChIP-seq platforms entering diagnostic applications. ISO 15189 accreditation standards for clinical laboratories drive quality management system adoption among kit manufacturers seeking hospital and reference lab contracts. The EU In Vitro Diagnostic Regulation imposes conformity assessment burdens on European market access for research-use-only products with potential clinical utility. Stakeholders must monitor evolving reimbursement frameworks for epigenetic biomarker tests and position their product portfolios across the research-to-clinical value chain.
Market Dynamics
Library preparation automation and single-cell resolution capabilities are compressing ChIP-seq turnaround times from weeks to days, forcing workflow standardization across academic core facilities and commercial service providers.
Growth Catalysts
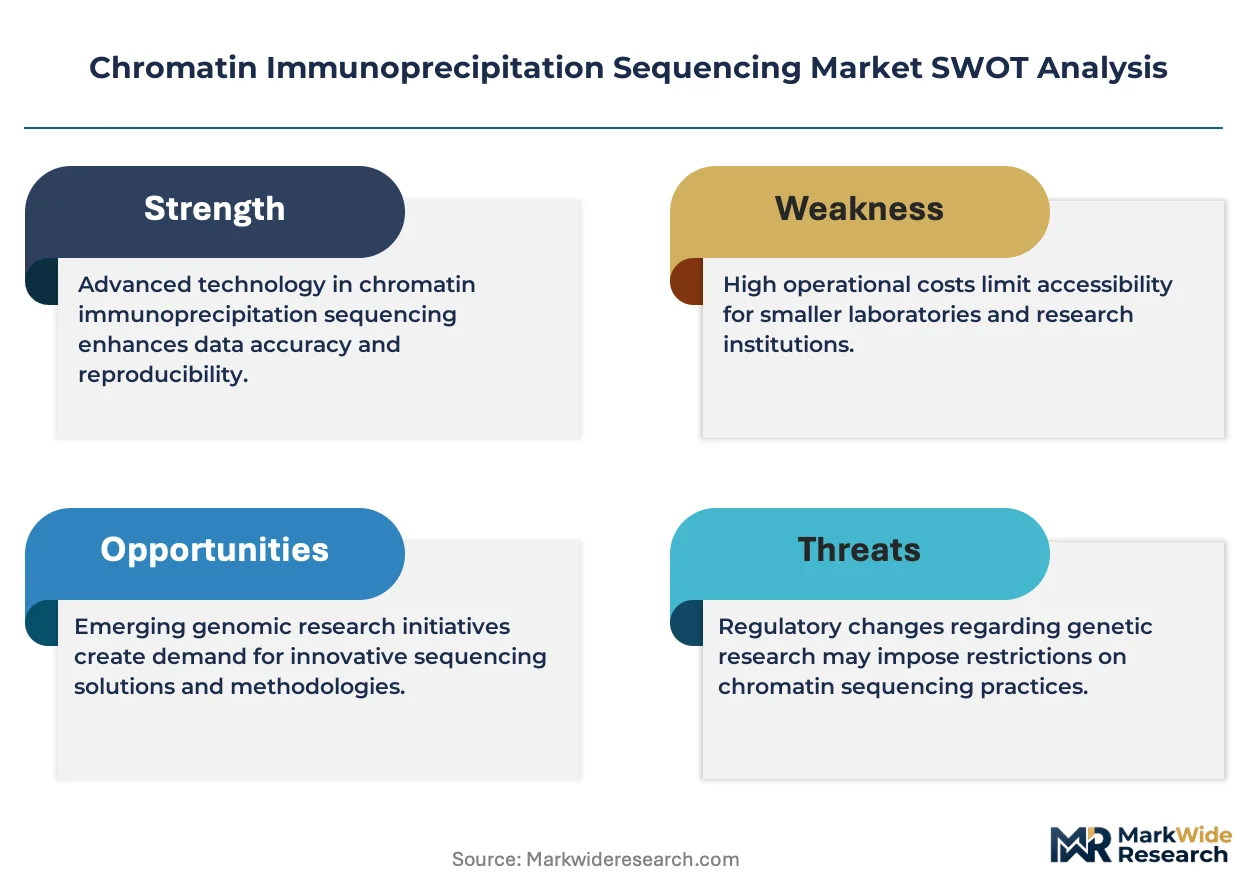
- NIH funding pipelines:Sustained extramural research budgets at the National Institutes of Health channel capital into epigenetic mapping initiatives at US academic medical centers.
- Histone modification mapping:Pharmaceutical toxicology programs require chromatin state profiling for mechanism-of-action studies in drug candidate screening.
- Cloud-based bioinformatics:Distributed computing infrastructure lowers computational barriers for smaller laboratories analyzing ChIP-seq datasets.
Market Restraints
- Antibody specificity failures:Batch-to-batch variability in commercial immunoprecipitation reagents generates irreproducible binding site calls.
- Sequencing instrument oligopoly:Concentrated supply of high-throughput sequencers creates vendor lock-in and limits price negotiation leverage.
- Input material requirements:Standard protocols demand millions of cells, excluding rare clinical specimens from routine analysis.
Strategic Opportunities
- Clinical diagnostic translation:FDA breakthrough device designation pathways accelerate regulatory clearance for epigenetic biomarker assays.
- Single-cell ChIP-seq:Droplet-based microfluidic integration enables cell-type-specific regulatory mapping in heterogeneous tissues.
- Direct-to-laboratory distribution:E-commerce portals for reagent procurement bypass distributor markups and reduce order fulfillment friction.
Industry Challenges
- Bioinformatics expertise scarcity:Peak calling algorithm selection and false discovery rate control require specialized computational biology training unavailable at most core facilities.
- Cross-platform standardization gaps:Absence of reference materials for chromatin quality metrics complicates inter-laboratory protocol harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chromatin Immunoprecipitation Sequencing Market |
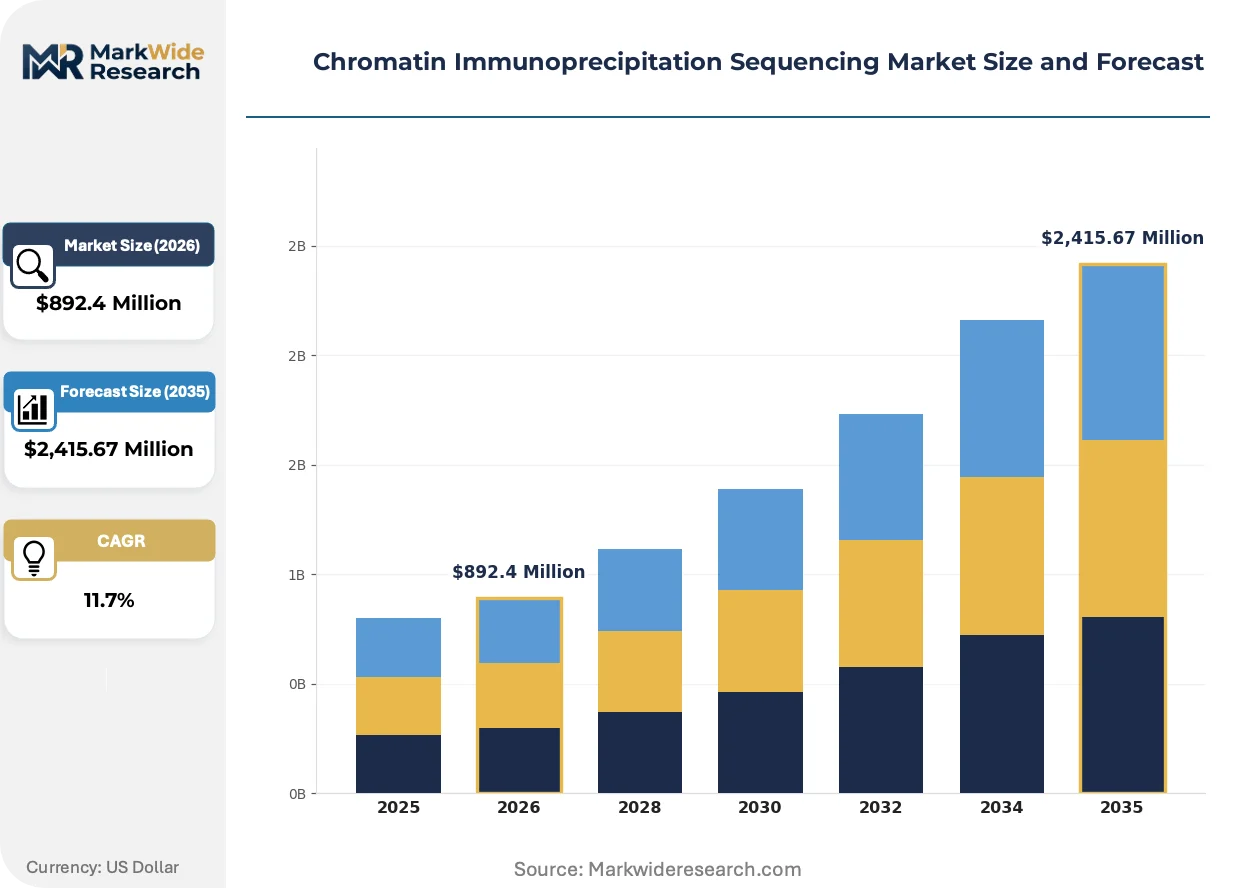
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $2,415.67 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Consumables, Accessories Technology: Next-Generation Sequencing, PCR, Microarray, Mass Spectrometry End User: Academic Research, Pharmaceutical Companies, Biotechnology Firms, Clinical Laboratories Application: Gene Regulation, Epigenetics, Cancer Research, Drug Development |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Illumina Inc., Bio-Rad Laboratories Inc., Agilent Technologies Inc., Abcam plc, Bio-Techne Corp., Qiagen N.V., PerkinElmer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chromatin Immunoprecipitation Sequencing Market Strategic Shifts
Automation and miniaturization are converging to democratize ChIP-seq access beyond elite genomics centers, while regulatory pressure on clinical-grade epigenetic assays intensifies validation requirements.
Microfluidic chromatin shearing systems are collapsing sample input requirements from millions to thousands of cells. Transcriptional regulatory biologists at cancer research institutes are adopting these platforms for patient-derived xenograft profiling. The technology is collapsing the barrier between bulk tissue analysis and single-cell regulatory genomics.
EU In Vitro Diagnostic Regulation conformity assessment procedures impose clinical validation documentation burdens on research-use-only kit manufacturers seeking European hospital contracts. Reagent suppliers must establish quality management systems meeting ISO 15189 accreditation standards. Academic core facilities in Germany and France are delaying procurement decisions pending regulatory clarity on dual-use product classifications.
Consolidated purchasing consortia at US academic medical centers are displacing individual laboratory reagent procurement. Multi-institutional buying cooperatives negotiate volume discounts directly with manufacturers, bypassing traditional distribution tiers. The University of California system and Texas Medical Center exemplify this concentration of procurement authority.
Chromatin Immunoprecipitation Sequencing Market Segmentation
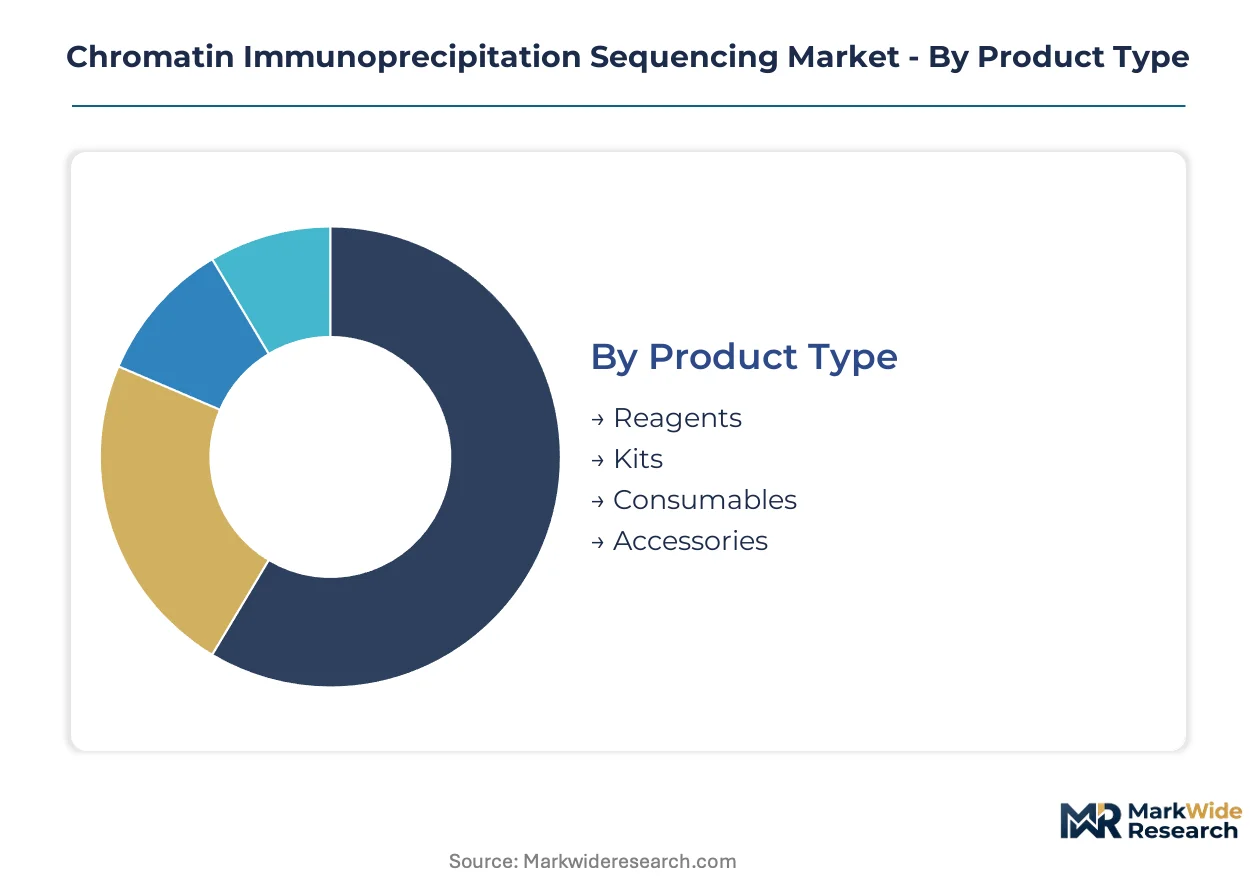
ChIP-seq market segmentation reveals distinct procurement patterns across product types, technologies, and end-user channels. Each dimension carries different service intensity requirements, from consumable replenishment cycles to platform validation support.
Product Type:
After-sales-service intensity varies sharply across product categories, with reagent and kit lines demanding continuous technical support while accessories require minimal intervention.
- Reagents:Antibodies, crosslinking agents, and chromatin shearing buffers constitute the highest-velocity procurement category. Academic core facilities at Johns Hopkins University and Stanford University maintain standing orders for validated antibody lots, driven by NIH-funded epigenetic mapping consortia requiring batch-to-batch consistency documentation.
- Kits:Integrated chromatin preparation and immunoprecipitation workflows reduce protocol variability. Pharmaceutical toxicology programs at Merck and Bristol Myers Squibb specify kit-based standardization for regulatory submission reproducibility, creating premium pricing power for validated suppliers.
- Consumables:Magnetic beads, spin columns, and library prep cartridges generate recurring revenue streams with predictable replacement cycles.
- Accessories:Tube racks, magnetic stands, and thermal cycler adapters represent low-margin, high-volume procurement with minimal technical support requirements.
By volume, Reagents leads. By growth pace, Kits is ahead.
Technology:
Platform selection determines capital commitment levels and bioinformatics infrastructure requirements, creating distinct customer lock-in patterns.
- Next-Generation Sequencing:Illumina NovaSeq and NextSeq platforms dominate readout standardization. Single-cell resolution capabilities are compressing turnaround times at cancer research institutes, though instrument oligopoly limits price negotiation leverage.
- PCR:Quantitative validation of ChIP-enriched regions remains essential for low-throughput confirmation studies. Smaller biotechnology firms deploy PCR-based workflows where sequencing infrastructure is unavailable.
- Microarray:Legacy tiling array platforms persist in retrospective cohort studies where sequencing library preparation costs are prohibitive.
- Mass Spectrometry:Proteomic characterization of co-immunoprecipitated complexes enables multi-omics integration at specialized academic centers.
By installed base, Next-Generation Sequencing dominates. By capability expansion, Mass Spectrometry integration is climbing fastest.
End User:
Customer type dictates pricing tolerance, validation requirements, and contract structure complexity across the procurement spectrum.
- Academic Research:University core facilities and medical centers constitute the largest addressable base. Consolidated purchasing consortia at the University of California system and Texas Medical Center negotiate volume discounts directly with manufacturers, bypassing traditional distribution tiers.
- Pharmaceutical Companies:Drug development programs command the highest margins due to regulatory-grade documentation requirements. Mechanism-of-action studies for histone modification mapping drive specialized chromatin state profiling contracts.
- Biotechnology Firms:Cell therapy developers and gene editing platforms require customized assay development support with flexible procurement terms.
- Clinical Laboratories:ISO 15189 accreditation standards and FDA oversight of laboratory-developed tests impose quality management burdens that filter supplier eligibility.
By transaction volume, Academic Research leads. By margin expansion, Clinical Laboratories is gaining share fastest.
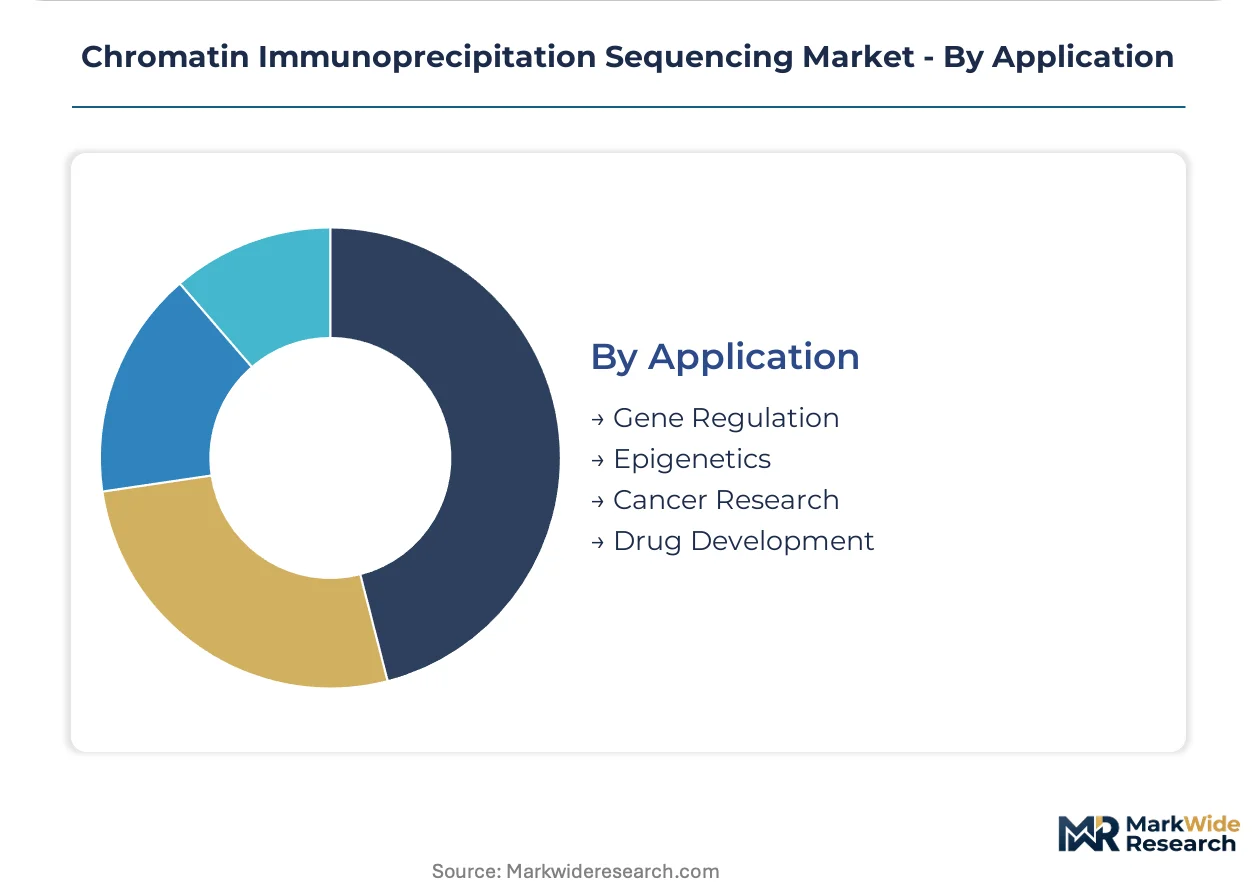
Application:
Use-case specificity determines protocol complexity, antibody panel requirements, and data analysis support needs.
- Gene Regulation:Transcription factor binding site mapping requires antibody specificity validation that generates irreproducible calls when batch variability occurs. Peak calling algorithm selection demands specialized computational biology training.
- Epigenetics:Histone modification landscape profiling spans broad chromatin state characterization. Cloud-based bioinformatics infrastructure at the Broad Institute and European Bioinformatics Institute lowers computational barriers for distributed research groups.
- Cancer Research:Patient-derived xenograft profiling leverages microfluidic chromatin shearing to collapse input requirements from millions to thousands of cells.
- Drug Development:Toxicology screening programs require standardized regulatory documentation for IND submission packages.
By protocol diversity, Epigenetics leads. By clinical translation urgency, Drug Development is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA oversight of laboratory-developed tests shapes validation requirements for ChIP-seq platforms entering diagnostic applications in the United States. Academic research institutions across multiple geographies are expanding adoption of epigenetic mapping workflows as sequencing costs decline.
United States
NIH extramural funding channels capital into epigenetic mapping initiatives at academic medical centers. The FDA's oversight framework for laboratory-developed tests imposes quality management burdens on kit manufacturers seeking hospital contracts. Research clusters in Boston and the San Francisco Bay Area concentrate sequencing infrastructure procurement.
Germany
Academic core facilities in Heidelberg and Munich drive demand for standardized chromatin preparation workflows. ISO 15189 accreditation standards filter supplier eligibility for clinical laboratory contracts. The country's national pharmaceutical regulator enforces conformity assessment for research-use-only products with potential diagnostic utility.
United Kingdom
The Wellcome Trust and Medical Research Council fund epigenetic research consortia at the Francis Crick Institute and Cambridge. GDPR compliance requirements shape data handling protocols for cloud-based bioinformatics infrastructure. London's biomedical research corridor concentrates core facility procurement authority.
China
NMPA regulatory pathways for in vitro diagnostics create compliance thresholds for imported sequencing platforms. The country's national genomics initiatives channel investment toward domestic chromatin analysis capabilities. Research institutes in Beijing and Shanghai expand single-cell resolution workflow adoption.
Japan
PMDA consultation procedures guide clinical-grade assay development for pharmaceutical toxicology programs. METI funding supports next-generation sequencing infrastructure at national research institutes. The Kanto region's biotechnology cluster concentrates chromatin immunoprecipitation service provider capacity.
Chromatin Immunoprecipitation Sequencing Market Competitive Environment
Integrated life science conglomerates and specialized reagent suppliers split the market along workflow control points. The vendor base concentrates around three strategic archetypes: end-to-end platform providers, consumable-focused kit manufacturers, and sequencing instrument specialists. Dominant competitive moves include portfolio diversification across the research-to-clinical value chain and strategic partnerships to anchor supply relationships with academic core facilities.
Within the integrated platform tier, Thermo Fisher Scientific Inc. and Illumina Inc. exemplify contrasting approaches to workflow capture. Qiagen N.V. occupies a position among specialized chromatin preparation suppliers competing through third-party sequencing integration. These three companies represent the primary competitive anchors shaping procurement patterns across academic and pharmaceutical end-user channels.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Illumina Inc. |
| Bio-Rad Laboratories Inc. |
| Agilent Technologies Inc. |
| Abcam plc |
| Bio-Techne Corp. |
| Qiagen N.V. |
| PerkinElmer Inc. |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific air freight corridors connecting reagent manufacturing hubs in Germany and Massachusetts to sequencing core facilities in California and Texas impose cost volatility that amplifies pricing power for domestic kit suppliers while compressing margins on imported chromatin preparation consumables. This logistics tension concentrates procurement authority among consolidated academic consortia capable of negotiating volume commitments that offset freight exposure.
Pricing Analysis
The customization-premium spread between configured-to-order antibody validation services and standard off-the-shelf chromatin preparation kits spans three performance tiers anchored by certification grade and batch documentation depth. Academic core facilities at Stanford and Johns Hopkins exhibit highest price sensitivity due to NIH grant budget constraints, while pharmaceutical toxicology programs at Merck and Bristol Myers Squibb absorb premium pricing for regulatory-grade reproducibility documentation. Cost compression in standard reagent tiers is intensifying because single-source antibody suppliers face competitive displacement from emerging recombinant validation platforms.
Supply Chain Analysis
Supplier-financing facilities extended by Illumina and Thermo Fisher Scientific to academic core facilities with 90-120 day payment terms are displacing traditional distributor credit lines and cementing direct procurement relationships. Chromatin immunoprecipitation reagent manufacturing concentrates in the United States, Germany, and China, with magnetic bead production drawing from rare earth processing facilities in Inner Mongolia and resin chemistry supply chains anchored in the Rhine-Ruhr industrial corridor. Single-source dependency on Illumina sequencing instruments creates tariff-exposure vulnerability for European service providers importing NovaSeq platforms. Distribution runs through direct-to-laboratory e-commerce portals that bypass multi-tier distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioinformatics expertise scarcity constrains market expansion as peak-calling algorithm selection and false discovery rate control demand computational biology training unavailable at most core facilities. This capability gap separates elite genomics centers from peripheral adopters unable to extract full value from chromatin immunoprecipitation sequencing investments.
For Market Incumbents: Entrench workflow control by backward integration into recombinant antibody production to eliminate batch-to-batch variability that generates irreproducible binding site calls. Anchor supply relationships with consolidated purchasing consortia at the University of California system and Texas Medical Center through dedicated technical field support teams. Capacity addition in microfluidic chromatin shearing instrumentation at Massachusetts manufacturing facilities will preempt emerging single-cell resolution competitors. For New Entrants and Emerging Players: Clinical diagnostic laboratories in Germany and France represent geographic underpenetration where ISO 15189 accreditation requirements filter incumbent eligibility and create procurement delays pending regulatory clarity. Target hospital system contracts in Heidelberg and Munich where conformity assessment burdens on research-use-only products have stalled established supplier negotiations. Deploy cloud-based bioinformatics infrastructure as the go-to-market anchor to bypass computational expertise scarcity at smaller core facilities. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates seeking to divest non-core chromatin preparation kit portfolios amid R&D prioritization shifts toward gene editing platforms. Long-term viability centers on regulatory-grade documentation capabilities that unlock pharmaceutical toxicology program contracts with premium margin structures. Watch FDA breakthrough device designation pathways for epigenetic biomarker assays as the inflection signal indicating clinical translation velocity acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Single-Cell Resolution Platform Launch | Droplet-based microfluidic integration enables cell-type-specific regulatory mapping at cancer research institutes. |
| Regulatory-Grade Kit Certification | ISO 15189 accreditation unlocks hospital and reference laboratory contracts in Germany and France. |
| Cloud Bioinformatics Partnership | Broad Institute and EBI distributed computing infrastructure lowers computational barriers for distributed research groups. |
| Direct-to-Laboratory Distribution Expansion | E-commerce portals for reagent procurement bypass distributor markups and reduce order fulfillment friction. |
| Recombinant Antibody Production Integration | In-house validation eliminates batch-to-batch variability generating irreproducible binding site calls. |
Study Parameters
The analysis maps chromatin preparation reagents, next-generation sequencing platforms, bioinformatics services, and antibody validation workflows, each validated through primary interviews with core facility directors, pharmaceutical toxicology program leads, regulatory affairs specialists at kit manufacturers, and NIH program officers. Secondary validation drew from FDA laboratory-developed test guidance documents, EMA in vitro diagnostic regulation filings, ClinicalTrials.gov epigenetic biomarker study registrations, and ISO 15189 accreditation databases. Bottom-up segment sizing triangulated against top-down funding flow analysis from NIH extramural budgets and Wellcome Trust research council allocations.
The assumption-set held fixed NIH funding continuity and Illumina instrument oligopoly structure while varying single-cell resolution adoption velocity and EU regulatory enforcement intensity across the projection horizon. Segmentation dimensions modeled include product type, technology platform, end-user channel, and application area with particular attention to clinical diagnostic translation pathways. CAGRs were derived from logistic diffusion curves fitted to technology adoption patterns in adjacent genomics markets, with inputs from cloud computing cost decline trajectories and antibody manufacturing yield improvement curves.
Practitioners should monitor NIH budget appropriation cycles, EU In Vitro Diagnostic Regulation enforcement delays, and FDA breakthrough device designation grant rates for early signals of forecast deviation. Macroeconomic contraction affecting academic endowment returns, regulatory restriction on research-use-only product clinical utility claims, or technological disruption from proximity ligation alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
Global Patient Derived Xenograft Models Market
Medical Research
Asia-Pacific Computer-Aided Drug Discovery Market
Medical Research
PDX Models Market
Medical Research
Organoids and Spheroids Market
Medical Research
Global Human Liver Models Market
Medical Research
FFPE Tissue Samples Market
Medical Research
Medical Device Contract Research Organization Market
Medical Research
Mice Model Technologies Market
Medical Research
Global Mice Model Market
Medical Research
Epigenomics Market
Medical Research
Placenta Market
Medical Research
Global in Vitro Lung Model Market
Medical Research
Malaria Vaccine Market
Medical Research
Europe Induced Pluripotent Stem Cells (Ipscs) Market
Medical Research
Methicillin-Resistant Staphylococcus Aureus (MRSA) Drugs Market
Medical Research
Lab Automation in Drug Discovery Market