
 Europe AMH Market | 2026-2036
Europe AMH Market Size, Share, and Industry Trends Forecast 2026-2036
Europe AMH Market Foresight
Modular assay platform configurations are restructuring procurement patterns across European fertility clinics and reference laboratories. SSI Schaefer AG leverages its logistics automation expertise to support diagnostic supply chain integration for AMH test distribution. TGW Logistics Group GmbH anchors cold-chain handling systems that preserve sample integrity from collection through laboratory processing. Daifuku Co. Ltd competes on automated storage and retrieval systems tailored to high-throughput diagnostic environments.
Anti-Müllerian hormone (AMH) testing measures a glycoprotein dimer of 140 kDa produced by granulosa cells in ovarian follicles, with serum assays typically detecting concentrations between 0.01 and 23 ng/mL to assess ovarian reserve. The technology dimension spans ELISA, RIA, LIA, and PCR methods, with chemiluminescence immunoassay platforms capturing the dominant share of routine clinical volume due to throughput advantages and standardization. Among applications, infertility assessment occupies the established revenue base while cancer-related AMH monitoring represents the fastest-expanding use case as oncofertility protocols gain protocol adoption across European university hospitals.
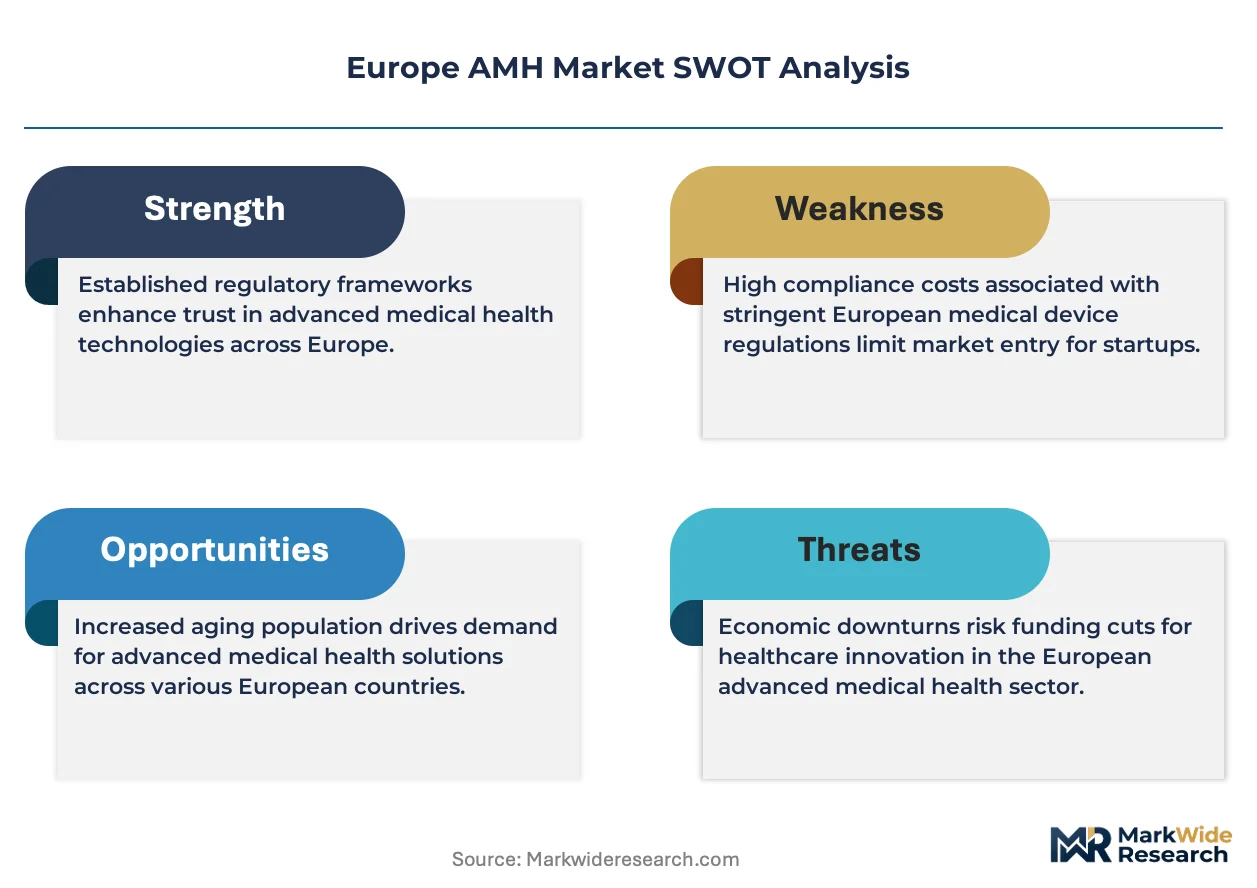
The European Medicines Agency (EMA) and the In Vitro Diagnostic Regulation (IVDR) framework under the European Commission are reshaping assay validation requirements and post-market surveillance obligations for AMH test manufacturers. CE marking transitions under IVDR Class C designation are extending compliance timelines and elevating clinical evidence standards for hormone diagnostic kits. Stakeholders must monitor notified body capacity constraints and evolving common specifications that will determine market access speed for next-generation AMH assays.
Market Dynamics
The IVDR recalibration is compressing compliance timelines and elevating clinical evidence standards for hormone diagnostic kits across European laboratory networks. This regulatory pressure is restructuring manufacturer-notified body relationships and reshaping competitive positioning among assay platform suppliers.
Growth Catalysts
- EU In Vitro Diagnostic Regulation:The IVDR framework mandates stricter post-market surveillance and clinical validation, creating pull-through demand for next-generation assay platforms that meet elevated evidence standards.
- Oncofertility protocols:European university hospitals are integrating AMH monitoring into cancer treatment pathways, expanding testing volumes beyond traditional infertility assessments.
- Chemiluminescence immunoassay platforms:Diagnostic laboratories in Germany and France are consolidating procurement around high-throughput systems that standardize ovarian reserve testing workflows.
Market Restraints
- Notified body capacity constraints:The limited pool of IVDR-designated conformity assessment bodies is extending CE marking timelines and delaying market access for new assay entrants.
- Reagent supply concentration:Critical antibody and conjugate inputs for AMH assays originate from a narrow supplier base, exposing manufacturers to input cost volatility and single-source risk.
- Assay harmonization gaps:Inter-method variability between ELISA, RIA, and chemiluminescence platforms limits result comparability across European reference laboratories.
Strategic Opportunities
- Point-of-care expansion:Underpenetrated fertility clinic networks in Spain and Italy present white space for decentralized AMH testing outside centralized laboratory hubs.
- Digital pathology integration:Convergence of automated immunoassay systems with laboratory information management platforms enables real-time result transmission and remote consultation workflows.
- CSRD alignment:The EU Corporate Sustainability Reporting Directive creates procurement preference for diagnostic suppliers with documented environmental product declarations and circular economy protocols.
Industry Challenges
- IVDR technical documentation:Manufacturers face compressed timelines to assemble performance evaluation reports and common specification compliance files for Class C device reclassification.
- Laboratory integration complexity:Assay platforms must interface with legacy middleware and electronic medical record systems across heterogeneous hospital IT environments.
- Specialized field service capacity:The shortage of trained instrumentation engineers capable of maintaining automated diagnostic systems is extending service response times in peripheral markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe AMH Market |
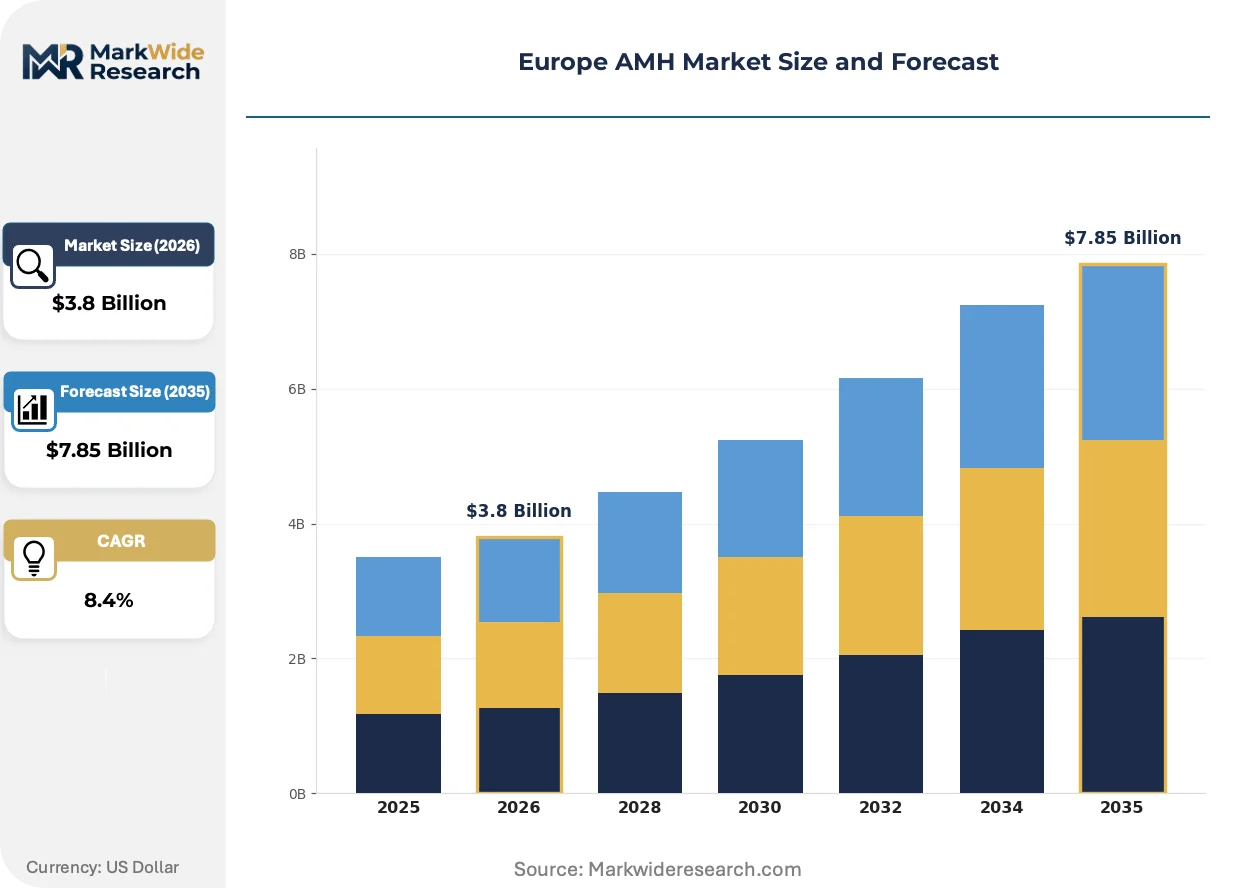
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serum, Plasma, Whole Blood, Dried Blood Spot Technology: ELISA, RIA, LIA, PCR End User: Diagnostic Laboratories, Hospitals, Research Institutes, Academic Institutions Application: Infertility, Endocrine Disorders, Hormonal Imbalance, Cancer |
| Companies Covered | Viastore Systems GmbH, Murata Machinery Ltd, Vanderlande Industries BV, BEUMER Group GmbH & Co. KG, KUKA AG, SSI Schaefer AG, TGW Logistics Group GmbH, Daifuku Co. Ltd, Kardex Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe AMH Market Shifts & Advancements
Automated platform architectures are absorbing manual workflow steps and compressing turnaround times for ovarian reserve assessment. Three developments are restructuring how European laboratories procure, operate, and validate AMH testing infrastructure.
Chemiluminescence immunoassay technology is absorbing market share from manual ELISA methods by embedding calibration traceability and reducing operator-dependent variability. Reference laboratories in France and Germany are prioritizing platforms with onboard quality control and automated sample handling. This technology compression is forcing smaller diagnostic manufacturers to abandon low-throughput product lines or partner with automation specialists.
The IVDR Class C designation is extending clinical evidence requirements for hormone assays beyond the previous IVD Directive thresholds. Manufacturers must now submit performance studies demonstrating diagnostic accuracy across intended use populations. High-volume AMH test suppliers are responding by consolidating product portfolios and discontinuing niche assay configurations that cannot justify validation costs.
Fertility clinic procurement departments are consolidating vendor relationships around full-service contracts that bundle reagents, instrumentation, and maintenance. This purchasing concentration is displacing transactional reagent supply agreements in favor of multi-year partnerships with predictable per-test economics. The shift is most visible in German hospital networks, where central purchasing cooperatives negotiate standardized terms across affiliated fertility centers.
Europe AMH Market Segmentation
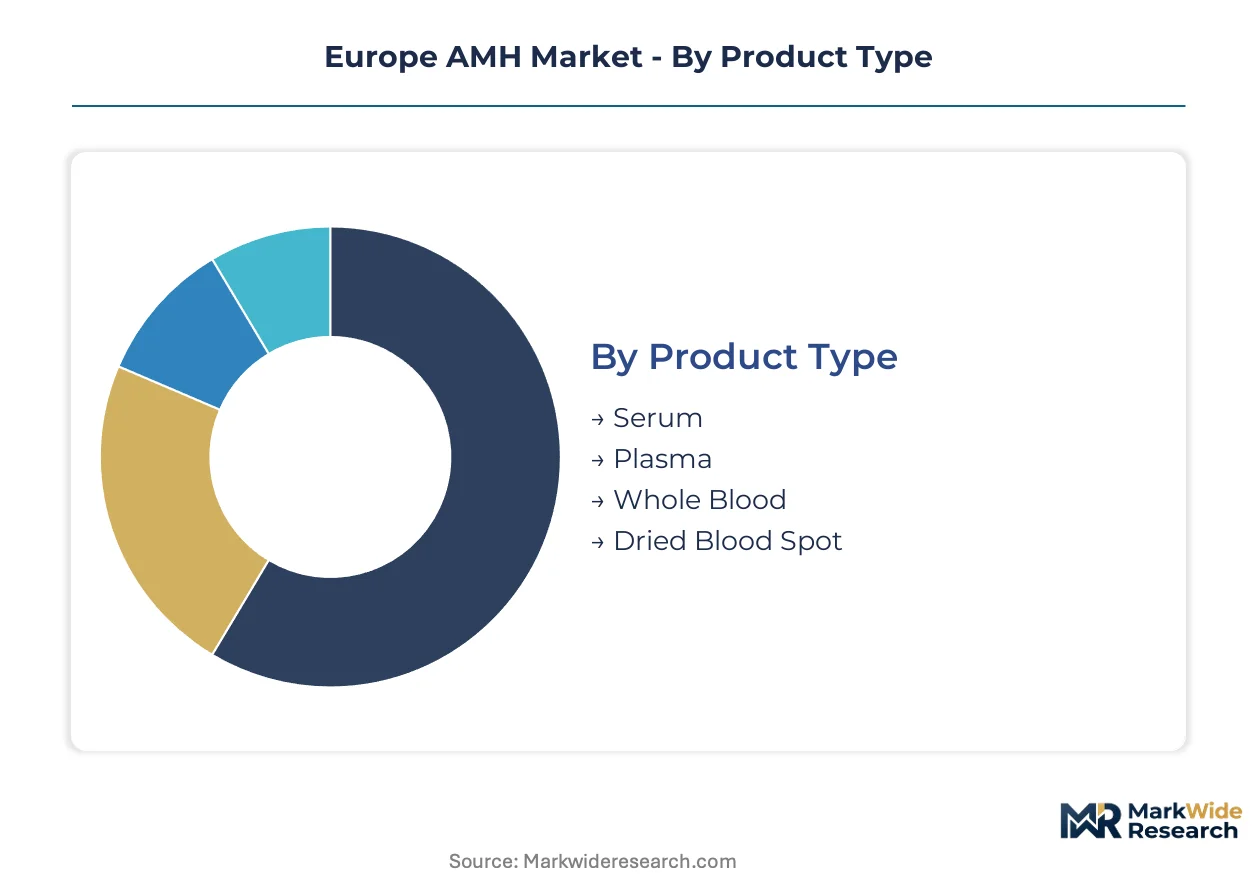
Segmentation in the Europe AMH Market reveals how specimen type, detection methodology, and care setting interact to determine procurement priorities. Laboratories align platform investments with specific clinical workflows, from high-throughput hospital laboratories to decentralized fertility clinic networks.
Product Type:
Specimen compatibility shapes platform architecture decisions across European laboratory networks, with automation readiness and stability requirements driving procurement differentiation.
- Serum:The gold standard matrix for AMH quantification offers standardized pre-analytical handling and established reference intervals across European reference laboratories. German and French hospital networks prioritize serum-based workflows for their compatibility with automated chemiluminescence platforms and established quality control frameworks.
- Plasma:Anticoagulant-dependent AMH stability variations require laboratory-specific validation, yet plasma appeals to networks seeking reduced centrifugation steps and faster turnaround times. Italian fertility clinics are adopting plasma protocols to support same-day consultation workflows where rapid ovarian reserve assessment informs immediate treatment decisions.
- Whole Blood:Point-of-care fertility assessments in Spain and Portugal leverage whole blood collection to eliminate processing delays, though assay sensitivity constraints limit deployment to qualitative screening applications.
- Dried Blood Spot:Remote specimen collection enables home-based AMH testing for oncofertility preservation programs, with Dutch and Belgian laboratories piloting postal sampling to extend monitoring access for patients undergoing gonadotoxic chemotherapy.
Mature deployment sits with serum. Newer deployment is concentrated in dried blood spot.
Technology:
Detection chemistry determines throughput capacity, sensitivity thresholds, and regulatory validation burden for AMH assay manufacturers navigating IVDR compliance.
- ELISA:Enzyme-linked immunosorbent assay platforms deliver cost-effective batch processing for mid-volume laboratories, with open-system configurations allowing reagent flexibility. Research institutes across Scandinavia retain ELISA infrastructure for protocol development and assay comparison studies where method harmonization remains unresolved.
- RIA:Radioimmunoassay methods persist in legacy installations at academic medical centers with established reference laboratory functions, though radioactive waste handling requirements and declining reagent availability are accelerating replacement timelines.
- LIA:Luminescence immunoassay technology captures expanding share in automated platforms, embedding magnetic particle separation and direct chemiluminescence detection to compress assay times below 30 minutes per sample.
- PCR:Polymerase chain reaction approaches target AMH receptor gene expression profiling in oncology research applications, with university hospitals in Switzerland and Austria deploying PCR-based panels to investigate granulosa cell tumor pathology.
Platform consolidation favors LIA for routine clinical volume. PCR commands premium positioning in research settings.
End User:
Procurement authority and testing volume concentration determine pricing leverage and service contract structure across European AMH testing infrastructure.
- Diagnostic Laboratories:Centralized reference networks in Germany and France negotiate multi-year reagent-instrument bundles, leveraging high-throughput commitments to secure preferential per-test economics and dedicated field engineering support.
- Hospitals:University hospital fertility centers integrate AMH testing within comprehensive reproductive endocrinology workflows, requiring bidirectional electronic medical record connectivity and STAT processing capabilities for urgent pre-surgical assessments.
- Research Institutes:Method validation studies and biomarker discovery programs demand assay platforms with open architectures and raw data export functionality, purchasing decisions prioritize analytical flexibility over turnaround speed.
- Academic Institutions:Training laboratories and clinical trial coordinating centers require cost-effective platforms with documented traceability to international reference preparations, often selecting ELISA configurations for educational deployment.
Diagnostic laboratories anchor commercial revenue. Hospital expansion is accelerating most quickly in Southern Europe.
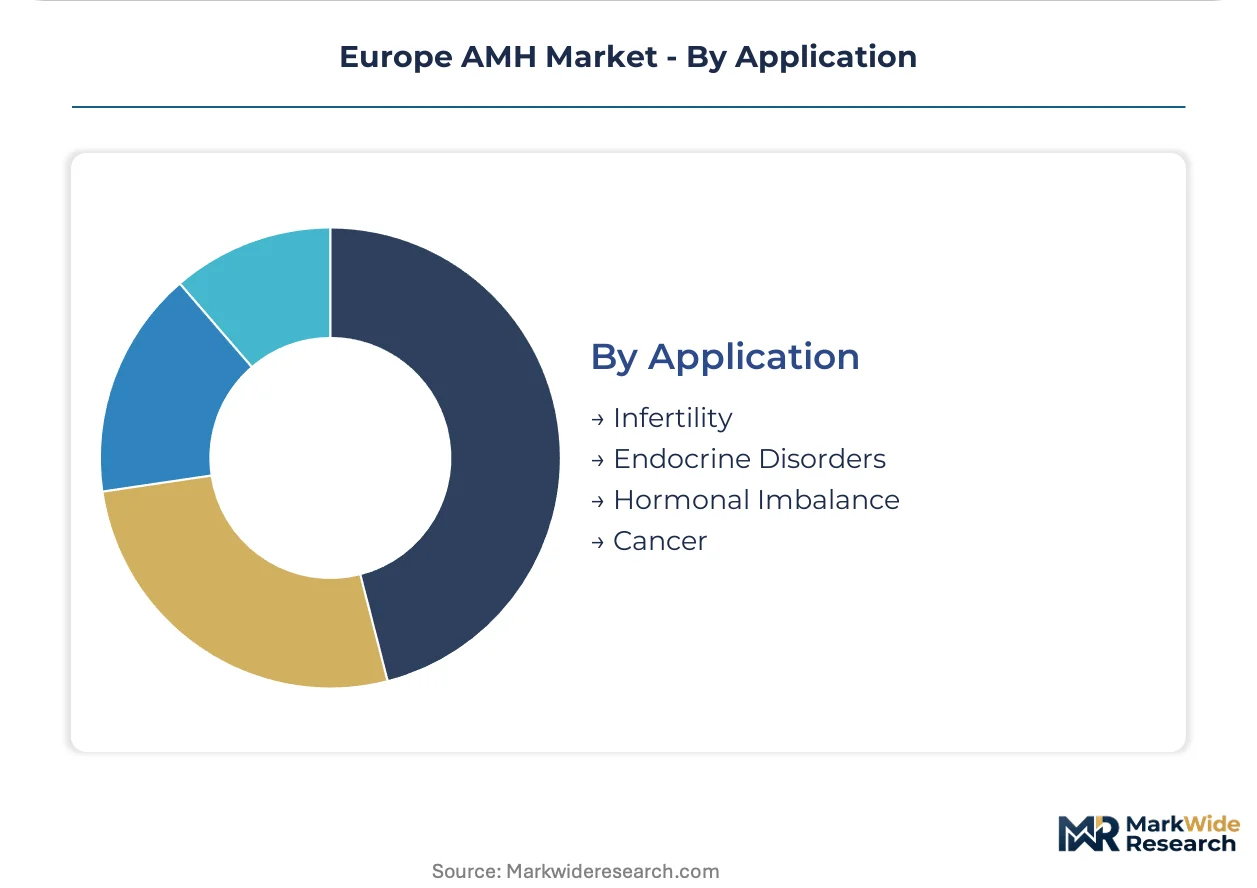
Application:
Clinical indication determines reimbursement coding, testing frequency, and patient population access criteria across European healthcare systems.
- Infertility:Ovarian reserve assessment for assisted reproductive technology candidacy and stimulation protocol selection represents the established revenue foundation, with German statutory health insurance covering AMH testing prior to IVF initiation.
- Endocrine Disorders:Polycystic ovary syndrome diagnostic workups and premature ovarian insufficiency monitoring drive repeat testing volumes in specialized gynecological endocrinology practices.
- Hormonal Imbalance:AMH serves as a granulosa cell function marker in amenorrhea differential diagnosis, though limited specificity constrains standalone clinical utility without complementary hormonal panels.
- Cancer:Oncofertility protocols for gonadotoxic therapy monitoring represent the steepest expansion trajectory, with French and British university hospitals mandating pre-treatment baseline and post-therapy recovery assessments for adolescent and young adult cancer patients.
Infertility assessment commands installed base concentration. Cancer-related monitoring is gaining share fastest among emerging applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of AMH diagnostic platforms concentrates in Germany and Switzerland, while consumption spreads across fertility clinic networks from Scandinavia to Southern Europe. This geographic split shapes how manufacturers configure logistics and service infrastructure.
Germany
Bavarian and North Rhine-Westphalian diagnostic manufacturers anchor European AMH assay production, supplying chemiluminescence platforms to domestic hospital networks. The BfArM and notified body TÜV SÜD enforce IVDR compliance timelines that compress product launch windows. Frankfurt and Munich laboratory clusters negotiate multi-year reagent bundles that standardize testing protocols across university hospital fertility centers.
France
Paris and Lyon metropolitan fertility clinics drive demand for high-throughput ovarian reserve assessment ahead of IVF protocol selection. ANSM oversight of Class C IVD devices elevates clinical evidence requirements for AMH test kits entering the market. The Île-de-France region hosts reference laboratories that validate assay harmonization across the national oncofertility monitoring network.
United Kingdom
London and Manchester academic medical centers integrate AMH testing into adolescent cancer survivor fertility preservation pathways. The MHRA post-Brexit regulatory framework maintains alignment with IVDR standards while operating separate conformity assessment procedures. Cambridge research clusters develop dried blood spot collection methods for remote oncofertility monitoring.
Italy
Milan and Rome fertility clinics adopt plasma-based AMH workflows to compress consultation-to-result turnaround times. The Italian Medicines Agency AIFA oversees reimbursement coding for ovarian reserve testing within assisted reproduction benefit packages. Northern Italian diagnostic distributors build cold-chain logistics networks reaching peripheral clinic locations in Sicily and Calabria.
Netherlands
Amsterdam and Rotterdam university hospitals pilot postal dried blood spot programs for chemotherapy patients requiring remote AMH monitoring. The Dutch Health and Youth Care Inspectorate enforces quality standards for home-collection specimen integrity. Eindhoven automation specialists supply robotic sample handling systems to Benelux reference laboratory networks.
Europe AMH Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across European AMH diagnostic infrastructure. Tier-one automation suppliers leverage multi-product portfolios to secure full-service contracts with centralized laboratory networks. Three archetypes dominate: integrated logistics-automation conglomerates, diagnostic-platform pure-plays, and component-specialist sub-tier suppliers. Consolidation through strategic partnerships and technology licensing agreements is restructuring vendor relationships with fertility clinic procurement departments.
Among German-based logistics automation specialists, SSI Schaefer AG and BEUMER Group GmbH & Co. KG occupy positions within the integrated systems tier, while TGW Logistics Group GmbH represents the cold-chain infrastructure archetype. Japanese conglomerates Murata Machinery Ltd and Daifuku Co. Ltd exemplify the diversified industrial-automation model extending into diagnostic laboratory environments. These entities anchor competitive positioning around service contract bundling and multi-year maintenance agreements rather than transactional equipment sales.
| Leading Market Players |
|---|
| Viastore Systems GmbH |
| Murata Machinery Ltd |
| Vanderlande Industries BV |
| BEUMER Group GmbH & Co. KG |
| KUKA AG |
| SSI Schaefer AG |
| TGW Logistics Group GmbH |
| Daifuku Co. Ltd |
| Kardex Group |
| Others |
Supply & Pricing Matrix
IVDR-mandated performance study requirements are compressing product launch windows and forcing assay manufacturers to consolidate validation investments into fewer platform configurations, concentrating pricing power among suppliers with established clinical evidence portfolios. German and French laboratory networks exploit this buyer concentration to negotiate multi-year reagent-instrument bundles that lock in per-test economics below standalone procurement levels.
Pricing Analysis
Cost-down pressure on mid-volume ELISA platforms accelerates because diagnostic laboratories in Italy and Spain are abandoning batch-processing methods in favor of automated chemiluminescence systems with predictable per-test costing. Pricing stratifies across premium, standard, and economy tiers based on throughput capacity and IVDR certification status. Margin tightening in the economy tier traces to notified body backlogs delaying CE marking for new entrants. Research institutes demonstrate lowest price sensitivity due to grant-funded procurement flexibility.
Supply Chain Analysis
Direct-to-laboratory channels handle high-throughput demand from German and French hospital networks, while distributor-mediated routes serve peripheral fertility clinics in Southern Europe. Critical antibody and conjugate inputs draw from specialized bioreagent suppliers concentrated in Switzerland and the Netherlands. Single-source vulnerability in magnetic particle substrates exposes manufacturers to input disruption. Distribution runs through cold-chain logistics specialists preserving sample integrity from collection through laboratory processing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Notified body capacity constraints prop pricing for IVDR-certified assay platforms by throttling new entrant supply and extending validation timelines for competing products.
For Market Incumbents: Deploy backward integration into antibody production to secure critical reagent supply against single-source concentration risk. Consolidate field service engineering capacity in German and French laboratory clusters to defend maintenance contract renewal rates against emerging automation specialists. IVDR technical documentation requirements favor incumbents with established performance study archives. For New Entrants and Emerging Players: Digital pathology integration partnerships offer a route to bypass capital-intensive instrumentation sales and embed software-layer value in existing laboratory workflows. Target underpenetrated fertility clinic networks in Spain and Portugal with dried blood spot collection systems that eliminate cold-chain infrastructure requirements. Remote monitoring applications for oncofertility patients represent the most penetrable white-space segment. For Investors and Strategic Acquirers: The window for entry favors diagnostic-platform pure-plays with validated IVDR Class C dossiers and established notified body relationships. Long-term viability hinges on consolidation of fragmented reagent supply capabilities into integrated manufacturing footprints. Watch for IVDR designation expansion among conformity assessment bodies as the inflection signal for new entrant supply acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical Documentation Investment | Accelerates market access speed for Class C hormone assay reclassification under EMA oversight. |
| Antibody Production Backward Integration | Reduces input cost volatility from Swiss and Dutch bioreagent supplier concentration. |
| Cold-Chain Logistics Partnership | Preserves sample integrity for Italian and Spanish fertility clinic network expansion. |
| Digital Pathology Platform Integration | Enables real-time result transmission for Dutch and Belgian remote oncofertility monitoring. |
| Dried Blood Spot Collection Pilot | Extends AMH testing access to chemotherapy patients in Netherlands postal sampling programs. |
Research Methodology
Document review covered IVDR guidance documents, EMA common specifications, and notified body designation records, complemented by interviews with diagnostic platform product managers, clinical laboratory directors, fertility clinic procurement officers, and regulatory affairs specialists at IVD manufacturers. Secondary validation drew from EMA public assessment reports, BfArM device registrations, and hospital procurement database extracts. Bottom-up testing volume estimates were triangulated against top-down market value reconstruction across the analysis window.
Historical volume trajectories were cross-referenced against panel input from laboratory network procurement committees to anchor projection assumptions. Segmentation modeling captured specimen type, detection technology, end-user category, and application indication dimensions across the modeling period. CAGRs were derived from logistic adoption curves fitted to technology transition patterns in German and French reference laboratories. Forecast inputs included IVDR transition timeline assumptions and oncofertility protocol adoption rates in university hospital networks.
The model holds under sustained notified body designation expansion and stable antibody supply availability; deviation in regulatory enforcement intensity or bioreagent trade restrictions would shift volume and value trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
India Computer-Aided Drug Discovery Market
Medical Research
Global Human Liver Models Market
Medical Research
Life Science R&D Infrastructure Outsourcing Market
Medical Research
Lab Automation in Drug Discovery Market
Medical Research
Antibody-Mediated Rejection Prevention Market
Medical Research
Global Patient Derived Xenograft Models Market
Medical Research
Placenta Market
Medical Research
Forensic Medicine Market
Medical Research
FFPE Tissue Samples Market
Medical Research
Epigenetics Market
Medical Research
North America Biobanks Market
Medical Research
Organoids and Spheroids Market
Medical Research
AAV Contract Development and Manufacturing Organizations Market
Medical Research
PDX Models Market
Medical Research
Human Osteoblasts Market
Medical Research
Asia-Pacific Computer-Aided Drug Discovery Market