
 Clinical Genomics Market | 2026-2036
Clinical Genomics Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Genomics Market Analysis
Next-generation sequencing chemistry is shifting from short-read dominance toward long-read platforms that reduce variant detection costs in complex genomic regions. Illumina sustains manufacturing scale across high-throughput instrument installed bases. Oxford Nanopore Technologies differentiates through portable real-time sequencing architectures. Foundation Medicine anchors clinical adoption via comprehensive genomic profiling services tied to therapeutic decision support.
Clinical genomics encompasses the laboratory analysis of patient DNA, RNA, and epigenetic markers using technologies with specifications such as read lengths from 150 base pairs to over 1 megabase and throughput exceeding 6 terabases per instrument run, primarily to diagnose disease, guide therapy selection, and assess hereditary risk. Oncology applications command the largest current revenue share due to biomarker-driven therapy pipelines, while rare disease diagnostics represent the fastest-growing application segment as undiagnosed patient programs expand. NGS platforms lead product category investment, though CRISPR-based diagnostic tools are gaining traction in point-of-care infectious disease testing.
The FDA regulates clinical genomic tests as in vitro diagnostics or laboratory-developed tests depending on commercial distribution model, while the EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements on genomic assay manufacturers seeking CE marking. China's NMPA has accelerated review pathways for innovative sequencing instruments under its priority review mechanism. Stakeholders must monitor evolving reimbursement coding for multi-gene panel tests versus whole-genome approaches as payer evidence requirements tighten.
Market Dynamics
The transition from short-read to long-read sequencing platforms is compressing variant detection costs in complex genomic regions, forcing incumbent vendors to defend installed bases while new entrants capture point-of-care infectious disease testing workflows.
Growth Catalysts
- FDA's accelerated approval pathways:The regulator's breakthrough device designation for companion diagnostics is compressing time-to-market for biomarker-driven oncology tests, pulling hospital laboratories toward comprehensive genomic profiling.
- Hereditary disease screening expansion:Undiagnosed patient programs in pediatric hospitals are scaling rare disease diagnostic pipelines, creating demand pull for whole-exome and whole-genome sequencing workflows.
- CRISPR-based diagnostic platforms:The gene-editing chemistry is migrating from research tools into point-of-care infectious disease testing, enabling rapid pathogen identification without centralized laboratory infrastructure.
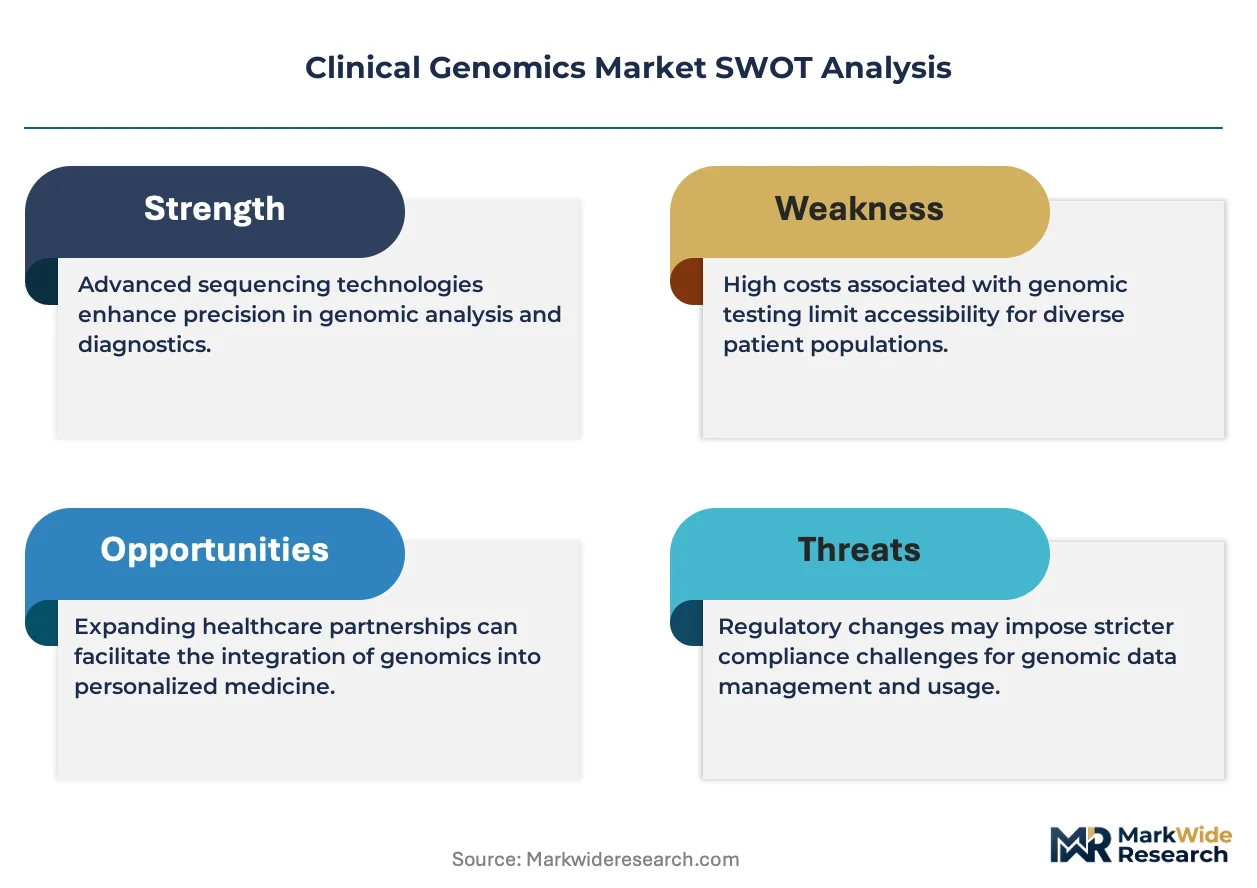
Market Restraints
- Reagent supply concentration:Sequencing consumables production clusters in a handful of contract manufacturers, exposing clinical laboratories to single-source dependency for flow cells and library preparation kits.
- EU In Vitro Diagnostic Regulation compliance costs:The EMA's stricter clinical evidence requirements for CE marking are forcing mid-sized assay developers to abandon European market entry or consolidate through acquisition.
- Bioinformatics bottleneck:Variant interpretation software licensing fees and computational infrastructure requirements are creating structural barriers for community hospitals lacking dedicated informatics staff.
Strategic Opportunities
- Liquid biopsy minimal residual disease monitoring:Circulating tumor DNA testing is expanding from late-stage therapy selection into early recurrence detection, opening white space in adjuvant oncology care.
- Pharmacogenomic testing integration:Payer reimbursement for preemptive genotyping ahead of psychiatric and cardiovascular prescribing is creating tailwinds for retail pharmacy and primary care clinic adoption.
- Epigenetic biomarker commercialization:DNA methylation assays for cancer screening are converging with machine learning classification algorithms, enabling multi-cancer early detection panels without tissue biopsy requirements.
Industry Challenges
- Variant scientist workforce scarcity:Clinical laboratories face acute shortages of board-certified molecular geneticists capable of interpreting rare variant pathogenicity against evolving ACMG guidelines.
- Electronic health record integration complexity:Genomic data structures lack standardized interoperability with Epic and Cerner systems, forcing manual abstraction of pharmacogenomic alerts into prescribing workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Genomics Market |
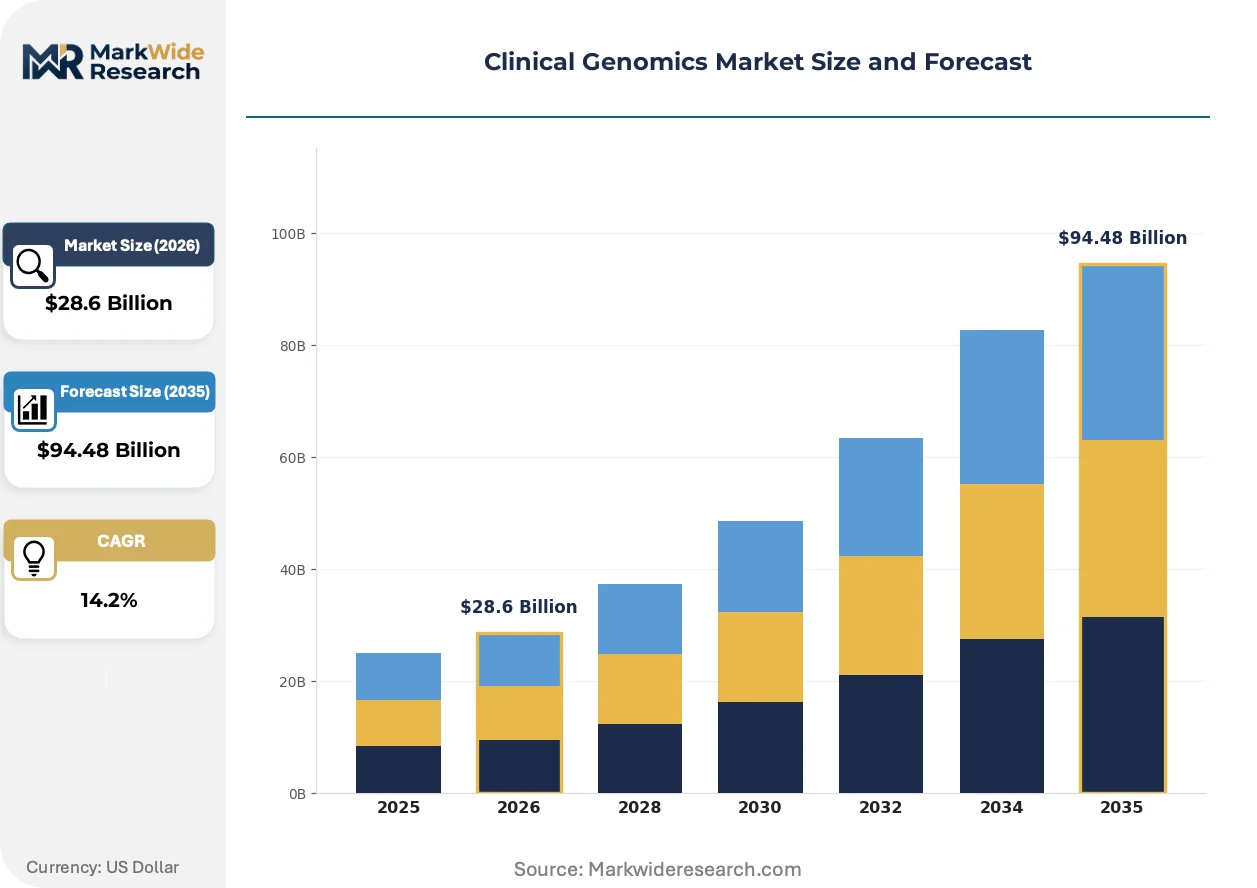
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Sequencers, PCR Machines, Gene Expression Analyzers, NGS Platforms Application: Oncology, Rare Diseases, Neurology, Infectious Diseases Technology: Next-Generation Sequencing, Sanger Sequencing, Microarray, CRISPR End User: Hospitals, Research Laboratories, Academic Institutions, Diagnostic Centers |
| Companies Covered | Tempus AI, Roche, Illumina, Caris Life Sciences, NeoGenomics Laboratories, 10x Genomics, BGI Group, Foundation Medicine, Oxford Nanopore Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Genomics Market Emerging Trajectories
Long-read sequencing chemistry is disrupting the cost-accuracy tradeoff that has governed clinical NGS procurement decisions for a decade, while regulatory frameworks in the United States and European Union accelerate evidence requirements for algorithm-driven diagnostic outputs.
Oxford Nanopore's portable real-time sequencing architecture is expanding into field-deployable infectious disease surveillance and remote clinic oncology workflows. Rural health systems and military medical units are adopting the platform for tuberculosis drug resistance profiling and SARS-CoV-2 variant monitoring where cold-chain logistics fail. The technology is compressing the turnaround time gap between centralized reference laboratories and point-of-care decision-making.
The FDA's oversight of laboratory-developed tests is tightening evidentiary standards for algorithm-based variant classification, particularly for artificial intelligence-assisted somatic mutation calling. Manufacturers must now submit analytical and clinical validation data previously exempt under enforcement discretion policies. High-complexity molecular pathology laboratories in the United States are responding by building in-house bioinformatics pipelines or outsourcing to CLIA-certified cloud platforms.
Hospital procurement committees are unbundling sequencing instrument purchases from multi-year reagent rental agreements, shifting toward capital acquisition with competitive consumables sourcing. Academic medical centers in Germany and the United States are leading this transition, pressuring vendors to separate hardware margins from captive chemistry revenue. The behavioral shift is most visible in oncology departments where test volumes justify in-house library preparation and third-party bioinformatics alternatives.
Clinical Genomics Market Segmentation
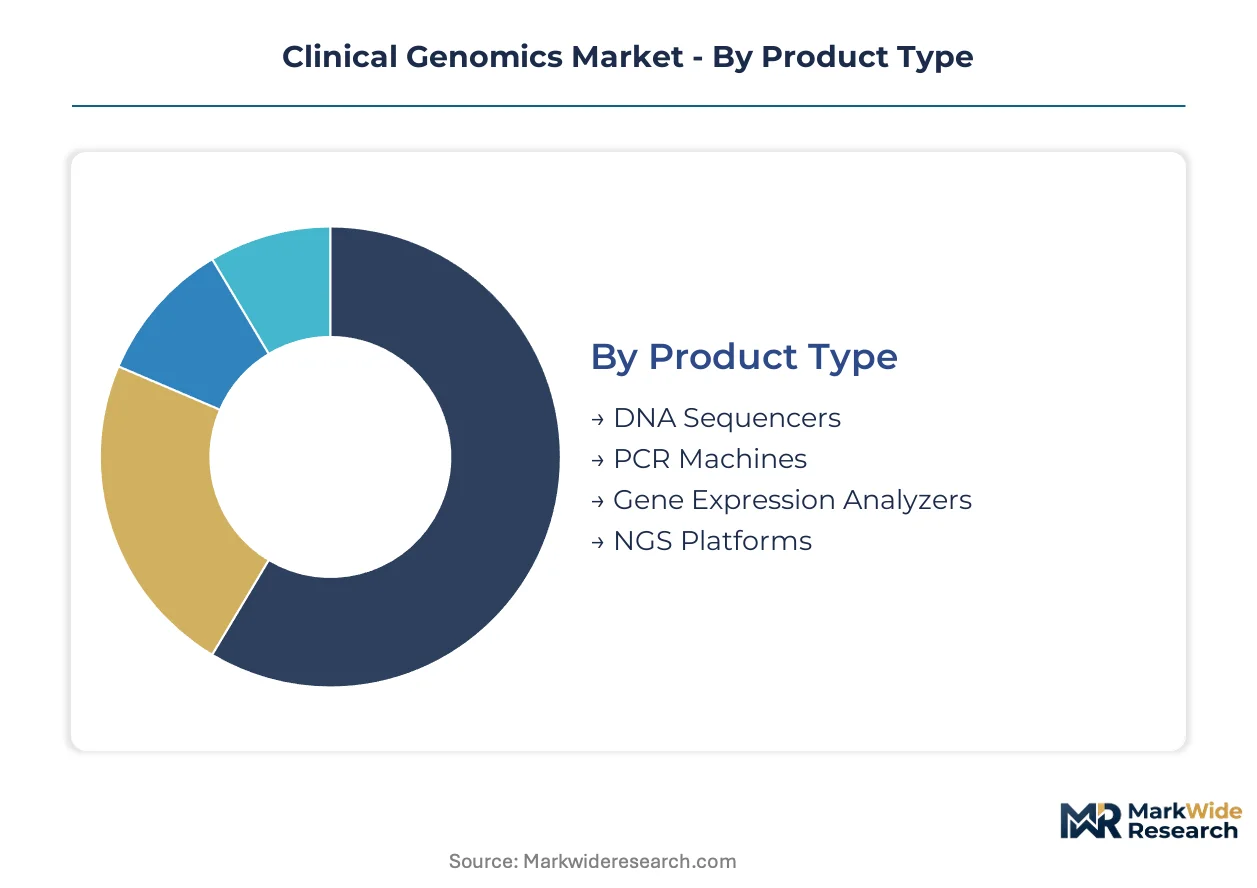
Clinical genomics segmentation reveals how hardware investments, disease-area priorities, and institutional capabilities diverge across the care continuum. Product configurations range from capital-intensive sequencers to portable diagnostic platforms, while application demand concentrates in oncology and rare disease workflows.
Product Type:
Standalone instruments dominate high-throughput reference laboratories, while modular platforms embed into distributed diagnostic networks requiring flexible throughput scaling.
- DNA Sequencers:Capillary and semiconductor-based systems achieve read lengths from 150 base pairs to over 1 megabase. Demand concentrates in United States academic medical centers expanding hereditary cancer screening programs, constrained by reagent supply concentration and cold-chain logistics requirements.
- NGS Platforms:Massively parallel sequencing instruments exceed 6 terabases per run, enabling whole-genome and whole-exome workflows. German hospital procurement committees are unbundling instrument purchases from captive reagent agreements, pressuring vendors toward hardware-only sales models.
- PCR Machines:Thermal cyclers support targeted amplification for companion diagnostic validation.
- Gene Expression Analyzers:Quantitative PCR and digital PCR systems measure transcript abundance for pharmacogenomic applications.
NGS platforms lead volumes today; DNA sequencers are gaining share fastest in point-of-care infectious disease deployments.
Application:
Disease-area segmentation tracks how biomarker-driven therapy pipelines reshape laboratory test menus and reimbursement coding.
- Oncology:Comprehensive genomic profiling identifies actionable mutations across solid tumors and hematologic malignancies. China's NMPA priority review mechanism accelerates approval for companion diagnostics, pulling domestic hospital laboratories toward tumor-agnostic testing panels.
- Rare Diseases:Whole-exome and whole-genome sequencing resolve diagnostic odysseys for pediatric undiagnosed disease programs. United States children's hospitals are scaling trio sequencing workflows, creating demand pull for rapid turnaround contracts with reference laboratories.
- Infectious Diseases:Metagenomic sequencing identifies pathogens in culture-negative sepsis and meningitis cases.
- Neurology:Genetic testing for epilepsy, neurodegenerative conditions, and neuromuscular disorders expands as gene therapy trials mature.
Oncology leads volumes today; rare diseases are climbing the fastest as undiagnosed patient programs scale.
Technology:
Technology segmentation captures the transition from short-read dominance toward long-read architectures and CRISPR-based diagnostic chemistries.
- Next-Generation Sequencing:Short-read platforms maintain installed base advantages in variant detection for single-nucleotide variants and small indels. United States community hospitals lacking dedicated bioinformatics staff face structural barriers from variant interpretation software licensing fees and computational infrastructure requirements.
- CRISPR:Gene-editing chemistry enables rapid pathogen identification without centralized laboratory infrastructure. China's infectious disease surveillance networks are adopting CRISPR-based diagnostics for tuberculosis drug resistance profiling in rural health systems where cold-chain logistics fail.
- Sanger Sequencing:First-generation sequencing remains the gold standard for confirmatory testing and forensic applications.
- Microarray:Genotyping arrays support pharmacogenomic screening and copy number variation detection at lower per-sample cost than sequencing.
Next-generation sequencing leads volumes today; CRISPR is expanding most quickly in point-of-care workflows.
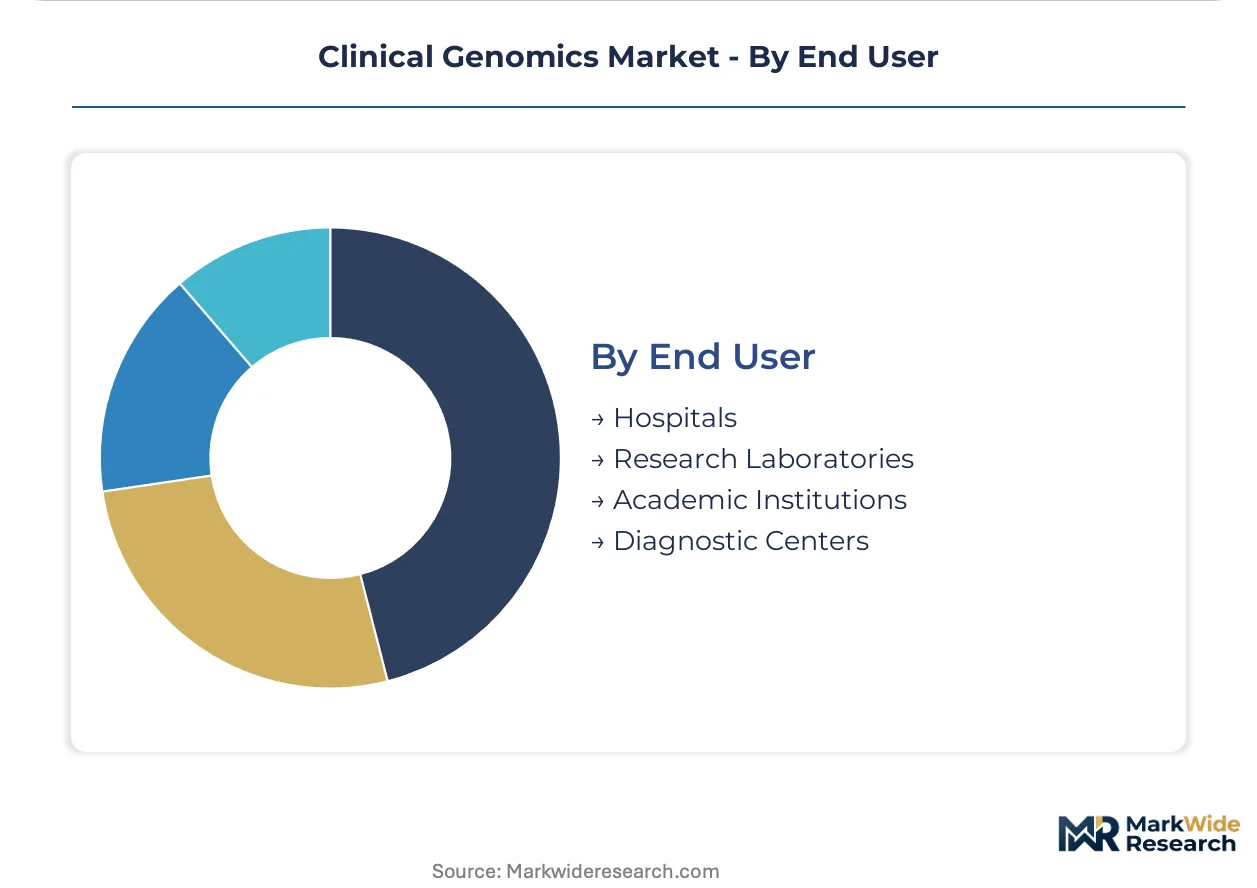
End User:
Institutional segmentation distinguishes between centralized reference capacity and distributed diagnostic access points.
- Hospitals:High-complexity molecular pathology laboratories integrate genomic testing into therapeutic decision support. United States health systems are responding to FDA's tightening oversight of laboratory-developed tests by building in-house bioinformatics pipelines or outsourcing to CLIA-certified cloud platforms.
- Diagnostic Centers:Independent reference laboratories achieve economies of scale in comprehensive genomic profiling. Germany's academic medical centers are leading procurement committee shifts toward capital acquisition with competitive consumables sourcing, separating hardware margins from captive chemistry revenue.
- Research Laboratories:Discovery-focused genomics supports biomarker validation and technology development.
- Academic Institutions:University-affiliated hospitals bridge clinical service and research missions.
Hospitals lead volumes today; diagnostic centers are gaining share fastest as test volumes justify outsourced scale economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Kendall Square anchors the densest concentration of clinical genomics infrastructure, with academic medical centers and venture-backed diagnostics firms clustering within a two-mile radius. Health system reimbursement policies and regulatory frameworks now determine geographic expansion trajectories more than technology access alone.
United States
Academic medical centers in Massachusetts and California are scaling comprehensive genomic profiling for oncology decision support. The FDA's breakthrough device designation for companion diagnostics compresses approval timelines, pulling hospital laboratories toward tumor-agnostic testing panels. The Research Triangle in North Carolina concentrates contract sequencing capacity serving Medicaid expansion states.
China
Domestic hospital laboratories in Beijing and Shanghai are adopting tumor profiling workflows as NMPA priority review accelerates instrument approvals. The national regulator's streamlined pathway for innovative sequencing platforms reduces time-to-market for local manufacturers. Shenzhen's precision medicine industrial park hosts integrated reagent production and bioinformatics development clusters.
Germany
University hospitals in Bavaria and Baden-Württemberg are unbundling sequencer purchases from multi-year reagent agreements. The EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements for CE marking, favoring large reference laboratories with dedicated regulatory affairs staff. Berlin-Brandenburg's health technology cluster concentrates pharmacogenomic testing infrastructure.
United Kingdom
The NHS Genomic Medicine Service is consolidating rare disease diagnostics into regional genomic laboratory hubs across England. Genomics England's 100,000 Genomes Project infrastructure now supports clinical whole-genome sequencing for pediatric undiagnosed disease programs. The Cambridge-Oxford arc anchors commercial spinouts from university research hospitals.
Japan
PMDA accelerated approval pathways for oncology companion diagnostics are expanding hospital-based comprehensive genomic profiling. METI funding for precision medicine infrastructure targets cancer genomic medicine hubs in Tokyo and Osaka. The Kobe biomedical innovation cluster concentrates sequencing instrument distribution and clinical laboratory partnerships.
Clinical Genomics Market Vendor Landscape
Global majors compete with regional champions across instrument manufacturing, reagent supply, and clinical laboratory service delivery. The vendor base stratifies into three tiers: integrated platform manufacturers with captive chemistry ecosystems, independent reference laboratories achieving scale in comprehensive genomic profiling, and emerging point-of-care diagnostic specialists. Dominant competitive moves include procurement committee unbundling of hardware from consumables agreements and strategic partnerships between sequencing platform vendors and cloud-based bioinformatics providers.
Among platform manufacturers, Illumina and Oxford Nanopore Technologies exemplify divergent architectural approaches to clinical sequencing infrastructure. Within the clinical laboratory services tier, Foundation Medicine and Tempus AI occupy positions as comprehensive genomic profiling providers tied to therapeutic decision support. Roche represents the integrated diagnostics conglomerate archetype, spanning reagent manufacturing, instrument platforms, and clinical testing services through subsidiary and partnership structures.
| Leading Market Players |
|---|
| Tempus AI |
| Roche |
| Illumina |
| Caris Life Sciences |
| NeoGenomics Laboratories |
| 10x Genomics |
| BGI Group |
| Foundation Medicine |
| Oxford Nanopore Technologies |
| Others |
Supply Flow & Price Mechanics
Long-read sequencing chemistry migration is simultaneously compressing per-base variant detection costs and redistributing manufacturing leverage from incumbent short-read platform vendors toward modular reagent suppliers and third-party bioinformatics providers.
Pricing Analysis
Input-cost pass-through from flow cell manufacturing and library preparation chemistry dominates pricing structures across clinical genomics, with three-tier pricing stratifying across premium CE-marked diagnostic kits, standard research-grade reagents, and economy-scale bulk consumables for high-throughput reference laboratories. Price differentiation hinges on FDA breakthrough device designation tier and ISO 13485 certification status, with German hospital procurement committees extracting steeper discounts through unbundled hardware acquisitions. Cost compression in standard-tier sequencing consumables is intensifying because Chinese domestic manufacturers are scaling NMPA-approved reagent production. Community hospitals lacking dedicated informatics staff exhibit highest price sensitivity, while academic medical centers with captive bioinformatics pipelines absorb premium pricing for comprehensive genomic profiling services.
Supply Chain Analysis
CE marking and FDA 510(k) qualification gating concentrates flow cell and sequencing reagent manufacturing among United States, German, and Chinese production facilities, with contract manufacturers in Shenzhen's precision medicine industrial park expanding capacity for NMPA priority review pathways. Raw material dependencies center on synthetic oligonucleotides, semiconductor wafers for sensor fabrication, and high-purity biochemical reagents for library preparation chemistry. Single-source vulnerability persists for specialized polymerase enzymes and modified nucleotide triphosphates, with tariff exposure escalating for Chinese-manufactured consumables entering United States hospital supply chains. Distribution runs through direct vendor-to-laboratory contracts for high-throughput instruments, while consumables flow via group purchasing organizations and specialized life science distributors serving mid-sized diagnostic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical genomics presents a geographic-arbitrage play between United States FDA enforcement discretion tightening and China's NMPA priority review acceleration, with cost differentials of 30-40% on comparable sequencing instrument approvals creating manufacturing relocation incentives.
For Market Incumbents: Acquire cloud-based bioinformatics pipeline capabilities to offset unbundling pressure from hospital procurement committees separating hardware from consumables agreements. Defend installed base positions through backward integration into flow cell manufacturing, reducing single-source dependency exposure. Prioritize CLIA-certified variant interpretation software development to address the bioinformatics bottleneck threatening community hospital retention.
For New Entrants and Emerging Players: Enter via point-of-care infectious disease testing workflows where Oxford Nanopore's portable architecture has validated field-deployable sequencing demand. Target rural health systems and military medical units lacking cold-chain logistics infrastructure for tuberculosis drug resistance profiling. Pursue strategic partnerships with Chinese infectious disease surveillance networks as the most penetrable regulatory pathway for CRISPR-based diagnostic commercialization.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized assay developers facing EU In Vitro Diagnostic Regulation compliance cost barriers, creating distressed acquisition opportunities for large reference laboratories with dedicated regulatory affairs staff. Long-term viability hinges on pharmacogenomic testing integration into retail pharmacy and primary care clinic workflows. Watch for FDA algorithm-based variant classification guidance tightening as the inflection indicator for bioinformatics platform consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Bioinformatics Platform Acquisition | Addresses FDA's tightening oversight of algorithm-based variant classification for hospital laboratories. |
| NMPA Priority Review Pathway Navigation | Accelerates time-to-market for domestic Chinese sequencing instrument manufacturers against Western incumbents. |
| Hospital Procurement Committee Unbundling | Separates hardware margins from captive chemistry revenue, pressuring vendor pricing power. |
| CLIA-Certified Variant Pipeline Development | Resolves bioinformatics bottleneck constraining community hospital comprehensive genomic profiling adoption. |
| Pharmacogenomic Reimbursement Strategy | Captures payer tailwinds for preemptive genotyping ahead of psychiatric and cardiovascular prescribing. |
Methodological Framework
Bottom-up hospital and diagnostic center procurement modeling reconciled against top-down sequencing instrument shipment tracking forms the analytical core of this study. Primary interviews with molecular pathology laboratory directors, hospital purchasing committee members, regulatory affairs specialists at assay developers, and bioinformatics pipeline architects combined with secondary validation against FDA 510(k) filings, EMA CE marking databases, NMPA priority review announcements, and CMS reimbursement coding updates. Triangulation across these sources ensures segmentation outputs reflect actual installed base dynamics rather than vendor-reported shipment figures alone.
Historical trendline analysis of NGS platform adoption curves and companion diagnostic approval velocities informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, application area, technology architecture, and end-user institutional category, with regional regulatory cluster and reimbursement policy stance as cross-cutting variables. CAGRs derive from fitted growth curves adjusted for EU In Vitro Diagnostic Regulation implementation friction and China's domestic substitution incentives. Forecast inputs incorporate hereditary disease screening program expansion rates and liquid biopsy minimal residual disease monitoring pipeline maturation.
Inputs from FDA breakthrough device designation announcements and NMPA priority review disclosures were available through the study window; gaps in real-time hospital procurement contract terms introduce uncertainty bands around instrument placement forecasts. Projections reflect assumptions regarding sustained payer reimbursement for multi-gene panel tests and stable reagent supply chain configuration. A model refresh is warranted upon material change in FDA laboratory-developed test enforcement discretion policy or EU In Vitro Diagnostic Regulation transitional period extensions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
Organoids and Spheroids Market
Medical Research
Asia-Pacific Computer-Aided Drug Discovery Market
Medical Research
Global Humanized Mouse Model Market
Medical Research
Malaria Vaccine Market
Medical Research
Global Patient Derived Xenograft Models Market
Medical Research
Mice Model Technologies Market
Medical Research
Epigenomics Market
Medical Research
Life Science R&D Infrastructure Outsourcing Market
Medical Research
Global in Vitro Lung Model Market
Medical Research
Europe Induced Pluripotent Stem Cells (Ipscs) Market
Medical Research
FFPE Tissue Samples Market
Medical Research
Chromatin Immunoprecipitation Sequencing Market
Medical Research
Global Mice Model Market
Medical Research
India Computer-Aided Drug Discovery Market
Medical Research
Medical Device Contract Research Organization Market
Medical Research
Europe AMH Market