
 Health Economics and Outcomes Research (HEOR) Services Market | 2026-2036
Health Economics and Outcomes Research (HEOR) Services Market Size, Share, and Industry Trends Forecast 2026-2036
Health Economics and Outcomes Research (HEOR) Services Market Analysis
Real-world evidence is repositioning traditional randomized controlled trial data as the primary currency for payer negotiations. IQVIA leverages its integrated data assets to anchor large-scale outcomes studies across multiple therapeutic areas. Optum sustains competitive differentiation through its access to UnitedHealth Group's claims databases and payer relationships. ICON PLC specializes in health economic modeling for rare disease therapies where trial data remains scarce.
Health Economics and Outcomes Research services encompass systematic evaluation of clinical efficacy, cost-effectiveness, and patient-reported outcomes to inform healthcare resource allocation and reimbursement decisions. These services employ statistical modeling, meta-analysis, and observational study designs to generate evidence that meets payer and regulator standards for formulary inclusion and pricing agreements. Cost-effectiveness analysis dominates service revenue due to mandatory requirements for national health technology assessment bodies across developed markets. Patient-reported outcomes represent the fastest-expanding service category as regulators and payers increasingly require patient-centric evidence for coverage decisions. Modeling services capture concentrated margin pools where proprietary simulation platforms create defensible intellectual property.
FDA's emphasis on real-world evidence under the 21st Century Cures Act framework shapes demand for HEOR services that supplement traditional clinical trial endpoints. EMA's parallel scientific advice procedures and HTA engagement initiatives create structured pathways for manufacturers to align evidence generation with European payer expectations. Payers in Germany through the G-BA and in England through NICE maintain rigorous cost-per-quality-adjusted-life-year thresholds that necessitate sophisticated economic modeling. Stakeholders must monitor evolving divergence between FDA evidentiary standards and European HTA body requirements when designing cross-border evidence strategies.
Market Dynamics
The EU Health Technology Assessment regulation is forcing pharmaceutical manufacturers to harmonize evidence packages across member states, compressing timelines for economic modeling and real-world evidence generation.
Growth Catalysts
- EMA Parallel Scientific Advice:The European Medicines Agency's structured engagement pathways enable manufacturers to align clinical trial designs with HTA body expectations before study initiation.
- United States:Complex reimbursement negotiations between manufacturers and pharmacy benefit managers create sustained demand for sophisticated cost-effectiveness analyses and budget impact models.
- Real-world evidence platforms:Distributed data networks and claims database integrations are reducing study timelines from years to months for observational outcomes research.
Market Restraints
- Specialized talent scarcity:Health economists with dual expertise in biostatistics and payer policy command premium compensation, constraining service expansion.
- Data access fragmentation:European electronic health record systems remain siloed across national borders, limiting cross-border patient cohort construction.
- Methodological divergence:FDA evidentiary standards under the 21st Century Cures Act framework increasingly diverge from European HTA body requirements, forcing redundant study designs.
Strategic Opportunities
- Japan:PMDA's expanding use of real-world evidence for post-market surveillance creates openings for Western HEOR providers with established data partnerships.
- Cell and gene therapy:Single-administration curative treatments require novel value demonstration frameworks including outcomes-based agreements and annuity payment models.
- Patient-reported outcomes:Regulatory mandates from EMA and FDA for patient-centric evidence are accelerating dedicated PRO instrument development and validation services.
Industry Challenges
- Health informatics expertise:Shortages in FHIR-standard data interoperability specialists delay real-world evidence platform deployments.
- Model transparency requirements:NICE and G-BA demands for open-source economic models threaten proprietary simulation platform differentiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Health Economics and Outcomes Research (HEOR) Services Market |
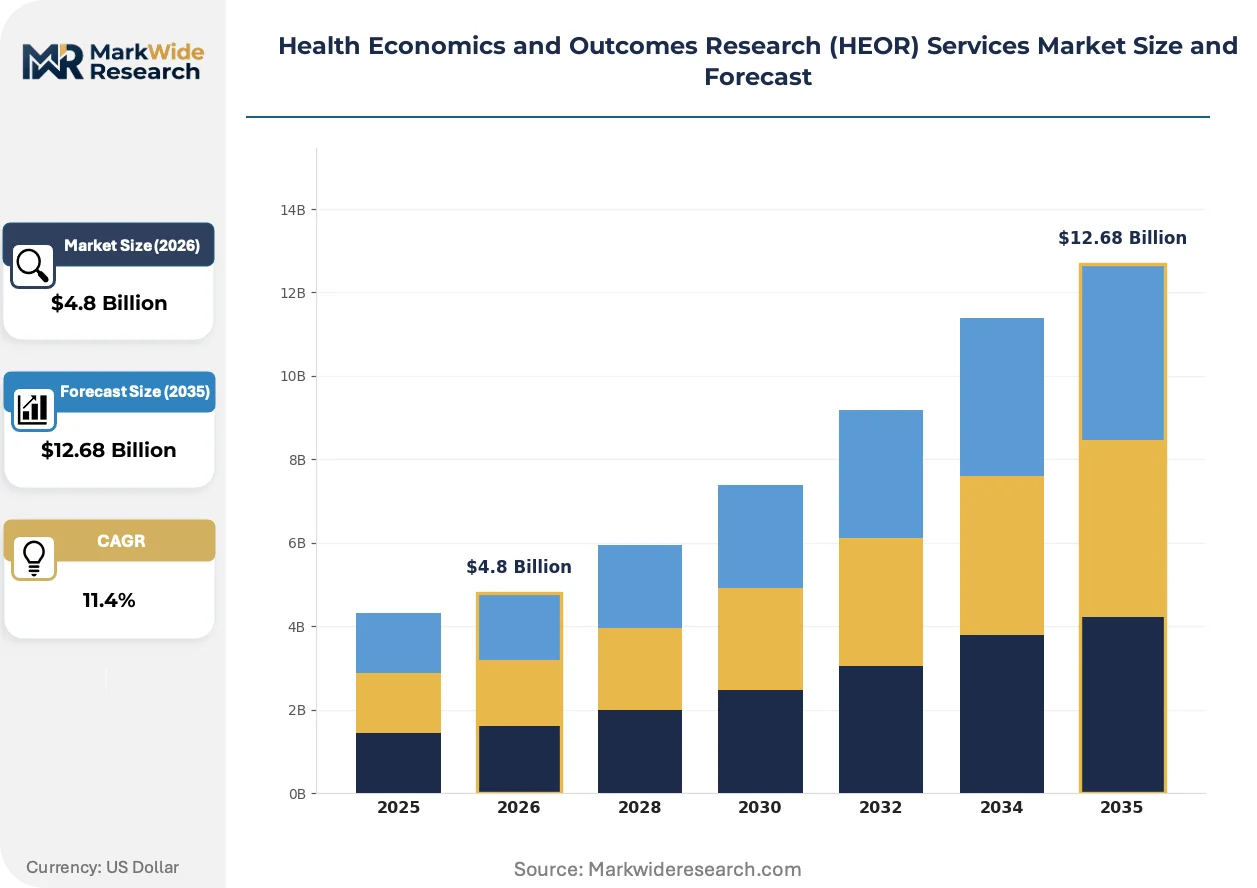
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cost-Effectiveness Analysis, Budget Impact Analysis, Modeling, Patient-Reported Outcomes Application: Pharmaceuticals, Biotechnology, Medical Devices, Clinical Trials End User: Healthcare Providers, Pharmaceutical Companies, Payers, Academic Institutions Delivery Model: Consulting, Software Solutions, On-Demand Services, In-House Models |
| Companies Covered | Optum (UnitedHealth Group), Pharmalex GmbH, McKesson Corporation, Cardinal Health, ICON PLC, IQVIA, Axtria, Inc., Thermo Fisher Scientific (PPD Inc.), Syneos Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Health Economics and Outcomes Research (HEOR) Services Market Emerging Trajectories
Artificial intelligence is compressing traditional HEOR workflows from evidence synthesis to model calibration, while regulatory convergence pressures reshape cross-border service delivery models.
Federated learning architectures are consolidating distributed analytics across institutional data silos without centralizing protected health information. Pharmaceutical manufacturers in oncology and rare disease portfolios are adopting these networks to accelerate external control arm construction. The technology is consolidating competitive advantage around data access breadth rather than methodological sophistication alone.
EU HTA Regulation implementation timelines are mandating joint clinical assessments across member states starting with oncology and advanced therapy medicinal products. Manufacturers must now submit unified evidence dossiers to the European Commission's Coordination Group rather than navigating twenty-seven national processes. Germany's G-BA and France's HAS are adapting internal review timelines to accommodate this centralized framework, compressing service provider response windows.
Integrated evidence planning now spans clinical development, regulatory submission, and market access functions within pharmaceutical organizations. HEOR teams are embedding earlier into phase II trial design to ensure endpoints satisfy both FDA and HTA body requirements. This organizational convergence is most visible among mid-cap biotech firms with single-asset dependencies where failed reimbursement negotiations threaten enterprise viability.
Health Economics and Outcomes Research (HEOR) Services Market Segmentation
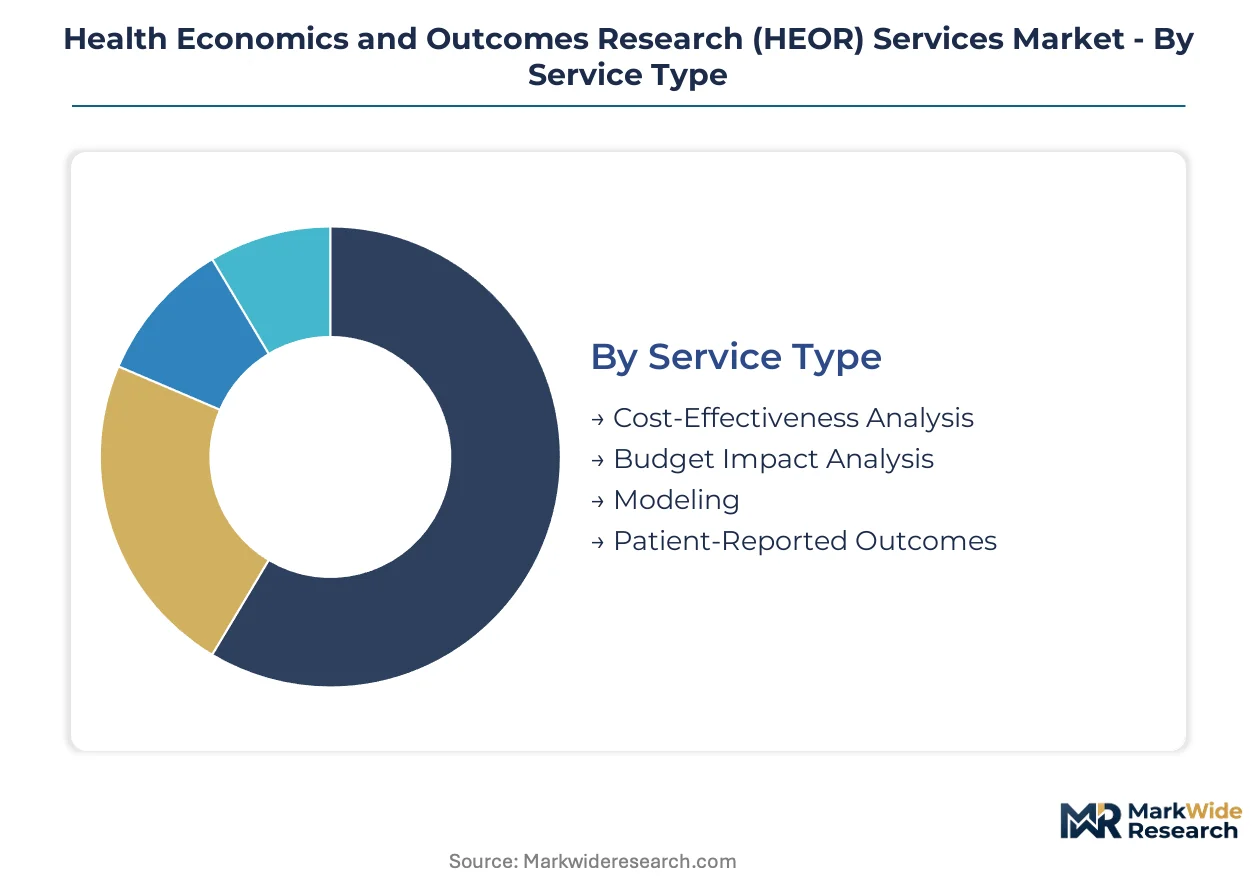
HEOR service providers structure offerings around distinct evidence-generation methodologies and client operational models. Segmentation reveals where proprietary capabilities command premium pricing versus commoditized analytical work.
Service Type:
Volume concentrates in established analytical categories while premium margins accrue to specialized modeling and patient-centric evidence services.
- Cost-Effectiveness Analysis:Systematic comparison of therapeutic alternatives through quality-adjusted life-year metrics satisfies mandatory submissions to Germany's G-BA and England's NICE. Demand from oncology and rare disease manufacturers intensifies as single-administration gene therapies disrupt traditional pricing frameworks.
- Budget Impact Analysis:Financial forecasting models project payer expenditure changes across defined patient populations and time horizons. Pharmaceutical companies negotiating with United States pharmacy benefit managers require these analyses for formulary access.
- Modeling:Discrete event simulation and Markov state-transition frameworks generate evidence where clinical trial data remains incomplete. Proprietary platform development creates defensible intellectual property for specialized providers.
- Patient-Reported Outcomes:Validated instrument development and health-related quality-of-life measurement capture patient-centric evidence. EMA and FDA regulatory mandates are accelerating dedicated PRO service expansion.
Today's leader: Cost-Effectiveness Analysis. Tomorrow's challenger: Patient-Reported Outcomes.
Application:
Therapeutic area complexity and regulatory scrutiny intensity determine service pricing tiers across client segments.
- Pharmaceuticals:Small-molecule and biologic manufacturers commission the majority of HEOR engagements for reimbursement dossiers. United States market access negotiations and EU HTA Regulation compliance drive sustained demand.
- Biotechnology:Cell and gene therapy developers require novel value demonstration frameworks including outcomes-based agreements. FDA's real-world evidence guidance under the 21st Century Cures Act shapes evidence generation strategies.
- Medical Devices:Diagnostic and therapeutic device manufacturers utilize comparative effectiveness research for coverage determinations. CMS national coverage decision processes necessitate robust economic evidence packages.
- Clinical Trials:Adaptive trial designs incorporate health economic endpoints to satisfy concurrent regulatory and payer requirements. Integrated evidence planning compresses development timelines for mid-cap biotech firms.
Pharmaceuticals anchor current revenue. Biotechnology applications are climbing the fastest as curative modalities reshape evidence requirements.
End User:
Payer sophistication and procurement centralization create divergent service delivery economics across customer types.
- Healthcare Providers:Hospital systems and integrated delivery networks utilize outcomes research for value-based care contract negotiation. United States Medicare accountable care organization participation drives internal analytics investment.
- Pharmaceutical Companies:Manufacturers represent the dominant client segment, embedding HEOR teams into phase II trial design. Cross-functional integration spans clinical development, regulatory affairs, and market access functions.
- Payers:Insurance plans and pharmacy benefit managers commission independent cost-effectiveness reviews for formulary decision-making. Proprietary modeling capabilities reduce reliance on manufacturer-submitted evidence.
- Academic Institutions:Universities and research hospitals generate methodological innovations and train specialized health economics talent. Federated learning partnerships with industry accelerate external control arm construction.
Pharmaceutical Companies dominate procurement. Payer direct engagement is gaining share fastest as vertical integration of evidence evaluation accelerates.
Delivery Model:
Client capability maturity and data infrastructure ownership determine preference for external versus internal service provision.
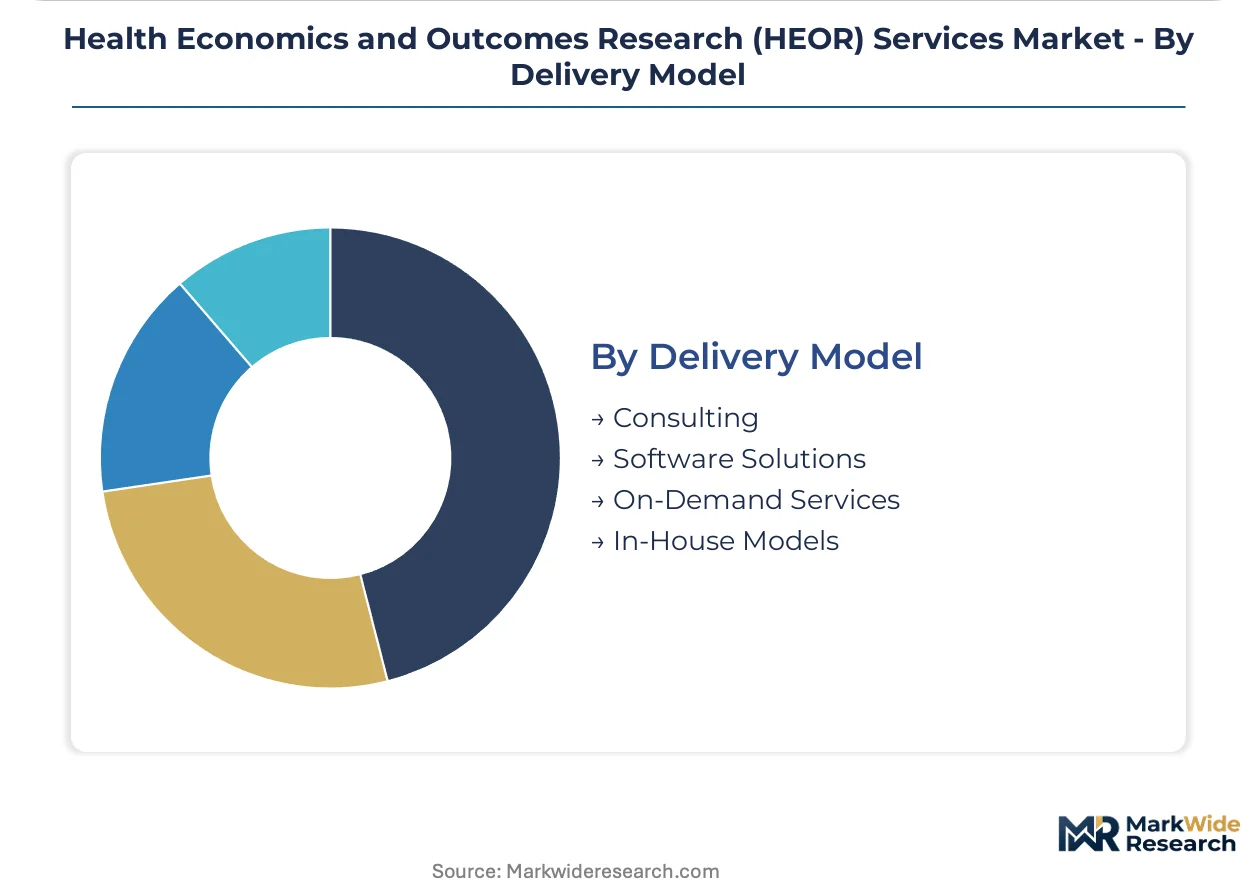
- Consulting:Project-based engagements deliver customized economic modeling and evidence synthesis. Boutique health economics practices compete with full-service contract research organizations for complex rare disease assessments.
- Software Solutions:Licensed platforms enable client self-service for budget impact and cost-effectiveness calculations. Subscription revenue models reduce transaction friction for recurring analytical needs.
- On-Demand Services:Modular offerings address surge capacity requirements during regulatory submission windows. Flexible resourcing accommodates compressed EU HTA Regulation timelines.
- In-House Models:Large pharmaceutical manufacturers build captive HEOR capabilities for strategic asset classes. Talent scarcity in health economics and biostatistics constrains internalization pace.
Consulting retains the largest share. Software Solutions show the steepest expansion trajectory as platform standardization reduces customization requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotech corridor concentrates HEOR service demand through dense pharmaceutical R&D activity and proximity to FDA headquarters. Payer contract negotiations in this cluster generate sustained analytical work. Academic medical centers supply specialized health economics talent to regional service providers.
United States
Pharmacy benefit manager negotiations and Medicare coverage determinations drive HEOR demand. FDA's 21st Century Cures Act real-world evidence framework shapes evidence generation standards. The Research Triangle Park cluster in North Carolina anchors contract research organization capacity for health economic modeling.
Germany
G-BA cost-per-quality-adjusted-life-year thresholds mandate sophisticated economic submissions for reimbursement. EU HTA Regulation harmonization compresses evidence preparation timelines for manufacturers. The Munich-Frankfurt corridor concentrates health technology assessment consultancy capacity serving both domestic and cross-border clients.
United Kingdom
NICE technology appraisals require robust cost-effectiveness evidence for National Health Service coverage. The Medicines and Healthcare products Regulatory Agency's parallel scientific advice procedures align trial designs with payer expectations. London's South Kensington-King's Cross corridor hosts specialized health economics consultancies serving European pharmaceutical clients.
Japan
PMDA's expanding real-world evidence utilization for post-market surveillance creates openings for Western analytical methodologies. Chuikyo price reimbursement reviews demand domestic health economic expertise for pharmaceutical submissions. The Tokyo-Osaka corridor concentrates pharmaceutical headquarters and associated HEOR procurement.
India
Domestic pharmaceutical manufacturers commission health economic evidence for export market access. CDSCO's evolving regulatory frameworks increasingly reference international HTA standards. Hyderabad's Genome Valley cluster builds health informatics capabilities supporting real-world evidence platform development.
Health Economics and Outcomes Research (HEOR) Services Market Vendor Landscape
Global majors compete with regional champions across data access breadth and payer relationship depth. The market structure tiers around integrated data asset owners, specialized health economics boutiques, and full-service contract research organizations. Strategic archetypes include claims database operators, rare disease modeling specialists, and federated learning platform developers. Competitive moves concentrate on proprietary data network expansion and cross-functional evidence planning integration.
Within the integrated data tier, Optum exemplifies payer-affiliated positioning through UnitedHealth Group claims access. IQVIA anchors the global CRO archetype with multi-therapeutic area outcomes study capabilities. ICON PLC occupies the specialized modeling segment for complex therapeutic categories. These three entities represent distinct competitive vectors rather than direct substitutes.
| Leading Market Players |
|---|
| Optum (UnitedHealth Group) |
| Pharmalex GmbH |
| McKesson Corporation |
| Cardinal Health |
| ICON PLC |
| IQVIA |
| Axtria, Inc. |
| Thermo Fisher Scientific (PPD Inc.) |
| Syneos Health |
| Others |
Supply Flow & Price Mechanics
Health economists with dual expertise in biostatistics and payer policy concentrate in the Boston-Cambridge and Research Triangle Park corridors, where labor-cost differentials between these US clusters and emerging analytics hubs in India widen pricing-tier spreads across HEOR service delivery.
Pricing Analysis
Input-cost pass-through from specialized talent scarcity anchors project-based consulting premiums, while software solutions deploy subscription tiers calibrated to client data infrastructure maturity. Price differentiation separates boutique rare-disease modeling specialists from standardized budget-impact template providers. Pricing pressure intensifies in commoditized analytical categories as platform automation displaces manual evidence synthesis. Mid-cap biotech firms with single-asset dependencies exhibit highest price sensitivity; large pharmaceutical manufacturers with captive HEOR capabilities demonstrate lowest sensitivity due to strategic rather than transactional procurement.
Supply Chain Analysis
Regional distribution centers for real-world evidence platforms concentrate in the United States, Germany, and the United Kingdom, where federated learning architectures consolidate distributed analytics without centralizing protected health information. Raw material dependencies include claims database licenses, EHR interoperability infrastructure, and FHIR-standard data specialists. Supply chain risk centers on single-source vulnerability where UnitedHealth Group's Optum unit controls exclusive access to proprietary claims datasets. Distribution runs through direct enterprise sales to pharmaceutical manufacturers, supplemented by academic institution partnerships for external control arm construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HEOR service procurement functions as a geographic-arbitrage play where EU HTA Regulation harmonization compresses evidence preparation timelines in Europe while FDA's divergent 21st Century Cures Act standards sustain parallel study requirements in the United States.
For Market Incumbents: Anticipate margin compression in standardized cost-effectiveness analysis as AI-enabled platforms automate model calibration and evidence synthesis. Defend positioning through backward integration into proprietary claims databases and federated learning network infrastructure. Prioritize certification investment for EU HTA Regulation joint clinical assessment readiness. Channel control via embedded phase II trial design partnerships with mid-cap biotech firms creates switching-cost barriers against platform competitors. For New Entrants and Emerging Players: Direct-to-pharmacist digital channels for patient-reported outcomes instrument deployment represent the most penetrable white-space target, bypassing incumbent CRO relationships. Japan's PMDA real-world evidence expansion offers geographic entry with lower competitive density than US or EU markets. Outcomes-based agreement modeling for cell and gene therapy developers provides specialized positioning against generalized competitors. For Investors and Strategic Acquirers: Payer-affiliated data asset owners are the most active acquirer in this space, consolidating analytical capabilities to verticalize evidence evaluation. Long-term viability hinges on proprietary data network breadth rather than methodological differentiation alone. Acquisition target archetype: federated learning platform developers with institutional data partnerships. Signal to watch: NICE and G-BA open-source model transparency mandates eroding proprietary simulation platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Network Expansion | IQVIA and academic medical centers consolidate distributed analytics across institutional EHR silos without PHI centralization. |
| EU HTA Regulation Compliance Buildout | Service providers compress response windows to accommodate Germany's G-BA and France's HAS timeline adaptations. |
| Patient-Reported Outcomes Platform Launch | EMA and FDA regulatory mandates for patient-centric evidence accelerate dedicated PRO instrument development services. |
| Cell and Gene Therapy Value Framework | Specialized providers construct novel outcomes-based agreements and annuity payment models for single-administration curative treatments. |
| Real-World Evidence Data Partnership | UnitedHealth Group's claims access through Optum creates defensible competitive moats in US payer negotiations. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with health economics directors, regulatory affairs leads, payer formulary managers, and biotech market access executives alongside secondary validation through FDA 21st Century Cures Act guidance documents, EMA parallel scientific advice procedures, NICE technology appraisal records, and G-BA benefit assessment dossiers. Bottom-up service provider revenue triangulation against top-down pharmaceutical R&D expenditure allocation ensures cross-verification.
Granularity-level framing models service type, application, end user, and delivery mode dimensions at the country level for the United States, Germany, United Kingdom, and Japan, with therapeutic area specificity for oncology and rare disease categories. CAGRs derive from segment-level growth trajectory analysis incorporating regulatory timeline compression effects and real-world evidence platform adoption curves across the projection horizon. Forecast inputs include EU HTA Regulation implementation schedules and PMDA real-world evidence utilization expansion.
The model assumes a particular technology adoption path; alternative pathways for federated learning architectures or AI-enabled evidence synthesis would alter the outlook. Forecasts reflect assumptions regarding regulatory convergence timelines and talent scarcity persistence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
Malaria Vaccine Market
Medical Research
India Computer-Aided Drug Discovery Market
Medical Research
Human Osteoblasts Market
Medical Research
Metabolomics Market
Medical Research
Global Humanized Mouse Model Market
Medical Research
AAV Contract Development and Manufacturing Organizations Market
Medical Research
Forensic Medicine Market
Medical Research
Epigenomics Market
Medical Research
Mice Model Technologies Market
Medical Research
US Academic Medical Centers Market
Medical Research
Lab Automation in Drug Discovery Market
Medical Research
Asia-Pacific Computer-Aided Drug Discovery Market
Medical Research
PDX Models Market
Medical Research
Chromatin Immunoprecipitation Sequencing Market
Medical Research
Placenta Market
Medical Research
Clinical Genomics Market