
 Human Osteoblasts Market | 2026-2036
Human Osteoblasts Market Size, Share, and Industry Trends Forecast 2026-2036
Human Osteoblasts Market Foresight
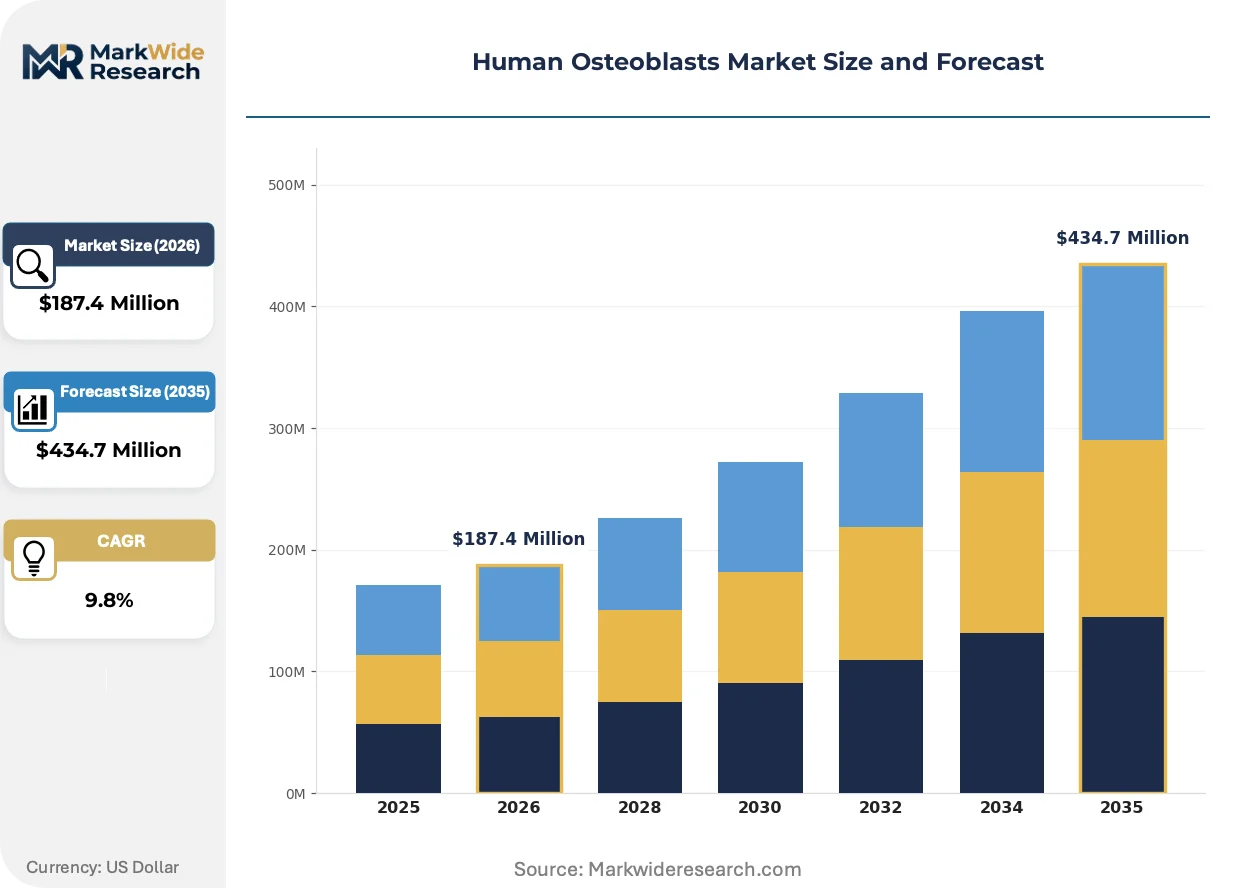
The EU Medical Device Regulation is decoupling osteoblast-based products from legacy tissue-engineering classifications, forcing manufacturers to recertify under stricter biocompatibility benchmarks. Thermo Fisher Scientific Inc. leverages its cryopreservation infrastructure to sustain distribution across European research corridors. Sigma-Aldrich anchors catalog supply for academic labs with standardized primary cell protocols. Lonza Group AG competes through custom manufacturing services that navigate evolving quality thresholds.
Human osteoblasts are bone-forming cells derived from mesenchymal stem lineages, typically cultured in alpha-MEM supplemented with ascorbic acid and beta-glycerophosphate to induce mineralization; they serve as essential substrates for studying skeletal biology, testing orthopedic biomaterials, and developing autologous bone regeneration therapies. Stem cells within the product type spectrum generate the fastest expansion as induced pluripotent and mesenchymal sources reduce donor variability. Regenerative medicine applications attract disproportionate R&D investment, while orthopedics retains the largest commercial volume due to established reimbursement for bone graft substitutes.
The FDA's regenerative medicine advanced therapy designation and the EU MDR framework collectively tighten sourcing documentation and traceability requirements for human-derived cell products. ISO 10993 biocompatibility standards further govern how osteoblast-seeded scaffolds qualify for surgical implantation pathways. Stakeholders must monitor how regional divergence in cell-therapy classification reshapes manufacturing location decisions and partnership structures.
Market Dynamics
The FDA's regenerative medicine advanced therapy designation is compressing clinical translation timelines for osteoblast-based products while simultaneously tightening documentation requirements for donor traceability and biocompatibility validation.
Growth Catalysts
- RMAT Pathway:The FDA's expedited review mechanism accelerates commercialization timelines for autologous bone regeneration therapies, reducing development cycles from decade-scale to five-to-seven-year windows.
- Orthopedic Biomaterial Testing:Implant manufacturers require validated human cell substrates to satisfy ISO 10993 biocompatibility standards for surgical scaffold qualification.
- Mesenchymal Stem Cell Sourcing:Induced pluripotent and adipose-derived lineages reduce lot-to-lot variability compared to cadaveric primary isolates, improving experimental reproducibility.
Market Restraints
- Donor Tissue Volatility:Primary osteoblast isolation depends on femoral head harvests from hip replacement surgeries, creating supply sensitivity to orthopedic procedure volumes.
- Cryopreservation Infrastructure Concentration:Liquid nitrogen logistics and GMP-compliant biobanking capacity clusters in the United States, Germany, and Japan, limiting access for mid-tier research institutions elsewhere.
- Xenogeneic Serum Dependency:Fetal bovine serum remains standard in alpha-MEM culture formulations, exposing manufacturers to price swings and BSE-related import restrictions.
Strategic Opportunities
- Synthetic Matrix Convergence:3D bioprinting platforms are integrating with osteoblast-laden bioinks to produce patient-specific bone grafts without secondary machining.
- EU MDR Recertification Window:Manufacturers who achieve MDR Class III designation for tissue-engineered products gain preferential access to European hospital procurement frameworks.
- Academic Catalog Expansion:Standardized primary cell protocols for CRISPR screening and disease modeling create recurring revenue streams beyond orthopedic applications.
Industry Challenges
- GMP Facility Scarcity:Cleanroom capacity for clinical-grade osteoblast expansion remains concentrated among contract manufacturers with decade-long qualification backlogs.
- Donor Consent Complexity:Evolving privacy frameworks require renegotiation of legacy tissue agreements, delaying new product launches by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Osteoblasts Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Grafts, Stem Cells, Biologics, Synthetic Biomaterials Application: Orthopedics, Dental, Research, Regenerative Medicine End User: Hospitals, Clinics, Research Institutions, Biotech Companies Delivery Mode: Injectable, Surgical Implants, Localized Delivery, Systemic Delivery |
| Companies Covered | Sigma-Aldrich, American Type Culture Collection, Thermo Fisher Scientific Inc., Merck KGaA, Creative Bioarray Inc., STEMCELL Technologies Inc., PromoCell GmbH, Zen-Bio Inc., Lonza Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Osteoblasts Market Shifts & Advancements
Perfusion bioreactor systems and defined serum-free media formulations are displacing static culture methods, enabling industrial-scale osteoblast expansion while reducing regulatory risk from animal-derived inputs.
Single-use perfusion bioreactors are integrating continuous media exchange with real-time metabolite monitoring, allowing manufacturers to achieve cell densities tenfold higher than flask-based methods. Contract development organizations in Massachusetts and North Carolina are adopting these platforms to serve orthopedic device clients. The technology is integrating process analytical technology standards from biopharmaceutical manufacturing, compressing batch release timelines.
EU MDR Annex XVI reclassification is forcing osteoblast-seeded scaffolds toward pharmaceutical-style quality management systems rather than legacy medical device pathways. Manufacturers must now demonstrate extended stability data and post-market surveillance comparable to advanced therapy medicinal products. German and Swiss notified bodies are experiencing eighteen-month backlogs for novel tissue-engineered product reviews.
Hospital procurement departments are consolidating vendor lists around suppliers with dual FDA-EMA master file documentation, displacing smaller catalog distributors. Academic medical centers in California and Texas now require ISO 13485 certification even for research-grade cell purchases. This concentration is visible most acutely in the bone graft substitute segment, where reimbursement codes favor validated supply chains over experimental sources.
Human Osteoblasts Market Segmentation
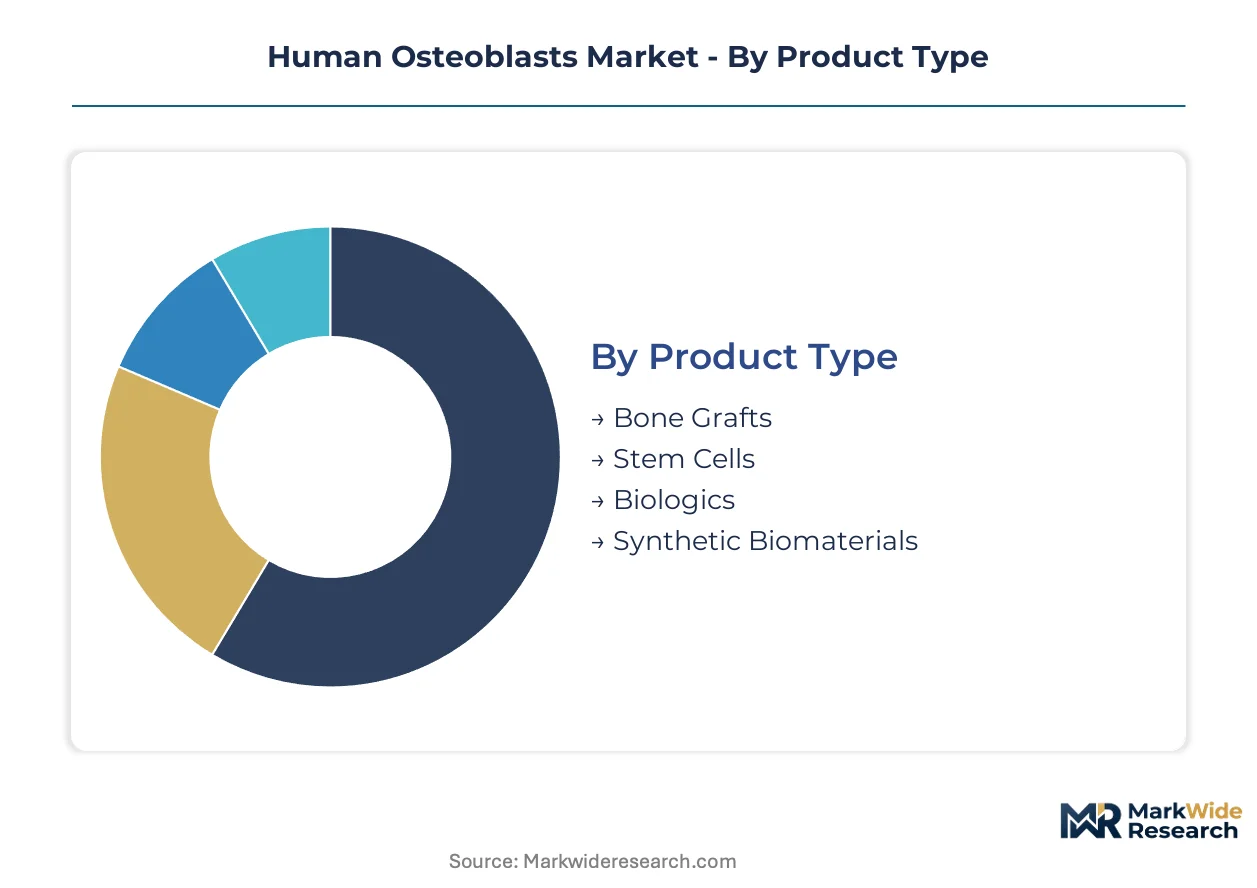
Osteoblast product differentiation determines regulatory pathway complexity and reimbursement eligibility. Segment boundaries are hardening as FDA RMAT designations and EU MDR recertification windows force strategic portfolio choices.
Product Type:
ISO 10993 biocompatibility tiers and FDA tissue-engineering classifications split certification burdens unevenly across this category.
- Stem Cells:Induced pluripotent and mesenchymal lineages reduce donor variability through renewable sourcing. Demand concentrates in Massachusetts and North Carolina contract development organizations serving orthopedic device clients, driven by RMAT pathway acceleration timelines.
- Bone Grafts:Cadaveric and synthetic matrices seeded with primary osteoblasts dominate hospital procurement volumes. Reimbursement codes in US academic medical centers favor validated supply chains with dual FDA-EMA master file documentation.
- Biologics:Growth factor-enhanced osteoblast formulations navigate pharmaceutical-style quality management systems under EU MDR Annex XVI.
- Synthetic Biomaterials:Ceramic and polymer scaffolds with osteoblast adhesion coatings qualify under legacy medical device pathways in select jurisdictions.
Leading the category by volume: Bone Grafts. Growing fastest: Stem Cells.
Application:
End-use economics range from fee-for-service surgical reimbursement to grant-funded academic research, reshaping margin structures.
- Orthopedics:Spinal fusion and trauma applications anchor commercial demand through established CPT codes. US hospital procurement departments consolidate vendor lists around ISO 13485-certified suppliers.
- Regenerative Medicine:Autologous bone regeneration therapies attract disproportionate R&D investment despite longer development cycles. German and Swiss notified bodies impose eighteen-month review backlogs for novel tissue-engineered products.
- Research:CRISPR screening and disease modeling protocols at California and Texas academic medical centers create recurring catalog revenue.
- Dental:Alveolar ridge augmentation and implant osseointegration procedures drive specialized formulation demand.
Highest revenue concentration: Orthopedics. Steepest expansion trajectory: Regenerative Medicine.
End User:
Customer scale dictates GMP compliance requirements and cryopreservation infrastructure access.
- Hospitals:Academic medical centers in California and Texas now require ISO 13485 certification even for research-grade purchases, displacing smaller distributors.
- Biotech Companies:Venture-backed developers in Massachusetts leverage contract manufacturing organizations with perfusion bioreactor capacity to compress batch release timelines.
- Research Institutions:Mid-tier universities face liquid nitrogen logistics constraints as GMP-compliant biobanking capacity clusters in the United States, Germany, and Japan.
- Clinics:Ambulatory surgical centers depend on pre-validated allograft products with simplified handling protocols.
Primary procurement volume: Hospitals. Fastest credential requirements tightening: Biotech Companies.
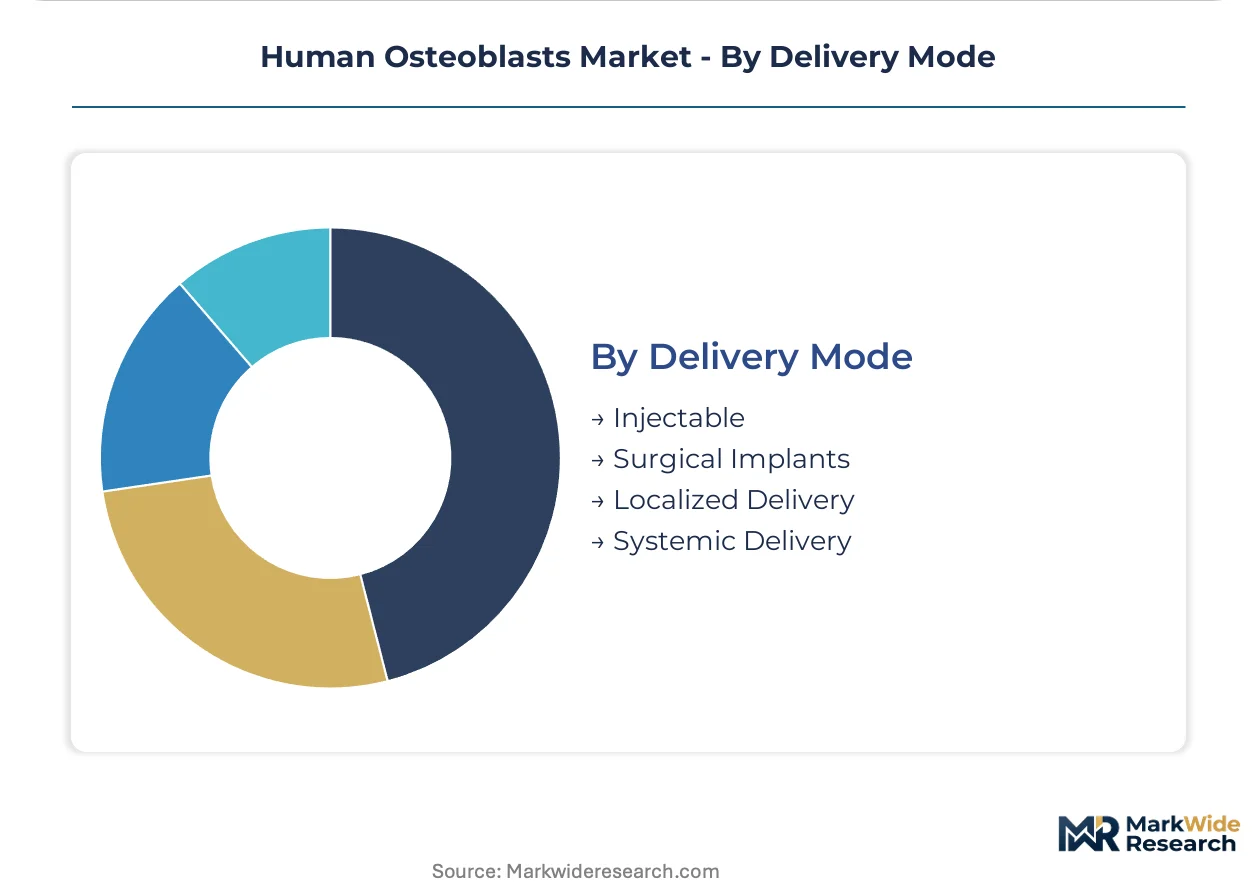
Delivery Mode:
Route of administration determines scaffold design complexity and sterilization validation scope.
- Surgical Implants:Pre-formed osteoblast-seeded scaffolds require extended stability data under EU MDR pharmaceutical-style surveillance comparable to advanced therapy medicinal products.
- Injectable:Cell-laden hydrogels and pastes enable minimally delivered procedures with reduced surgical morbidity. 3D bioprinting platforms integrate with osteoblast-laden bioinks to produce patient-specific grafts without secondary machining.
- Localized Delivery:Sustained-release carriers target specific anatomical sites with reduced systemic exposure.
- Systemic Delivery:Intravenous osteoblast precursors remain experimental, constrained by homing efficiency and off-target distribution challenges.
Dominant commercial form: Surgical Implants. Most rapid technology convergence: Injectable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors the most concentrated cluster of contract development organizations serving orthopedic device clients, with Massachusetts and North Carolina biotech corridors drawing disproportionate R&D investment in autologous bone regeneration therapies.
United States
Academic medical centers in California and Texas now require ISO 13485 certification even for research-grade cell purchases, consolidating procurement around validated suppliers. The FDA's RMAT pathway compresses development cycles for Massachusetts-based biotech developers. Perfusion bioreactor capacity clusters in Boston and Research Triangle Park serve orthopedic device clients.
Germany
German notified bodies impose eighteen-month review backlogs for novel tissue-engineered products under EU MDR Annex XVI reclassification. Stuttgart and Munich host GMP-compliant biobanking infrastructure serving European research corridors. The country's pharmaceutical-style quality management requirements favor manufacturers with extended stability data capabilities.
Switzerland
Swissmedic oversight of tissue-engineered products creates a parallel regulatory track to EU MDR, attracting developers seeking regulatory arbitrage opportunities. Basel and Zurich anchor cryopreservation infrastructure for clinical-grade osteoblast distribution. Swiss contract manufacturers leverage dual FDA-EMA master file documentation to access consolidated hospital vendor lists.
Japan
PMDA alignment with ISO 10993 biocompatibility standards governs osteoblast-seeded scaffold qualification for surgical implantation. Tokyo and Osaka metropolitan areas concentrate liquid nitrogen logistics and GMP-compliant biobanking capacity. METI funding for regenerative medicine accelerates clinical translation timelines for domestic developers.
United Kingdom
Post-Brexit divergence from EU MDR creates dual certification burdens for London and Cambridge-based cell therapy developers. The MHRA's accelerated access pathway offers an alternative route for osteoblast-based products. Oxford and Manchester research institutions drive catalog demand for standardized primary cell protocols.
Human Osteoblasts Market Competitive Landscape
The competitive structure tilts toward diversified life science conglomerates with cryopreservation infrastructure and catalog distribution networks. Market position depends on GMP facility access, dual FDA-EMA regulatory documentation, and perfusion bioreactor manufacturing capacity. Three archetypes dominate: integrated biobank-cryopreservation operators, contract development organizations with bioreactor platforms, and catalog distributors serving academic labs. Capacity expansion and strategic partnerships with orthopedic device manufacturers constitute the primary competitive moves.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. and Merck KGaA exemplify the integrated biobank-cryopreservation archetype, while Lonza Group AG occupies a position within the contract manufacturing tier. Sigma-Aldrich anchors the catalog distribution segment for standardized primary cell protocols. These three entities collectively represent the structural poles around which mid-tier specialists and regional distributors organize their market access strategies.
| Leading Market Players |
|---|
| Sigma-Aldrich |
| American Type Culture Collection |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Creative Bioarray Inc. |
| STEMCELL Technologies Inc. |
| PromoCell GmbH |
| Zen-Bio Inc. |
| Lonza Group AG |
| Others |
Supply & Pricing Matrix
Captive biobanking infrastructure in the United States, Germany, and Japan anchors supply positions and pricing power for clinical-grade human osteoblasts, with GMP-compliant cryopreservation capacity functioning as the gatekeeper tier separating premium-certified products from research-grade alternatives. Manufacturers with in-house liquid nitrogen logistics and FDA-EMA dual master file documentation command substantial premiums over catalog distributors dependent on third-party cold chain intermediaries.
Pricing Analysis
Outcome-based pricing anchors the regenerative medicine tier, where FDA RMAT-designated autologous bone regeneration therapies command substantial premiums tied to clinical efficacy endpoints rather than per-unit cell counts. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade: GMP-compliant clinical lots with full donor traceability, ISO 13485-certified research grades, and non-certified primary isolates. Cost compression in the research-grade tier is intensifying because academic medical centers in California and Texas now mandate ISO 13485 documentation even for catalog purchases, forcing smaller distributors to absorb certification investments or exit. Hospital procurement departments show lowest price sensitivity due to reimbursement code protection, while mid-tier research institutions face acute budget constraints.
Supply Chain Analysis
Femoral head tissue supply rests on hip replacement surgery volumes in the United States, Germany, and Japan, with cadaveric primary osteoblast isolation drawing from hospital operating room harvests coordinated through specialized tissue recovery organizations. Fetal bovine serum, alpha-MEM culture media, and GMP-grade cryopreservation reagents constitute critical input dependencies. Single-source vulnerability concentrates in liquid nitrogen logistics providers serving GMP biobanking clusters. Distribution runs through dual-track channels: direct hospital contracts for bone graft substitutes and catalog distributors for research applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GMP facility scarcity props pricing across all certification tiers, with cleanroom capacity for clinical-grade osteoblast expansion concentrated among contract manufacturers with decade-long qualification backlogs. This supply constraint insulates incumbent pricing power while creating acquisition premiums for qualified assets.
For Market Incumbents: Deploy perfusion bioreactor capacity additions in Massachusetts and North Carolina to capture orthopedic device client demand. Defensive consolidation moves should prioritize dual FDA-EMA master file documentation to maintain hospital vendor list positioning against emerging contract manufacturers. The threat of EU MDR Annex XVI reclassification toward pharmaceutical-style quality systems demands accelerated stability data investments. For New Entrants and Emerging Players: Enter via CRISPR screening and disease modeling protocols at mid-tier universities facing liquid nitrogen logistics constraints, offering regional cryopreservation partnerships as a bundled service. The most penetrable segment lies in synthetic biomaterial coatings for ceramic and polymer scaffolds, which qualify under legacy medical device pathways in select jurisdictions. A go-to-market angle centered on defined serum-free media formulations addresses regulatory risk from animal-derived inputs. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified life science conglomerates seeking GMP facility access. Long-term viability over the analysis window favors contract development organizations with integrated biobank-cryopreservation infrastructure. The signal to watch is FDA RMAT designation velocity, which accelerates commercialization timelines and revalues qualified manufacturing assets.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Facility Acquisition | Captures scarce cleanroom capacity with decade-long qualification backlogs in Boston and Research Triangle Park. |
| Dual Master File Documentation | Unlocks consolidated hospital procurement frameworks requiring simultaneous FDA and EMA regulatory submissions. |
| Perfusion Bioreactor Deployment | Compresses batch release timelines through process analytical technology integration from biopharmaceutical manufacturing. |
| EU MDR Class III Designation | Gains preferential access to European hospital procurement under pharmaceutical-style quality management systems. |
| Serum-Free Media Formulation | Reduces regulatory exposure to BSE-related import restrictions and fetal bovine serum price volatility. |
Research Methodology
Document review covered FDA RMAT designation filings, EU MDR Annex XVI guidance documents, and ISO 10993 biocompatibility standards, complemented by interviews with contract manufacturing executives, orthopedic device regulatory affairs leads, hospital procurement managers at academic medical centers, and GMP facility operators. Secondary validation drew from SEC 10-K disclosures of diversified life science conglomerates, notified body review timelines published by German and Swiss regulators, and CMS reimbursement code databases. Bottom-up triangulation across product type, application, and end user segments was cross-checked against top-down market sizing from cryopreservation infrastructure capacity estimates.
Historical revenue trajectories were cross-referenced against panel input from industry stakeholders to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type tiers split by ISO 10993 biocompatibility classification, application categories spanning orthopedics through regenerative medicine, and end user scale differentiated by GMP compliance requirements. CAGRs were derived from weighted capacity expansion schedules and regulatory pathway velocity differentials. Forecast inputs incorporated perfusion bioreactor adoption curves and EU MDR recertification window timing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated FDA RMAT designations or prolonged EU MDR review backlogs. Assumptions reflect documented regulatory frameworks, disclosed facility capacity, and validated procurement requirements. A small set of named triggers warrants ongoing watch: femoral head tissue supply disruption from orthopedic procedure volume shifts, BSE-related fetal bovine serum import restrictions, and GMP facility qualification timeline extensions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
Epigenomics Market
Medical Research
Life Science R&D Infrastructure Outsourcing Market
Medical Research
India Computer-Aided Drug Discovery Market
Medical Research
Methicillin-Resistant Staphylococcus Aureus (MRSA) Drugs Market
Medical Research
Global Mice Model Market
Medical Research
Chromatin Immunoprecipitation Sequencing Market
Medical Research
Global Humanized Mouse Model Market
Medical Research
US Academic Medical Centers Market
Medical Research
Asia-Pacific Computer-Aided Drug Discovery Market
Medical Research
Global Patient Derived Xenograft Models Market
Medical Research
Epigenetics Market
Medical Research
FFPE Tissue Samples Market
Medical Research
Organoids and Spheroids Market
Medical Research
Placenta Market
Medical Research
Mice Model Technologies Market
Medical Research
Preventive Medicine Market