
 6 Hexanediol Market | 2026-2036
6 Hexanediol Market Size, Share, and Industry Trends Forecast 2026-2036
6 Hexanediol Market Outlook
Specialty chemical distribution channels serving Asia-Pacific industrial clusters is reconfiguring around direct mill-to-plant supply agreements that bypass traditional distributor markups. BASF SE leverages its Ludwigshafen integrated site to sustain captive adipic acid feedstock for European 6 hexanediol derivatives. UBE Corporation anchors Japanese supply through its caprolactam-adjacent operations, while Fushun Tianfu Chemicals Co., Ltd competes on Liaoning province manufacturing scale for domestic Chinese offtake.
6 hexanediol is a linear six-carbon diol produced primarily via catalytic hydrogenation of adipic acid or its esters, featuring terminal hydroxyl groups that enable polyurethane chain extension and polyester polyol synthesis at molecular weights typically spanning 118.17 g/mol. Industrial grade material dominates volume flows into coatings and adhesives formulations where cost sensitivity outweighs purity premiums, though high purity grades command stronger margin pools from pharmaceutical and specialized cosmetic applications. Technical grade deliveries through bulk and drum modes serve construction and automotive end users with standardized offtake schedules.
EPA oversight under the Toxic Substances Control Act shapes product notification pathways for new 6 hexanediol derivatives entering US commerce, while REACH registration mandates in Europe enforce full toxicological dossiers for continued import and manufacture above threshold tonnages. China's SAMR administers GB standard compliance for domestic chemical purity claims, creating a fragmented compliance landscape that favors producers with multi-jurisdiction regulatory affairs capabilities. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions that could redirect demand toward 6 hexanediol-based alternatives in certain coating segments.
Market Dynamics
Integrated adipic acid hydrogenation capacity in China and tightening purity mandates under REACH and EPA standards are restructuring competitive advantage toward producers with captive feedstock supply and multi-jurisdiction regulatory dossiers.
Growth Catalysts
- REACH registration thresholds:European manufacturers face renewed purity documentation requirements that favor established producers with existing toxicological dossiers over import-dependent compounders.
- Polyurethane coatings expansion:Automotive refinish and industrial maintenance sectors in Germany and the United States are specifying 6 hexanediol chain extenders for abrasion-resistant topcoats.
- Adipic acid hydrogenation yield improvements:Continuous catalytic process refinements at integrated Chinese petrochemical complexes are compressing unit production costs.
Market Restraints
- Feedstock concentration risk:Over half of merchant adipic acid supply originates from integrated nylon-6,6 producers, creating allocation vulnerability during caprolactam demand surges.
- Propylene glycol substitution:Lower-cost diols penetrate economy-grade adhesive formulations where hydroxyl functionality requirements permit molecular weight trade-offs.
- EPA notification timelines:Toxic Substances Control Act pre-manufacture review periods extend 90-180 days for novel 6 hexanediol derivatives, delaying formulation launches.
Strategic Opportunities
- Pharmaceutical-grade certification:USP and EP monograph compliance for high-purity material unlocks excipient and active pharmaceutical intermediate applications at 3-4x industrial grade margins.
- India specialty chemical import substitution:Domestic formulators under BIS quality mandates seek qualified local diol supply to replace European and Northeast Asian imports.
- Waterborne polyurethane convergence:Formulation technology advances enable 6 hexanediol incorporation into low-VOC coating systems without solvent-borne performance sacrifice.
Industry Challenges
- Catalytic process engineering talent scarcity:Hydrogenation unit optimization requires specialized expertise in continuous flow reactor design that outpaces vocational training pipeline output.
- Legacy adipic acid ester inventory reconciliation:Producers maintaining dual feedstock flexibility face working capital strain from methyl ester price volatility versus acid spot markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 6 Hexanediol Market |
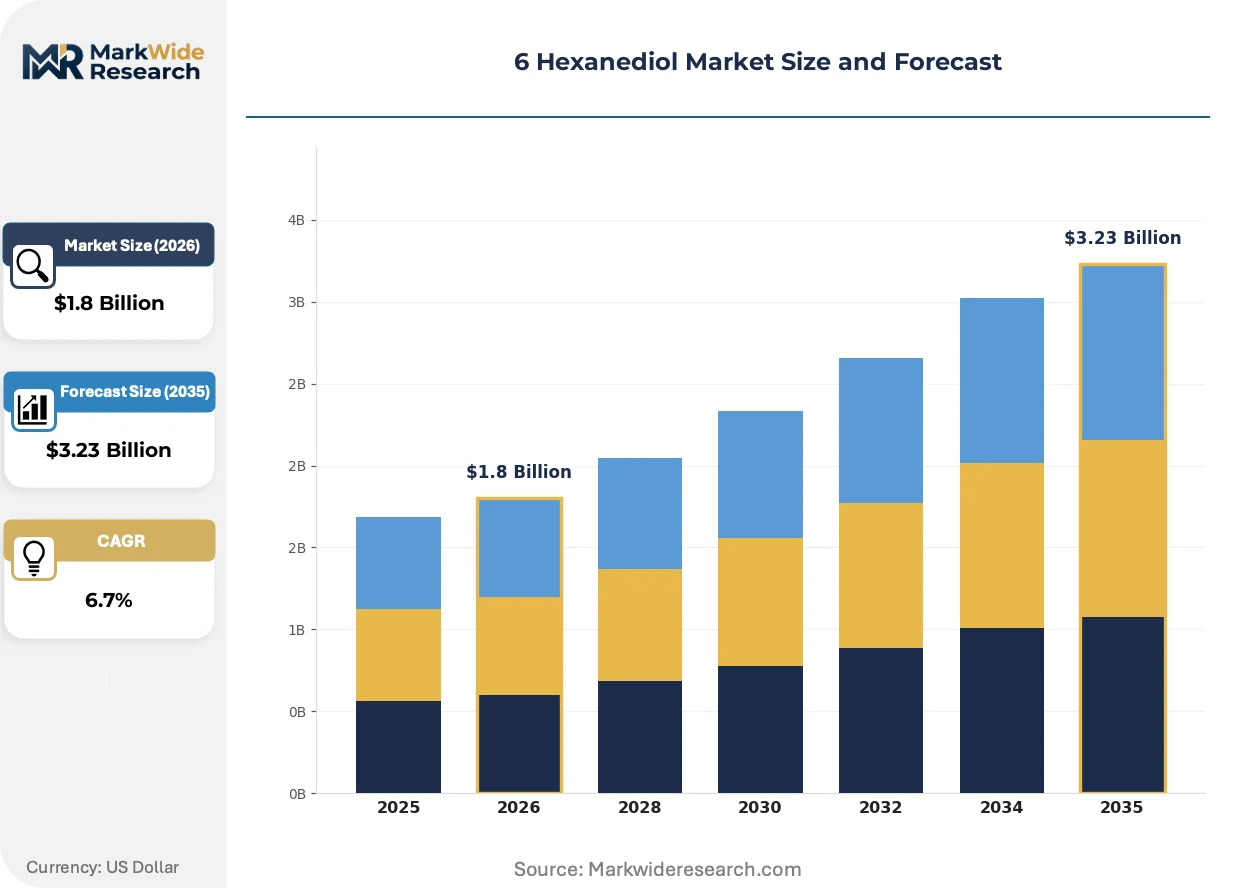
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Coatings, Adhesives, Plasticizers, Cosmetics End User: Automotive, Construction, Pharmaceuticals, Textiles Product Type: Industrial Grade, High Purity, Food Grade, Technical Grade Delivery Mode: Bulk, Drums, IBCs, Containers |
| Companies Covered | BASF SE, LANXESS, UBE Corporation, Evonik Industries AG, Perstorp Holding AB, Fushun Tianfu Chemicals Co., Ltd, Lishui Nanming Chemical Co., Ltd, Prasol Chemicals Ltd., Shandong Yuanli Science and Technology Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
6 Hexanediol Market Strategic Shifts
Process intensification and regulatory chemistry are compressing traditional production economics while opening molecular application spaces previously blocked by purity or performance constraints.
Continuous flow hydrogenation reactor technology is hybridizing batch adipic acid reduction protocols into integrated pipeline systems. German and Japanese engineering contractors are deploying skid-mounted units for mid-scale producers seeking yield consistency without billion-dollar grassroots investment. This capital-light scale approach is fragmenting capacity geography and eroding historical site-scale advantages.
REACH substance evaluation under the 2024-2026 Community Rolling Action Plan is extending scrutiny to adipic acid derivatives including 6 hexanediol downstream applications. Coating formulators serving EU automotive OEMs are accelerating substitution studies to preempt authorization list placement. The regulatory pressure is compressing product development cycles and favoring producers with early dossier completion.
Direct mill-to-plant supply contracting is displacing traditional distributor intermediation in Asia-Pacific industrial clusters. Large polyurethane system houses in China and South Korea now negotiate annual volume commitments with Liaoning and Shandong producers, capturing 8-12 point margin compression previously absorbed by regional traders. This channel consolidation is visible most acutely in automotive seating and footwear adhesive supply chains.
6 Hexanediol Market Segmentation
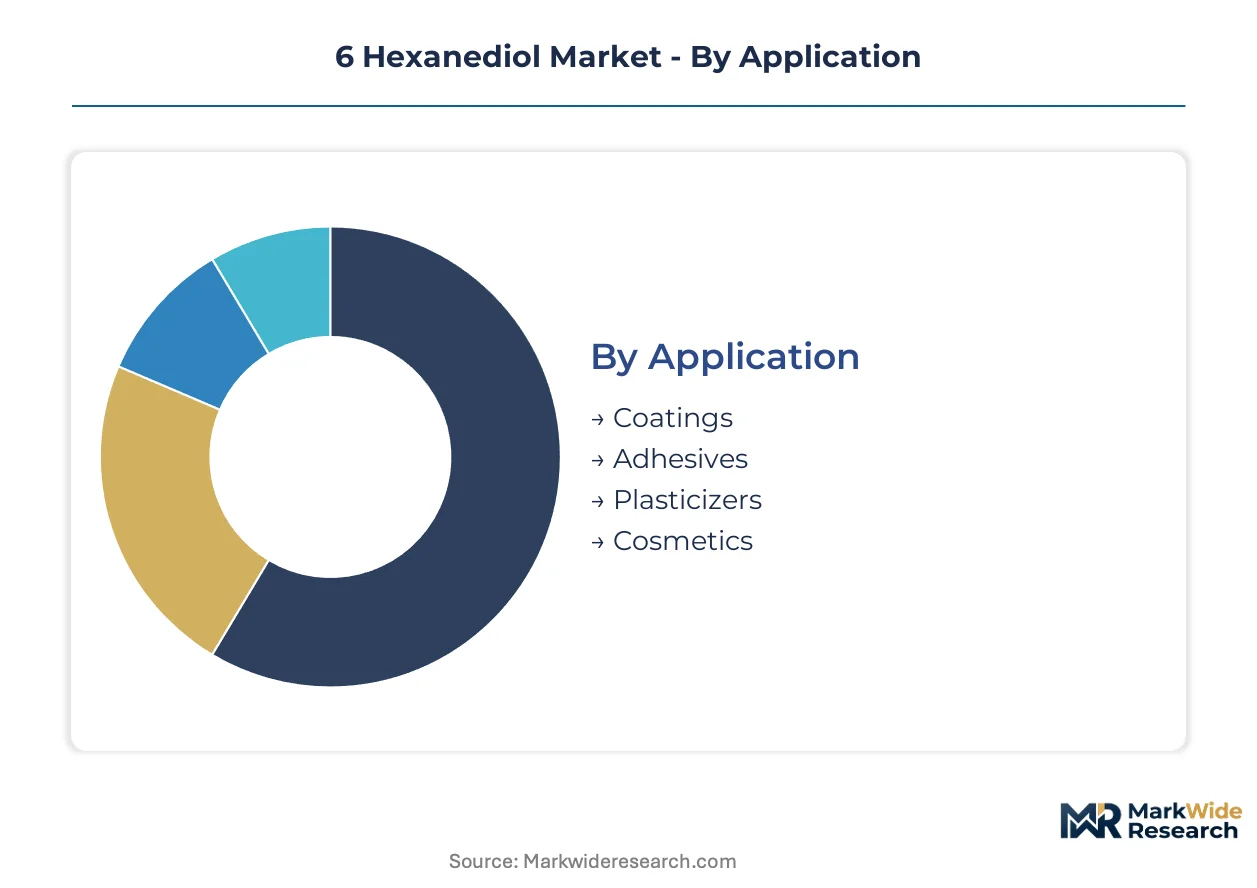
Segmentation in 6 hexanediol markets reveals how purity grades, delivery logistics, and end-use specifications fragment procurement behavior. Technical requirements diverge sharply between automotive coatings formulators and pharmaceutical excipient buyers, creating distinct margin pools that reward specialized supply configurations.
Application:
After-sales technical support intensity varies dramatically across applications, with coatings and adhesives buyers demanding formulation troubleshooting while cosmetics clients prioritize regulatory documentation.
- Coatings:Polyurethane chain extension applications dominate volume consumption, with automotive refinish and industrial maintenance sectors in Germany and the United States specifying 6 hexanediol for abrasion-resistant topcoats. REACH substance evaluation under the 2024-2026 Community Rolling Action Plan is compressing product development cycles for coating formulators serving EU automotive OEMs.
- Adhesives:Reactive hot-melt and solvent-borne systems incorporate 6 hexanediol as a chain extender to tune crystallization rates and open times. Large polyurethane system houses in China and South Korea negotiate annual volume commitments directly with Liaoning and Shandong producers, bypassing traditional distributor markups.
- Plasticizers:Polyester polyol synthesis for flexible PVC alternatives drives demand from construction and wire-cable applications.
- Cosmetics:High-purity grades serve humectant and emollient functions where USP and EP monograph compliance commands premium positioning.
By volume, coatings leads. By growth pace, cosmetics is ahead.
End User:
Customer concentration patterns split between consolidated automotive OEM supply chains and fragmented construction sector procurement.
- Automotive:Seating, interior trim, and refinish coatings consume industrial-grade material through just-in-time delivery agreements. German OEMs enforce REACH-compliant documentation thresholds that favor established producers with existing toxicological dossiers.
- Construction:Waterproofing membranes and flooring adhesives absorb technical-grade deliveries through bulk and drum modes with standardized offtake schedules.
- Pharmaceuticals:Excipient and active pharmaceutical intermediate applications require USP and EP monograph compliance at margins three to four times industrial-grade levels.
- Textiles:Synthetic leather and fiber treatments represent emerging volume with specialized softness and durability requirements.
Automotive commands the largest revenue pool. Pharmaceuticals delivers the steepest expansion trajectory.
Product Type:
Margin stratification across purity tiers creates distinct competitive arenas where certification investments erect barriers to entry.
- Industrial Grade:Standard hydrogenation output serves cost-sensitive coatings and adhesives where hydroxyl functionality outweighs trace impurity concerns. Chinese domestic adipic acid hydrogenation capacity supports integrated output for regional consumption.
- High Purity:Additional distillation and crystallization steps reduce cyclic oligomer content below pharmaceutical thresholds. EPA oversight under the Toxic Substances Control Act shapes notification pathways for derivatives entering US commerce.
- Food Grade:Limited applications in food-contact adhesives and coatings require migration testing compliance under FDA and EFSA frameworks.
- Technical Grade:Mid-tier specification bridges industrial and high-purity segments for construction and automotive applications with moderate purity requirements.
Industrial grade dominates tonnage. High purity captures the fastest margin expansion.
Delivery Mode:
Logistics configuration directly reflects customer scale and inventory management sophistication across end-use segments.
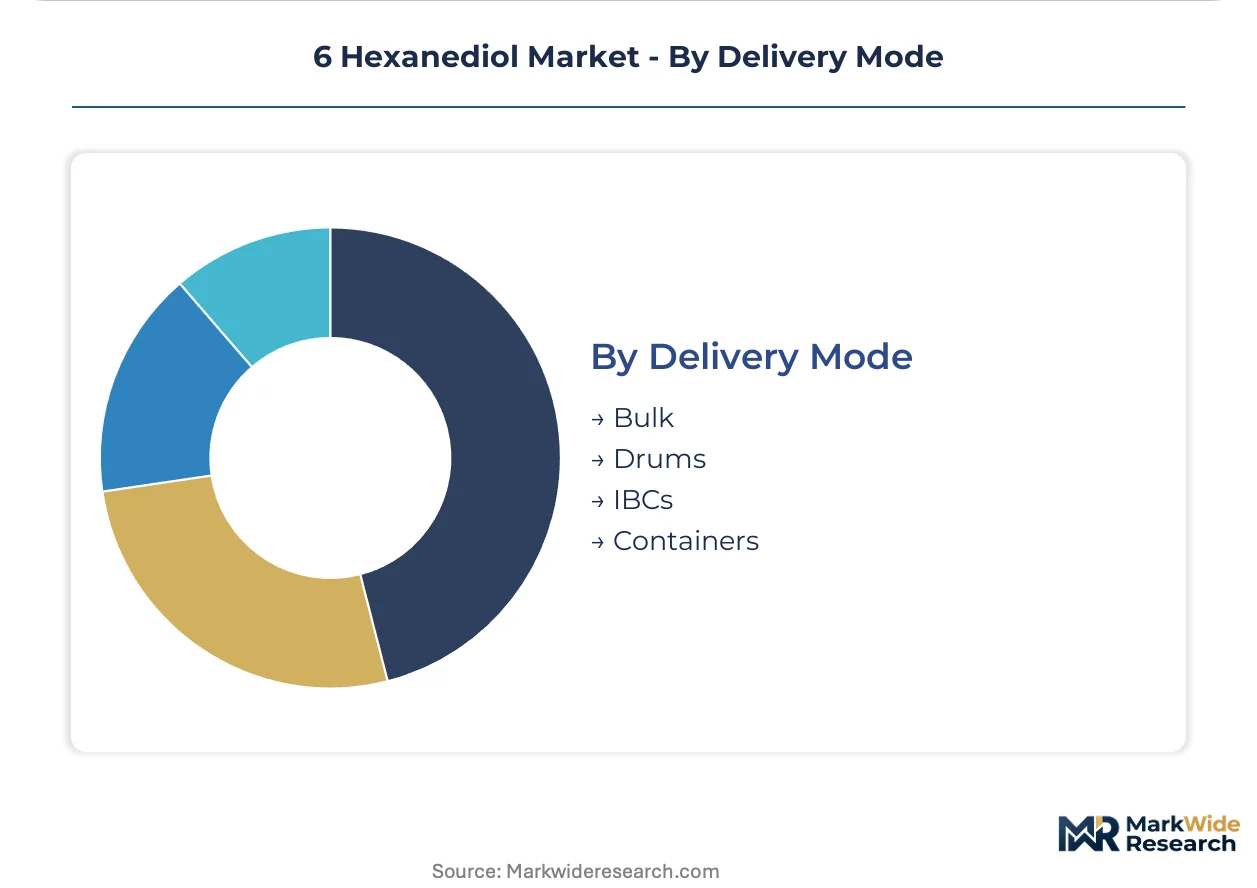
- Bulk:Tank truck and railcar deliveries serve large polyurethane system houses with dedicated storage infrastructure. Direct mill-to-plant contracting in Asia-Pacific clusters captures margin compression previously absorbed by regional traders.
- Drums:Standard 200-liter steel and plastic drums accommodate mid-scale formulators without bulk handling capabilities.
- IBCs:Intermediate bulk containers offer flexibility for specialty chemical distributors serving fragmented customer bases.
- Containers:ISO tank and flexitank modes facilitate intercontinental shipment for import-dependent compounders.
Bulk moves the greatest volume. IBCs are expanding most quickly as distributor channels consolidate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's chemical terminal throughput underwrites China's dominance in adipic acid derivative logistics, while Rotterdam's liquid bulk infrastructure anchors European hydrogenation feedstock flows.
China
Liaoning province's integrated petrochemical complexes consume domestic adipic acid hydrogenation output for regional coatings and adhesives manufacturing. SAMR's GB standard compliance requirements for chemical purity claims create documentation hurdles for import-dependent compounders. Shandong producers negotiate direct mill-to-plant agreements with polyurethane system houses in Qingdao and Yantai, displacing traditional distributor channels.
Germany
Automotive OEMs in Stuttgart and Wolfsburg specify 6 hexanediol chain extenders for abrasion-resistant refinish coatings. REACH substance evaluation under ECHA's 2024-2026 Community Rolling Action Plan compresses product development cycles for coating formulators. The Ludwigshafen chemical cluster sustains captive adipic acid feedstock integration for European derivative output.
United States
Industrial maintenance coating formulators in the Gulf Coast corridor specify 6 hexanediol for solvent-borne polyurethane systems. EPA oversight under the Toxic Substances Control Act shapes 90-180 day pre-manufacture notification pathways for novel derivatives. Houston's petrochemical storage and blending infrastructure supports bulk delivery logistics to large polyurethane system houses.
Japan
Caprolactam-adjacent operations in the Chubu region anchor domestic 6 hexanediol supply for automotive seating and footwear adhesive applications. METI's chemical substance management frameworks align with international regulatory convergence pressures. Ube City's integrated nylon precursor complexes maintain hydrogenation yield consistency through continuous catalytic process refinements.
India
Domestic formulators under BIS quality mandates seek qualified local diol supply to replace European and Northeast Asian imports. The central bank's trade credit facilities support specialty chemical import substitution financing for Maharashtra-based coating compounders. Gujarat's Mundra Port liquid bulk terminals facilitate raw material logistics for emerging hydrogenation capacity investments.
6 Hexanediol Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with feedstock-adjacent positions. The vendor base stratifies between integrated petrochemical conglomerates with captive adipic acid supply and merchant hydrogenation specialists serving regional offtake. Three archetypes dominate: integrated nylon-6,6 producers leveraging caprolactam co-product streams; standalone diol specialists optimizing continuous flow reactor yields; and Asia-Pacific scale players compressing unit costs through provincial manufacturing clusters. Capacity expansion and direct supply contracting constitute the dominant competitive moves, eroding distributor intermediation in industrial chemical procurement.
Among European integrated chemical producers, BASF SE and LANXESS occupy positions anchored by Rhine corridor infrastructure and regulatory dossier completeness. UBE Corporation exemplifies the Asia-Pacific archetype of caprolactam-adjacent hydrogenation integration. Fushun Tianfu Chemicals Co., Ltd represents the Chinese scale-driven tier competing on Liaoning province manufacturing density for domestic offtake.
| Leading Market Players |
|---|
| BASF SE |
| LANXESS |
| UBE Corporation |
| Evonik Industries AG |
| Perstorp Holding AB |
| Fushun Tianfu Chemicals Co., Ltd |
| Lishui Nanming Chemical Co., Ltd |
| Prasol Chemicals Ltd. |
| Shandong Yuanli Science and Technology Co., Ltd |
| Others |
Value Chain & Pricing Dynamics
The Port of Shanghai's chemical terminal throughput compresses logistics costs for Liaoning and Shandong producers, concentrating pricing power among integrated adipic acid hydrogenators while forcing merchant buyers into volume-commitment structures that differentiate industrial-grade spot purchases from pharmaceutical-grade contract premiums.
Pricing Analysis
Three-tier pricing structure across pharmaceutical, industrial, and technical grades separates USP-certified excipient supply from construction-sector bulk deliveries. Price differentiation centers on REACH dossier completeness and hydroxyl functionality certification, with German automotive OEMs absorbing premiums for documented purity. Cost compression in industrial-grade spot markets intensifies as Chinese hydrogenation yield improvements expand merchant supply. Construction sector buyers exhibit highest price sensitivity; pharmaceutical formulators prioritize regulatory documentation over unit economics.
Supply Chain Analysis
Adipic acid feedstock availability anchors supply concentration in China, Germany, and Japan, where caprolactam-adjacent operations and standalone hydrogenation units compete for regional offtake. Raw material dependencies span merchant adipic acid, methyl ester intermediates, and specialized hydrogenation catalysts. Single-source vulnerability concentrates in integrated nylon-6,6 producers allocating adipic acid during caprolactam demand surges. Distribution runs through direct mill-to-plant agreements in Asia-Pacific clusters, displacing traditional distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as waterborne polyurethane formulation advances penetrate low-VOC coating segments without solvent-borne performance sacrifice, accelerating specification shifts across automotive refinish and industrial maintenance applications.
For Market Incumbents: Insulate margin pools by completing REACH substance evaluation dossiers ahead of ECHA's 2024-2026 Community Rolling Action Plan scrutiny, while securing captive adipic acid supply through backward integration into hydrogenation capacity or long-term ester feedstock contracts. Propylene glycol substitution in economy-grade adhesives and emerging Indian domestic production capacity threaten established pricing structures. For New Entrants and Emerging Players: India's underpenetrated specialty chemical import substitution offers qualified local diol supply opportunities under BIS quality mandates, with Maharashtra-based coating compounders actively seeking European and Northeast Asian import replacements. Target pharmaceutical-grade certification as the most penetrable tier, leveraging USP and EP monograph compliance gaps to capture 3-4x industrial-grade margins through excipient and active pharmaceutical intermediate applications. For Investors and Strategic Acquirers: Continuous flow reactor technology specialists with skid-mounted hydrogenation unit deployment capabilities represent the priority acquisition archetype, as capital-light scale approaches fragment capacity geography and erode historical site-scale advantages. Monitor REACH authorization list placement for adipic acid derivatives as the critical inflection signal; early dossier completion by targets indicates defensive positioning against regulatory compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adipic Acid | Captive feedstock supply insulates against caprolactam demand surge allocation risks. |
| Pharmaceutical-Grade Certification Investment | USP and EP monograph compliance unlocks excipient margins at premium tier positioning. |
| Continuous Flow Reactor Deployment | Skid-mounted units enable mid-scale yield consistency without billion-dollar grassroots investment. |
| Direct Mill-to-Plant Supply Contracting | Annual volume commitments with Liaoning producers capture distributor margin compression. |
| Waterborne Polyurethane Formulation R&D | Low-VOC coating system advances expand addressable market beyond solvent-borne applications. |
Study Parameters
Operator-level perspectives from hydrogenation plant managers, polyurethane system house procurement leads, coatings formulators, and specialty chemical distribution channel partners anchored the qualitative base. Secondary validation drew from customs and trade data, Cefic and ACC industry reports, SEC 10-K chemical segment disclosures, and ECHA REACH registration databases. Bottom-up capacity and utilization estimates triangulated against top-down end-use consumption models across the analysis window.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning purity grade tier, coatings versus adhesives versus pharmaceutical end-use, bulk versus drum delivery mode, and regional production hub clustering. CAGRs derived from historical price-volume elasticity patterns and forward capacity announcement tracking, incorporating adipic acid hydrogenation yield improvement trajectories and REACH regulatory timeline assumptions as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by merchant hydrogenation specialists or accelerated Indian domestic capacity buildouts would shift outcomes beyond modeled ranges. Cross-checking against customs trade flow data and regional hydrogenation unit commissioning announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Latin America Construction Chemicals Market
Chemicals
Global Electronic Grade Phosphoric Acid Market
Chemicals
Aluminum Chemicals Market
Chemicals
Global Phosphorus Trichloride Market
Chemicals
Global Biotechnology-Based Chemical Market
Chemicals
North America Methanol Market
Chemicals
Concrete Surface Treatment Chemicals Market
Chemicals
Middle East and Africa Methyl Acrylate Market
Chemicals
Oxybenzone Market
Chemicals
Hexamethylenetetramine (HMTA) Market
Chemicals
Global Tetraacetylethylenediamine (TAED) Market
Chemicals
Non PVC Plasticizers Market
Chemicals
Acid Anhydrides Market
Chemicals
Hexamine Market
Chemicals
Global Amines Market
Chemicals
Global Fluorosilicic Acid Market