
 Concrete Surface Treatment Chemicals Market | 2026-2036
Concrete Surface Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Surface Treatment Chemicals Market Analysis
Industrial facility managers are unwinding historical reliance on residential contractors as the dominant buyer archetype for concrete surface treatment chemicals. Sika AG leverages its European manufacturing footprint to sustain leadership in epoxy flooring systems for logistics hubs. BASF SE anchors its position through backward integration into acrylic polymer feedstocks that serve water-based coating lines. Dow Inc. competes on specialty silane chemistry for penetrating sealants used in highway infrastructure.
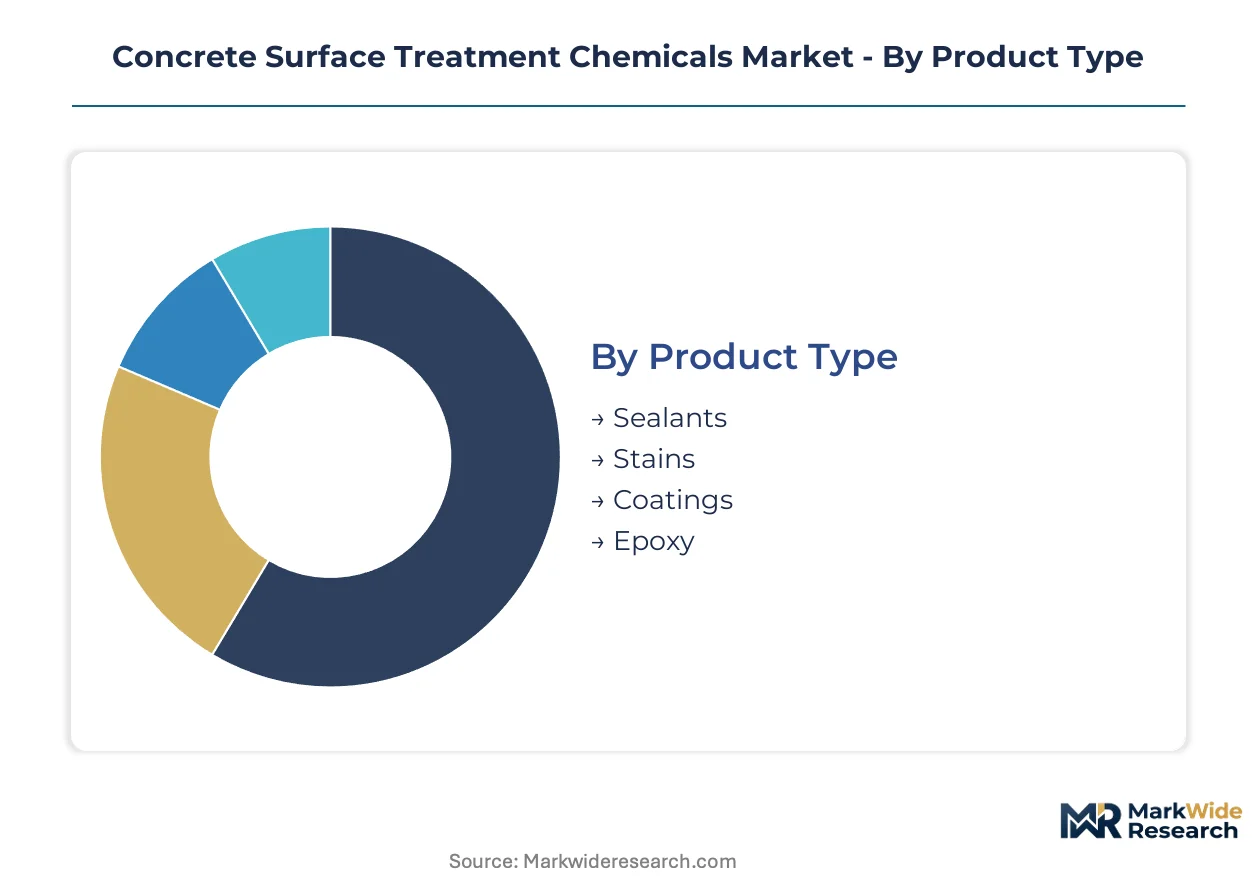
Concrete surface treatment chemicals encompass formulated preparations including silanes, siloxanes, epoxies, and acrylic dispersions applied to cured concrete to modify surface properties such as permeability, abrasion resistance, or aesthetic finish. These formulations typically achieve penetration depths of 2–5 millimeters for sealants or build dry-film thicknesses of 100–500 microns for coating systems, serving primarily to extend substrate service life in trafficked or chemically exposed environments. Epoxy coatings command the dominant share of product type value pools due to their superior chemical resistance in industrial flooring applications, while water-based technologies represent the fastest-expanding technology segment as environmental compliance tightens across jurisdictions. The commercial end-user category generates concentrated demand from retail and healthcare construction, whereas residential applications remain comparatively price-sensitive and fragmented.
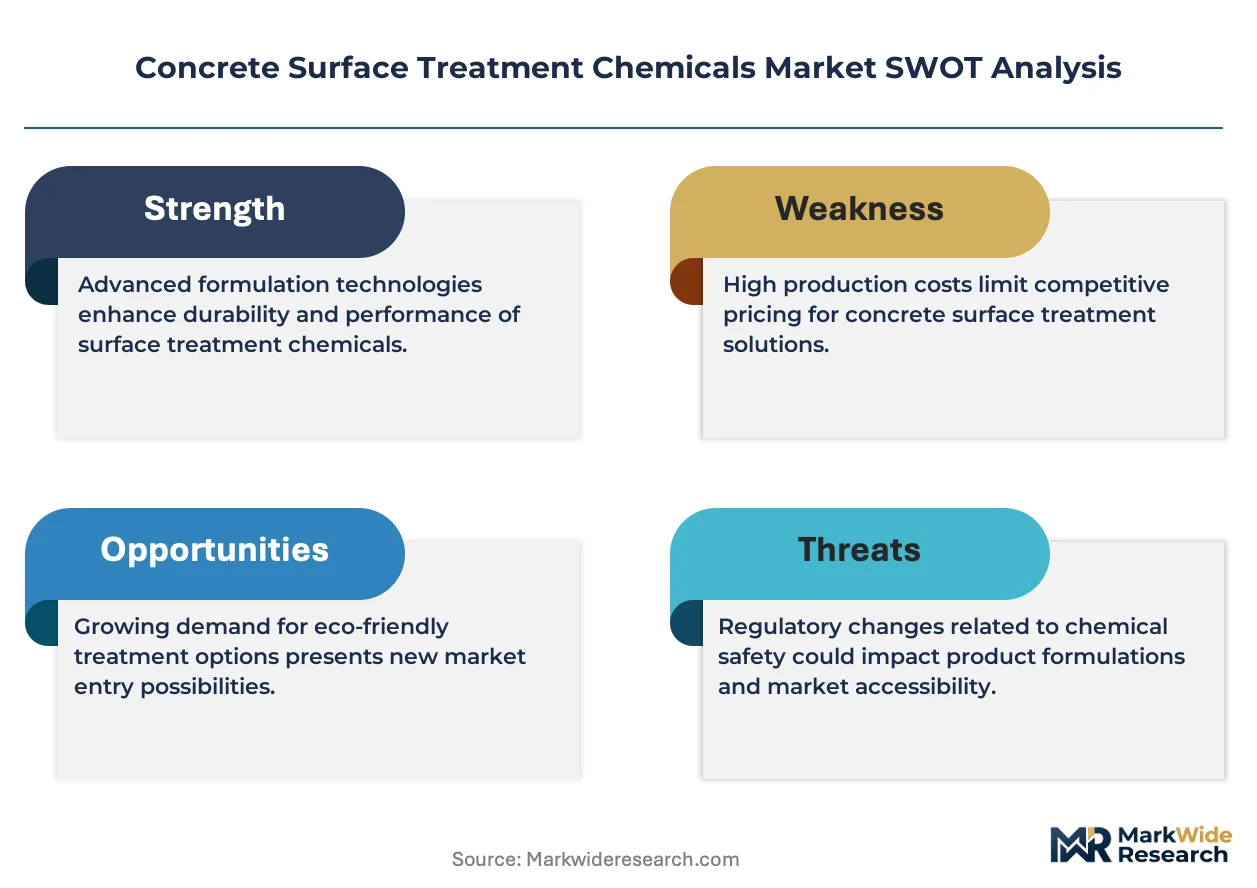
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based formulation production in the United States, while REACH registration requirements in Europe elevate compliance costs for imported epoxy hardeners. China's MEE enforces GB standards on VOC content that redirect domestic formulation toward water-borne and hybrid technologies. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional product registration or unified global formulation platforms offer superior capital efficiency.
Market Dynamics
Water-borne formulation chemistry is displacing solvent-based systems as the dominant platform for concrete surface treatment chemicals, driven by tightening VOC regulations across manufacturing jurisdictions and warehouse flooring specifications demanding lower environmental footprints during application.
Growth Catalysts
- REACH Phase-Down of Solvent Content:The European Chemicals Agency's progressive tightening of VOC thresholds in decorative and protective coatings redirects specification toward compliant water-based epoxies and hybrid silane systems in logistics construction.
- Epoxy Flooring in Cold Chain Infrastructure:Refrigerated warehouse operators specify high-build epoxy coatings for thermal shock resistance and chemical durability under pallet jack traffic, concentrating procurement in third-party logistics hubs.
- China's Coastal Manufacturing Reinvestment:Provincial infrastructure budgets in Jiangsu and Guangdong prioritize industrial floor refurbishment, generating concentrated demand for penetrating sealants in electronics and automotive assembly plants.
Market Restraints
- Petrochemical Feedstock Volatility:Epoxy resin prices fluctuate with bisphenol-A and epichlorohydrin supply disruptions, compressing margin predictability for coating formulators serving price-sensitive municipal infrastructure bids.
- Application Labor Scarcity:Skilled concrete surface preparation technicians remain concentrated in established industrial corridors, limiting deployment speed for large-scale warehouse projects in secondary logistics markets.
- Cure Time Requirements:Water-based epoxy systems require extended ambient temperature windows for full crosslinking, restricting application seasons in northern climates and compressing contractor scheduling flexibility.
Strategic Opportunities
- India's Industrial Corridor Expansion:Delhi-Mumbai Industrial Corridor and dedicated freight corridor projects generate underpenetrated demand for high-performance warehouse flooring specifications as foreign logistics operators establish greenfield distribution centers.
- Silane-Nanoparticle Convergence:Hybrid penetrating sealants combining alkylsilane chemistry with colloidal silica nanoparticles offer extended hydrophobic performance for highway infrastructure, opening specification in transportation departments seeking 15-year service life guarantees.
- Direct Contractor Platforms:Digital procurement channels connecting coating manufacturers with certified applicator networks bypass traditional distributor markups, capturing margin in fragmented residential and light commercial segments.
Industry Challenges
- Certification Timeline Compression:Multi-jurisdictional product registration for epoxy hardeners under REACH, EPA NESHAP, and China's MEE GB standards extends time-to-market by 18-24 months, straining R&D portfolio prioritization.
- Substrate Compatibility Complexity:Legacy concrete surfaces with unknown curing compound residues or previous sealant applications create specification failure risk, demanding costly job-site testing protocols before warranty issuance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Surface Treatment Chemicals Market |
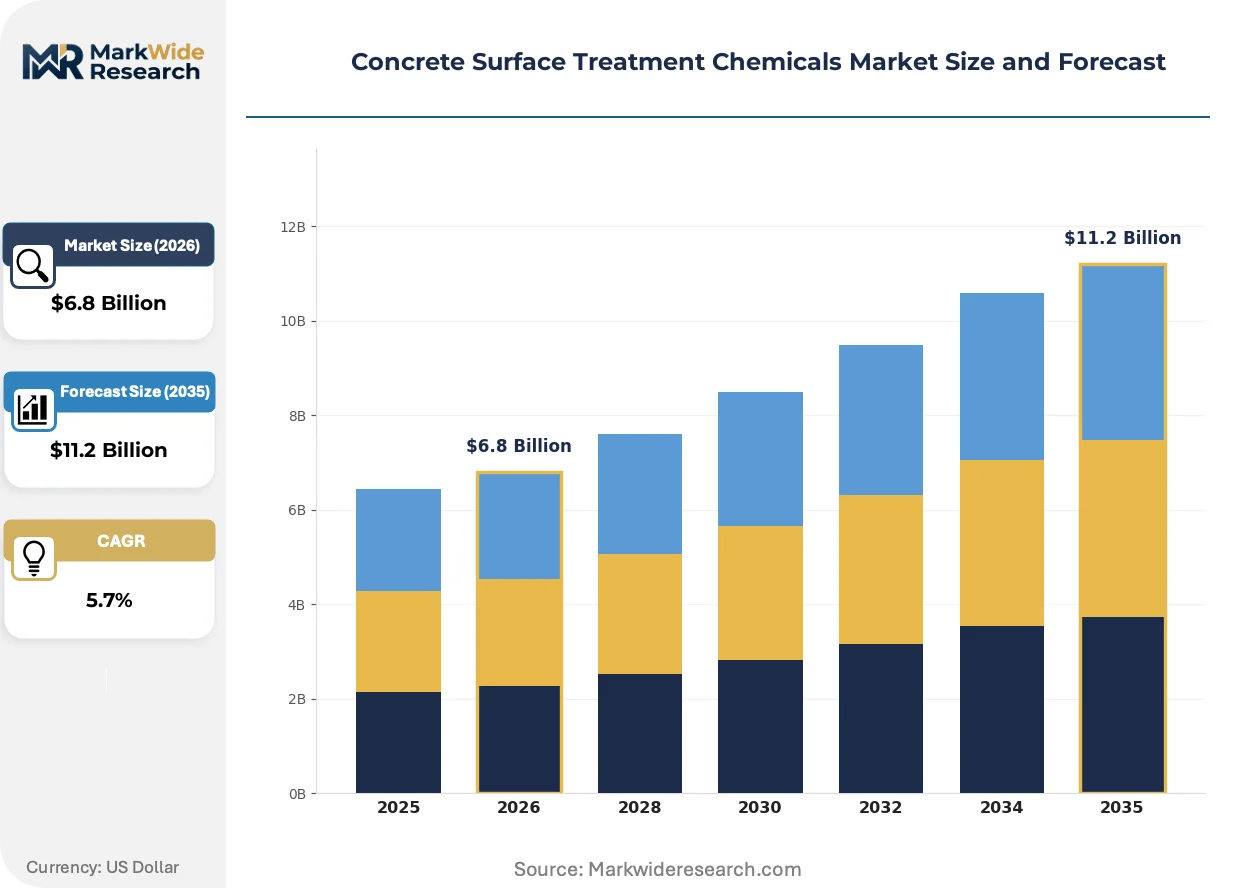
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
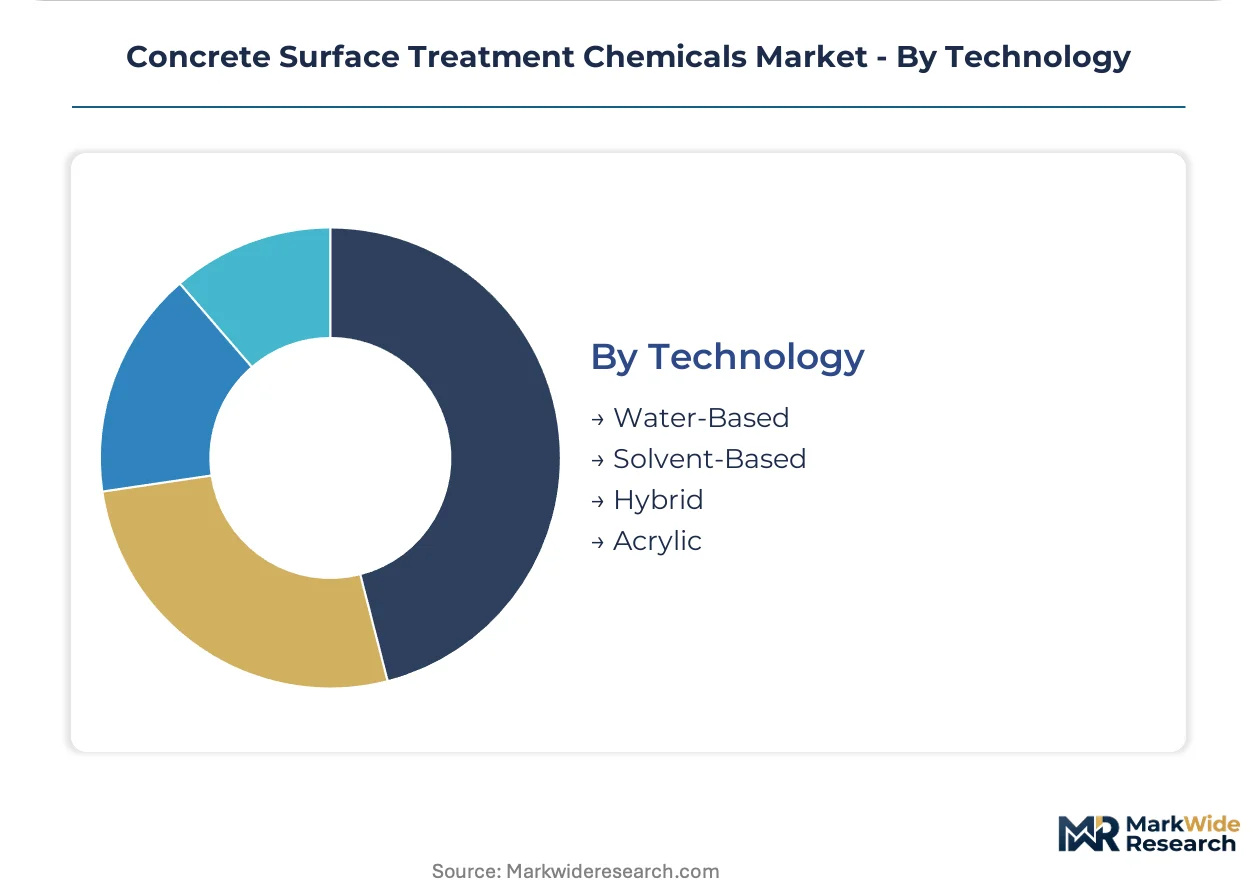
| Segmentation | Product Type: Sealants, Stains, Coatings, Epoxy Application: Flooring, Driveways, Pavements, Walls End User: Construction, Industrial, Residential, Commercial Technology: Water-Based, Solvent-Based, Hybrid, Acrylic |
| Companies Covered | Dow Inc., The Euclid Chemical Company, BASF SE, MAPEI S.p.A., RPM International Inc., Sika AG, Fosroc International Ltd., Akzo Nobel N.V., 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Surface Treatment Chemicals Market Emerging Trajectories
Formulation chemistry is splitting into parallel development tracks serving divergent performance and compliance requirements, while application methods and procurement channels undergo simultaneous digitization and specialization.
Hybrid water-borne epoxy technology is bifurcating the industrial flooring specification landscape. These systems combine acrylic-epoxy copolymer backbones to achieve solvent-grade chemical resistance with sub-100 g/L VOC content. Major third-party logistics operators in Germany and the Netherlands now mandate hybrid systems for new warehouse construction, compressing specification share for conventional high-solids epoxies in premium segments while leaving economy solvent-based products to compete solely on first-cost in developing markets.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants is intensifying compliance documentation for solvent-based concrete coating production facilities. Manufacturers must implement leak detection and repair programs for equipment handling hazardous air pollutants, elevating operating costs for smaller batch operations. This regulatory pressure concentrates production among facilities with capitalized emission control infrastructure, particularly affecting custom-color and small-volume specialty coating lines serving regional contractor markets.
Facility managers now specify performance-based warranty structures rather than material-only procurement for warehouse flooring projects. Contractors assume substrate preparation risk and long-term performance accountability, bundling surface profiling, coating application, and maintenance protocols into single-source agreements. This behavioral shift is most visible in North American retail distribution centers, where e-commerce fulfillment operators demand 10-year wear warranties backed by certified applicator networks with bonded capacity guarantees.
Concrete Surface Treatment Chemicals Market Segmentation
Concrete surface treatment chemicals flow through distinct procurement channels shaped by project scale, specification complexity, and contractor certification requirements. Each segment category carries different margin structures and technical support demands that determine manufacturer channel strategy.
Product Type:
Sealants and coatings dominate specification through distributor networks serving certified applicator pools, while stains and epoxies concentrate in direct contractor channels for large industrial projects.
- Sealants:Penetrating silane and siloxane formulations achieve 2–5 millimeter depth in concrete substrates. Demand concentrates in German highway rehabilitation projects where transportation departments specify 15-year hydrophobic performance guarantees under ECHA-compliant VOC thresholds.
- Coatings:Film-forming systems build 100–500 micron dry-film thickness for abrasion resistance. Warehouse operators in Jiangsu province specify high-build epoxy-acrylic hybrids for electronics manufacturing floors, prioritizing thermal shock resistance under automated guided vehicle traffic.
- Stains:Reactive metallic salt formulations penetrate concrete capillaries to produce decorative color effects. Residential contractors in secondary US markets favor water-based stains for garage floor upgrades, constrained by EPA NESHAP documentation requirements for solvent alternatives.
- Epoxy:Two-component thermoset systems achieve superior chemical resistance through crosslinked polymer networks. Cold chain logistics operators in the Netherlands mandate solvent-free formulations for refrigerated warehouse floors, eliminating thermal cycling failure risks.
By volume, Coatings leads. By growth pace, Epoxy is ahead.
Application:
Cost tier stratification separates premium industrial flooring specifications from price-sensitive residential driveway applications, with margin compression most severe in commoditized wall treatments.
- Flooring:Industrial specifications demand 10-year wear warranties backed by certified applicator networks. Third-party logistics operators in North American retail distribution centers bundle surface preparation, coating application, and maintenance protocols into single-source performance contracts.
- Pavements:Highway infrastructure departments specify silane-nanoparticle hybrids for bridge deck waterproofing. China's coastal provinces prioritize penetrating sealants for marine exposure zones under MEE GB standards compliance.
- Driveways:Residential applications remain fragmented across independent contractors with limited specification influence. Price sensitivity restricts technology adoption to economy solvent-based stains in developing markets lacking VOC enforcement infrastructure.
- Walls:Vertical surface treatments require modified rheology for sag resistance. Commercial construction in healthcare and education sectors specifies low-odor water-based acrylics for occupied building renovations.
Flooring commands the highest specification authority. Pavements show the steepest expansion trajectory as infrastructure reinvestment accelerates.
End User:
Customer type determines procurement complexity, with industrial buyers consolidating spend through framework agreements while residential demand fragments across thousands of small contractors.
- Industrial:Facility managers specify performance-based warranties rather than material-only procurement. Refrigerated warehouse operators in Germany and the Netherlands mandate hybrid water-borne epoxies with sub-100 g/L VOC content for new construction.
- Commercial:Retail and healthcare construction generates concentrated demand for aesthetic finishes with rapid return-to-service characteristics. US hospital renovation projects prioritize low-odor formulations enabling phased occupancy during application.
- Construction:General contractors balance first-cost pressures against long-term maintenance liability. Municipal infrastructure bids in price-sensitive markets default to economy solvent-based products where VOC enforcement remains limited.
- Residential:Homeowner-driven projects exhibit extreme price sensitivity and limited technical specification knowledge. Digital procurement platforms connecting manufacturers with certified applicators are capturing margin in this fragmented segment.
Industrial users drive premium technology adoption. Residential represents the largest addressable user base by project count.
Technology:
Supply concentration favors water-borne and hybrid platforms as regulatory pressure consolidates production among capitalized emission control facilities, while solvent-based capacity retreats to custom-color specialty lines.
- Water-Based:Acrylic-epoxy copolymer backbones achieve solvent-grade chemical resistance with compliant VOC profiles. Major logistics operators now mandate these systems, compressing specification share for conventional high-solids epoxies in premium segments.
- Hybrid:Silane-acrylic combinations penetrate concrete while forming breathable surface films. Highway departments in multiple jurisdictions are evaluating 15-year service life guarantees for nanoparticle-enhanced variants.
- Solvent-Based:Conventional high-solids epoxies retain economy positioning in developing markets. EPA NESHAP leak detection and repair programs elevate operating costs, concentrating production among facilities with capitalized emission control infrastructure.
- Acrylic:Pure acrylic dispersions serve decorative and light-duty protective applications. Extended cure time requirements restrict application seasons in northern climates, compressing contractor scheduling flexibility.
Water-Based leads by current volume penetration. Hybrid platforms are climbing the fastest as compliance thresholds tighten across manufacturing jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta port cluster underwrites China's dominance in industrial flooring demand, while Germany's Rhine-Alpine corridor anchors European specification standards for high-performance coatings.
United States
Cold chain logistics expansion drives specification of thermal-shock-resistant epoxy systems in Dallas-Fort Worth distribution hubs. EPA NESHAP enforcement elevates compliance costs for solvent-based production facilities, concentrating capacity among capitalized emission-control operations. Third-party logistics operators in the Inland Empire now mandate 10-year performance warranties backed by certified applicator networks.
Germany
Refrigerated warehouse construction in the Rhine-Ruhr corridor generates concentrated procurement of hybrid water-borne epoxies. ECHA REACH phase-down of VOC thresholds redirects specification toward compliant acrylic-epoxy copolymer systems. The Port of Rotterdam hinterland logistics zone anchors premium technology adoption across Benelux-connected distribution infrastructure.
China
Jiangsu and Guangdong provincial infrastructure budgets prioritize industrial floor refurbishment in electronics and automotive assembly plants. MEE GB standards on VOC content redirect domestic formulation toward water-borne and hybrid technologies. The Yangtze River Delta manufacturing belt generates the steepest demand concentration for penetrating sealants in semiconductor fabrication facilities.
India
Delhi-Mumbai Industrial Corridor projects generate underpenetrated demand for high-performance warehouse flooring as foreign logistics operators establish greenfield distribution centers. BIS certification requirements for imported epoxy hardeners extend registration timelines. The Mumbai-Pune logistics cluster concentrates early specification adoption among multinational third-party operators.
Netherlands
Rotterdam port logistics and Schiphol cargo corridors drive specification of solvent-free epoxy formulations for refrigerated warehouse floors. EU Green Deal compliance timelines accelerate warehouse operator procurement decisions. The Randstad logistics ring anchors European adoption of performance-based warranty structures bundling surface preparation and long-term maintenance protocols.
Concrete Surface Treatment Chemicals Market Vendor Landscape
Concentration sits with diversified chemical conglomerates possessing backward integration into acrylic polymer and epoxy resin feedstocks. The vendor base stratifies across three tiers: global formulation leaders with multi-jurisdictional registration capabilities, regional specialists serving certified applicator networks, and commodity producers competing on first-cost in price-sensitive municipal bids. Dominant competitive moves include capacity consolidation among emission-compliant production facilities and strategic partnerships between coating manufacturers and digital procurement platforms connecting directly to certified contractor networks.
Among European-based diversified chemical groups, BASF SE and Sika AG exemplify the integrated formulation archetype combining captive feedstock supply with multi-jurisdictional product registration capabilities. Dow Inc. occupies a position among North American specialty chemical producers leveraging silane chemistry expertise for infrastructure penetration. MAPEI S.p.A. represents the Mediterranean-origin construction chemical specialist archetype with concentrated presence in flooring system specification. These three anchors illustrate divergent strategic postures: feedstock integration, specialty chemistry depth, and construction-sector vertical focus.
| Leading Market Players |
|---|
| Dow Inc. |
| The Euclid Chemical Company |
| BASF SE |
| MAPEI S.p.A. |
| RPM International Inc. |
| Sika AG |
| Fosroc International Ltd. |
| Akzo Nobel N.V. |
| 3M Company |
| Others |
Supply Flow & Price Mechanics
REACH Phase-Down of VOC thresholds gates both supply qualification and price differentiation simultaneously, concentrating production among emission-compliant facilities while compressing margins for non-compliant batch operations. Certification timelines extend 18-24 months across ECHA, EPA NESHAP, and China's MEE GB standards, forcing formulators to absorb compliance premiums or surrender specification share in premium segments.
Pricing Analysis
Volume-discount tiering separates certified applicator framework agreements from spot-market municipal bids. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and warranty duration, with hybrid water-borne epoxies commanding premium positioning against solvent-based alternatives. Pricing pressure stems from bisphenol-A and epichlorohydrin feedstock volatility compressing margin predictability. Municipal infrastructure buyers exhibit highest price sensitivity; cold chain logistics operators demonstrate lowest sensitivity due to performance-based procurement mandates.
Supply Chain Analysis
Germany and China anchor epoxy resin and acrylic polymer production for concrete surface treatment formulations. Raw material supply draws from petrochemical feedstocks, colloidal silica nanoparticles, and specialty silane monomers. Single-source vulnerability concentrates in epichlorohydrin supply chains tethered to chlor-alkali co-production economics. Distribution runs through certified applicator networks for industrial flooring, with direct manufacturer-to-contractor platforms gaining share in fragmented residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial construction cycles are recovering from pandemic-depressed warehousing investment, with cold chain infrastructure expansion driving specification velocity for thermal-shock-resistant systems.
For Market Incumbents: Consolidate production capacity among REACH-compliant facilities to defend specification share against regional formulators lacking multi-jurisdictional registration capabilities. Backward integration into acrylic polymer feedstocks anchors margin control as water-borne technology displaces solvent-based alternatives. Acquire certified applicator networks to capture performance-based warranty bundling value in North American retail distribution. For New Entrants and Emerging Players: Differentiate on silane-nanoparticle hybrid chemistry for highway infrastructure applications where 15-year service life guarantees remain underpenetrated. Target India's Delhi-Mumbai Industrial Corridor for greenfield warehouse flooring specifications as foreign logistics operators establish distribution centers. Deploy digital procurement platforms connecting directly with residential contractors to bypass traditional distributor markups in price-sensitive segments. For Investors and Strategic Acquirers: EPA NESHAP enforcement intensity reshapes the acquisition landscape toward emission-control-capitalized production assets. Five-to-ten-year viability favors formulators with captive feedstock supply and multi-jurisdictional product registration infrastructure. Monitor BIS certification timeline compression for imported epoxy hardeners into India as inflection indicator for regional market access friction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Polymers | BASF SE's captive feedstock supply secures margin stability for water-borne coating lines. |
| Capacity Expansion in Emission-Compliant Facilities | Sika AG's European manufacturing footprint sustains leadership in epoxy flooring for logistics hubs. |
| Long-term Supply Agreement with Certified Applicators | Performance-based warranties bundle surface preparation and maintenance protocols for 10-year wear guarantees. |
| Joint Venture for Silane-Nanoparticle Development | Dow Inc.'s specialty chemistry expertise opens transportation department specifications for highway infrastructure. |
| Green Manufacturing Transition to Water-Borne Platforms | Hybrid acrylic-epoxy copolymer systems achieve solvent-grade resistance with sub-100 g/L VOC content. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, and Cefic industry reports. Plant managers at coating formulation facilities, procurement leads at third-party logistics operators, distribution channel partners, and technical R&D directors provided demand-side and supply-side perspectives. Bottom-up volume modeling triangulated against top-down value estimates across product type, application, end user, and technology segments.
Segmentation dimensions modeled include formulation chemistry platform, substrate application method, warranty structure tier, and regional regulatory compliance cluster. CAGRs derived from regression analysis of historical volume trajectories and forward projection of specification adoption curves. Forecast inputs incorporated VOC threshold phase-down schedules, cold chain infrastructure investment pipelines, and provincial infrastructure budget allocations.
Material uncertainties — feedstock price volatility, certification timeline extensions, substrate compatibility failures — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and industrial construction cycle recovery. Recalibration cycles align with material shifts in MEE GB standard revisions and EPA NESHAP enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Tetrapotassium Pyrophosphate Market
Chemicals
Global E Series Glycol Ether Market
Chemicals
Germany Methanol Market
Chemicals
Thioacetic Acid Market
Chemicals
Industrial Odor Management Market
Chemicals
Potassium Alum Market
Chemicals
RDX and HMX Market
Chemicals
Electronic Grade Choline Hydroxide Market
Chemicals
Sulfuric Acid Market
Chemicals
Methanol to Gasoline Market
Chemicals
Middle East Construction Chemicals Market
Chemicals
1, 4 Butanediol Market
Chemicals
Precious Metal Plating Chemicals Market
Chemicals
Ferric Oxide Market
Chemicals
Sodium Tripolyphosphate (STPP) Market
Chemicals
3-Fluoro-5-Nitrotoluene Market