
 Hexamine Market | 2026-2036
Hexamine Market Size, Share, and Industry Trends Forecast 2026-2036
Hexamine Market Intelligence
Project finance tied to ammonia-derivative complexes is reconfiguring capital barriers for new hexamine entrants. Chemanol leverages its methanol feedstock integration to sustain cost advantages across Middle Eastern supply corridors. Metafrax anchors its position through captive formaldehyde output, while Hexion dominates specialty resin formulations that absorb premium-grade crystalline hexamine.
Hexamine, also known as methenamine or hexamethylenetetramine, is a heterocyclic organic compound with the formula C₆H₁₂N₄, synthesized via the condensation of formaldehyde and ammonia under controlled pH conditions; it functions primarily as a chemical intermediate, curing agent, and fuel source across industrial and pharmaceutical systems. The powder segment leads volume throughput due to its compatibility with bulk resin manufacturing, while fuel tablet applications extend into military and recreational heating markets where portability commands margin premiums. Pharmaceutical-grade crystals occupy a narrower but higher-margin niche tied to urinary antiseptic formulations and controlled-release drug matrices.
EPA standards govern formaldehyde emissions from resin curing operations in the United States, while REACH registration requirements in Europe enforce traceability and hazard communication across the hexamine value chain. China's GB standards and evolving MEE directives on volatile organic compound emissions are tightening process controls for domestic manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions to align certification investments with destination-market access requirements.
Market Dynamics
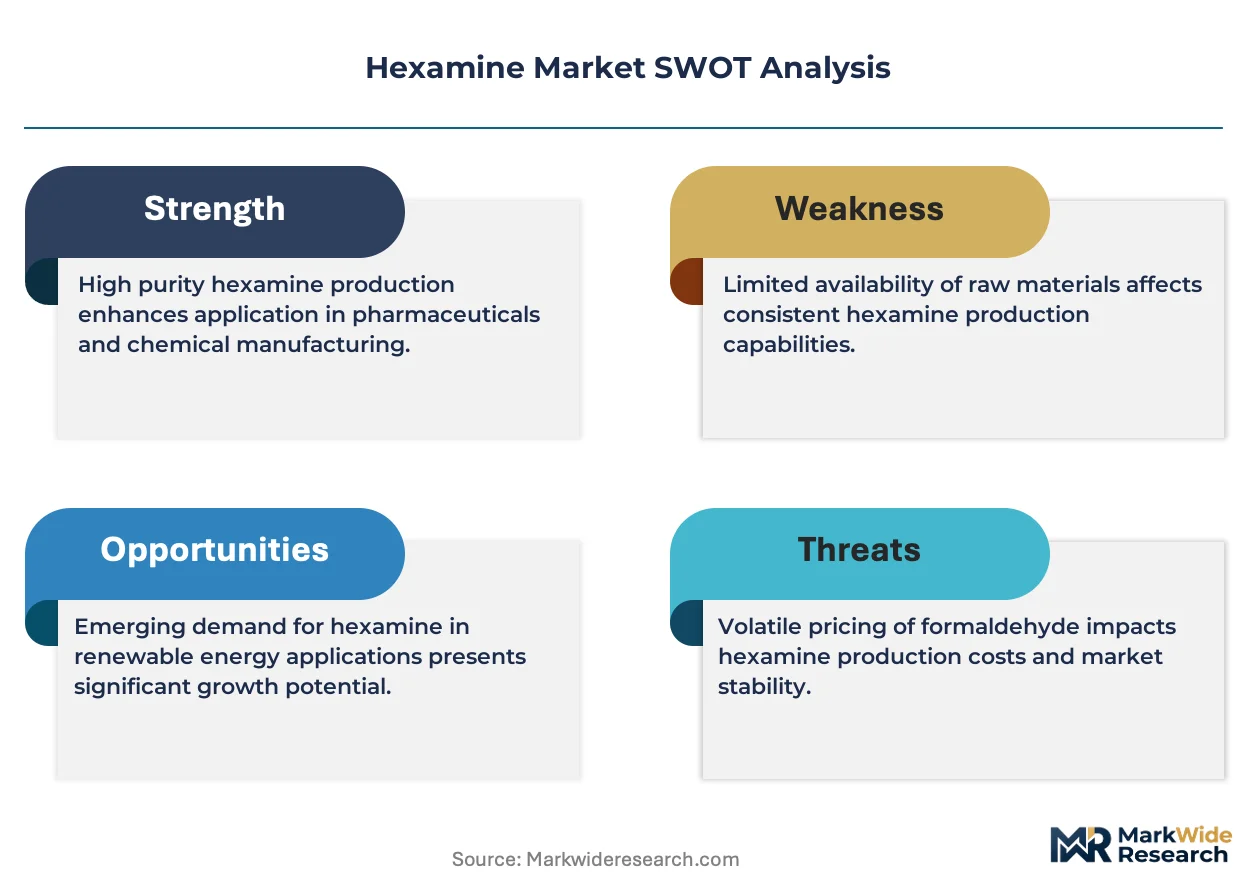
Formaldehyde-ammonia feedstock volatility is compressing margin structures for non-integrated hexamine producers while resin-grade purity specifications tighten under evolving emissions frameworks across multiple jurisdictions.
Growth Catalysts
- Phenolic resin demand:Automotive lightweighting programs in Germany and Japan are expanding hexamine consumption for high-temperature brake linings and electrical laminates. Powder-grade material throughput rises with each new vehicle platform launch.
- REACH substance registration:ECHA's updated dossier requirements for hexamine derivatives are accelerating documentation investments among European formulators, filtering out marginal suppliers and consolidating procurement toward certified producers.
- Methenamine pharmaceutical synthesis:Urinary antiseptic production in Indian pharmaceutical clusters is drawing crystalline hexamine volumes away from industrial applications, tightening pharmaceutical-grade availability.
Market Restraints
- Natural gas price volatility:Methanol production costs swing with Henry Hub and TTF benchmarks, transmitting instability to formaldehyde feedstock pricing for hexamine synthesis.
- East Asian supply concentration:Shandong and Jiangsu provinces host over sixty percent of global crystallization capacity, creating geographic vulnerability to regional energy rationing or environmental enforcement actions.
- Substitute curing agents:Phenolic resin formulators in North America are trialing paraformaldehyde and resole systems that reduce or eliminate hexamine loading in specific applications.
Strategic Opportunities
- Middle East methanol integration:Saudi Arabian and Qatari producers with captive methanol-to-formaldehyde streams can backward-integrate into hexamine at feedstock cost structures unavailable to European or North American competitors.
- Military fuel tablet specifications:NATO standardization of solid fuel chemistry for field rations is opening qualification pathways for hexamine tablet producers meeting specific calorific and ignition protocols.
- India PLI scheme alignment:Pharmaceutical manufacturing incentives under India's production-linked incentive framework are expanding domestic methenamine API capacity, reducing import dependence for urinary antiseptic production.
Industry Challenges
- Process safety certification timelines:Seveso III compliance for formaldehyde handling facilities in Europe extends permitting cycles by fourteen to twenty-four months, delaying capacity additions.
- Analytical chemistry talent scarcity:Pharmaceutical-grade hexamine production requires chromatographic purity verification capabilities that compete for limited skilled labor pools with biologics manufacturing sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hexamine Market |
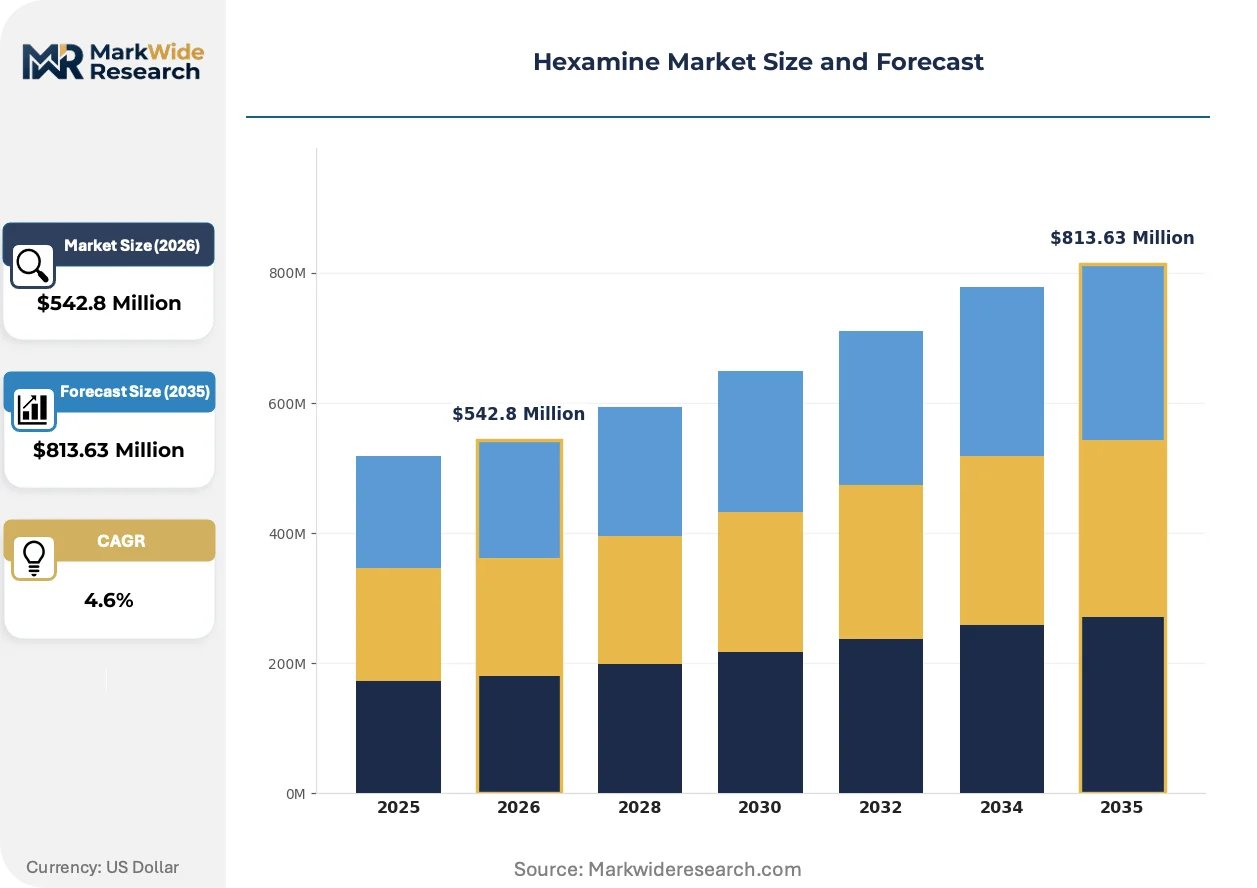
| Market Size in 2026 | $542.8 Million |
| Market Size in 2035 | $813.63 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Crystals, Tablets End Use Industry: Plastics, Paints, Pharmaceutical, Agriculture Application: Resin Production, Fuel Tablets, Adhesives, Explosives Packaging Type: Bags, Drums, Containers, Bulk |
| Companies Covered | Methanol Chemicals Company (Chemanol), Metafrax Group, Hexion Inc., Shchekinoazot JSC, INEOS Group Holdings S.A., Mitsubishi Gas Chemical Company, Inc., Simalin Chemical Industries Pvt Ltd., Huntsman Corporation, Kanoria Chemicals & Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hexamine Market Strategic Shifts & Innovations
Continuous crystallization technology and regulatory data transparency requirements are reconfiguring production economics and competitive positioning across hexamine supply tiers.
Membrane filtration is hybridizing with conventional evaporative crystallization in hexamine production trains. European specialty chemical producers are retrofitting existing assets with ceramic membrane modules to reduce energy intensity in pharmaceutical-grade crystal recovery. This technology convergence is compressing payback periods for purity upgrades while displacing legacy solvent-wash purification steps.
EPA formaldehyde emission standards under TSCA Title VI are tightening permissible off-gassing from composite wood products that use hexamine-cured resins. Panel manufacturers in the United States are reformulating resin recipes or investing in emission capture systems to maintain market access. The regulatory pressure falls most heavily on particleboard and medium-density fiberboard segments serving residential construction.
Specification-driven procurement is consolidating hexamine buying among resin formulators with in-house analytical capabilities. Tier-one automotive suppliers in Germany and Japan are requiring lot-specific purity certificates and traceable formaldehyde sourcing documentation, displacing spot-market purchasing for critical applications. This behavioral shift is most visible in electrical laminate supply chains serving semiconductor packaging substrate manufacturers.
Hexamine Market Segmentation
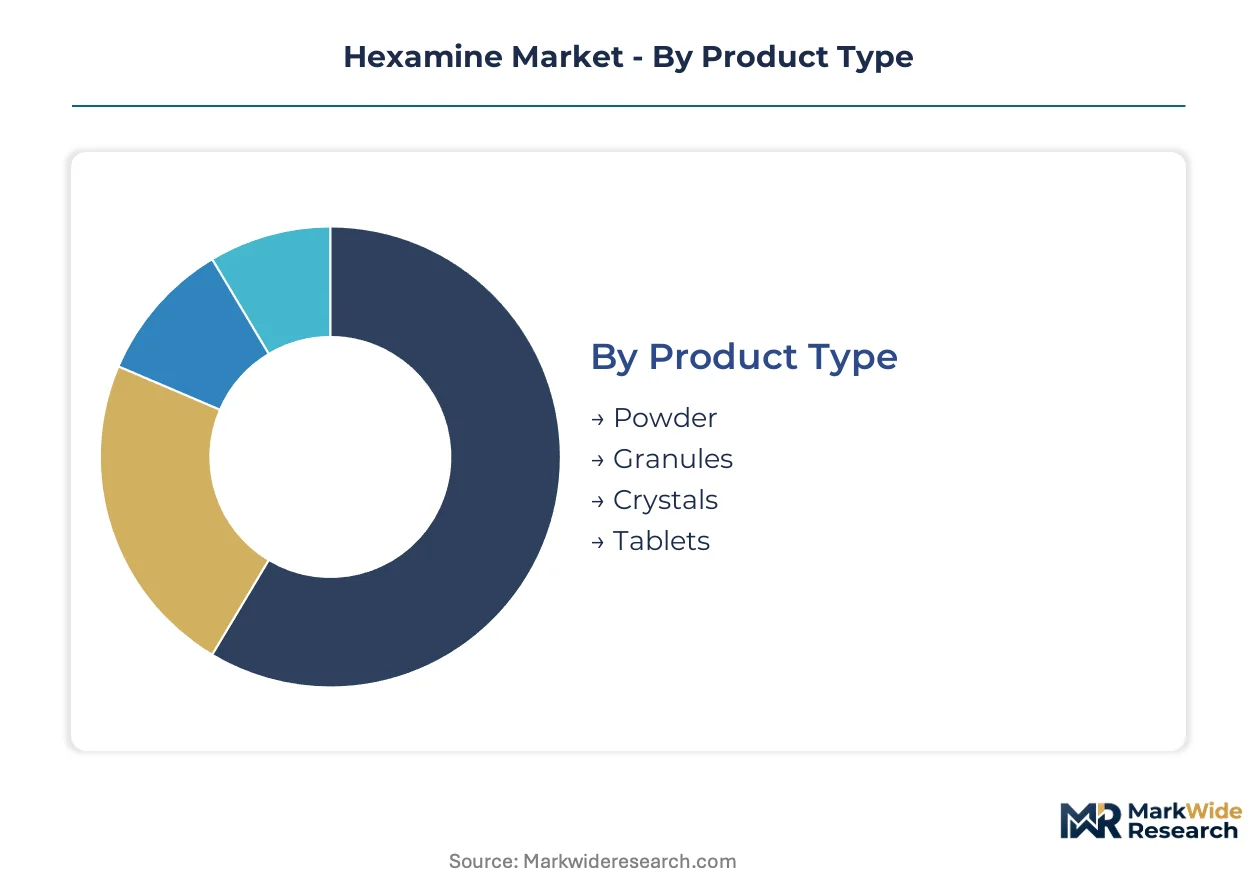
Hexamine segmentation reflects divergent purity requirements and handling protocols across pharmaceutical synthesis, resin curing, and fuel combustion applications. Each segment carries distinct regulatory footprints and procurement patterns that reshape supplier economics and customer loyalty structures.
Product Type:
After-sales service intensity varies sharply across physical forms, with crystalline grades demanding chromatographic certification support and tablet formulations requiring military specification compliance documentation.
- Powder:Fine particulate hexamine dominates bulk resin manufacturing through rapid dissolution kinetics and uniform distribution in phenolic curing reactions. Automotive brake lining producers in Germany and Japan specify powder-grade material for high-temperature composite formulations. By volume, powder leads. By growth pace, pharmaceutical crystals are ahead.
- Crystals:High-purity crystalline hexamine meets USP and EP pharmacopoeia specifications for methenamine API synthesis. Indian pharmaceutical clusters in Hyderabad and Ahmedabad are expanding crystalline procurement for urinary antiseptic production under CDSCO oversight.
- Granules:Intermediate particle size reduces dust exposure during resin compounding operations. Foundry binder applications in China's Shandong province favor granules for controlled release in sand mold curing.
- Tablets:Compressed hexamine serves military field ration heating and recreational camping fuel markets. NATO standardization protocols govern calorific content and ignition reliability specifications.
Powder commands the largest throughput position. Pharmaceutical crystals generate the steepest margin expansion trajectory.
End Use Industry:
Cost tier stratification separates commodity resin feedstock buyers from pharmaceutical manufacturers paying purity premiums.
- Plastics:Phenolic and amino resin production consumes hexamine as a formaldehyde-releasing curing agent. Panel manufacturers in the United States face EPA TSCA Title VI emission limits that are reformulating resin recipes.
- Pharmaceutical:Methenamine synthesis for urinary tract antiseptics requires crystalline grades with heavy metal limits below 10 ppm. India's PLI scheme is expanding domestic API capacity in Gujarat and Maharashtra.
- Paints:Alkyd and epoxy coating formulations use hexamine as a latent hardener for corrosion-resistant industrial finishes. Marine coating producers in Japan specify low-ash grades for shipyard applications.
- Agriculture:Controlled-release nitrogen fertilizers and soil fumigation applications utilize technical-grade material. Brazil's ANVISA-regulated agrochemical formulators are evaluating hexamine derivatives for nematode control.
Plastics generates the highest absolute consumption. Pharmaceutical applications deliver the fastest value-per-tonne gains.
Application:
Volume concentration in resin production contrasts with niche premium capture in military fuel tablets.
- Resin Production:Hexamine functions as a crosslinking catalyst in phenolic resins for electrical laminates and friction materials. Semiconductor packaging substrate manufacturers in Taiwan and South Korea specify ultra-low free formaldehyde grades.
- Fuel Tablets:Solid fuel chemistry for field rations demands precise calorific density and smokeless combustion. Saudi Arabian producers are qualifying for NATO standardization pathways.
- Adhesives:Wood bonding applications use hexamine-reinforced urea-formaldehyde resins for plywood and particleboard. The United States EPA emission standards are pressuring reformulation toward reduced hexamine loading.
- Explosives:Hexamine serves as a precursor in RDX synthesis for defense and mining applications. Strict international precursor controls govern trade flows and end-user certification.
Resin production anchors volume demand. Fuel tablets are climbing the fastest on specification-driven procurement.
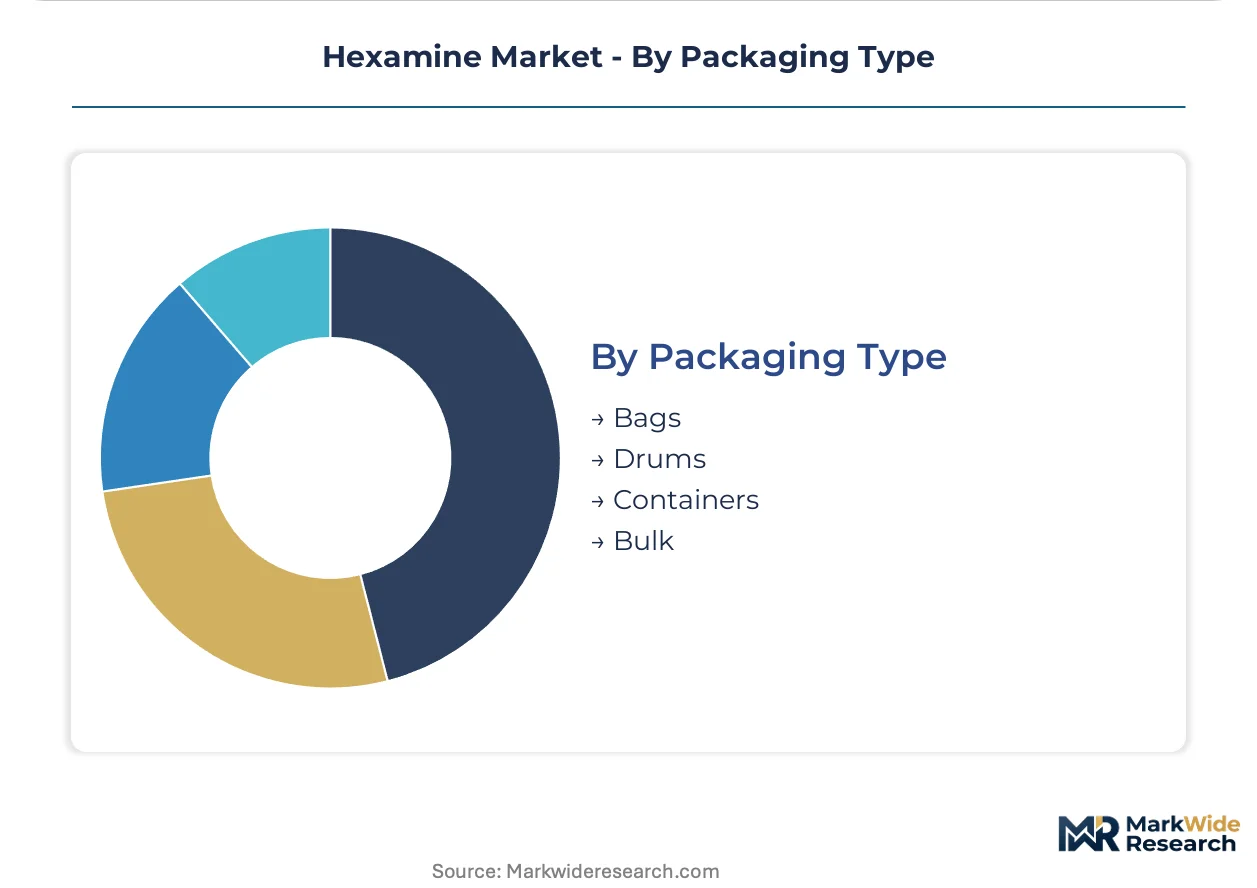
Packaging Type:
Customer type segmentation separates bulk terminal operators from drum-handling specialty chemical distributors.
- Bulk:Tanker and hopper car deliveries serve integrated resin manufacturers with dedicated unloading infrastructure. Large phenolic producers in Germany's Ruhr region contract annual bulk volumes.
- Drums:Steel and fiber drums accommodate mid-scale pharmaceutical and adhesive formulators requiring lot traceability. REACH-compliant labeling and SDS documentation accompany drum shipments.
- Bags:Multi-wall paper and woven polypropylene bags target foundry and agricultural users with moderate consumption rates. China's GB standards govern bag construction and hazard labeling.
- Containers:Intermediate bulk containers and totes serve regional distributors supplying fragmented coating and explosives manufacturers. Container tracking systems enable formaldehyde source documentation.
Bulk shipments dominate tonnage movements. Container formats are gaining share fastest among specialty chemical distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are redrawing hexamine trade corridors, with feedstock-integrated producers in the Middle East and Asia capturing incremental volume from European and North American buyers facing formaldehyde cost volatility. Regional regulatory divergence on formaldehyde emissions and pharmaceutical purity standards is fragmenting certification requirements across destination markets.
China
Phenolic resin production for automotive brake linings and semiconductor packaging substrates drives crystalline hexamine consumption in Jiangsu and Shandong provinces. MEE directives on volatile organic compound emissions are tightening process controls for domestic manufacturers. The Yangtze River Delta hosts over sixty percent of global crystallization capacity, concentrating supply vulnerability to regional energy rationing.
Germany
Automotive lightweighting programs for high-temperature brake linings and electrical laminates expand powder-grade procurement from Ruhr region resin formulators. ECHA's updated REACH dossier requirements for hexamine derivatives accelerate documentation investments among European formulators. Bavarian specialty chemical producers are retrofitting assets with ceramic membrane modules to reduce energy intensity in pharmaceutical-grade crystal recovery.
United States
Panel manufacturers serving residential construction face EPA TSCA Title VI emission limits that are reformulating hexamine-cured resin recipes toward reduced loading. The agency's formaldehyde standards for composite wood products are pressuring investment in emission capture systems. Southeast distribution hubs are consolidating procurement toward certified producers with in-house analytical capabilities.
India
Pharmaceutical manufacturing incentives under the PLI scheme are expanding domestic methenamine API capacity for urinary antiseptic production. CDSCO oversight of crystalline hexamine procurement is tightening heavy metal limits below 10 ppm for API synthesis. Hyderabad and Ahmedabad pharmaceutical clusters are drawing crystalline volumes away from industrial applications.
Saudi Arabia
Captive methanol-to-formaldehyde streams enable backward integration into hexamine at feedstock cost structures unavailable to European competitors. Saudi producers are qualifying for NATO standardization pathways for military fuel tablet specifications. The Eastern Province's ammonia-derivative complexes are reconfiguring capital barriers for new regional entrants.
Hexamine Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying feedstock or intermediate grades to formulators with end-market relationships. The vendor base stratifies across methanol-integrated petrochemical conglomerates, formaldehyde-captive resin specialists, and pharmaceutical-grade refiners. Three archetypes dominate: feedstock-integrated Middle Eastern producers, European specialty chemical refiners with membrane filtration capabilities, and Asian volume manufacturers serving resin bulk demand. Competitive moves center on backward integration into methanol-formaldehyde chains and purity upgrade investments for pharmaceutical certification.
Among Middle Eastern petrochemical conglomerates, Methanol Chemicals Company (Chemanol) exemplifies feedstock-integrated positioning through its methanol feedstock advantages. Metafrax Group occupies a position within the formaldehyde-captive archetype, while Hexion Inc. represents specialty resin formulation dominance that absorbs premium-grade crystalline material. These three anchors illustrate how competitive advantage accrues to players controlling upstream inputs or downstream specification compliance.
| Leading Market Players |
|---|
| Methanol Chemicals Company (Chemanol) |
| Metafrax Group |
| Hexion Inc. |
| Shchekinoazot JSC |
| INEOS Group Holdings S.A. |
| Mitsubishi Gas Chemical Company, Inc. |
| Simalin Chemical Industries Pvt Ltd. |
| Huntsman Corporation |
| Kanoria Chemicals & Industries Ltd. |
| Others |
Cost & Logistics Intelligence
Yangtze River Delta port congestion amplifies freight cost volatility for crystalline hexamine shipments, compressing margins for European pharmaceutical buyers while rewarding Shandong-based producers with captive formaldehyde supply. This logistics corridor's cost dynamics concentrate pricing power among methanol-integrated Middle Eastern suppliers and fragment procurement leverage for North American resin formulators facing Henry Hub gas price swings.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across pharmaceutical-grade premiums, resin-grade standard tiers, and technical-grade economy levels. Price differentiation hinges on USP/EP certification status and lot-specific chromatographic documentation, with automotive brake lining producers in Germany showing lowest sensitivity while agricultural formulators in Brazil face acute cost compression. Pricing pressure intensifies from paraformaldehyde substitution trials in North American phenolic resin applications, forcing crystalline grade suppliers to absorb documentation costs to maintain pharmaceutical contracts.
Supply Chain Analysis
Formaldehyde and ammonia feedstock sourcing draws from methanol production clusters concentrated in Saudi Arabia, China, and Trinidad. Raw material dependencies center on natural gas benchmarks, merchant methanol spot markets, and ammonia derivative complex output. Single-source vulnerability runs through Shandong and Jiangsu crystallization capacity exceeding sixty percent of global pharmaceutical-grade supply. Distribution runs through bulk tanker deliveries to integrated resin manufacturers, steel drum shipments for pharmaceutical formulators, and containerized totes serving regional coating distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hexamine incumbents face sustained substitution pressure from paraformaldehyde and resole curing systems that threaten resin-grade volume anchors. Defense requires building structural moats around feedstock integration and certification barriers that emerging entrants cannot replicate quickly.
For Market Incumbents: Build backward integration moats through captive methanol-to-formaldehyde streams that neutralize Henry Hub volatility exposure. Secure Seveso III process safety certification ahead of European competitors to extend permitting timelines as a defensive barrier against capacity additions. Anchor pharmaceutical-grade positions through chromatographic purity verification capabilities that compete for scarce analytical chemistry talent pools. For New Entrants and Emerging Players: Build out military fuel tablet qualification pathways under NATO standardization protocols where Saudi Arabian methanol integration has not yet penetrated. Target Indian pharmaceutical clusters in Hyderabad and Ahmedabad leveraging PLI scheme incentives for methenamine API capacity expansion. Establish go-to-market presence through CDSCO-compliant documentation support that incumbent commodity producers underserve. For Investors and Strategic Acquirers: Formaldehyde-captive resin specialists with membrane filtration retrofit capabilities represent the most defensible acquisition archetype for pharmaceutical-grade margin capture. Long-term viability hinges on positioning ahead of EPA TSCA Title VI emission standard tightening that will consolidate procurement toward certified producers. Watch for ECHA REACH dossier update timelines as inflection indicators for European formulator consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methanol-Formaldehyde Chain | Chemanol's feedstock cost advantages demonstrate margin protection against Henry Hub volatility. |
| Ceramic Membrane Filtration Retrofit | Bavarian specialty chemical producers compress pharmaceutical-grade crystal recovery energy intensity. |
| NATO Military Fuel Tablet Qualification | Saudi Arabian producers open specification-driven procurement pathways with calorific standard compliance. |
| Seveso III Process Safety Certification | European incumbents extend permitting cycles to delay competitor capacity additions. |
| India PLI Scheme Alignment for Methenamine API | Domestic crystalline capacity expansion reduces import dependence for urinary antiseptic production. |
Research Approach
Operator-level perspectives from phenolic resin plant managers, pharmaceutical procurement leads at Indian API manufacturers, automotive brake lining compounders in Germany, and ceramic membrane technology suppliers anchored the qualitative base. Secondary validation drew from ECHA REACH dossier filings, EPA TSCA Title VI compliance disclosures, CDSCO pharmaceutical import records, and ACC chemical trade data. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Scenario-bracketing framed volume and value outputs across powder, crystalline, granule, and tablet product tiers intersecting with plastics, pharmaceutical, paints, and agriculture end-use industries. CAGRs derived from regression analysis of formaldehyde feedstock cost trajectories, regulatory enforcement intensity indices, and substitution elasticity parameters for paraformaldehyde curing systems. Modeling incorporated MEE VOC directive compliance timelines and NATO standardization protocol adoption curves as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Middle Eastern methanol conglomerates or rapid membrane filtration adoption by European refiners would shift outcomes. Cross-checking against EIA natural gas price benchmarks and ECHA substance registration timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Hydrogen Fluoride Market
Chemicals
Trichlorosilane Market
Chemicals
Pyrogallol Market
Chemicals
Oxybenzone Market
Chemicals
Hypophosphorous Acid Market
Chemicals
Carbon Tetrabromide Market
Chemicals
Airbag Propellant Chemicals Market
Chemicals
China Inorganic Iodide Market
Chemicals
Anticoagulant Rodenticides Market
Chemicals
Fireworks Market
Chemicals
Hexafluorosilicic Acid Market
Chemicals
Phosgene Market
Chemicals
Flame Retardants Chemicals Market
Chemicals
Automotive Appearance Chemicals Market
Chemicals
United States Construction Chemicals Market
Chemicals
Welding Chemicals Market