
 Global Fluorosilicic Acid Market | 2026-2036
Global Fluorosilicic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fluorosilicic Acid Market Foresight
Direct sales channels for fluorosilicic acid is fragmenting as regional chemical wholesalers and specialized distributors capture mid-size water utility accounts. Hubei Xingfa Group leverages captive phosphate rock supply to anchor cost positions in industrial-grade output. Solvay differentiates through pharmaceutical-grade certification and European REACH compliance infrastructure. The Mosaic Company sustains volume leadership by controlling integrated fertilizer-to-acid production corridors in North America.
Fluorosilicic acid, a byproduct of phosphate fertilizer manufacturing with typical concentrations of 20-30% H2SiF6 in aqueous solution, serves primarily as a fluoridating agent for municipal water supplies and as a feedstock for aluminum fluoride and cryolite production. Industrial-grade material dominates volume flows into water treatment and metal processing applications, where margin pools remain thin but contract-stable. Pharmaceutical-grade output commands premium positioning through CDSCO and FDA compliance overhead, while food-grade supply chains face tightening EFSA purity thresholds across European agricultural firms.
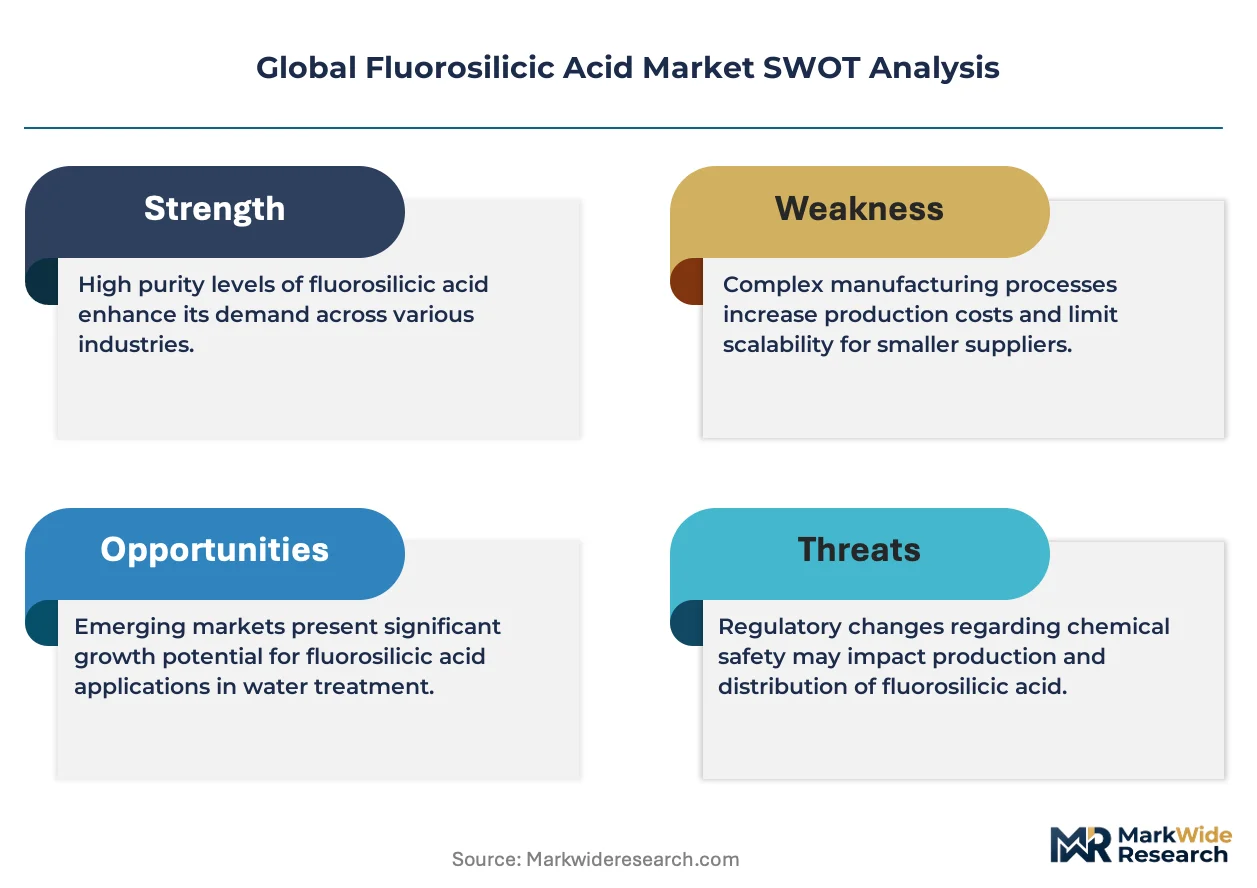
EPA drinking water regulations and the EU F-Gas Regulation constrain product specifications and cross-border trade routes for fluorosilicic acid derivatives. China's MEE enforces wastewater discharge limits that raise recovery costs for phosphate fertilizer coproduction. India's BIS certification requirements for water treatment chemicals create non-tariff entry barriers for imported material. Stakeholders must monitor regulatory divergence between REACH-aligned purity standards and emerging economy compliance thresholds to align capacity investments with accessible demand pockets.
Market Dynamics
Phosphate fertilizer production corridors concentrate fluorosilicic acid supply, binding acid economics to phosphate rock processing economics and creating geographic supply lock-in that shapes competitive positioning across water treatment and aluminum fluoride feedstock markets.
Growth Catalysts
- EPA drinking water mandates:Municipal utilities in the United States face compliance deadlines for fluoridation infrastructure upgrades, sustaining bulk procurement volumes for industrial-grade acid.
- Aluminum smelter demand:Cryolite and aluminum fluoride synthesis consumes fluorosilicic acid as primary fluorine feedstock, with smelter capacity expansion in the Middle East and Southeast Asia pulling additional volume.
- China's dual carbon targets:Beijing's emissions intensity requirements for phosphate fertilizer operations are accelerating acid recovery investments, tightening coproduct availability and supporting price floors.
Market Restraints
- Phosphate rock cost volatility:Sulfur and ammonia input swings transmit directly into fertilizer economics, compressing acid coproduct margins during phosphate market downturns.
- EU F-Gas Regulation friction:Cross-border acid derivative shipments face fluorinated gas tracking requirements, lengthening customs clearance and raising documentation overhead for European traders.
- Fluoride-free water treatment substitution:Membrane filtration and UV-C systems displace chemical fluoridation in some Scandinavian and German municipal contracts.
Strategic Opportunities
- India BIS certification gap:Domestic water treatment chemical standards create non-tariff entry barriers that local acid producers can exploit before import competition intensifies.
- Pharmaceutical-grade acid white space:CDSCO and FDA compliance infrastructure for high-purity H2SiF6 remains underdeveloped outside Solvay's European footprint, leaving margin capture potential for certified entrants.
- Direct-to-utility digital channels:Regional chemical wholesalers are building e-procurement platforms that bypass traditional distributor markups for mid-size North American water districts.
Industry Challenges
- Fluorine chemist talent scarcity:Specialized handling expertise for corrosive aqueous acid transport and storage constrains operational expansion at smaller regional distributors.
- MEE wastewater compliance timelines:China's Ministry of Ecology and Environment discharge limit enforcement requires rapid capital deployment for phosphate fertilizer acid recovery retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fluorosilicic Acid Market |
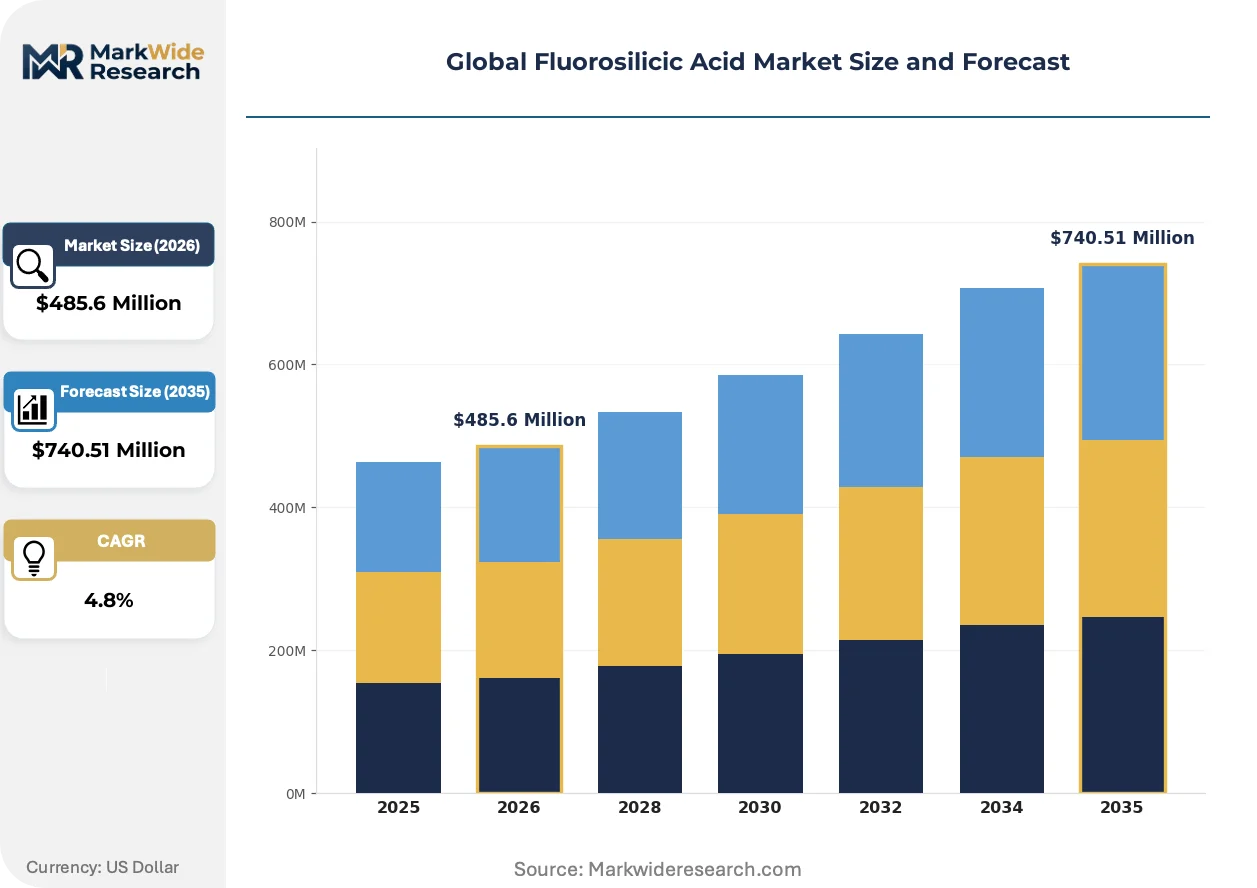
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $740.51 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Food Grade, Pharmaceutical Grade, Technical Grade Application: Water Treatment, Metal Processing, Pulp & Paper, Fertilizers, Chemicals Manufacturing End User: Water Utilities, Metal Fabricators, Agricultural Firms, Chemical Plants Distribution Channel: Direct Sales, Distributors, Online Platforms, Chemical Wholesalers |
| Companies Covered | Hubei Xingfa Group, Solvay, The Mosaic Company, Jayfluoride Private Limited, Fengyuan Group, Honeywell International, Hydrite Chemical, American Elements, IXOM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fluorosilicic Acid Market Shifts & Advancements
Processing technology and regulatory tracking systems are reshaping how fluorosilicic acid moves from phosphate fertilizer coproduct to end-use application, with purity certification and digital procurement emerging as decisive competitive differentiators.
Membrane concentration systems are hybridizing traditional evaporation-based acid purification with selective ion exchange, enabling fertilizer producers to upgrade industrial-grade output to water-treatment specifications without dedicated standalone facilities. North American phosphate corridor operators are piloting these units to capture municipal utility premiums. The technology is hybridizing asset-light acid upgrading, compressing capital barriers for mid-tier producers seeking margin expansion.
REACH substance registration requirements are tightening purity documentation thresholds for fluorosilicic acid derivatives entering European aluminum fluoride supply chains, forcing exporters to deploy batch-level testing infrastructure previously reserved for pharmaceutical-grade material. German and French customs authorities are rejecting shipments lacking ECHA-compliant safety data sheet attestations. Specialty chemical traders with pre-positioned compliance documentation are consolidating market access at the expense of commodity exporters.
Consolidated procurement consortia are displacing individual municipal utility purchasing for fluoridation chemicals across the United Kingdom and Netherlands, with regional water boards aggregating volume to extract price concessions and technical service bundling. Small and mid-size utilities surrender specification autonomy in exchange for cost predictability. This concentration is most visible in England's privatized water sector, where Thames Water and United Utilities coordinate acid tenders through shared procurement platforms.
Global Fluorosilicic Acid Market Segmentation
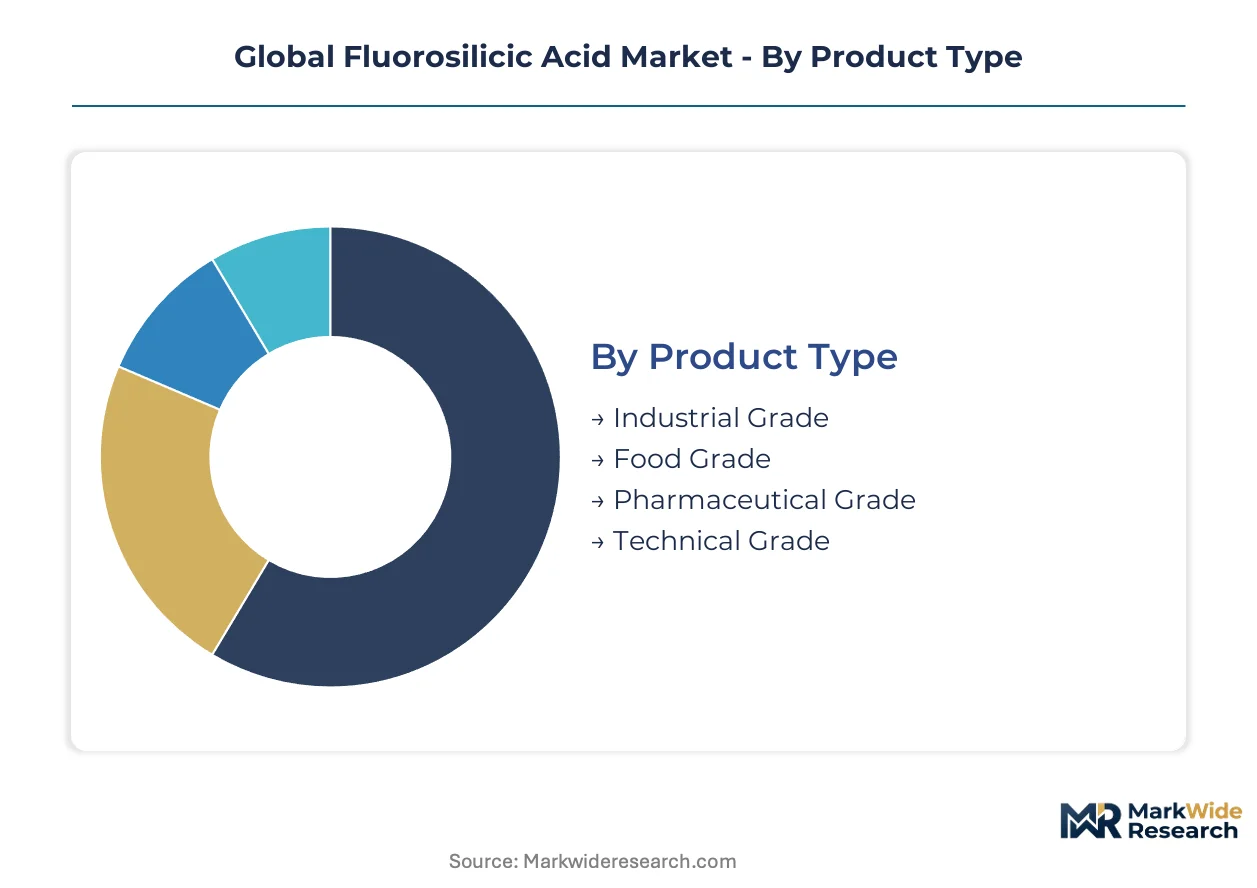
Fluorosilicic acid flows through distinct quality tiers and application channels that reshape procurement economics. Understanding how product grades, end-use specifications, and distribution pathways intersect reveals where margin pools concentrate and where volume commoditization accelerates.
Product Type:
Use-case spectrum spans from bulk municipal fluoridation to precision pharmaceutical synthesis, with purity thresholds determining accessible market tiers and pricing power.
- Industrial Grade:Aqueous solutions of 20-30% H2SiF6 dominate volume flows into municipal water treatment and aluminum fluoride feedstock production. Demand concentrates in United States utilities facing EPA compliance deadlines for aging infrastructure upgrades.
- Pharmaceutical Grade:Ultra-high purity material meeting FDA and CDSCO certification requirements commands premium positioning through specialized handling protocols and batch-level documentation. Solvay's European REACH compliance infrastructure currently anchors supply for this segment.
- Food Grade:Tightening EFSA purity thresholds across European agricultural applications constrain import eligibility and raise qualification barriers for new entrants.
- Technical Grade:Intermediate purity tier serves niche metal processing and chemical synthesis applications where industrial-grade specifications fall short but pharmaceutical certification is uneconomical.
Established volume favors Industrial Grade; emerging adoption favors Pharmaceutical Grade.
Application:
End-use diversification reflects fluorosilicic acid's dual identity as water treatment commodity and fluorine feedstock for industrial chemistry.
- Water Treatment:Municipal fluoridation programs across North America and Europe sustain bulk procurement volumes under tightened drinking water safety protocols. Membrane filtration substitution in Scandinavian markets introduces demand erosion risk.
- Metal Processing:Cryolite and aluminum fluoride synthesis consumes acid as primary fluorine source, with Middle Eastern and Southeast Asian smelter expansions pulling incremental volume.
- Chemicals Manufacturing:Fluorine derivative production for refrigerants and specialty intermediates faces EU F-Gas Regulation tracking requirements that lengthen customs clearance.
- Fertilizers:Phosphate fertilizer coproduction economics bind acid supply to sulfur and ammonia input volatility, compressing margins during phosphate market downturns.
- Pulp & Paper:Bleaching and wood preservation applications represent stable but lower-volume demand pocket with limited growth trajectory.
Contract stability concentrates in Water Treatment; expansion momentum clusters in Metal Processing.
End User:
Customer-type concentration determines procurement scale and technical service requirements across the value chain.
- Water Utilities:Consolidated procurement consortia in England and the Netherlands displace individual municipal purchasing, with Thames Water and United Utilities coordinating tenders through shared platforms.
- Metal Fabricators:Aluminum smelter demand ties to capacity expansion timelines in energy-cost-advantaged geographies, creating cyclical volume spikes.
- Chemical Plants:Fluorine derivative producers require REACH-aligned purity documentation that commodity exporters struggle to supply.
- Agricultural Firms:European agricultural applications face tightening EFSA thresholds that reshape supplier qualification requirements.
Procurement scale favors Water Utilities; technical complexity favors Chemical Plants.
Distribution Channel:
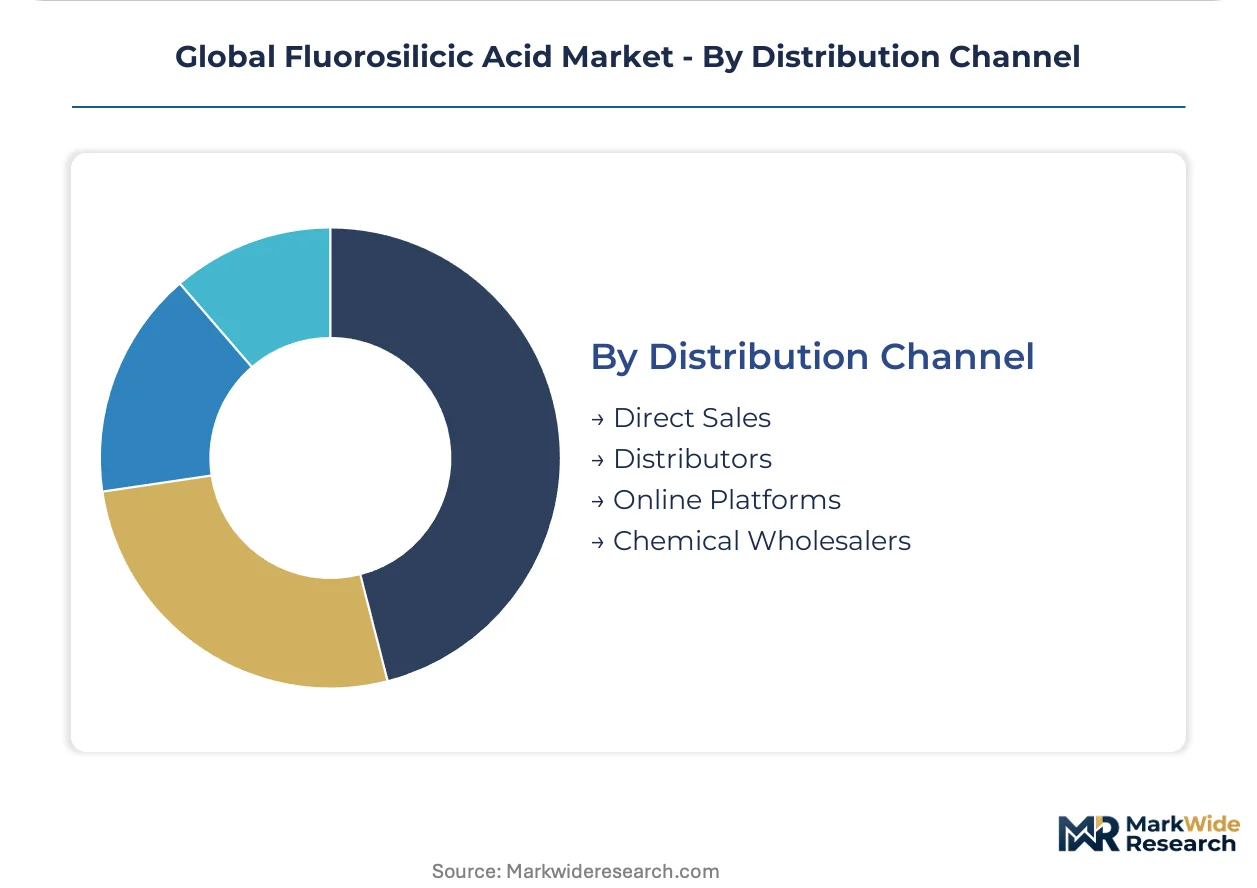
Channel structure is fragmenting as digital platforms and regional wholesalers capture mid-size accounts from traditional distributor networks.
- Direct Sales:Large-volume municipal utilities and integrated aluminum smelters negotiate direct contracts with phosphate corridor producers, bypassing intermediary markups.
- Chemical Wholesalers:Regional specialists are building e-procurement platforms that aggregate mid-size North American water district demand.
- Distributors:Traditional full-service distributors retain value in technical service bundling for smaller utilities lacking in-house fluoridation expertise.
- Online Platforms:Digital channels remain nascent for corrosive aqueous acid transport, constrained by specialized handling certification requirements.
Volume concentration favors Direct Sales; margin capture favors Chemical Wholesalers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that of China by a significant margin, driven by EPA compliance mandates and consolidated utility procurement. European markets command intermediate premiums through REACH-aligned purity requirements. Geographic supply lock-in to phosphate fertilizer corridors constrains arbitrage opportunities across these three demand centers.
United States
Municipal water utilities in the Great Lakes and Ohio River basins drive industrial-grade acid consumption for fluoridation infrastructure upgrades. EPA drinking water regulations enforce compliance deadlines that sustain bulk procurement volumes. The Florida phosphate corridor anchors domestic supply through integrated fertilizer-to-acid production.
China
MEE wastewater discharge limits and dual carbon targets are tightening acid recovery economics for phosphate fertilizer coproducers. GB standards for chemical manufacturing are evolving to align with emissions intensity requirements. The Yangtze River Delta concentrates acid processing capacity where retrofit investments are accelerating.
Germany
REACH substance registration and ECHA-compliant safety data documentation constrain cross-border derivative shipments into aluminum fluoride supply chains. The EU F-Gas Regulation imposes fluorinated gas tracking requirements that lengthen customs clearance. The Rhine-Ruhr industrial cluster hosts specialized traders with pre-positioned compliance infrastructure.
India
BIS certification requirements for water treatment chemicals create non-tariff entry barriers that domestic producers exploit. CDSCO pharmaceutical-grade compliance infrastructure remains underdeveloped, leaving margin capture potential for certified entrants. Gujarat and Maharashtra industrial zones concentrate phosphate fertilizer coproduction and acid recovery investments.
Netherlands
Consolidated procurement consortia among regional water boards displace individual municipal utility purchasing for fluoridation chemicals. EFSA purity thresholds for food-grade applications constrain import eligibility. The Randstad logistics hub facilitates REACH-aligned acid distribution into German and Belgian aluminum smelter markets.
Global Fluorosilicic Acid Market Competitive Landscape
Integrated phosphate producers and specialized chemical distributors split the market along volume-versus-margin fault lines. Supply concentrates in fertilizer corridor operators with captive acid recovery, while service-intensive tiers fragment across regional wholesalers. Three archetypes dominate: vertically integrated fertilizer majors controlling upstream phosphate rock; European REACH-compliant specialists commanding pharmaceutical-grade premiums; and regional distributors building digital procurement platforms. Competitive moves center on backward integration into phosphate mining and certification investments for high-purity tiers.
Within the integrated producer tier, Hubei Xingfa Group and The Mosaic Company exemplify divergent geographic anchoring strategies. Solvay occupies a position representing European regulatory compliance specialization. Among Asia-Pacific-based operators, Fengyuan Group and Jayfluoride Private Limited sit within the industrial-grade volume segment. These named entities illustrate how phosphate corridor control and purity certification infrastructure determine accessible market tiers without requiring specific operational claims about individual facilities.
| Leading Market Players |
|---|
| Hubei Xingfa Group |
| Solvay |
| The Mosaic Company |
| Jayfluoride Private Limited |
| Fengyuan Group |
| Honeywell International |
| Hydrite Chemical |
| American Elements |
| IXOM |
| Others |
Supply & Pricing Matrix
Undercapacity in China's Yangtze River Delta acid recovery infrastructure is tightening spot availability and pushing industrial-grade premiums higher, while US Gulf Coast producers leverage captive phosphate rock supply to hold contract pricing stable against input volatility.
Pricing Analysis
The customization-premium spread between standard industrial-grade offtake and pharmaceutical-grade certified batches runs wide, with FDA and CDSCO compliance overhead adding substantial documentation and handling costs. Pricing stratifies across pharmaceutical, industrial, and technical tiers, with quality grade and certification level as primary differentiation drivers. Cost compression in industrial-grade municipal contracts is intensifying because membrane filtration substitutes erode volume commitments in Scandinavian markets. Small and mid-size water utilities exhibit highest price sensitivity, while aluminum smelters with long-term offtake agreements show lowest.
Supply Chain Analysis
Export-control regime friction around fluorinated gas derivatives constrains cross-border acid shipments into European aluminum fluoride supply chains, lengthening customs clearance and raising documentation overhead. Supply concentrates in the United States, China, and Morocco as phosphate fertilizer corridors anchor acid coproduction. Raw material dependencies draw from phosphate rock, sulfur, and ammonia inputs. Single-source vulnerability runs through integrated fertilizer-to-acid production corridors where geographic lock-in limits supplier switching. Distribution runs through direct sales channels for large utilities and regional chemical wholesalers for mid-size accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where EPA compliance mandates and REACH-aligned purity documentation create sticky supplier relationships that resist price-driven switching.
For Market Incumbents: Insulate contract positions by deepening backward integration into phosphate mining and accelerating acid recovery retrofit investments ahead of China's MEE wastewater compliance timelines. Prioritize certification infrastructure for pharmaceutical-grade tiers before Solvay's European footprint faces competition. Threat: Membrane filtration substitutes in Scandinavian and German municipal contracts. Lever: Captive supply of phosphate rock. For New Entrants and Emerging Players: India's underpenetrated pharmaceutical-grade acid segment offers margin capture potential before CDSCO compliance infrastructure matures. Target BIS-certified water treatment chemical supply to exploit non-tariff entry barriers against import competition. White-space targets: pharmaceutical-grade certification for domestic Indian market, and direct-to-utility digital channels for mid-size North American water districts. Go-to-market angle: e-procurement platform aggregation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across acid recovery retrofit investments as China's dual carbon targets enforce emissions intensity requirements. Long-term viability favors integrated producers with captive phosphate rock supply and pre-positioned REACH compliance infrastructure. Acquisition target archetype: regional distributors with digital procurement platforms and established municipal utility relationships. Signal to watch: BIS certification timeline acceleration in India as domestic production scales.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Mining | Captive rock supply anchors cost positions against sulfur and ammonia volatility. |
| Pharmaceutical-Grade Certification Investment | FDA and CDSCO compliance infrastructure unlocks premium pricing tiers beyond industrial-grade commoditization. |
| Acid Recovery Retrofit Deployment | MEE wastewater limits and dual carbon targets tighten coproduct availability and support price floors. |
| Direct-to-Utility Digital Platform Buildout | E-procurement channels bypass traditional distributor markups for mid-size North American water districts. |
| Long-Term Municipal Supply Agreement | EPA compliance deadlines sustain bulk procurement volumes with contract-stable pricing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC filings from integrated phosphate producers, EPA regulatory dockets, and ECHA substance registration records. Primary interviews engaged plant managers at fertilizer corridor operations, procurement leads at municipal water utilities, distribution channel partners in regional chemical wholesaling, and technical R&D directors handling acid purification systems. Bottom-up segmentation modeling triangulates against top-down macroeconomic anchoring.
Forecast inputs include grade tier differentiation, end-use industry demand patterns, regional production hub capacity utilization, and regulatory compliance timeline acceleration. The analytical framework models volume and value trajectories across the projection horizon through segmented CAGR derivation. Industry-specific inputs incorporate phosphate fertilizer coproduction economics, fluoridation infrastructure replacement cycles, and aluminum smelter capacity expansion timelines in energy-cost-advantaged geographies.
Macroeconomic conditions sit as an overlay; deviation in phosphate rock pricing, sulfur input costs, or ammonia market volatility would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and substitution technology adoption rates. Material shifts in EPA mandate timelines, EU F-Gas Regulation implementation scope, or China's MEE discharge limit stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Europe Flame Retardant Chemicals Market
Chemicals
Diethyl Sulfate Market
Chemicals
Flatting Agents Market
Chemicals
Hydrazine Market
Chemicals
Global Inorganic Fluorides Market
Chemicals
Europe Biguanide Market
Chemicals
Methidathion (CAS 950-37-8) Market
Chemicals
Global Photoresist Chemicals Market
Chemicals
Cetyl Stearyl Alcohol Market
Chemicals
Global Cysteine Market
Chemicals
Benzalkonium Bromide Market
Chemicals
Potassium Hydrogen Phthalate Market
Chemicals
Anhydrous Hydrogen Fluoride Market
Chemicals
Coal Tar Market
Chemicals
Superphosphoric Acid (SPA) Market
Chemicals
Iso Nonanol Market