
 1,2 Hexanediol Market | 2026-2036
1,2 Hexanediol Market Size, Share, and Industry Trends Forecast 2026-2036
1,2 Hexanediol Market Analysis
Software-defined formulation services is decoupling raw material procurement from finished product development in personal care supply chains. BASF SE leverages its integrated intermediates platform to anchor European cosmetic-grade supply. Solvay S.A. competes through specialty alkoxide chemistry leadership in high-purity grades. Celanese Corporation extends its acetyls chain downstream into diol derivatives for industrial coatings.
1,2 Hexanediol is a linear six-carbon diol with hydroxyl groups at adjacent carbon positions, typically manufactured via catalytic hydrogenation of hexanoic acid derivatives or oxidation of 1-hexene, exhibiting hygroscopic properties and broad solvent compatibility that make it valuable as a moisturizing agent, preservative enhancer, and co-solvent across formulated products. Cosmetic Grade dominates value capture due to stringent purity requirements and brand-audited supply chains, while Pharmaceutical Grade represents the fastest-growing margin pool as injectable and topical drug formulations tighten excipient specifications. Industrial Grade remains mature with volume concentrated in coatings and adhesives applications where cost efficiency outweighs certification overhead.
REACH in Europe mandates full substance registration and toxicity documentation for cosmetic-grade 1,2 hexanediol imports, while FDA oversight in the United States governs pharmaceutical-grade excipient qualification through the Inactive Ingredient Database. China's NMPA and GB standards for cosmetic raw materials impose additional testing protocols that shape market access for foreign suppliers. Stakeholders must monitor evolving purity thresholds and regional certification divergence when allocating capacity across grade portfolios.
Market Dynamics
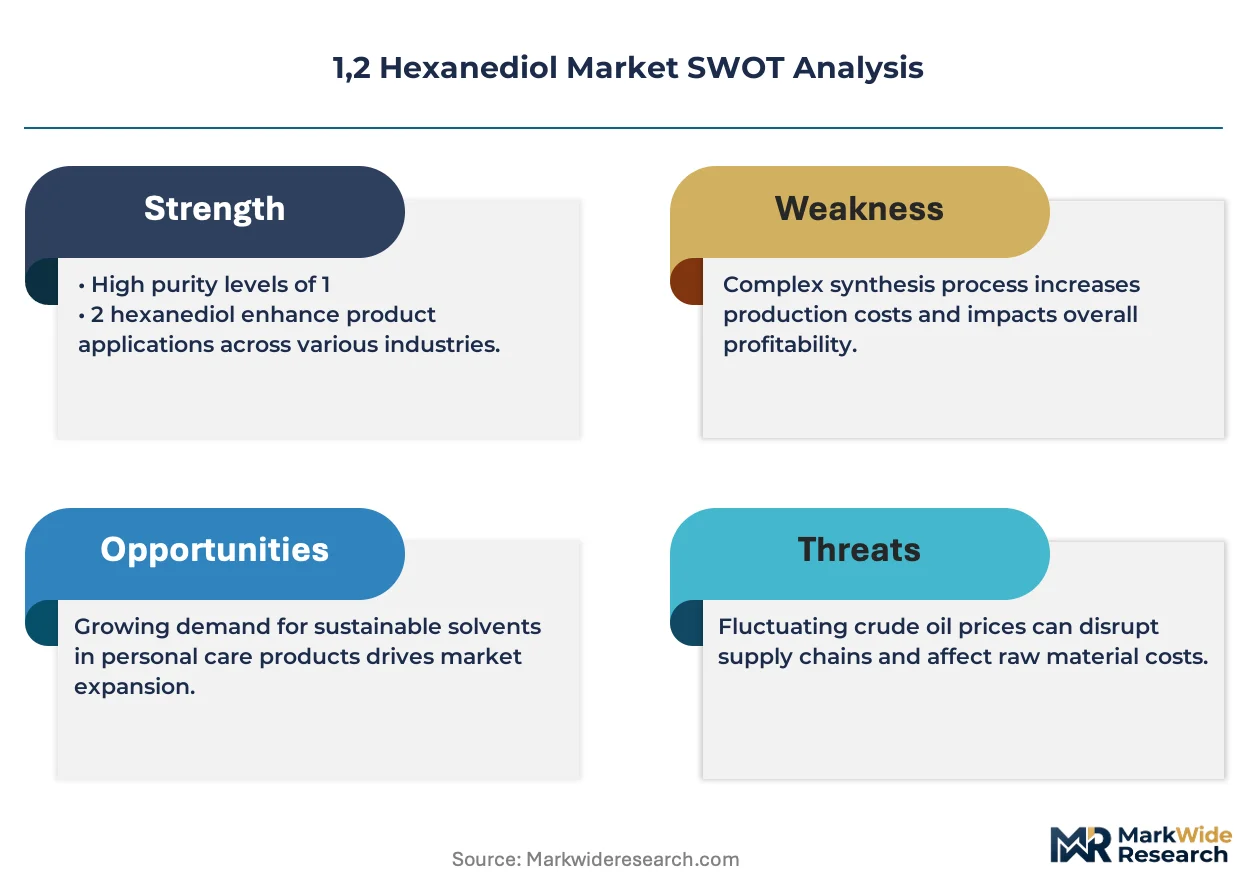
REACH compliance in Europe tightens purity thresholds for cosmetic-grade 1,2 hexanediol, forcing suppliers to revalidate manufacturing processes and redirect lower-grade output toward industrial coatings markets.
Growth Catalysts
- Cosmetic formulator consolidation in South Korea:Major personal care manufacturers in Seoul and Incheon clusters standardize on diol-based preservative boosters to reduce paraben load in export formulations.
- GB standards alignment:China's NMPA cosmetic raw material protocols create regulatory convergence that simplifies multinational qualification for compliant suppliers.
- Bio-based feedstock piloting:Catalytic hydrogenation of renewable hexanoic acid derivatives from sugarcane bagasse offers pathway to lower Scope 3 emissions for brand-audited supply chains.
Market Restraints
- Hexanoic acid price volatility:Crude palm kernel oil and petrochemical feedstock swings compress margin predictability for non-integrated producers.
- East Asian supply concentration:Overreliance on hydrogenation capacity in Zhejiang and Jiangsu provinces exposes buyers to regional logistics disruptions and port congestion.
- Propylene glycol substitution:Lower-cost diols with comparable humectant performance threaten volume in mass-market personal care and industrial adhesive segments.
Strategic Opportunities
- Pharmaceutical-grade excipient expansion:Injectable and topical drug formulations tightening excipient specifications create premium margin pool for validated suppliers.
- Software-defined formulation services:Digital platforms decouple raw material procurement from finished product development, enabling direct supplier relationships with mid-tier cosmetic brands.
- EU Green Deal chemistry incentives:Sustainable process certification opens preferential procurement channels for European personal care manufacturers with net-zero commitments.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous REACH registration, FDA Inactive Ingredient Database qualification, and NMPA filing create 18-24 month market entry delays.
- Analytical method standardization gaps:Divergent purity testing protocols between cosmetic and pharmaceutical grade specifications force redundant quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 1,2 Hexanediol Market |
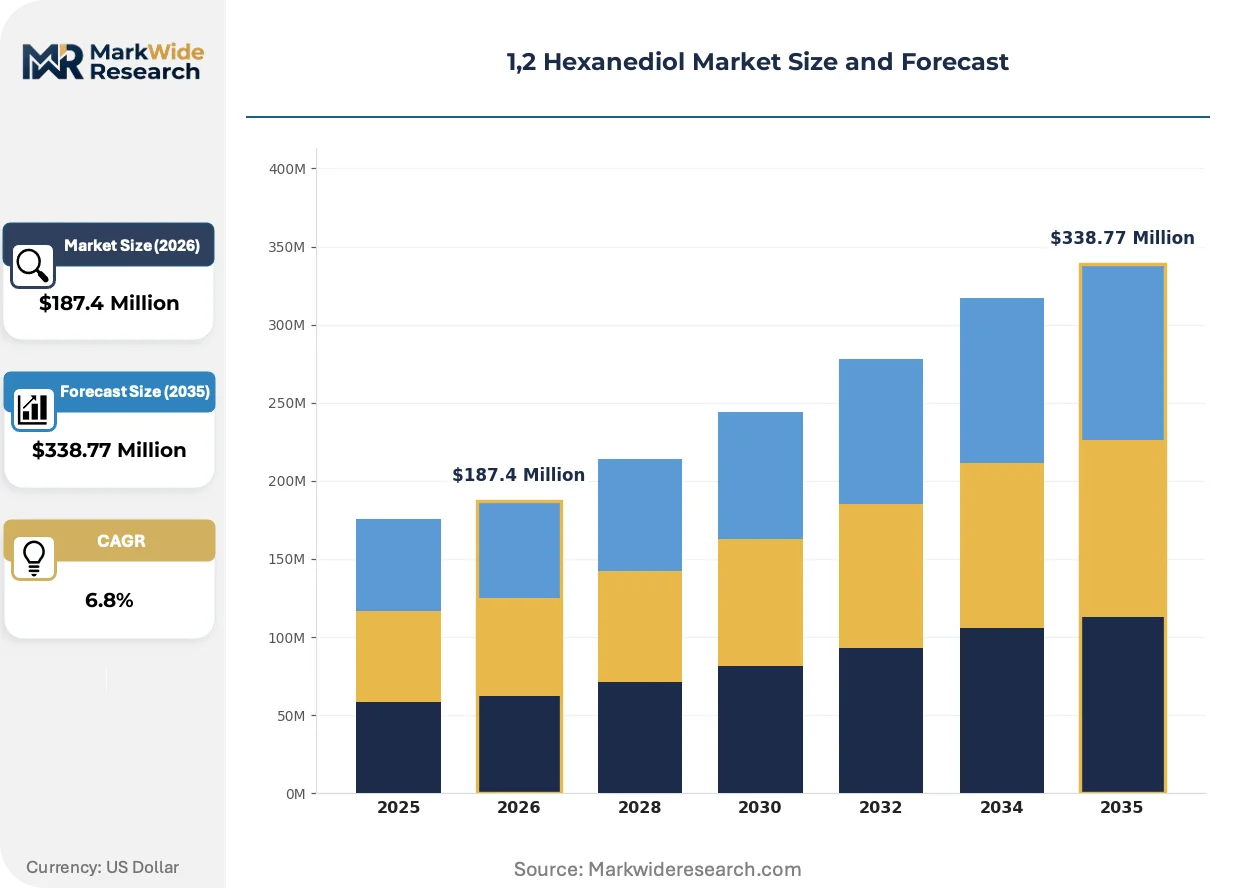
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetics, Pharmaceuticals, Coatings, Adhesives Application: Skin Care, Hair Care, Antimicrobial Agents, Industrial Solvents Grade: Cosmetic Grade, Industrial Grade, Pharmaceutical Grade, Technical Grade End User: Beauty Brands, Pharmaceutical Companies, Chemical Manufacturers, Food Industry |
| Companies Covered | BASF SE, Solvay S.A., Celanese Corporation, Eastman Chemical Company, Evonik Industries AG, Kao Corporation, Clariant AG, Ashland Global Holdings Inc., Wanhua Chemical Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
1,2 Hexanediol Market Emerging Trajectories
Process intensification and digital supply chain orchestration are compressing development cycles for formulated products, while regulatory divergence between major markets forces modular manufacturing architectures.
Bio-catalytic oxidation of 1-hexene is expanding into commercial-scale production as enzymatic routes achieve selectivity parity with traditional hydrogenation. Specialty chemical producers in the Netherlands and Belgium pilot continuous-flow reactors that reduce solvent waste and energy intensity. This technology is expanding into cosmetic-grade supply chains as brand sustainability audits scrutinize manufacturing footprints.
REACH substance evaluation under the 2023-2025 work program intensifies data requirements for skin sensitization endpoints. ECHA's extended one-generation reproductive toxicity study demands force reformulators to document exposure scenarios across leave-on and rinse-off product categories. Cosmetic-grade suppliers with existing OECD-compliant dossiers capture accelerated re-registration timelines versus new market entrants.
Direct supplier engagement through digital procurement platforms fragments traditional distributor relationships in personal care raw materials. Mid-tier Korean and Chinese cosmetic brands now source 1,2 hexanediol through validated e-procurement channels that bypass regional chemical traders. This pattern concentrates most visibly in Seoul's Gangnam and Shanghai's Pudong formulation clusters where technical service expectations remain high despite disintermediation.
1,2 Hexanediol Market Segmentation
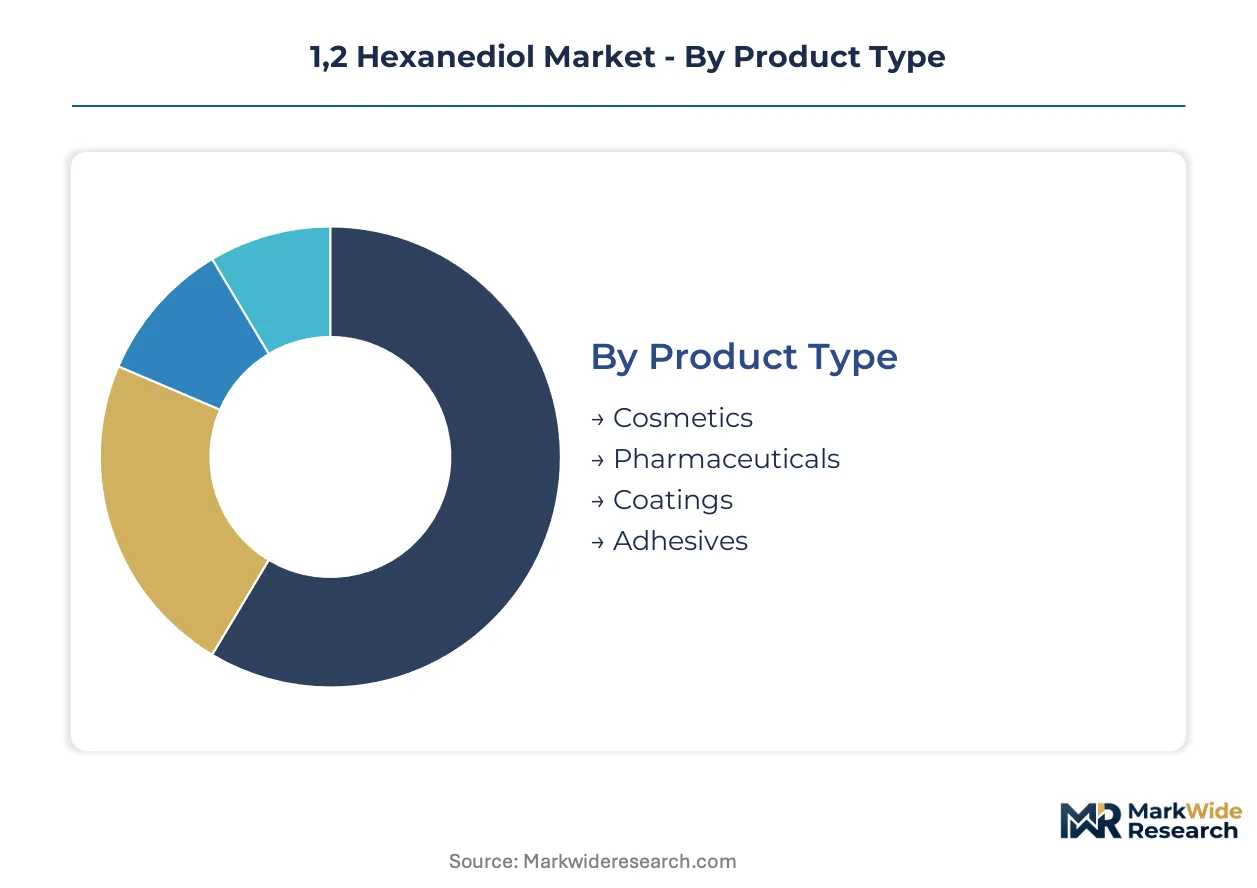
Grade purity thresholds and end-use certification requirements fragment the 1,2 hexanediol market into distinct value tiers. Buyers prioritize validated supply chains for cosmetic and pharmaceutical applications while industrial segments prioritize cost efficiency.
Grade:
Cosmetic brands and drug manufacturers differentiate procurement by analytical purity and regulatory documentation burden.
- Cosmetic Grade:Stringent limits on heavy metals and microbial contamination define this specification. Seoul-based formulators in Gangnam and Incheon clusters drive procurement volumes for K-beauty export formulations. REACH-compliant dossiers with OECD skin sensitization data command premium positioning.
- Pharmaceutical Grade:USP-NF and EP monograph compliance with residual solvent testing qualifies material for injectable and topical drug delivery. FDA Inactive Ingredient Database listing requirements extend qualification timelines to 18-24 months for new suppliers.
- Industrial Grade:Coatings and adhesives manufacturers in Zhejiang province absorb volume from downgraded cosmetic production.
- Technical Grade:Intermediate purity tier serves specialty chemical synthesis with reduced certification overhead.
Cosmetic Grade leads volumes today; Pharmaceutical Grade is gaining share fastest.
Product Type:
Application-specific formulation requirements concentrate demand in personal care while industrial uses expand volume scale.
- Cosmetics:Humectant and preservative booster functions in leave-on and rinse-off products. South Korean beauty brands standardize diol-based systems to reduce paraben content in EU and US export formulations.
- Pharmaceuticals:Excipient applications in topical creams and transdermal patches with documented biocompatibility profiles.
- Coatings:Celanese Corporation and integrated acetyls producers target industrial coatings with cost-optimized supply.
- Adhesives:Solvent compatibility and low volatility support pressure-sensitive adhesive formulations.
Cosmetics dominates revenue capture; Pharmaceuticals expands most quickly on excipient specification tightening.
Application:
Functional performance in formulation determines procurement priority across personal care and industrial segments.
- Skin Care:Moisturizing efficacy and sensory profile drive adoption in serums, essences, and creams. Seoul formulation clusters specify diol content for hydration claims in premium product lines.
- Hair Care:Conditioning agents and humectant properties support leave-in treatments and styling formulations.
- Antimicrobial Agents:Preservative enhancement through membrane disruption mechanisms reduces traditional biocide load.
- Industrial Solvents:Broad polarity range and low toxicity profile enable cleaning and degreasing applications.
Skin Care anchors current demand; Antimicrobial Agents climbs fastest on clean-label preservation trends.
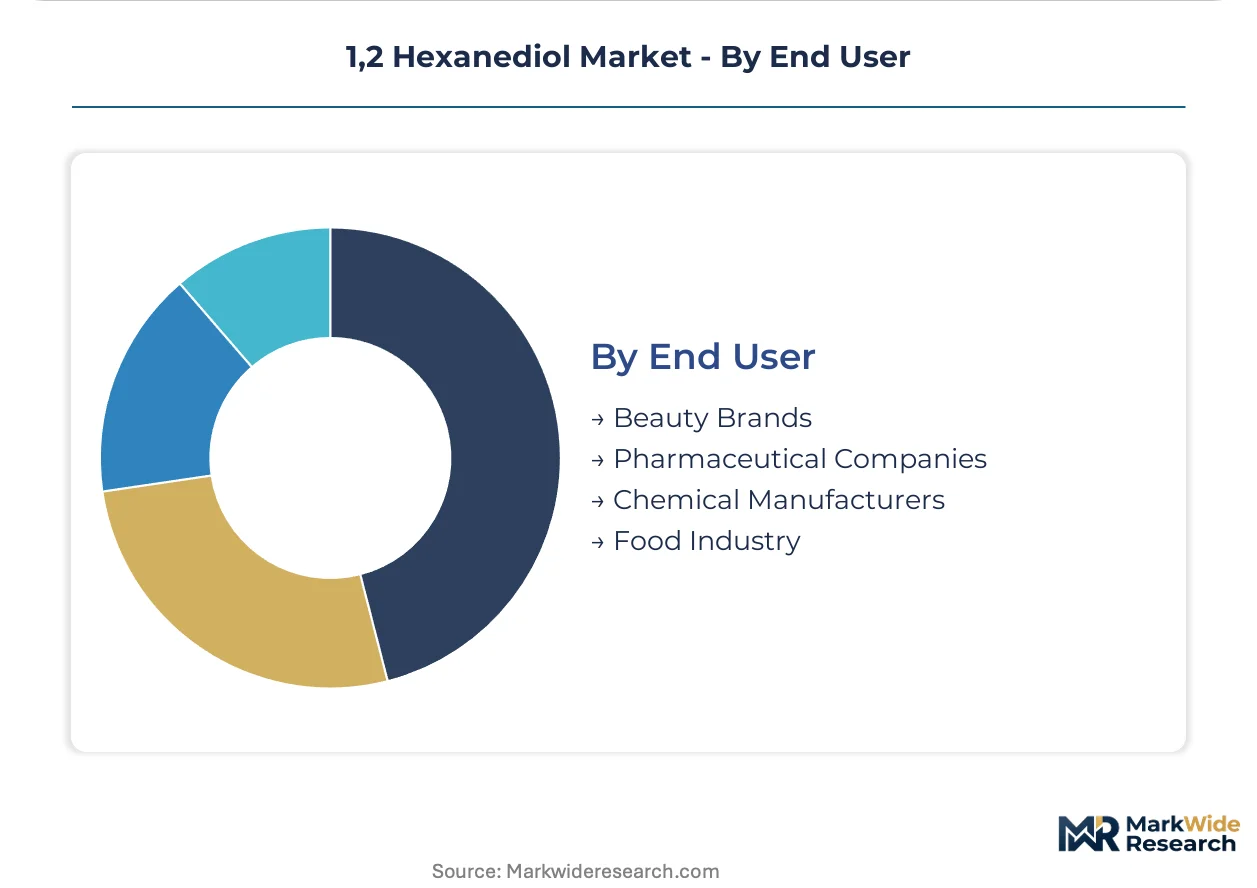
End User:
Supply chain integration depth and technical service requirements separate procurement behaviors across customer categories.
- Beauty Brands:Direct supplier engagement through digital procurement platforms fragments traditional distributor relationships. Mid-tier Korean and Chinese brands in Pudong and Gangnam clusters source through validated e-procurement channels.
- Pharmaceutical Companies:Excipient qualification protocols with multi-jurisdiction filing requirements favor established suppliers with existing FDA and NMPA dossiers.
- Chemical Manufacturers:Intermediate demand for downstream derivative production with specification flexibility.
- Food Industry:Limited food-grade applications with FSSAI and regional food safety authority compliance requirements.
Beauty Brands generate highest transaction frequency; Pharmaceutical Companies deliver steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's cosmetic formulators outpace German chemical demand for high-purity diols, while China's hydrogenation capacity anchors industrial-grade supply chains. Regulatory divergence between REACH, FDA, and NMPA protocols fragments qualification timelines across major consumption centers.
South Korea
Seoul's Gangnam and Incheon formulation clusters standardize diol-based preservative boosters for K-beauty exports. MFDS cosmetic raw material protocols align with EU REACH standards to streamline multinational brand qualification. Daegu-Gyeongbuk manufacturing corridors absorb volume from domestic hydrogenation capacity expansions.
China
Zhejiang and Jiangsu provinces concentrate catalytic hydrogenation output for both cosmetic and industrial grades. NMPA GB standards impose additional testing protocols that shape market access for foreign suppliers. Shanghai's Pudong district hosts formulation R&D centers where technical service expectations remain high despite digital procurement disintermediation.
Germany
BASF SE anchors European cosmetic-grade supply through integrated intermediates platforms in Ludwigshafen. ECHA's REACH substance evaluation intensifies data requirements for skin sensitization endpoints under the 2023-2025 work program. The Netherlands and Belgium pilot continuous-flow reactors that reduce solvent waste for brand-audited supply chains.
United States
FDA Inactive Ingredient Database qualification governs pharmaceutical-grade excipient procurement for injectable and topical drug formulations. Eastman Chemical Company extends acetyls chain downstream into diol derivatives for industrial coatings applications. Texas and Louisiana petrochemical corridors feed hexanoic acid derivative supply to domestic hydrogenation units.
Japan
METI industrial chemical standards intersect with PMDA pharmaceutical excipient requirements for dual-use material qualification. Kao Corporation leverages domestic alkoxide chemistry expertise in high-purity cosmetic-grade production. Osaka-Kobe chemical manufacturing clusters serve Southeast Asian personal care export markets.
1,2 Hexanediol Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated chemical majors commanding cosmetic-grade premiums and regional hydrogenation specialists absorbing industrial volume. The vendor base organizes into three archetypes: petrochemical-integrated majors with backward control over hexanoic acid feedstocks, specialty alkoxide producers with purity leadership, and Asian hydrogenation specialists with cost-optimized scale. Dominant competitive moves include capacity rationalization toward pharmaceutical-grade qualification and digital platform partnerships that bypass traditional distributor relationships.
Among European-integrated majors, BASF SE and Solvay S.A. occupy positions at opposite ends of the value chain archetype spectrum, with the former representing petrochemical integration depth and the latter exemplifying specialty alkoxide selectivity. Celanese Corporation anchors the acetyls-derivative tier with downstream extension into industrial coatings applications. These three entities collectively represent the structural tension between feedstock control and formulation chemistry expertise that defines competitive positioning in high-purity diol supply.
| Leading Market Players |
|---|
| BASF SE |
| Solvay S.A. |
| Celanese Corporation |
| Eastman Chemical Company |
| Evonik Industries AG |
| Kao Corporation |
| Clariant AG |
| Ashland Global Holdings Inc. |
| Wanhua Chemical Group Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Hexanoic acid derivative costs cascade through three pricing tiers as Zhejiang hydrogenation capacity feeds both cosmetic-grade and industrial-grade buyers with divergent purity requirements. Crude palm kernel oil volatility compresses margin predictability for non-integrated producers serving mass-market coatings segments.
Pricing Analysis
Capacity additions in Zhejiang province are reshaping price floors for industrial-grade material while cosmetic-grade premiums widen. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial levels reflects certification burden and analytical purity thresholds. Price differentiation centers on REACH dossier completeness and FDA Inactive Ingredient Database listing status. Cost compression in industrial tiers intensifies because propylene glycol substitution threats force volume discounts; coatings manufacturers exhibit highest price sensitivity while pharmaceutical companies accept premium positioning for validated supply chains.
Supply Chain Analysis
Freight cost differentials between East Asian hydrogenation hubs and European formulation clusters compress netback values for spot cargo sales. Supply concentrates in China, South Korea, and Germany with raw material dependencies on hexanoic acid derivatives, catalytic hydrogenation equipment, and analytical testing services. Single-source vulnerability runs through Zhejiang-Jiangsu corridor concentration where port congestion disrupts just-in-time delivery to Seoul and Shanghai formulation centers. Distribution runs through validated e-procurement platforms that disintermediate regional chemical traders for mid-tier cosmetic brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where pharmaceutical-grade excipient specifications tighten faster than industrial-grade commoditization. Buyers now prioritize validated supply chains over spot price optimization.
For Market Incumbents: Hedge propylene glycol substitution threats in mass-market personal care by deepening backward integration into hexanoic acid feedstocks. Lock in long-term offtake agreements with Seoul-based K-beauty formulators before digital procurement platforms fragment distributor relationships further. Prioritize pharmaceutical-grade qualification investments to capture premium margin pools as FDA and NMPA filing timelines extend. For New Entrants and Emerging Players: Mid-tier Chinese cosmetic brands in Shanghai's Pudong district represent the most penetrable buyer archetype for validated e-procurement channel entry. White-space targets include bio-based feedstock certification for EU Green Deal compliance and continuous-flow reactor technology licensing to Dutch-Belgian specialty producers. Lead with technical service capabilities that match incumbent response times despite disintermediated distribution. For Investors and Strategic Acquirers: Roll-up economics work for specialty alkoxide producers with existing OECD-compliant dossiers because regulatory filing backlogs create acquisition premiums for qualified assets. Platform viability extends through the next decade as multi-jurisdiction certification timelines favor incumbent dossier libraries. Watch for ECHA substance evaluation acceleration under REACH work programs as inflection signal for re-registration cost spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hexanoic Acid Feedstocks | Captive supply of palm kernel oil derivatives insulates margin predictability from commodity swings. |
| Pharmaceutical-Grade Qualification Investment | USP-NF and EP monograph compliance opens injectable excipient premiums for validated suppliers. |
| Continuous-Flow Reactor Technology Adoption | Belgian and Dutch pilot programs reduce solvent waste for brand-audited cosmetic supply chains. |
| Digital Procurement Platform Partnership | Direct supplier relationships with Gangnam and Pudong formulators bypass regional chemical traders. |
| Bio-Based Feedstock Certification | Sugarcane bagasse hydrogenation pathways unlock EU Green Deal preferential procurement channels. |
Methodological Framework
Coverage spans East Asia, Europe, and North America, with primary inputs from each region's hydrogenation and formulation clusters. Plant managers at Zhejiang hydrogenation facilities, procurement leads at Seoul-based cosmetic OEMs, distribution channel partners in Shanghai's Pudong district, and technical R&D directors at European alkoxide producers provided operational data. Secondary validation drew from customs and trade databases, Cefic chemical industry reports, SEC 10-K filings for listed intermediates producers, and REACH registration dossiers published by ECHA. Bottom-up capacity and utilization estimates triangulated against top-down consumption models across grade tiers.
Rate-of-change decomposition separated volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include grade purity tier, end-use industry, regional production hub, and certification status. CAGRs derived from iterative reconciliation of supply-side capacity additions with demand-side formulation trends. Industry-specific forecast inputs incorporated ECHA substance evaluation timelines and NMPA GB standards alignment progress.
Underlying measurement precision varies by segment; pharmaceutical-grade volumes carry tighter precision than industrial-grade spot market estimates due to longer qualification visibility. Forecasts reflect assumptions about regulatory filing timelines, feedstock cost trajectories, and substitution elasticity that could revise with unexpected REACH enforcement intensity or bio-catalytic oxidation technology breakthroughs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Fragrance-Release Control Agents for Long-Lasting Home Care Scents Market
Specialty Chemicals
Esterquats Market
Specialty Chemicals
Global Silicone Defoamer Market
Specialty Chemicals
CMIT/MIT Market
Specialty Chemicals
Global 28-Homobrassinolide Market
Specialty Chemicals
Isostearyl Alcohol Market
Specialty Chemicals
Bio-Based Aromatics Market
Specialty Chemicals
UV Light Stabilizers Market
Specialty Chemicals
Global 1,5-Cyclooctadiene Market
Specialty Chemicals
2-(2,2,2-Trifluoroethoxy)-1,3,2-Dioxaphospholane-2-Oxide Market
Specialty Chemicals
Free-From Titanium Dioxide Market
Specialty Chemicals
Global Vinyl Sulfone Market
Specialty Chemicals
Thermolysin Market
Specialty Chemicals
Silver Iodide Market
Specialty Chemicals
Hydroxyproline Market
Specialty Chemicals
Petroleum Jelly Market