
 Hyperscale Edge Computing Market | 2026-2036
Hyperscale Edge Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperscale Edge Computing Market Analysis
Enterprise-grade redundancy specifications are unwinding legacy tolerance bands across hyperscale edge infrastructure procurement. Microsoft Corporation sustains R&D intensity in AI-optimized edge silicon partnerships. NVIDIA dominates inference acceleration at the network boundary through its Grace-Hopper architecture. Amazon Web Services Inc. extends its Outposts footprint into on-premises environments with unified control-plane management.
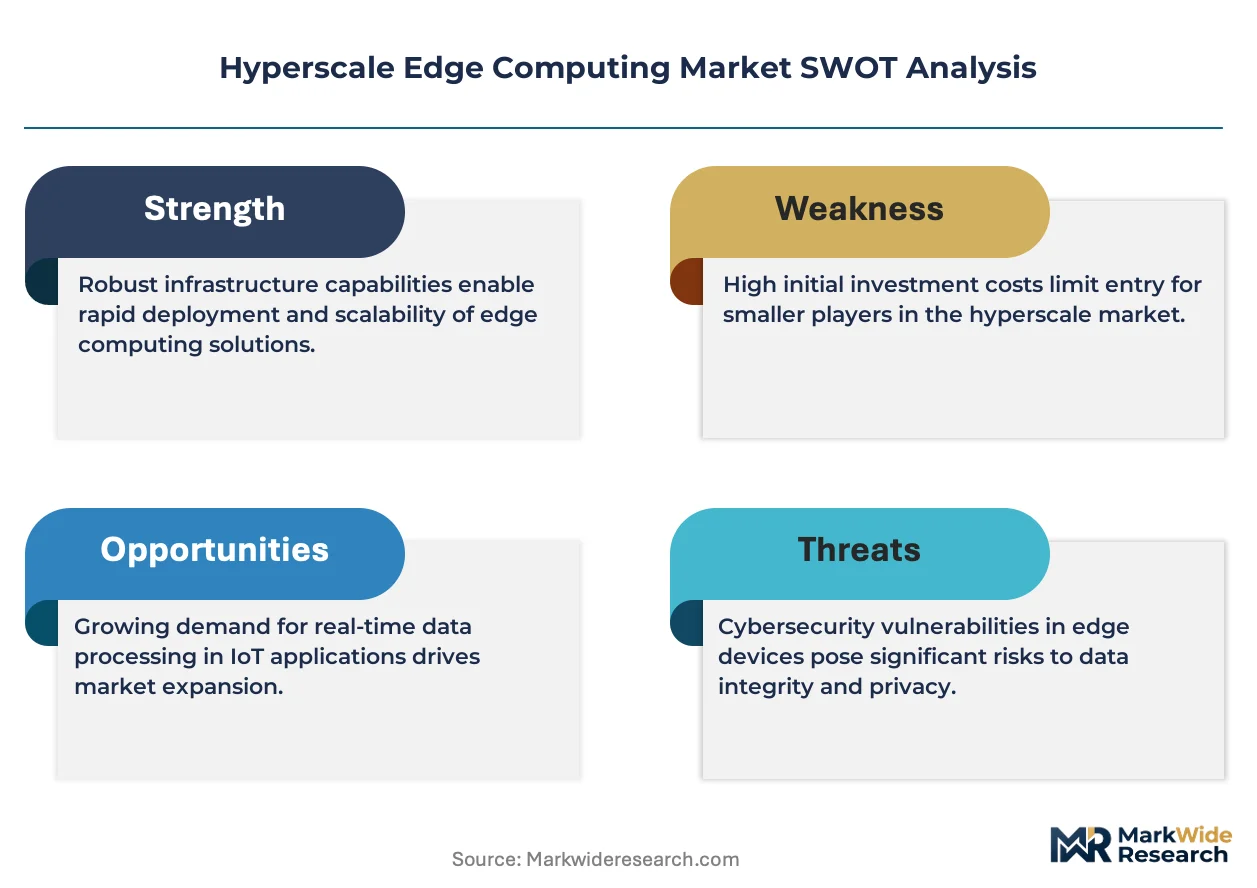
Hyperscale edge computing denotes distributed data processing architectures that position compute, storage, and networking resources within 10 milliseconds of endpoint devices, typically employing ARM-based or x86 microservers with liquid-cooled thermal envelopes. These systems serve industrial automation, autonomous mobility, and real-time analytics by eliminating backhaul latency to centralized cloud regions. The software segment captures disproportionate margin pools as orchestration platforms abstract heterogeneous hardware across hybrid deployments. Managed services within the service type dimension are expanding fastest as telecommunications operators outsource edge infrastructure lifecycle management to specialist providers.
The FCC enforces spectrum allocation rules that shape where edge nodes may operate in unlicensed and CBRS bands, while the EU AI Act imposes conformity assessment requirements on automated decision-making systems deployed at the edge. ISO 27001 and IEC 62443 certifications increasingly gate market access for infrastructure vendors serving critical manufacturing and healthcare end users. Stakeholders must weigh sovereign data requirements against the capital efficiency of shared edge facilities when selecting deployment architectures.
Market Dynamics
Autonomous vehicle fleets and smart factory networks are compressing latency tolerance bands from 50 milliseconds to sub-10 milliseconds, forcing infrastructure procurement cycles to accelerate and co-location requirements to tighten around production corridors.
Growth Catalysts
- EU AI Act Conformity Mandates:Automated decision-making systems deployed at manufacturing edges must undergo third-party assessment, creating captive demand for certified local compute infrastructure.
- CBRS Spectrum Liberalization:The FCC's mid-band allocation rules enable private 5G networks for industrial campuses, allowing automotive OEMs to deploy dedicated edge nodes without carrier dependency.
- Liquid-Cooled Thermal Architectures:Precision manufacturers in Germany's industrial corridor now specify direct-to-chip cooling as standard for microserver deployments adjacent to production lines.
Market Restraints
- Specialized Silicon Supply Concentration:Advanced inference accelerators for network boundary deployment depend on a concentrated foundry base in Taiwan, exposing procurement timelines to geopolitical friction.
- Energy Input Cost Volatility:Edge facilities require 24/7 baseload power guarantees; European industrial electricity pricing swings above €100/MWh are compressing facility operating margins.
- Data Residency Fragmentation:Divergent national implementations of GDPR Article 44 cross-border transfer rules force redundant infrastructure deployment across jurisdictions.
Strategic Opportunities
- India PLI Scheme for Electronics:Production-linked incentives for semiconductor assembly and testing are attracting hyperscale edge hardware manufacturing to Gujarat and Tamil Nadu.
- Healthcare Edge Convergence:Real-time surgical robotics and diagnostic imaging at hospital networks create demand for HIPAA-compliant local processing with sub-5 millisecond response.
- Telecommunications Outsourcing Wave:Managed services contracts for edge infrastructure lifecycle management are displacing in-house operator engineering teams across European markets.
Industry Challenges
- Certification Timeline Compression:IEC 62443 industrial cybersecurity certification for edge hardware now requires 14-18 month validation cycles, gating vendor market access.
- Legacy OT Integration Friction:Brownfield manufacturing environments operate proprietary protocols that resist API-based orchestration without middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperscale Edge Computing Market |
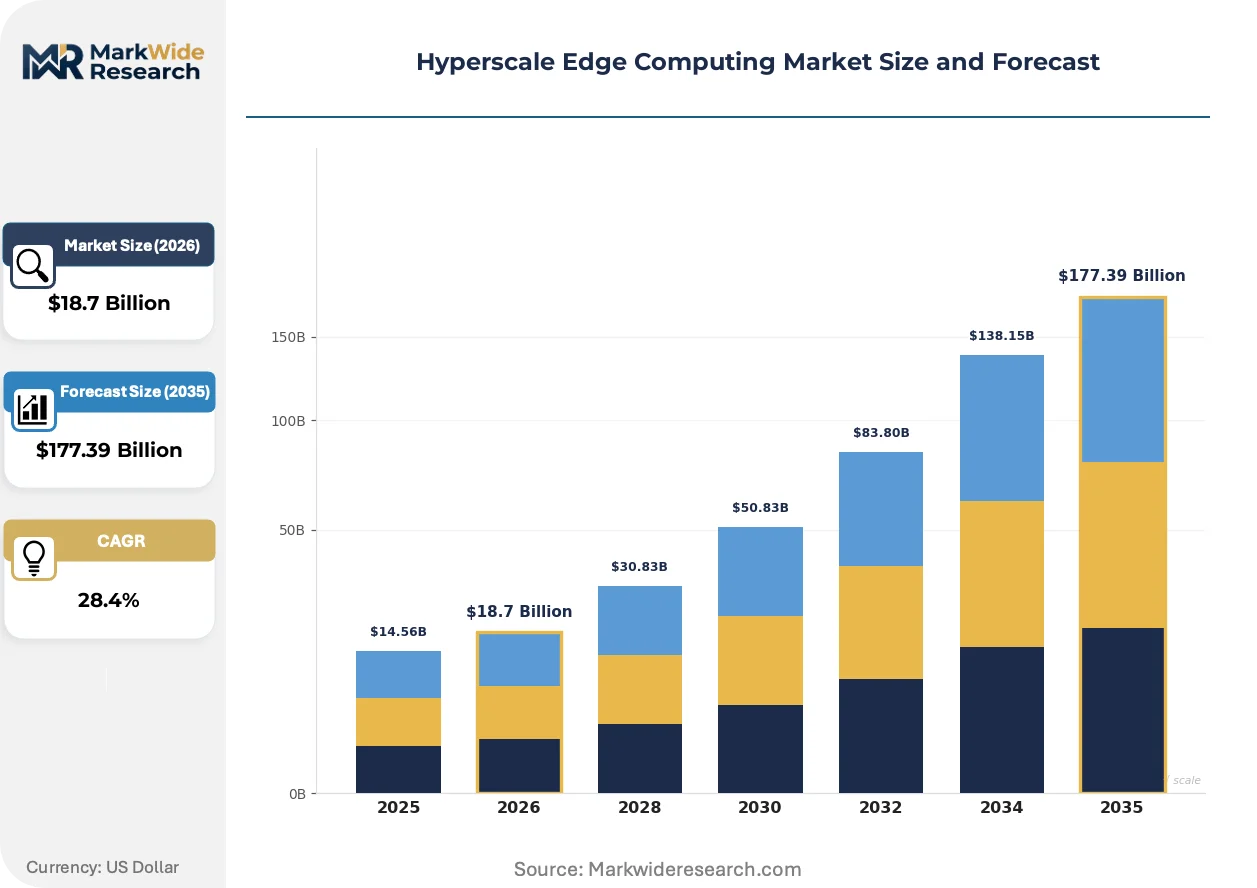
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $177.39 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Servers, Networking Equipment, Storage Solutions, Software Deployment Model: On-Premises, Hybrid, Private Cloud, Public Cloud End User: Telecommunications, Retail, Healthcare, Manufacturing Service Type: Consulting, Managed Services, Maintenance, Integration |
| Companies Covered | Amazon Web Services Inc., Microsoft Corporation, Google Cloud, Hewlett Packard Enterprise Development LP, Intel Corporation, Cisco Systems Inc., NVIDIA, Alibaba Cloud, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperscale Edge Computing Market Emerging Trajectories
Silicon architectures and orchestration platforms are splitting into divergent optimization paths—one stream chasing maximum inference throughput per watt, the other prioritizing deterministic latency for safety-critical workloads.
ARM-based microserver designs with integrated NPUs are bifurcating the hardware procurement landscape. Automotive tier-1 suppliers now specify these configurations for in-vehicle edge gateways, while precision manufacturers demand x86 compatibility for legacy software stacks. This split is compressing vendor R&D budgets across two incompatible instruction set optimization paths.
The EU AI Act's conformity assessment framework for high-risk automated systems is reshaping deployment architectures. Edge nodes processing quality-control decisions must maintain audit trails and human oversight interfaces, adding firmware complexity. German automotive OEMs are responding by segregating inference workloads between certified and non-certified hardware tiers.
Buyers are unbundling infrastructure procurement from connectivity contracts. Industrial automation customers now source compute hardware directly from silicon vendors, then contract managed services separately for orchestration and maintenance. This pattern is most visible in Japan's automotive supply chain, where METI's smart factory subsidies accelerate direct procurement experimentation.
Hyperscale Edge Computing Market Segmentation
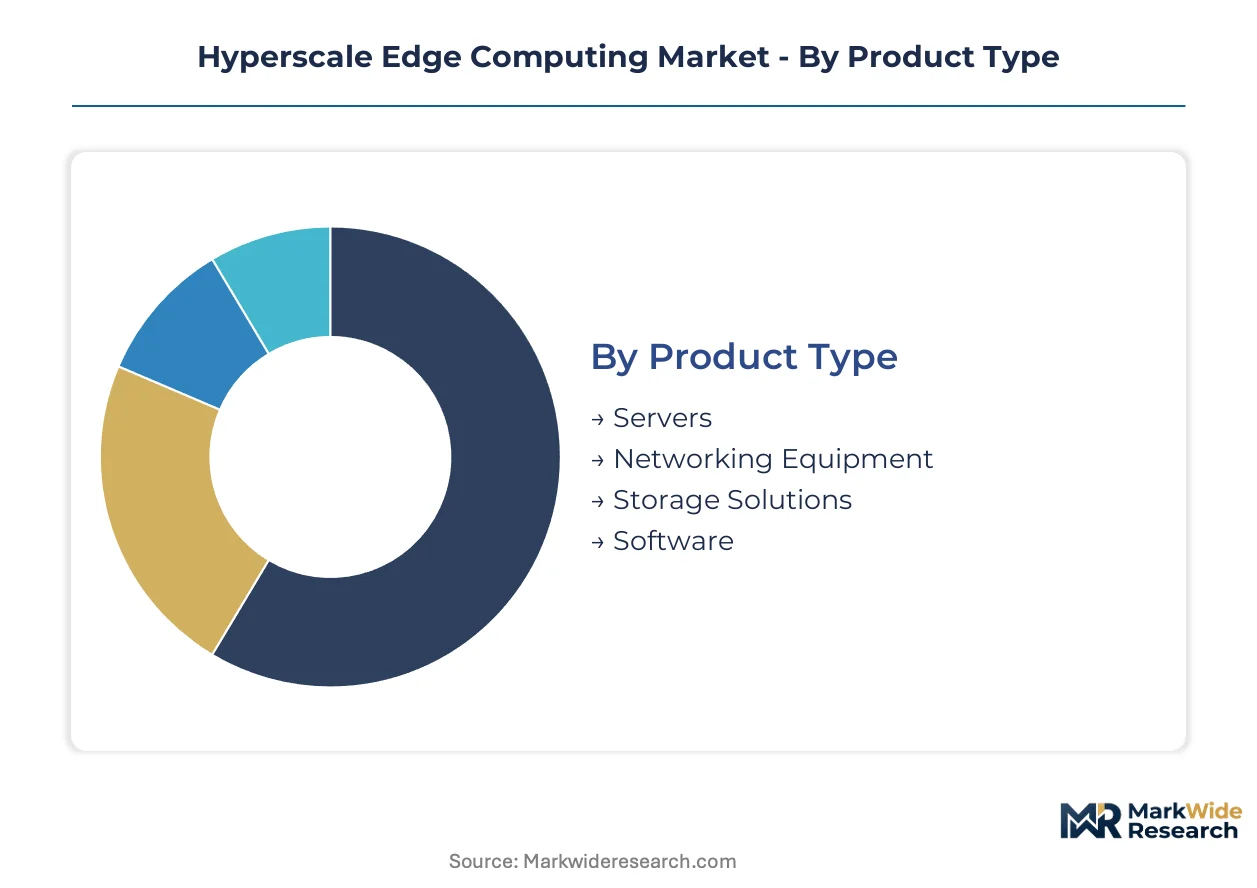
Hyperscale edge computing procurement channels diverge sharply by segment maturity. Hardware flows through direct OEM relationships with automotive and industrial buyers, while software and services route through systems integrators and telecommunications operators managing multi-tenant facilities.
Product Type:
Channel mix varies by hardware versus software intensity—servers and networking equipment move through direct procurement with large manufacturing end users, while software licenses increasingly route through cloud marketplaces and managed service aggregators.
- Servers:ARM-based and x86 microservers with liquid-cooled thermal envelopes dominate industrial corridor deployments. German automotive OEMs and precision manufacturers in Bavaria and Baden-Württemberg specify these for production line adjacency, driven by sub-10 millisecond latency mandates from autonomous vehicle fleet operators.
- Software:Orchestration platforms abstract heterogeneous hardware across hybrid deployments, capturing disproportionate margin pools. Kubernetes-based edge management tools flow through telecommunications operator marketplaces in Japan and South Korea, where METI and government smart factory subsidies accelerate procurement experimentation.
- Networking Equipment:Private 5G radios and CBRS-enabled gateways connect isolated production cells.
- Storage Solutions:NVMe-based edge caches handle real-time analytics datasets without cloud backhaul.
Servers dominate installed base. Software is where expansion concentrates.
Deployment Model:
Cost tier stratification separates capital-intensive on-premises builds from operational expenditure models—hybrid deployments split infrastructure ownership between customer balance sheets and service provider leases.
- Hybrid:Combines on-premises edge nodes with burst capacity to centralized cloud regions, enabling workload portability for seasonal manufacturing demand. Japanese automotive suppliers favor this model to preserve capital for METI-subsidized smart factory retrofits while maintaining elastic compute for simulation workloads.
- On-Premises:Fully customer-owned infrastructure adjacent to production lines or vehicle depots.
- Private Cloud:Single-tenant edge facilities operated by specialist providers on customer-dedicated hardware.
- Public Cloud:Shared edge nodes from hyperscale providers with unified control-plane management.
On-premises captures legacy manufacturing investment. Hybrid deployments are climbing the fastest as procurement patterns shift toward operational expenditure models.
End User:
Application intensity varies by sector—manufacturing and telecommunications drive hardware volume, while healthcare and retail concentrate software and services spend per node.
- Manufacturing:Precision manufacturers and automotive OEMs deploy microservers directly adjacent to production lines for quality-control inference and predictive maintenance. Germany's industrial corridor from Stuttgart to Wolfsburg concentrates demand, with EU AI Act conformity mandates forcing certified hardware tiers for automated decision-making systems.
- Telecommunications:Mobile network operators deploy multi-tenant edge facilities to support private 5G slices for enterprise customers. European operators outsource lifecycle management to specialist providers, displacing in-house engineering teams.
- Healthcare:Hospital networks deploy HIPAA-compliant local processing for surgical robotics and diagnostic imaging.
- Retail:Warehouse automation and inventory tracking drive edge node deployment at distribution centers.
Manufacturing dominates installed base. Healthcare is where expansion concentrates.
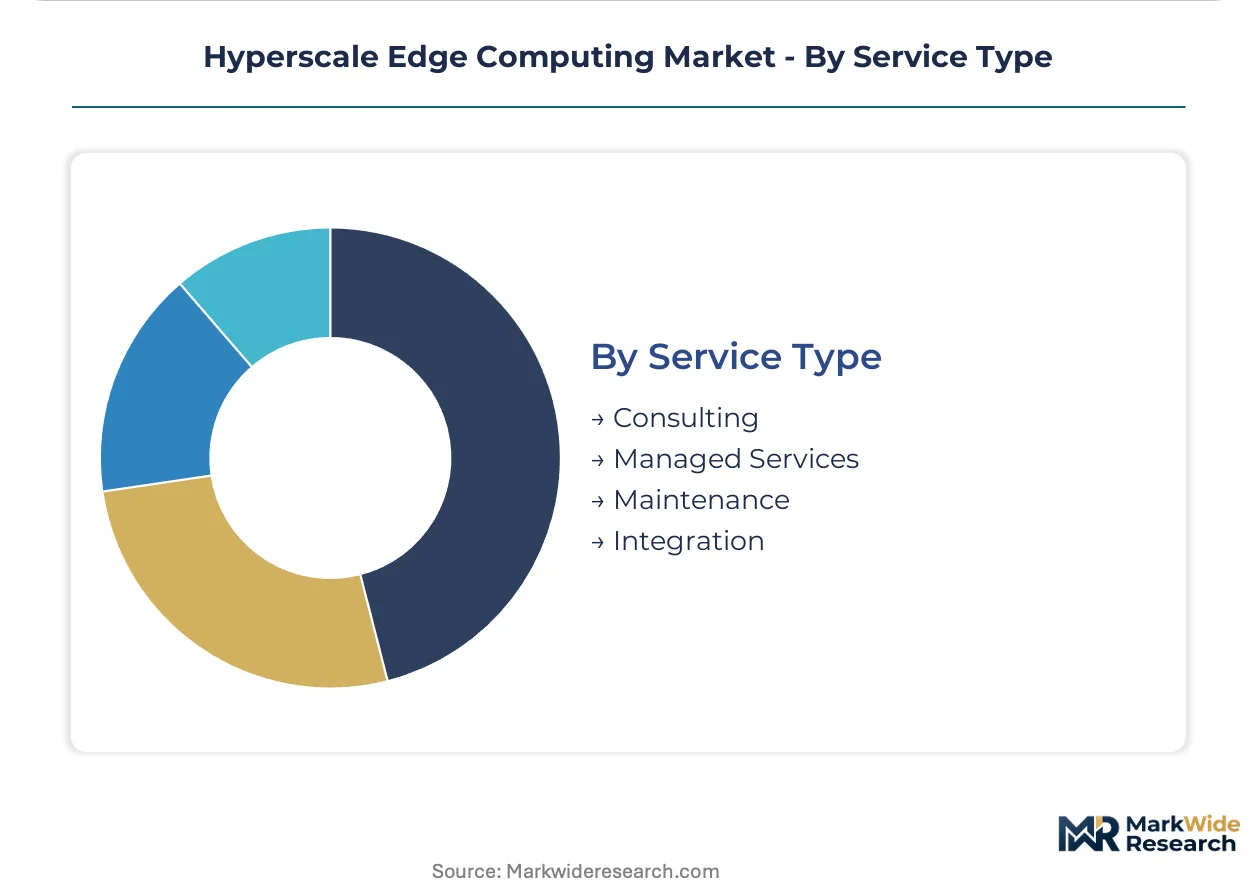
Service Type:
Margin concentration follows complexity gradient—integration and consulting capture project-based premiums, while managed services generate recurring revenue with multi-year contract tenors.
- Managed Services:Specialist providers assume full lifecycle management of edge infrastructure including orchestration, security patching, and thermal optimization. Telecommunications operators across European markets outsource these functions to reduce engineering headcount and accelerate deployment timelines.
- Integration:Middleware development for legacy OT protocol translation in brownfield manufacturing environments.
- Consulting:Architecture design for multi-jurisdiction data residency compliance.
- Maintenance:Hardware replacement and firmware update services for distributed node populations.
Integration dominates legacy deployment revenue. Managed services is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale edge infrastructure concentrates in industrial corridors where automotive OEMs and precision manufacturers co-locate compute with production lines. Germany's automotive belt and Japan's smart factory clusters anchor hardware procurement volumes. Regulatory divergence across the EU AI Act, FCC spectrum rules, and METI subsidies shapes deployment architectures.
United States
Autonomous vehicle fleets in Detroit and Austin compress latency requirements below 10 milliseconds for fleet coordination systems. FCC CBRS spectrum liberalization enables private 5G networks at industrial campuses without carrier dependency. Michigan and Texas concentrate edge node deployments adjacent to automotive engineering centers and vehicle depots.
Germany
Precision manufacturers along the Stuttgart-to-Wolfsburg corridor specify liquid-cooled microservers for quality-control inference at production line adjacency. EU AI Act conformity mandates force certified hardware tiers for automated decision-making systems. Bavaria and Baden-Württemberg host the densest concentration of edge infrastructure serving automotive OEM supply chains.
Japan
Automotive tier-1 suppliers favor hybrid deployment models to preserve capital for METI-subsidized smart factory retrofits. METI production-linked incentives accelerate direct procurement experimentation outside traditional telecommunications channels. Nagoya and Osaka industrial zones drive demand for ARM-based edge gateways with integrated neural processing units.
India
Production-linked incentives for semiconductor assembly and testing attract hyperscale edge hardware manufacturing to Gujarat and Tamil Nadu. Central Electricity Authority grid reliability standards shape facility siting decisions for 24/7 baseload power guarantees. Chennai and Ahmedabad emerge as assembly hubs for microservers destined to European and North American industrial markets.
South Korea
Telecommunications operators outsource edge infrastructure lifecycle management to specialist providers, displacing in-house engineering teams. Ministry of Trade, Industry and Energy smart factory programs channel subsidies toward hybrid cloud-edge architectures. Seoul Capital Area and Busan-Ulsan industrial zones concentrate multi-tenant edge facilities for private 5G enterprise slices.
Hyperscale Edge Computing Market Vendor Landscape
Concentration sits with hyperscale cloud providers and silicon architects who control the hardware-software interface. The vendor base splits between vertically integrated platform operators and specialist infrastructure fabricators. Three archetypes dominate: cloud-native platform providers, semiconductor architects with edge-optimized silicon, and telecommunications operators repositioning as managed services aggregators. Strategic moves center on AI-optimized edge silicon partnerships and unified control-plane extensions into on-premises environments.
Within the cloud platform tier, Amazon Web Services Inc. and Microsoft Corporation exemplify the vertically integrated archetype, each extending unified control-plane management from centralized regions into customer-owned facilities. NVIDIA occupies a position as the dominant inference acceleration specialist at the network boundary. These three anchors represent divergent strategic postures: AWS and Microsoft compete through control-plane ubiquity, while NVIDIA exemplifies the silicon-first approach to edge workload optimization.
| Leading Market Players |
|---|
| Amazon Web Services Inc. |
| Microsoft Corporation |
| Google Cloud |
| Hewlett Packard Enterprise Development LP |
| Intel Corporation |
| Cisco Systems Inc. |
| NVIDIA |
| Alibaba Cloud |
| Oracle Corporation |
| Others |
Supply Flow & Price Mechanics
Fourteen-to-eighteen-month IEC 62443 certification cycles compress vendor pricing power by gating market access, while Taiwan foundry concentration for advanced inference accelerators forces buyers into long-term offtake commitments that lock in cost structures regardless of spot silicon availability.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for edge infrastructure by mandating third-party conformity assessment for high-risk automated decision-making systems. Three-tier pricing stratifies across certified, pre-certified, and non-certified hardware tiers, with automotive OEMs in Germany absorbing premium positioning for audit-trail-compliant inference nodes. Cost compression in non-certified tiers intensifies as Japanese automotive suppliers source ARM-based microservers directly from silicon vendors, bypassing systems integrator markups. Manufacturing end users exhibit highest price sensitivity, while healthcare networks deploying HIPAA-compliant surgical robotics tolerate substantial premiums for sub-5 millisecond latency guarantees.
Supply Chain Analysis
Strategic stockpiling of advanced inference accelerators dominates procurement behavior as lead times stretch beyond standard planning horizons. Taiwan, South Korea, and the United States anchor supply for AI-optimized edge silicon, with German precision manufacturers and Japanese automotive tier-1s drawing from concentrated foundry output. Raw material dependencies center on high-bandwidth memory modules, liquid-cooling components, and specialized substrate materials. Single-source vulnerability at the leading-edge node level exposes procurement timelines to geopolitical friction. Distribution runs through direct OEM relationships for hardware and telecommunications operator marketplaces for orchestration software.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyperscale edge infrastructure investment cycles track automotive capital expenditure recovery patterns, with autonomous vehicle fleet expansion and smart factory retrofit programs serving as the cyclical demand anchor.
For Market Incumbents: Secure certification pipeline capacity by pre-positioning engineering resources for EU AI Act conformity assessment bottlenecks. Capture backward integration into liquid-cooled thermal component supply to defend margin position against Taiwan foundry pricing volatility. Lock multi-year managed services contracts with European telecommunications operators before outsourcing waves consolidate vendor relationships.
For New Entrants and Emerging Players: Differentiate on deterministic latency optimization for safety-critical workloads rather than throughput-per-watt competition with NVIDIA. Target healthcare edge convergence in Japan and South Korea, where METI and MOTIE smart factory subsidies accelerate procurement experimentation outside established cloud provider channels. Pursue channel partnerships with systems integrators specializing in brownfield OT protocol translation.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-as-utility play because edge node deployments generate recurring managed services revenue with multi-year contract tenors and high switching costs. Acquisition candidates include specialist providers of IEC 62443 certification consulting and private 5G network integrators with established European automotive relationships. Watch CBRS spectrum auction participation rates and India PLI scheme uptake as inflection indicators for demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Optimized Silicon Partnership | NVIDIA Grace-Hopper architecture locks in inference acceleration dominance at network boundaries. |
| Unified Control-Plane Extension | AWS Outposts and Microsoft Azure Stack HCI collapse operational complexity for hybrid deployments. |
| Managed Services Outsourcing | European telecommunications operators displace in-house engineering teams to specialist lifecycle providers. |
| Certification Pre-Positioning | Early IEC 62443 compliance investment gates vendor access to German automotive OEM procurement. |
| Direct Procurement Channel | Japanese automotive tier-1s bypass systems integrators to source ARM-based microservers from silicon vendors. |
Methodological Framework
A spread of perspectives from cloud platform engineering directors, telecommunications operator procurement leads, automotive OEM IT architects, and industrial automation systems integrators converged on the working assumptions underlying demand projections. Primary fieldwork combined structured interviews with secondary validation against hyperscaler capex disclosures, FCC spectrum allocation filings, EU regulatory impact assessments, and METI subsidy program documentation. Bottom-up node deployment counts triangulated against top-down infrastructure spending estimates across the analysis window.
Segmentation dimensions modeled include product type, deployment model, end-user vertical, and service type, with additional granularity on regulatory compliance tier and thermal architecture specification. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in comparable infrastructure markets. Forecast inputs incorporated private 5G spectrum allocation timelines, EU AI Act implementation schedules, and automotive fleet electrification roadmaps throughout the projection horizon.
Forecasts assume regulatory continuity in EU AI Act conformity frameworks and FCC CBRS licensing regimes; material policy shifts would require re-modeling demand trajectories for certified hardware tiers. Revision becomes warranted when Taiwan foundry utilization rates or European industrial electricity pricing volatility cross thresholds that compress facility operating margins below deployment viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Next Generation Technologies
Information and Communications Technology (ICT) Market
Next Generation Technologies
Ireland ICT Market
Next Generation Technologies
Next-Generation Communication Devices Market
Next Generation Technologies
Fog Computing Market
Next Generation Technologies
Poc Platform and Technology Market
Next Generation Technologies
M2M Connections Market
Next Generation Technologies
Enterprise Quantum Computing Market
Next Generation Technologies
Nearfield Communication (NFC) Market
Next Generation Technologies
Oman ICT Market
Next Generation Technologies
Quantum Information Processing Market
Next Generation Technologies
Global Next Generation Wireless Communication Market
Next Generation Technologies
Europe Quantum Computing Market
Next Generation Technologies
Bulgaria ICT Market
Next Generation Technologies
Smart Surfaces Market
Next Generation Technologies
5G New Radio Market
Next Generation Technologies
Malaysia ICT Market