
 5G Remote Radio Head Market | 2026-2036
5G Remote Radio Head Market Size, Share, and Industry Trends Forecast 2026-2036
5G Remote Radio Head Market Analysis
Aftermarket service revenue is reconfiguring margin distribution across the 5G Remote Radio Head value chain. Huawei sustains manufacturing scale advantages in integrated RRU assemblies. Samsung leverages its semiconductor captive supply for beamforming chipsets. Nokia anchors European operator relationships through Open RAN-compatible portfolio expansion.
A 5G Remote Radio Head is a transceiver unit that converts digital baseband signals to radio frequency for transmission over cellular spectrum, typically operating in sub-6 GHz or millimeter wave bands with output power ranging from tens of watts to several hundred watts depending on macro or small cell deployment. Its primary purpose is to extend network capacity and coverage while enabling centralized baseband processing through fronthaul interfaces such as eCPRI. Massive MIMO configurations dominate outdoor macro deployments due to spectral efficiency gains from 64T64R and 32T32R arrays. Sub-6 GHz technology occupies the largest installed base because of propagation advantages for wide-area coverage. Millimeter wave installations concentrate in dense urban hotspots and indoor venues where high bandwidth compensates for limited range.
The FCC in the United States, ETSI and national regulators across Europe, and Japan's MIC enforce spectrum allocation, electromagnetic exposure limits, and equipment certification standards that directly shape product design cycles and market entry timelines for Remote Radio Head vendors. Open RAN security specifications from the O-RAN Alliance and national cybersecurity frameworks in Germany, Japan, and South Korea are adding compliance layers that favor modular, interoperable architectures over proprietary integrated systems. Stakeholders must monitor evolving spectrum auction schedules and Open RAN mandate timelines to align R&D roadmaps with procurement cycles across tier-one operators and private network deployers.
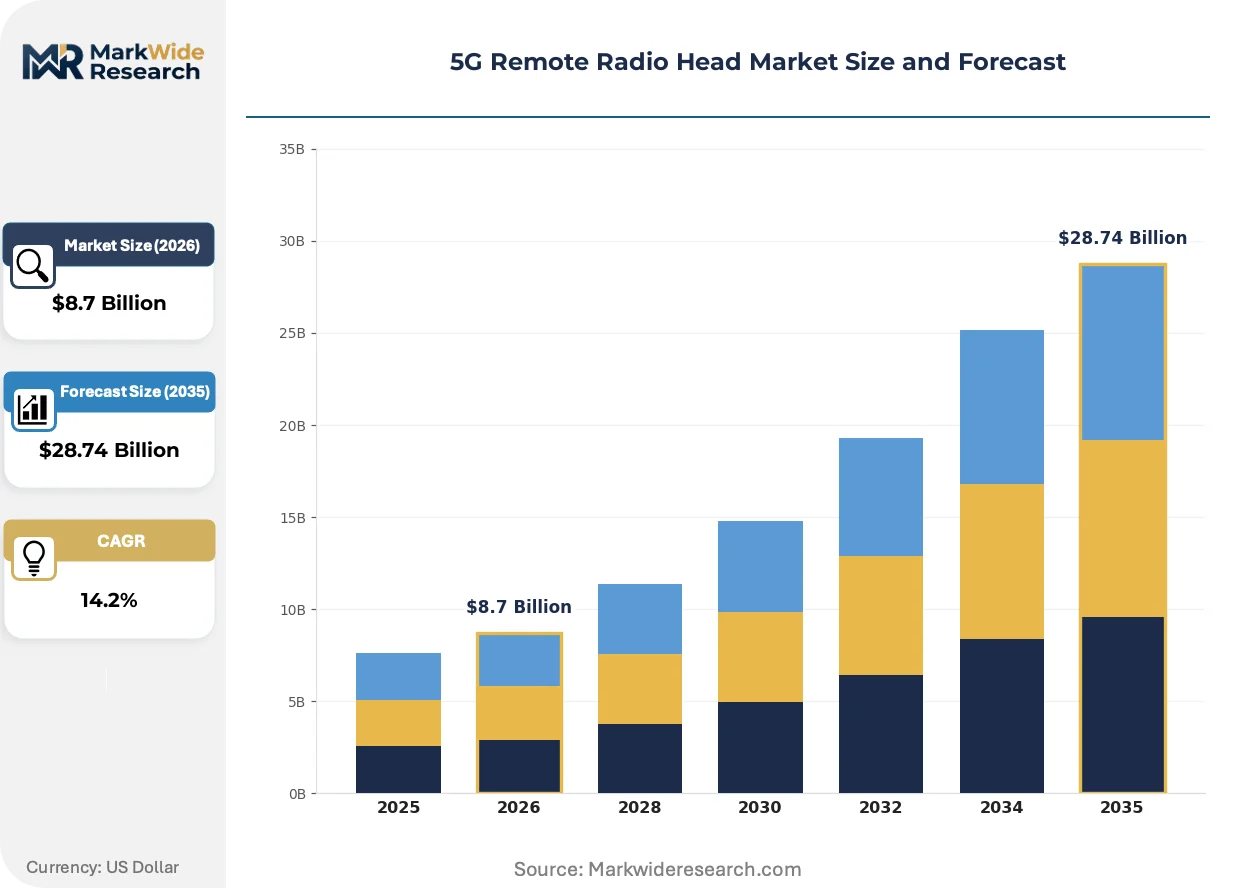
Market Dynamics
Open RAN architecture mandates from the FCC and EU frameworks are compressing proprietary hardware cycles while forcing interoperability investments across multi-vendor supply chains.
Growth Catalysts
- Massive MIMO Deployment:64T64R and 32T32R configurations in dense urban corridors are pulling demand for high-channel-count remote radio heads as operators maximize spectral efficiency per site.
- EU Open RAN Framework:European regulatory pressure for vendor interoperability is accelerating procurement of modular, standards-compliant equipment across German and French operator networks.
- Private Network Expansion:Manufacturing campuses and logistics hubs in Japan and South Korea are deploying integrated RRUs for localized 5G coverage with guaranteed latency performance.
Market Restraints
- Beamforming Chipset Concentration:Advanced semiconductor fabrication for mmWave beamforming remains concentrated among captive foundry operations, creating supply vulnerability for independent RRU vendors.
- Electromagnetic Exposure Compliance:Japan's MIC and Germany's Federal Network Agency enforce stringent RF exposure limits that extend product certification timelines and restrict installation density.
- Copper and Aluminum Input Volatility:Raw material price swings for thermal management housings and RF cabling directly compress gross margins on high-power macro cell units.
Strategic Opportunities
- India Spectrum Auction Tailwinds:Reliance Jio and Bharti Airtel 5G rollout commitments create procurement windows for sub-6 GHz massive MIMO configurations through 2027.
- AI-Driven Network Optimization:Convergence of machine learning inference at the RRU edge with centralized baseband processing enables predictive beam management and energy savings.
- Enterprise Channel Bypass:Direct-to-factory sales models for private 5G deployments circumvent traditional operator procurement cycles, capturing full-stack margins.
Industry Challenges
- RF Engineer Talent Scarcity:Specialized expertise in mmWave antenna design and thermal-mechanical integration for outdoor enclosures outpaces university pipeline output.
- Legacy 4G Integration Friction:Multi-standard RRUs must maintain backward compatibility with existing baseband hotels while adding 5G NR capability, complicating firmware architecture.
- O-RAN Security Certification Delays:Fragmented national cybersecurity frameworks across Germany, Japan, and South Korea create overlapping compliance requirements that stall product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Remote Radio Head Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Massive MIMO, Conventional RRU, Ultra Compact RRU, Integrated RRU Technology: Millimeter Wave, Sub-6 GHz, Beamforming, Network Slicing End User: Telecom Operators, Enterprises, Government, Private Network Providers Installation: Outdoor, Indoor, Rooftop, Pole-Mounted |
| Companies Covered | ZTE Corporation, KMW, Huawei, NEC Corporation, Fujitsu, Nokia, Comba Telecom, NXP Semiconductors, Samsung, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Remote Radio Head Market Emerging Trajectories
Virtualization of baseband functions and disaggregation of hardware layers are fundamentally restructuring how remote radio heads interface with network cores and how vendors compete on software value.
Cloud-native RAN software is virtualizing baseband processing that previously ran on proprietary silicon. Tier-one operators in South Korea and Germany are deploying virtualized distributed units alongside commercial-off-the-shelf servers. This architecture is virtualizing the traditional RRU-DU boundary, enabling third-party software vendors to capture value historically retained by hardware-integrated suppliers.
The O-RAN Alliance security specifications and EU Cybersecurity Act are mandating zero-trust architectures for fronthaul interfaces. Equipment vendors must now embed hardware security modules and encrypted eCPRI transport as standard features. Japanese operators are responding by requiring O-RAN compliance certifications before final acceptance testing, filtering supplier pools to those with dedicated security engineering teams.
Enterprise buyers are unbundling hardware procurement from managed service contracts for private 5G deployments. Manufacturing conglomerates in Japan and automotive clusters in Germany now source RRUs directly while contracting system integration separately. This pattern is most visible in industrial IoT verticals where internal IT organizations possess sufficient RF planning capability to self-deploy.
5G Remote Radio Head Market Segmentation
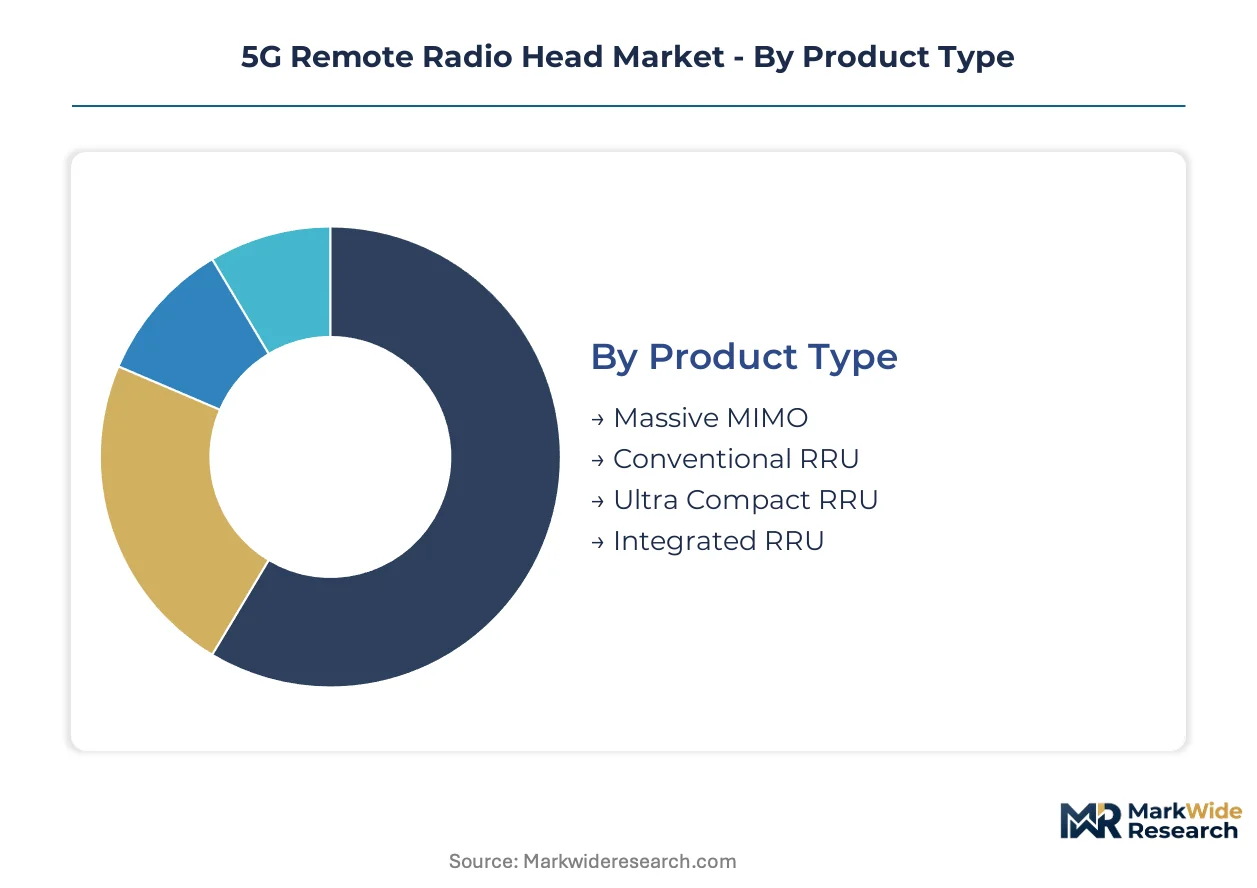
5G Remote Radio Head segmentation reveals how deployment scenarios, spectrum strategies, and buyer economics fragment procurement patterns. Operators balance coverage density against unit economics, while enterprise buyers prioritize form factor and latency guarantees over raw throughput.
Product Type:
Massive MIMO configurations dominate urban corridors where spectral efficiency per site determines network economics, while compact and integrated variants serve edge cases requiring rapid deployment or captive infrastructure ownership.
- Massive MIMO:64T64R and 32T32R arrays with active antenna systems integrate hundreds of radiating elements and transceiver chains into single enclosures. Dense urban corridors in Japan and South Korea concentrate procurement as operators maximize capacity per macro site without additional tower real estate.
- Conventional RRU:Standalone transceiver units separate from antenna systems, typically 4T4R or 8T8R configurations. Rural coverage expansions across Germany and suburban rollouts in the United States sustain demand where channel count requirements remain modest and existing antenna infrastructure can be reused.
- Ultra Compact RRU:Low-power units under 10 liters volume designed for rapid pole mounting and concealed urban deployment.
- Integrated RRU:Combined radio and baseband units for private networks and enterprise edge deployments.
The dominant share belongs to Massive MIMO, while Ultra Compact RRU is closing the gap fastest.
Technology:
Spectrum positioning and signal processing architectures divide the technology landscape, with propagation physics and regulatory band availability determining regional deployment mixes.
- Sub-6 GHz:Operating in 3.5 GHz and 2.6 GHz bands with superior building penetration and range economics. Sub-6 GHz installations anchor wide-area coverage across the United States, Europe, and Asia-Pacific due to propagation advantages that reduce site count requirements for equivalent geographic coverage.
- Beamforming:Active antenna systems with dynamic beam steering and null placement for interference mitigation. Urban hotspots and stadium venues drive adoption where user density demands spatial multiplexing gains and targeted energy delivery to mobile devices.
- Millimeter Wave:24 GHz and above operation delivering multi-gigabit throughput across limited ranges.
- Network Slicing:Virtualized radio resource allocation enabling differentiated service tiers over shared infrastructure.
Sub-6 GHz commands the largest installed base, though beamforming exhibits the steepest expansion trajectory as massive MIMO penetration accelerates.
End User:
Buyer sophistication and procurement autonomy create distinct commercial dynamics, from centralized operator tenders to direct enterprise sourcing.
- Telecom Operators:Tier-one carriers with centralized procurement functions and multi-year infrastructure roadmaps. Japanese operators NTT Docomo and KDDI, alongside German incumbents Deutsche Telekom and Vodafone, anchor volume demand through macro network densification programs and 5G standalone core migrations.
- Enterprises:Manufacturing conglomerates, logistics hubs, and mining operations deploying captive 5G infrastructure. Automotive clusters in Germany and semiconductor fabs in South Korea source integrated RRUs directly to guarantee deterministic latency for robotic control systems.
- Government:Defense and public safety agencies requiring hardened, spectrum-agile radio heads.
- Private Network Providers:System integrators and neutral host operators offering 5G-as-a-service to vertical industries.
Telecom Operators retain the dominant procurement volume, yet Enterprises are expanding most quickly as private spectrum allocations proliferate.
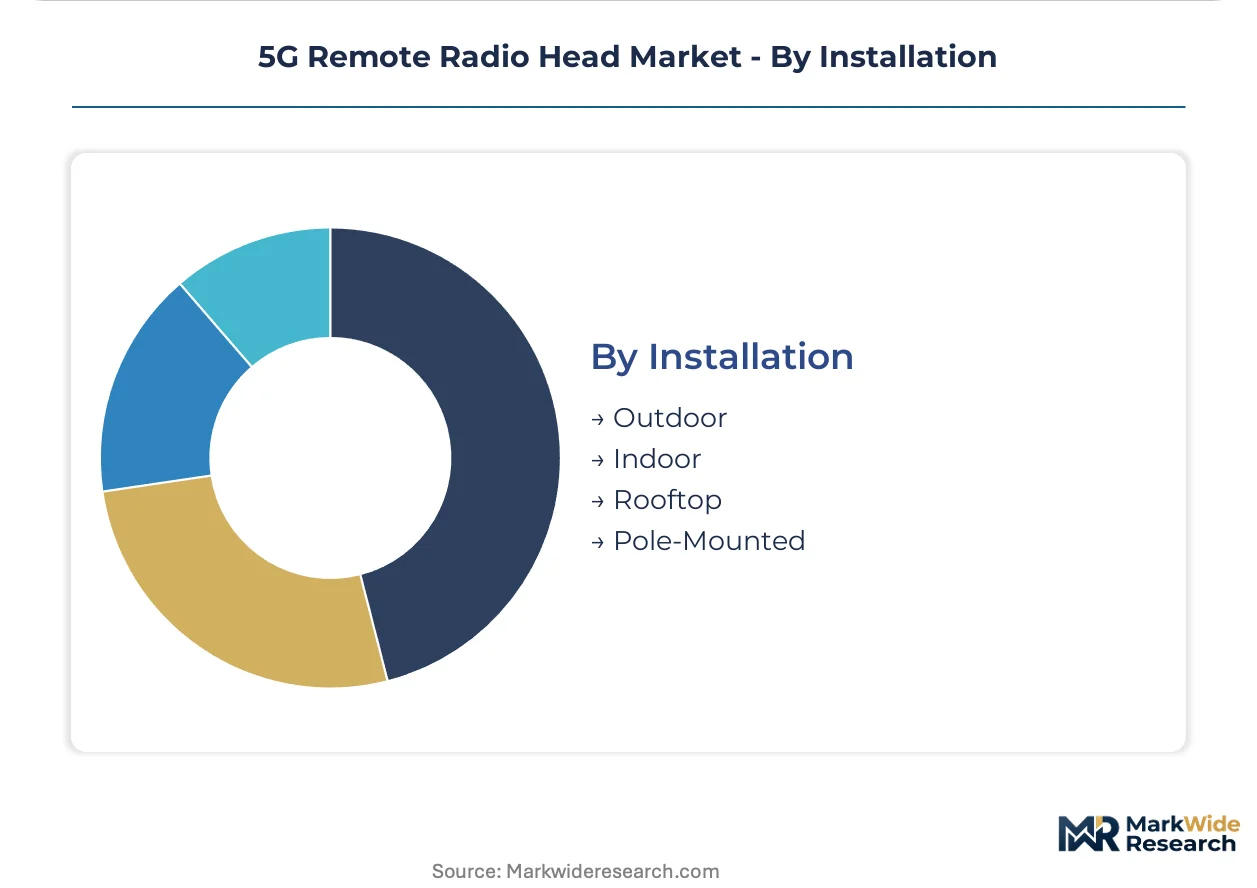
Installation:
Physical mounting constraints and environmental exposure ratings segment hardware specifications, with thermal management and wind loading driving enclosure engineering.
- Outdoor:IP67-rated enclosures with active cooling and corrosion-resistant finishes for macro towers and monopoles. Macro site deployments across South Korea and Germany concentrate demand where thermal design must sustain full transmit power across ambient temperature extremes from -40°C to +55°C.
- Indoor:Compact, fanless units for stadiums, airports, and shopping complexes. Dense venue coverage in Japan's urban centers and Germany's exhibition halls drives procurement where aesthetic constraints and human proximity limit noise and visual impact.
- Rooftop:Intermediate form factors balancing wind loading with output power for urban infill.
- Pole-Mounted:Street furniture and utility pole attachments for small cell densification.
Outdoor installations hold the dominant deployment share, while Indoor configurations are gaining share fastest as venue densification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in Germany exhibit the lowest price elasticity as automotive clusters prioritize latency guarantees over unit cost, while Indian operators show highest sensitivity as spectrum auction debt loads constrain capex flexibility.
United States
Verizon and AT&T macro densification programs drive massive MIMO procurement for urban corridors. FCC spectrum auctions and Open RAN interoperability mandates compress vendor qualification timelines. Dallas-Fort Worth and Atlanta metropolitan clusters anchor deployment concentration for stadium and airport venue coverage.
Germany
Deutsche Telekom and Vodafone 5G standalone core migrations sustain demand for sub-6 GHz configurations with O-RAN compliance. The Federal Network Agency enforces stringent RF exposure limits that extend certification cycles. Bavaria's automotive manufacturing belt around Munich sources integrated RRUs directly for robotic control networks.
Japan
NTT Docomo and KDDI prioritize 64T64R deployments in Tokyo and Osaka dense urban zones. MIC electromagnetic exposure regulations restrict installation density and tower proximity. Yokohama's port logistics hub deploys private 5G infrastructure with guaranteed latency for automated container handling.
South Korea
SK Telecom and KT beamforming investments concentrate in Seoul Capital Area hotspots. National cybersecurity frameworks overlap with O-RAN Alliance specifications, creating dual compliance layers. Samsung's captive semiconductor supply anchors domestic RRU production scale for export markets.
India
Reliance Jio and Bharti Airtel 5G rollout commitments through 2027 create procurement windows for cost-optimized sub-6 GHz units. TRAI spectrum allocation rules and phased manufacturing program requirements shape vendor selection criteria. Maharashtra's Pune industrial corridor pilots private network deployments for manufacturing automation.
5G Remote Radio Head Market Vendor Landscape
Capability concentration sits with integrated semiconductor-to-system vendors; scale advantage sits with telecom infrastructure incumbents with captive operator relationships. The market structures around three tiers: captive silicon suppliers, Open RAN modular specialists, and integrated hardware-software vendors. Dominant competitive moves include strategic partnerships for beamforming chipset access and geographic expansion into private network verticals bypassing traditional operator channels.
Among Asia-Pacific headquartered vendors, Huawei and ZTE Corporation exemplify integrated infrastructure scale, while Samsung occupies a position bridging captive semiconductor supply with RRU system integration. Nokia anchors the European vendor tier through O-RAN-compatible portfolio positioning. These three represent divergent strategic archetypes: silicon-captive vertical integration, cost-optimized manufacturing scale, and standards-compliant modular architecture.
| Leading Market Players |
|---|
| ZTE Corporation |
| KMW |
| Huawei |
| NEC Corporation |
| Fujitsu |
| Nokia |
| Comba Telecom |
| NXP Semiconductors |
| Samsung |
| Others |
Supply Flow & Price Mechanics
Shenzhen's electronics manufacturing corridor anchors global RRU assembly capacity, with its foundry and EMS concentration translating directly into procurement leverage for tier-one operators negotiating multi-year supply agreements. Downstream pricing power concentrates with telecom operators in Germany and Japan, while raw material volatility in copper and aluminum thermal management components compresses margins for independent vendors lacking captive semiconductor supply.
Pricing Analysis
Aftermarket service contracts and extended warranty tiers now drive lifetime value capture across the RRU value chain. Three-tier pricing structure across premium O-RAN-certified, standard interoperable, and economy proprietary configurations segments buyer access, with certification grade and volume scale as primary differentiation levers. Cost compression in economy-tier units is intensifying because of India's spectrum auction debt loads constraining Reliance Jio and Bharti Airtel capex flexibility. Enterprise buyers in Germany's automotive belt exhibit lowest price sensitivity, prioritizing latency guarantees over unit economics.
Supply Chain Analysis
Foundry capacity at TSMC and Samsung's captive semiconductor operations holds concentrated control over beamforming chipset fabrication for mmWave arrays. Geographic supply concentration centers on China for thermal management housings, South Korea for RF front-end components, and Taiwan for advanced semiconductor nodes. Raw material dependencies draw from copper and aluminum for enclosures, gallium nitride substrates for power amplifiers, and specialized RF laminates for antenna boards. Single-source vulnerability in advanced beamforming silicon creates structural risk. Distribution runs through direct operator procurement teams and emerging direct-to-factory enterprise channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated telecom operators with multi-year infrastructure roadmaps and toward fragmented enterprise buyers self-deploying private networks, fragmenting traditional vendor-customer relationships.
For Market Incumbents: Build switching-cost moats through embedded software value and O-RAN certification depth. Deepen backward integration into beamforming silicon to offset captive foundry advantages held by Samsung. Anchor capacity expansion in India to capture Reliance Jio and Bharti Airtel procurement windows. Defend against modular specialists by controlling fronthaul interface standardization. For New Entrants and Emerging Players: Pursue private network verticals in Germany's automotive clusters and Japan's logistics hubs where operator bypass creates white-space access. Target indoor stadium and airport venue deployments as most penetrable segment given aesthetic constraints favoring compact form factors. Establish direct sales engineering presence in industrial zones rather than competing through operator channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among system integrators offering managed private network services with hardware refresh cycles. Long-term viability favors vendors with O-RAN compliance depth and security certification capabilities across German, Japanese, and South Korean frameworks. Acquisition target archetype: modular RRU specialists with dedicated security engineering teams and existing neutral-host operator relationships. Watch O-RAN mandate enforcement timelines as inflection indicator for procurement preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| O-RAN Compliance Certification | NTT Docomo and Deutsche Telekom now require certification before final acceptance testing, filtering supplier pools. |
| Beamforming Chipset Partnership | Access to Samsung or TSMC foundry capacity secures supply priority for 64T64R massive MIMO configurations. |
| Private Network Direct Sales | Bypassing operator procurement captures full-stack margins in Germany's automotive manufacturing belt. |
| AI-Driven Network Optimization | Machine learning inference at the RRU edge enables predictive beam management and energy savings for SK Telecom. |
| India Manufacturing Localization | TRAI phased manufacturing program requirements shape vendor selection criteria for Reliance Jio rollout commitments. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with RF engineering directors at tier-one operators, procurement leads at automotive OEMs deploying private 5G, semiconductor foundry planning officers, and system integrators specializing in neutral-host deployments. Secondary validation drew from FCC equipment authorization databases, ETSI standardization filings, O-RAN Alliance specification releases, and customs trade data for RRU component flows. Bottom-up unit shipment estimates triangulated against top-down operator capex disclosures.
Calibration against historical deployment cycles and regulatory milestone timing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, spectrum band, installation environment, end-user category, and regional regulatory cluster. CAGRs were derived from slope analysis of deployment trajectories, adjusted for spectrum auction schedules and Open RAN mandate phase-ins. Forecast inputs incorporated beamforming chipset availability constraints and electromagnetic exposure compliance timeline variations across Japan's MIC and Germany's Federal Network Agency.
Macroeconomic conditions sit as an overlay; deviation in copper and aluminum commodity indices, semiconductor capital expenditure cycles, or spectrum auction financing costs would shift the trajectory. Forecasts reflect documented assumptions regarding Open RAN adoption velocity and private network enterprise penetration. Quarterly review of operator procurement pipeline disclosures and foundry capacity utilization indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Bangladesh Telecommunication Industry Market
Telecommunications
Telecom Managed Services Market
Telecommunications
Europe Telecom Expense Management Market
Telecommunications
Argentina Telecom Market
Telecommunications
Virtualized RAN (Vran) Market
Telecommunications
Hungary ICT Market
Telecommunications
South Africa Telecom Market
Telecommunications
IoT Telecom Services Market
Telecommunications
Costa Rica Telecom Market
Telecommunications
Germany ICT Market
Telecommunications
Switzerland Telecom Market
Telecommunications
Indonesia Telecom Towers Market
Telecommunications
Utility Communications Market
Telecommunications
LTE Base Station System Market
Telecommunications
Peru Telecom Market
Telecommunications
Rich Communication Services (RCS) Messaging Market