
 Global Roaming Tariff Market | 2026-2036
Global Roaming Tariff Market Size, Share, and Industry Trends Forecast 2026-2036
Global Roaming Tariff Market Foresight
European wholesale roaming rate caps are decoupling operator margins from traditional per-minute voice economics. Deutsche Telekom AG leverages its integrated pan-European network to sustain cross-border data volumes at regulated wholesale ceilings. Bharti Airtel Limited anchors its roaming portfolio on African and Middle Eastern corridors where bilateral agreements still permit flexible retail pricing.
Global roaming tariffs represent the negotiated price schedules that mobile network operators apply when subscribers access voice, data, or SMS services outside their home network registration territory, typically measured in per-megabyte data increments or per-minute voice intervals and settled through wholesale clearinghouse arrangements between host and home operators. The primary commercial purpose is to monetize cross-border network access while maintaining subscriber connectivity continuity during international travel. Data roaming dominates current revenue pools as smartphone-dependent travelers consume bandwidth-intensive applications, while bundled plans capture the fastest-growing subscriber preference by capping usage uncertainty. Voice roaming persists as a mature margin contributor among business travelers requiring reliable callback numbers, though its share of total roaming yield is compressing.
The European Commission's Roam Like at Home regulation and the International Telecommunication Union's wholesale accounting rate frameworks jointly constrain retail pricing flexibility while mandating cost-oriented wholesale transparency. The Federal Communications Commission in the United States enforces bilateral roaming reciprocity rules that prevent dominant carriers from withholding domestic roaming access to smaller competitors, indirectly shaping outbound international negotiation leverage. Stakeholders must monitor whether emerging market regulators in India and Brazil replicate EU-style retail price caps or preserve bilateral commercial flexibility as 5G standalone roaming protocols mature.
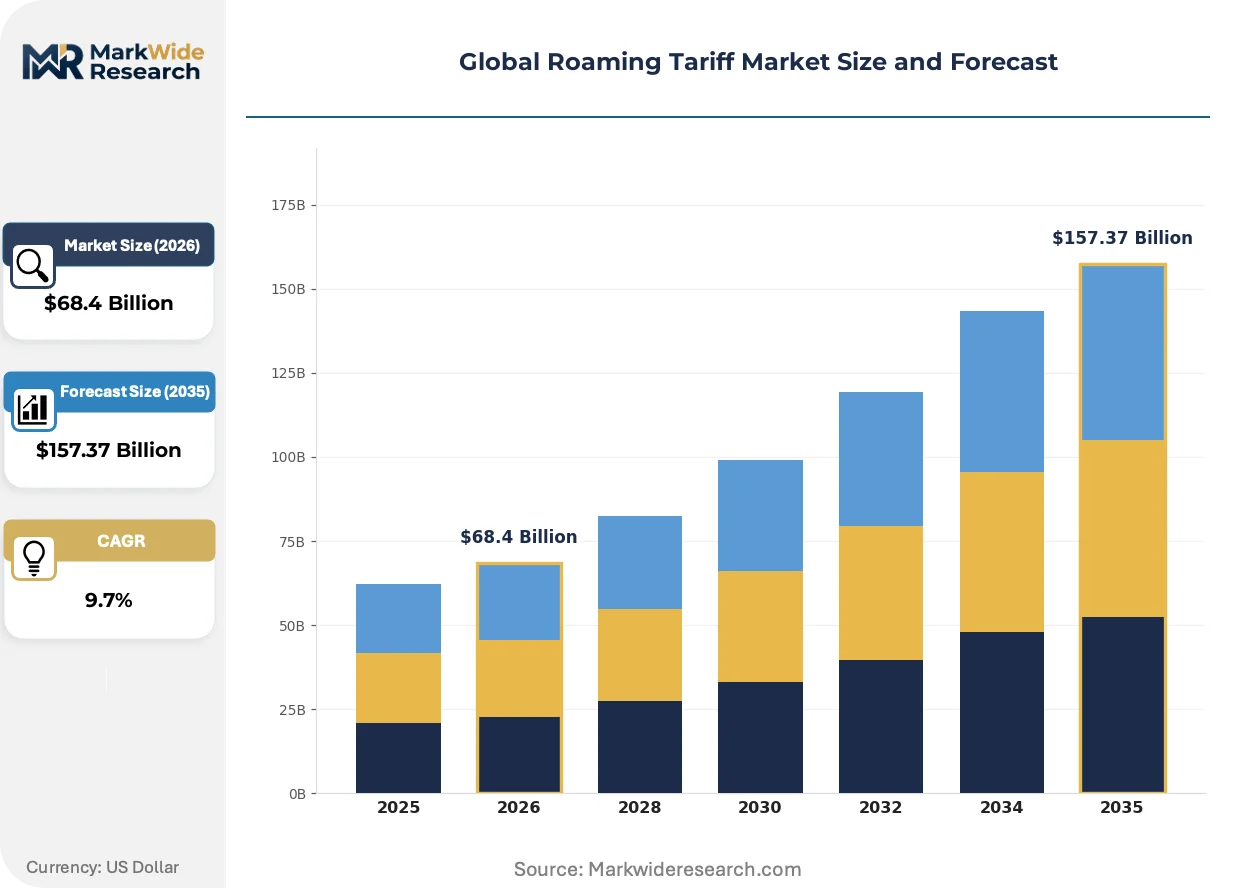
Market Dynamics
The European Union's Roam Like at Home framework has permanently altered how operators monetize cross-border mobility, forcing wholesale rate caps to subsume legacy per-minute voice economics while data volumes surge.
Growth Catalysts
- 5G Standalone Roaming Protocols:The International Telecommunication Union's accounting rate frameworks are enabling seamless authentication handoffs between host and home networks, accelerating bandwidth-intensive application usage among international travelers.
- Business Traveler Mobility:Corporate account procurement of bundled data roaming plans is compressing subscriber churn as finance departments negotiate enterprise-wide connectivity guarantees.
- Asia-Pacific Corridor Density:Bilateral agreements connecting China, Japan, and India are sustaining flexible retail pricing architectures where wholesale reciprocity remains commercially negotiated rather than regulatorily capped.
Market Restraints
- Wholesale Margin Compression:The European Commission's retail surcharge abolition has eliminated price elasticity on voice and data services, constraining operator profitability across Schengen-zone corridors.
- Clearinghouse Concentration:Settlement infrastructure for inter-operator roaming charges aggregates through a limited pool of specialized financial intermediaries, creating systemic counterparty exposure.
- Legacy Voice Dependency:Per-minute billing architectures still underpin roaming revenue recognition systems, delaying full migration to pure data-centric monetization models.
Strategic Opportunities
- IoT Roaming Specialization:Machine-to-machine connectivity across automotive and industrial telemetry applications is opening subscription models decoupled from human traveler seasonality.
- Regulatory Arbitrage Corridors:Bilateral agreements in African and Middle Eastern markets preserve flexible retail pricing where the EU's Roam Like at Home framework has not extended.
- Edge Computing Convergence:Distributed cloud infrastructure at network boundaries is enabling latency-sensitive roaming services for financial trading and telemedicine applications.
Industry Challenges
- Interoperability Certification Delays:GSMA's IR.21 and IR.85 technical specifications require continuous compliance updates, extending time-to-market for new roaming service launches.
- Legacy Billing System Integration:Convergent charging platforms must reconcile real-time data session metering with batch-processed wholesale settlement cycles, creating reconciliation complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Roaming Tariff Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $157.37 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Voice Roaming, Data Roaming, SMS Roaming, International Call Packages, Roaming Add-ons End User: Business Travelers, Leisure Tourists, Digital Nomads, Expatriates Distribution Channel: Telecom Operators, Online Marketplaces, Mobile Retailers, Travel Agencies Pricing Model: Per Use, Daily Pass, Monthly Subscription, Pay As You Go, Bundled Plans |
| Companies Covered | Deutsche Telekom AG, Telefónica S.A., AT&T Inc., NTT Docomo Inc., Bharti Airtel Limited, Vodafone Group PLC, China Mobile Ltd., Orange S.A., Verizon Communications Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Roaming Tariff Market Shifts & Advancements
Roaming tariff architecture is fragmenting between regulatorily capped wholesale corridors and commercially flexible bilateral markets, with technology convergence determining competitive positioning in each zone.
5G Standalone (SA) roaming with network slicing capabilities is electrifying how operators segment quality-of-service guarantees. Business travelers accessing bandwidth-intensive video conferencing now demand dedicated slices with committed latency thresholds. This capability is compressing differentiation between premium-tier mobile network operators and mid-market competitors lacking edge infrastructure.
REACH and the EU AI Act are mandating algorithmic transparency in roaming fraud detection systems. Automated traffic analysis tools must now document decision pathways for blocked or throttled sessions. European operators are responding by restructuring machine-learning procurement contracts to include audit rights and explainability modules.
Enterprise procurement teams are consolidating roaming spend under managed mobility service contracts with committed volume tiers. Traditional per-employee reimbursement models are yielding to centralized billing platforms that aggregate usage across thousands of international travelers. This pattern is most visible in Germany and France, where large manufacturing conglomerates negotiate pan-European connectivity guarantees.
Global Roaming Tariff Market Segmentation
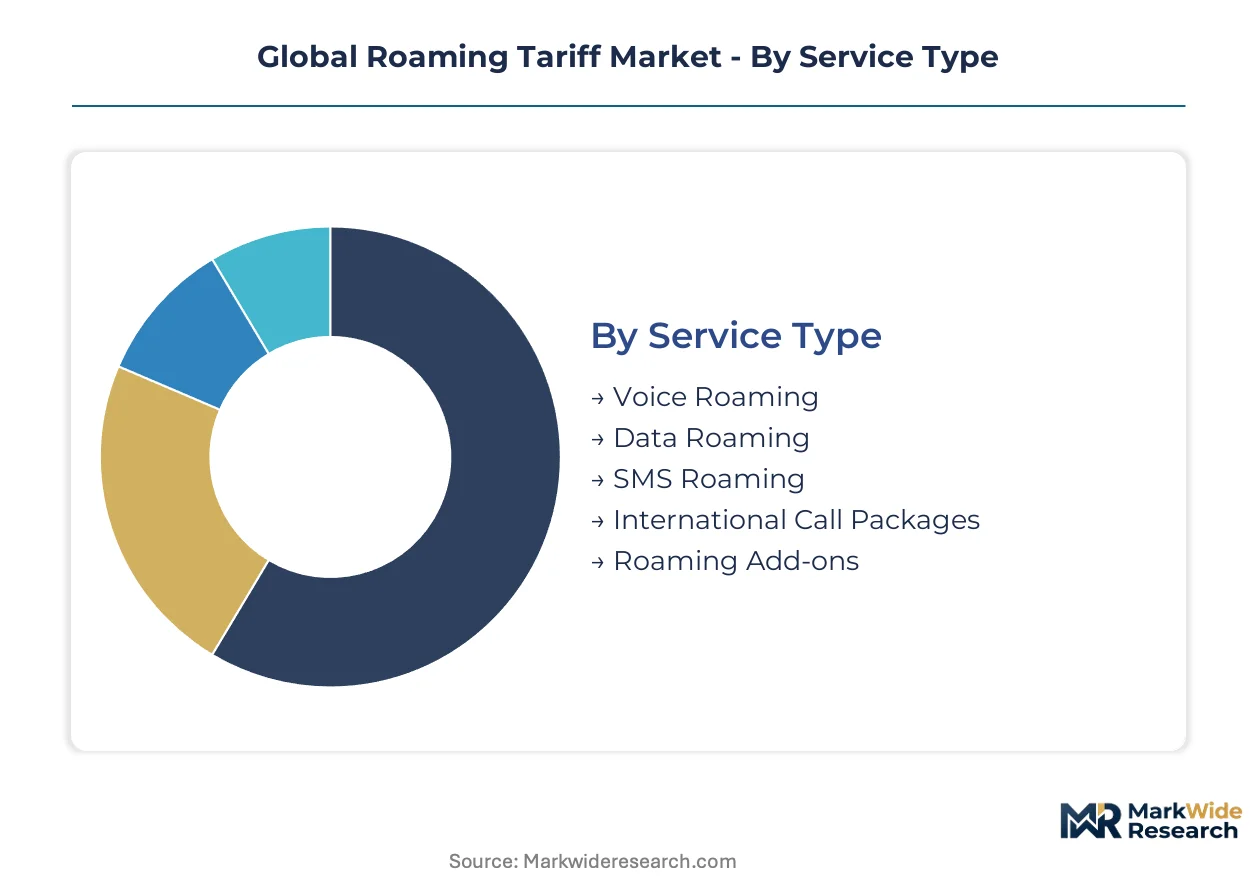
Roaming tariff segmentation reflects divergent monetization strategies across service types, user behaviors, and procurement channels. Operators calibrate wholesale negotiations and retail packaging against distinct willingness-to-pay profiles and usage predictability.
Service Type:
Enterprise procurement teams prioritize predictability over per-unit economics when selecting roaming service tiers for employee mobility programs.
- Voice Roaming:Per-minute billing architectures persist for callback reliability requirements among corporate account holders. Deutsche Telekom and Bharti Airtel maintain dedicated voice roaming portfolios for financial services clients in Frankfurt and Mumbai corridors where regulatory callback mandates apply.
- Data Roaming:Megabyte-tiered and unlimited session models dominate current revenue pools as bandwidth-intensive applications displace legacy voice dependencies. Asia-Pacific corridors connecting China, Japan, and India sustain the steepest data volume trajectories where 5G standalone protocols enable network slicing guarantees.
- SMS Roaming:Two-factor authentication and banking alert traffic sustains residual demand despite OTT messaging displacement. European operators bundle SMS roaming as a loss-leader within Roam Like at Home compliant packages.
- International Call Packages:Pre-negotiated minute buckets for outbound dialing from host networks serve price-sensitive leisure segments. African and Middle Eastern bilateral agreements preserve flexible retail pricing architectures for this category.
- Roaming Add-ons:Session-based top-ups activated through self-service portals capture impulse purchases at airport arrival zones. Online marketplace distribution concentrates demand for this segment.
Data roaming leads on scale; roaming add-ons lead on momentum.
End User:
Usage intensity and price elasticity diverge sharply across mobility purpose, forcing operators to maintain parallel pricing architectures.
- Business Travelers:Corporate procurement departments negotiate enterprise-wide connectivity guarantees with committed volume tiers and SLA-backed latency thresholds. Germany and France exhibit the densest concentration of managed mobility service contracts among manufacturing conglomerates.
- Leisure Tourists:Price-sensitive episodic users activate short-duration daily passes or rely on bundled travel insurance products. Seasonal demand spikes concentrate in Mediterranean and Southeast Asian destination corridors.
- Digital Nomads:Extended-stay remote workers require multi-month subscriptions with regional coverage flexibility. Portugal and Estonia have attracted dense clustering of this segment through specialized visa frameworks.
- Expatriates:Long-term foreign residents demand local-number portability with home-country reachability preserved. UAE and Singapore host the largest expatriate roaming subscriber bases relative to domestic population.
Business travelers anchor revenue stability; digital nomads drive subscription model innovation.
Distribution Channel:
Channel selection determines margin capture and customer acquisition cost structures for roaming service providers.
- Telecom Operators:Direct carrier relationships enable integrated billing and loyalty program linkage. Incumbent operators in Germany, Japan, and India leverage proprietary retail footprints for roaming package attachment.
- Online Marketplaces:Aggregator platforms compare real-time pricing across multiple host networks. This channel concentrates demand among price-sensitive leisure tourists and digital nomads prioritizing transparency.
- Mobile Retailers:Physical point-of-sale activation at airports and transit hubs captures impulse purchases. Travel corridor density in Dubai, Singapore, and Amsterdam sustains specialized roaming retail operations.
- Travel Agencies:Bundled itinerary packaging embeds connectivity within comprehensive trip provisioning. Corporate travel management companies in France and the United States consolidate roaming spend under centralized procurement.
Telecom operators dominate current volume; online marketplaces are expanding most quickly.
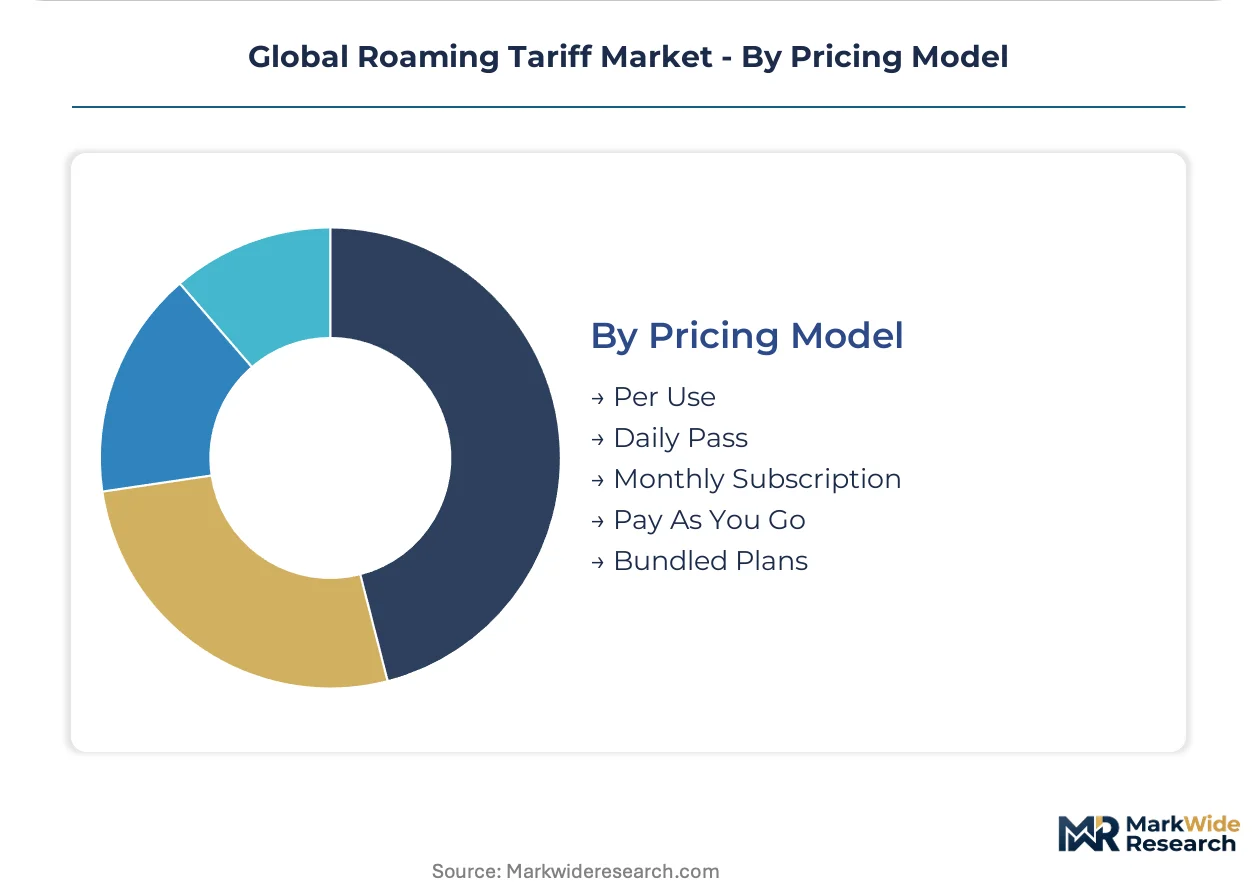
Pricing Model:
Monetization architecture selection balances revenue predictability against usage risk exposure for operators and subscribers.
- Per Use:Metered consumption without commitment suits highly irregular travel patterns. This model retains relevance in African and Middle Eastern corridors lacking retail price cap frameworks.
- Daily Pass:Fixed-fee 24-hour activation eliminates bill shock anxiety for short-stay tourists. European operators refined this structure under Roam Like at Home transitional arrangements.
- Monthly Subscription:Recurring revenue models with regional or global coverage tiers target frequent travelers. Corporate account procurement in Germany and Japan concentrates demand here.
- Pay As You Go:Pre-loaded credit balances with automatic top-up triggers serve unbanked or privacy-conscious segments. This model persists in cash-preferred economies.
- Bundled Plans:Integrated domestic and roaming allowances within standard subscription tiers. EU regulatory mandates have normalized this structure across Schengen-zone corridors.
Monthly subscriptions anchor enterprise procurement; bundled plans are gaining share fastest where retail price caps apply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
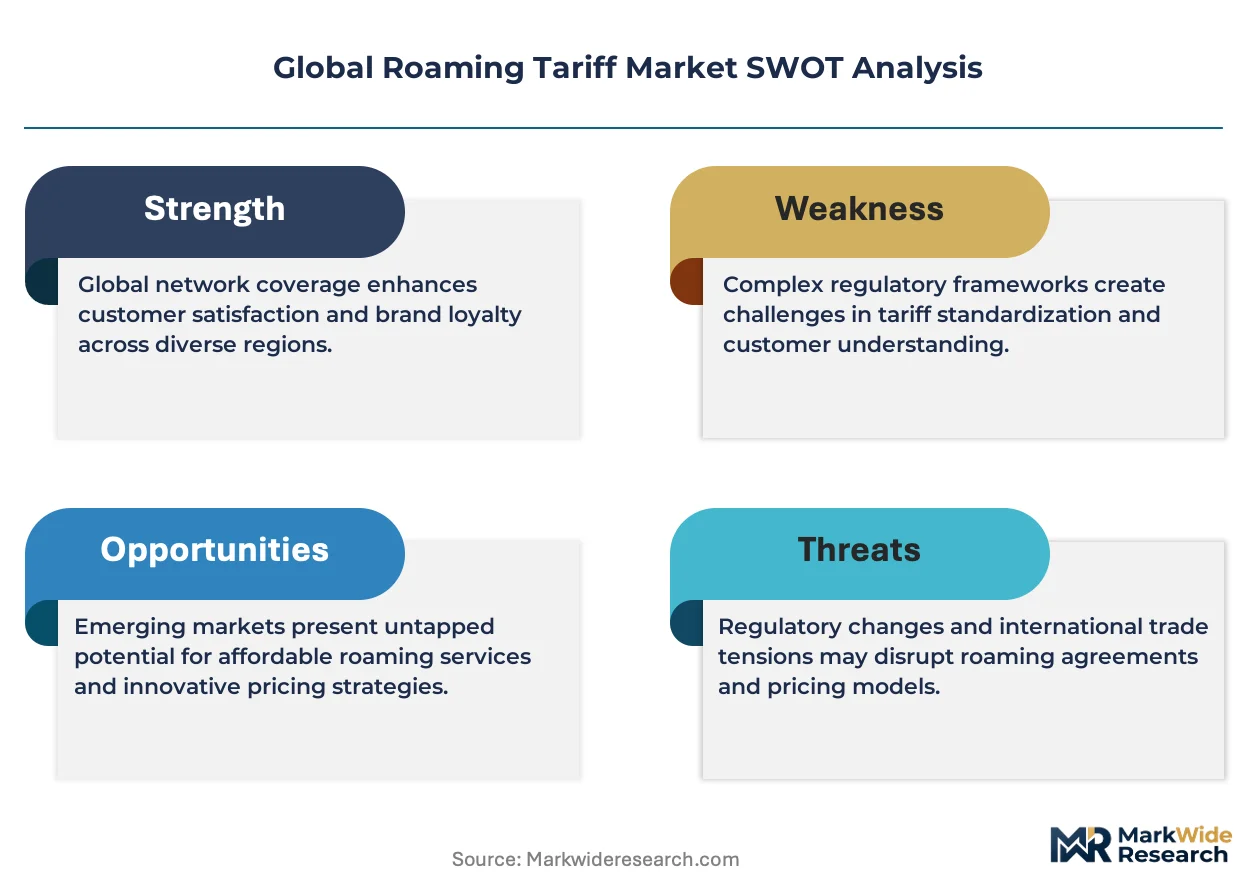
Regulatory divergence between capped wholesale corridors and flexible bilateral markets is redistributing operator investment toward jurisdictions preserving commercial pricing autonomy. Deutsche Telekom and Bharti Airtel exemplify contrasting strategies anchored in their respective regulatory environments.
Germany
Enterprise procurement of managed mobility services concentrates in Frankfurt and Munich manufacturing corridors. The EU's Roam Like at Home framework caps retail surcharges, forcing operators to monetize through wholesale volume commitments. Bavaria hosts dense clustering of automotive and industrial conglomerates negotiating pan-European connectivity guarantees.
United States
Corporate travel management companies in Chicago and New York consolidate roaming spend under centralized billing platforms. FCC bilateral roaming reciprocity rules prevent dominant carriers from withholding domestic access, indirectly shaping outbound negotiation leverage. Dallas-Fort Worth anchors telecommunications infrastructure investment for cross-border Latin American corridors.
India
Outbound mobility recovery drives data volume surges along China and Japan corridors. TRAI preserves bilateral commercial flexibility absent retail price caps, enabling flexible retail pricing architectures. Mumbai and Delhi-NCR host the largest expatriate roaming subscriber bases relative to domestic population.
Japan
5G standalone roaming protocols enable network slicing guarantees for bandwidth-intensive business applications. METI frameworks support seamless authentication handoffs between host and home networks. Tokyo and Osaka metropolitan areas concentrate enterprise procurement of latency-sensitive financial trading connectivity.
United Arab Emirates
MOHAP regulatory frameworks preserve flexible retail pricing for African and Middle Eastern bilateral agreements. Dubai and Abu Dhabi sustain specialized roaming retail operations at transit corridor density unmatched elsewhere. Expatriate roaming subscriber bases exceed domestic population ratios, driving multi-month subscription innovation.
Global Roaming Tariff Market Competitive Landscape
European operators anchor one tier through integrated pan-European networks sustaining cross-border data volumes at regulated wholesale ceilings; Asia-Pacific specialists hold flexible pricing corridors through bilateral commercial negotiations. Market structure consolidates around three strategic archetypes: pan-regional integrated carriers, corridor-focused bilateral negotiators, and enterprise mobility service consolidators. Dominant competitive moves include wholesale partnership restructuring and edge infrastructure co-investment for latency-sensitive service differentiation.
Among Germany-based integrated carriers, Deutsche Telekom AG exemplifies the pan-regional archetype leveraging contiguous network infrastructure. Spain's Telefónica S.A. and India's Bharti Airtel Limited occupy positions as corridor-focused bilateral negotiators in markets preserving commercial pricing flexibility. These three entities represent contrasting strategic responses to regulatory fragmentation between capped and flexible pricing jurisdictions.
| Leading Market Players |
|---|
| Deutsche Telekom AG |
| Telefónica S.A. |
| AT&T Inc. |
| NTT Docomo Inc. |
| Bharti Airtel Limited |
| Vodafone Group PLC |
| China Mobile Ltd. |
| Orange S.A. |
| Verizon Communications Inc. |
| Others |
Supply & Pricing Matrix
EU Green Deal sustainability disclosure mandates gate both qualified supply and premium-tier pricing access, as operators must document carbon intensity across roaming traffic routing and data center energy consumption before qualifying for enterprise procurement shortlists in Frankfurt and Munich corridors.
Pricing Analysis
Retailer markup layers at airport activation points and transit hub kiosks compress final pricing to subscribers while inflating customer acquisition costs. Wholesale rate caps under EU frameworks enforce three-tier pricing structure across premium, standard, and economy levels, with enterprise SLA-backed tiers commanding sustained premiums. Cost compression in leisure tourist segments intensifies because aggregator platforms force transparent price comparison. Digital nomads exhibit lowest price sensitivity due to extended-stay subscription lock-in, while impulse-activated daily pass buyers show highest elasticity.
Supply Chain Analysis
Returns and SIM card refurbishment flows from expired tourist subscriptions feed circular economy programs in Germany and the Netherlands, reducing plastic waste volumes. Network infrastructure sourcing draws from China, Finland, and Sweden for 5G base station components. Clearinghouse settlement software depends on specialized financial intermediaries concentrated in Belgium and Luxembourg. Single-source vulnerability concentrates in GSMA specification certification bodies. Distribution runs through bilateral roaming agreements negotiated directly between host and home operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Roaming Tariff Market functions as a stable compounder, with business traveler mobility programs driving steady recurring revenue regardless of economic cyclicality.
For Market Incumbents: Acquire edge computing infrastructure in financial corridor cities to defend latency-sensitive enterprise contracts against cloud hyperscaler encroachment. Prioritize wholesale partnership restructuring in African and Middle Eastern corridors where retail price caps have not eroded margin flexibility. Consolidate clearinghouse counterparty exposure through multi-lateral settlement pool participation.
For New Entrants and Emerging Players: Digital nomad visa programs in Portugal and Estonia represent the most penetrable subscriber acquisition channel, with multi-month subscription models bypassing seasonal tourist volatility. Target IoT automotive telemetry roaming where human traveler seasonality does not apply. Deploy direct-to-device eSIM provisioning through airline partnership channels.
For Investors and Strategic Acquirers: Roll-up economics work for corridor-focused bilateral negotiators because regulatory fragmentation between capped and flexible pricing jurisdictions prevents pan-regional scale dominance. Five-to-ten year viability rests on 5G standalone roaming protocol maturation and network slicing monetization. Monitor TRAI and Anatel regulatory filings for retail price cap replication signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Wholesale Partnership Restructuring | Deutsche Telekom leverages pan-European network scale to sustain margin at regulated ceilings. |
| Edge Infrastructure Co-Investment | Tokyo and Osaka operators deploy distributed cloud for financial trading latency guarantees. |
| IoT Roaming Specialization | Automotive OEMs negotiate machine-to-machine connectivity decoupled from human seasonality. |
| Regulatory Arbitrage Corridor Entry | Bharti Airtel anchors African bilateral agreements preserving flexible retail pricing. |
| eSIM Platform Integration | Airline partnership channels enable direct-to-device provisioning at transit corridor density points. |
Research Methodology
Multiple input streams — roaming tariff filings with national regulators, wholesale clearinghouse settlement records, and enterprise mobility contract disclosures — were reconciled against primary interviews with network engineering directors, roaming partnership managers, and corporate procurement leads at travel-intensive conglomerates. Secondary validation drew from TRAI consultation papers, GSMA IR.21 and IR.85 specification updates, EU Commission roaming market reviews, and operator annual reports. Bottom-up subscriber volume estimates and top-down revenue aggregation were cross-triangulated.
Historical wholesale rate trajectories were cross-referenced against panel input from roaming managers to construct projection scenarios across the analysis window. Segmentation dimensions modeled include service type, end-user mobility purpose, distribution channel, and pricing model commitment structure. CAGRs were derived from volume-weighted average growth across corridor-specific bilateral agreements and regulatorily capped wholesale zones. 5G standalone protocol adoption curves and enterprise IoT device attach rates served as industry-specific demand drivers.
Underlying measurement precision varies by segment; European Roam Like at Home corridors carry tighter precision due to mandatory disclosure, while African bilateral agreements exhibit wider variance. Forecasts reflect assumptions on regulatory replication timing and protocol interoperability certification delays. Practitioners should monitor emerging market regulator consultation papers and GSMA specification revision cycles for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global SMB Telecom Voice and Data Services Market
Telecommunications
Malaysia Telecom Market
Telecommunications
5G Transport Networks Market
Telecommunications
Cambodia ICT Market
Telecommunications
Promotional Sms Market
Telecommunications
Mexico Telecom Market
Telecommunications
MVNO Market
Telecommunications
IP Centrex Platforms Market
Telecommunications
International Wholesale Voice Carrier Market
Telecommunications
Austria ICT Market
Telecommunications
GPON Equipment Market
Telecommunications
Satcom Terminal Market
Telecommunications
Italy Telecom Market
Telecommunications
Global 5G Base Station Market
Telecommunications
C-RAN Market
Telecommunications
Explosion Proof Mobile Communication Devices Market