
 Kenya Telecom Market | 2026-2036
Kenya Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Kenya Telecom Market Insights
The capital-intensity divergence between fiber-backbone operators and last-mile resellers is rotating competitive dynamics across Kenya's telecom landscape. Safaricom leverages its extensive mobile money integration to sustain subscriber stickiness in both prepaid and postpaid segments. Airtel Kenya competes through aggressive data pricing while Telkom Kenya anchors its position in fixed-line enterprise connectivity.
Kenya telecom encompasses voice, data, and internet services delivered through wireless and wireline infrastructure operating across frequency bands from 700 MHz to 3.5 GHz and fiber optic cable networks. The sector enables commercial communication, financial transactions, and digital service delivery for consumers, businesses, and government entities. Mobile data and 4G LTE currently dominate traffic volumes, while fiber optics is capturing margin pools in enterprise broadband as SMEs migrate from satellite-dependent connectivity. 5G is expanding fastest among large enterprises in Nairobi's technology parks, though satellite retains structural importance for rural residential coverage beyond fiber reach.
The Communications Authority of Kenya governs spectrum allocation, licensing, and quality-of-service enforcement, while the Central Bank of Kenya coordinates mobile money interoperability standards that shape platform competition. The National Information Communications and Technology Policy framework mandates universal service obligations that direct infrastructure investment toward underserved counties. Stakeholders must monitor pending spectrum auction timelines and evolving data localization requirements to calibrate capital deployment and partnership strategies.
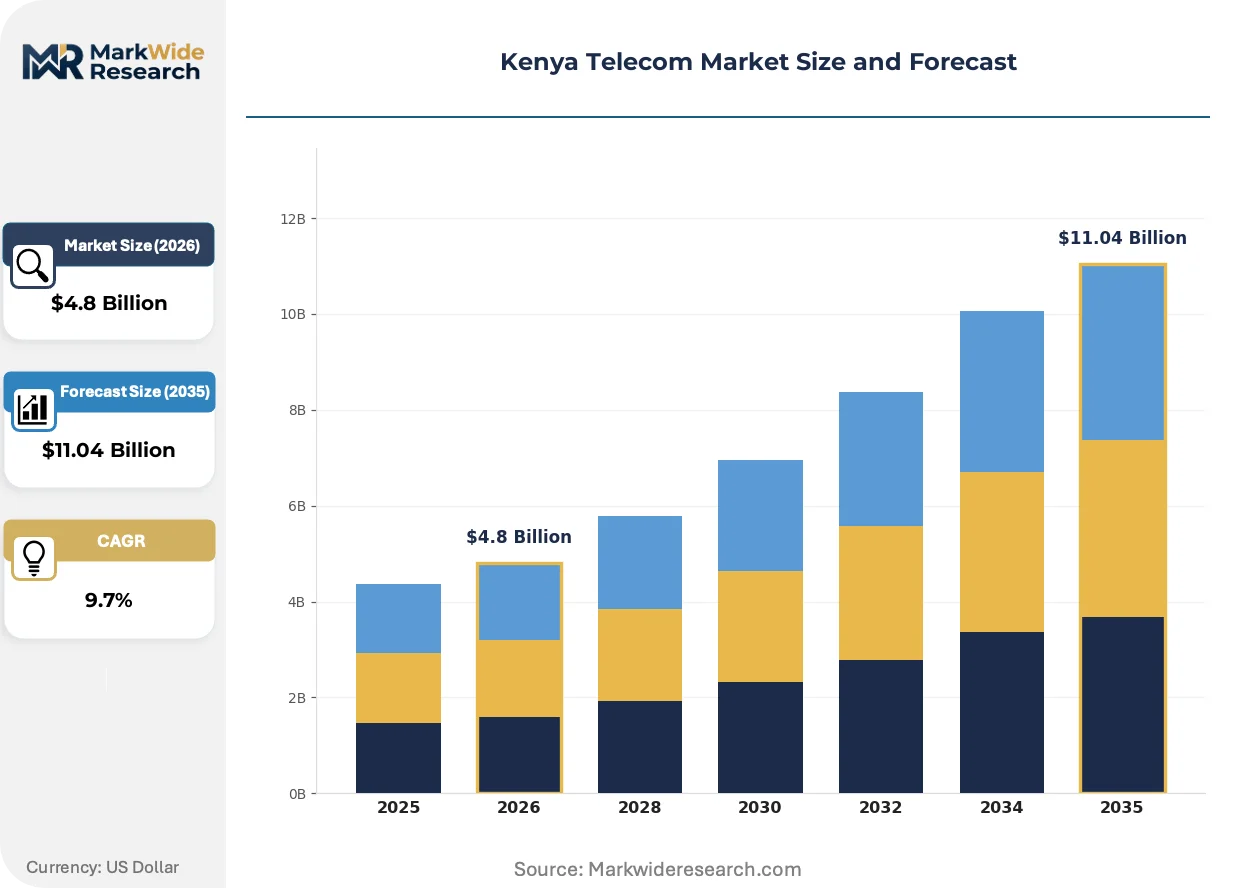
Market Dynamics
Spectrum reallocation by the Communications Authority of Kenya is compressing 5G deployment timelines and redistributing infrastructure investment across Nairobi's technology corridors and secondary counties.
Growth Catalysts
- Universal Service Obligations:The National Information Communications and Technology Policy framework mandates connectivity expansion into underserved counties, directing capital toward fiber backbone extension and rural base station deployment.
- SME Digital Migration:Small and medium enterprises across Kenya's agricultural processing and logistics sectors are abandoning satellite-dependent connectivity for fiber-based enterprise broadband, generating sustained data revenue pools.
- Mobile Money Interoperability:Central Bank of Kenya coordination standards have unified platform competition, embedding telecom operators deeper into financial transaction infrastructure and reducing subscriber churn.
Market Restraints
- Input Cost Volatility:Import-dependent network equipment and fiber optic cable components expose operators to currency fluctuation risks and extended procurement cycles.
- Supply Concentration Risk:Core routing and switching hardware concentrates among a limited set of international vendors, creating vulnerability to geopolitical trade restrictions and shipping disruptions.
- Right-of-Way Friction:County-level permitting inconsistencies for fiber trenching and tower construction extend deployment timelines and inflate civil works expenditure.
Strategic Opportunities
- Coastal County Underpenetration:Mombasa and surrounding port logistics zones remain underserved by dedicated fiber enterprise connectivity, presenting whitespace for fixed-line infrastructure investment.
- 5G Enterprise Convergence:Integration of fixed wireless access with industrial IoT sensor networks is opening dedicated spectrum utilization models for manufacturing and warehousing facilities in Nairobi's special economic zones.
- Data Localization Tailwind:Pending data sovereignty requirements under national cybersecurity frameworks are stimulating demand for domestic data center construction and edge computing node deployment.
Industry Challenges
- Specialized Workforce Scarcity:Network engineering and 5G radio frequency planning expertise remains concentrated among a limited pool of professionals, inflating talent acquisition costs and project delays.
- Legacy System Integration Complexity:Operators maintaining 2G and 3G voice infrastructure face technical debt burdens as they overlay 4G and 5G architectures, complicating spectrum refarming strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kenya Telecom Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Voice, Mobile Data, Fixed Line, Broadband Technology: 4G LTE, 5G, Fiber Optics, Satellite Customer Type: Residential, SMEs, Large Enterprises, Government Pricing Model: Prepaid, Postpaid, Bundled Offers, Pay-As-You-Go |
| Companies Covered | Safaricom, Airtel Kenya, Telkom Kenya, Jamii Telecommunications, Finserve, Cloud One Limited, iWay Africa Kenya, The East African Marine Systems, Mobile Pay, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kenya Telecom Market Trends and Innovations
Technology deployment patterns across Kenya's telecom infrastructure are fragmenting into divergent investment priorities, separating premium enterprise connectivity from mass-market mobile service delivery.
Open RAN architectures are bifurcating vendor ecosystems in Kenya's mobile network infrastructure. These disaggregated hardware-software stacks enable multi-vendor interoperability at base station sites. Tier-two operators and new market entrants are adopting Open RAN aggressively to reduce dependency on integrated equipment suppliers. The technology is compressing incumbent vendor pricing power while expanding equipment sourcing flexibility for operators with limited capital reserves.
The Communications Authority of Kenya's spectrum reallocation framework is accelerating 5G frequency band assignments and clearing 3.5 GHz holdings for commercial use. This regulatory momentum is compressing infrastructure deployment timelines for operators holding existing 4G spectrum assets. Nairobi-based enterprises in fintech and business process outsourcing are the most affected segment, demanding dedicated network slicing and guaranteed latency commitments.
Enterprise procurement of connectivity services is consolidating around multi-year managed service contracts with uptime guarantees. Large agricultural cooperatives and logistics operators are abandoning month-to-month data subscriptions in favor of bundled fiber, cloud access, and security offerings. This pattern is most visible in the Rift Valley's tea and flower export processing clusters, where operational continuity requirements override pure price competition.
Kenya Telecom Market Segmentation
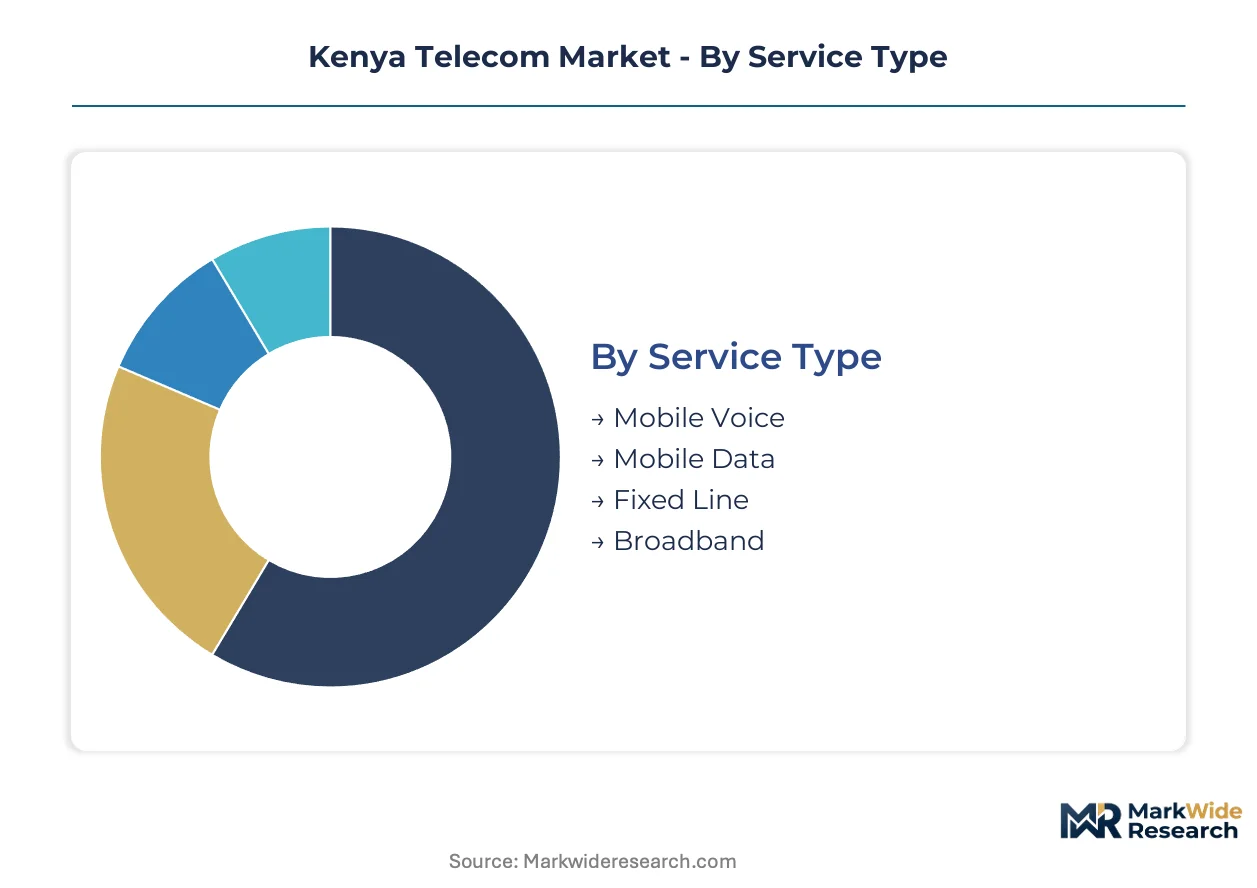
Segmentation in Kenya's telecom market exposes divergent margin structures across service delivery modes. Understanding where revenue pools concentrate enables operators to calibrate infrastructure investment and pricing architecture against distinct customer willingness-to-pay profiles.
Service Type:
Margin pools concentrate in data-centric services as voice revenues commoditize and broadband penetration deepens in Nairobi's commercial corridors.
- Mobile Data:Packet-switched data transmission over cellular networks dominates traffic volumes across Kenya's subscriber base. SME demand in Nairobi's technology parks and agricultural processing zones is compressing price elasticity as enterprises abandon satellite for fiber-backed mobile connectivity.
- Broadband:Fixed-line and fixed wireless access delivering sustained bandwidth to premises captures premium pricing in Kenya's enterprise segment. Large agricultural cooperatives in the Rift Valley's tea and flower export clusters are consolidating procurement around multi-year managed service contracts with uptime guarantees.
- Mobile Voice:Circuit-switched and VoLTE voice services sustain subscriber stickiness through mobile money integration. Prepaid segments in peri-urban counties maintain volume despite declining average revenue per user.
- Fixed Line:Traditional copper and fiber-based voice connectivity anchors enterprise accounts in government and banking verticals. Telkom Kenya retains structural position in this legacy infrastructure category.
Mobile Data holds installed capacity. Broadband is rotating up the share rankings.
Technology:
Deployment timelines stretch across generations as spectrum refarming and infrastructure overlay costs fragment investment returns.
- Fiber Optics:Optical fiber transmission infrastructure delivers the lowest latency and highest capacity for enterprise and residential broadband. Nairobi's metropolitan corridor and Mombasa port logistics zones are seeing concentrated trenching activity despite county-level right-of-way friction.
- 5G:Fifth-generation cellular networks operating in 3.5 GHz and sub-6 GHz bands enable network slicing for industrial IoT. Manufacturing and warehousing facilities in Nairobi's special economic zones are driving initial enterprise adoption ahead of mass-market availability.
- 4G LTE:Fourth-generation cellular technology remains the workhorse for mobile data delivery across Kenya's subscriber base. Universal service obligations are extending coverage into underserved counties where 5G economics remain prohibitive.
- Satellite:Geostationary and low-earth orbit systems provide connectivity beyond fiber and cellular reach. Rural residential coverage in arid and semi-arid counties retains structural dependence on satellite backhaul.
Fiber Optics commands capital deployment. 5G is climbing the fastest in enterprise share rankings.
Customer Type:
Procurement sophistication and contract duration separate enterprise accounts from volatile consumer segments.
- Large Enterprises:Multinational corporations, banks, and agricultural exporters with dedicated connectivity requirements and compliance obligations. Fintech and business process outsourcing clusters in Nairobi are demanding guaranteed latency commitments and network slicing.
- SMEs:Small and medium enterprises spanning logistics, retail, and agricultural processing with growing data dependence. Kenya's flower and tea export cooperatives are migrating from satellite-dependent connectivity to fiber-based enterprise broadband.
- Government:National and county government entities with universal service mandates and security-sensitive communications. The National Information Communications and Technology Policy framework directs procurement toward domestic infrastructure.
- Residential:Individual consumers and households served through prepaid mobile and emerging fixed wireless access. Nairobi's middle-income suburbs are seeing initial fiber-to-the-home penetration.
Large Enterprises anchor contract value. SMEs are expanding most quickly as a customer category.
Pricing Model:
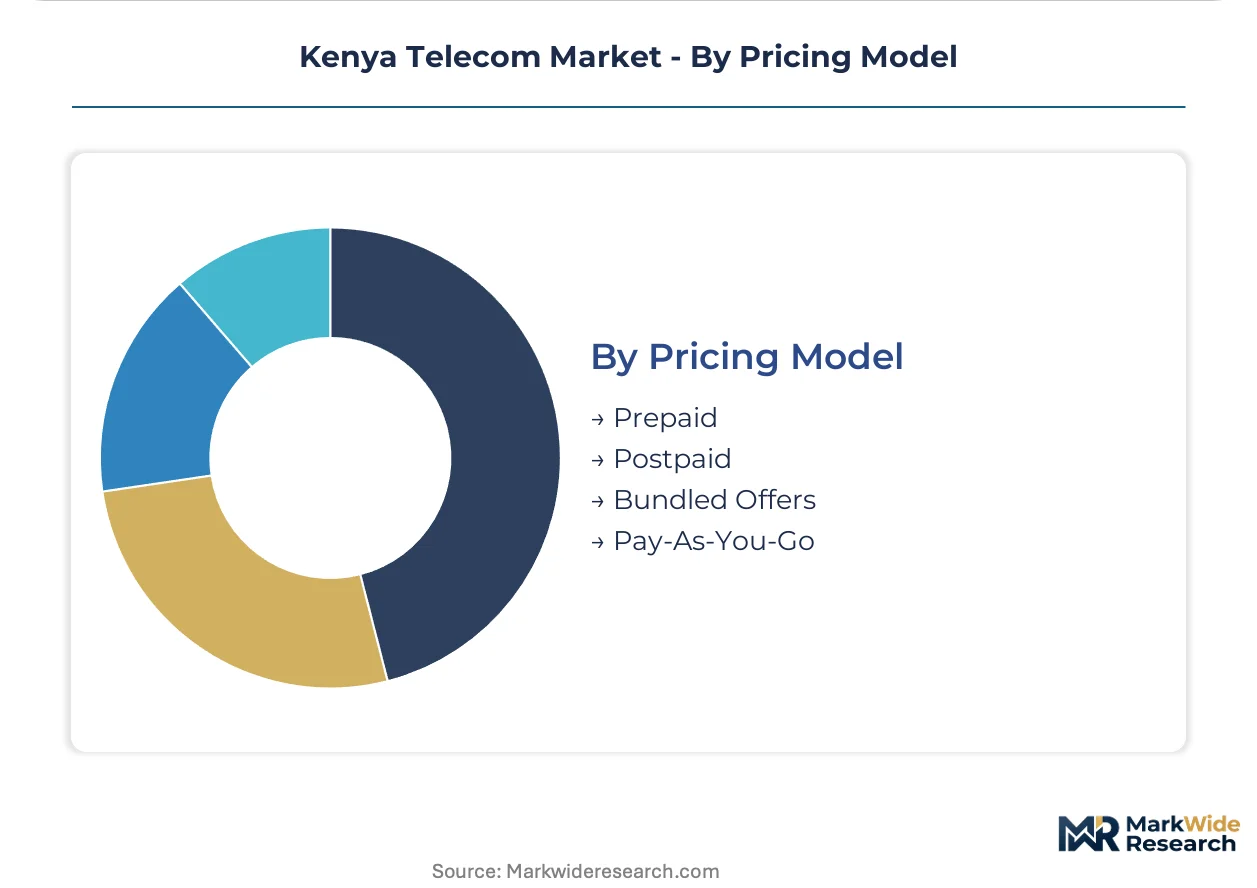
Payment structure aligns with customer cash flow patterns and churn risk profiles across Kenya's income distribution.
- Postpaid:Monthly billing with contracted minimums and credit-checked subscribers. Corporate accounts and affluent residential segments in Nairobi's technology corridor sustain this model.
- Bundled Offers:Combined voice, data, and mobile money packages with loyalty incentives. Safaricom leverages extensive mobile money integration to sustain subscriber stickiness through bundled architecture.
- Prepaid:Pay-in-advance mobile services dominating Kenya's mass market. Airtime distribution networks and mobile money top-up channels embed this model in informal commerce.
- Pay-As-You-Go:Usage-based billing without commitment, common in data services and international calling. Price-sensitive segments in secondary counties retain preference for this flexibility.
Postpaid holds contract stability. Bundled Offers are gaining share fastest in customer retention metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Kenya's telecom landscape. Nairobi's enterprise corridor shows low price sensitivity for guaranteed uptime, while peri-urban prepaid segments remain highly elastic to airtime discounts.
Nairobi Metropolitan Corridor
Fintech clusters and business process outsourcing hubs drive premium connectivity demand. The Communications Authority of Kenya's spectrum reallocation accelerates 5G frequency assignments for enterprise zones. Technology parks in Westlands and Upper Hill attract dedicated fiber and fixed wireless infrastructure investment.
Mombasa and Coastal Counties
Port logistics operators and maritime service providers generate concentrated enterprise broadband requirements. County-level right-of-way permitting inconsistencies delay fiber trenching timelines. Freeport zones and container terminals anchor specialized connectivity procurement for customs and shipping verticals.
Rift Valley Agricultural Belt
Tea and flower export cooperatives migrate from satellite-dependent systems to fiber-backed enterprise solutions. Universal service obligations under the National Information Communications and Technology Policy direct base station deployment into underserved highland areas. Nakuru and Eldoret processing clusters consolidate procurement around multi-year managed service contracts.
Central Kenya Highlands
Coffee and horticulture value chains drive SME data demand for supply chain traceability and export documentation. The Central Bank of Kenya's mobile money interoperability standards embed telecom platforms deeper into agricultural payment systems. Kiambu and Murang'a agricultural processing zones see rising fixed wireless adoption among mid-tier cooperatives.
Arid and Semi-Arid Northern Counties
Sparse population density and infrastructure gaps sustain satellite as the primary connectivity mode. Government universal service mandates direct subsidized base station construction toward administrative centers. Marsabit, Turkana, and Wajir rely on geostationary and emerging low-earth orbit systems for basic voice and mobile money services.
Kenya Telecom Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Kenya's telecom structure. The upper tier combines mobile network infrastructure with mobile money platforms and enterprise fiber assets. The specialist tier fragments across fixed wireless resellers, data center operators, and satellite service providers. Two strategic archetypes dominate: integrated full-service operators leveraging cross-platform subscriber lock-in, and infrastructure-light resellers competing on price elasticity in underserved segments. Competitive moves concentrate on spectrum acquisition positioning and fiber backbone extension into whitespace corridors.
Among integrated operators, Safaricom and Airtel Kenya exemplify the full-service archetype combining consumer mobile, enterprise connectivity, and financial transaction infrastructure. Telkom Kenya occupies a distinct position anchoring fixed-line heritage in government and banking verticals while rebuilding mobile relevance. These three represent the competitive poles around which smaller specialists orbit.
| Leading Market Players |
|---|
| Safaricom |
| Airtel Kenya |
| Telkom Kenya |
| Jamii Telecommunications |
| Finserve |
| Cloud One Limited |
| iWay Africa Kenya |
| The East African Marine Systems |
| Mobile Pay |
| Others |
Pricing and Supply Chain Analysis
Base station densification economics in Nairobi's technology corridors concentrate procurement power among operators with fiber backbone ownership, compressing margins for last-mile resellers while elevating price floors for enterprise-grade connectivity. The Communications Authority of Kenya's spectrum reallocation timeline shapes capital deployment urgency, translating infrastructure scarcity into sustained pricing leverage for holders of cleared 3.5 GHz holdings.
Pricing Analysis
Multi-year managed service contracts with uptime guarantees anchor lifetime value in Kenya's enterprise segment, particularly for agricultural cooperatives in the Rift Valley's tea and flower export clusters. Three-tier pricing structure across premium, standard, and economy levels separates fiber-backed enterprise broadband from fixed wireless access and prepaid mobile data tiers. Cost compression in the prepaid segment intensifies because Safaricom's mobile money integration sustains subscriber stickiness without pure price competition. SMEs migrating from satellite-dependent connectivity show lowest price sensitivity, while peri-urban prepaid consumers remain highly elastic to airtime discounting.
Supply Chain Analysis
Mombasa port customs clearance and inland trucking corridors to Nairobi constitute the critical logistics chokepoint for network equipment importation, with extended procurement cycles amplifying currency fluctuation exposure. Core routing and switching hardware concentrates supply from China, South Korea, and the United States, while fiber optic cable components draw from Chinese and European manufacturers. Single-source vulnerability in 5G radio access equipment creates structural risk given geopolitical trade restriction potential. Distribution runs through international vendor-direct relationships with tier-one operators and specialized ICT distributors serving the reseller tier.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kenya's telecom market represents a high-growth disruption as 5G enterprise convergence and data localization requirements under national cybersecurity frameworks compress infrastructure deployment timelines. The Communications Authority of Kenya's spectrum reallocation accelerates competitive repositioning across fixed and mobile domains.
For Market Incumbents: Compound fiber backbone extension into Mombasa port logistics zones and Rift Valley agricultural processing clusters to preempt whitespace capture by specialist entrants. Anchor subscriber retention through deeper mobile money platform integration as Airtel Kenya's aggressive data pricing threatens prepaid margin pools. Prioritize 5G radio frequency planning talent acquisition ahead of competitor hiring cycles. For New Entrants and Emerging Players: Coastal county underpenetration in dedicated fiber enterprise connectivity offers immediate addressable whitespace, particularly for customs and shipping verticals in freeport zones. Target SME agricultural cooperatives in Central Kenya Highlands with fixed wireless access solutions bridging satellite-to-fiber migration gaps. Pursue Open RAN equipment sourcing flexibility to reduce capital intensity versus integrated vendor dependencies. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among operators combining fiber backbone ownership with mobile money platform integration, suggesting superior cash flow durability across economic cycles. Long-term viability favors integrated full-service operators over infrastructure-light resellers given spectrum scarcity and right-of-way friction. Monitor pending data sovereignty requirement implementation as inflection indicator for domestic data center and edge computing investment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| 5G Spectrum Acquisition Positioning | Secures cleared 3.5 GHz holdings ahead of Communications Authority of Kenya auction timelines. |
| Fiber Backbone Extension | Captures enterprise broadband margin pools in Mombasa port logistics and Rift Valley agricultural zones. |
| Open RAN Architecture Adoption | Reduces vendor lock-in and capital intensity for tier-two operators and new market entrants. |
| Mobile Money Platform Deepening | Embeds telecom operators into Central Bank of Kenya interoperability standards, reducing churn. |
| Data Center Domestic Construction | Addresses pending data localization requirements under national cybersecurity frameworks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with network engineering directors, enterprise sales leads at tier-one operators, procurement managers at agricultural cooperatives, and regulatory affairs specialists at the Communications Authority of Kenya. Secondary validation drew from Communications Authority of Kenya spectrum allocation records, Central Bank of Kenya mobile money interoperability circulars, National Information Communications and Technology Policy framework documents, and infrastructure deployment permit databases at county government levels. Bottom-up subscriber and revenue modeling triangulated against top-down market sizing from capital expenditure disclosures and equipment import customs data.
Across the analysis window, volume and value outputs reflect segmented modeling across service type, technology generation, customer tier, and pricing model dimensions. CAGRs were derived from infrastructure deployment run rates, spectrum assignment timelines, and enterprise procurement pattern shifts. Industry-specific forecast inputs include base station construction permits, fiber trenching right-of-way approvals, and mobile money transaction velocity indices.
Forecasts assume regulatory continuity in Communications Authority of Kenya spectrum management and Central Bank of Kenya mobile money oversight; material policy shifts would require re-modeling. Infrastructure deployment timelines reflect historical county-level permitting friction patterns. Practitioners should keep alternative scenarios live as data localization requirement specifications and universal service obligation funding mechanisms evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Software Defined Radio Market
Telecommunications
C-RAN Market
Telecommunications
5G Radio Access Network Market
Telecommunications
Global Ip Multimedia Subsystem (Ims) Market
Telecommunications
Mobile Satellite Services (MSS) Market
Telecommunications
Chile Telecom Market
Telecommunications
A2P SMS Market
Telecommunications
Tetra Terminals Market
Telecommunications
Promotional Sms Market
Telecommunications
Land Professional Mobile Radio Market
Telecommunications
Middle East and Africa Telecom Expense Management Market
Telecommunications
Ireland Telecom Market
Telecommunications
Smart Feature Phone Market
Telecommunications
Iceland Telecom Market
Telecommunications
Denmark ICT Market
Telecommunications
Telecommunication Service Market