
 United Kingdom Telecom Market | 2026-2036
United Kingdom Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Telecom Market Outlook
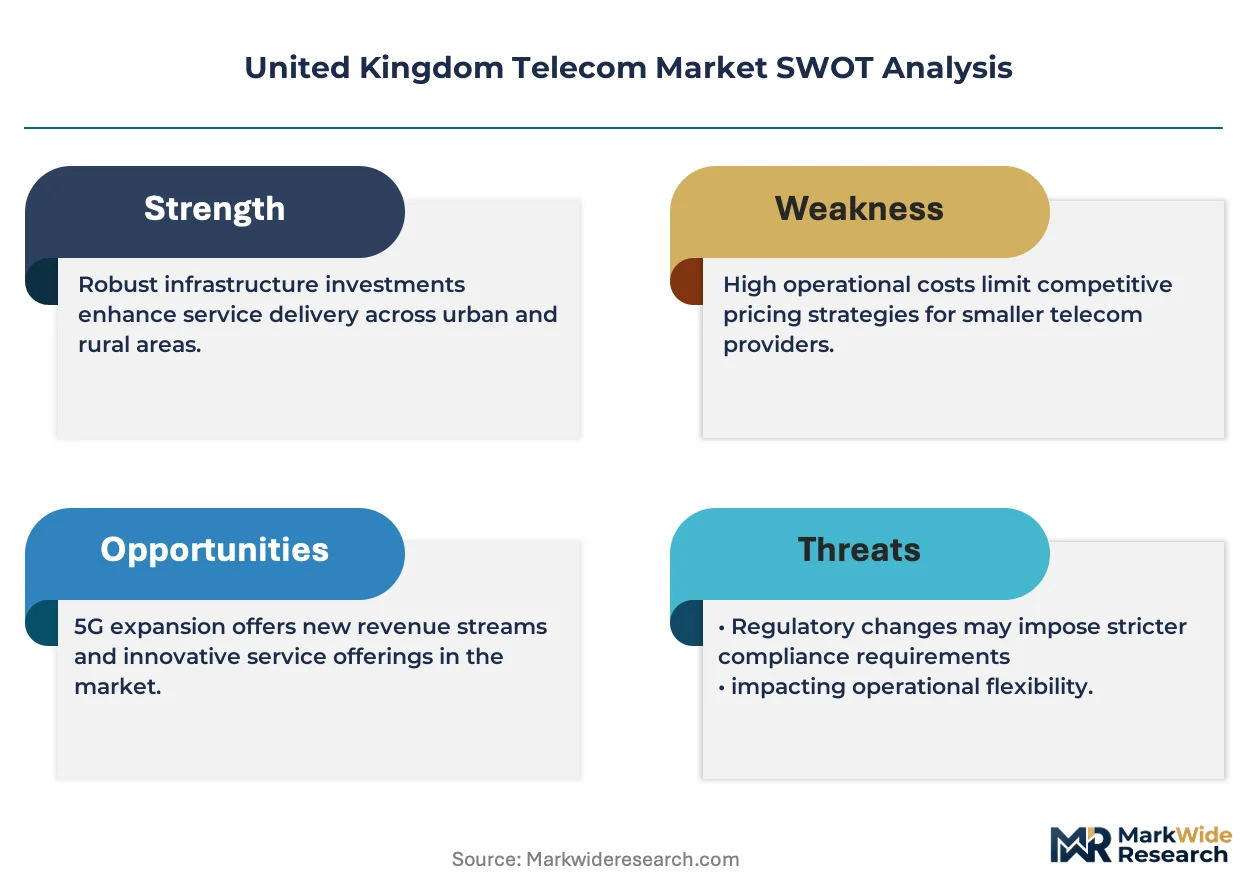
Wholesale network access margins is narrowing as fiber unbundling and mobile virtual network operator agreements commoditize middle-layer connectivity. BT Group anchors its position through Openreach infrastructure control and regulated wholesale pricing frameworks. Virgin Media O2 competes by converging cable and mobile assets into bundled propositions. CityFibre specializes in pure-play fiber wholesale, targeting third-party retail service providers with dark fiber and lit services.
United Kingdom Telecom encompasses wired and wireless communication infrastructure delivering voice, data, and video services across copper, fiber, and radio frequency mediums operating between 700 MHz and 3.8 GHz spectrum bands with latency requirements under 10 milliseconds for 5G ultra-reliable applications. Fixed Broadband and 5G technology segments carry the dominant investment flows, with fiber-to-the-premises deployment absorbing the majority of capital expenditure as DSL obsolescence accelerates. Enterprise end users represent the fastest-growing service category, driven by software-defined wide area network migration and edge computing co-location requirements.
Ofcom enforces wholesale access obligations and spectrum auction terms that determine market entry economics for new infrastructure competitors. The UK's Telecommunications (Security) Act imposes supply chain restrictions on high-risk vendor equipment, directly affecting 5G radio access network procurement decisions. Stakeholders must monitor Ofcom's forthcoming spectrum release consultations and the Competition and Markets Authority's periodic review of wholesale pricing remedies to anticipate margin structure shifts.
Market Dynamics
Ofcom's Shared Rural Network mandate and Open RAN interoperability requirements are compressing infrastructure procurement timelines while redistributing capital toward fiber densification and neutral host models. Wholesale access obligations now force incumbents to unbundle dark fiber at regulated rates, eroding legacy margin structures.
Growth Catalysts
- Ofcom's Shared Rural Network mandate:Requires MNOs to extend 4G coverage to 95% of UK geography by 2025, pooling infrastructure investments and accelerating rural site deployment.
- Software-defined WAN migration:Financial services and healthcare enterprises are replacing MPLS circuits with cloud-managed connectivity, expanding addressable service revenue per customer.
- Manchester digital cluster concentration:MediaCityUK and surrounding enterprise zones are absorbing fiber-to-the-premises capacity faster than national averages, pulling infrastructure investment northward.
Market Restraints
- Copper decommissioning cost burden:BT Openreach faces structural expense in retiring legacy DSL plant while maintaining universal service obligations, straining free cash flow for fiber overbuild.
- High-risk vendor equipment restrictions:The Telecommunications (Security) Act limits 5G radio access network procurement to approved suppliers, constraining vendor competition and extending equipment lead times.
- Wayleave agreement friction:Property access rights for street works and building entry require individual negotiations with local authorities and landlords, delaying fiber deployment in dense urban cores.
Strategic Opportunities
- Scottish Highlands connectivity gap:Subsidized rural infrastructure programs create neutral host opportunities for shared mobile and fixed wireless access networks in underpenetrated northern geographies.
- Edge computing co-location services:Convergence of 5G network slicing with distributed cloud infrastructure enables low-latency hosting for autonomous systems and industrial IoT applications.
- Open RAN interoperability standards:Ofcom's vendor diversification push rewards disaggregated radio access network suppliers with faster regulatory approval pathways and spectrum access priority.
Industry Challenges
- Radio frequency planning expertise scarcity:5G mmWave propagation modeling and interference management require specialized engineering skills concentrated among incumbent equipment vendors, constraining operator hiring.
- Multi-vendor integration complexity:Open RAN disaggregation introduces interoperability testing burdens between radio units, distributed units, and centralized units from different suppliers, extending commissioning timelines.
- Fiber splicing technician pipeline gaps:Full-fiber rollout targets exceed available skilled labor for micro-trenching, blown fiber, and premises connection work, inflating subcontractor rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Telecom Market |
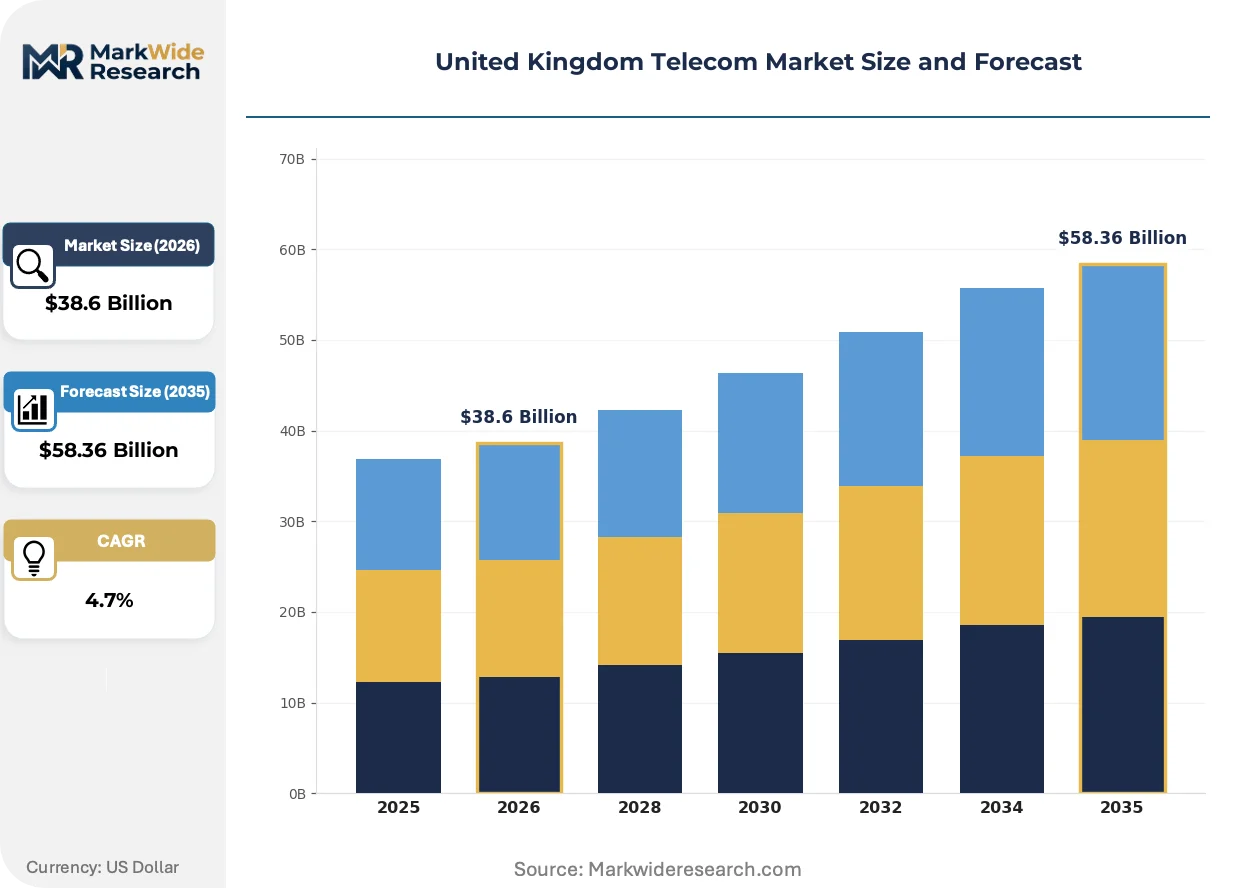
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.36 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Voice, Mobile Data, Fixed Voice, Fixed Broadband Technology: 4G, 5G, DSL, Fiber Optic End User: Residential, Small Business, Enterprise, Government Delivery Mode: Direct Sales, Online Sales, Retail, Wholesale |
| Companies Covered | Virgin Media O2, O2, BT Group, VodafoneThree, Sky UK, EE, Three UK, CityFibre, Vodafone UK, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Telecom Market Strategic Shifts
Network function virtualization and cloud-native core architectures are dissolving traditional hardware-software boundaries, enabling operators to deploy services via software updates rather than physical site visits. This shift compresses both capital intensity and time-to-market for new connectivity products.
Passive optical networking technology is collapsing the cost structure of residential and small business connectivity by eliminating active electronics in street cabinets. CityFibre and altnets are deploying XGS-PON at scale across Midlands and Northern England, enabling symmetrical gigabit services without the power and maintenance overhead of active Ethernet. The structural consequence is margin compression on sub-gigabit tiers and accelerated DSL obsolescence.
Ofcom's wholesale fixed telecoms market review is mandating virtual unbundled local access and physical infrastructure access remedies that force Openreach to publish reference offers for dark fiber and duct access. Alternative network operators are leveraging these regulated inputs to overbuild in Greater London and Manchester without full civil engineering duplication. The most affected segment is business connectivity, where retail service providers now compete on service layer differentiation rather than infrastructure ownership.
Enterprise procurement of connectivity is consolidating toward multi-year managed service contracts with guaranteed latency and uptime service level agreements, displacing transactional bandwidth purchasing. Systems integrators and managed service providers are capturing this relationship, inserting themselves between wholesale infrastructure owners and end customers. This pattern is most visible in financial services, where trading floor and data center interconnection requirements now specify deterministic performance rather than best-effort bandwidth.
United Kingdom Telecom Market Segmentation
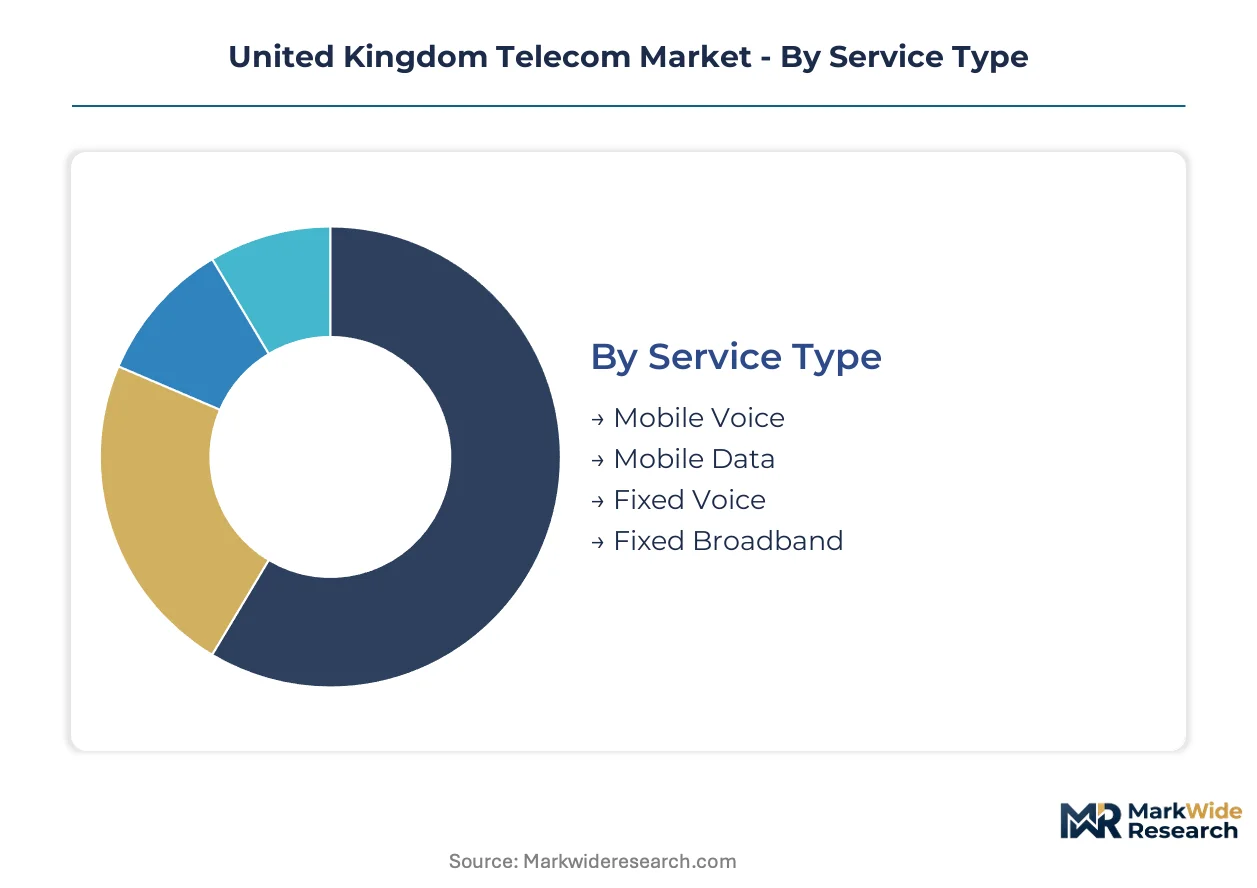
Segmentation reveals how infrastructure investment and revenue capture diverge across connectivity modes, customer economics, and procurement channels. Each dimension exposes distinct margin structures and competitive entry points for operators and service providers.
Service Type:
Customer spend patterns vary sharply between fixed and mobile connectivity, with contract duration and churn economics driving divergent capital allocation.
- Mobile Voice:Circuit-switched and VoLTE calling services retain residual enterprise demand for regulated industries requiring guaranteed service quality. Financial services compliance mandates in the City of London sustain premium pricing for dedicated voice circuits despite over-the-top displacement elsewhere.
- Mobile Data:5G network slicing and unlimited data plans absorb the majority of consumer ARPU growth as video streaming and cloud application usage intensifies. Manchester's MediaCityUK and Greater London's financial districts exhibit the steepest per-capita consumption curves nationally.
- Fixed Voice:Copper-based PSTN services face accelerated obsolescence as BT Openreach executes its 2025 all-IP migration deadline, compressing residual revenue to legacy business installations.
- Fixed Broadband:Fiber-to-the-premises subscriptions dominate new connection growth, with symmetrical gigabit tiers displacing DSL across suburban and urban footprints.
Fixed Broadband commands the established base. The steepest expansion runs through Mobile Data.
Technology:
Network generation and physical medium determine capital intensity, spectral efficiency, and competitive differentiation for infrastructure owners.
- 4G:LTE-Advanced Pro networks carry the majority of current mobile traffic while serving as fallback coverage layer for 5G non-standalone deployments. Ofcom's Shared Rural Network mandate extends 4G obligation timelines through 2025, preserving upgrade investment requirements.
- 5G:New radio access technology enables network slicing and ultra-reliable low-latency communications for industrial automation and autonomous vehicle trials. Enterprise adoption concentrates in Birmingham's manufacturing corridor and Bristol's aerospace cluster.
- DSL:Asymmetric digital subscriber line infrastructure enters managed decline as Openreach accelerates copper retirement, stranding sunk costs in less dense geographies.
- Fiber Optic:XGS-PON and point-to-point fiber deployments absorb the majority of fixed network capital expenditure, with CityFibre and altnets overbuilding incumbent infrastructure in target cities.
Fiber Optic anchors infrastructure valuation. The most rapid technology transition occurs in 5G.
End User:
Customer scale and procurement sophistication create tiered service requirements that reshape product packaging and sales channel economics.
- Residential:Mass-market consumers select primarily on price and bundled entertainment content, with Virgin Media O2 and BT Group competing through converged quad-play propositions. Churn sensitivity peaks in urban fiber-competitive zones.
- Small Business:SOHO and SME segments demand reliable connectivity without dedicated account management, creating opportunity for automated provisioning and self-service portals. Regional digital clusters in Leeds and Edinburgh show elevated penetration.
- Enterprise:Large organizations procure managed WAN and cloud connectivity through multi-year contracts with stringent SLA requirements. Financial services and healthcare verticals in London and Manchester drive premium service tier adoption.
- Government:Central and local authority contracts require security-cleared personnel and accredited supply chains, limiting vendor eligibility to established infrastructure operators.
Residential subscriptions generate volume scale. Enterprise contracts deliver the fastest margin expansion.
Delivery Mode:
Channel structure determines customer acquisition cost and service bundling flexibility across direct and indirect routes to market.
- Direct Sales:Field-based account teams and inside sales operations target enterprise and public sector contracts with customized solution design. Complex procurement cycles in Whitehall and NHS trusts favor relationship-based selling.
- Online Sales:Digital self-service platforms reduce acquisition costs for standardized residential and small business products, with price comparison site traffic shaping competitive positioning.
- Retail:High street and shopping centre storefronts provide physical presence for consumer handset sales and service troubleshooting, though foot traffic decline compresses channel economics.
- Wholesale:Regulated access obligations enable mobile virtual network operators and retail service providers to resell incumbent and altnet infrastructure, fragmenting end-customer relationships.
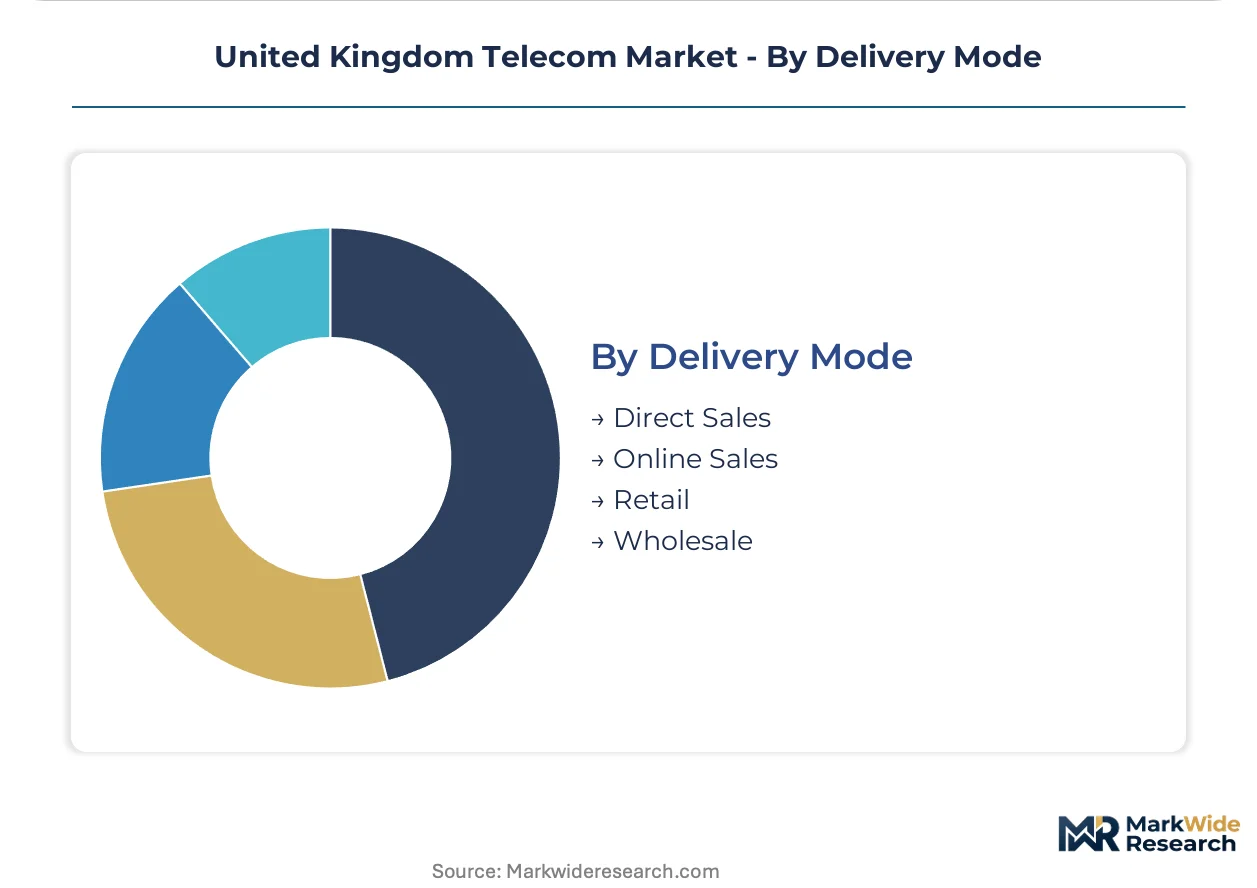
Wholesale underpins market structure through regulatory mandate. Online Sales channels are expanding most quickly as consumer preferences shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in Greater London exhibit low price elasticity for guaranteed latency services, while residential segments in Northern England and Wales remain highly sensitive to monthly subscription costs. This demand-elasticity contrast shapes infrastructure investment geography across the United Kingdom.
Greater London and Southeast England
Financial services firms in the City and Canary Wharf drive premium connectivity procurement with sub-millisecond latency requirements. Ofcom's wholesale fixed telecoms market review mandates virtual unbundled local access remedies that enable altnets to compete in hyperconnected business districts. The London-Stansted-Cambridge-Peterborough corridor concentrates data center interconnection demand.
North England
MediaCityUK in Salford and Manchester's emerging digital cluster absorb fiber-to-the-premises capacity faster than national averages. The Shared Rural Network mandate pools mobile infrastructure investment across Yorkshire and Lancashire to extend 4G coverage. Leeds and Sheffield enterprise zones show elevated small business connectivity penetration.
Midlands
Birmingham's manufacturing corridor generates industrial IoT and 5G network slicing demand for autonomous systems trials. CityFibre and altnets deploy XGS-PON at scale across the region, enabling symmetrical gigabit services. West Midlands 5G Testbed accelerates enterprise adoption timelines.
Scotland
Scottish Highlands connectivity gaps create neutral host opportunities for subsidized rural infrastructure programs. The Scottish Government's Reaching 100% (R100) superfast broadband program extends fiber deployment north of the central belt. Edinburgh's financial services cluster mirrors London's premium service requirements at smaller scale.
Wales
Wayleave agreement friction delays fiber deployment in dense urban cores of Cardiff and Swansea. The Welsh Government's Access Broadband Cymru scheme subsidizes connectivity in underpenetrated valleys and coastal communities. Openreach accelerates copper retirement in South Wales while maintaining universal service obligations.
United Kingdom Telecom Market Competitive Environment
Incumbent infrastructure owners and challenger wholesale specialists split the market along asset-control boundaries. BT Group anchors the consolidated tier through Openreach infrastructure control and regulated wholesale pricing frameworks. Virgin Media O2 competes by converging cable and mobile assets into bundled propositions. The dominant competitive moves involve fiber overbuild acceleration and strategic partnerships with retail service providers.
Among infrastructure-centric operators, BT Group, Virgin Media O2, and CityFibre occupy distinct strategic positions. BT Group represents the integrated incumbent archetype with wholesale and retail operations under common governance. Virgin Media O2 exemplifies the converged operator model combining fixed cable infrastructure with mobile spectrum assets. CityFibre anchors the pure-play fiber wholesale tier, targeting third-party retail service providers with dark fiber and lit services rather than direct consumer relationships.
| Leading Market Players |
|---|
| Virgin Media O2 |
| O2 |
| BT Group |
| VodafoneThree |
| Sky UK |
| EE |
| Three UK |
| CityFibre |
| Vodafone UK |
| Others |
Value Chain & Pricing Dynamics
High-risk vendor equipment restrictions under the Telecommunications (Security) Act create single-source dependency in 5G radio access network procurement, compressing pricing tier spreads between approved premium suppliers and constraining supply chain flexibility for operators seeking cost optimization.
Pricing Analysis
Managed service contracts and extended SLAs drive lifetime value capture beyond transactional connectivity sales. Three-tier pricing structure across premium, standard, and economy levels segments enterprise, small business, and residential buyers respectively. Price differentiation hinges on latency guarantees and after-sales support intensity. Cost compression in residential broadband intensifies because altnets deploy XGS-PON at scale. Enterprise buyers in Greater London exhibit lowest price sensitivity for guaranteed sub-millisecond services.
Supply Chain Analysis
Supply-chain finance facilities and extended payment terms from infrastructure vendors help operators manage fiber densification capital cycles. Equipment sourcing draws from China, South Korea, and Finland for radio units, optical components, and core network systems. Critical dependencies include gallium nitride semiconductors, fiber optic cable, and lithium-ion backup power systems. Single-source vulnerability concentrates in 5G massive MIMO antenna supply. Distribution runs through direct procurement for enterprise contracts and wholesale access frameworks for retail service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom Telecom Market operates as a defensive-moat story anchored in regulatory entrenchment, where Ofcom's wholesale access obligations and spectrum licensing frameworks create structural barriers that protect incumbent infrastructure returns while constraining challenger economics.
For Market Incumbents: Entrench Openreach's fiber infrastructure control through accelerated XGS-PON deployment in Manchester and Birmingham corridors before altnet overbuild matures. Deepen wholesale pricing discipline by leveraging regulated virtual unbundled local access frameworks to compress challenger margins. Prioritize vertical integration into edge computing co-location services to capture enterprise software-defined WAN migration spend.
For New Entrants and Emerging Players: Build out neutral host infrastructure in Scottish Highlands and Welsh valleys where subsidized rural programs reduce capital intensity. Target wholesale-only fiber models serving retail service providers rather than direct consumer acquisition. Exploit Open RAN interoperability requirements to disaggregate radio access network procurement and bypass incumbent equipment vendor lock-in.
For Investors and Strategic Acquirers: Ofcom's forthcoming spectrum release consultations reshape the acquisition landscape by determining entry economics for infrastructure competitors. Five-to-ten year viability favors pure-play fiber wholesale operators with duct and dark fiber assets in Greater London and Manchester enterprise zones. Watch the Competition and Markets Authority's wholesale pricing remedy reviews as the inflection signal for margin structure shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Fiber-to-the-Premises Acceleration | XGS-PON deployment absorbs capital expenditure as DSL obsolescence accelerates nationwide. |
| Open RAN Vendor Diversification | Disaggregated radio access networks bypass high-risk vendor restrictions and shorten procurement cycles. |
| Edge Computing Co-location Buildout | 5G network slicing convergence enables low-latency hosting for autonomous systems and industrial IoT. |
| Wholesale Infrastructure Access | Regulated dark fiber and duct remedies fragment end-customer relationships toward retail service providers. |
| Shared Rural Network Partnership | Pooled mobile infrastructure investment extends 4G coverage to 95% of UK geography per Ofcom mandate. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with network engineering directors, wholesale pricing strategists, enterprise procurement officers, and regulatory affairs leads at Ofcom. Secondary validation incorporated operator capex disclosures, Ofcom market reviews, spectrum auction results, and Competition and Markets Authority filings. Bottom-up connection forecasts triangulated against top-down infrastructure investment projections.
Calibration against historical deployment timelines and regulatory decision lags anchored the analytical framework across the analysis window. Segmentation dimensions modeled include service type, technology generation, end user scale, and delivery channel structure. CAGRs derived from infrastructure investment run-rates, subscriber adoption curves, and enterprise contract value expansion. Key inputs encompassed fiber premises passed data, 5G site deployment rates, and wholesale pricing remedy scenarios.
Stress conditions across spectrum allocation delays, vendor approval timelines, and wayleave negotiation friction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and infrastructure competition economics. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global 5G Services Market
Telecommunications
Hong Kong Telecom Market
Telecommunications
US 5G Radio Access Network Professional Services Market
Telecommunications
Peru Telecom Market
Telecommunications
Kenya Telecom Market
Telecommunications
Belgium ICT Market
Telecommunications
Optical Fronthaul Market
Telecommunications
SIP Trunking Services Market
Telecommunications
United Arab Emirates Telecom Market
Telecommunications
5G Remote Radio Head Market
Telecommunications
Middle East and Africa Telecom Market
Telecommunications
Telecom API Platform Market
Telecommunications
MENA Mobile Virtual Network Operator Market
Telecommunications
Qatar Telecom Market
Telecommunications
Telecom Service Assurance Market
Telecommunications
Global International Calling Apps Market